Game Development reports and market data
Documents
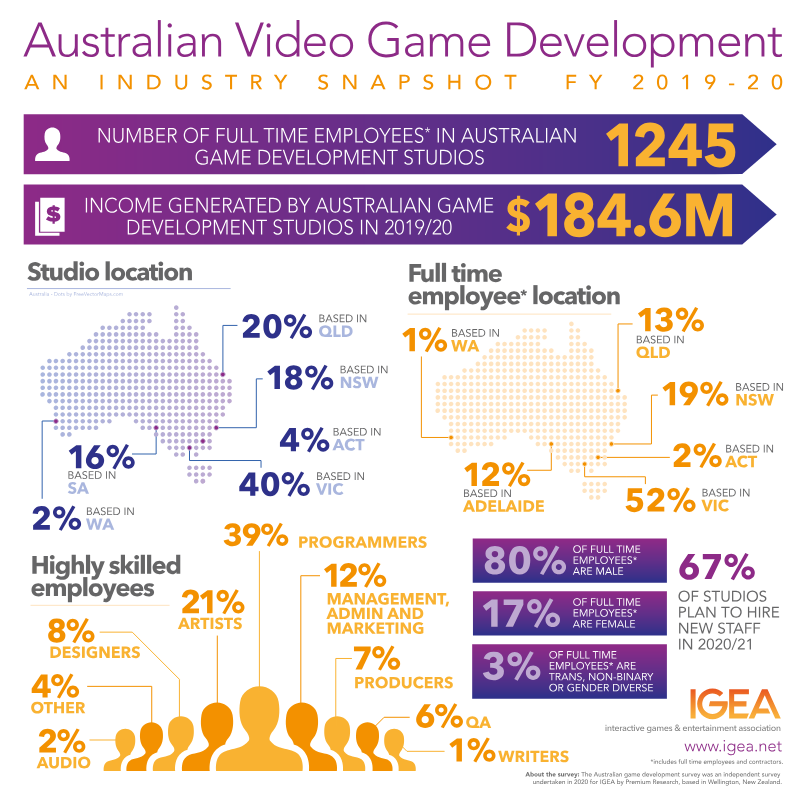
Australian Game Development Industry Snapshot FY 2019-20
The Australian Game Development Industry Snapshot for FY 2019-20, produced by the Interactive Games & Entertainment Association (IGEA), profiles the country's game development sector at a time when COVID-19 was beginning to reshape its operations.
- The Australian game development sector employed about 1,245 full-time staff and contractors in FY 2019-20 and generated roughly $184.6 million in income, with studios concentrated in New South Wales, Victoria, and Queensland.
- The industry is export-oriented, with about 51 percent of studio income coming from overseas markets, and 78 percent of responding studios developing their own intellectual property.
- Studios are relatively young, with roughly half having operated for five years or less, and development focuses heavily on mobile platforms, with PC/Mac and console also prominent while VR and AR remain small shares of activity.
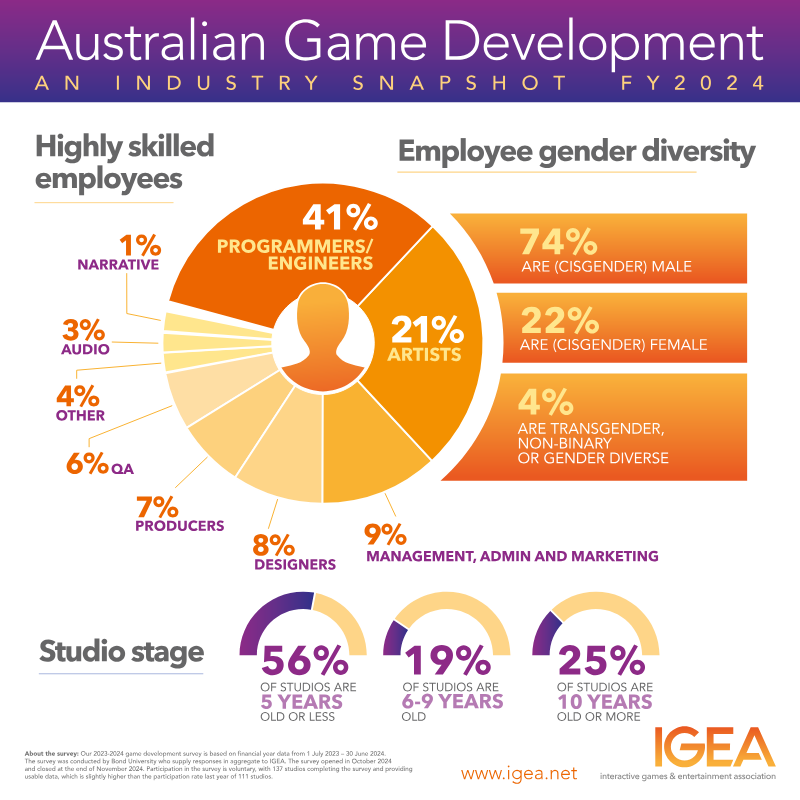
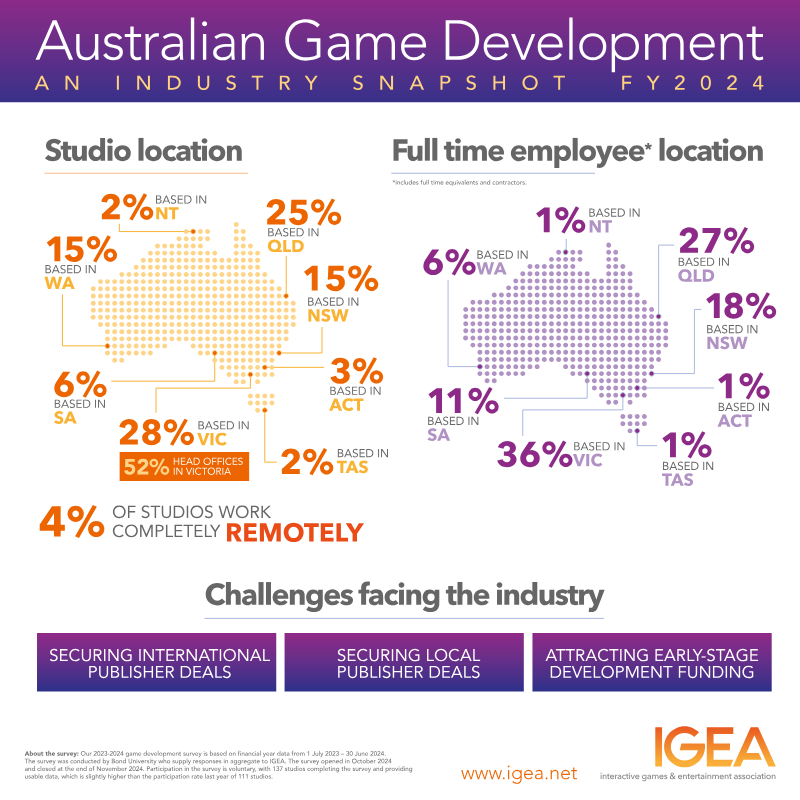
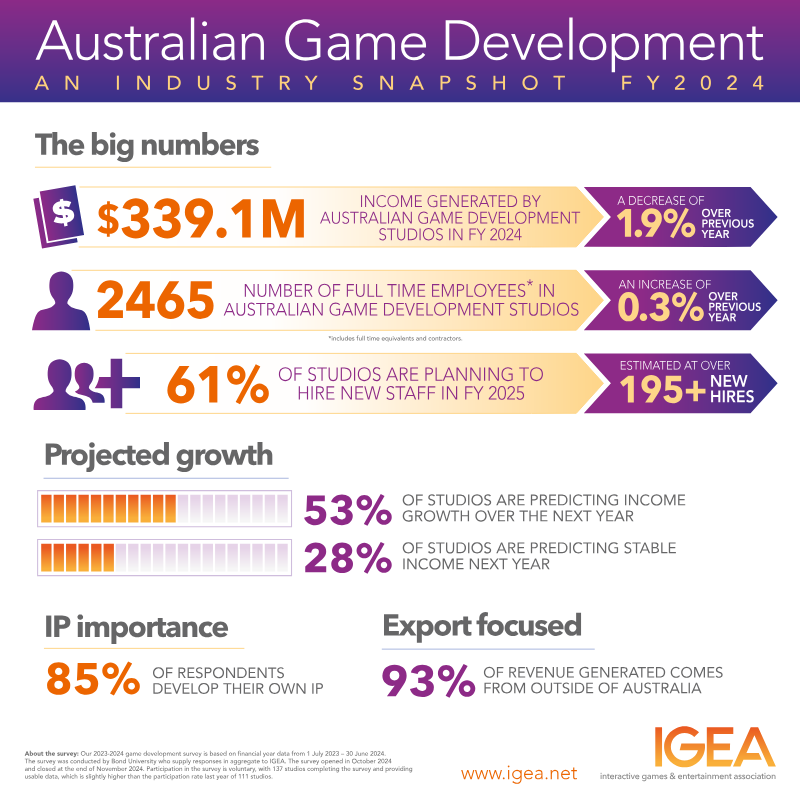
Australian Industry Snapshot FY 2024
The Australian Industry Snapshot FY 2024 presents a financial and workforce overview of the country's game development sector for the financial year running from 1 July 2023 to 30 June 2024.
- Australia's game development sector generated about $339.1 million in income in FY 2024, down 0.9% year on year, while its workforce of 2,465 (including FTEs and contractors) grew 0.3%.
- The industry is strongly export-oriented, with 93% of revenue coming from outside Australia.
- Intellectual property is central to the sector: 85% of respondents develop their own IP.
Industry Snapshot 2025: Australian Game Development
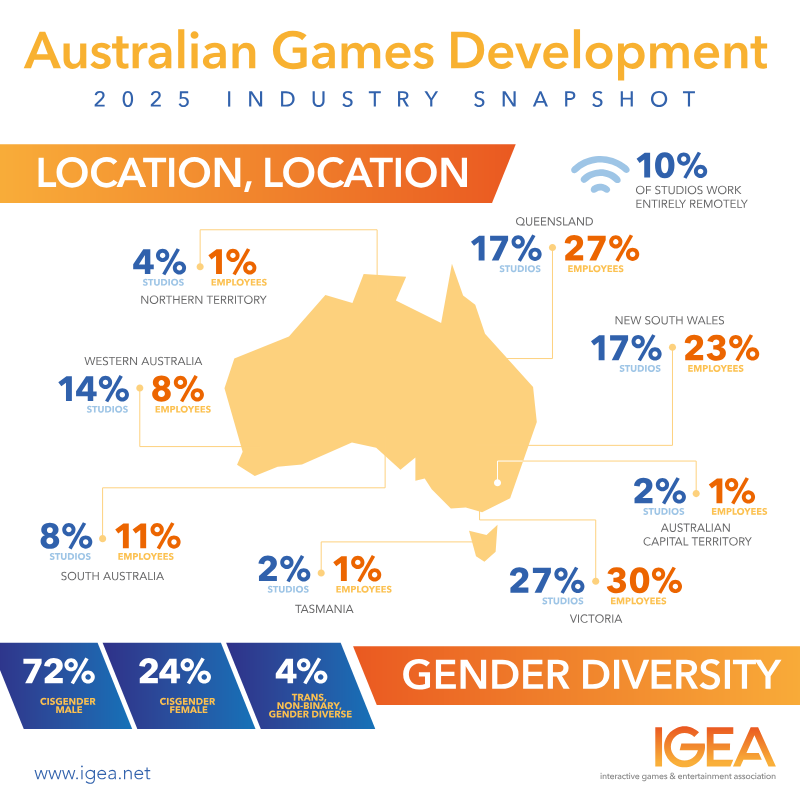
The Industry Snapshot 2025 provides an overview of Australian game development for the 2024–25 financial year, drawing on a voluntary survey of studios conducted by Bond University.
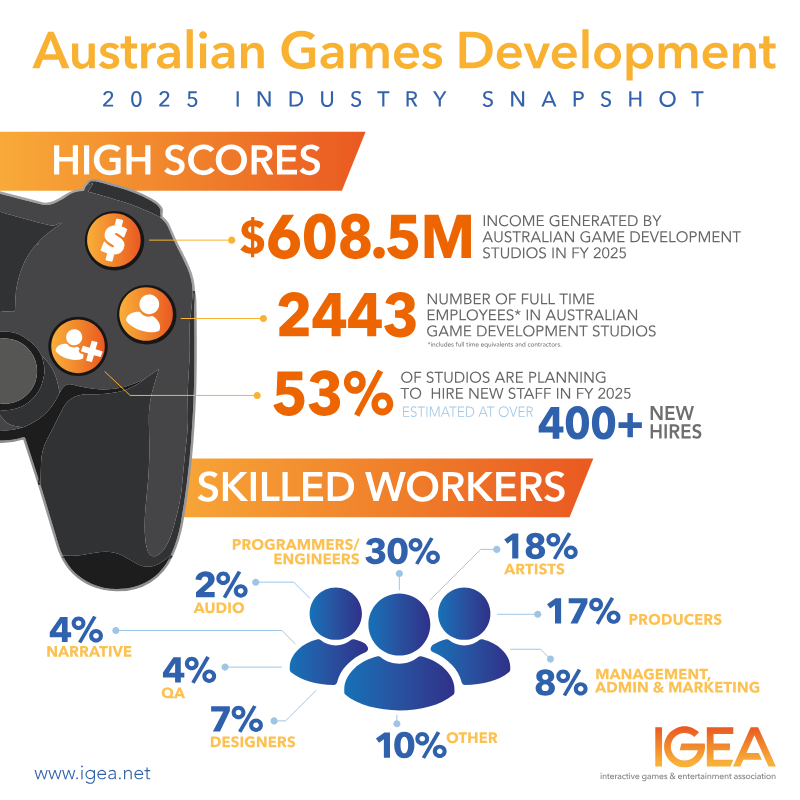
- The Australian game development industry generated roughly $608.5 million in income across an estimated 243 studios in the 2024–25 financial year (1 July 2024 to 30 June 2025).
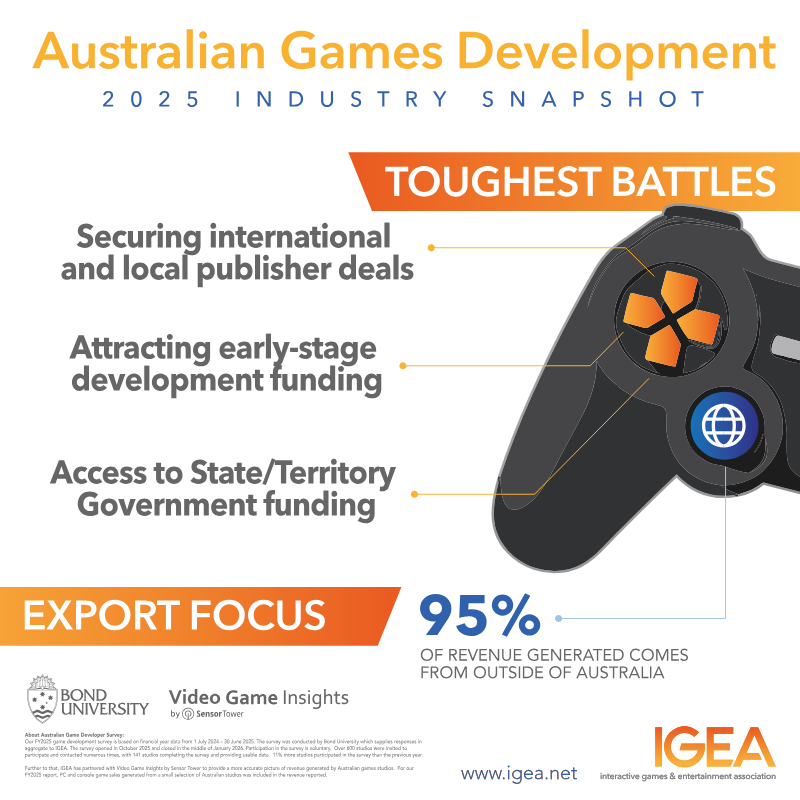
- The industry is heavily export-oriented, with 95% of revenue coming from outside Australia.
- Studios plan over 400 new hires in the coming year, with 53% of studios expecting to recruit staff.
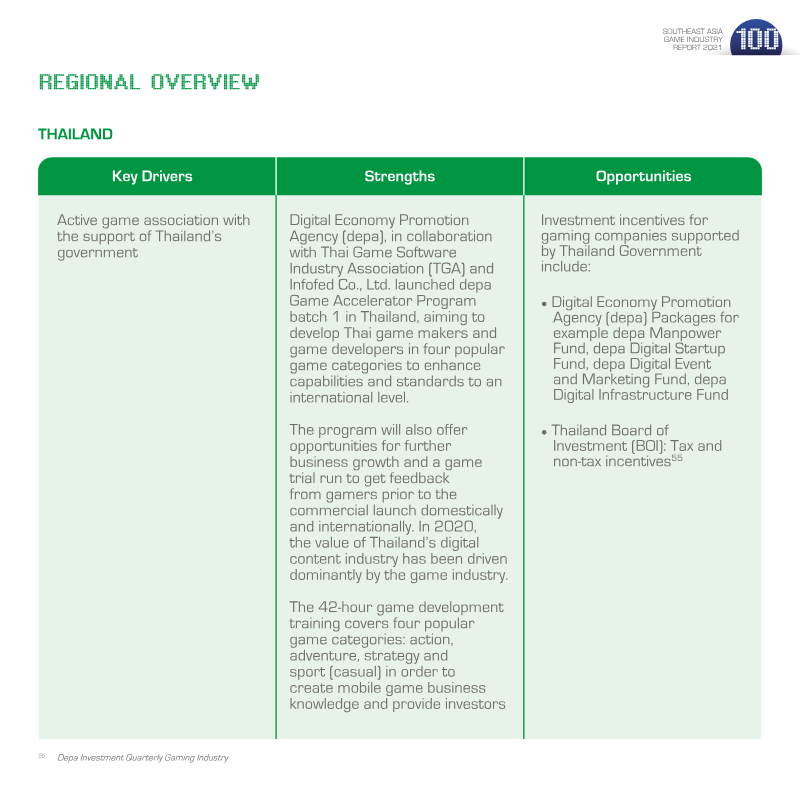
Southeast Asia Game Industry Report 2021
The Southeast Asia Game Industry Report 2021, published by Malaysia Digital Economy Corporation (MDEC), is the third regional study of the games sector following 2015 and 2016 reports.
- Southeast Asia's game industry was reported at US$4.4 billion, with 70% of that coming from mobile.
- Most surveyed companies are small and young, with 48% having less than three years in the market.
- The majority of companies (60%) employ fewer than 11 people, while only 10% have more than 100 employees.
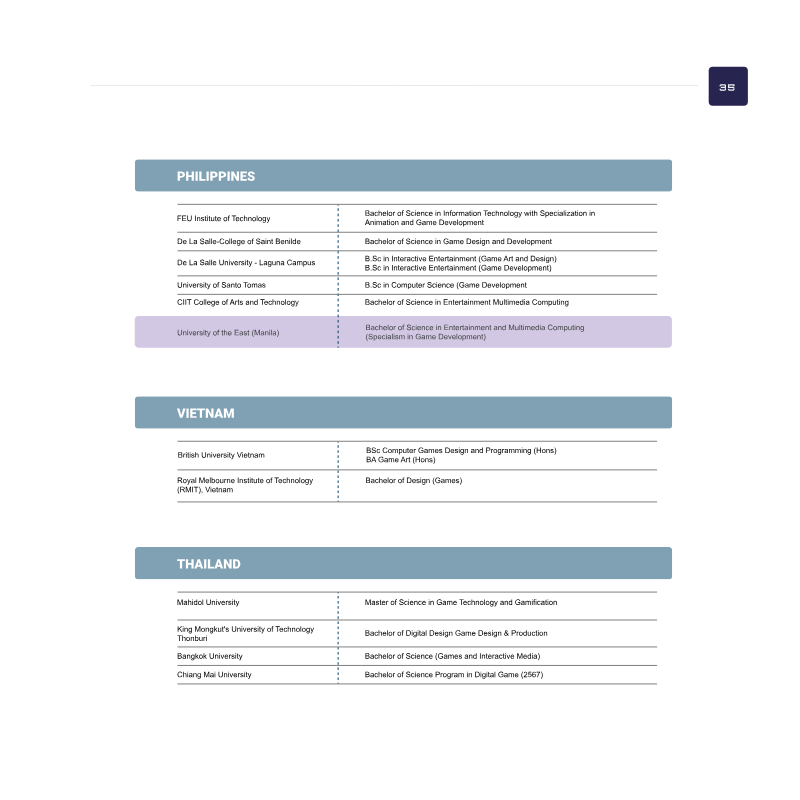
Malaysia Game Development Industry Talent Economics Report 2024
This Malaysia Digital Economy Corporation (MDEC) and TalentCorp-supported report, produced with Asia Pacific University, examines talent economics in Southeast Asia's game development industry for 2024.
- Men in the regional sample earn about 16% more per month than women, with the gap widening as experience increases.
- Among the three major specialisations, game programmers have the highest average monthly salary, while game designers have the lowest.
- Singapore's average monthly game development salary is far above other surveyed countries, with Indonesia the lowest.
Costa Rica's Videogame Industry Catalog 2023
Costa Rica's Videogame Industry Catalog 2023 is a catalog produced by PROCOMER, the Export Promotion Agency of Costa Rica, together with ASODEV, the Videogame Developer's Association of Costa Rica.
- The catalog states that more than 20 studios are located in Costa Rica, with the main focus on exporting services and original IPs.
- The stated main export destinations are the United States, Europe and Asia.
- Green Lava Studios' My Name is Mayo trilogy is described as having become top sellers on PSN at launch.
Argentine Videogame Industry
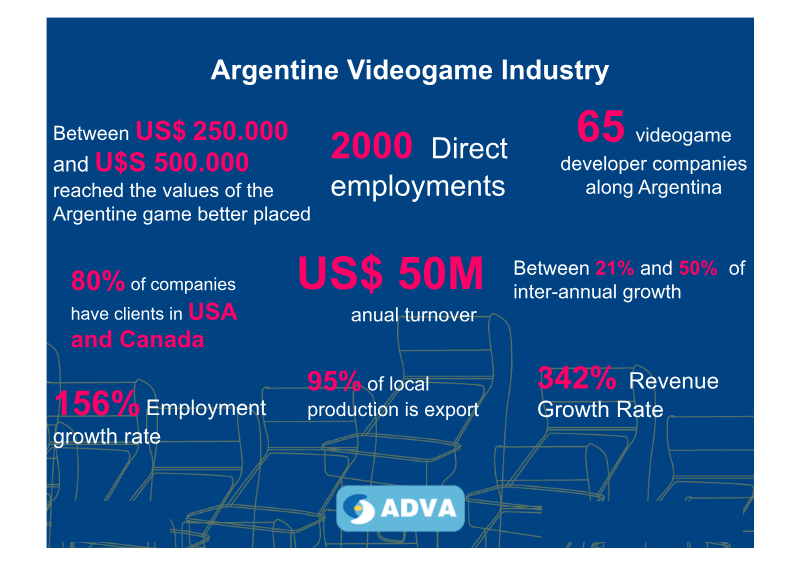
The Argentine Videogame Industry is a dynamic and rapidly growing sector, characterized by high growth rates in both revenue and employment.
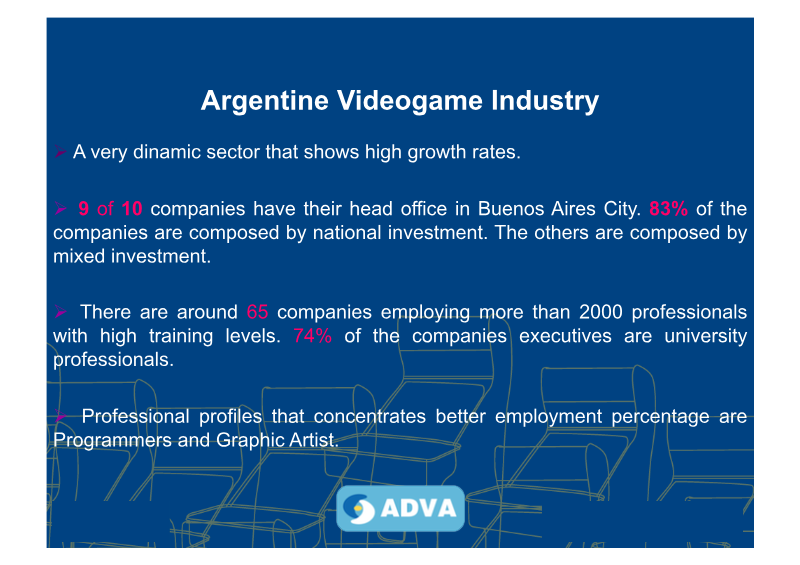
- Argentina's videogame industry comprises roughly 65 companies employing more than 2,000 professionals, with programmers and graphic artists making up the largest share of jobs.
- Between 2006 and 2011, sector revenues grew 156 percent and employment more than doubled, with 2012 projections anticipating nearly 50 percent revenue growth and a 34 percent rise in on-site workers.
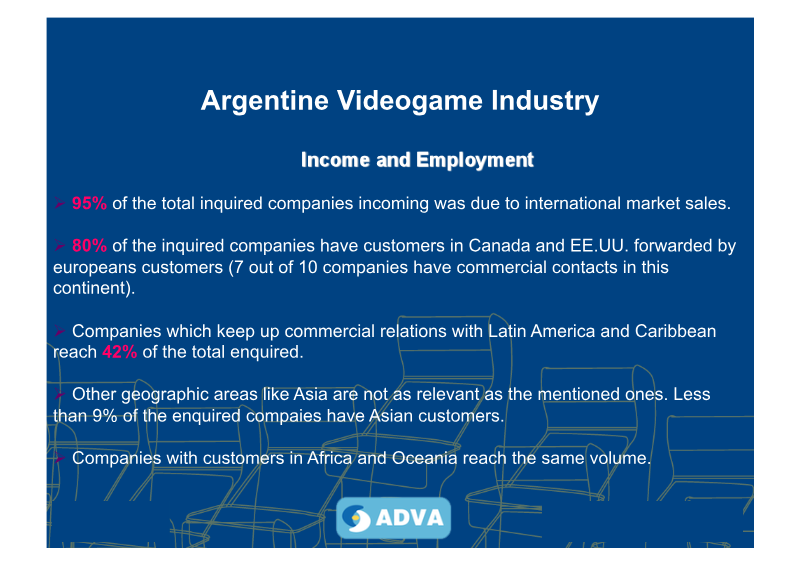
- Exports account for 95 percent of sector sales, with 80 percent of surveyed companies serving clients in the United States and Canada, often through European intermediaries.
Observatorio de la Industria Argentina de Videojuegos: Informe 2025
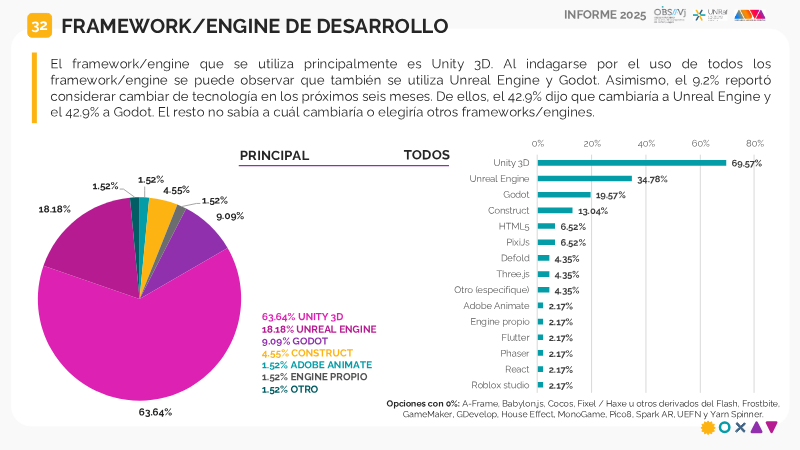
The Observatorio de la Industria Argentina de Videojuegos, a public-private project launched in 2017 from the Universidad Nacional de Rafaela (UNRaf) and backed by ADVA, presents its 2025 report on activities carried out in 2024.
- Access to financing is reported as the main perceived obstacle to developing the activity, followed by economic instability and high tax pressure relative to salaries.
- The report estimates the industry's economic value at U$S 87,344,640, based on 1,432 human resources in activity.
- In 2024, development started on 41 small games and 23 large games, and 17 small and 10 large games were published.
The Funding Landscape of the Swiss Game Industry 2026
This preliminary study by the Swiss Game Developers Association (SGDA) assesses the funding landscape of the Swiss game industry in 2026, focusing on the impact of public funding and regional disparities.
- The SGDA's 2026 study, based on a voluntary survey of 51 Swiss game studios (25 in Zurich, 26 elsewhere) conducted April–May 2026, concludes that the Swiss industry is internationally respected but small and under-capitalised, with sustained production-stage funding as the decisive missing element.
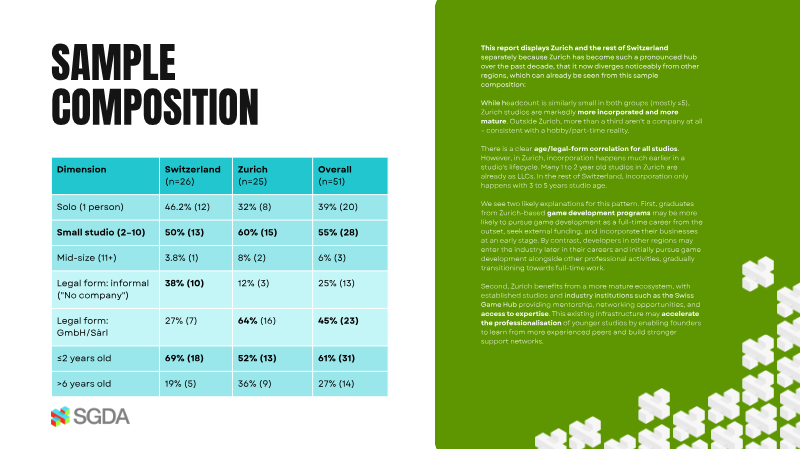
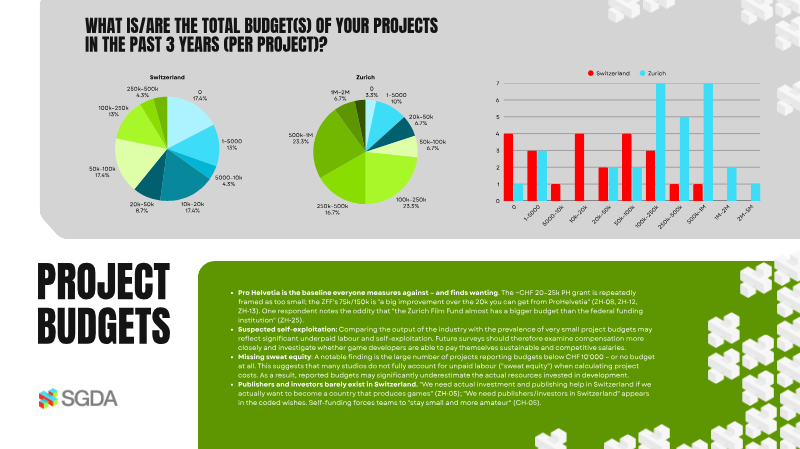
- Zurich studios are far better resourced than those elsewhere in Switzerland: 64% are incorporated as GmbH or Sàrl versus 27% outside the canton, and the median project budget is CHF 275k compared with CHF 30k.
- Zurich studios receive a median of 15% of their budgets from public support, while studios outside Zurich receive none, as most cantons offer no support for games at all.
eGames Lab Research Midterm Report 2023-2024
The eGames Lab Research Midterm Report covers the 2023-2024 midterm of a national Portuguese cluster for electronic games, funded under Portugal's Recovery and Resilience Plan (PRR) and based in Madeira, Lisbon, Évora and the Azores.
- The eGames Lab reports a total investment of 29,991,847.46€, of which 20,181,482.23€ is allocated to research and development.
- The consortium brings together 22 private and public entities organised across Madeira, Lisbon, Évora and the Azores.
- The lab's staff includes 18 PhD students, 14 MSc students, 12 post-docs and 4 BSc students, drawn from 9 nationalities.
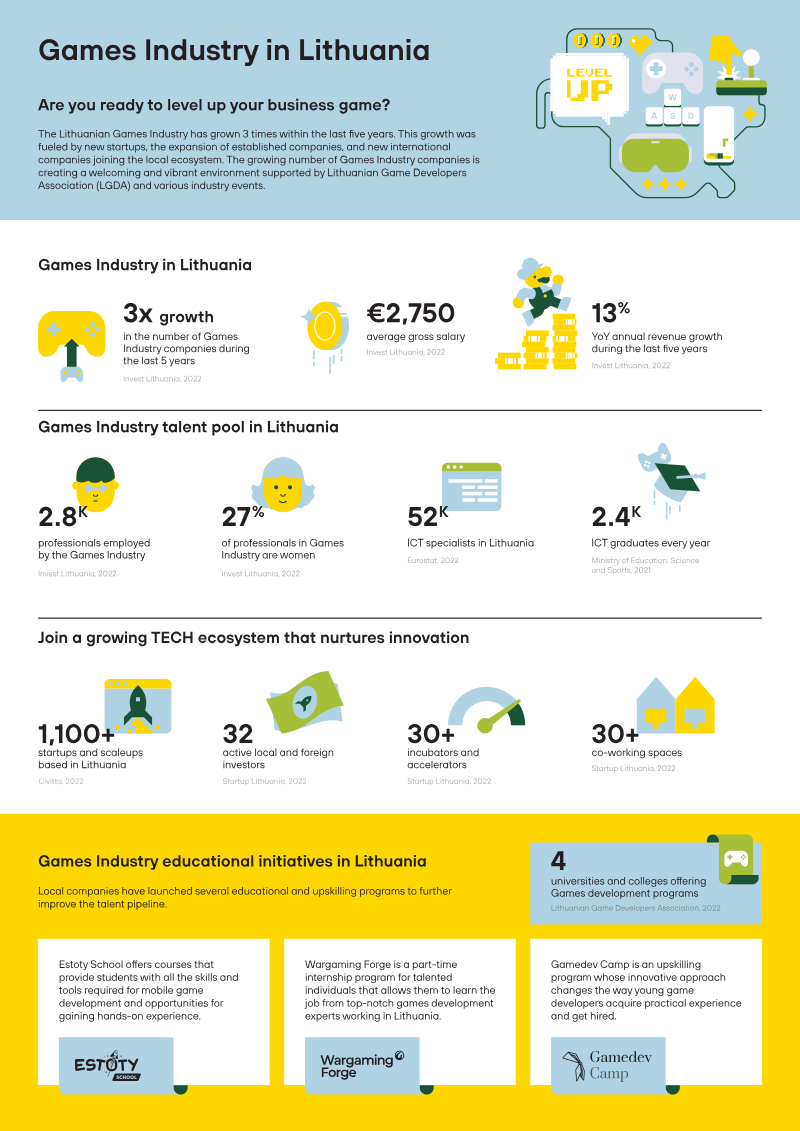
Games Industry in Lithuania
The Lithuanian games industry has experienced substantial growth, tripling in company count over the past five years, driven by new startups, existing company expansion, and international entrants.
- Lithuania's games industry has grown threefold over the past five years, driven by new startups, expansion of established studios, and international companies entering the local ecosystem.
- The games sector employs about 2,800 professionals, 27% of them women, with an average gross salary of €2,750, and annual revenue has grown 13% year over year.
- The broader ICT talent base includes roughly 52,000 specialists, with around 2,400 ICT graduates produced each year.
The Game Industry of Estonia 2021
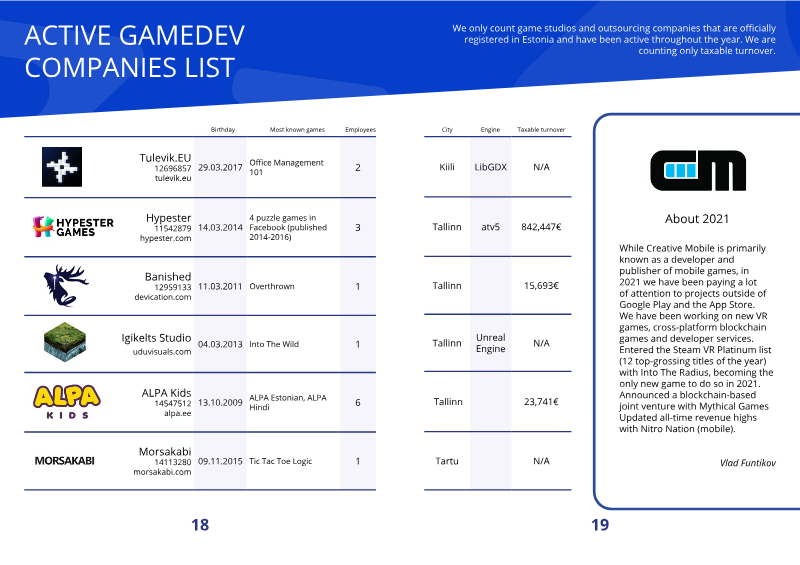
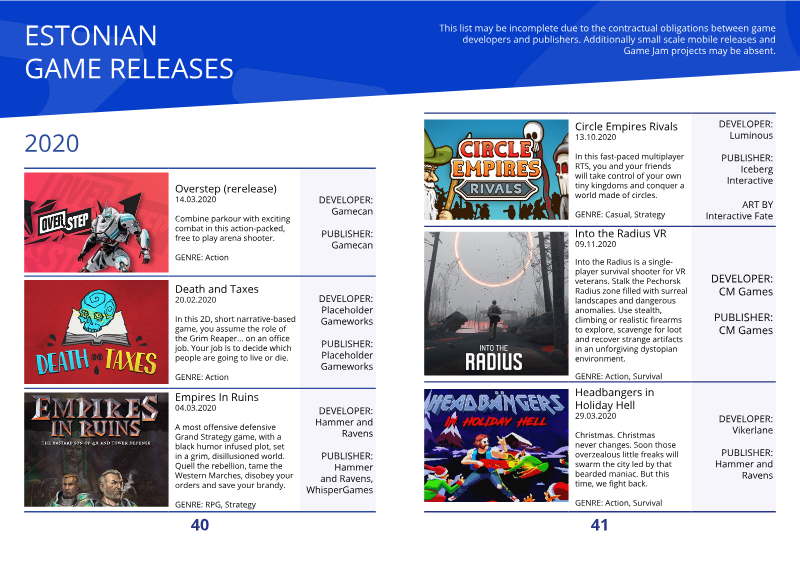
The paper, produced by GameDev Estonia, maps the Estonian game industry, covering game development studios, educational entities and support organisations that were active through 2021.
- Taxable turnover of the industry rose from 40,003,013€ in 2020 to 50,440,641€ in 2021, a growth of 20.69%.
- The document states that 38% of studios have two to five workers and another 38% have one working person, placing 76% of development companies in the tiny category.
- Of the engines counted, Unity accounted for 52.9% (18 of 34) and Unreal Engine for 29.4% (10 of 34).
Writers
Games and companies
Games