Report24 pages
Politics in Live Streaming: 2024
Live streaming has emerged as a critical venue for political discourse, effectively rivaling traditional media in its capacity to engage younger, tech-savvy audiences in real time. This analysis examines the intersection of politics and live streaming across major platforms—including Twitch, YouTube, Kick, and Rumble—from January 2023 through September 2024. The findings indicate that political content is a rapidly growing segment of the live-streaming ecosystem, with the market share of political streams increasing from 0.8% to nearly 3% over the first nine months of 2024.
Data reveals a significant surge in political engagement during major 2024 events, such as the U.S. presidential campaign announcements and the September debate between Donald Trump and Kamala Harris. YouTube Live has established itself as the dominant platform for this content, capturing 87% of the political streaming market in September 2024 and experiencing a 530% increase in political viewership since January. While Rumble maintains the highest concentration of political content relative to its total viewership at 32%, Twitch and Kick have also seen substantial growth in political engagement.
The analysis also highlights potential irregularities in viewership data, specifically identifying a subset of YouTube channels that exhibited suspicious behavior, such as rapid name changes or deletion following broadcasts related to the 2024 U.S. election. These compromised channels accounted for approximately 35% of the hours watched for streams mentioning the presidential candidates in Q3 2024. Despite these anomalies, the data confirms that live-streaming audiences are highly responsive to political developments, with chat sentiment and engagement metrics providing a granular view of public reaction to candidates and policy issues. Ultimately, the shift toward live-streamed news consumption reflects a broader transformation in how global audiences interact with and participate in contemporary political events.
- YouTube Live dominates the political streaming market with an 87% share as of September 2024, having experienced a 530% increase in political viewership since January 2024.
- Political content's share of the total live-streaming market grew significantly in 2024, rising from 0.8% to nearly 3% within the first nine months of the year.
- Approximately 35% of hours watched for streams mentioning U.S. presidential candidates in Q3 2024 originated from compromised YouTube channels exhibiting suspicious behaviors like rapid name changes or post-broadcast deletions.
- Rumble maintains the highest concentration of political content relative to its total platform viewership at 32%.
- Live-streaming engagement shows a direct correlation with major political milestones, evidenced by significant viewership surges during U.S. presidential campaign announcements and the September 2024 debate.
+1
Stream Hatchet
Report13 pages
Winning Audiences Through YouTube Gaming
YouTube Gaming experienced significant growth in 2025, solidifying its position as a dominant force in the live-streaming industry. The platform recorded 8.8 billion hours of viewership, accounting for approximately one in every four hours spent on live-streaming gaming platforms globally. This performance represents a 12% year-over-year increase, driven by a diverse international audience and a robust ecosystem of creators. The platform’s reach is particularly strong in North America, Asia, and Latin America, with Japan, the United States, and India emerging as the top markets for viewership.
The platform’s content strategy has successfully diversified beyond traditional long-form live streams. YouTube Shorts saw consistent growth throughout 2025, peaking at 6.15 million gaming-related posts in August. Simultaneously, sponsored content experienced a resurgence, with streams featuring paid partnerships reaching 4.5 million hours watched in the final quarter of 2025, the highest level since 2020. Roblox emerged as the most-watched game on the platform, while esports remained a critical pillar, contributing 1.2 billion hours of viewership, led by major titles such as League of Legends and Mobile Legends: Bang Bang.
Demographically, the audience is predominantly male and concentrated in the 20-34 age range, though the platform maintains a broad appeal that includes significant engagement from VTubers and variety streamers. The data indicates that top-tier creators often leverage a multi-platform approach, frequently streaming on competing services alongside YouTube to maximize their reach. The analysis relies on proprietary streaming metrics, including hours watched, peak concurrent viewers, and third-party demographic modeling based on social media behavioral patterns, to provide a comprehensive overview of the platform's influence within the global gaming sector.
- YouTube Gaming captured 8.8 billion hours of viewership in 2025, marking a 12% year-over-year growth and securing a 25% share of the global live-streaming gaming market.
- Roblox ranked as the most-watched game on the platform, while esports titles like League of Legends and Mobile Legends: Bang Bang generated 1.2 billion hours of total viewership.
- YouTube Shorts reached a peak of 6.15 million gaming-related posts in August 2025, highlighting the platform's successful diversification beyond long-form live content.
- Sponsored content saw a significant resurgence in Q4 2025, reaching 4.5 million hours watched, the highest level recorded since 2020.
- The platform's viewership is geographically concentrated in Japan, the United States, and India, with a core audience demographic of males aged 20–34.
+1
Stream Hatchet
Report29 pages
Esports Trends Report 2025
The 2025 Esports Trends Report provides a comprehensive analysis of the global esports landscape, focusing on viewership patterns, platform consolidation, and the evolving role of creator-led content. Tracking nearly 2,000 events across 78 titles, the data reveals a total of 2.7 billion hours watched. The industry remains highly concentrated, with League of Legends and Counter-Strike alone accounting for nearly 45% of total viewership. While Twitch and YouTube Gaming dominate the market with a combined 84.1% share, the report highlights the increasing significance of mobile esports, which, despite lower total hours watched, achieves higher average viewership per tournament than non-mobile counterparts.
A primary finding is the shift toward decentralized viewership, as co-streaming now accounts for 51.2% of all esports hours watched. This trend underscores the importance of linguistic accessibility and the influence of high-profile creators in driving engagement. Furthermore, the report identifies a growing synergy between brands and competitive gaming; tournaments headlined by brands generated 29.2% of total hours watched. Endemic brands like BLAST and StarLadder continue to lead in volume, but non-endemic entities, particularly in the betting sector, are increasingly capturing market share, suggesting significant untapped potential for diverse industries to engage with gaming audiences.
Methodologically, the analysis relies on granular, real-time tracking of Premier, Major, and Minor tournaments, excluding non-esports gaming content such as speedruns or showcases. By utilizing advanced metrics—including chat sentiment analysis, logo recognition, and match-by-match breakdowns—the report demonstrates how organizers and publishers can now achieve deeper insights into fan behavior. The findings conclude that the esports ecosystem is moving toward a more sophisticated, data-driven model where creator partnerships and regional league structures, particularly in Southeast Asia and South Korea, serve as the primary engines for sustained growth and audience retention.
- Co-streaming has become the dominant viewership model, accounting for 51.2% of all esports hours watched and highlighting the critical role of creator-led content.
- The esports market remains highly concentrated, with League of Legends and Counter-Strike generating nearly 45% of the total 2.7 billion hours watched across 2,000 tracked events.
- Twitch and YouTube Gaming maintain a combined 84.1% market share of total viewership, though mobile esports tournaments are achieving higher average viewership per event than non-mobile titles.
- Brand-headlined tournaments now generate 29.2% of total hours watched, with non-endemic companies in the betting sector increasingly capturing market share.
- Future industry growth is increasingly dependent on data-driven fan engagement strategies and regional league structures, specifically within Southeast Asia and South Korea.
+1
Stream Hatchet
Presentation9 pages
Gamer Motivation Model: Reference Sheets and Details
The Gamer Motivation Model provides a comprehensive framework for understanding player behavior by categorizing gaming preferences into twelve distinct motivations. Developed through psychometric factor analysis of data from over two million global participants, the model identifies how specific psychological drivers cluster together to influence game selection and engagement. By linking demographic data with preferred game titles and franchises, the research offers a data-driven approach to analyzing audience segments and predicting player retention.
The model organizes these twelve motivations into six related pairs, which are further grouped into three high-level clusters: Action-Social, Mastery-Achievement, and Immersion-Creativity. Action-Social focuses on immediate, adrenaline-fueled experiences and interpersonal interaction. Mastery-Achievement emphasizes long-term, goal-oriented gameplay characterized by strategic planning and cumulative progression. Immersion-Creativity centers on expansive, expressive play, curiosity, and the exploration of narrative or design-based boundaries. These clusters are conceptually described as bright, tall, and wide, respectively, to illustrate their distinct psychological orientations.
Each motivation is treated as a spectrum rather than a binary preference, acknowledging that gamers possess varying degrees of interest across all categories. By defining the anchors at both ends of these spectrums, the model allows for nuanced profiling of player types. For instance, the model distinguishes between players who prioritize social collaboration versus those who prefer independent, non-adversarial environments, or those who seek skill-based challenges versus those who prefer spontaneous, low-cognitive-load gameplay. This empirical approach provides actionable insights for developers and analysts to map specific game mechanics to the underlying psychological needs of diverse player demographics, facilitating a deeper understanding of the global gaming landscape.
- The Gamer Motivation Model categorizes player behavior into twelve distinct motivations derived from psychometric factor analysis of over two million global participants.
- Motivations are organized into three high-level clusters: Action-Social (immediate, interpersonal), Mastery-Achievement (goal-oriented, progression), and Immersion-Creativity (narrative, expressive).
- Player preferences are measured as spectrums rather than binary choices, allowing for nuanced profiling of how individuals balance competing psychological drivers.
- The framework maps specific game mechanics to underlying psychological needs, enabling developers to predict player retention and engagement based on target audience segments.
- By linking demographic data with preferred game titles, the model provides a data-driven methodology for analyzing global gaming audiences and their specific engagement patterns.
+1
Quantic Foundry
Report2 pages
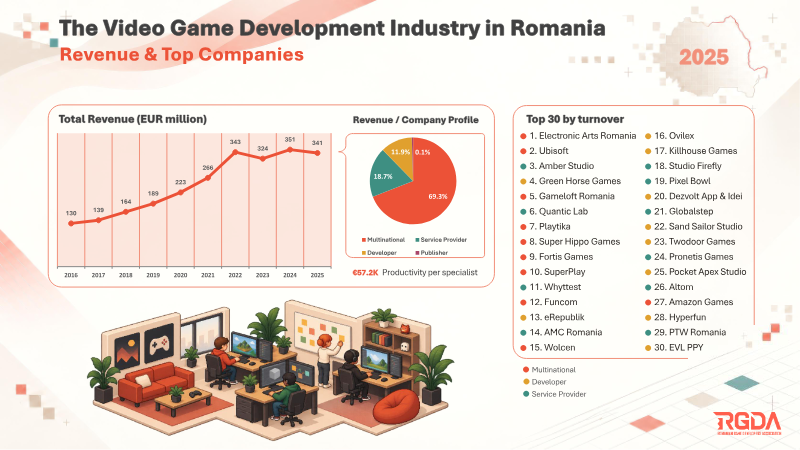
Revenue & Top Companies: Romania 2025
The Romanian video game industry has demonstrated significant resilience and structural evolution, reaching a total revenue of 351 million EUR by 2025. While the sector experienced a post-pandemic contraction that impacted service providers, the market has pivoted toward a surge in creative output. This shift is evidenced by a 2.5-fold increase in game releases over the past two years, signaling a robust expansion within the independent development sector. The industry currently maintains a productivity rate of 57,200 EUR per specialist, supported by a workforce of 6,000 professionals.
Geographically, the industry remains heavily concentrated in major urban hubs, with Bucharest serving as the primary center of operations, hosting 46 percent of all studios. Cluj, Iași, Timiș, and Brașov follow as secondary clusters, collectively accounting for 28 percent of the ecosystem. The current landscape comprises 234 active studios, ranging from multinational corporations to independent developers and service providers. Among the top 30 companies by turnover are major international players such as Electronic Arts Romania, Ubisoft, and Gameloft, alongside a diverse array of specialized local studios.
The industry ecosystem is supported by a domestic player base of 8.6 million individuals. The transition from a service-heavy model to a more balanced mix of development and publishing has fostered a more sustainable environment for local talent. By diversifying its operational focus, the Romanian gaming sector has successfully navigated recent economic pressures, positioning itself as a key European hub for both large-scale multinational production and agile, independent game creation.
- The Romanian video game industry reached a total revenue of 351 million EUR in 2025, supported by a workforce of 6,000 professionals.
- The sector has shifted from a service-heavy model to a balanced mix of development and publishing, resulting in a 2.5-fold increase in game releases over the last two years.
- The industry is comprised of 234 active studios, with major international players like Electronic Arts Romania, Ubisoft, and Gameloft ranking among the top 30 companies by turnover.
- Geographic concentration remains high, with 46 percent of all studios located in Bucharest and an additional 28 percent distributed across Cluj, Iași, Timiș, and Brașov.
- The industry maintains a productivity rate of 57,200 EUR per specialist.
RGDA – Romanian Game Developers Association
Report37 pages
Report of the German Games Industry: 2026
The German video games market solidified its status as Europe’s largest in 2025, achieving a total revenue of 9.4 billion euros. This four percent growth was primarily fueled by a 12 percent surge in hardware sales and the milestone achievement of online gaming services exceeding one billion euros in revenue. Despite these gains, the sector faces a complex transition, marked by a 13 percent decline in one-off game purchases and a slight three percent contraction in the workforce, even as the total number of industry companies grew to 956.
Domestic production remains a critical area for development, as local companies currently capture only 5.50 euros of every 100 euros spent within the German market. To address this, the industry is leveraging increased federal funding, which is set to reach 125 million euros annually by 2026, alongside new tax-based incentive proposals and infrastructure projects like the House of Games Berlin. These initiatives aim to provide the long-term planning certainty required to improve international competitiveness and foster a more robust ecosystem for developers, publishers, and academic institutions.
Beyond economic metrics, the industry is undergoing significant professionalization and cultural integration. Regulatory frameworks, such as the USK’s expanded youth protection measures, and the formal recognition of esports clubs as charitable organizations reflect a maturing sector. With the average gamer age now at 38.2 years and major events like gamescom maintaining record attendance, Germany continues to serve as a central global hub for innovation. Industry associations are further driving progress through standardized diversity initiatives and environmental sustainability programs, ensuring that the sector remains aligned with modern social and economic expectations.
- The German video games market reached 9.4 billion euros in 2025, a four percent increase driven by a 12 percent surge in hardware sales and over one billion euros in online gaming service revenue.
- Domestic production remains low, with local companies capturing only 5.50 euros of every 100 euros spent in the German market.
- Federal funding for the industry is set to reach 125 million euros annually by 2026, supplemented by proposed tax incentives and infrastructure projects like the House of Games Berlin to boost competitiveness.
- The industry faces a structural shift characterized by a 13 percent decline in one-off game purchases and a three percent contraction in the workforce, despite the total number of companies rising to 956.
- The German gaming demographic is maturing, with the average gamer age now at 38.2 years.
+1
game – Verband der deutschen Games-Branche e. V.
Whitepaper38 pages
White Paper on Spanish Videogame Development 2025
The Spanish video game industry stands at a pivotal juncture, characterized by steady growth alongside significant structural vulnerabilities. Comprising 820 studios and employing over 10,500 professionals, the sector generated €1.464 billion in 2024. Despite this output, the industry remains highly consolidated, with 78 percent of total revenue concentrated among a small group of large-scale studios. A pervasive reliance on external financing, affecting 80 percent of companies, underscores the fragility of the current ecosystem, particularly as nearly half of all studios report negative impacts from recent economic instability, including project cancellations and workforce reductions.
To secure long-term viability and global competitiveness, the industry must transition toward a model that prioritizes the retention of intellectual property and the scaling of mid-sized enterprises. Strategic objectives include quadrupling annual turnover and doubling high-quality employment through a framework of five core pillars. These initiatives emphasize the necessity of robust tax incentives, expanded public funding, and the cultivation of a national investment ecosystem. Furthermore, while generative artificial intelligence has been adopted by 53 percent of studios, the lack of consensus regarding its utility suggests that future growth depends on balanced, responsible technological integration rather than uncritical adoption.
Ultimately, the sector’s evolution requires deeper collaboration between local creators and international platforms to bridge the gap between creative potential and financial sustainability. By fostering stronger ties between academic institutions, professional organizations, and independent developers, the industry aims to solidify its position within the global market. The path forward necessitates a coordinated policy approach that mitigates economic risks while providing the capital and infrastructure required to transform Spain into a premier hub for high-value digital entertainment production.
- The Spanish video game industry generated €1.464 billion in 2024 across 820 studios, but 78 percent of this revenue is concentrated within a small group of large-scale companies.
- Eighty percent of studios rely on external financing, leaving the sector vulnerable to economic instability, which has already caused project cancellations and workforce reductions for nearly half of all firms.
- The industry employs over 10,500 professionals and has set strategic goals to quadruple annual turnover and double high-quality employment through improved tax incentives and public funding.
- While 53 percent of Spanish studios have adopted generative artificial intelligence, there is no industry consensus on its utility, signaling a need for cautious and balanced technological integration.
- Long-term viability depends on transitioning toward a model that prioritizes the retention of intellectual property and the scaling of mid-sized enterprises.
+1
Asociación Española de Empresas Productoras y Desarrolladoras de Videojuegos
Report87 pages
Libro Blanco del Desarrollo Español de Videojuegos 2025
The Spanish video game industry stands at a critical juncture, characterized by resilience and creative output despite a global climate of economic instability. As of 2024, the sector generated €1,464 million in turnover and sustained over 10,500 direct jobs, with Catalonia and Madrid serving as the primary hubs for development. While the industry maintains a stable core—with 72% of studios operating for over five years—it faces a notable slowdown in growth. Currently, 820 active studios operate within the country, yet approximately 200 of these entities remain at risk of closure due to project cancellations and workforce reductions, reflecting a broader vulnerability to international market volatility.
Structural challenges persist, particularly regarding the industry's reliance on self-financing and self-publishing models. Most studios operate on a small scale, often managing only one project at a time, which complicates the transition toward complex "games as a service" models. While 53% of companies have begun integrating generative artificial intelligence into their workflows, adoption remains cautious and technically experimental. Furthermore, the industry continues to depend heavily on international sales, which account for 52% of revenue, highlighting a need for stronger domestic investment ecosystems and more robust collaboration with international platforms to retain intellectual property within Spain.
To ensure long-term competitiveness, the sector requires a strategic shift toward institutional support. Key priorities include the implementation of targeted tax incentives, the consolidation of public funding, and improved professional training programs to address the persistent shortage of experienced talent in programming and design. By fostering a more sustainable financial environment and bridging the gap between small-scale production and global market demands, the industry aims to transition from a fragmented landscape of small studios to a more scalable, technologically advanced, and strategically recognized pillar of the Spanish economy.
- The Spanish video game industry generated €1,464 million in turnover and supports over 10,500 direct jobs, with Catalonia and Madrid acting as the primary development hubs.
- Approximately 200 of the 820 active studios are currently at risk of closure due to project cancellations and workforce reductions, signaling significant vulnerability to international market volatility.
- While 72% of studios have been operational for over five years, the industry faces a growth slowdown and a structural reliance on self-financing and single-project development models.
- International sales account for 52% of total revenue, underscoring a critical need for stronger domestic investment and strategies to retain intellectual property within Spain.
- 53% of Spanish studios have begun integrating generative artificial intelligence into their workflows, though current adoption remains in an experimental and cautious phase.
+2
Asociación Española de Empresas Productoras y Desarrolladoras de Videojuegos
Report38 pages
Libro Blanco del Desarrollo Español de Videojuegos 2025
The Spanish video game industry serves as a critical engine for national innovation, currently comprising 820 studios that generate 1,464 million euros in annual revenue and employ over 10,500 professionals. Despite this robust footprint, the sector faces a period of significant volatility, with nearly half of all studios reporting negative impacts from the current economic climate, including project cancellations and workforce reductions. While the industry remains characterized by a highly educated, young workforce and a strong specialization in PC development via the Unity engine, the reliance on internal self-financing remains a structural vulnerability that hinders the scaling of larger, more sustainable AAA projects.
Human talent remains the primary driver of the industry, even as the integration of generative artificial intelligence becomes more prevalent. Although 53 percent of studios have adopted AI tools, widespread skepticism regarding their reliability persists, reinforcing the necessity of human expertise in programming and design. The industry is currently navigating a transition where the ease of hiring has improved, yet the demand for experienced, specialized talent remains unmet. To address these challenges, the sector is prioritizing the retention of intellectual property and economic value within Spain, aiming to shift away from a reliance on international operators toward a more self-sustaining national ecosystem.
Strategic efforts are now focused on securing legislative recognition to integrate game development into national audiovisual tax incentive programs. By fostering a coalition of developers, technology partners, and academic institutions, the industry is implementing a roadmap through 2026 that emphasizes international promotion and professional networking. These initiatives are designed to mitigate the current crisis by expanding public funding and creating a more favorable investment climate, ultimately ensuring that the Spanish gaming sector can compete effectively on the global stage while maintaining its long-term economic viability.
- The Spanish video game industry comprises 820 studios generating 1,464 million euros in annual revenue and employing over 10,500 professionals.
- Nearly 50% of studios report negative economic impacts, including project cancellations and workforce reductions, highlighting a vulnerability caused by a reliance on internal self-financing.
- The industry is lobbying for legislative changes to integrate game development into national audiovisual tax incentive programs to improve investment and long-term sustainability.
- While 53% of studios have adopted generative AI, widespread skepticism regarding tool reliability maintains a strong reliance on human expertise in programming and design.
- The sector is executing a strategic roadmap through 2026 focused on international promotion, professional networking, and retaining intellectual property within Spain.
+2
Asociación Española de Empresas Productoras y Desarrolladoras de Videojuegos
Report29 pages
Gaming Report 2026: Choose Your Player
The leadership team of Bain & Company's Global Gaming Sector practice prepared this report, with special direction from Anders Christofferson, partner and Global Gaming Sector lead, and Brandon Rogers, Media practice manager. The authors would like to thank Danielle Schwenker, Aman Sharma, Gunjan Dawar, Shray Arora, Rohan Doomra, Shagun Jain, and Christoffer Karlsmose for their contributions to this work.
- The gaming market has shifted from a supply-constrained environment to one of infinite choice, where success now requires deep engagement with specific player segments rather than broad, unfocused appeal.
- Focused games—those designed for a specific, identifiable audience—achieved an 83% commercial success rate, significantly outperforming the 50% success rate of unfocused titles.
- Player preferences are highly fragmented, with no single experience type (such as story-driven, sandbox, or multiplayer) capturing more than 26% of the market, and two-thirds of gamers preferring to stick to familiar franchises or existing habits.
- Nearly half of all gamers now purchase content directly from developer web stores at least once a year, and 75% of top-grossing mobile games currently operate their own direct-to-consumer storefronts, up from just 12% in 2019.
- Studios should adopt AI-driven, real-time personalization—specifically contextual bandit algorithms—to optimize individual player experiences, as the highest-spending segment of the market accounts for approximately 75% of total gaming revenue.
+2
Bain & Company
Report72 pages
Cyprus Video Game Industry Report 2025
Cyprus has emerged as the world’s most efficient video game development ecosystem, functioning as a critical hub within the $263.7 billion global gaming market. By 2025, the island’s industry comprised over 400 companies and a workforce exceeding 4,300 employees, contributing approximately €1.15 billion directly to the national GDP. This rapid expansion, which saw the number of firms more than double between 2019 and 2024, is underpinned by a mobile-first strategy, a favorable IP Box tax regime, and a high concentration of mobile game installs per capita. Despite its small population, Cyprus ranks third globally in mobile downloads and eleventh in mobile in-app revenue, reflecting a mature, export-oriented sector.
The ecosystem’s financial health is characterized by significant capital activity, including €2.76 billion in M&A and €137 million in equity funding between 2020 and 2025. A unique feature of this landscape is the prevalence of user-acquisition financing, which provided €128.3 million in non-dilutive capital in 2025, allowing studios to maintain agility. Furthermore, Cyprus-based developers are at the forefront of the industry-wide shift toward direct-to-consumer (D2C) sales models. By bypassing traditional platform fees and securing direct access to player data, these studios have gained a distinct competitive advantage in an increasingly saturated global market that now prioritizes profitability and player relationship management over rapid, unchecked expansion.
Despite these successes, the industry faces structural challenges regarding long-term sustainability. While the tax framework is highly competitive for established studios, there is a notable deficit in dedicated early-stage grants and seed funding for startups. Additionally, the talent pipeline remains a bottleneck; although the nation hosts a large student population, the annual output of graduates specifically trained for game development is insufficient to meet current demand. Future growth will depend on closing these funding and educational gaps, as exemplified by upcoming initiatives like the 2026 Plug&Play accelerator, which aim to solidify Cyprus’s position as a premier global gaming destination.
- By 2025, Cyprus's video game industry became a critical global hub, comprising over 400 companies and 4,300 employees, contributing approximately €1.15 billion directly to the national GDP.
- The industry's rapid expansion, with firms more than doubling between 2019 and 2024, is driven by a mobile-first strategy, a favorable IP Box tax regime, and high mobile game installs per capita.
- Cyprus ranks third globally in mobile downloads and eleventh in mobile in-app revenue, reflecting a mature, export-oriented sector.
- The ecosystem's financial health is strong, with €2.76 billion in M&A and €137 million in equity funding between 2020 and 2025, alongside €128.3 million in user-acquisition financing in 2025.
- Cyprus-based developers are leading the shift to direct-to-consumer (D2C) sales models, gaining competitive advantage by bypassing platform fees and accessing player data.
+1
Cyprus Game Makers Association
Report72 pages
Appendix J: Apple's and Google's Privacy Changes
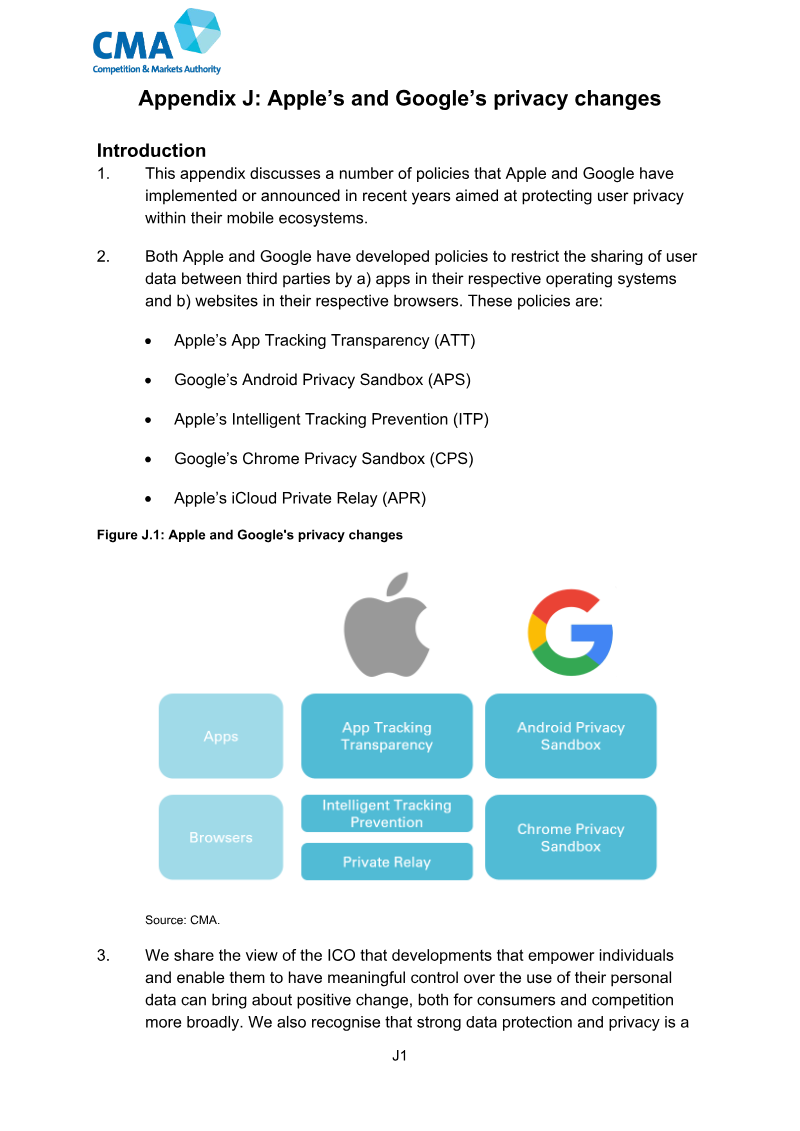
The mobile advertising ecosystem is undergoing a fundamental transformation as Apple and Google implement restrictive privacy frameworks, including App Tracking Transparency, the Privacy Sandbox, and Intelligent Tracking Prevention. While these initiatives provide tangible benefits by enhancing user control over personal data and limiting cross-app tracking, they simultaneously disrupt the technical infrastructure required for third-party ad targeting and attribution. By restricting access to device-level identifiers like IDFA and AdID, these policies have significantly increased costs for developers and reduced the efficacy of digital marketing, forcing a widespread shift in advertising budgets and monetization strategies across the global mobile industry.
A central concern is that these privacy-centric design choices create competitive imbalances that favor the platforms' own advertising services. Evidence suggests that Apple’s choice architecture—specifically the framing and placement of consent prompts—may leverage behavioral biases to discourage data sharing, while its proprietary attribution tools, such as SKAdNetwork, offer inferior data granularity compared to the insights available to Apple Search Ads. This asymmetry effectively creates a barrier to entry for third-party competitors, potentially consolidating market power within Apple and Google’s ecosystems. Developers report that these constraints not only hinder campaign optimization but also force a reliance on commission-based models that further entrench the platforms' dominance.
Ultimately, the transition toward privacy-first frameworks presents a complex trade-off between individual user protection and market competition. While the policies align with broader regulatory goals regarding data privacy, their implementation risks distorting the digital advertising landscape. The ongoing shift necessitates careful oversight to ensure that privacy-enhancing technologies do not serve as a pretext for self-preferencing or the suppression of competition, as the long-term viability of the app economy depends on maintaining a fair and transparent environment for all participants.
- Apple and Google’s privacy frameworks—including App Tracking Transparency, Privacy Sandbox, and Intelligent Tracking Prevention—have fundamentally disrupted the technical infrastructure for third-party ad targeting and attribution.
- The restriction of device-level identifiers like IDFA and AdID has increased costs for developers while simultaneously reducing the efficacy of digital marketing campaigns.
- Apple’s proprietary attribution tools, such as SKAdNetwork, provide lower data granularity than the insights available through Apple Search Ads, creating a competitive disadvantage for third-party advertisers.
- The framing and placement of consent prompts by Apple may leverage behavioral biases to discourage data sharing, effectively creating barriers to entry for competitors.
- These privacy-centric policies risk consolidating market power within Apple and Google by forcing developers to rely on the platforms' own advertising services and commission-based monetization models.
+2
CompetitionAug 2026
Report27 pages
Global DevOps and DataOps Report: Q2 2026
The DevOps and DataOps sectors are undergoing a period of rapid expansion and structural transformation, with the combined market value projected to reach $85 billion by 2031. This growth is fundamentally driven by the rise of AI-native development and the increasing convergence of software and data engineering. As enterprises prioritize large-scale automation, the industry is seeing a surge in transaction activity, which totaled $99.8 billion over the past twelve months—a 2.1x increase year-over-year. Private placements currently dominate this landscape, accounting for 78% of total deal value as capital flows heavily into AI-integrated observability and data-streaming platforms.
Market dynamics reflect a distinct shift in investor sentiment, favoring infrastructure-focused Ops solutions over traditional Dev software. While high growth remains a primary valuation driver, there is a growing emphasis on profitability, particularly among smaller market participants who currently trade at a discount compared to established category leaders. This environment has accelerated strategic consolidation, as major platforms aggressively integrate security, observability, and AI capabilities to maintain competitive advantages.
Global investment activity remains robust, with recent funding rounds pushing valuations for top-tier software delivery and observability platforms as high as $188 billion. These capital inflows are specifically targeted at scaling AI-powered automation and establishing viable alternatives to legacy CI/CD and infrastructure providers. As the sector matures, the focus remains on building resilient, automated ecosystems capable of supporting the complex demands of modern enterprise software and data lifecycles.
- The combined DevOps and DataOps market is projected to reach $85 billion by 2031, fueled by the convergence of software and data engineering alongside AI-native development.
- Transaction activity in the sector reached $99.8 billion over the last twelve months, representing a 2.1x year-over-year increase.
- Private placements dominate the investment landscape, accounting for 78% of total deal value as capital prioritizes AI-integrated observability and data-streaming platforms.
- Valuations for top-tier software delivery and observability platforms have reached as high as $188 billion due to robust global investment activity.
- Investor sentiment has shifted to favor infrastructure-focused Ops solutions over traditional development software, with a new emphasis on profitability for smaller market participants.
+1
Drake Star Partners
Report33 pages
Annual Report of the German Games Industry 2023
The German games industry demonstrated remarkable resilience throughout 2022, maintaining a stable market valuation of 9.87 billion euros despite global economic headwinds, inflationary pressures, and hardware supply constraints. This performance represents a 1% growth rate, bucking international trends of market decline. The sector’s expansion is further evidenced by a 15.5% increase in the number of companies and a 7% rise in the workforce over the past year. Mobile gaming continues to dominate revenue streams, while digital distribution has solidified its position as the primary purchasing method for PC users and younger demographics.
Despite this growth, the industry faces structural challenges that threaten its long-term international competitiveness. A critical shortage of skilled labor in programming, technical art, and production persists, exacerbated by bureaucratic hurdles that impede the recruitment of international talent. Furthermore, the intermittent availability of federal funding has created an environment of instability, hindering strategic planning. To address these issues, the industry is advocating for a transition toward tax-based incentives, improved educational standards, and the establishment of specialized academic institutions to foster domestic expertise.
Beyond economic metrics, the sector is increasingly focused on professionalizing its ecosystem and enhancing its global footprint. Events such as Gamescom and the devcom Developer Conference have reinforced Germany’s status as a central hub for digital innovation, attracting significant international attention and political engagement. Simultaneously, the industry is prioritizing sustainability through climate-neutral initiatives and strengthening youth protection frameworks to ensure a safe gaming environment. By aligning advocacy efforts with a commitment to diversity and educational outreach, the German games sector aims to secure its position as a leading global player in the digital economy.
- The German games market remained resilient in 2022 with a valuation of 9.87 billion euros, achieving 1% growth despite global economic pressures.
- The industry saw significant structural expansion, marked by a 15.5% increase in the number of companies and a 7% rise in the total workforce.
- Mobile gaming remains the primary revenue driver, while digital distribution has become the standard purchasing method for PC users and younger demographics.
- A persistent shortage of skilled labor in programming, technical art, and production is currently hindering the industry's long-term international competitiveness.
- Industry advocates are pushing for a shift from intermittent federal funding to a more stable system of tax-based incentives to improve strategic planning.
+1
game – Verband der deutschen Games-Branche e. V.
Report41 pages
Annual Report of the German Games Industry 2024
The German games industry reached a total revenue of 9.97 billion euros in 2023, marking a 6 percent increase driven largely by hardware sales, mobile gaming, and in-game purchases. Despite this financial expansion and a 52 percent growth in the number of development and publishing companies since 2020, the sector faces a period of cooling optimism. A challenging international economic climate, coupled with the unpredictability of federal funding, has slowed the pace of new company formations and employment growth. While Germany maintains its position as the largest games market in Europe, domestic developers are increasingly disadvantaged by a reliance on fixed-budget funding models that lack the stability of the tax credit systems utilized by international competitors.
To secure long-term competitiveness, the industry is advocating for a transition to a hybrid, tax-based funding model. Strategic priorities for 2024 include the cultivation of a specialized workforce, the integration of gaming into educational frameworks, and the expansion of digital infrastructure. These efforts are complemented by a strong commitment to social and environmental responsibility. A significant majority of companies have adopted sustainability measures, such as transitioning to green energy, while industry-led initiatives continue to promote diversity, combat toxicity, and provide professional support for esports athletes through structured talent development programs.
The industry’s cultural and economic influence remains anchored by the global success of gamescom, which continues to expand its international footprint through satellite events in Singapore and Brazil. Furthermore, the sector is prioritizing rigorous youth protection standards and the promotion of games as essential cultural and educational tools. By balancing these community-focused initiatives with a push for more consistent federal policy, the German games industry aims to solidify its status as a premier global hub for development, innovation, and esports, ensuring both economic resilience and social sustainability in an evolving digital landscape.
- The German games industry generated 9.97 billion euros in revenue in 2023, representing a 6 percent year-over-year increase driven by hardware, mobile gaming, and in-game purchases.
- While the number of development and publishing companies has grown by 52 percent since 2020, the sector is experiencing a slowdown in new company formations and employment growth due to economic instability and unpredictable federal funding.
- Industry stakeholders are advocating for a shift from fixed-budget funding to a hybrid, tax-based model to remain competitive against international rivals who benefit from more stable tax credit systems.
- Germany remains the largest games market in Europe, with its global influence bolstered by the international expansion of the gamescom event into markets like Singapore and Brazil.
- Strategic priorities for 2024 include workforce development, the integration of gaming into educational frameworks, and the improvement of digital infrastructure.
+1
game – Verband der deutschen Games-Branche e. V.
Report14 pages
Medium-Term Vision: Our Growth Strategy in the We-Time Economy
The We-Time Economy serves as the central strategic framework for future growth, predicated on the belief that artificial intelligence will increase leisure time and heighten the value of shared, trust-based human experiences. By facilitating social interaction through digital platforms and services, the organization aims to capture a significant portion of a global market estimated at US$10–15 trillion. The core thesis posits that shared emotional experiences—ranging from social betting and sports entertainment to family-oriented digital products—create high-retention, high-profitability ecosystems that rely on word-of-mouth growth and community engagement.
Financial targets for the medium term include doubling net sales to 300 billion yen, with a specific focus on scaling the sports and lifestyle segments. To achieve these objectives, the company is implementing a rigorous business portfolio management strategy. This involves classifying business units based on growth potential and profitability relative to a 6.18% weighted average cost of capital. Resources are dynamically allocated to high-growth areas, while underperforming units are subject to restructuring or divestment. Key growth drivers include the global expansion of social betting through PointsBet, the scaling of the FamilyAlbum economic sphere, and the continued monetization of domestic intellectual property like MONSTER STRIKE.
Operational efficiency and shareholder value are prioritized through a commitment to raising the EBITDA margin to 20% and the return on equity (ROE) to 15%. Governance reforms, including the appointment of independent directors to lead compensation committees and the alignment of executive incentives with long-term performance, support these financial goals. The company has also committed to a more robust shareholder return policy, targeting a 40% dividend payout ratio to reflect its transition into a sustained profit growth phase.
- The company aims to double net sales to 300 billion yen by focusing on the 'We-Time Economy,' a strategy targeting a global market estimated at US$10–15 trillion.
- Financial performance targets include achieving a 20% EBITDA margin and a 15% return on equity (ROE).
- Capital allocation is governed by a strict portfolio management strategy that evaluates business units against a 6.18% weighted average cost of capital, leading to the restructuring or divestment of underperforming assets.
- Key growth drivers include the global expansion of social betting via PointsBet, the scaling of the FamilyAlbum ecosystem, and the continued monetization of the MONSTER STRIKE intellectual property.
- The company has established a new shareholder return policy targeting a 40% dividend payout ratio to reflect its transition into a phase of sustained profit growth.
mixi
Report17 pages
The Future of Gaming Infrastructure: 2026-2028
The gaming industry is currently undergoing a critical architectural transition as live-service titles face a trilemma of escalating operational demands: the need for sub-10ms AI-driven decision-making, strict regulatory compliance, and rising cloud egress costs. The primary thesis is that legacy, fragmented backend architectures—which rely on separate databases, caches, and search layers—are no longer capable of supporting modern, high-velocity live-ops. To remain competitive, studios must shift toward unified, AI-native data planes that co-locate compute and data to ensure deterministic performance.
Key findings indicate that optimizing real-time matchmaking through low-latency infrastructure can drive a 4% to 15% uplift in player retention. However, achieving this requires moving away from asynchronous batch processing toward millisecond-level inference. This shift is further necessitated by the 2027 EU Data Act, which mandates the removal of cloud switching fees, and the EU AI Act, which classifies algorithmic matchmaking and personalization as high-risk systems requiring transparency, explainability, and immutable audit logs. Currently, only 5% of studios successfully implement player-facing AI, largely due to the latency bottlenecks inherent in traditional, multi-hop network architectures.
The industry is responding by adopting hybrid deployment models that combine self-hosted infrastructure with cloud resources to stabilize operating margins against unpredictable egress fees. By collapsing fragmented stacks into a single, coherent execution layer, studios can eliminate redundant systems and network round-trips. This consolidation allows for atomic, event-driven transactions that satisfy both performance requirements and emerging regulatory mandates.
Spanning the 2026–2028 period, this analysis highlights a fundamental shift in infrastructure strategy. As decision-making complexity grows—with matchmaking engines now processing hundreds of thousands of micro-decisions per second—the ability to execute logic directly on the data plane has become a primary competitive advantage. Studios that fail to modernize their backends risk both top-line revenue losses from poor engagement and bottom-line margin erosion caused by inefficient, legacy cloud consumption.
- Studios must transition from fragmented legacy backends to unified, AI-native data planes that co-locate compute and data to overcome latency bottlenecks and support high-velocity live-ops.
- Optimizing real-time matchmaking through low-latency infrastructure can increase player retention by 4% to 15%.
- Regulatory compliance with the 2027 EU Data Act and EU AI Act requires studios to implement immutable audit logs and transparent, explainable algorithmic systems for matchmaking and personalization.
- Only 5% of studios currently implement player-facing AI successfully, primarily due to latency issues caused by traditional, multi-hop network architectures.
- To stabilize operating margins against rising cloud egress costs, studios are increasingly adopting hybrid deployment models that combine self-hosted infrastructure with cloud resources.
+2
InvestGame
Report9 pages
Ramadan App Trends Decoded: Benchmarks and Insights for 2026
This analysis examines mobile app performance trends during the 2025 Ramadan season to provide strategic benchmarks for 2026. By tracking installs, session counts, and session lengths across seven key verticals—including e-commerce, finance, gaming, and social—the findings highlight how shifting consumer routines during the fasting period and Eid al-Fitr create distinct opportunities for user acquisition and engagement. The scope covers global data with a specific focus on the METAP region, encompassing 22 countries such as Saudi Arabia, Indonesia, Pakistan, and the UAE.
Data indicates that Ramadan acts as a significant driver of mobile activity, with average daily installs in the METAP region rising 11% during the month compared to the preceding two weeks. Session counts also saw a 6% increase during the period. Engagement patterns varied by vertical; gaming and social apps emerged as primary drivers of session growth, while e-commerce experienced significant spikes in specific markets like Pakistan and the UAE. Notably, session lengths for gaming apps remained the longest across all regions, averaging 35.6 minutes during Ramadan.
The analysis emphasizes that Ramadan should be treated as a phased growth cycle rather than a single peak. While overall install growth reached 10% during Ramadan and climbed to 13% in the post-Eid period, performance varied significantly by country and category. The findings suggest that marketers should avoid uniform regional strategies, instead utilizing country-level benchmarks to guide budget allocation. Success during this season requires sustained, conversion-focused activity that extends through Eid al-Fitr, alongside a focus on high-intent engagement windows, particularly during late-night hours, to maximize user retention and long-term loyalty.
- Ramadan drives a 11% increase in average daily installs and a 6% rise in session counts across the METAP region compared to the two weeks prior.
- Gaming apps maintain the highest engagement levels during the season, with average session lengths reaching 35.6 minutes.
- The Ramadan growth cycle extends beyond the fasting period, with overall install growth climbing from 10% during Ramadan to 13% in the post-Eid period.
- Marketers should avoid uniform regional strategies, as performance metrics for categories like e-commerce vary significantly by specific markets such as Pakistan and the UAE.
- To maximize long-term loyalty, campaigns should prioritize conversion-focused activity during late-night hours and maintain engagement through the Eid al-Fitr period.
+2
Adjust
Report37 pages
The Shopping App Insights Report: 2025 Edition
The global e-commerce landscape, currently valued at $6.42 trillion, is undergoing a significant transformation as marketers navigate economic volatility and evolving consumer expectations. While the first half of 2025 saw a 14% year-over-year decline in total app installs, session growth remains resilient, signaling a shift toward deeper engagement rather than mere acquisition volume. Success in this environment requires a transition from broad-reach tactics to sophisticated, omnichannel strategies that leverage artificial intelligence for hyper-personalization and predictive modeling.
Performance data from the first half of 2025 reveals a strategic pivot toward paid user acquisition and re-engagement, with the global reattribution share rising to 0.18 and the paid-to-organic ratio climbing to 0.54. Regional performance is increasingly polarized; while Thailand and Brazil have emerged as high-growth markets, other regions like the UAE and Saudi Arabia have experienced notable contractions. Marketplace apps continue to lead in session volume, yet dedicated shopping apps maintain a stronger hold on new install acquisition.
Despite competitive engagement metrics, the industry faces challenges with a 13% decline in day-one retention and rising costs per install. To counter these trends, developers are diversifying partner ecosystems and utilizing tools such as deep linking and smart banners to reduce friction in the user journey. Sustainable growth now depends on prioritizing long-term retention through data-driven, localized experiences rather than relying on seasonal traffic spikes. By integrating AI-powered measurement and analytics, businesses can better optimize their return on investment and maintain a competitive edge in a privacy-first, global marketplace.
- Global e-commerce app installs declined 14% year-over-year in H1 2025, though sessions grew by 2%, indicating a shift toward re-engaging existing users over new acquisition.
- Global reattribution share for e-commerce apps rose to 0.18 in H1 2025, up from 0.14 in 2023, with the UAE (0.40) and U.K. & Ireland (0.36) leading in win-back activity.
- Global e-commerce app install per mille (IPM) reached nearly 3.0 in Q1 2025, with North America maintaining the highest regional performance at 5.21.
- External economic factors, such as U.S. tariffs introduced in May 2025, prompted 68% of marketers to adjust holiday strategies, including frontloading consumer purchases to early summer.
- LATAM emerged as a growth outlier in H1 2025, recording an 18% increase in installs and a 27% increase in sessions compared to the previous year.
+3
Adjust
Report35 pages
The Gaming App Insights Report: 2026 Edition
The mobile gaming industry is undergoing a fundamental strategic transition, moving away from a reliance on high-volume user acquisition toward a model centered on long-term retention and high-value player engagement. This shift is driven by a challenging economic environment characterized by a 33% increase in global cost-per-click and a 30% rise in cost-per-install throughout 2025. To mitigate these rising expenses, studios are consolidating their marketing efforts, reducing the average number of advertising partners per application to focus on high-performing channels that promise superior return on investment.
Technological innovation serves as a primary lever for this transformation, with generative artificial intelligence and machine learning now integral to creative production and audience targeting. These tools allow developers to optimize ad performance and refine engagement tactics in an era where data privacy remains a critical factor. Notably, App Tracking Transparency opt-in rates on iOS reached 39% in early 2026, providing studios with more reliable data to fuel their direct-to-consumer strategies. This data-driven approach is increasingly vital as the industry seeks to balance the dominance of hyper-casual titles, which still account for 29.1% of installs, with the superior session-to-install ratios found in action and puzzle genres.
The global landscape reflects a maturing market where session lengths and day-1 retention rates remain stable despite the broader cost pressures. While hyper-casual games maintain the largest share of installs, the industry is clearly pivoting toward hybrid monetization and cross-platform experiences to sustain growth. By prioritizing long-term progression over rapid acquisition, developers are successfully navigating a period of rising costs, ensuring that engagement remains robust even as the industry shifts toward more sustainable, value-based growth models.
- Global gaming app CPC rose 33% from $0.03 to $0.04 between 2024 and 2025, while global CPM increased 20% from $3.63 to $4.34.
- Hyper-casual games maintained the largest market share of installs at 29.1% in 2025, while action games dominated session share at 17.1%.
- Strategy games saw the most significant increase in session length, growing 18% to 37.51 minutes, and experienced a 133% surge in CPC from $0.03 to $0.07.
- Over 90% of game developers now utilize AI to automate and streamline core production tasks, including playtesting, localization, and game balancing.
- North America recorded the highest regional CPC at $0.12 in 2025, representing a 71% increase, with the U.S. market specifically rising 86% to $0.13.
+3
Adjust