The Catch Up
The latest reports and industry news, in one place — filter to see just what you want.
Financial9 pages
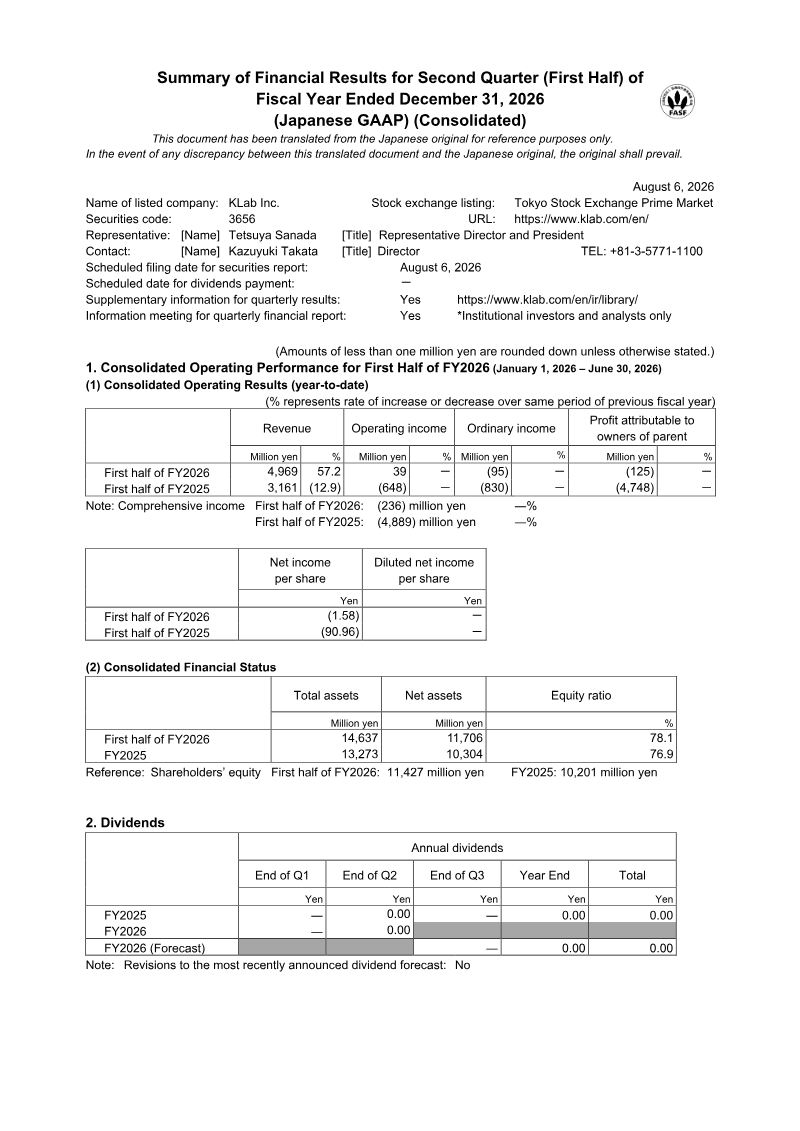
Summary of Financial Results for Second Quarter: Fiscal Year Ended December 31, 2026
KLab Inc.’s financial results for the first half of the fiscal year ending December 31, 2026, indicate a significant recovery in operating performance compared to the same period in the previous year. The company reported consolidated revenue of 4,969 million yen, representing a 57.2% increase over the first half of 2025. Operating income reached 39 million yen, a notable improvement from the 648 million yen operating loss recorded in the prior year’s first half. Despite these gains, the company remained in a net loss position, reporting a loss attributable to owners of the parent of 125 million yen, though this is a substantial reduction from the 4,748 million yen loss incurred during the first half of 2025.
The company’s financial position remains stable, with total assets increasing to 14,637 million yen as of June 30, 2026, compared to 13,273 million yen at the end of 2025. The equity ratio stands at 78.1%, reflecting a slight increase from 76.9% at the end of the previous fiscal year. The primary business segment, the Game Business, generated 4,551 million yen in revenue, with a segment profit of 1,614 million yen. The company has maintained its full-year earnings forecast for 2026, projecting total revenue of 17,000 million yen and an operating income of 1,000 million yen.
These results were prepared in accordance with Japanese GAAP and cover the consolidated operations of KLab Inc. for the period from January 1, 2026, to June 30, 2026. The financial statements reflect the impact of crypto asset valuation losses and foreign exchange fluctuations, while benefiting from the absence of the significant impairment losses on fixed assets that heavily impacted the previous year’s performance. No changes to accounting policies or significant shifts in the scope of consolidation were reported for this period.
- KLab Inc. achieved a 57.2% year-over-year revenue increase for H1 2026, reaching 4,969 million yen.
- Operating performance improved significantly, moving from a 648 million yen loss in H1 2025 to an operating profit of 39 million yen in H1 2026.
- The net loss attributable to owners of the parent was reduced to 125 million yen, down from 4,748 million yen in the same period last year.
- The core Game Business segment generated 4,551 million yen in revenue and 1,614 million yen in segment profit during the first half of 2026.
- KLab maintained its full-year 2026 forecast, targeting 17,000 million yen in total revenue and 1,000 million yen in operating income.
Report29 pages
Gaming Report 2026: Choose Your Player
The leadership team of Bain & Company's Global Gaming Sector practice prepared this report, with special direction from Anders Christofferson, partner and Global Gaming Sector lead, and Brandon Rogers, Media practice manager. The authors would like to thank Danielle Schwenker, Aman Sharma, Gunjan Dawar, Shray Arora, Rohan Doomra, Shagun Jain, and Christoffer Karlsmose for their contributions to this work.
- The gaming market has shifted from a supply-constrained environment to one of infinite choice, where success now requires deep engagement with specific player segments rather than broad, unfocused appeal.
- Focused games—those designed for a specific, identifiable audience—achieved an 83% commercial success rate, significantly outperforming the 50% success rate of unfocused titles.
- Player preferences are highly fragmented, with no single experience type (such as story-driven, sandbox, or multiplayer) capturing more than 26% of the market, and two-thirds of gamers preferring to stick to familiar franchises or existing habits.
- Nearly half of all gamers now purchase content directly from developer web stores at least once a year, and 75% of top-grossing mobile games currently operate their own direct-to-consumer storefronts, up from just 12% in 2019.
- Studios should adopt AI-driven, real-time personalization—specifically contextual bandit algorithms—to optimize individual player experiences, as the highest-spending segment of the market accounts for approximately 75% of total gaming revenue.
+2
Financial25 pages
H1 2026 Earnings
The CD PROJEKT RED Group H1 2026 earnings report outlines the company’s financial performance and strategic roadmap, emphasizing the continued commercial success of its two primary intellectual properties: The Witcher and Cyberpunk 2077. The company reports a strong financial position, characterized by a 23% increase in sales revenue compared to the first half of 2025, reaching 435 million PLN. Net profit from continuing operations rose by 37% to 249 million PLN, reflecting a net profitability margin of 57.2%.
Key operational highlights include the sustained lifecycle performance of Cyberpunk 2077, which has reached 40 million units sold, alongside 15 million copies of the Phantom Liberty expansion. The Witcher franchise remains a cornerstone of the company’s portfolio, with 90 million total units sold across the series, including 65 million for The Witcher 3: Wild Hunt. The company is actively expanding its IP through licensing agreements for trading card games and the upcoming return of the Edgerunners animated series.
Development efforts are heavily focused on the future of The Witcher franchise, with a commitment to releasing a major title annually through 2028, starting with The Witcher 3: Wild Hunt Remastered in late 2026. As of July 2026, the company’s development headcount reached 1,045, with the largest portion of staff dedicated to the next installment of The Witcher. Financial data indicates a significant increase in capitalized development expenditures, which grew by 32% to over 1.5 billion PLN, signaling substantial ongoing investment in the company’s future product pipeline. The report concludes by reinforcing the company's focus on long-term franchise growth and operational efficiency.
- CD PROJEKT RED reported strong H1 2026 financial growth with sales revenue reaching 435 million PLN, a 23% increase over H1 2025.
- Net profit from continuing operations rose 37% to 249 million PLN, resulting in a high net profitability margin of 57.2%.
- Capitalized development expenditures grew by 32% to over 1.5 billion PLN, reflecting heavy investment in the upcoming product pipeline.
- The Witcher franchise has reached 90 million total units sold, while Cyberpunk 2077 has achieved 40 million units sold alongside 15 million copies of the Phantom Liberty expansion.
- The company plans to release a major Witcher title annually through 2028, beginning with The Witcher 3: Wild Hunt Remastered in late 2026.
+2
Financial10 pages
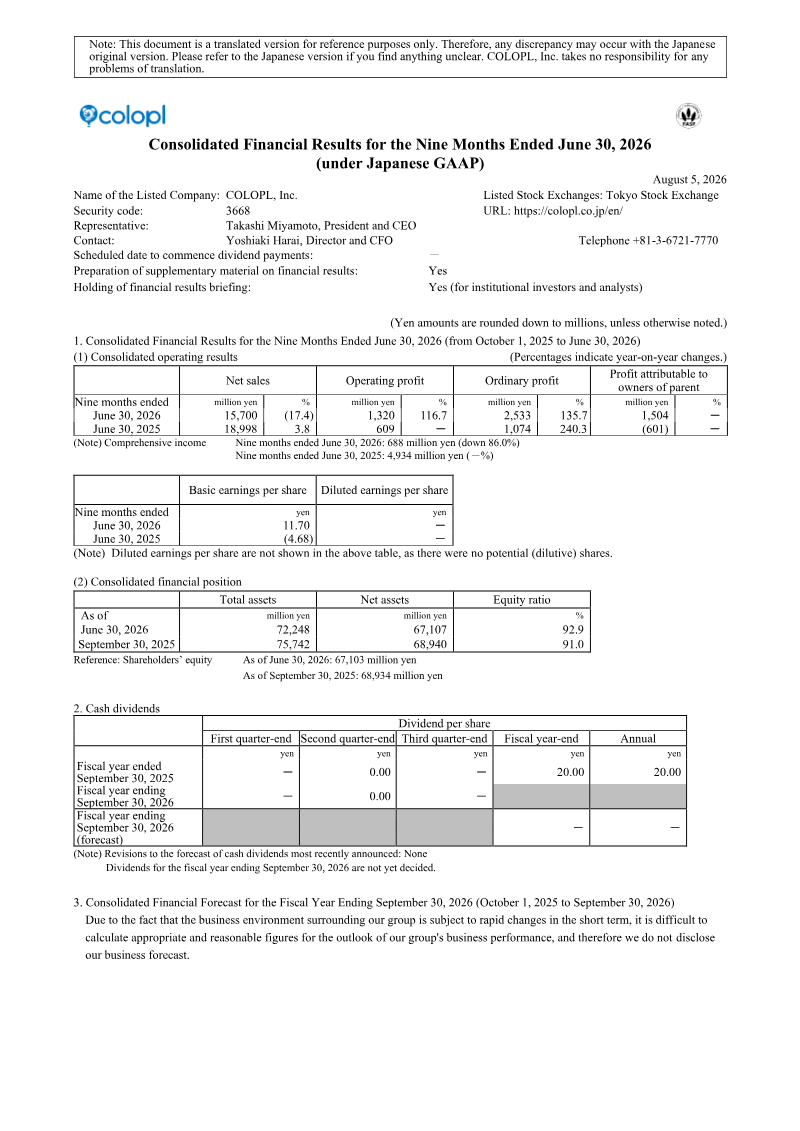
Consolidated Financial Results for the Nine Months Ended June 30, 2026: Japan
COLOPL, Inc. reported its consolidated financial results for the nine-month period ending June 30, 2026, reflecting a strategic shift toward cost optimization and improved profitability despite a decline in top-line revenue. The company operates primarily within the Japanese entertainment and investment sectors, focusing on smartphone game development and IT-related investments.
Financial performance for the period showed net sales of 15,700 million yen, a 17.4% decrease compared to the same period in the previous year. Despite this revenue contraction, the company achieved a significant turnaround in profitability, with operating profit rising 116.7% to 1,320 million yen and ordinary profit increasing 135.7% to 2,533 million yen. Profit attributable to owners of the parent reached 1,504 million yen, recovering from a 601 million yen loss in the prior year. This improved bottom-line performance was largely driven by a group-wide reduction in advertising and operational expenses within the Entertainment Business, which offset the impact of declining sales from legacy titles.
The Entertainment Business, anchored by the title Dragon Quest Walk, generated 14,676 million yen in sales. Meanwhile, the Investment and Development Business recorded 1,023 million yen in sales, a 52.2% decline attributed to the absence of large-scale deals that occurred in the previous year and the recognition of impairment losses on certain securities. As of June 30, 2026, the company maintained a strong financial position with total assets of 72,248 million yen and an equity ratio of 92.9%. Due to the volatility of the current business environment, the company has opted not to disclose specific earnings forecasts for the remainder of the fiscal year.
- COLOPL, Inc. achieved a significant profit turnaround for the nine months ending June 30, 2026, reporting a net profit of 1,504 million yen compared to a 601 million yen loss in the same period last year.
- Operating profit surged 116.7% to 1,320 million yen and ordinary profit rose 135.7% to 2,533 million yen, despite a 17.4% decline in net sales to 15,700 million yen.
- Profitability improvements were driven by aggressive cost-cutting measures, specifically a group-wide reduction in advertising and operational expenses within the Entertainment Business.
- The Entertainment Business remains the primary revenue driver, generating 14,676 million yen, largely anchored by the performance of the title Dragon Quest Walk.
- The Investment and Development Business saw a 52.2% revenue decline to 1,023 million yen, impacted by the absence of large-scale deals and the recognition of impairment losses on securities.
+1
Financial38 pages
3Q FY Sep. 2026 Financial Results Presentation: Japan
Financial Results Presentation Note: This document is a translated version for reference purposes only. Therefore, any discrepancy may occur with the Japanese original version. Please refer to the Japanese version if you find anything unclear. COLOPL, Inc. takes no responsibility for any problems of translation.
- COLOPL achieved a financial turnaround in 3Q FY2026, reporting 5.6 billion yen in total sales (up 13.2% YoY) and an operating profit of 0.7 billion yen, compared to an 804 million yen operating loss in the same period last year.
- The Investment and Development business segment saw significant growth, with sales reaching 0.7 billion yen—a 600.2% increase YoY—and contributing 0.3 billion yen to operating profit.
- The core Entertainment business generated 4.8 billion yen in sales, maintaining steady performance with a 0.2% YoY increase, supported by collaboration events for titles like 'Alice Gear Aegis' and 'Quiz RPG: The World of Mystic Wiz'.
- COLOPL announced the upcoming release of a new game, 'Active Cinema RPG 369', and confirmed that a console title, 'Shironeko Project INFINITY', is scheduled for launch in 2027.
- The company reported a net profit of 0.6 billion yen for the quarter, reflecting a net profit margin of 12.1% and a recovery from the 779 million yen net loss recorded in 3Q FY2025.
+1
Financial29 pages
3Q FY Sep. 2026 Financial Results Presentation: Japan
COLOPL’s financial results for the third quarter of the fiscal year ending September 30, 2026, demonstrate a successful turnaround to profitability, driven by robust performance in its core mobile gaming portfolio and strategic exits within its investment arm. The company reported consolidated sales of 5.6 billion yen, representing a 13.2% year-on-year increase, and an operating profit of 0.7 billion yen. This financial recovery was supported by disciplined cost optimization, particularly in advertising expenditures, and significant gains from the secondary sale of shares in an investee company.
The Entertainment Business remains the primary revenue driver, contributing 4.8 billion yen in sales. Performance was bolstered by sustained engagement with major mobile titles, including DRAGON QUEST WALK and Shironeko Project, the latter of which celebrated its 12th anniversary during the quarter. The Investment and Development Business also saw substantial growth, with sales rising by 600.2% year-on-year to 0.7 billion yen, largely due to the divestment of SALOWIN Co., Ltd. The company maintains a strong financial position, characterized by an equity ratio of 92.9% and a stable balance of operational investment securities totaling 8.8 billion yen.
Looking forward, the company is executing a mid-term management strategy aimed at achieving "Global Top 20" status in the mobile game market, targeting 100 billion yen in sales and 50 billion yen in operating profit. Future growth initiatives include the development of new location-based games, the upcoming release of the "Active Cinema RPG 369," and the expansion of its console footprint with the 2027 launch of Shironeko Project INFINITY. Additionally, the company continues to leverage its XR and digital twin technologies through its subsidiary, 360Channel, to diversify its service offerings beyond traditional gaming.
- COLOPL returned to profitability in 3Q FY2026 with 5.6 billion yen in consolidated sales, a 13.2% year-on-year increase, and an operating profit of 0.7 billion yen.
- The Entertainment Business generated 4.8 billion yen in sales, supported by the continued performance of core titles DRAGON QUEST WALK and the 12th-anniversary milestone of Shironeko Project.
- The Investment and Development Business saw a 600.2% year-on-year sales increase to 0.7 billion yen, primarily driven by the divestment of SALOWIN Co., Ltd.
- The company maintains a strong balance sheet with an equity ratio of 92.9% and 8.8 billion yen in operational investment securities.
- COLOPL is targeting long-term growth of 100 billion yen in sales and 50 billion yen in operating profit as part of its 'Global Top 20' mid-term management strategy.
+1
Financial2 pages
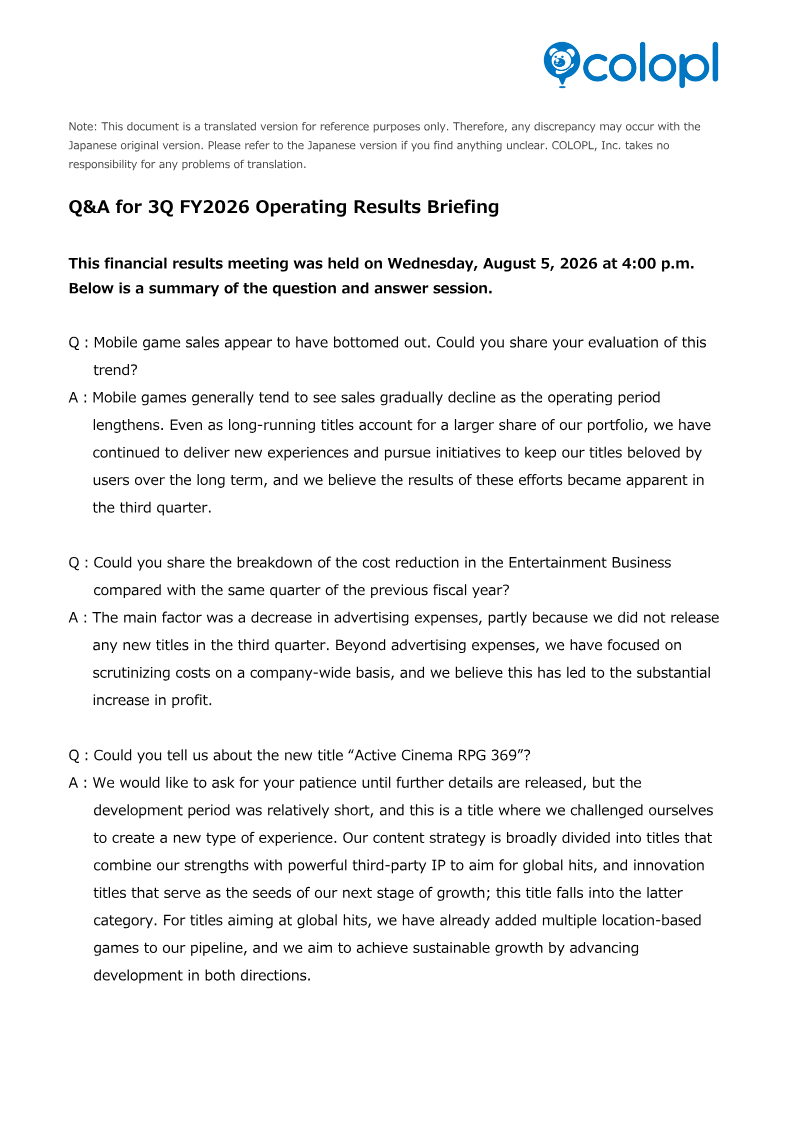
Q&A for 3Q FY2026 Operating Results Briefing
COLOPL’s third-quarter fiscal year 2026 performance reflects a strategic stabilization in mobile game revenue, signaling that long-running titles have successfully reached a performance floor. This trend is attributed to sustained efforts in user engagement and content longevity, which have mitigated the typical revenue decay associated with aging mobile portfolios. Profitability saw a substantial increase during this period, driven primarily by a disciplined reduction in advertising expenditures and a company-wide initiative to scrutinize operational costs. The absence of new title launches in the third quarter further contributed to this lean expenditure profile.
The company’s content strategy is bifurcated into two distinct pillars: leveraging third-party intellectual property for global market penetration and developing innovation-focused titles to serve as future growth catalysts. The upcoming Active Cinema RPG 369 represents the latter category, characterized by a condensed development cycle and an emphasis on experimental gameplay experiences. Simultaneously, the company is expanding its pipeline with multiple location-based games designed to secure sustainable, long-term growth.
Strategic expansion into the console market is also underway, marked by the announcement of Shironeko Project INFINITY. This project represents a departure from simple porting, as the company has invested in a bespoke development approach tailored to console hardware capabilities. Supported by an optimized personnel structure and advancements in development technology, the title is currently slated for a 2027 release. These initiatives collectively underscore a shift toward balancing the maintenance of established mobile assets with targeted investments in new platforms and innovative gaming experiences.
- COLOPL achieved increased profitability in 3Q FY2026 by significantly reducing advertising expenditures and implementing company-wide operational cost controls.
- Mobile game revenue has stabilized as long-running titles reached a performance floor, effectively mitigating typical revenue decay through sustained user engagement.
- The company is developing 'Active Cinema RPG 369,' an experimental title utilizing a condensed development cycle to serve as a future growth catalyst.
- COLOPL is expanding its console presence with 'Shironeko Project INFINITY,' a bespoke title built for console hardware rather than a simple port, scheduled for release in 2027.
- The current content strategy focuses on two pillars: leveraging third-party intellectual property for global reach and developing location-based games for long-term sustainability.
+2
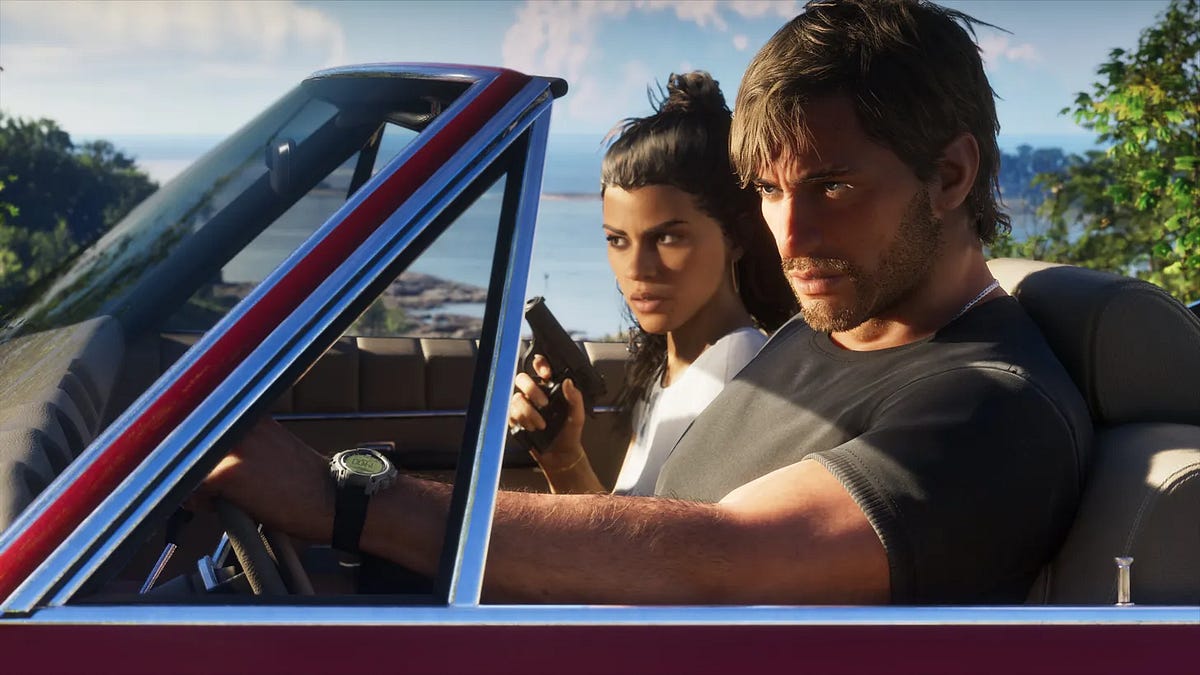
Grand Theft Auto Netflix: The Lukewarm Takes Edition
- The Grand Theft Auto VI reveal on Netflix generated 31.1 million views within four days and reached the top-watched spot in 87 of 93 tracked territories.
- Rockstar Games experienced a 436% surge in pre-orders on August 27, 2026, following the gameplay showcase.
- The reveal event triggered significant hardware demand, resulting in PlayStation 5 Pro shortages across key markets including the UK and Germany.
- Netflix saw a 125% increase in web traffic and a 60-place jump in iOS download rankings directly tied to the partnership.
- Rockstar is expanding its user-generated content ecosystem through a new partnership with nopixel.
- Despite a strong financial position and successful reveal, Rockstar faces ongoing legal challenges regarding a pending employment tribunal over union-busting allegations.
Market AnalysisGlobalStreaming
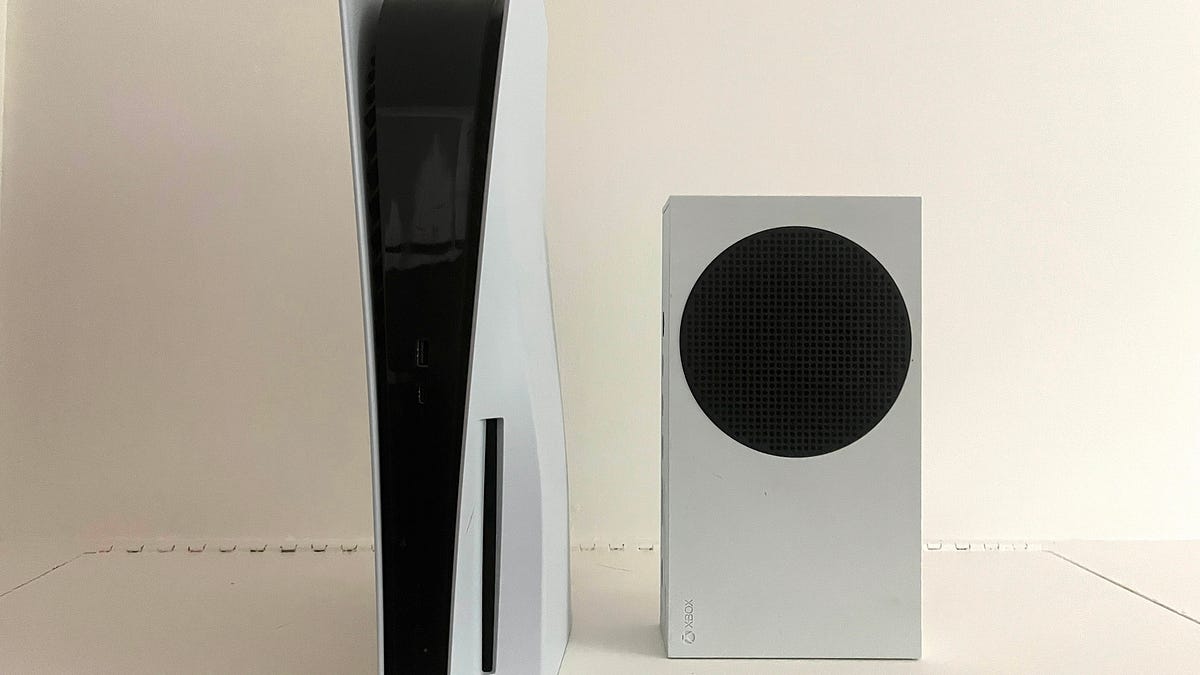
Sony and Microsoft Say They’re Not Obligated to Pass U.S. Tariff Refunds to Consumers
- Sony and Microsoft are defending against class-action lawsuits seeking to force the distribution of U.S. government tariff refunds to consumers following a 2026 Supreme Court ruling that invalidated 2025 console import tariffs.
- Sony expects to recoup approximately $508 million in tariff refunds and argues that it has no legal obligation to reimburse customers who purchased hardware at agreed-upon retail prices.
- Manufacturers contend that pricing is driven by complex variables like inflation, component costs, and competitive dynamics rather than a direct pass-through of tariff expenses.
- Sony cited its continued price increases after the tariffs were ruled illegal as evidence that pricing strategies are not solely dependent on regulatory costs.
- Legal battles involving Sony, Microsoft, and Nintendo are currently ongoing in federal courts across California and Washington.
- Panic, the manufacturer of the Playdate handheld, is the only hardware company to date that has committed to passing tariff refunds on to its consumers.
Market AnalysisUSAGlobal
If It's Not Competitive, the Market Is Too Small
- Market competition is a positive indicator of a large-scale, viable opportunity rather than a deterrent for new founders.
- Founders should prioritize identifying existing, high-value problems where enterprises are already spending significant capital rather than attempting to invent entirely novel concepts.
- Product discovery must be treated as a rigorous sales process that confirms financial commitment, budget ownership, and clear return on investment.
- Competitive advantage should be built through superior sales execution, faster product iteration, and seamless integration with existing enterprise workflows.
- Startups must transition from custom, forward-deployed engineering to standardized, scalable products to avoid the scaling limitations of the 'deploy company' model.
- The most successful AI agents are those designed to interface with enterprise systems and teams in the same manner as human employees to automate high-value tasks.
Market AnalysisGame DevelopmentGame Publishing
Financial1 pages
Financial Report for Fiscal 2026: Bushiroad
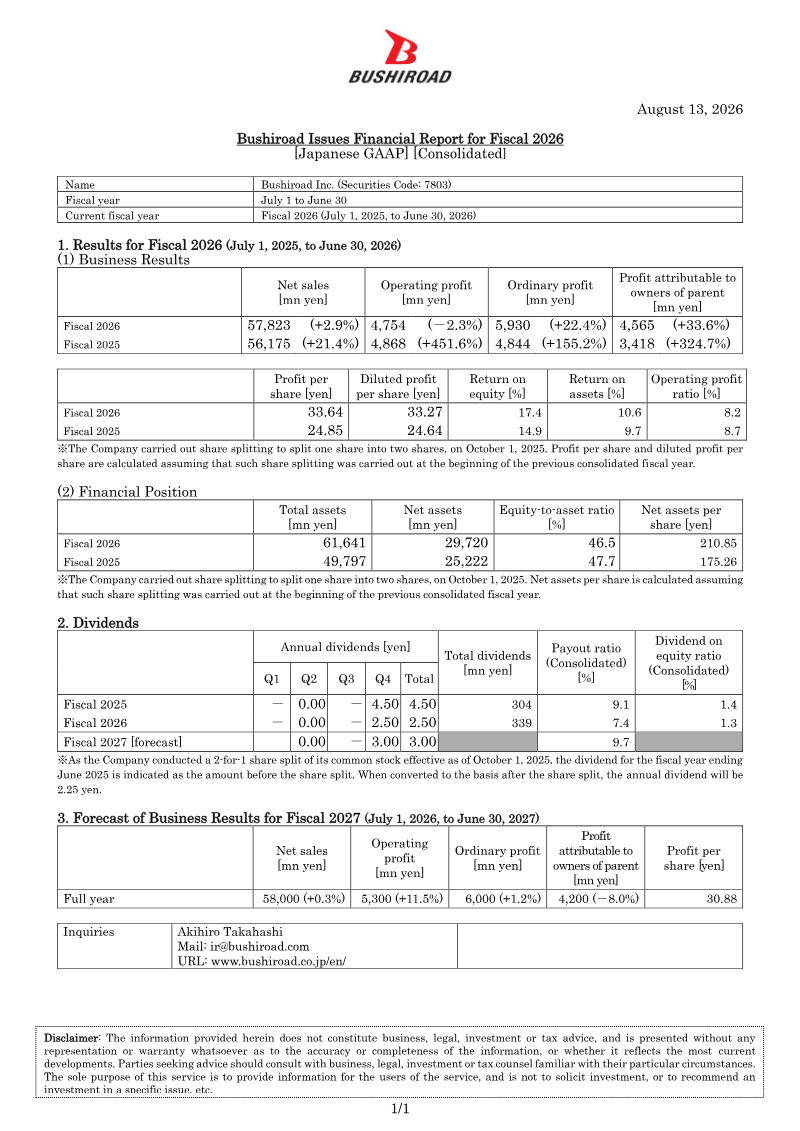
Bushiroad’s financial performance for the fiscal year ending June 30, 2026, reflects steady top-line growth alongside significant improvements in bottom-line profitability. The company achieved net sales of 57,823 million yen, representing a 2.9% increase over the previous fiscal year. While operating profit saw a slight contraction of 2.3% to 4,754 million yen, ordinary profit grew by 22.4% to 5,930 million yen. Most notably, profit attributable to owners of the parent surged by 33.6% to 4,565 million yen, resulting in a profit per share of 33.64 yen.
The company’s financial position strengthened during this period, with total assets rising to 61,641 million yen from 49,797 million yen in the prior year. Net assets also increased to 29,720 million yen, maintaining an equity-to-asset ratio of 46.5%. These results incorporate the impact of a 2-for-1 share split executed on October 1, 2025, which was accounted for in the calculation of per-share metrics to ensure consistency across reporting periods.
Looking ahead to fiscal 2027, the company projects continued stability with forecasted net sales of 58,000 million yen, a marginal increase of 0.3%. Management anticipates an 11.5% rise in operating profit to 5,300 million yen, though profit attributable to owners of the parent is expected to decline by 8.0% to 4,200 million yen. The company remains committed to shareholder returns, projecting an annual dividend of 3.00 yen per share for the upcoming fiscal year, up from the 2.50 yen distributed in fiscal 2026. These figures are prepared in accordance with Japanese GAAP and reflect the consolidated operations of the organization.
- Bushiroad achieved a 33.6% surge in net profit attributable to owners of the parent, reaching 4,565 million yen for the fiscal year ending June 30, 2026.
- Net sales grew by 2.9% year-over-year to 57,823 million yen, while ordinary profit rose by 22.4% to 5,930 million yen.
- The company’s financial position strengthened significantly, with total assets increasing to 61,641 million yen and an equity-to-asset ratio of 46.5%.
- Operating profit experienced a slight contraction of 2.3% to 4,754 million yen during the 2026 fiscal year.
- For fiscal 2027, management forecasts net sales of 58,000 million yen and an 11.5% increase in operating profit to 5,300 million yen.
Financial35 pages
FY2026 Full-Year Financial Results Briefing Material
This document is an excerpt translation of the original Japanese document and is only for reference purposes. In the event of any discrepancy between this translated version and the original Japanese version, the latter shall prevail. For prompt disclosure, this document is translated Japanese to English based on machine translation, and some parts of this document may be written in Japanese or other languages without translation.
- Bushiroad achieved record full-year sales in both the Merchandising (MD) and Media Content business units for FY2026.
- The figure brand 'PalVerse' experienced significant growth across Japan, East Asia, Europe, and North America, becoming a primary driver for the MD business's record-breaking performance.
- Overseas sales reached 11,447 million yen, accounting for 43.4% of total revenue, bolstered by international demand for the English editions of 'Weiβ Schwarz,' 'Cardfight!! Vanguard,' and 'hololive OFFICIAL CARD GAME.'
- The company divested New Japan Pro-Wrestling, which is now a consolidated subsidiary of TV Asahi, while retaining STARDOM to evolve it into a broader 'ultimate live entertainment' brand.
- Bushiroad reported a gain of 1,384 million yen from the sale of shares in affiliated companies, contributing to overall financial results alongside solid performance in core TCG products.
Financial29 pages
Results Presentation: Q1 for the Fiscal Year Ending March 2027
Q1 for the Fiscal Year Ending March 2027 The market forecasts, performance outlooks, plans, strategies, and other forward-looking statements contained in this document are based on information available to the Company and the judgment of its management at the time this material was created. They do not constitute a guarantee of future performance.
- SEGA Sammy reported a strong Q1 FY2027/3 performance, with consolidated sales of 95.0 billion yen and operating income of 2.3 billion yen, exceeding initial expectations across all business segments.
- The Entertainment Contents business saw Q1 catalogue sales reach 9.7 billion yen, driven by the Persona series, with major new titles like 'STRANGER THAN HEAVEN' and 'Persona 4 Revival' scheduled for release from Q3 onward.
- The Pachislot & Pachinko segment performed strongly in Q1, with notable unit sales including 10,400 units for 'Smart Pachislot BIG DREAM THE GOLDEN PUSHER' and 3,400 units for 'A-SLOT+ Isekai Quartet BT'.
- The Gaming business experienced increased sales but a widened operating loss compared to Q1 FY2026/3, primarily due to the consolidation of GAN and Stakelogic into the P&L.
- PARADISE CITY in South Korea reported steady performance with record-high casino drop amounts in May 2026, though equity method earnings decreased due to one-time initial hotel expenses and reduced tax refunds.
+1
Financial6 pages
FY2027/3 Q1 Major Questions Regarding Financial Results
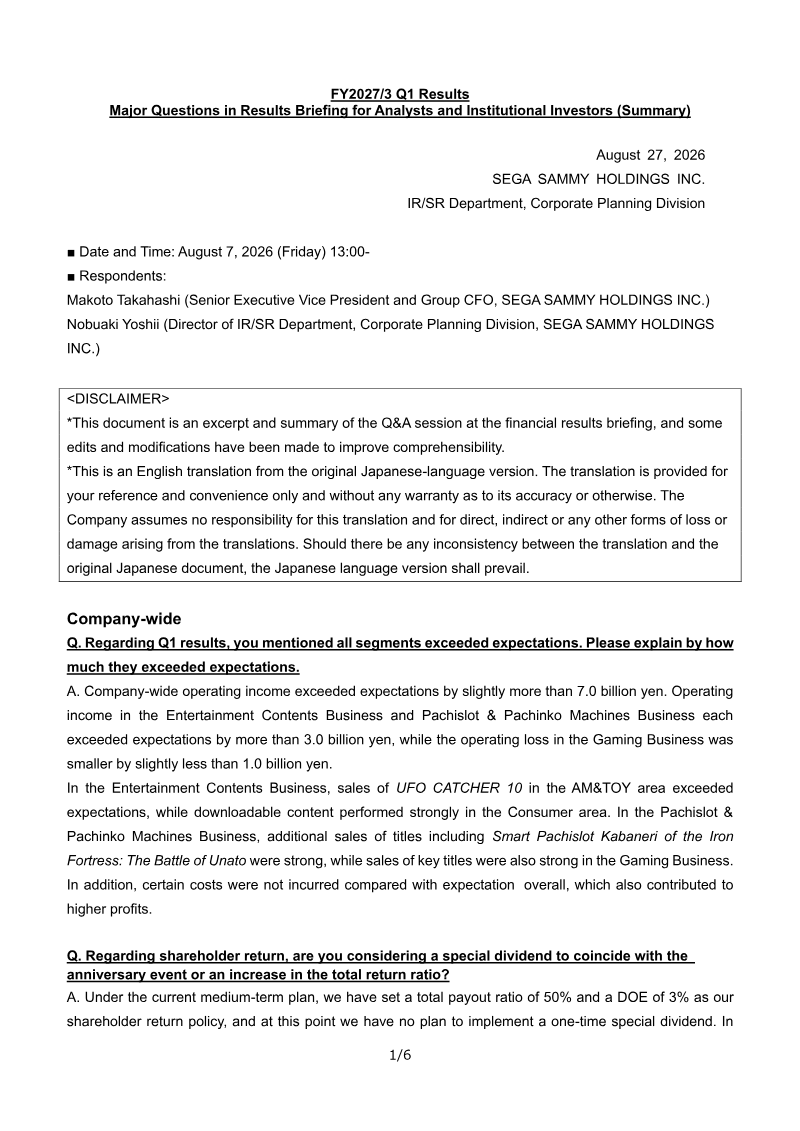
The financial results briefing for the first quarter of the fiscal year ending March 2027 outlines the performance of Sega Sammy Holdings across its core business segments. The primary objective of the session was to address analyst inquiries regarding the company’s financial outperformance, which saw consolidated operating income exceed initial expectations by more than 7.0 billion yen. This growth was driven by strong results in the Entertainment Contents and Pachislot & Pachinko Machines segments, alongside a narrower-than-anticipated operating loss in the Gaming Business.
Key findings indicate that the Entertainment Contents Business benefited from robust sales of arcade hardware and strong performance in downloadable content, despite a year-over-year decline in operating income due to the absence of one-time licensing revenue recorded in the previous year. The company is currently transitioning toward a unified global marketing structure and a simultaneous multi-platform release strategy for new titles. Meanwhile, the Pachislot & Pachinko Machines segment saw improved profit margins attributed to high demand for specific titles and increased sales of reel units. Management noted that while regulatory shifts regarding machine features are unlikely to impact short-term performance, they are expected to support long-term industry revitalization.
The Gaming Business, which operates primarily in the North American market, reported a smaller operating loss than projected, largely due to a higher-than-expected proportion of outright machine sales compared to the anticipated lease-based model. Regarding capital allocation, the company maintains its commitment to a 50% total payout ratio and a 3% dividend on equity (DOE), prioritizing a balance between growth investments and shareholder returns. The company continues to pursue a transmedia strategy, leveraging its intellectual property across games, video adaptations, and merchandise to maximize brand value globally.
- Sega Sammy Holdings exceeded initial Q1 FY2027/3 consolidated operating income expectations by over 7.0 billion yen.
- The Entertainment Contents segment is shifting to a unified global marketing structure and a simultaneous multi-platform release strategy for new titles.
- The Gaming Business in North America outperformed loss projections due to a higher-than-expected volume of outright machine sales rather than the anticipated lease-based model.
- Pachislot & Pachinko segment profit margins increased due to high demand for specific titles and higher sales of reel units, with management viewing regulatory shifts as a long-term industry benefit.
- Entertainment Contents operating income declined year-over-year due to the absence of one-time licensing revenue recorded in the previous fiscal period.
+1
Financial13 pages
Data Appendix: FY2027/3 Q1
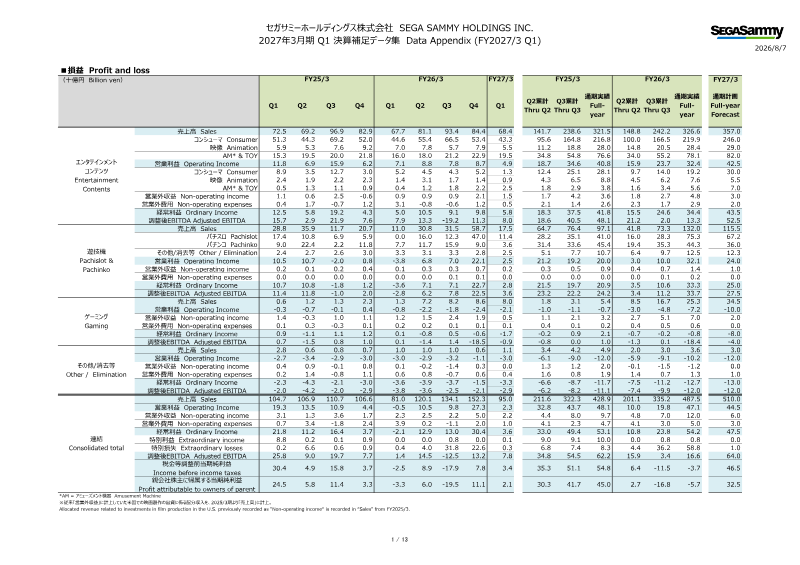
2027年3月期 Q1 決算補足データ集 Data Appendix (FY2027/3 Q1) 2026/8/7 (十億円 Billion yen) FY25/3 FY25/3 FY26/3 FY27/3 FY26/3 FY27/3 Q2累計 Q3累計 通期実績 Q2累計 ...
- Consolidated sales for FY2027/3 Q1 reached 148.8 billion yen, with a full-year forecast of 510.0 billion yen.
- The Consumer segment remains the primary revenue driver, contributing 100.0 billion yen in Q1 sales out of the 148.8 billion yen total.
- Operating income for the consolidated group in Q1 was 10.0 billion yen, significantly trailing the full-year target of 44.5 billion yen.
- Overseas sales remain a critical component of the business, accounting for 85.4% of total sales in Q1, with North America and Europe being the primary geographic markets.
- Paradise Sega Sammy reported Q1 sales of 291.4 billion KRW, with casino operations generating 238.2 billion KRW and attracting 202,000 users.
Financial2 pages
Notice Concerning Finalization of Details of Cash-Settled Forward Transaction Relating to the Company's Own Shares
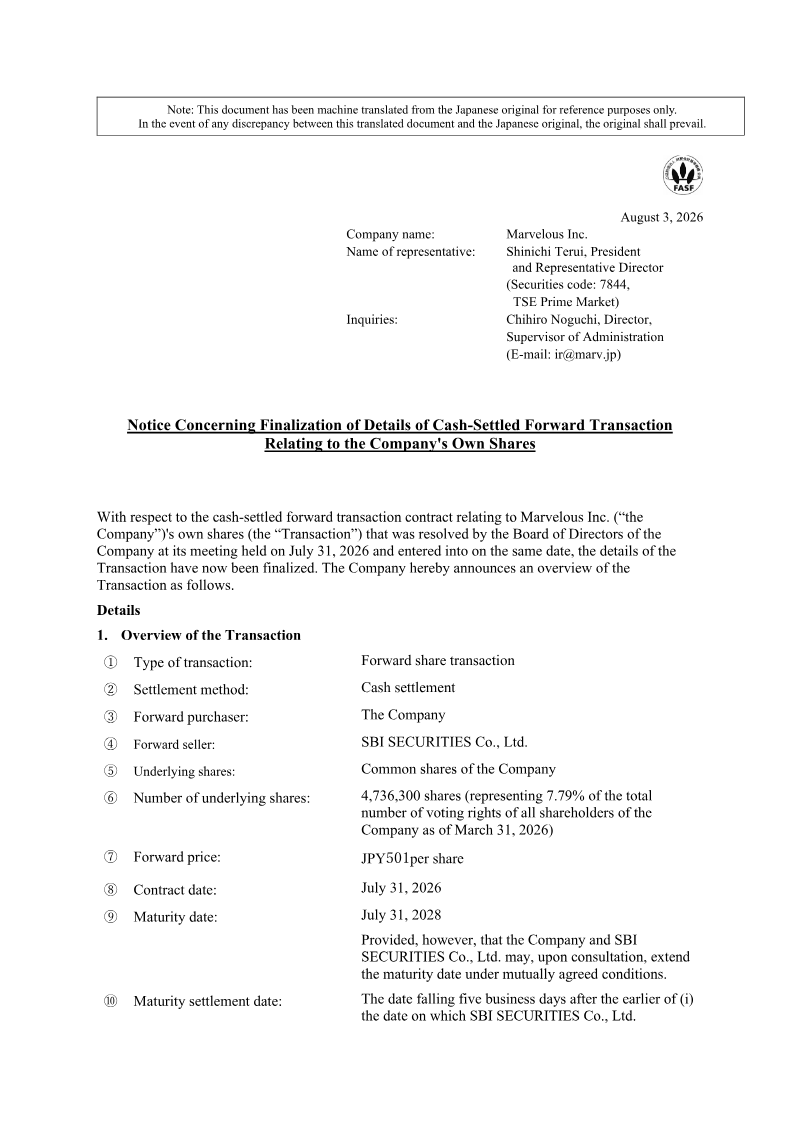
Marvelous Inc. has finalized the terms of a cash-settled forward transaction involving its own common shares, a strategic financial arrangement initially authorized by the Board of Directors on July 31, 2026. This transaction involves a forward contract with SBI SECURITIES Co., Ltd. acting as the forward seller. The agreement covers 4,736,300 underlying shares, which accounts for 7.79% of the company’s total voting rights as of March 31, 2026.
The financial parameters of the agreement establish a forward price of JPY 501 per share. The contract is set to mature on July 31, 2028, though the parties retain the flexibility to extend this date upon mutual consultation. Settlement will be conducted on a cash basis, with the specific maturity settlement date determined by the completion of share sales by the counterparty or through a mark-to-value settlement method, depending on the circumstances at the time of maturity.
This transaction represents a significant capital management initiative for the Tokyo-listed entertainment company. By utilizing a cash-settled forward structure, Marvelous Inc. manages its equity position without immediate physical share transfer, providing a mechanism to influence or hedge its own share value over a two-year horizon. The finalization of these details confirms the operational framework for the transaction, ensuring that the company’s treasury management remains aligned with the previously disclosed board resolutions.
- Marvelous Inc. has finalized a cash-settled forward transaction for 4,736,300 of its own shares, representing 7.79% of the company's total voting rights as of March 31, 2026.
- The transaction is structured with SBI SECURITIES Co., Ltd. acting as the forward seller at a fixed price of JPY 501 per share.
- The contract is scheduled to mature on July 31, 2028, with provisions allowing for a potential extension upon mutual agreement between the parties.
- Settlement will be conducted on a cash basis, utilizing either mark-to-value methods or proceeds from the counterparty's share sales at the time of maturity.
- This financial arrangement serves as a strategic capital management tool, allowing the company to hedge or influence its share value without an immediate physical transfer of equity.
Financial1 pages
Notice Regarding Completion of Cancellation of Treasury Shares: Japan
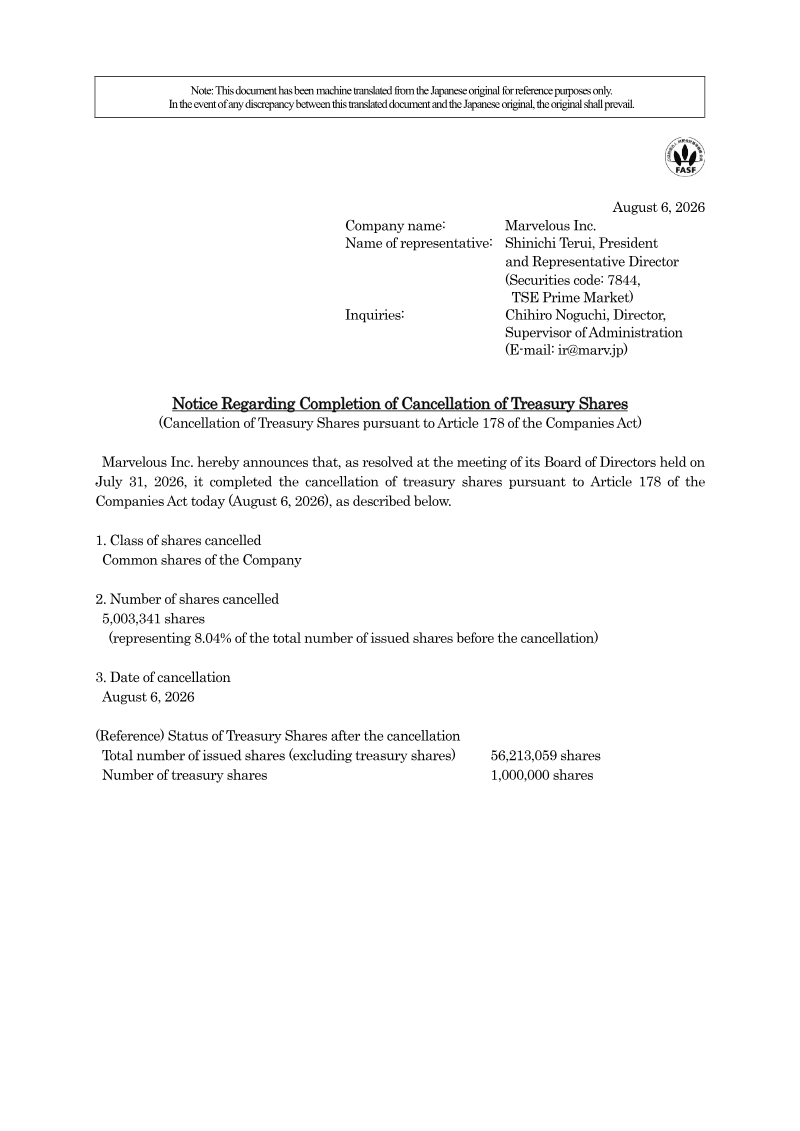
Marvelous Inc. has finalized the cancellation of 5,003,341 common shares, a strategic corporate action executed under Article 178 of the Companies Act. This reduction, which took effect on August 6, 2026, represents 8.04% of the company’s total issued shares prior to the cancellation. The move follows a formal resolution passed by the Board of Directors on July 31, 2026, and serves to adjust the company’s capital structure by permanently removing these treasury shares from circulation.
The scope of this action is limited to the Japanese market, specifically impacting the equity structure of the Tokyo Stock Exchange Prime Market-listed entity. Following the completion of this cancellation, the total number of issued shares, excluding remaining treasury holdings, stands at 56,213,059. The company retains a balance of 1,000,000 treasury shares following the transaction.
This corporate restructuring reflects a standard administrative procedure for managing share capital and optimizing shareholder value. By eliminating a significant portion of its treasury stock, the company effectively reduces its total share count, which typically serves to increase earnings per share for remaining stakeholders. The data provided confirms the successful execution of the board’s mandate, marking the conclusion of this specific capital management initiative.
- Marvelous Inc. completed the cancellation of 5,003,341 common shares on August 6, 2026, following a board resolution on July 31, 2026.
- The cancelled shares represent 8.04% of the company's total issued shares prior to the transaction.
- The total number of issued shares for the Tokyo Stock Exchange Prime Market-listed entity now stands at 56,213,059.
- Marvelous Inc. retains a remaining balance of 1,000,000 treasury shares following the completion of this capital adjustment.
- This corporate action was executed under Article 178 of the Companies Act to optimize capital structure and shareholder value.
Mattel Wants Studios to Pitch the Uncomfortable
- Mattel is actively seeking high-risk, 'uncomfortable' creative pitches for its portfolio of over 800 brands, moving away from safe, predictable licensed titles.
- The company views intellectual property as a tool to lower user acquisition costs and improve conversion, provided it is supported by a strong core gameplay loop.
- Mattel has streamlined its operational model by implementing tools like the Roblox License Manager, which replaces per-asset sign-offs with pre-set guardrails to increase creative velocity.
- Studios frequently miscalculate by prioritizing broad demographics over LTV curves and failing to distinguish between specific cohorts like casual players and adult collectors.
- The greatest opportunities for development partners lie in leveraging Mattel's dormant intellectual property, which offers lower entry barriers and greater creative flexibility than marquee franchises.
- As of August 2026, only a small fraction of Mattel’s 50-plus active development partners are successfully executing on the company's strategy of pushing creative boundaries.
Game PublishingMarketingGame Design
Esports World Cup 2026 Viewership Recap: Key Statistics, Platforms, and Audience Trends
EsportsStreamingMarket Analysis
How Regional Creators and Co-streams Shaped Esports World Cup 2026 Viewership
EsportsStreamingMarketing