Samsung
Company
Documents about Samsung
Festive Season 2025: App Marketing Trends and Strategies for India
India’s festive season—from Onam in August through Diwali and Christmas in December—drives more than 30% of the country’s annual digital advertising spend, making it a pivotal period for app marketers.
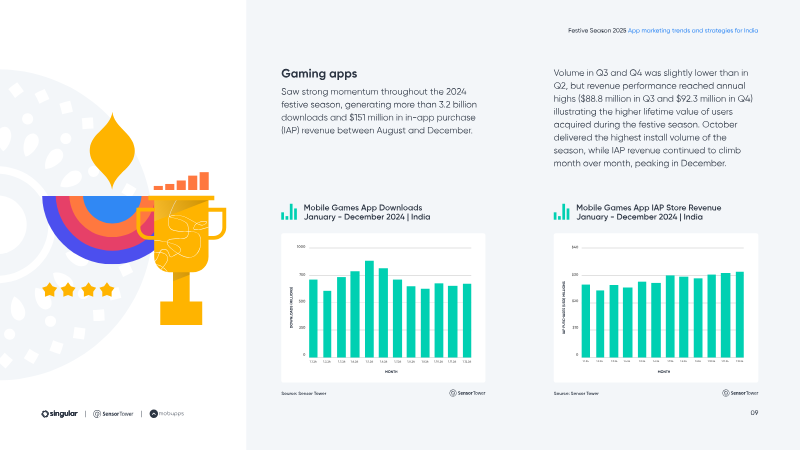
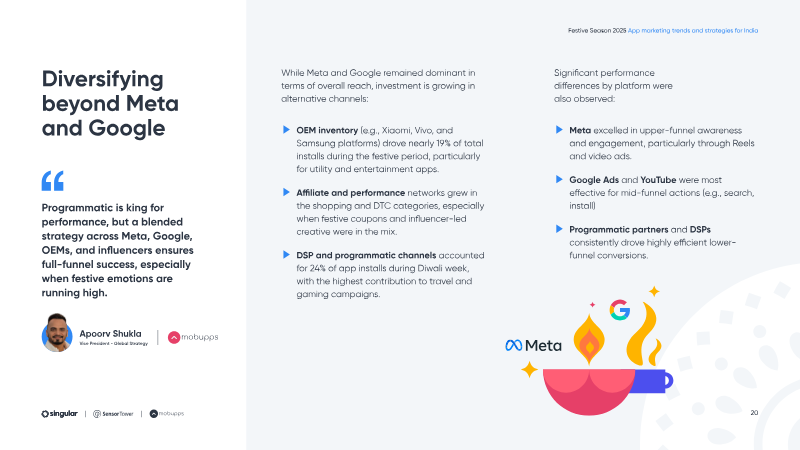
- India's festive season (August–December) accounts for over 30% of annual digital ad spend, driving a 36% increase in installs and a 69% surge in re-engagements during the peak window.
- Mobile gaming remains a primary growth driver, recording 3.2 billion downloads and $151 million in-app purchase revenue in 2024.
- Ad spend efficiency improved during the festive period, with a 53% increase in mobile ad investment accompanied by a 12% reduction in cost-per-install (CPI).
Corporate Overhaul: Why Does CVC Play a Bigger Role Than Ever?
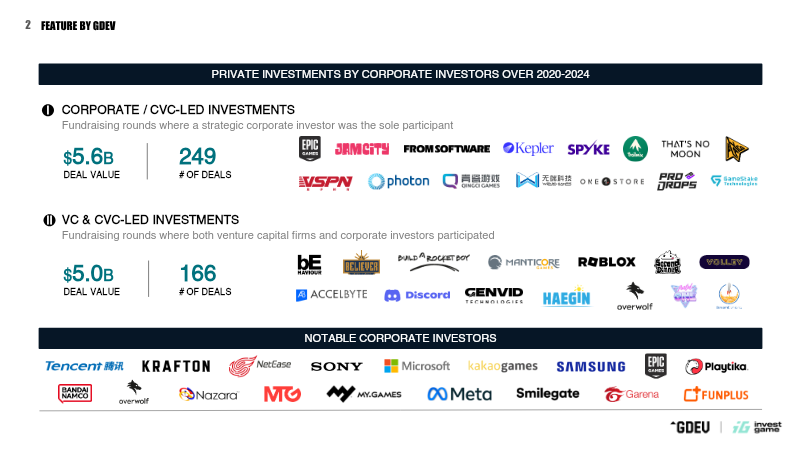
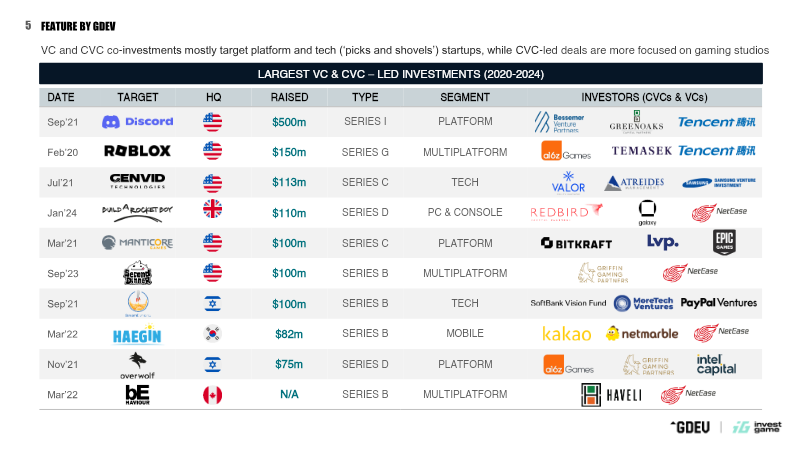
The analysis demonstrates that corporate venture capital (CVC) has become the dominant force in gaming investment from 2020 to 2024, accounting for more than half of all capital raised in the sector.
- Corporate venture capital (CVC) has become the dominant force in gaming investment from 2020 to 2024, accounting for over half of all capital raised with $4.0 billion across 93 CVC-led deals.
- Investment strategies have shifted toward co-investment models between CVCs and traditional VCs, which collectively raised $3.5 billion across 80 deals to spread risk and access high-profile startups.
- Asian firms, specifically from South Korea and Japan, are the most active investors, completing 105 deals worth $1.8 billion and surpassing Western peers in total deal volume.
Digital Market Index: Q4 2024
Global digital markets reached a significant milestone in the final quarter of 2024, with in-app purchase revenue hitting a record $39.4 billion.
- Global in-app purchase revenue reached a record $39.4 billion in Q4 2024, bolstered by a 28.2% year-over-year surge in non-game application spending.
- TikTok became the first application to surpass $6 billion in annual revenue, highlighting the massive monetization potential of non-game platforms.
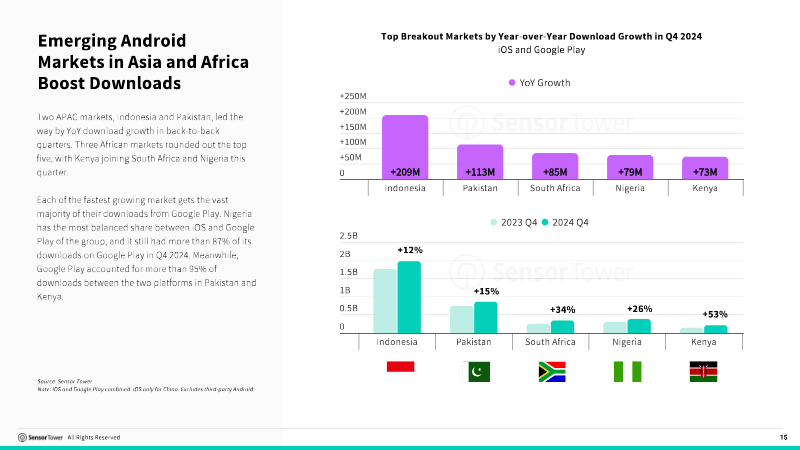
- The iOS ecosystem captured 70% of total revenue, while Google Play maintained its dominance in scale by facilitating nearly 75% of the 34.1 billion global downloads.
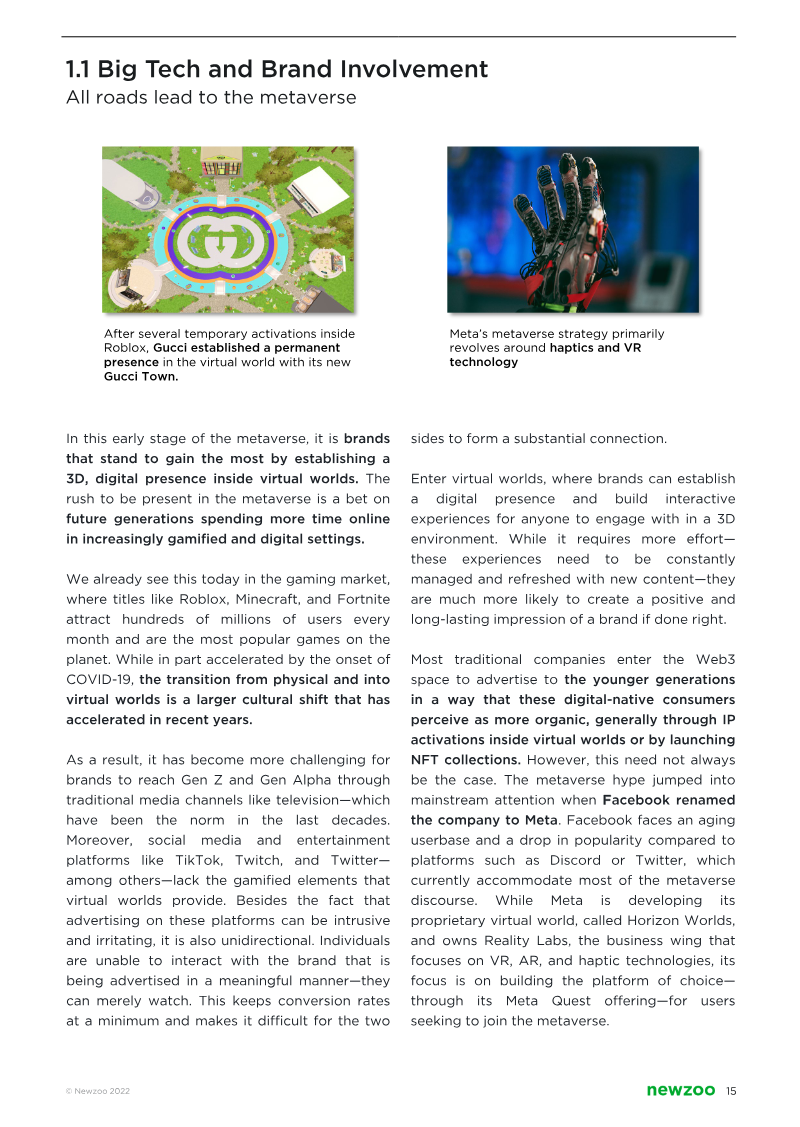
The Metaverse, Blockchain Gaming, and NFTs: Navigating the Internet’s Uncharted Waters 2022
The analysis demonstrates that the metaverse, blockchain gaming, and NFTs have transitioned from niche curiosities to mainstream commercial forces, reshaping consumer engagement across entertainment, fashion, and gaming.
- The metaverse and blockchain gaming have evolved into mainstream commercial forces, with major brands like Nike, Gucci, Samsung, and Louis Vuitton investing in virtual storefronts and digital real estate.
- Virtual events are demonstrating massive scale, as evidenced by Ariana Grande’s Rift Tour and Justin Bieber’s Wave performance attracting millions of concurrent viewers.
- Blockchain gaming is expanding through play-to-earn models, highlighted by Axie Infinity’s 3 billion gamers and Illuvium’s $72 million in funding, though long-term viability depends on engagement beyond speculative gains.
Global Mobile Market Report 2019
The mobile gaming industry reached a significant inflection point in 2019, characterized by the emergence of 5G technology and its potential to redefine hardware performance and user engagement.
- Global mobile game revenue reached $68.5 billion in 2019, marking a 26.7% year-on-year increase.
- The industry is supported by a global base of 3.2 billion smartphone users, with China serving as the primary market hub with 851.2 million active users.
- Hardware market leadership remains concentrated, with Samsung holding a 25.4% share of the global smartphone market and Apple commanding 67.6% of the tablet sector.
Global Mobile Market Report 2018
The global mobile market is undergoing a significant transformation characterized by a shift toward immersive, competitive gaming experiences and the integration of high-engagement subscription services.
- Mobile gaming generated $70 billion in 2018, representing 76 percent of the $92.1 billion total global app store revenue.
- Global smartphone adoption is projected to reach 3.8 billion users by 2021, with the Asia-Pacific region serving as the primary driver of market penetration.
- The mobile market is shifting toward immersive, competitive gaming experiences and subscription-based service models.
Mobile Games Whitebook: Q1 2017
The mobile gaming market in Southeast Asia is experiencing rapid expansion, positioning the region as a global leader in growth.
- Southeast Asia's mobile gaming revenue is projected to grow at a 45.3% compound annual growth rate between 2015 and 2019.
- The 'Big Six' markets—Indonesia, Malaysia, the Philippines, Singapore, Thailand, and Vietnam—generate 97% of the region's total mobile gaming revenue.
- The region is the world's fastest-growing esports market, with the number of enthusiasts expected to rise from 9.5 million in 2016 to 20 million by 2019.
Global Mobile Market Report 2017
The global mobile market is undergoing a period of rapid expansion, with the total number of smartphone users projected to climb from 2.3 billion in 2016 to 3.6 billion by 2020.
- The global smartphone user base is projected to grow from 2.3 billion in 2016 to 3.6 billion by 2020, driven primarily by adoption in the Asia-Pacific region.
- Mobile games currently dominate the app economy, accounting for 82% of the $56.4 billion in projected 2017 revenue.
- Total app economy revenue is expected to reach $85 billion by 2020, with non-game applications steadily increasing their market share.
China Mobile Market Update: November 2016
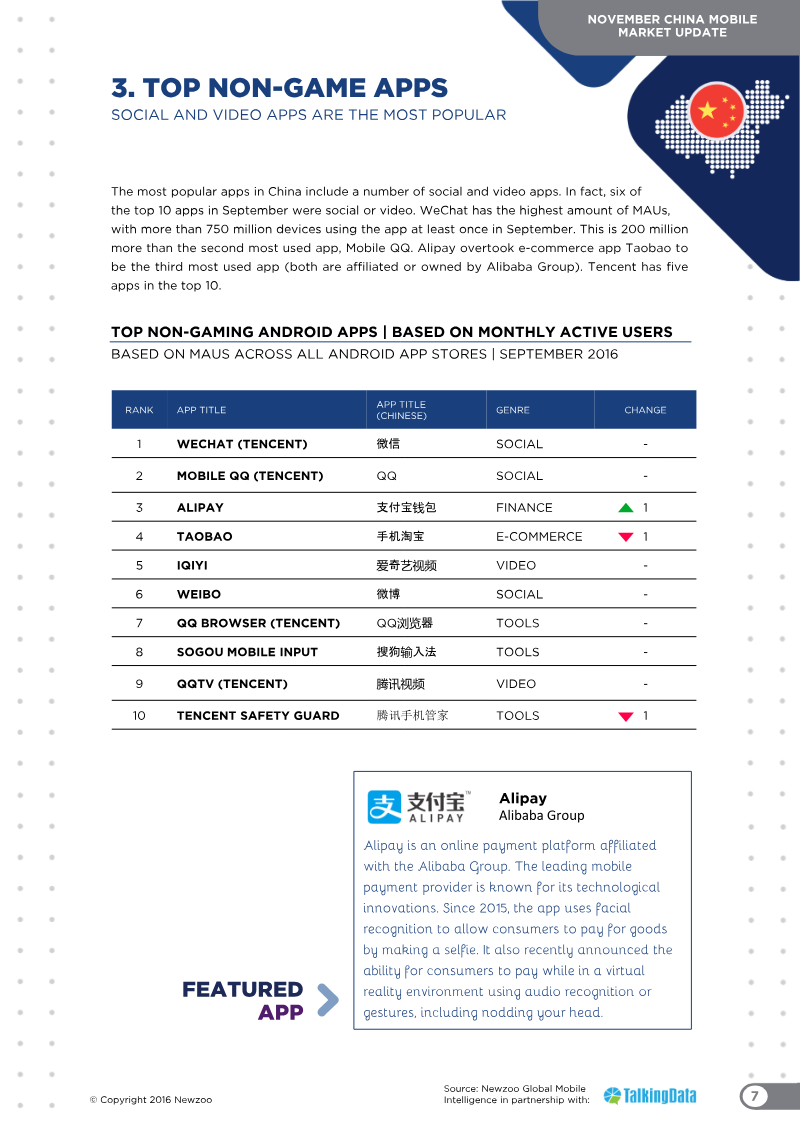
The November 2016 China Mobile Market Update provides a comprehensive analysis of the Chinese mobile ecosystem, focusing on device market share, app store performance, and top-grossing applications for September 2016.
- Tencent and NetEase dominate the Chinese mobile gaming revenue landscape, with Tencent’s 'King of Glory' leading Android and NetEase’s 'Onmyoji' achieving top-grossing status on iOS shortly after its release.
- Apple remains the leading mobile brand in China with a 23.6% market share, while OPPO has displaced Samsung to become the fourth-largest manufacturer behind Huawei and Xiaomi.
- Tencent’s Myapp holds 24% coverage of the Android app store market, while Alibaba’s acquisition of Wandoujia has driven significant growth in that platform's user base.
1H 2025 Amazon Retail Media: An Inside Look at How Brands Are Showing Up
Amazon Retail Media dominated the first half of 2025, capturing $618 million in ad spend—more than double Walmart’s $236 million and nearly six times Chewy’s $105 million—while attracting 9,542 unique advertisers, a figure nine times larger than Walmart’s 1,076.
- Amazon Retail Media dominated the market in 1H 2025 with $618 million in ad spend, significantly outpacing Walmart ($236 million) and Chewy ($105 million).
- Amazon’s advertiser base is nine times larger than Walmart’s, hosting 9,542 unique advertisers compared to Walmart’s 1,076.
- Samsung, Unilever, and L’Oréal were the top spenders in 1H 2025, contributing $7.1 million, $5.7 million, and $5.3 million respectively.