Report24 pages
Politics in Live Streaming: 2024
Live streaming has emerged as a critical venue for political discourse, effectively rivaling traditional media in its capacity to engage younger, tech-savvy audiences in real time. This analysis examines the intersection of politics and live streaming across major platforms—including Twitch, YouTube, Kick, and Rumble—from January 2023 through September 2024. The findings indicate that political content is a rapidly growing segment of the live-streaming ecosystem, with the market share of political streams increasing from 0.8% to nearly 3% over the first nine months of 2024.
Data reveals a significant surge in political engagement during major 2024 events, such as the U.S. presidential campaign announcements and the September debate between Donald Trump and Kamala Harris. YouTube Live has established itself as the dominant platform for this content, capturing 87% of the political streaming market in September 2024 and experiencing a 530% increase in political viewership since January. While Rumble maintains the highest concentration of political content relative to its total viewership at 32%, Twitch and Kick have also seen substantial growth in political engagement.
The analysis also highlights potential irregularities in viewership data, specifically identifying a subset of YouTube channels that exhibited suspicious behavior, such as rapid name changes or deletion following broadcasts related to the 2024 U.S. election. These compromised channels accounted for approximately 35% of the hours watched for streams mentioning the presidential candidates in Q3 2024. Despite these anomalies, the data confirms that live-streaming audiences are highly responsive to political developments, with chat sentiment and engagement metrics providing a granular view of public reaction to candidates and policy issues. Ultimately, the shift toward live-streamed news consumption reflects a broader transformation in how global audiences interact with and participate in contemporary political events.
- YouTube Live dominates the political streaming market with an 87% share as of September 2024, having experienced a 530% increase in political viewership since January 2024.
- Political content's share of the total live-streaming market grew significantly in 2024, rising from 0.8% to nearly 3% within the first nine months of the year.
- Approximately 35% of hours watched for streams mentioning U.S. presidential candidates in Q3 2024 originated from compromised YouTube channels exhibiting suspicious behaviors like rapid name changes or post-broadcast deletions.
- Rumble maintains the highest concentration of political content relative to its total platform viewership at 32%.
- Live-streaming engagement shows a direct correlation with major political milestones, evidenced by significant viewership surges during U.S. presidential campaign announcements and the September 2024 debate.
+1
Stream Hatchet
Report13 pages
Winning Audiences Through YouTube Gaming
YouTube Gaming experienced significant growth in 2025, solidifying its position as a dominant force in the live-streaming industry. The platform recorded 8.8 billion hours of viewership, accounting for approximately one in every four hours spent on live-streaming gaming platforms globally. This performance represents a 12% year-over-year increase, driven by a diverse international audience and a robust ecosystem of creators. The platform’s reach is particularly strong in North America, Asia, and Latin America, with Japan, the United States, and India emerging as the top markets for viewership.
The platform’s content strategy has successfully diversified beyond traditional long-form live streams. YouTube Shorts saw consistent growth throughout 2025, peaking at 6.15 million gaming-related posts in August. Simultaneously, sponsored content experienced a resurgence, with streams featuring paid partnerships reaching 4.5 million hours watched in the final quarter of 2025, the highest level since 2020. Roblox emerged as the most-watched game on the platform, while esports remained a critical pillar, contributing 1.2 billion hours of viewership, led by major titles such as League of Legends and Mobile Legends: Bang Bang.
Demographically, the audience is predominantly male and concentrated in the 20-34 age range, though the platform maintains a broad appeal that includes significant engagement from VTubers and variety streamers. The data indicates that top-tier creators often leverage a multi-platform approach, frequently streaming on competing services alongside YouTube to maximize their reach. The analysis relies on proprietary streaming metrics, including hours watched, peak concurrent viewers, and third-party demographic modeling based on social media behavioral patterns, to provide a comprehensive overview of the platform's influence within the global gaming sector.
- YouTube Gaming captured 8.8 billion hours of viewership in 2025, marking a 12% year-over-year growth and securing a 25% share of the global live-streaming gaming market.
- Roblox ranked as the most-watched game on the platform, while esports titles like League of Legends and Mobile Legends: Bang Bang generated 1.2 billion hours of total viewership.
- YouTube Shorts reached a peak of 6.15 million gaming-related posts in August 2025, highlighting the platform's successful diversification beyond long-form live content.
- Sponsored content saw a significant resurgence in Q4 2025, reaching 4.5 million hours watched, the highest level recorded since 2020.
- The platform's viewership is geographically concentrated in Japan, the United States, and India, with a core audience demographic of males aged 20–34.
+1
Stream Hatchet
Report29 pages
Esports Trends Report 2025
The 2025 Esports Trends Report provides a comprehensive analysis of the global esports landscape, focusing on viewership patterns, platform consolidation, and the evolving role of creator-led content. Tracking nearly 2,000 events across 78 titles, the data reveals a total of 2.7 billion hours watched. The industry remains highly concentrated, with League of Legends and Counter-Strike alone accounting for nearly 45% of total viewership. While Twitch and YouTube Gaming dominate the market with a combined 84.1% share, the report highlights the increasing significance of mobile esports, which, despite lower total hours watched, achieves higher average viewership per tournament than non-mobile counterparts.
A primary finding is the shift toward decentralized viewership, as co-streaming now accounts for 51.2% of all esports hours watched. This trend underscores the importance of linguistic accessibility and the influence of high-profile creators in driving engagement. Furthermore, the report identifies a growing synergy between brands and competitive gaming; tournaments headlined by brands generated 29.2% of total hours watched. Endemic brands like BLAST and StarLadder continue to lead in volume, but non-endemic entities, particularly in the betting sector, are increasingly capturing market share, suggesting significant untapped potential for diverse industries to engage with gaming audiences.
Methodologically, the analysis relies on granular, real-time tracking of Premier, Major, and Minor tournaments, excluding non-esports gaming content such as speedruns or showcases. By utilizing advanced metrics—including chat sentiment analysis, logo recognition, and match-by-match breakdowns—the report demonstrates how organizers and publishers can now achieve deeper insights into fan behavior. The findings conclude that the esports ecosystem is moving toward a more sophisticated, data-driven model where creator partnerships and regional league structures, particularly in Southeast Asia and South Korea, serve as the primary engines for sustained growth and audience retention.
- Co-streaming has become the dominant viewership model, accounting for 51.2% of all esports hours watched and highlighting the critical role of creator-led content.
- The esports market remains highly concentrated, with League of Legends and Counter-Strike generating nearly 45% of the total 2.7 billion hours watched across 2,000 tracked events.
- Twitch and YouTube Gaming maintain a combined 84.1% market share of total viewership, though mobile esports tournaments are achieving higher average viewership per event than non-mobile titles.
- Brand-headlined tournaments now generate 29.2% of total hours watched, with non-endemic companies in the betting sector increasingly capturing market share.
- Future industry growth is increasingly dependent on data-driven fan engagement strategies and regional league structures, specifically within Southeast Asia and South Korea.
+1
Stream Hatchet
Presentation9 pages
Gamer Motivation Model: Reference Sheets and Details
The Gamer Motivation Model provides a comprehensive framework for understanding player behavior by categorizing gaming preferences into twelve distinct motivations. Developed through psychometric factor analysis of data from over two million global participants, the model identifies how specific psychological drivers cluster together to influence game selection and engagement. By linking demographic data with preferred game titles and franchises, the research offers a data-driven approach to analyzing audience segments and predicting player retention.
The model organizes these twelve motivations into six related pairs, which are further grouped into three high-level clusters: Action-Social, Mastery-Achievement, and Immersion-Creativity. Action-Social focuses on immediate, adrenaline-fueled experiences and interpersonal interaction. Mastery-Achievement emphasizes long-term, goal-oriented gameplay characterized by strategic planning and cumulative progression. Immersion-Creativity centers on expansive, expressive play, curiosity, and the exploration of narrative or design-based boundaries. These clusters are conceptually described as bright, tall, and wide, respectively, to illustrate their distinct psychological orientations.
Each motivation is treated as a spectrum rather than a binary preference, acknowledging that gamers possess varying degrees of interest across all categories. By defining the anchors at both ends of these spectrums, the model allows for nuanced profiling of player types. For instance, the model distinguishes between players who prioritize social collaboration versus those who prefer independent, non-adversarial environments, or those who seek skill-based challenges versus those who prefer spontaneous, low-cognitive-load gameplay. This empirical approach provides actionable insights for developers and analysts to map specific game mechanics to the underlying psychological needs of diverse player demographics, facilitating a deeper understanding of the global gaming landscape.
- The Gamer Motivation Model categorizes player behavior into twelve distinct motivations derived from psychometric factor analysis of over two million global participants.
- Motivations are organized into three high-level clusters: Action-Social (immediate, interpersonal), Mastery-Achievement (goal-oriented, progression), and Immersion-Creativity (narrative, expressive).
- Player preferences are measured as spectrums rather than binary choices, allowing for nuanced profiling of how individuals balance competing psychological drivers.
- The framework maps specific game mechanics to underlying psychological needs, enabling developers to predict player retention and engagement based on target audience segments.
- By linking demographic data with preferred game titles, the model provides a data-driven methodology for analyzing global gaming audiences and their specific engagement patterns.
+1
Quantic Foundry
Report29 pages
Gaming Report 2026: Choose Your Player
The leadership team of Bain & Company's Global Gaming Sector practice prepared this report, with special direction from Anders Christofferson, partner and Global Gaming Sector lead, and Brandon Rogers, Media practice manager. The authors would like to thank Danielle Schwenker, Aman Sharma, Gunjan Dawar, Shray Arora, Rohan Doomra, Shagun Jain, and Christoffer Karlsmose for their contributions to this work.
- The gaming market has shifted from a supply-constrained environment to one of infinite choice, where success now requires deep engagement with specific player segments rather than broad, unfocused appeal.
- Focused games—those designed for a specific, identifiable audience—achieved an 83% commercial success rate, significantly outperforming the 50% success rate of unfocused titles.
- Player preferences are highly fragmented, with no single experience type (such as story-driven, sandbox, or multiplayer) capturing more than 26% of the market, and two-thirds of gamers preferring to stick to familiar franchises or existing habits.
- Nearly half of all gamers now purchase content directly from developer web stores at least once a year, and 75% of top-grossing mobile games currently operate their own direct-to-consumer storefronts, up from just 12% in 2019.
- Studios should adopt AI-driven, real-time personalization—specifically contextual bandit algorithms—to optimize individual player experiences, as the highest-spending segment of the market accounts for approximately 75% of total gaming revenue.
+2
Bain & Company
Report72 pages
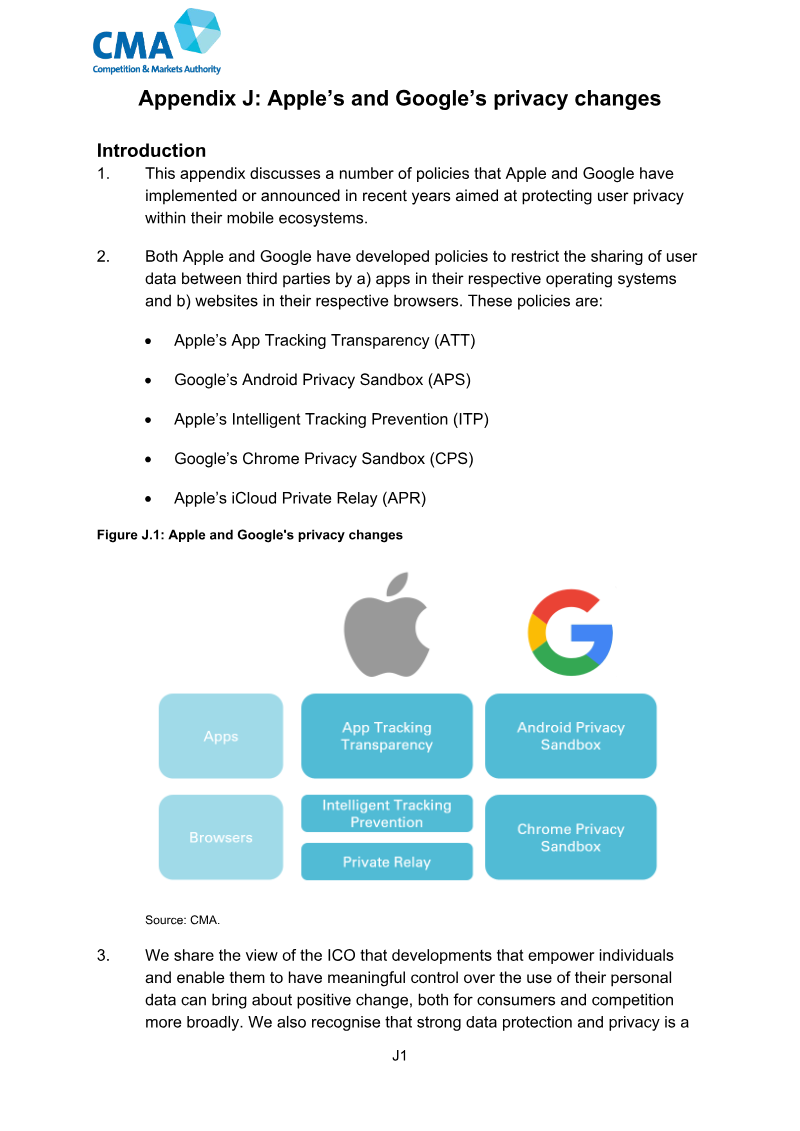
Appendix J: Apple's and Google's Privacy Changes
The mobile advertising ecosystem is undergoing a fundamental transformation as Apple and Google implement restrictive privacy frameworks, including App Tracking Transparency, the Privacy Sandbox, and Intelligent Tracking Prevention. While these initiatives provide tangible benefits by enhancing user control over personal data and limiting cross-app tracking, they simultaneously disrupt the technical infrastructure required for third-party ad targeting and attribution. By restricting access to device-level identifiers like IDFA and AdID, these policies have significantly increased costs for developers and reduced the efficacy of digital marketing, forcing a widespread shift in advertising budgets and monetization strategies across the global mobile industry.
A central concern is that these privacy-centric design choices create competitive imbalances that favor the platforms' own advertising services. Evidence suggests that Apple’s choice architecture—specifically the framing and placement of consent prompts—may leverage behavioral biases to discourage data sharing, while its proprietary attribution tools, such as SKAdNetwork, offer inferior data granularity compared to the insights available to Apple Search Ads. This asymmetry effectively creates a barrier to entry for third-party competitors, potentially consolidating market power within Apple and Google’s ecosystems. Developers report that these constraints not only hinder campaign optimization but also force a reliance on commission-based models that further entrench the platforms' dominance.
Ultimately, the transition toward privacy-first frameworks presents a complex trade-off between individual user protection and market competition. While the policies align with broader regulatory goals regarding data privacy, their implementation risks distorting the digital advertising landscape. The ongoing shift necessitates careful oversight to ensure that privacy-enhancing technologies do not serve as a pretext for self-preferencing or the suppression of competition, as the long-term viability of the app economy depends on maintaining a fair and transparent environment for all participants.
- Apple and Google’s privacy frameworks—including App Tracking Transparency, Privacy Sandbox, and Intelligent Tracking Prevention—have fundamentally disrupted the technical infrastructure for third-party ad targeting and attribution.
- The restriction of device-level identifiers like IDFA and AdID has increased costs for developers while simultaneously reducing the efficacy of digital marketing campaigns.
- Apple’s proprietary attribution tools, such as SKAdNetwork, provide lower data granularity than the insights available through Apple Search Ads, creating a competitive disadvantage for third-party advertisers.
- The framing and placement of consent prompts by Apple may leverage behavioral biases to discourage data sharing, effectively creating barriers to entry for competitors.
- These privacy-centric policies risk consolidating market power within Apple and Google by forcing developers to rely on the platforms' own advertising services and commission-based monetization models.
+2
CompetitionAug 2026
Report27 pages
Global DevOps and DataOps Report: Q2 2026
The DevOps and DataOps sectors are undergoing a period of rapid expansion and structural transformation, with the combined market value projected to reach $85 billion by 2031. This growth is fundamentally driven by the rise of AI-native development and the increasing convergence of software and data engineering. As enterprises prioritize large-scale automation, the industry is seeing a surge in transaction activity, which totaled $99.8 billion over the past twelve months—a 2.1x increase year-over-year. Private placements currently dominate this landscape, accounting for 78% of total deal value as capital flows heavily into AI-integrated observability and data-streaming platforms.
Market dynamics reflect a distinct shift in investor sentiment, favoring infrastructure-focused Ops solutions over traditional Dev software. While high growth remains a primary valuation driver, there is a growing emphasis on profitability, particularly among smaller market participants who currently trade at a discount compared to established category leaders. This environment has accelerated strategic consolidation, as major platforms aggressively integrate security, observability, and AI capabilities to maintain competitive advantages.
Global investment activity remains robust, with recent funding rounds pushing valuations for top-tier software delivery and observability platforms as high as $188 billion. These capital inflows are specifically targeted at scaling AI-powered automation and establishing viable alternatives to legacy CI/CD and infrastructure providers. As the sector matures, the focus remains on building resilient, automated ecosystems capable of supporting the complex demands of modern enterprise software and data lifecycles.
- The combined DevOps and DataOps market is projected to reach $85 billion by 2031, fueled by the convergence of software and data engineering alongside AI-native development.
- Transaction activity in the sector reached $99.8 billion over the last twelve months, representing a 2.1x year-over-year increase.
- Private placements dominate the investment landscape, accounting for 78% of total deal value as capital prioritizes AI-integrated observability and data-streaming platforms.
- Valuations for top-tier software delivery and observability platforms have reached as high as $188 billion due to robust global investment activity.
- Investor sentiment has shifted to favor infrastructure-focused Ops solutions over traditional development software, with a new emphasis on profitability for smaller market participants.
+1
Drake Star Partners
Report17 pages
The Future of Gaming Infrastructure: 2026-2028
The gaming industry is currently undergoing a critical architectural transition as live-service titles face a trilemma of escalating operational demands: the need for sub-10ms AI-driven decision-making, strict regulatory compliance, and rising cloud egress costs. The primary thesis is that legacy, fragmented backend architectures—which rely on separate databases, caches, and search layers—are no longer capable of supporting modern, high-velocity live-ops. To remain competitive, studios must shift toward unified, AI-native data planes that co-locate compute and data to ensure deterministic performance.
Key findings indicate that optimizing real-time matchmaking through low-latency infrastructure can drive a 4% to 15% uplift in player retention. However, achieving this requires moving away from asynchronous batch processing toward millisecond-level inference. This shift is further necessitated by the 2027 EU Data Act, which mandates the removal of cloud switching fees, and the EU AI Act, which classifies algorithmic matchmaking and personalization as high-risk systems requiring transparency, explainability, and immutable audit logs. Currently, only 5% of studios successfully implement player-facing AI, largely due to the latency bottlenecks inherent in traditional, multi-hop network architectures.
The industry is responding by adopting hybrid deployment models that combine self-hosted infrastructure with cloud resources to stabilize operating margins against unpredictable egress fees. By collapsing fragmented stacks into a single, coherent execution layer, studios can eliminate redundant systems and network round-trips. This consolidation allows for atomic, event-driven transactions that satisfy both performance requirements and emerging regulatory mandates.
Spanning the 2026–2028 period, this analysis highlights a fundamental shift in infrastructure strategy. As decision-making complexity grows—with matchmaking engines now processing hundreds of thousands of micro-decisions per second—the ability to execute logic directly on the data plane has become a primary competitive advantage. Studios that fail to modernize their backends risk both top-line revenue losses from poor engagement and bottom-line margin erosion caused by inefficient, legacy cloud consumption.
- Studios must transition from fragmented legacy backends to unified, AI-native data planes that co-locate compute and data to overcome latency bottlenecks and support high-velocity live-ops.
- Optimizing real-time matchmaking through low-latency infrastructure can increase player retention by 4% to 15%.
- Regulatory compliance with the 2027 EU Data Act and EU AI Act requires studios to implement immutable audit logs and transparent, explainable algorithmic systems for matchmaking and personalization.
- Only 5% of studios currently implement player-facing AI successfully, primarily due to latency issues caused by traditional, multi-hop network architectures.
- To stabilize operating margins against rising cloud egress costs, studios are increasingly adopting hybrid deployment models that combine self-hosted infrastructure with cloud resources.
+2
InvestGame
Whitepaper24 pages
A Deep Dive into Deep Links: The All-in-One Handbook for Mobile App Marketers, Developers, and Product Managers
Deep linking serves as a foundational strategy for mobile growth, functioning as a critical mechanism to bridge the gap between web and app environments. By directing users to specific in-app content rather than generic landing pages, this approach effectively minimizes friction throughout the user funnel. The primary thesis posits that a robust, standardized linking infrastructure is essential for modern mobile marketing, as it directly correlates with higher activation, improved retention rates, and more precise attribution across diverse digital touchpoints.
The current landscape of mobile marketing faces significant technical fragmentation, exacerbated by the recent deprecation of legacy services like Google’s Firebase Dynamic Links. To address these challenges, centralized solutions such as Adjust’s TrueLink provide a scalable framework for managing direct, deferred, and contextual links. These tools enable automated link generation and sophisticated cross-platform routing, ensuring that user journeys remain uninterrupted whether they originate on mobile, desktop, or connected television environments. By standardizing these interactions, organizations can maintain consistent performance and data integrity across the entire ecosystem.
These strategies are particularly impactful within high-growth verticals such as e-commerce, gaming, and finance, where the quality of the initial user experience dictates long-term engagement. Data indicates that implementing comprehensive linking platforms not only streamlines the transition for brands migrating from deprecated services but also enhances the granular measurement capabilities required for data-driven decision-making. Ultimately, the integration of a unified linking architecture is a prerequisite for scaling app growth, as it transforms fragmented traffic sources into cohesive, high-converting user experiences that support sustained business objectives.
- Deep linking significantly improves app performance, with CleverTap data showing that users attributed to deep links achieve 81% higher activation rates, 2.5x higher retention rates, and 2x higher conversion rates compared to those using standard links.
- Deep linking technology functions by routing users directly to specific in-app content or screens upon clicking an ad or link, utilizing standards such as Apple Universal Links, Android App Links, and URI schemes.
- Deferred deep linking drives user acquisition by directing individuals who have not yet installed the app to the appropriate app store landing page, thereby reducing friction in the installation process.
- Modern deep linking solutions like Adjust's TrueLink provide comprehensive management features, including branded short links, localized landing pages in 11 languages, and automated UTM tag translation for unified campaign measurement.
- Deep linking supports diverse marketing use cases across verticals, such as enabling level-specific gaming campaigns, offline-to-app transitions via QR codes, and personalized re-engagement through push notifications.
+2
Adjust
Report9 pages
Ramadan App Trends Decoded: Benchmarks and Insights for 2026
This analysis examines mobile app performance trends during the 2025 Ramadan season to provide strategic benchmarks for 2026. By tracking installs, session counts, and session lengths across seven key verticals—including e-commerce, finance, gaming, and social—the findings highlight how shifting consumer routines during the fasting period and Eid al-Fitr create distinct opportunities for user acquisition and engagement. The scope covers global data with a specific focus on the METAP region, encompassing 22 countries such as Saudi Arabia, Indonesia, Pakistan, and the UAE.
Data indicates that Ramadan acts as a significant driver of mobile activity, with average daily installs in the METAP region rising 11% during the month compared to the preceding two weeks. Session counts also saw a 6% increase during the period. Engagement patterns varied by vertical; gaming and social apps emerged as primary drivers of session growth, while e-commerce experienced significant spikes in specific markets like Pakistan and the UAE. Notably, session lengths for gaming apps remained the longest across all regions, averaging 35.6 minutes during Ramadan.
The analysis emphasizes that Ramadan should be treated as a phased growth cycle rather than a single peak. While overall install growth reached 10% during Ramadan and climbed to 13% in the post-Eid period, performance varied significantly by country and category. The findings suggest that marketers should avoid uniform regional strategies, instead utilizing country-level benchmarks to guide budget allocation. Success during this season requires sustained, conversion-focused activity that extends through Eid al-Fitr, alongside a focus on high-intent engagement windows, particularly during late-night hours, to maximize user retention and long-term loyalty.
- Ramadan drives a 11% increase in average daily installs and a 6% rise in session counts across the METAP region compared to the two weeks prior.
- Gaming apps maintain the highest engagement levels during the season, with average session lengths reaching 35.6 minutes.
- The Ramadan growth cycle extends beyond the fasting period, with overall install growth climbing from 10% during Ramadan to 13% in the post-Eid period.
- Marketers should avoid uniform regional strategies, as performance metrics for categories like e-commerce vary significantly by specific markets such as Pakistan and the UAE.
- To maximize long-term loyalty, campaigns should prioritize conversion-focused activity during late-night hours and maintain engagement through the Eid al-Fitr period.
+2
Adjust
Report37 pages
The Shopping App Insights Report: 2025 Edition
The global e-commerce landscape, currently valued at $6.42 trillion, is undergoing a significant transformation as marketers navigate economic volatility and evolving consumer expectations. While the first half of 2025 saw a 14% year-over-year decline in total app installs, session growth remains resilient, signaling a shift toward deeper engagement rather than mere acquisition volume. Success in this environment requires a transition from broad-reach tactics to sophisticated, omnichannel strategies that leverage artificial intelligence for hyper-personalization and predictive modeling.
Performance data from the first half of 2025 reveals a strategic pivot toward paid user acquisition and re-engagement, with the global reattribution share rising to 0.18 and the paid-to-organic ratio climbing to 0.54. Regional performance is increasingly polarized; while Thailand and Brazil have emerged as high-growth markets, other regions like the UAE and Saudi Arabia have experienced notable contractions. Marketplace apps continue to lead in session volume, yet dedicated shopping apps maintain a stronger hold on new install acquisition.
Despite competitive engagement metrics, the industry faces challenges with a 13% decline in day-one retention and rising costs per install. To counter these trends, developers are diversifying partner ecosystems and utilizing tools such as deep linking and smart banners to reduce friction in the user journey. Sustainable growth now depends on prioritizing long-term retention through data-driven, localized experiences rather than relying on seasonal traffic spikes. By integrating AI-powered measurement and analytics, businesses can better optimize their return on investment and maintain a competitive edge in a privacy-first, global marketplace.
- Global e-commerce app installs declined 14% year-over-year in H1 2025, though sessions grew by 2%, indicating a shift toward re-engaging existing users over new acquisition.
- Global reattribution share for e-commerce apps rose to 0.18 in H1 2025, up from 0.14 in 2023, with the UAE (0.40) and U.K. & Ireland (0.36) leading in win-back activity.
- Global e-commerce app install per mille (IPM) reached nearly 3.0 in Q1 2025, with North America maintaining the highest regional performance at 5.21.
- External economic factors, such as U.S. tariffs introduced in May 2025, prompted 68% of marketers to adjust holiday strategies, including frontloading consumer purchases to early summer.
- LATAM emerged as a growth outlier in H1 2025, recording an 18% increase in installs and a 27% increase in sessions compared to the previous year.
+3
Adjust
Report35 pages
The Gaming App Insights Report: 2026 Edition
The mobile gaming industry is undergoing a fundamental strategic transition, moving away from a reliance on high-volume user acquisition toward a model centered on long-term retention and high-value player engagement. This shift is driven by a challenging economic environment characterized by a 33% increase in global cost-per-click and a 30% rise in cost-per-install throughout 2025. To mitigate these rising expenses, studios are consolidating their marketing efforts, reducing the average number of advertising partners per application to focus on high-performing channels that promise superior return on investment.
Technological innovation serves as a primary lever for this transformation, with generative artificial intelligence and machine learning now integral to creative production and audience targeting. These tools allow developers to optimize ad performance and refine engagement tactics in an era where data privacy remains a critical factor. Notably, App Tracking Transparency opt-in rates on iOS reached 39% in early 2026, providing studios with more reliable data to fuel their direct-to-consumer strategies. This data-driven approach is increasingly vital as the industry seeks to balance the dominance of hyper-casual titles, which still account for 29.1% of installs, with the superior session-to-install ratios found in action and puzzle genres.
The global landscape reflects a maturing market where session lengths and day-1 retention rates remain stable despite the broader cost pressures. While hyper-casual games maintain the largest share of installs, the industry is clearly pivoting toward hybrid monetization and cross-platform experiences to sustain growth. By prioritizing long-term progression over rapid acquisition, developers are successfully navigating a period of rising costs, ensuring that engagement remains robust even as the industry shifts toward more sustainable, value-based growth models.
- Global gaming app CPC rose 33% from $0.03 to $0.04 between 2024 and 2025, while global CPM increased 20% from $3.63 to $4.34.
- Hyper-casual games maintained the largest market share of installs at 29.1% in 2025, while action games dominated session share at 17.1%.
- Strategy games saw the most significant increase in session length, growing 18% to 37.51 minutes, and experienced a 133% surge in CPC from $0.03 to $0.07.
- Over 90% of game developers now utilize AI to automate and streamline core production tasks, including playtesting, localization, and game balancing.
- North America recorded the highest regional CPC at $0.12 in 2025, representing a 71% increase, with the U.S. market specifically rising 86% to $0.13.
+3
Adjust
Report27 pages
Rovio Sustainability Report 2025
The Rovio Sustainability Report 2025 outlines the company’s voluntary environmental, social, and governance performance for the fiscal period spanning April 1, 2025, to March 31, 2026. As a subsidiary of SEGA SAMMY Holdings, Rovio utilizes this disclosure to maintain transparency and accountability regarding its sustainability strategy, which is structured around three core pillars: Positive Play, Empowered People, and Protecting our Planet. The report aligns partially with European Sustainability Reporting Standards, though it remains a voluntary exercise for the organization.
Key findings highlight a total carbon footprint of 20,980 tons of CO2e, with Scope 3 emissions accounting for 98.6% of the total. For the first time, the company included downstream emissions from initial game downloads in its accounting, which significantly improved coverage but precluded direct year-over-year comparisons. Operationally, Rovio maintains six global locations with 508 employees, reporting a gender pay gap of 1.4% when adjusted for location, level, and role. The company continues to prioritize industry collaboration, maintaining active memberships in the Playing for the Planet Alliance and the Sustainable Games Alliance to drive collective climate action.
Strategic conclusions emphasize a pragmatic approach to sustainability, acknowledging challenges in formalizing long-term emission reduction plans due to supply chain limitations and evolving market realities. While the company successfully implemented new internal "Rovio Way" principles and improved data tracking for career progression, it faced capacity constraints that delayed the rollout of certain accessibility scorecards and carbon pricing models. Looking ahead, the organization intends to focus on integrating AI sustainability frameworks, enhancing inclusive game design, and embedding its new corporate principles into daily operations to ensure long-term, sustainable growth across its transmedia and mobile gaming portfolio.
- Rovio reported a total carbon footprint of 20,980 tons of CO2e for the fiscal period ending March 31, 2026, with Scope 3 emissions representing 98.6% of that total.
- The company expanded its carbon accounting to include downstream emissions from initial game downloads, a change that improved data coverage but prevented direct year-over-year comparisons.
- Rovio maintains a workforce of 508 employees across six global locations and reports an adjusted gender pay gap of 1.4%.
- The organization is prioritizing industry collaboration through active memberships in the Playing for the Planet Alliance and the Sustainable Games Alliance to address climate action.
- Capacity constraints caused delays in the implementation of planned accessibility scorecards and internal carbon pricing models.
+3
Rovio
Report43 pages
Video Game Market Update: Q2 2026
The global video game industry experienced a period of divergent performance during the second quarter of 2026, characterized by a resilient PC sector and a stagnant console market. While Steam sustained a 13 percent year-over-year growth trajectory, console revenues remained flat as the successful launch of the Nintendo Switch 2 balanced out declines in PlayStation and Xbox hardware sales. Conversely, the mobile gaming segment faced significant headwinds, marked by a 4 percent contraction in gross revenue and a 12 percent decline in new installs. This mobile stagnation is compounded by a lack of innovation in top-grossing charts, which remain dominated by legacy titles released more than four years ago.
Financial activity within the sector showed signs of a robust recovery, with 54 merger and acquisition transactions deploying $2.3 billion in capital. Private investment experienced a dramatic sixfold year-over-year surge, totaling $3.1 billion, driven largely by mega-rounds focused on artificial intelligence, adtech, and immersive hardware. This shift in investment strategy reflects a broader trend where capital is increasingly concentrated in infrastructure and enabling technologies rather than traditional content-focused development.
Despite this transactional health, public gaming equities remain under significant pressure, suffering from double-digit year-to-date declines and compressed valuation multiples. Investors are prioritizing profitability and sustainable growth, favoring large-cap publishers that demonstrate resilience in a volatile equity environment. While early-stage venture activity persists, the industry continues to undergo widespread consolidation through strategic divestments and M&A, signaling a transition toward a more mature, efficiency-focused market landscape.
- Private investment in the gaming sector surged sixfold year-over-year to $3.1 billion, with capital increasingly shifting away from content development toward infrastructure, AI, adtech, and immersive hardware.
- The PC sector remains a primary growth driver with Steam recording a 13 percent year-over-year revenue increase, while the console market remains stagnant as Switch 2 gains offset declines in PlayStation and Xbox hardware.
- Mobile gaming is facing a downturn, evidenced by a 4 percent contraction in gross revenue and a 12 percent decline in new installs, with top charts remaining stagnant due to a reliance on legacy titles.
- Financial activity remains robust with 54 M&A transactions totaling $2.3 billion, signaling a broader industry trend toward consolidation and efficiency-focused market maturity.
- Public gaming equities are under significant pressure with double-digit year-to-date declines, forcing investors to prioritize profitability and large-cap publishers over speculative growth.
+1
Aream & Co
Report17 pages
Direct-to-Consumer: A $17 Billion Market for Mobile Gaming
The mobile gaming industry is undergoing a fundamental structural shift toward direct-to-consumer (DTC) distribution models, a transition that has already established a $17 billion market. By bypassing traditional app store ecosystems, publishers are successfully reclaiming profit margins previously lost to platform fees while simultaneously securing ownership of first-party player data. This evolution represents a strategic pivot from passive reliance on third-party storefronts to the active cultivation of proprietary, data-driven player relationships that foster long-term retention and competitive differentiation.
While the transition presents significant hurdles regarding technical infrastructure and player acquisition, the industry is increasingly adopting a hybrid model. This approach balances internal, player-facing strategies with specialized external partnerships for payment processing and regulatory compliance. Early adopters of these DTC frameworks are already demonstrating superior revenue growth and improved engagement metrics, creating a widening performance gap between firms that have integrated these channels and those that remain tethered to traditional distribution methods.
Looking toward the next decade, the broader digital economy is poised to mirror the success of mobile gaming, with the global in-app purchase market projected to reach $721.4 billion by 2034. DTC strategies are no longer the exclusive domain of large-scale enterprises; they have become a scalable imperative for developers of all sizes. By leveraging personalized experiences and sophisticated marketing analytics, firms can achieve higher year-over-year growth and greater valuation stability. Ultimately, the ability to control the end-to-end user experience has emerged as the primary driver of economic sustainability and long-term success in the modern mobile landscape.
- The mobile gaming direct-to-consumer (DTC) market has reached a valuation of $17 billion as publishers shift away from traditional app store ecosystems to reclaim platform fees.
- The global in-app purchase market is projected to grow to $721.4 billion by 2034, signaling a long-term shift toward DTC distribution across the digital economy.
- DTC models allow publishers to secure ownership of first-party player data, which is being used to drive long-term retention and competitive differentiation.
- Early adopters of DTC frameworks are currently outperforming competitors by demonstrating superior revenue growth and improved engagement metrics.
- Developers are increasingly adopting hybrid models that combine internal player-facing strategies with specialized external partnerships for payment processing and regulatory compliance.
+2
Appcharge
Report14 pages
Gamescom Awesome Indies Show: 2025 by the Numbers
The Gamescom Awesome Indies Show serves as a premier international platform for independent developers, studios, and publishers to debut new titles, gameplay, and trailers. By highlighting creative and emerging projects, the event functions as a high-visibility showcase within the broader Gamescom ecosystem. The 2025 iteration successfully engaged a global audience, demonstrating the significant reach of indie-focused programming through a combination of live streaming and on-demand content.
Performance metrics for the 2025 event underscore its substantial digital footprint. The showcase featured 24 indie titles and generated 36,500 hours of watch time during the live broadcast. Audience engagement remained strong, peaking at 44,000 concurrent viewers, while the event was supported by 116 co-streams. Furthermore, the program achieved 57,800 views on video-on-demand (VOD) platforms, confirming sustained interest in the showcased content beyond the initial live window.
To sustain and expand these efforts, the event offers structured sponsorship opportunities for the 2026 cycle. These commercial tiers range from $10,000 for spotlight trailers to $50,000 for official product partnerships, which include product placement and custom content integration. The sponsorship model is designed to integrate brands directly into the broadcast through branded snipes, developer interviews, and booth tours. By leveraging IGN Entertainment’s production capabilities and established digital channels, these partnerships provide brands with direct access to a dedicated gaming audience, ensuring that the showcase remains a viable and professional vehicle for industry promotion.
- The 2025 Gamescom Awesome Indies Show featured 24 independent titles and reached a peak of 44,000 concurrent viewers during its live broadcast.
- The event generated 36,500 hours of live watch time and secured 57,800 views on video-on-demand platforms, indicating strong sustained interest.
- The broadcast achieved significant distribution through 116 co-streams, amplifying the reach of the indie-focused content.
- Sponsorship tiers for the 2026 cycle range from $10,000 for spotlight trailers to $50,000 for official product partnerships.
- Commercial partnerships for 2026 include integrated brand opportunities such as product placement, branded snipes, developer interviews, and booth tours.
+1
IGN EntertainmentJul 2026
Whitepaper23 pages
The Esports Generation: Who They Are, and Why They Spend
The global esports industry has matured into a significant economic force, reaching an estimated 640 million fans and generating $3 billion in annual revenue by 2026. This ecosystem functions as a primary cultural touchpoint for Generation Z, a digitally native demographic that views competitive gaming with the same level of emotional investment and community identity traditionally reserved for professional sports. Because this audience is currently in a formative stage of brand loyalty, the industry represents a critical environment for companies seeking to establish long-term relationships with high-value consumers.
Engagement within this space is driven less by the games themselves and more by social connectivity, the influence of professional players, and high-quality production standards. Fans demonstrate a high propensity for commercial activity, with over 76 percent having made esports-related purchases within the past year. This demographic is particularly receptive to brand integration, as 85 percent of fans actively notice esports branding, and nearly three-quarters report that these sponsorships directly influence their purchasing decisions. The effectiveness of this channel extends across diverse sectors, including electronics, fashion, and food and beverage, proving that esports serves as a highly efficient gateway for cross-industry marketing.
Ultimately, the esports landscape offers a unique opportunity for brands to leverage the intersection of gaming, music, and streaming to capture a highly engaged audience. By prioritizing authentic engagement strategies that respect the publisher-driven nature of the ecosystem, brands can successfully convert digital interest into tangible loyalty. As these fans continue to prioritize in-game spending and subscription-based services, the industry remains a proven, high-value environment for sustained commercial growth and brand association on a global scale.
- Gen Z esports fans represent a massive, high-value demographic of 400 million potential global viewers, with 76.3% of fans having made an esports-related purchase in the past year.
- The esports industry generates $3 billion in annual revenue, driven by a global audience of 640 million and high engagement from a cohort that is largely employed and well-educated.
- Esports fans are highly receptive to brand partnerships, with 47.1% of fans stating that brand collaborations with teams or athletes positively influence their purchase behavior.
- Digital items like skins and cosmetics are the most popular esports-related purchase (50%), followed by physical merchandise (40.9%) and branded peripherals (33%).
- YouTube (81.8%) and TikTok (56.6%) are the primary international broadcast platforms for esports, while China relies on domestic giants like Bilibili (48.1%) and Douyu (36.2%).
+2
Niko PartnersJul 2026
Report37 pages
Brands in Gaming 101: Virtual Worlds
Virtual worlds have emerged as a critical marketing frontier, fundamentally reshaping how brands engage with younger demographics. As Gen Z increasingly prioritizes immersive gaming platforms over traditional social media, these environments offer a unique opportunity to capture sustained, high-level attention. This shift necessitates that brands transition from viewing gaming as a peripheral experiment to integrating it as a core component of their broader omnichannel marketing strategies.
The current landscape is defined by rapid expansion, with over 2,800 brand experiences launched to date and a notable trend toward high-impact, lower-commitment integrations. While activity is heavily concentrated within Roblox and Fortnite, success depends on selecting platforms that align with specific audience demographics rather than pursuing scale alone. By moving away from standalone owned worlds toward more agile, targeted activations, brands can better navigate the complexities of these digital ecosystems while maintaining consistent engagement levels.
Effective participation in virtual worlds requires a rigorous, data-driven approach that bridges the gap between on-platform interaction and tangible business outcomes. Brands must implement comprehensive measurement frameworks that track performance across the entire marketing funnel, linking virtual engagement to off-platform metrics such as sales uplift and brand search volume. When executed through bespoke strategies and strategic partnerships, these activations move beyond mere visibility, delivering measurable value that justifies the investment in immersive digital experiences. This evolution reflects a broader industry maturation, where the focus has shifted from simple presence to the strategic optimization of virtual environments as high-performing commercial channels.
- Virtual worlds command higher user attention than other channels, with 73% of players in a focused state compared to 57% for video streaming and 40% for social media.
- Gaming is a primary social space for Gen Z, as 92% of women and 93% of men aged 16 to 24 play video games, and 17.7% have engaged with a branded game in the past month.
- The virtual world market is dominated by four platforms: Roblox (380 million monthly active users), Minecraft (200 million), Fortnite (130 million), and ZEPETO (33 million).
- Brand activity is highly concentrated, with 88% of all brand activations occurring on Roblox and Fortnite.
- Integrations are currently more common than owned worlds (337 vs 252) because they offer a faster, lower-cost entry point that can be launched in weeks rather than quarters.
+2
GEEIQJul 2026
Report13 pages
Farming Sims: Cultivating Long-term Engagement
Farming simulation games have established themselves as a dominant and enduring genre within the global mobile gaming market. By analyzing data from a survey of 1,000 US mobile gamers aged 18 to 55, it is evident that these titles possess significant staying power, with 60% of mobile gamers having played at least one of the top ten farming sims. The genre’s success transcends casual demographics, attracting a broad audience that includes players of complex genres like RPGs, shooters, and strategy games, as well as those who primarily play on PC and consoles.
The core appeal of farming sims lies in their ability to satisfy fundamental human motivations defined by Self-Determination Theory: autonomy, competence, and relatedness. Unlike many other genres, farming sims excel at providing players with a sense of control through farm layout planning, a feeling of mastery via task completion and progression, and social connection through cooperative play and community interaction. These psychological drivers, combined with the "work-as-play" trend, foster long-term engagement through daily rituals, creative expression, and the evolution of virtual spaces.
To maintain this momentum, developers must navigate a saturated market by prioritizing consistent live-ops, community-driven content, and user-generated features. While the genre offers high accessibility and flexible session lengths, it faces challenges regarding content cadence and the risk of undermining the low-pressure experience through aggressive monetization. Ultimately, the longevity of farming sims serves as a blueprint for other genres, demonstrating that combining low-stress gameplay with deep, meaningful progression and social mechanics is a highly effective strategy for cultivating a dedicated, long-term player base.
- Farming simulation games maintain high long-term engagement by satisfying core human motivations defined by Self-Determination Theory: autonomy, competence, and relatedness.
- The genre appeals to a broad demographic, with 60% of mobile gamers having played a top farming title, including 73% of RPG players and 65% of console gamers.
- Farming sims demonstrate exceptional longevity, as evidenced by titles like Township, Hay Day, and FarmVille 2, which were released in 2012 and continue to command massive player bases with over 100 million to 500 million downloads each.
- Players prioritize building, experimentation, and daily rituals, with 36% of farming sim players citing 'building and evolving my farm' as a top motivation compared to only 7% in other genres.
- The 'work-as-play' trend is expanding beyond traditional farming, with job-based simulators like Truck Simulator and My Supermarket Simulator achieving over 100 million downloads each.
+3
BryterJul 2026
Report16 pages
Rewarded UA Handbook: 2026
Rewarded user acquisition (UA) has evolved into a foundational component of the mobile marketing mix, serving as a critical solution to the industry’s ongoing challenges of rising acquisition costs and high user churn. As the global mobile gaming market matures and user growth plateaus, rewarded UA provides a mechanism to drive long-term engagement and retention by incentivizing users to reach specific in-game milestones. The practice is now standard, with 93% of surveyed developers across 10 tier-1 markets currently utilizing rewarded channels, and 61% planning to increase their budget allocations in 2026.
The methodology behind this analysis involved an online survey of 912 mobile game developers conducted between December 2025 and January 2026, supplemented by performance data from over 1,200 advertisers on the Freecash platform. Findings indicate that successful campaigns are no longer treated as experimental, with 31% of studios classifying rewarded UA as an always-on, core channel. High-performing studios typically allocate between 11% and 50% of their total UA budget to these efforts, often managing a portfolio of four or more channels to optimize reach and performance.
Strategic implementation requires a shift toward long-term event architecture. Data shows that campaigns optimizing for multiple, layered events—such as daily streaks, VIP tiers, and repeat purchases—consistently outperform single-event models. By extending reward structures to 90 or 180 days, developers can significantly improve retention and return on ad spend (ROAS). Furthermore, the industry is increasingly adopting automated bidding technologies, such as dynamic ROAS-based bidding, to replace fixed cost-per-install models. While gaming remains the primary sector, the model is rapidly expanding into non-gaming verticals like fintech and e-commerce, where gamification features are being leveraged to drive similar habit-forming behaviors and sustainable user value.
- Rewarded UA is now a core marketing channel, with 61% of surveyed studios planning to increase their budget in 2026 and 65% of studios allocating between 11% and 50% of their total UA spend to the channel.
- Extending reward structures beyond traditional short-term windows is critical for retention; for example, Candivore increased their Match Masters reward structure from 50 to 90 days, resulting in a 50% increase in D60 retention and a 70% uplift in D90 ROAS.
- Campaigns that layer multiple event types outperform single-event campaigns, with IAP/hybrid games utilizing an average of 3.25 distinct event types per campaign to drive long-term engagement.
- Automation is a primary industry focus, as evidenced by Almedia’s MaxROAS system, which has delivered up to a 35% ROAS uplift and a 100% increase in spending for participating advertisers since December 2025.
- Rewarded UA is increasingly viewed as a go-to-market strategy, with 93% of studios launching rewarded campaigns within the first year of their game's lifecycle and 46% implementing them within the first three months of global launch.
+3
AlmediaJun 2026