Monetization reports and market data
Documents
Mobile Games: Placing Smartphone and Tablet Gaming in Perspective of the Total Games Market 2012
The 2012 mobile gaming landscape was defined by a rapid shift in consumer behavior, characterized by the adoption of multiple screens and the dominance of free-to-play (F2P) monetization models.
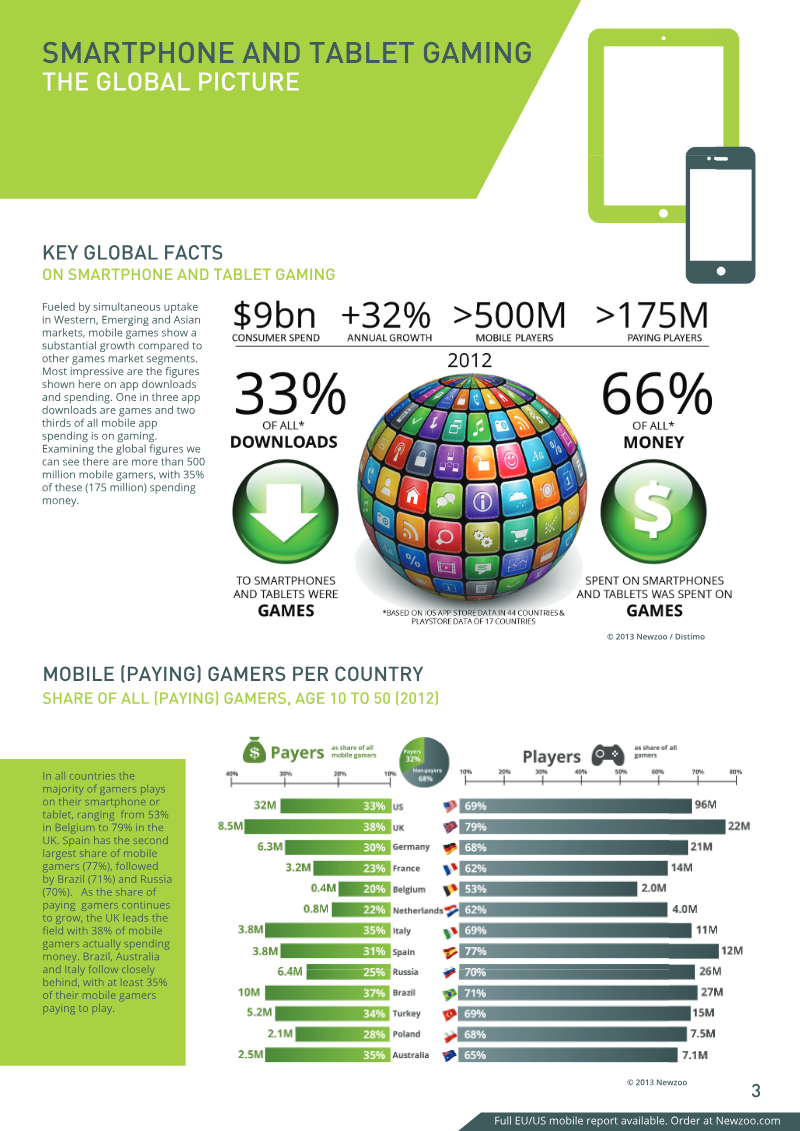
- Mobile gaming became a primary revenue driver in 2012, with two out of every three dollars spent on smartphones and tablets allocated to games.
- Free-to-play (F2P) models dominated the market, accounting for 70% of all iOS revenue in the US and Europe by the end of 2012.
- The global mobile gaming audience reached over 500 million users by the end of 2012, with 175 million identified as paying players.
Global Monetization of Games: Emerging Markets as Drivers of Growth
The global gaming industry is undergoing a significant transformation, with total market value projected to reach $70.4 billion.
- The global gaming market is projected to reach a total value of $70.4 billion, driven primarily by mobile gaming's 35% year-over-year growth rate.
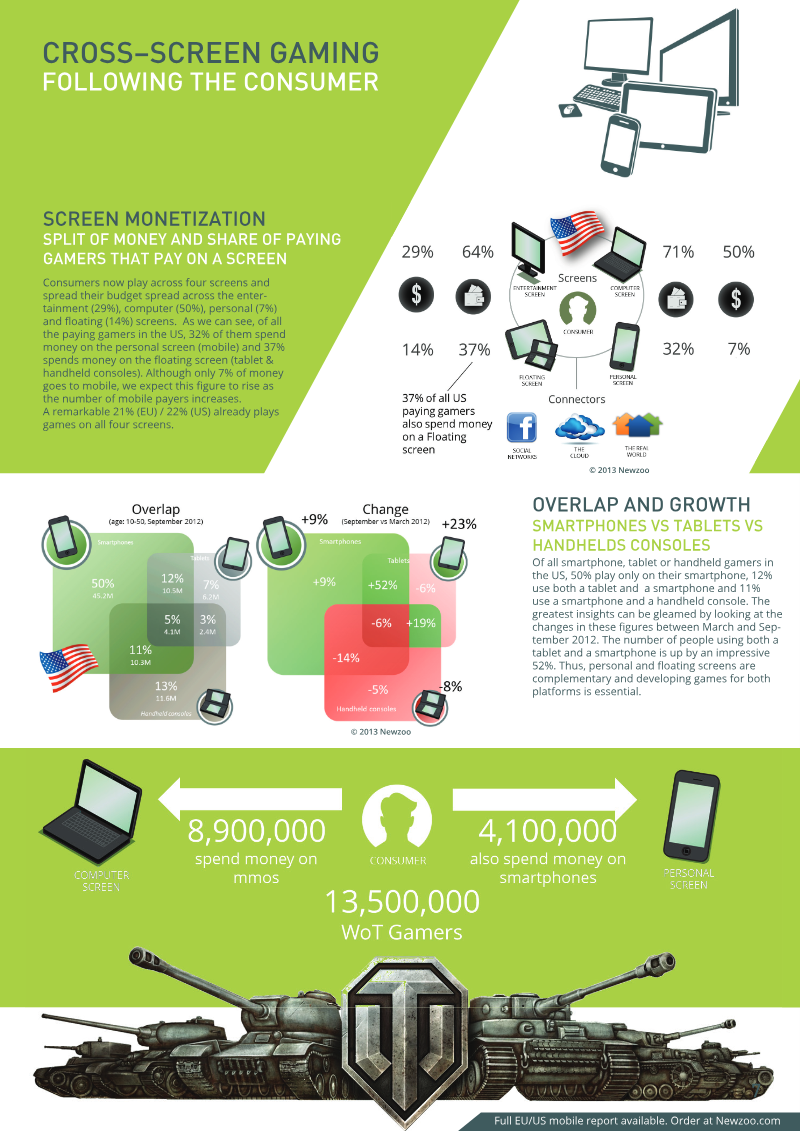
- Companies must shift from platform-centric metrics to a screen segmentation model that tracks player behavior, time investment, and conversion rates across devices.
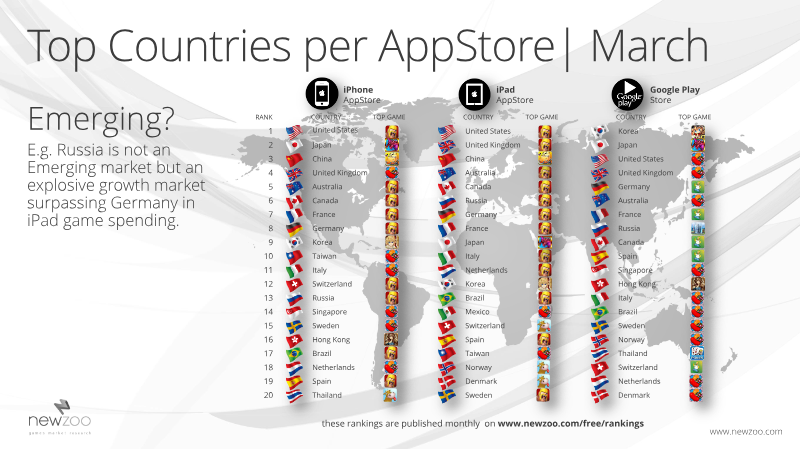
- Emerging markets, specifically Russia, are identified as the primary engines for industry-wide growth in the 2013 landscape.
Impact of Free-to-Play: Online, Mobile & Cross-Platform
The global games industry is undergoing a fundamental transformation as the traditional boxed product model stagnates in favor of free-to-play mechanics and cross-platform accessibility.
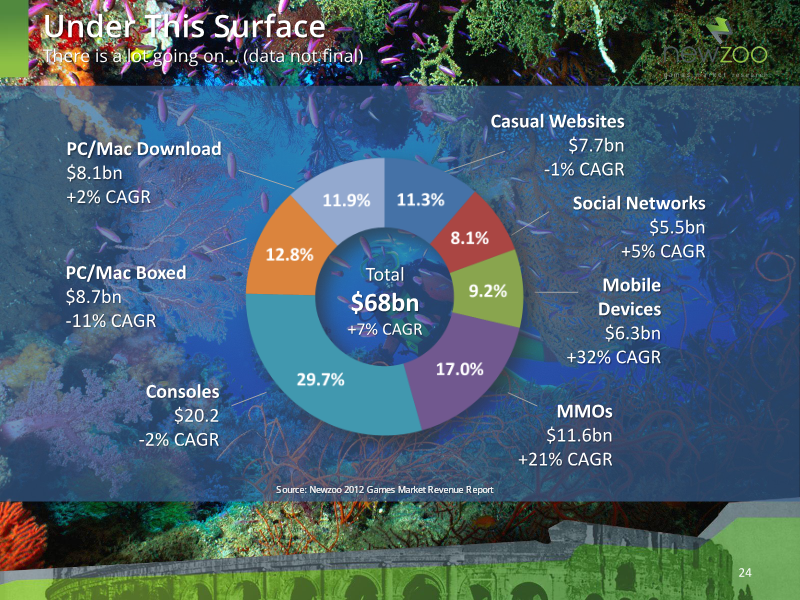
- The global games market is shifting from boxed products to a service-oriented model, with mobile revenue projected to grow at a 32% compound annual growth rate.
- Success in the current market requires treating free-to-play as a holistic business strategy rather than a pricing tactic, as evidenced by the performance of titles like League of Legends and Kingdoms of Camelot.
- Publishers must shift focus from legacy revenue metrics to tracking granular data points, specifically player engagement time and the conversion rates of paying users.
The Global Games Market: Trends, Market Data and Opportunities
The global games industry is currently undergoing a fundamental transformation characterized by the rapid ascent of mobile gaming and the professionalization of competitive esports.
- Mobile gaming is the dominant global revenue driver, with the United States, China, and Japan serving as the primary engines of growth.
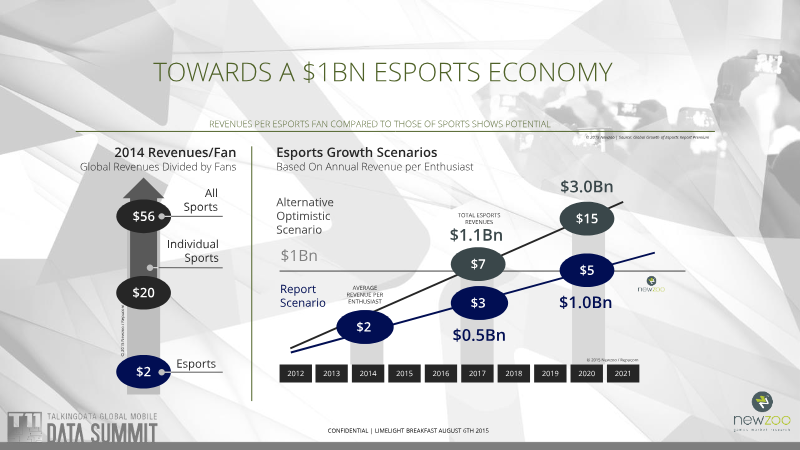
- The esports sector is projected to reach a $1 billion valuation by 2019, driven by the convergence of traditional sports and digital competitive play.
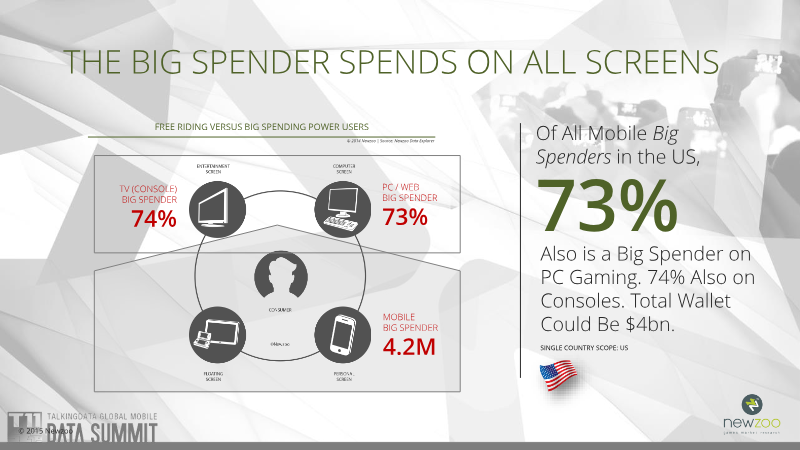
- In the United States, the most valuable consumer segment is comprised of employed, family-oriented males aged 21 to 35 who engage across multiple platforms.
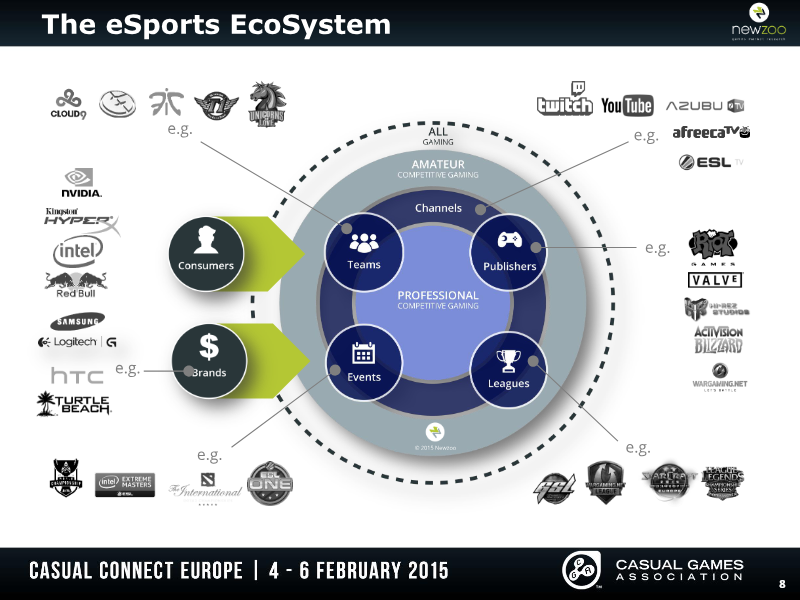
The eSports Economy: Trends, Audience and Revenue Growth Towards 2017
The eSports economy is experiencing rapid expansion, driven by a fundamental shift in how consumers interact with gaming content.
- The eSports enthusiast base is projected to exceed 100 million by 2017, maintaining a 20% compound annual growth rate between 2012 and 2017.
- Approximately 40% of eSports viewers are spectators who do not actively play the games they watch, indicating a shift toward viewing as a standalone entertainment medium.
- Streaming platforms are central to the industry's infrastructure, exemplified by Twitch reaching 100 million unique monthly viewers in 2014.
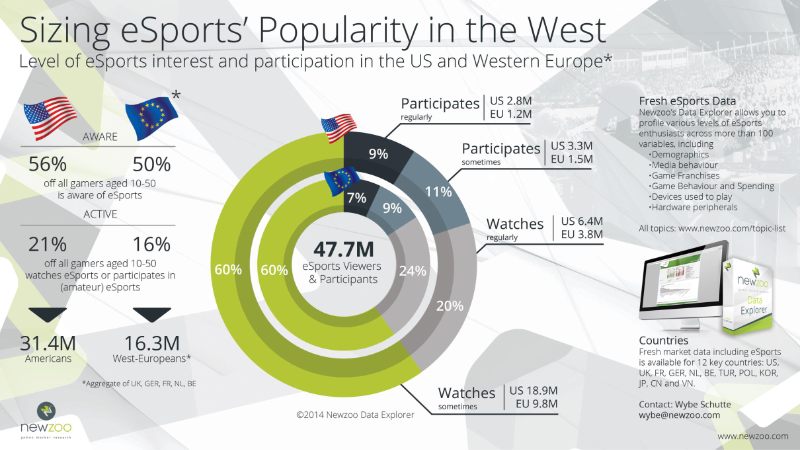
Sizing & Profiling eSports' Popularity: The West
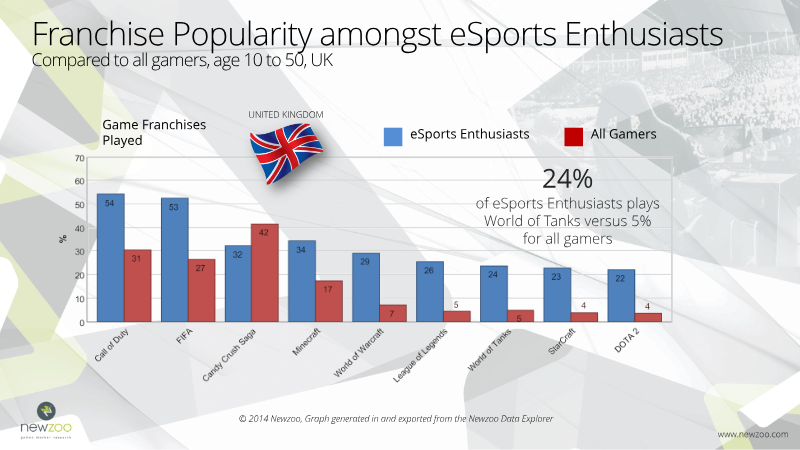
The rapid expansion of eSports in Western markets represents a significant shift in the gaming industry, driven by the rise of free-to-play titles such as League of Legends, Dota 2, and World of Tanks.
- eSports viewership is doubling year-over-year, with the average viewer watching over 10 times per month for an average session length of 2.2 hours.
- Total eSports prize money increased by 350% over the four-year period ending in 2013, with top events like The International 2013 awarding $2,874,381.
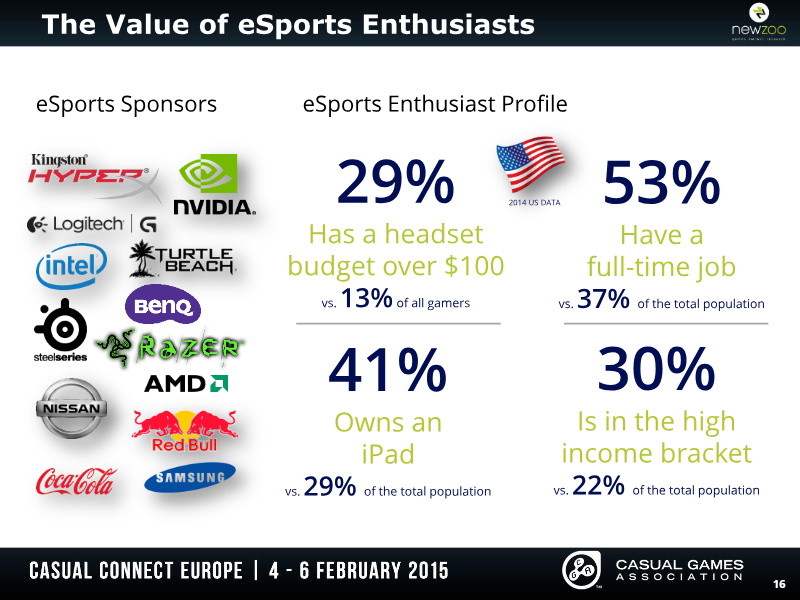
- eSports enthusiasts are significantly more valuable to publishers than the average gamer, with 22% of enthusiasts identified as 'big spenders' compared to only 8% of the general gaming population.
Understanding the iPhone: Current Usage and Trends
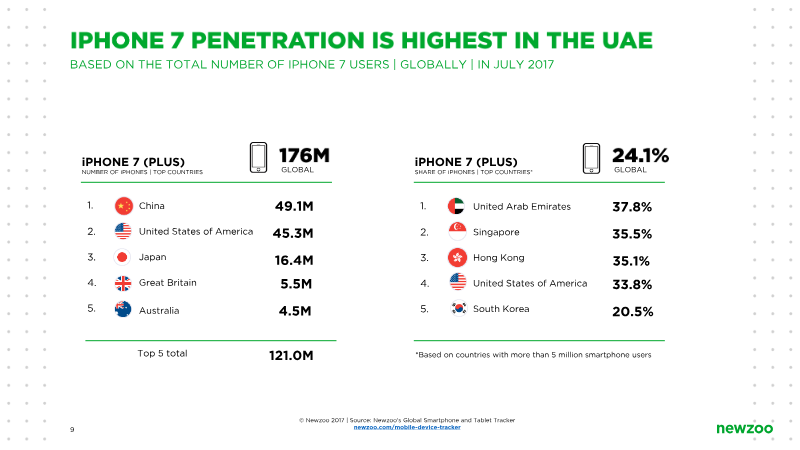
As of July 2017, the global landscape of iPhone usage reflects a decade of significant market penetration, with 730 million active devices worldwide.
- As of July 2017, there are 730 million active iPhones worldwide, representing approximately 10% of the global population.
- 61% of all iPhones ever sold since the 2007 launch remain in active use, with 82% of those active devices released in 2014 or later.
- China is the largest market for iPhone adoption with 243 million active users.
Betting on Billions: Unlocking the Power of Mobile Gamers
Mobile gaming represents a significant, underutilized opportunity for brands to engage a vast and influential consumer base.
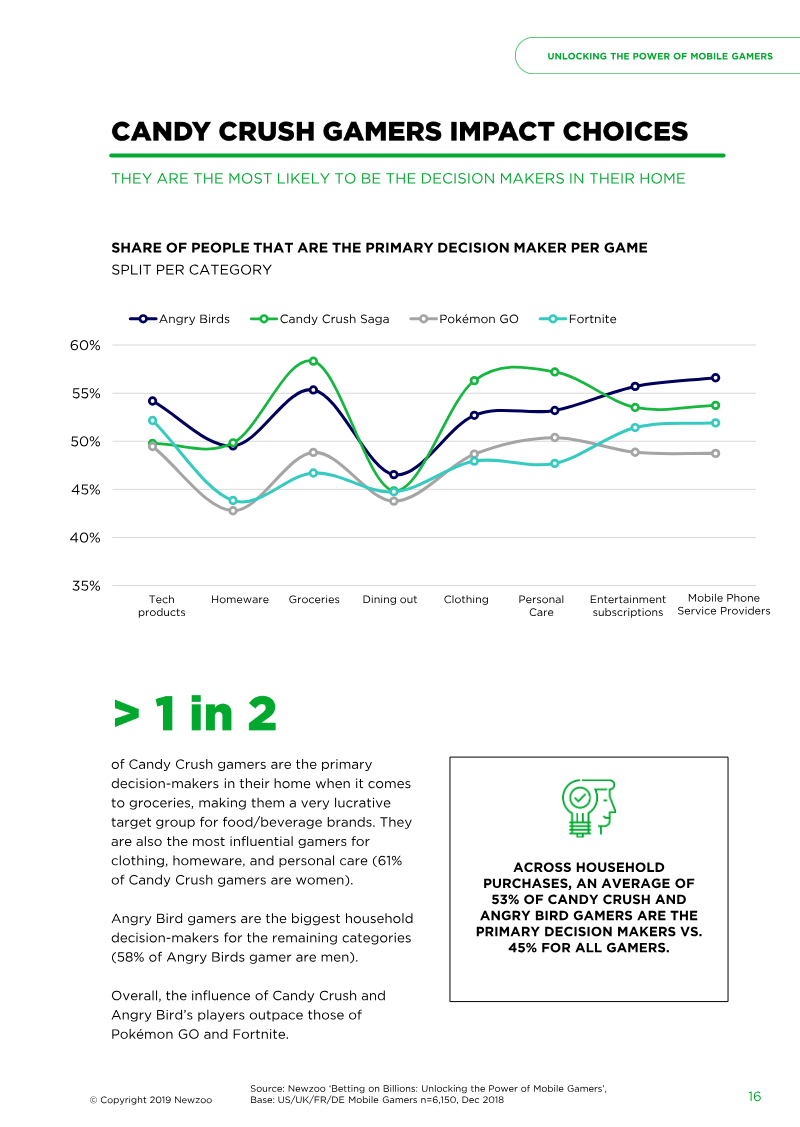
- Mobile gamers are 23% more likely than non-gamers to influence the purchasing decisions of their peers, family, and colleagues.
- Gaming is the third-most-popular app category globally, with 50% of surveyed users engaging with games on a weekly basis.
- Over half (53%) of mobile gamers report that they are receptive to advertising, viewing it as a helpful way to stay informed about products and services.
Casino Gaming Report & Data: US Social Casino Market
The social casino market in the United States exhibits high levels of engagement and monetization, characterized by a diverse player base that frequently interacts with multiple franchises.
- The US social casino market is highly fragmented, with the average user actively engaging with 5.6 different gaming titles.
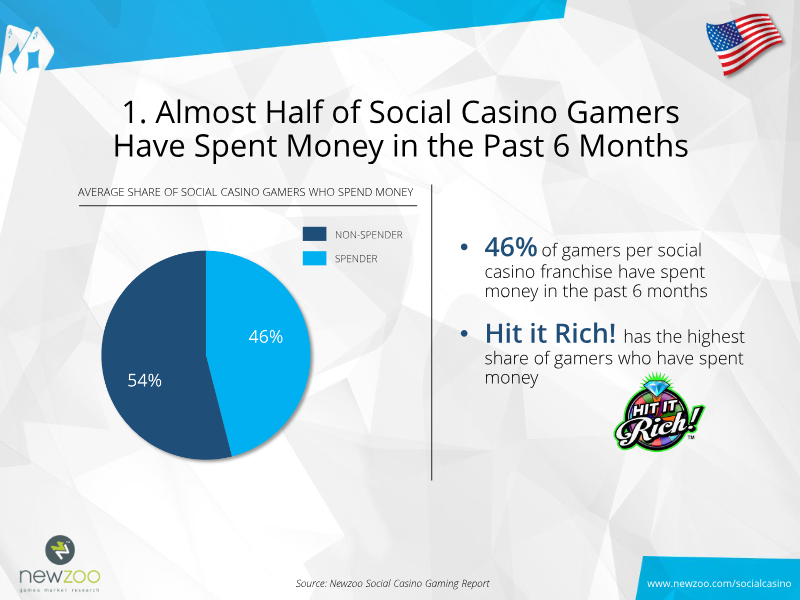
- Monetization is robust, as 46% of social casino gamers have made in-game expenditures within the last six months.
- Men aged 21 to 35 represent the largest segment of paying users, accounting for one-third of total industry spend.
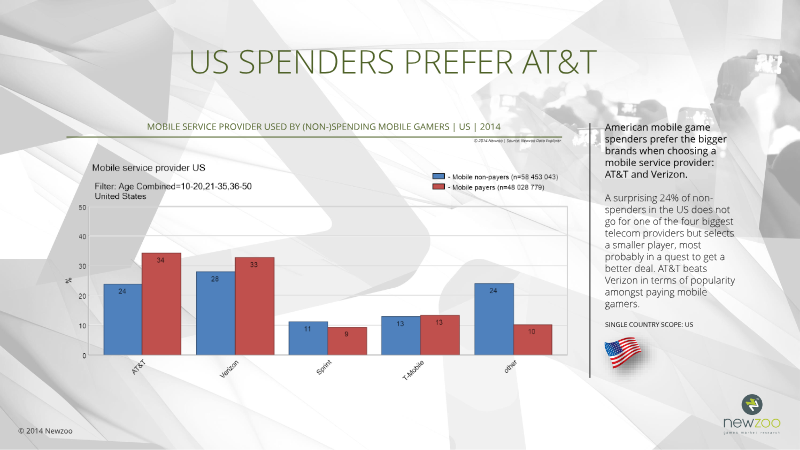
Spotting the Mobile Spenders: An Analysis of Paying Smartphone and Tablet Gamers
The mobile gaming industry is experiencing significant expansion, with global revenues projected to reach $25 billion in 2014.
- Mobile gaming is projected to reach $25 billion in global revenue by 2014, with mobile expected to account for 50% of total game revenues by 2017.
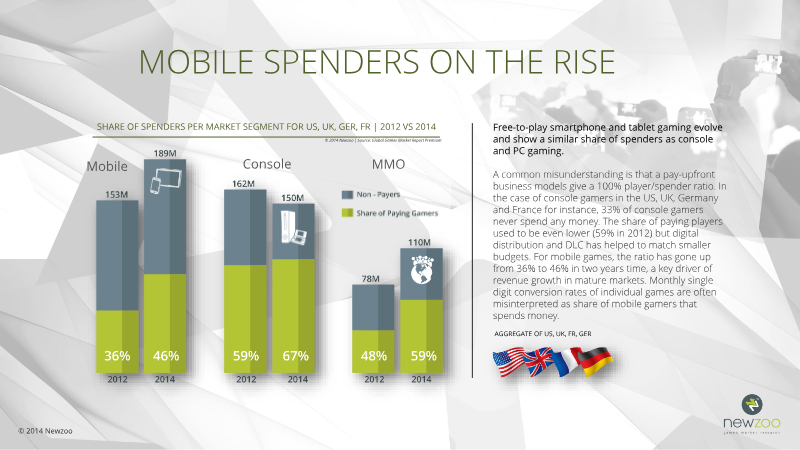
- The share of paying mobile users in Western Europe and the United States grew from 36% to 46% over the last two years, debunking claims of market saturation.
- The Amazon Appstore is an undervalued channel, as its users demonstrate a higher propensity to spend money compared to those on Google Play or Apple platforms.
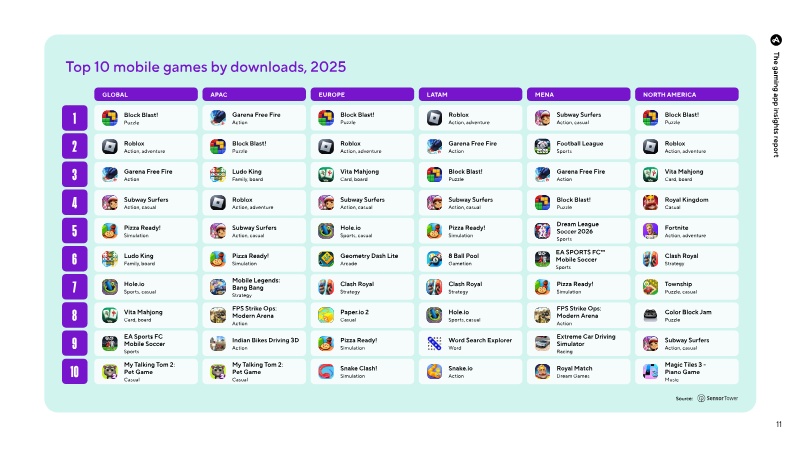
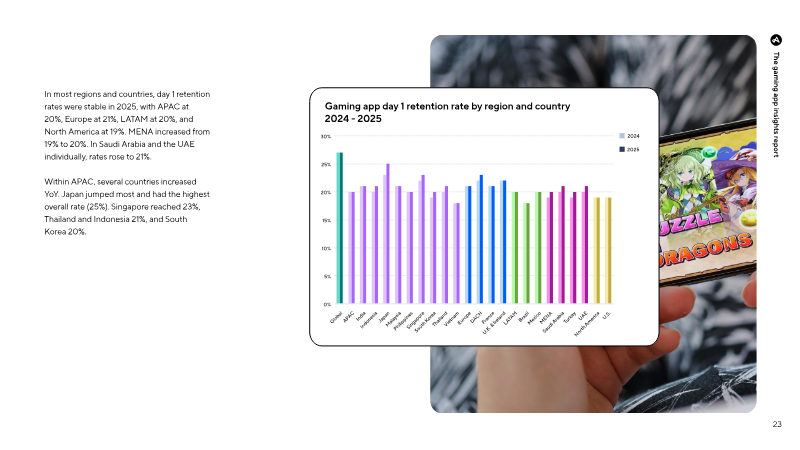
The Gaming App Insights Report: 2026 Edition
Adjust's 2026 gaming app report argues that the mobile gaming market has moved from a volume-driven model to one centered on retention and lifetime value, as acquisition costs climb and growth in installs slows.
- Global gaming app CPC rose 33% from $0.03 to $0.04 between 2024 and 2025, while global CPM increased 20% from $3.63 to $4.34.
- Hyper-casual games maintained the largest market share of installs at 29.1% in 2025, while action games dominated session share at 17.1%.
- Strategy games saw the most significant increase in session length, growing 18% to 37.51 minutes, and experienced a 133% surge in CPC from $0.03 to $0.07.
China Steam & PC Gaming Market Report: 2025
The Chinese PC gaming market has reached a valuation of approximately $11–12 billion within a broader national gaming industry worth RMB 350.78 billion.
- Steam dominates the Chinese PC gaming market with an 87% share, contributing to a total PC gaming valuation of approximately $11–12 billion.
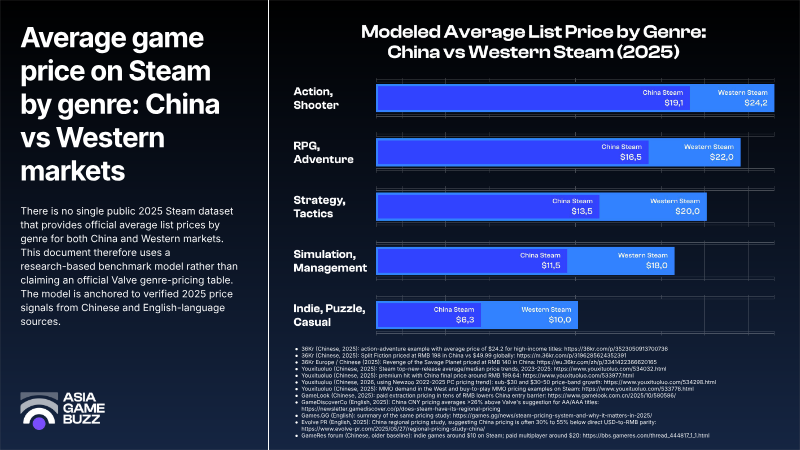
- Pricing for Steam titles in China must be adjusted 21% to 37% lower than Western benchmarks to align with local purchasing power and consumer expectations.
- Market discovery is driven by community-led engagement on platforms like Bilibili, TapTap, Heybox, and Sonkwo rather than traditional store-page traffic.