Market Analysis reports and market data
Documents
Video Game Market Update: Q2 2026
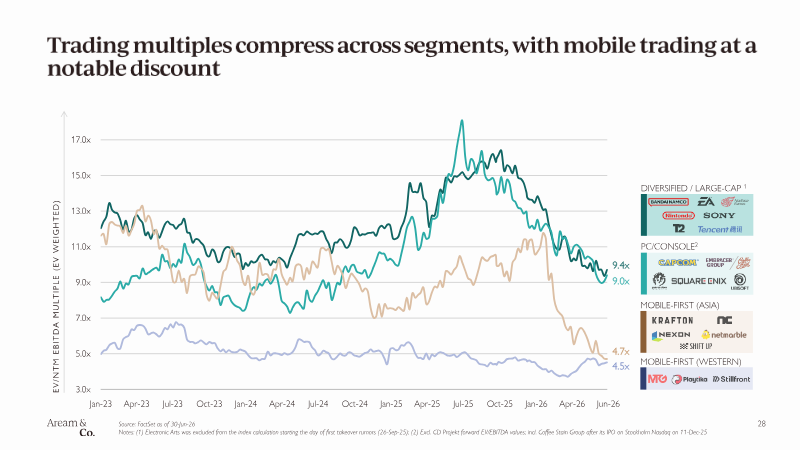
The global video game industry experienced a period of divergent performance during the second quarter of 2026, characterized by a resilient PC sector and a stagnant console market.
- Private investment in the gaming sector surged sixfold year-over-year to $3.1 billion, with capital increasingly shifting away from content development toward infrastructure, AI, adtech, and immersive hardware.
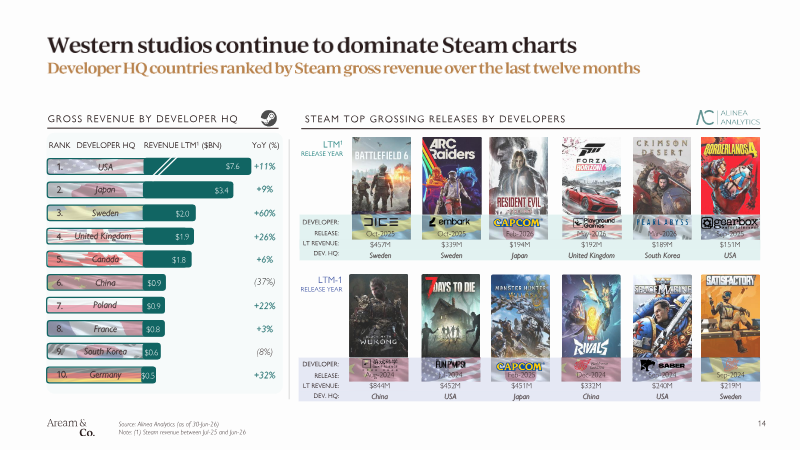
- The PC sector remains a primary growth driver with Steam recording a 13 percent year-over-year revenue increase, while the console market remains stagnant as Switch 2 gains offset declines in PlayStation and Xbox hardware.
- Mobile gaming is facing a downturn, evidenced by a 4 percent contraction in gross revenue and a 12 percent decline in new installs, with top charts remaining stagnant due to a reliance on legacy titles.
Essential Facts About the U.S. Video Game Industry: 2026
The 2026 Essential Facts About the U.S.
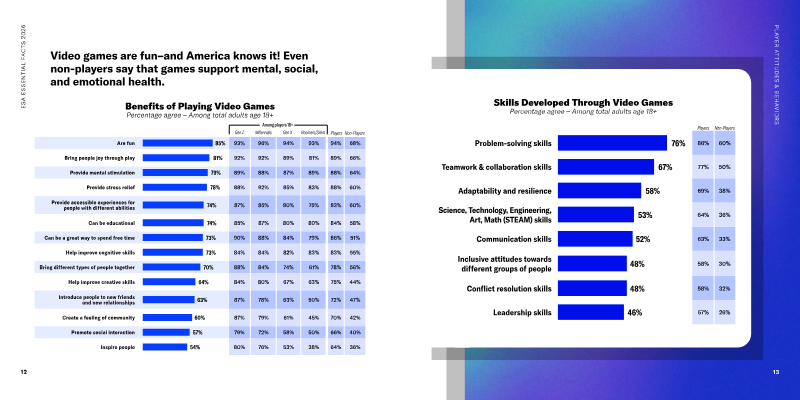
- The U.S. video game industry reaches 212.3 million Americans, representing 67% of the total population.
- The average American gamer is 37 years old, with a gender distribution that is nearly equal across all generations.
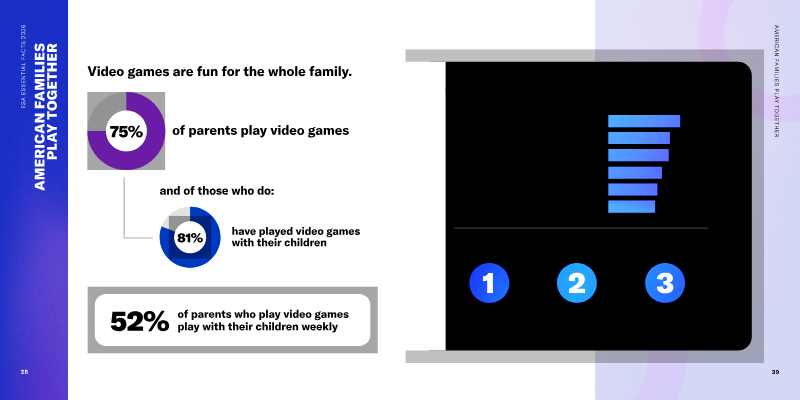
- Gaming is a primary social activity, with 70% of players interacting with others and 81% of gaming parents playing alongside their children.
Direct-to-Consumer: A $17 Billion Market for Mobile Gaming
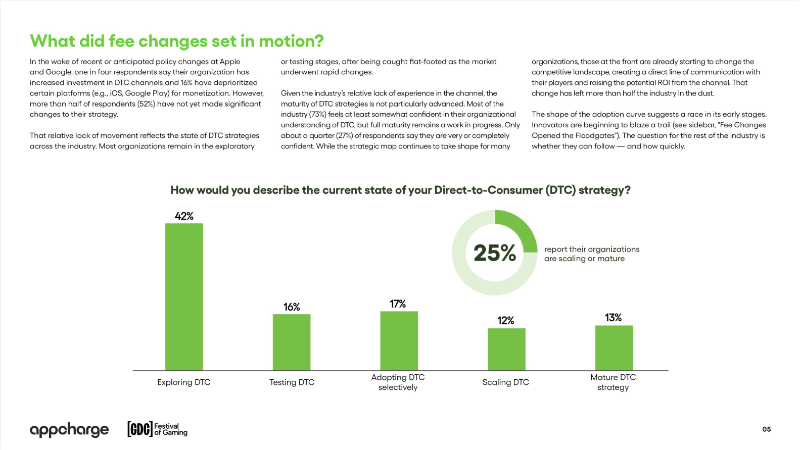
The mobile gaming industry is undergoing a fundamental structural shift toward direct-to-consumer (DTC) distribution models, a transition that has already established a $17 billion market.
- The mobile gaming direct-to-consumer (DTC) market has reached a valuation of $17 billion as publishers shift away from traditional app store ecosystems to reclaim platform fees.
- The global in-app purchase market is projected to grow to $721.4 billion by 2034, signaling a long-term shift toward DTC distribution across the digital economy.
- DTC models allow publishers to secure ownership of first-party player data, which is being used to drive long-term retention and competitive differentiation.
Essential Facts about Video Games in Italy: 2025
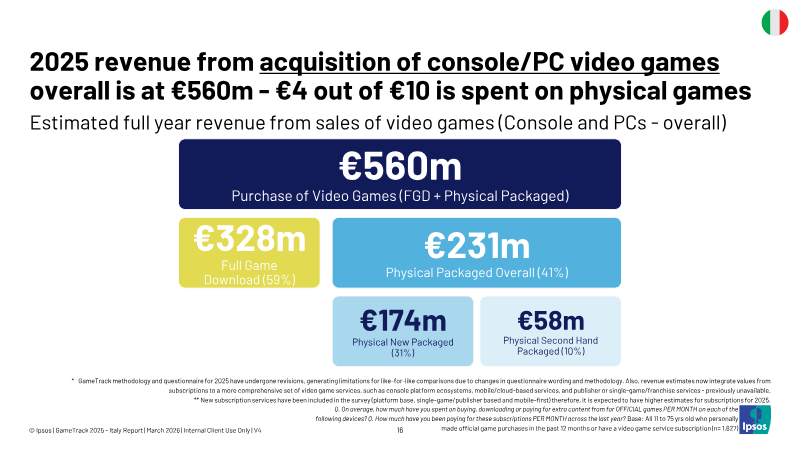
In 2025, roughly 14.2 million Italians—about a third of the population aged six to seventy-five—engage in video gaming, with a pronounced male bias and a concentration of players under 35.
- The Italian video game market generated €2.4 billion in 2025, with game sales accounting for 77 percent (€1.8 billion) of total revenue.
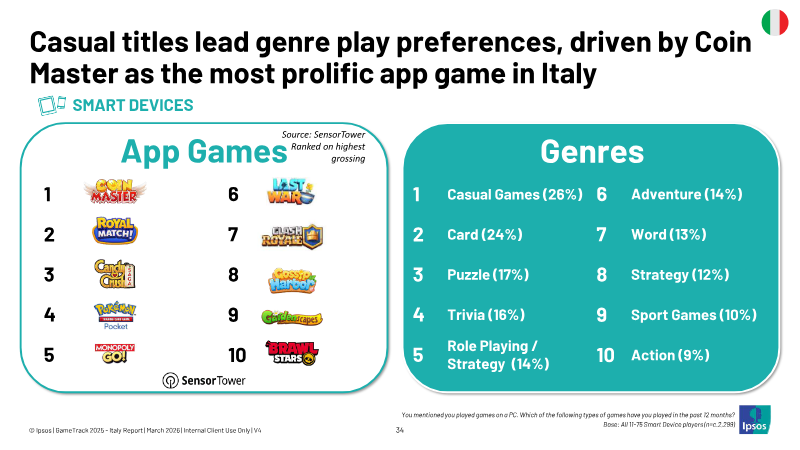
- App-based gaming dominates the market, representing over half of total revenue with a freemium model where only one percent of earnings come from upfront purchases.
- Smart devices are the primary revenue driver at €929 million, while console gaming accounts for €643 million, supported by an average of eight hours of gameplay per week across the population.
Is There a Shift from Content to Tech Startups Among Gaming VCs?
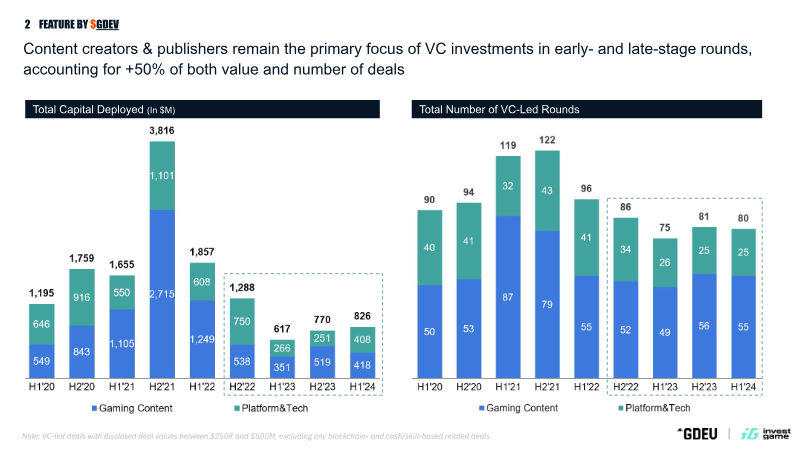
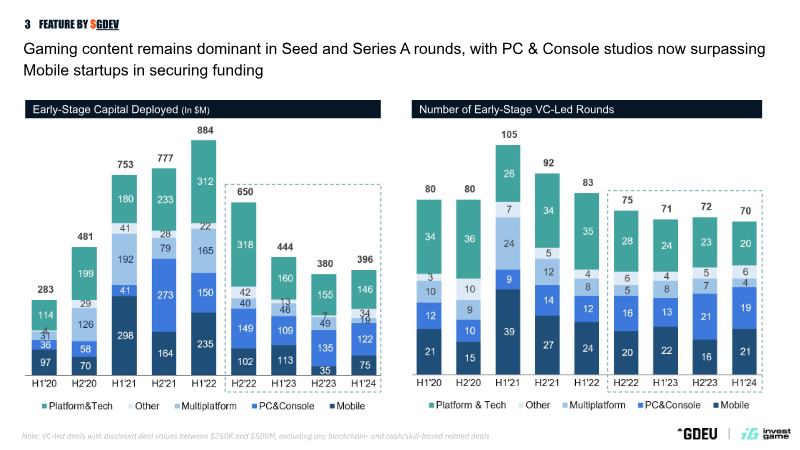
The analysis examines venture capital activity in the gaming sector from 2020 to early 2024, focusing on whether investment priorities are shifting from traditional content creation and publishing toward technology-driven startups.
- Content creators and publishers remain the primary focus of gaming VC, accounting for over half of all capital deployed (approximately $1.76 billion) and the majority of deal volume across all stages.
- Gaming-focused VC funds, including VENTURES, BEHOLD Venture, and Lightspeed Lvp., significantly increased their activity between 2020 and H1 2024, with capital deployed rising from $1.3 billion to over $2.4 billion.
- The number of VC-led funding rounds grew substantially from 67 in early 2020 to 289 by H1 2024, reflecting an overall increase in investment activity.
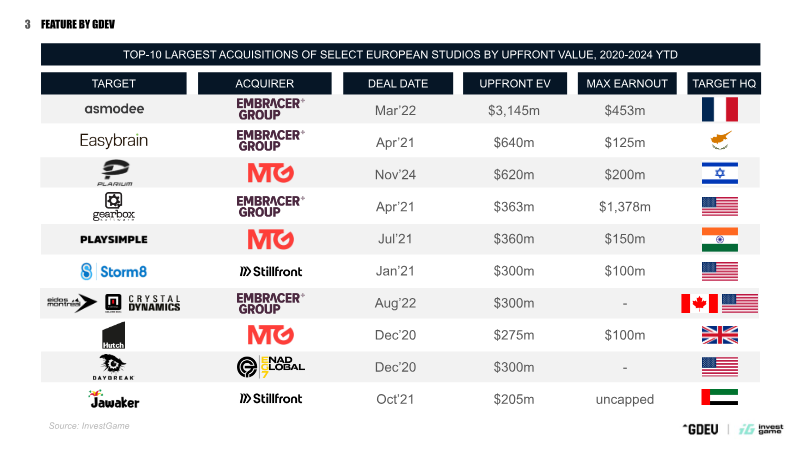
Europe’s Gaming Consolidators: The Magnificent Seven Post-M&A Rush
The analysis examines the surge of M&A activity among European gaming publishers between 2020 and 2024, highlighting a capital deployment of $19 billion across more than 140 deals.
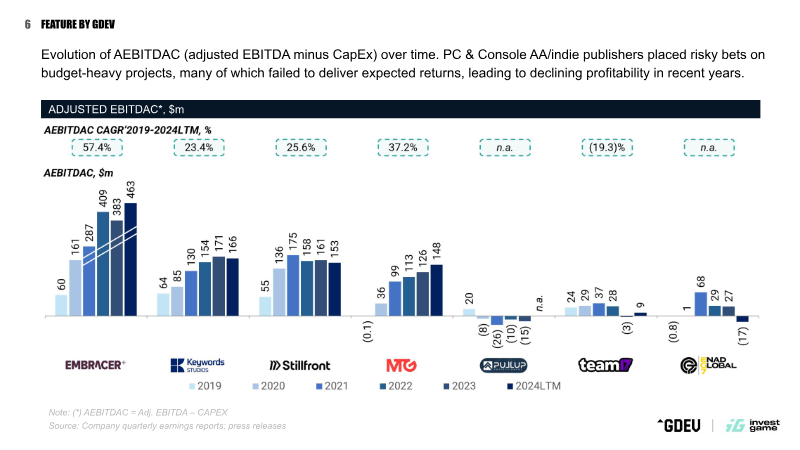
- Between 2020 and 2024, seven major European gaming consolidators deployed $19 billion across over 140 deals, with mienn Easybrain Group accounting for 78 deals totaling $14.1 billion.
- Aggressive inorganic growth strategies failed to deliver sustainable shareholder value, as evidenced by a market cap collapse from a $25.5 billion peak in April 2021 to approximately $5.4 billion.
- Share prices for the primary acquirers corrected significantly, falling 30–70% from December 2019 levels as valuation multiples contracted from highs of 30× EV/NTM revenue.
The Alumni Effect: Studios Founded by Ex-Activision, Blizzard, and King Employees
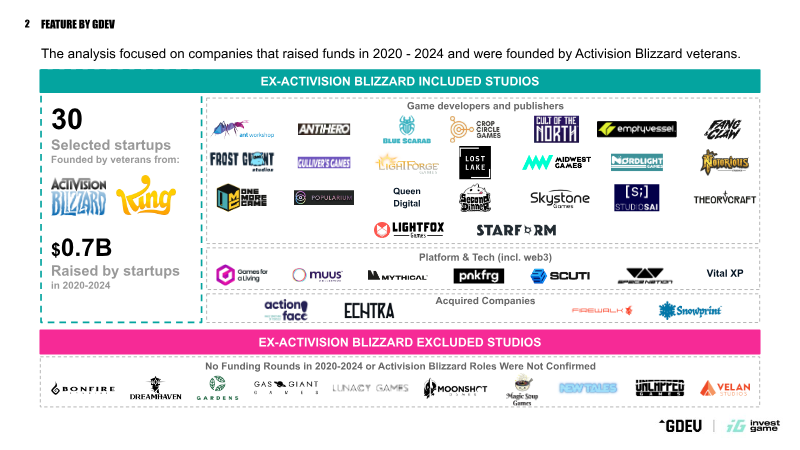
The analysis examines venture capital activity directed toward studios founded by former Activision Blizzard employees between 2020 and 2024.
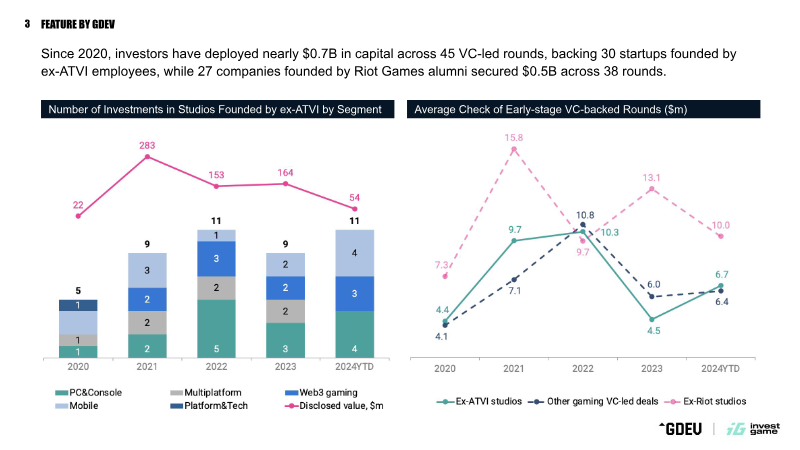
- Between 2020 and 2024, 30 studios founded by former Activision Blizzard employees secured approximately $0.7 billion in venture capital across 45 funding rounds.
- Ex-Activision studios demonstrate a 'first-round momentum' effect, being roughly four times more likely than peer startups to secure a second round of financing within the same calendar year.
- Investor confidence in alumni teams peaked in 2021, when 43% of ex-Activision studios raised a subsequent round compared to only 9% of broader gaming startups.
Game & Network Services Segment Presentation
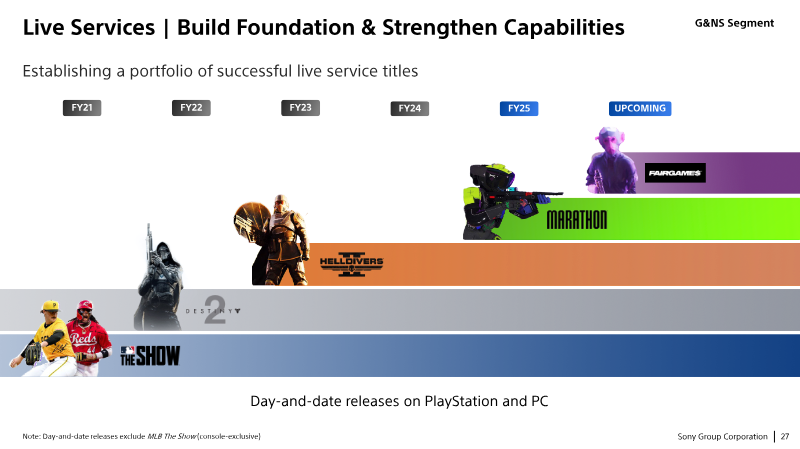
Sony Interactive Entertainment’s Game & Network Services segment demonstrates a clear trajectory of growth and increasing operating leverage.
- Sony’s Game & Network Services segment has achieved a significant financial turnaround, growing from a $4 billion operating loss in 2000 to $13 billion in operating income by 2024.
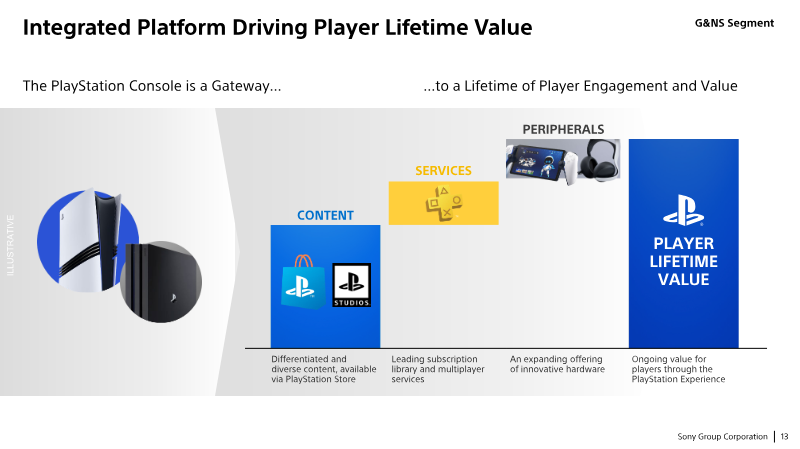
- Revenue is increasingly driven by services, the PlayStation Store, and peripherals, which now account for 52–54% of the segment's total revenue.
- The PlayStation ecosystem has reached 124 million monthly active users, representing a 14% year-over-year increase, with a life-to-date spend of $846 per console.
Public Mobile Gaming Publishers: Resilience & Adaptation in a Shifting Landscape
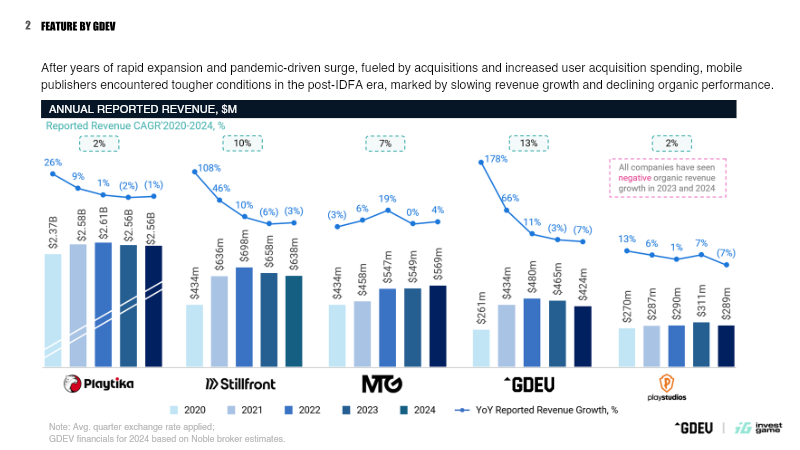
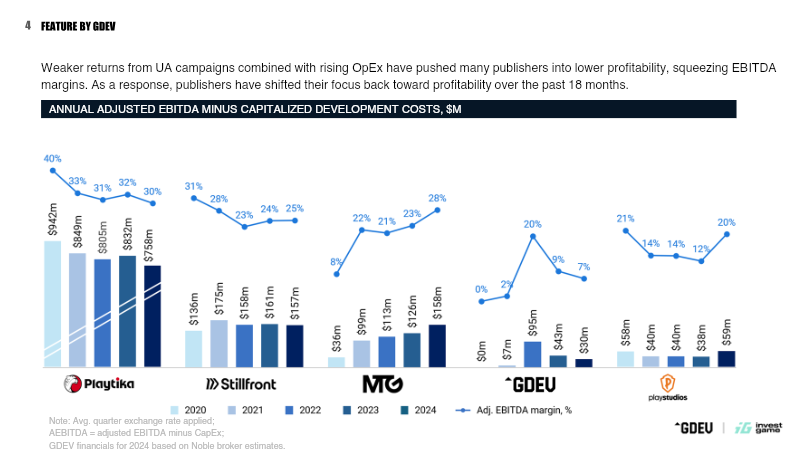
The analysis examines the post-IDFA mobile gaming landscape, focusing on revenue dynamics, user acquisition spending, profitability trends, and market valuation shifts across key publishers.
- Aggregate market capitalization for major mobile gaming publishers has plummeted by more than 50% since January 2022, with most stocks remaining below pre-IDFA valuation peaks.
- User acquisition costs have surged to as high as $40 million per firm, while diminishing returns on these campaigns have compressed EBITDA margins and forced a shift toward cost control.
- MTG outperformed the broader market with a 50%+ share price increase and 9% organic growth in Q4 2024, driven by disciplined M&A and operational efficiency.
Enabling Growth: Cohort User Acquisition Financing
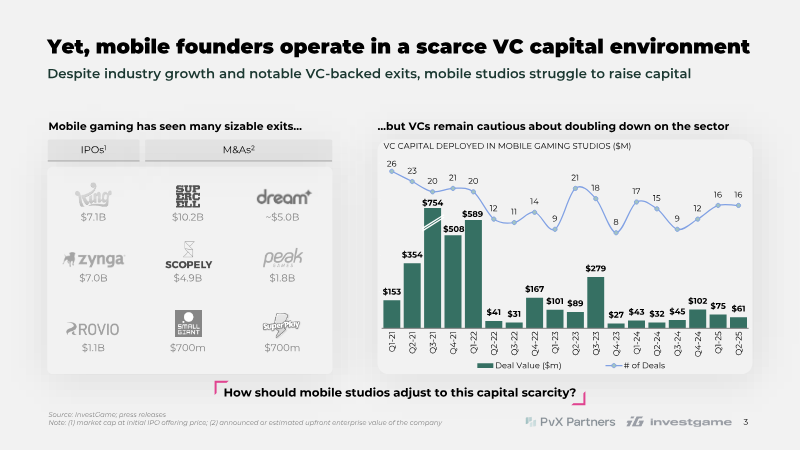
Mobile gaming has rebounded from the downturn of 2022-23, with a projected compound annual growth rate of 5.0% from 2020 to 2025, driven largely by a 16.2% rise in in-app advertising and the continued popularity of casual puzzle titles.
- Mobile gaming is projected to grow at a 5.0% CAGR from 2020 to 2025, supported by a 16.2% increase in in-app advertising and AI-driven ad tech.
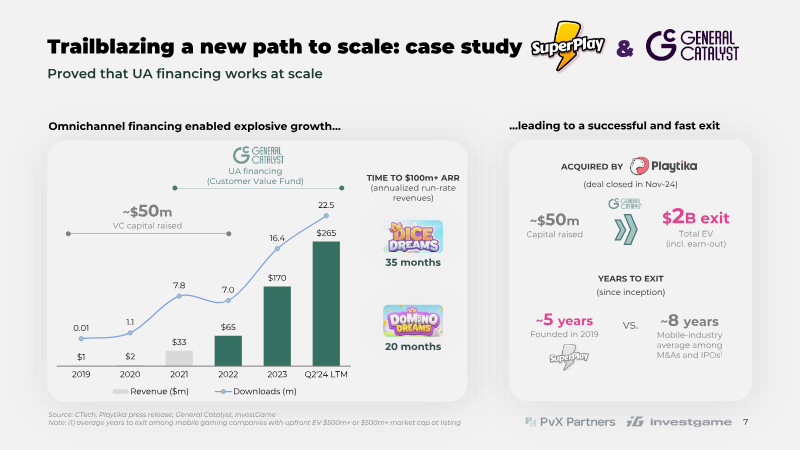
- Cohort-based UA financing allows studios to fund up to 80% of monthly acquisition costs by leveraging future revenues, providing an alternative to scarce venture capital.
- Studios utilizing cohort-based financing have demonstrated the ability to increase monthly marketing spend by 16–38% while maintaining founder control over equity and IP.
The 2025 Benchmark Report: Roblox Platform Trends
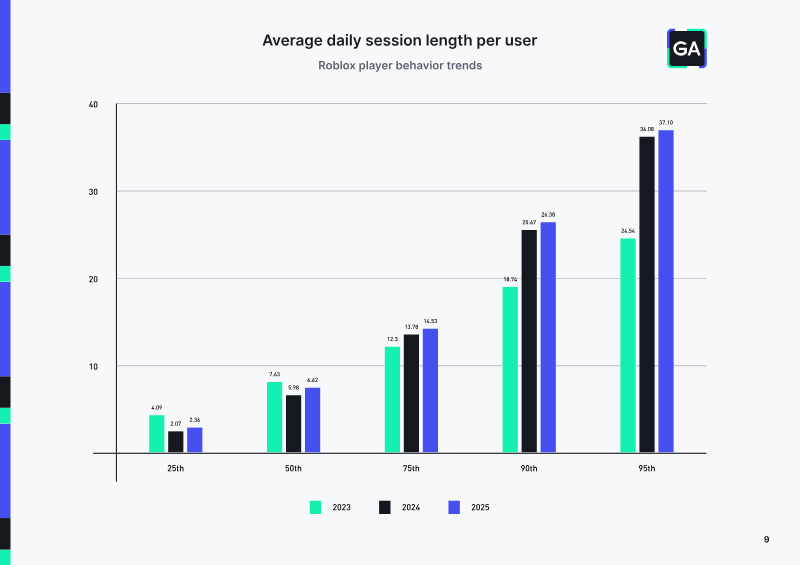
The report establishes that Roblox’s player base is sharply divided between casual users who spend only a few minutes per session and core players who log in multiple times daily, often exceeding 30-minute sessions.
- Games with median session lengths under six minutes suffer from negligible Day-1 retention of approximately 6% and ARPPU below $1, while top-tier titles achieve ARPPU exceeding $6 with average transaction values of $3–$4.
- The top 5% of Roblox games generate over $20 per day from a single player, demonstrating that sustained engagement is the primary driver of high-value monetization.
- Platform discovery algorithms prioritize games with consistent 7-day spend and high engagement, causing low-engagement titles to fall below 5% Day-1 and 2% Day-7 retention.

The Rise of the Financial Kingmakers: Private Equity’s $21B+ Bet on Gaming
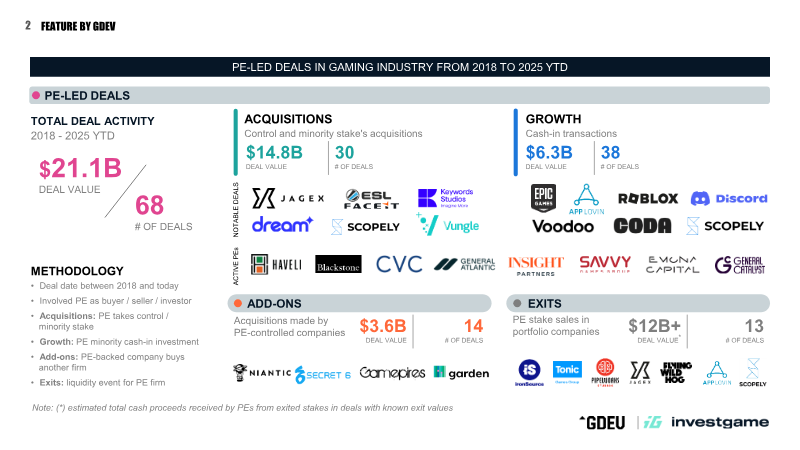
The analysis demonstrates that private equity (PE) has increasingly positioned itself as a decisive force in the gaming sector, channeling more than $21 billion into acquisitions and growth investments from 2018 through the first half of 2025.
- Private equity firms deployed over $21 billion into the gaming sector between 2018 and mid-2025, with annual deal values consistently surpassing $1 billion.
- Control acquisitions represent the primary investment strategy, accounting for approximately 60% of total capital deployed in the sector.
- Content creation studios holding strong IP portfolios are the most targeted assets, securing 42 of the 68 total private equity-led deals identified.