1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReport InvestGame
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReportInvestGame
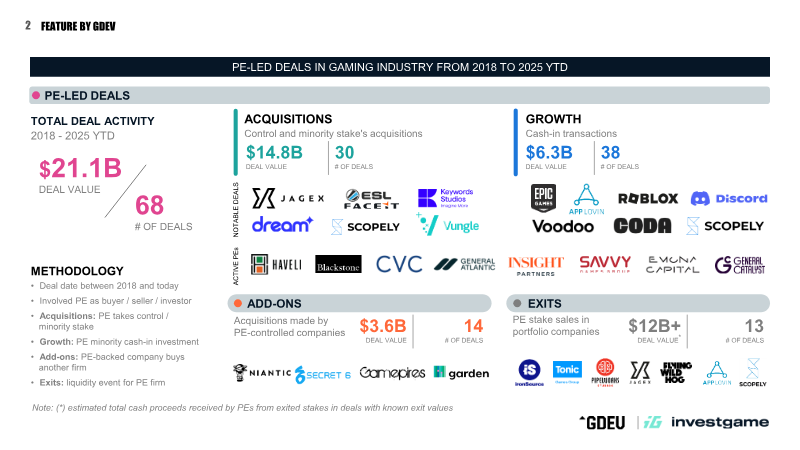
Private equity channelled more than $21 billion into acquisitions and growth investments in the gaming sector. Annual deal values consistently exceeded $1 billion.
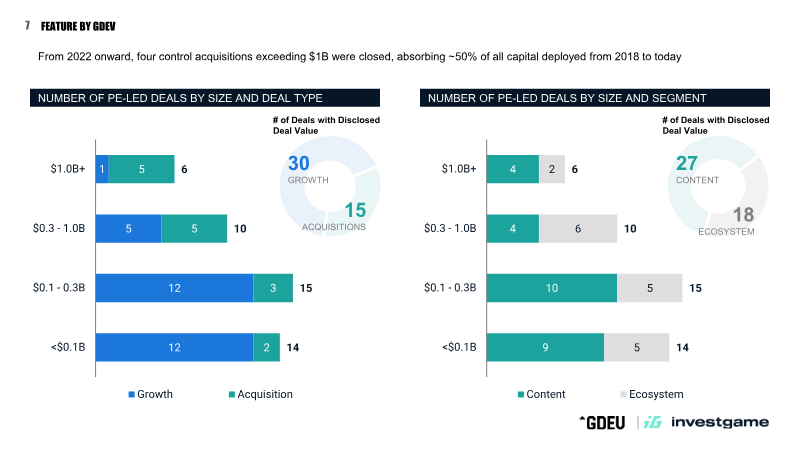
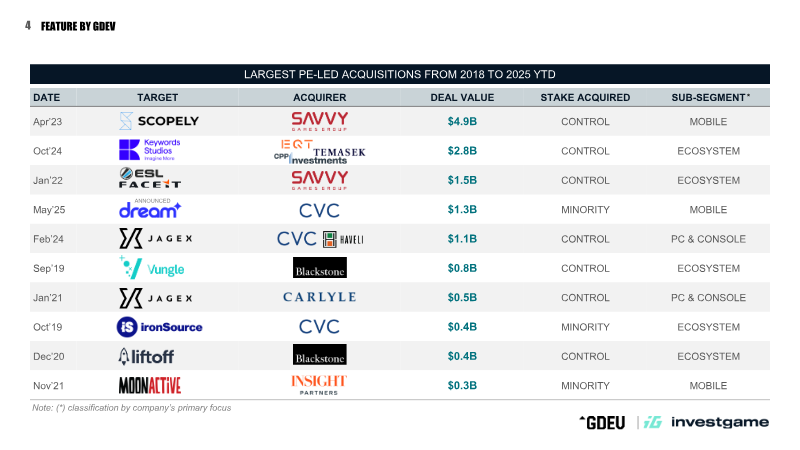
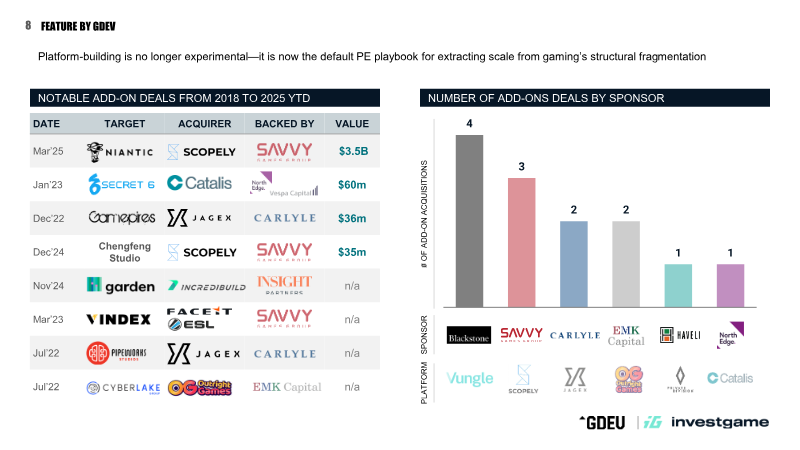
The analysis demonstrates that private equity (PE) has increasingly positioned itself as a decisive force in the gaming sector, channeling more than $21 billion into acquisitions and growth investments from 2018 through the first half of 2025. Annual deal values consistently exceeded $1 billion, underscoring the industry’s institutional maturity and attracting a broad spectrum of PE participants. Control acquisitions dominate, accounting for roughly 60% of total capital deployed, with notable deals such as Scopely’s $4.9 billion purchase of Games Group and ESL’s $1.5 billion takeover of Facet Games Group. Minority stake purchases, while smaller in dollar terms, remain significant for content and ecosystem players, exemplified by Vungle’s $0.8 billion control of an ecosystem firm.
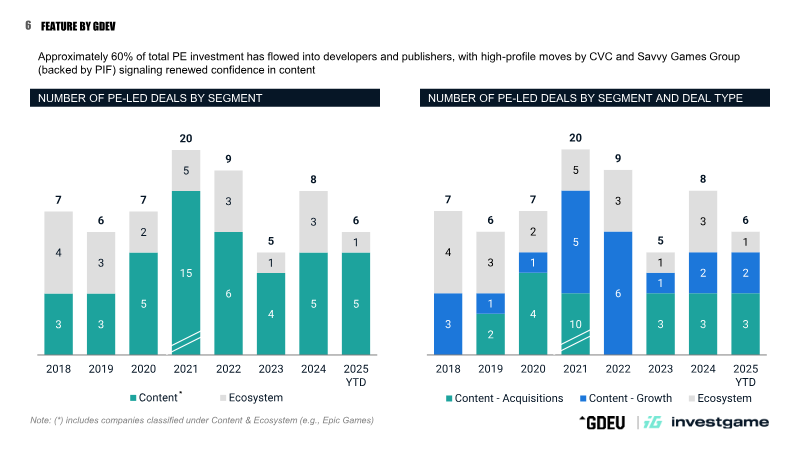
Geographically, the focus is global but heavily weighted toward North America and Europe, with a growing presence in mobile and PC/console segments. The data reveal that content creation—particularly studios with strong IP portfolios—is the most attractive segment, receiving 42 of the 68 PE-led deals. Ecosystem investments, including platform and service providers, constitute a substantial share of growth capital, reflecting PE’s strategy to build scalable ecosystems around core IP.
Methodologically, the study aggregates publicly disclosed transactions from 2018 to mid-2025, classifying deals by type (control acquisition, minority stake, growth investment, add-on) and segment. Deal values are sourced from press releases, SEC filings, and reputable financial databases, with exit returns estimated where available. The findings illustrate a shift toward platform-building and ecosystem consolidation as the default PE playbook, positioning financial investors as key enablers of scale in a structurally fragmented gaming market.
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
InvestGame · 2026
Deconstructor of Fun · 2026