Discovery
CompanyJapan
Documents about Discovery
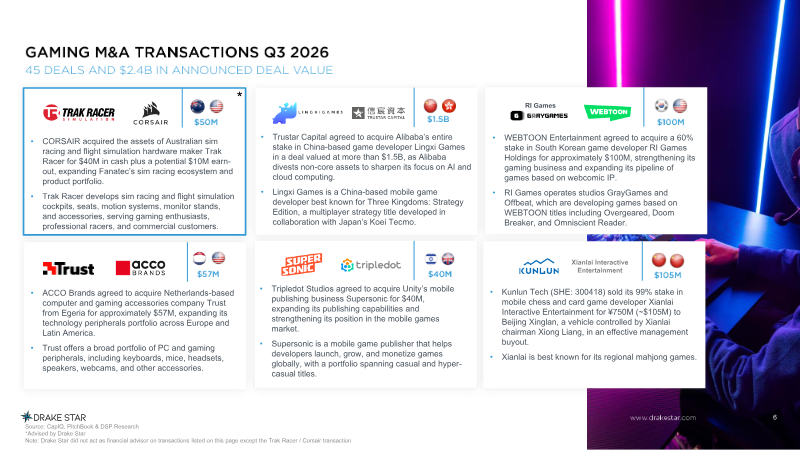
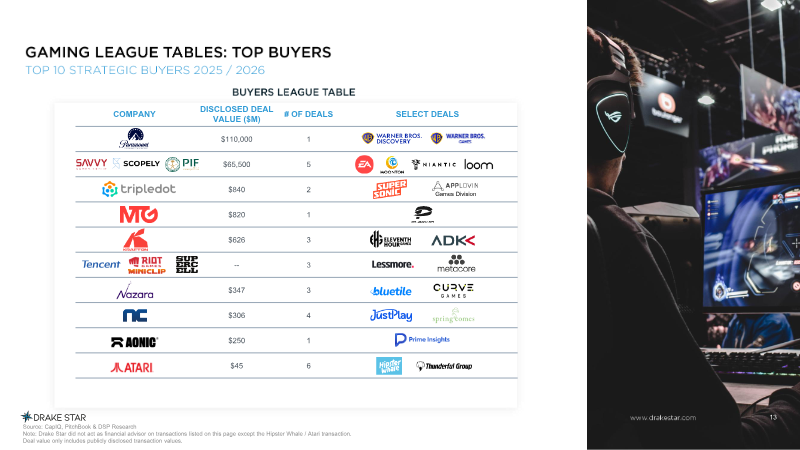
Global Gaming Report: Q3 2026
The global gaming industry experienced a period of significant financial revitalization during the third quarter of 2026, characterized by a robust rebound in market valuations and sustained investment activity.
- The gaming industry saw $4 billion in total capital activity in Q3 2026, comprising $2.4 billion across 45 M&A deals and $1.6 billion in private financing.
- Over 80 percent of private funding was directed toward AI-native development, 3D foundation models, and advanced tools, with notable investments in Tripo AI, Nex, and PixVerse.
- The Drake Star Gaming Index reported a 12.4 percent return for the quarter, reflecting a strong recovery in market valuations.
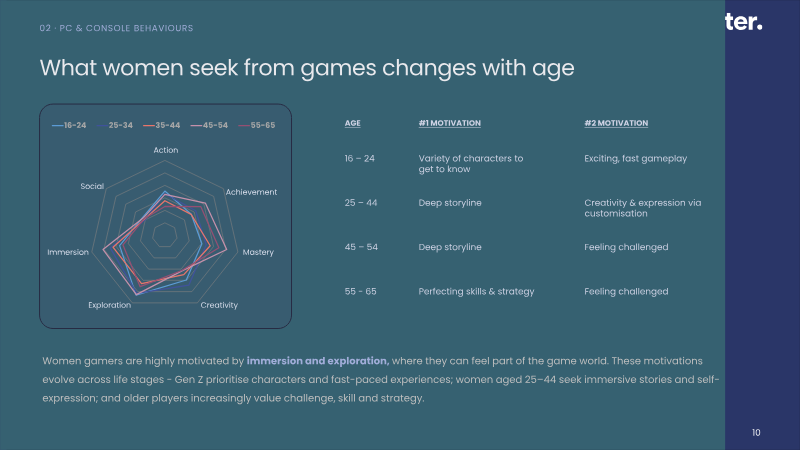
Women Gamers 2026: 9th Annual Edition
The ninth annual edition of the Women Gamers study provides a comprehensive analysis of how women engage with the gaming industry, drawing on nine years of longitudinal research.
- Toxicity remains a significant barrier to engagement, with 51% of all women reporting negative experiences, a figure that spikes to 79% among Gen Z players.
- To avoid harassment, many women are actively hiding their gender or opting out of voice chat, contributing to a broader industry trend where solo play is increasingly preferred over multiplayer experiences.
- While women play an average of six genres, engagement on PC and console platforms has plateaued since 2024 as Gen Z players increasingly prioritize social media over traditional gaming.
Global Gaming Report Q1 2026
The global gaming industry experienced a period of significant structural realignment during the first quarter of 2026, characterized by a surge in high-value consolidation alongside a cooling of public market sentiment.
- Q1 2026 saw 106 private placement deals totaling $785 million, a significant decrease from Q1 2025's $5.0 billion across 149 deals, indicating a cooling investment landscape.
- Project financing is now the primary funding path for studios due to headwinds in studio equity, with dedicated User Acquisition (UA) funds emerging as a new lifeline for mid-stage mobile studios.
- Key strategics to watch include PIF/Scopely, KRAFTON, NCSoft, Tencent, MTG, Take-Two, Netflix, everplay, and Keywords Studios, while Private Equity is expected to drive take-private transactions of publicly listed gaming firms.
The AI Disruption Index: How AI Is Reshaping Consumer Discovery
The AI Disruption Index demonstrates that artificial intelligence is fundamentally altering how U.S. consumers discover and purchase brands, with one-third of adults now using personal AI agents to find products and nearly half employing AI for purchase research.
- One-third of U.S. adults now use personal AI agents for product discovery, while nearly 50% utilize AI for purchase research.
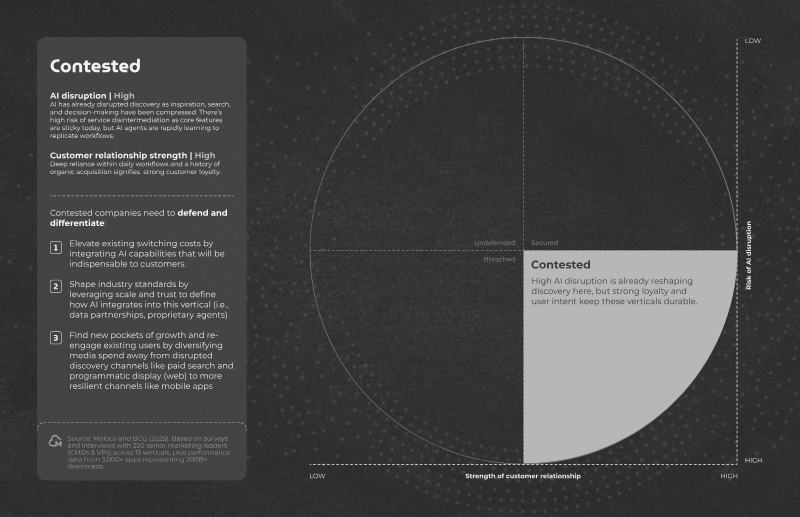
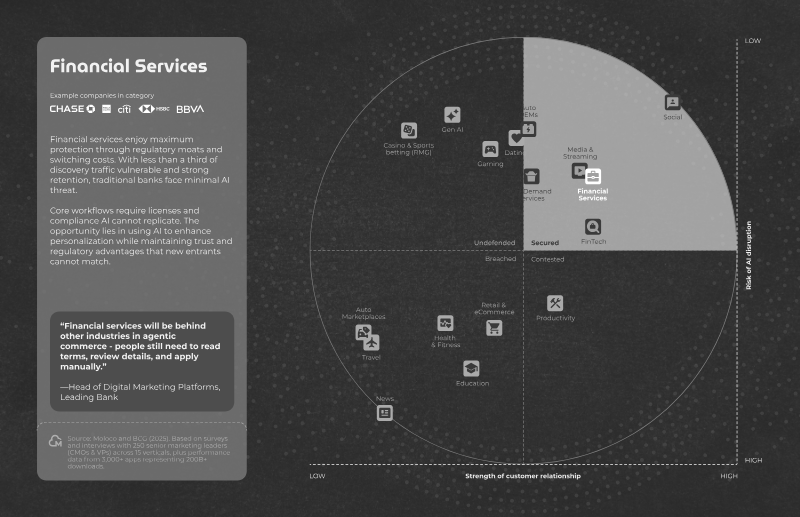
- AI-driven 'zero-click' discovery is actively eroding traditional paid search and organic search channels, threatening sectors like retail, education, and health & fitness.
- Sectors with strong regulatory or content moats, specifically financial services, media rights holders, and auto OEMs, currently maintain a defensive advantage against AI disintermediation.
Global Gaming Report 2025
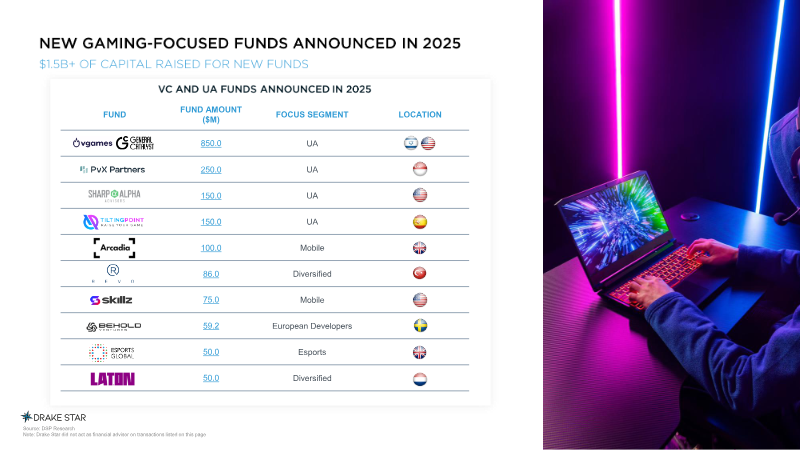
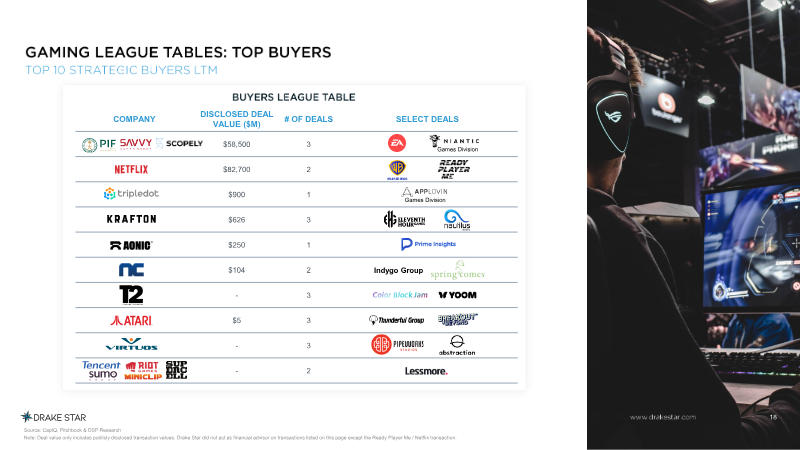
The global gaming industry experienced a transformative year in 2025, defined by unprecedented consolidation and a strategic pivot toward artificial intelligence.
- The gaming industry saw record-breaking M&A activity, headlined by Netflix’s $82.7 billion acquisition of Warner Bros. Discovery’s gaming division and a $55 billion buyout of Electronic Arts.
- Private financing rebounded with 509 deals totaling $6.2 billion, as investors shifted capital toward AI-focused infrastructure and mobile platforms.
- The Drake Star Gaming Index rose 12 percent in 2025, reflecting overall sector resilience despite a 0.5 percent stagnation in the mobile gaming market.
Understanding Korea’s Indie Game Audience in 2024
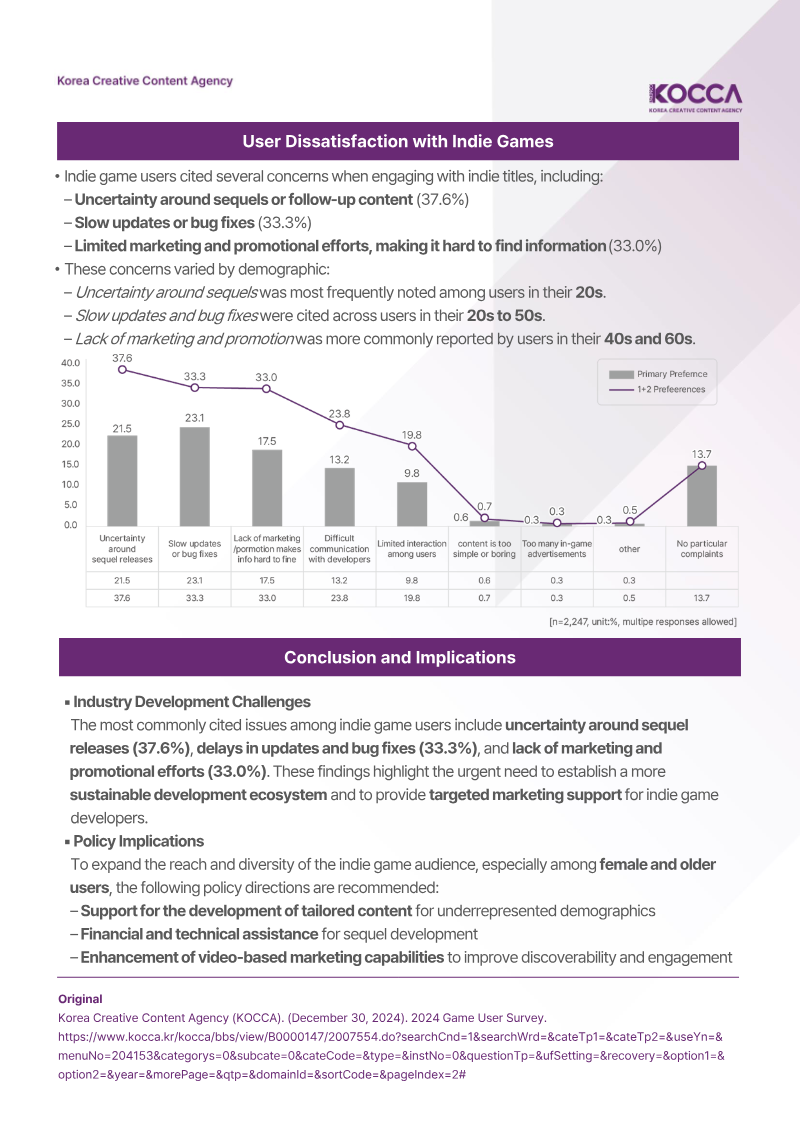
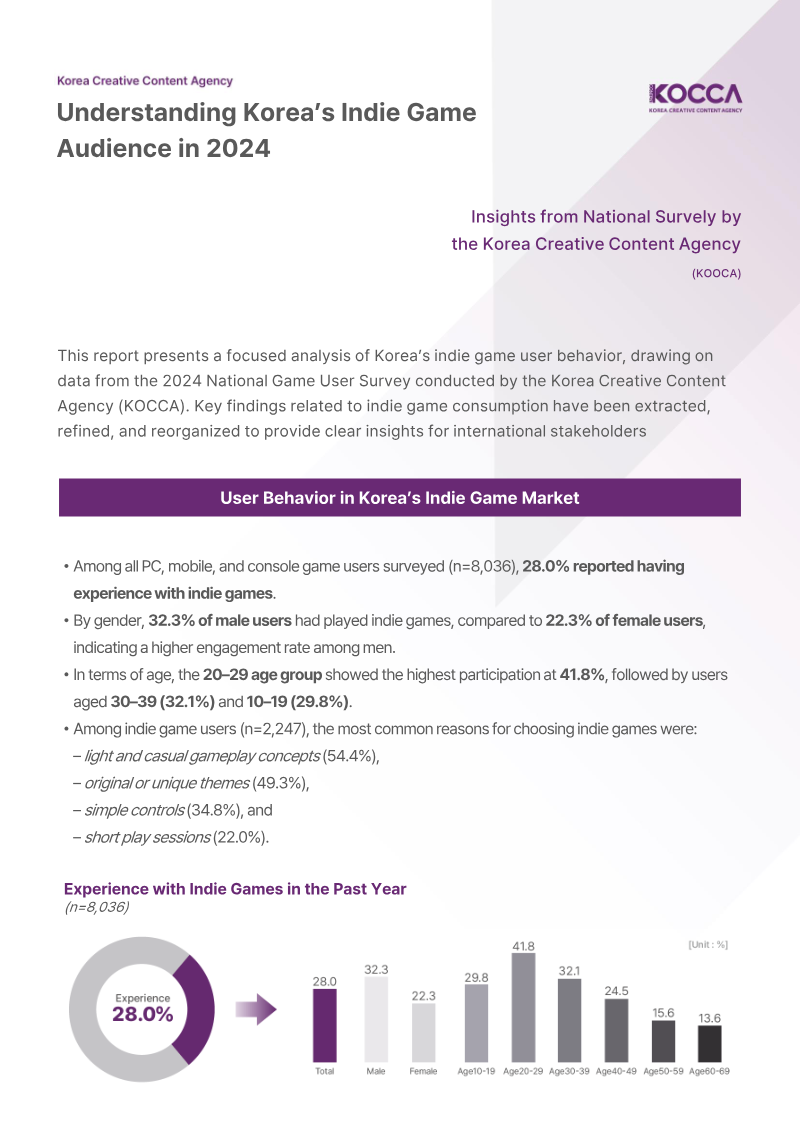
The 2024 analysis of Korea’s indie game market provides a comprehensive overview of user behavior, preferences, and industry challenges within the domestic gaming landscape.
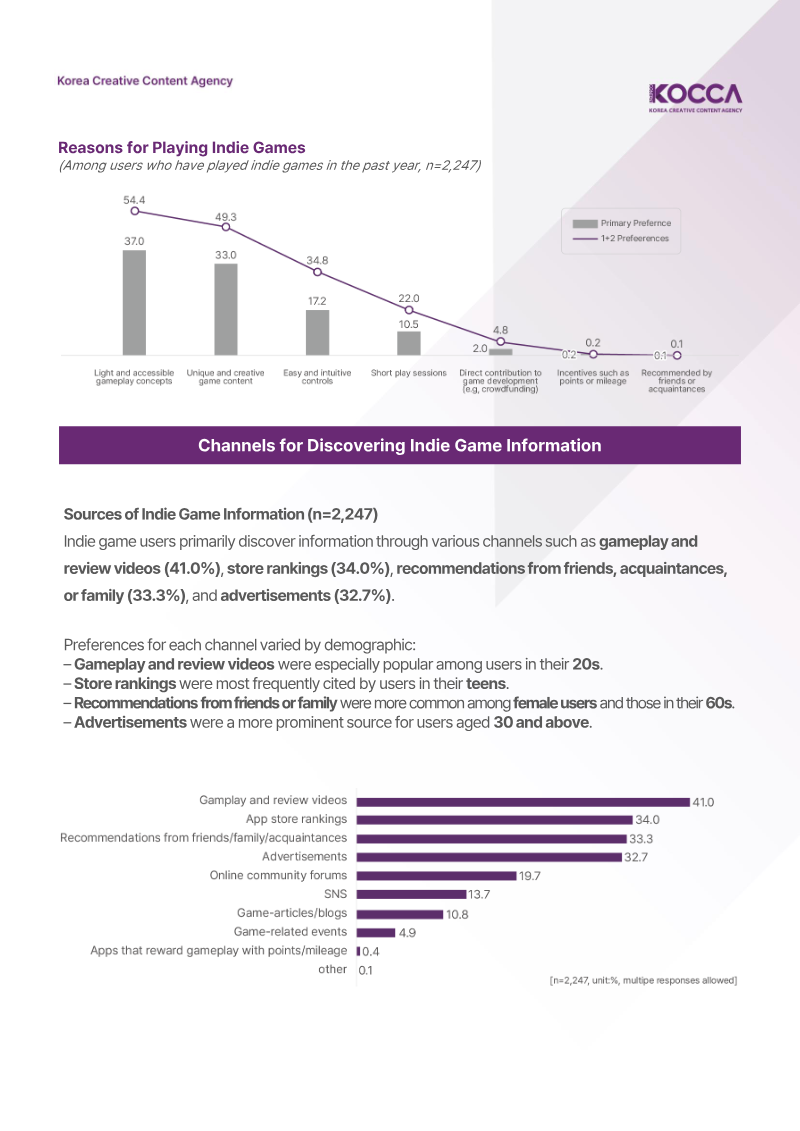
- Approximately 28% of the total Korean game user base engages with indie titles, with the highest participation rate found in the 20–29 age demographic at 41.8%.
- The primary drivers for indie game consumption are light, casual gameplay (54.4%) and original or unique themes (49.3%), followed by simple controls (34.8%).
- Gameplay and review videos are the most effective discovery channel at 41%, though store rankings (34%) and friend recommendations (33.3%) remain critical for specific demographics like teens and female users.
Videojuegos en el Aula: Guía para un Aprendizaje Adecuado
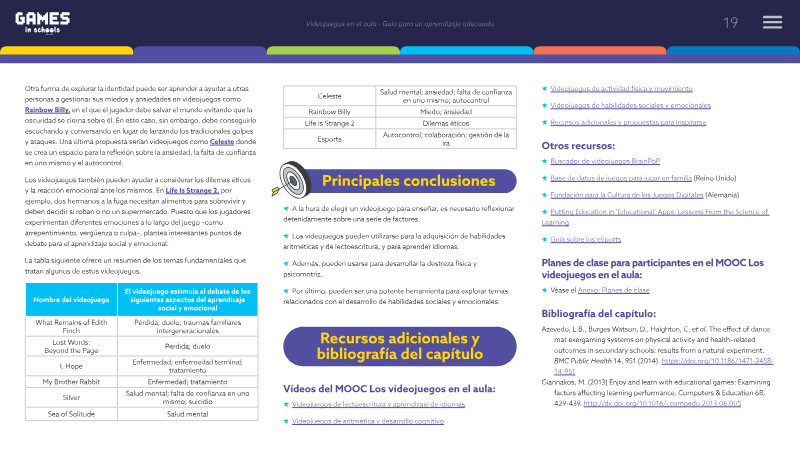
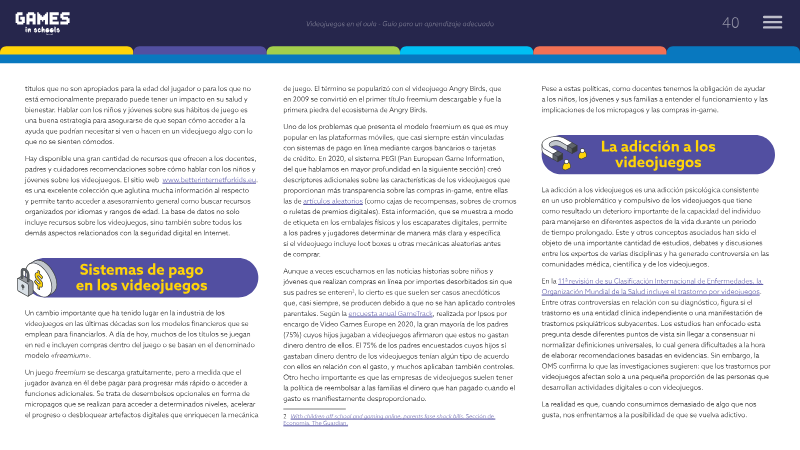
The guide argues that video games, when deliberately selected and scaffolded, can become powerful learning tools across primary, secondary and vocational settings.
- Video games are effective pedagogical tools that improve cognitive functions like memory and problem-solving, with studies such as Parker & Thomsen (2019) linking game mechanics to measurable gains in literacy and clinical ADHD assessment.
- The global games market now encompasses over three billion active players, including 70% of Europeans aged 6–24, providing a massive, accessible platform for cooperative and project-based learning.
- Educational integration is most successful when educators use a continuum from free play to structured activities, utilizing titles like Minecraft and Assassin’s Creed Discovery Tour to support interdisciplinary curricula.
Female Gamers in Asia: Version for Women in Games Asia Panel
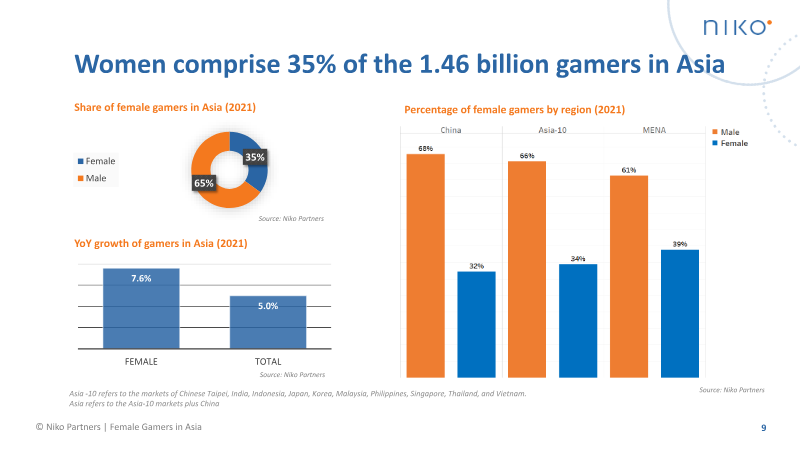
Female gamers represent a primary engine of growth within the Asian interactive entertainment market, accounting for 35% of the region's 1.46 billion total gamers as of 2021.
- Female gamers in Asia represent 35% of the region's 1.46 billion total gamers, with a year-over-year growth rate of 7.6% that outpaces the 5.0% growth of the general gaming population.
- In 2021, female gamer spending on mobile titles reached $13.07 billion in China and $5.52 billion across the Asia-10, while PC spending reached $9.70 billion and $3.93 billion respectively.
- Mobile is the primary platform for this demographic, with 95% of female gamers playing on mobile devices, compared to 60% on PC and 17% on consoles.
Modern Mobile Consumer 2022: App Discovery Report
The Modern Mobile Consumer 2022: App Discovery Report examines the evolving journey of mobile users from initial app discovery to daily usage and long-term engagement.
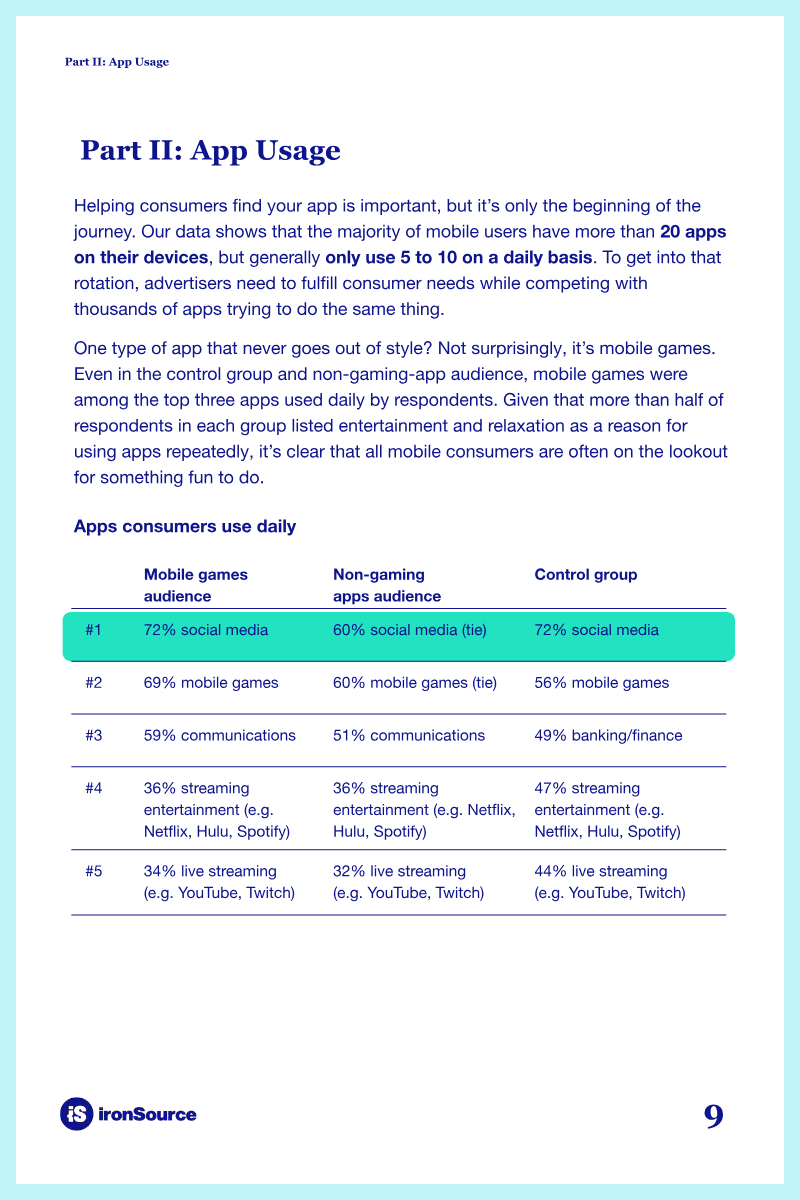
- Mobile gaming has become a universal behavior, with 60% of non-gaming app users playing mobile games daily, matching social media as the top usage category.
- In-app advertising is a primary driver for app discovery, leading to downloads for 70% of gaming audiences and 78% of non-gaming control group users.
- While users typically maintain over 20 apps on their devices, the majority limit their daily engagement to only five to ten apps.
Gamer Motivation Profile: Model and Findings
The Gamer Motivation Profile provides a comprehensive framework for understanding why individuals play video games by categorizing player behavior into six distinct motivation clusters: Action, Social, Mastery, Achievement, Immersion, and Creativity.
- The Gamer Motivation Profile categorizes player behavior into six core clusters: Action, Social, Mastery, Achievement, Immersion, and Creativity.
- Analysis of 222,964 unique gamers across North America, Europe, South America, and Southeast Asia confirms that gaming habits are statistically correlated with 'Big Five' personality traits.
- Age is a stronger predictor of behavioral shifts than gender, with competitive and action-oriented motivations showing a consistent decline as players mature.
Global Gaming Report Q1 2026
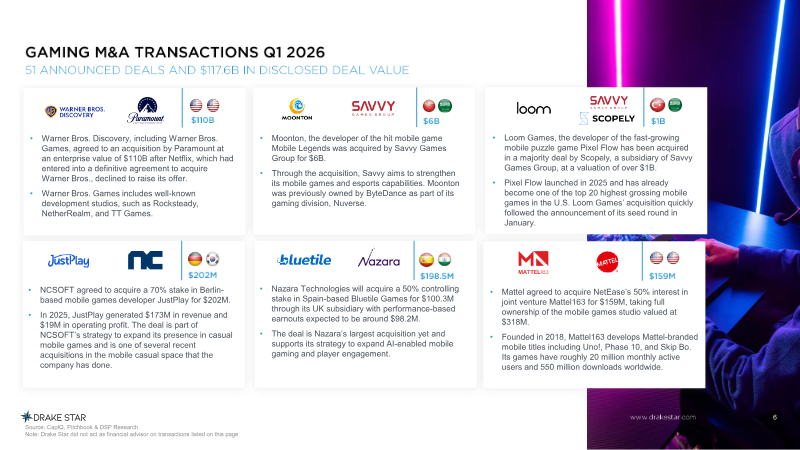
The global gaming industry experienced a complex start to 2026, characterized by a sharp divergence between high-level strategic consolidation and broader market volatility.
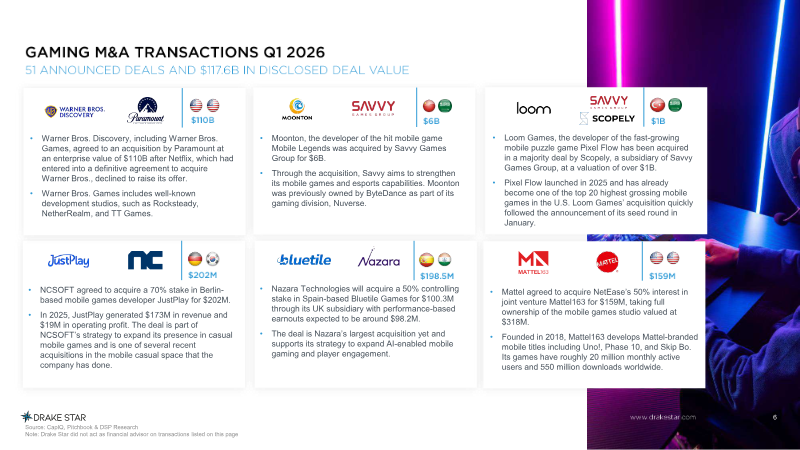
- M&A activity reached a 15-month peak in Q1 2026 with 51 transactions totaling over $100 billion, headlined by the Paramount acquisition of Warner Bros. Discovery and Savvy Games Group's purchase of Moonton.
- Private financing remained steady with $785 million raised across 106 deals, showing a clear investor preference for AR/XR hardware and infrastructure over traditional software.
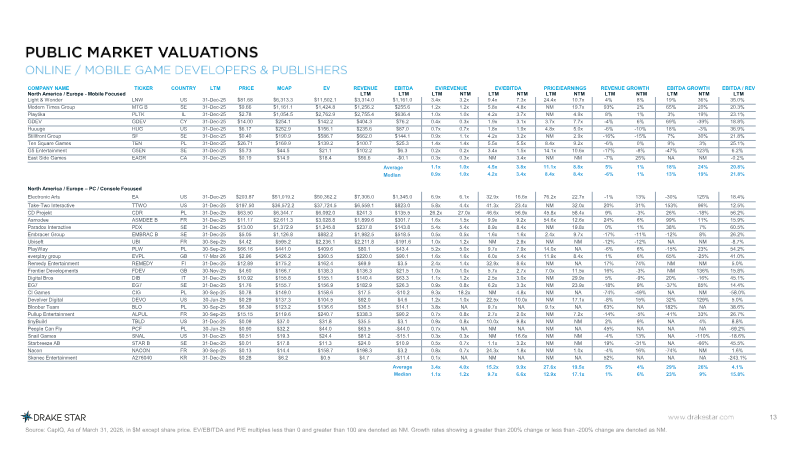
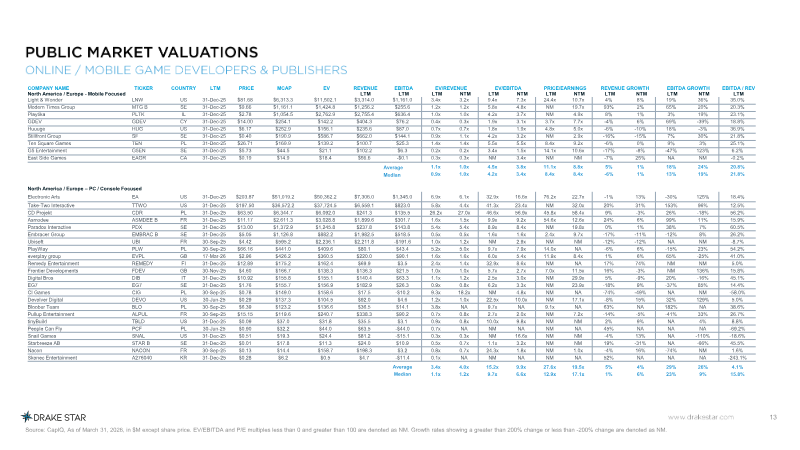
- The Drake Star Gaming Index declined by 1.8 percent, driven by market weakness in Western regions and the mobile gaming sector.
Gamer Motivation Profile: Empirical Research Methodology
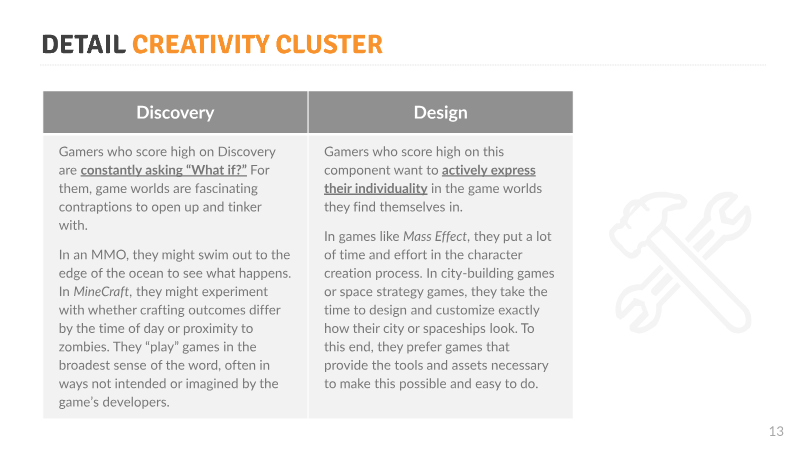
The Gamer Motivation Profile provides an empirical framework for understanding player behavior by categorizing gaming preferences into twelve distinct motivational factors.
- The Gamer Motivation Profile categorizes player behavior into twelve distinct factors grouped into six thematic clusters: Action-Social, Mastery-Achievement, and Immersion-Creativity.
- The model is built on a global dataset of over 1.25 million unique gamers, providing a statistically significant foundation for analyzing player engagement.
- The participant demographic is 74% male, 22% female, and 3% non-binary, with a median age of 23 and a primary geographic concentration in North America (33%) and Western Europe (14%).