Unreal
Game
Documents about Unreal
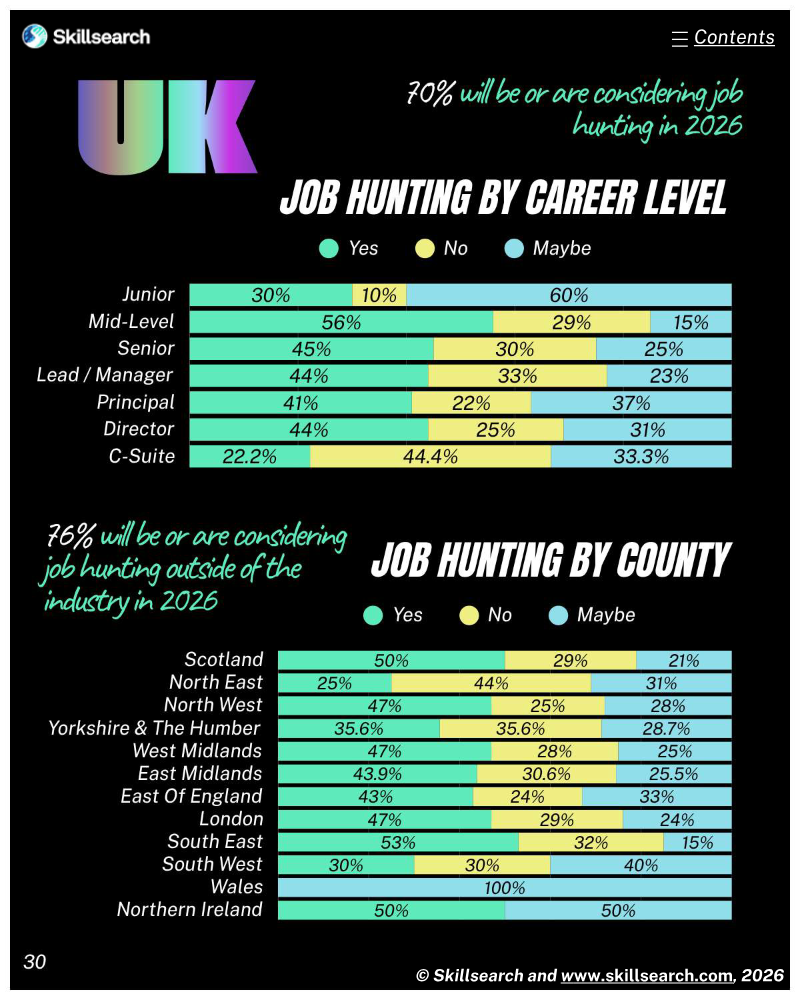
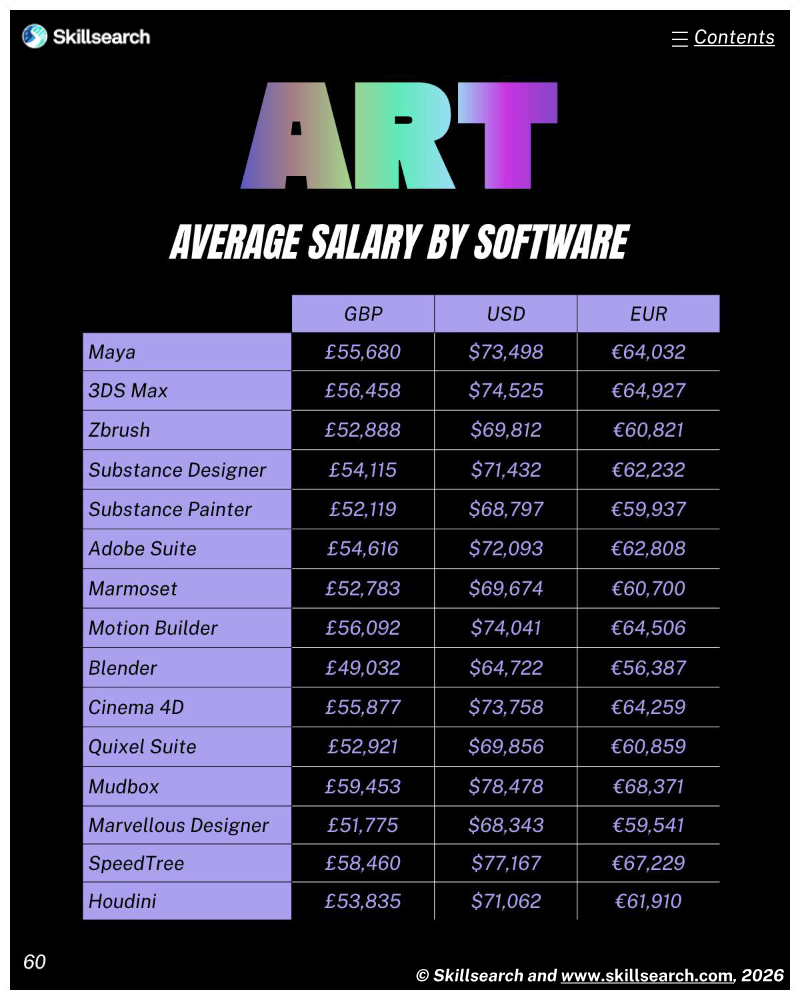
Games and Immersive: Salary & Satisfaction 2026 Report
The global games and immersive technology industry is currently navigating a period of profound instability characterized by widespread redundancies, economic uncertainty, and a pervasive sense of professional dissatisfaction.
- Between 69% and 84% of industry professionals are actively considering new employment due to widespread job insecurity and inadequate compensation.
- The workforce is experiencing a significant mental health crisis, with 67% of employees reporting burnout and nearly 50% experiencing poor mental health over the past year.
- While over 50% of professionals have adopted AI tools, the industry remains deeply divided over concerns regarding creative authenticity, ethics, and job displacement.
State of African Games 2026
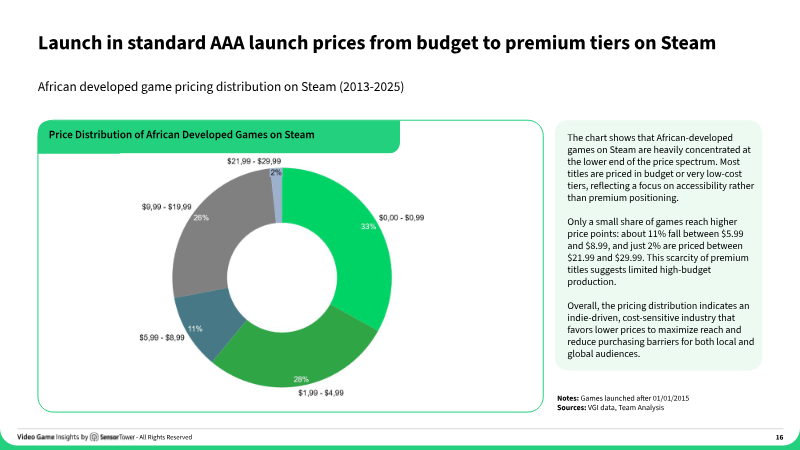
The analysis delivers a data-driven overview of African-developed video games, concentrating on performance across global platforms—primarily Steam, with supplemental PlayStation and Xbox data—from 2015 through 2025.
- South Africa dominates the African game development sector, accounting for all top-ten selling titles and contributing to a 2% share of global Steam unit sales.
- The industry is shifting from volume-driven growth to longer development cycles, evidenced by a decline in annual Steam releases from a peak of 23 in 2023 to 11 in 2025.
- There is a significant genre mismatch in the market, as action titles dominate release volume while simulation games achieve the highest median sales at approximately 372,000 units.
Wyniki Finansowe 3Q25
This financial analysis details the third-quarter 2025 performance of PCF Group S.A. (People Can Fly), a global game development studio.
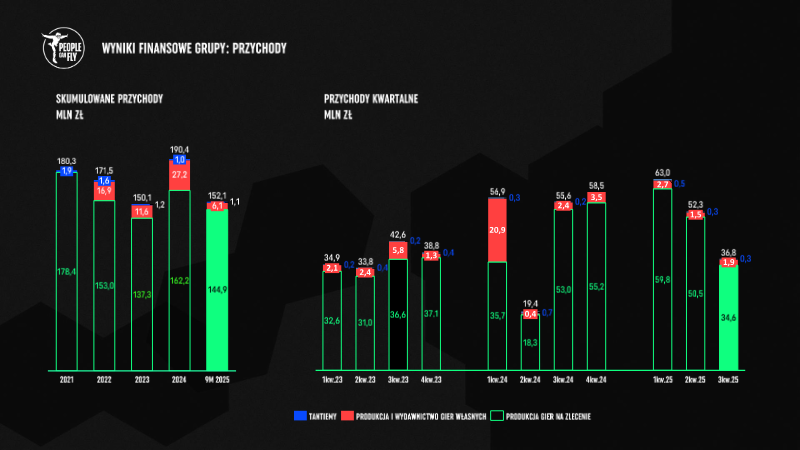
- PCF Group S.A. reported a net loss of 117 million PLN for the first nine months of 2025, a significant increase from the 33.3 million PLN loss recorded in the same period of 2024.
- A 92 million PLN write-down for the project 'Lost Rift' (Victoria) following its September 25, 2025, Early Access launch was the primary driver of the group's financial deficit.
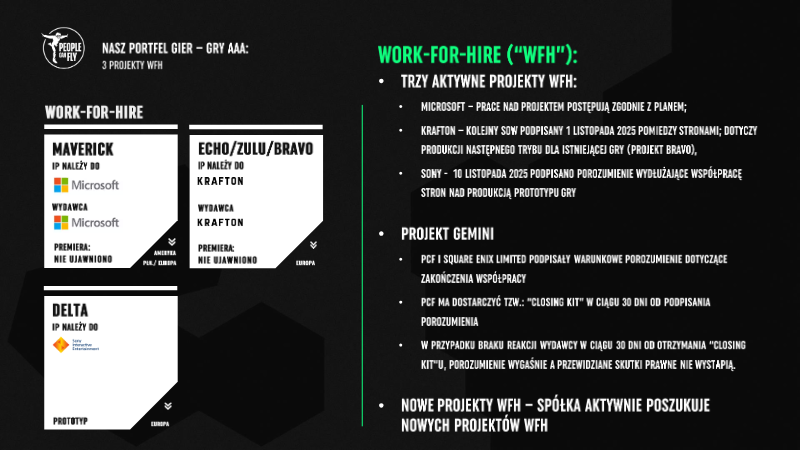
- Despite the net loss, total revenue grew to 152.1 million PLN in the first nine months of 2025, up from 131.9 million PLN in 2024, driven by work-for-hire projects including Delta, Zulu, and Echo.
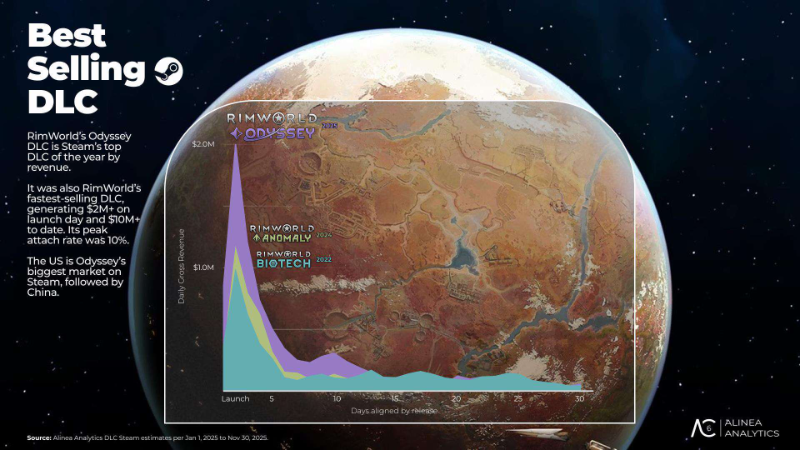
PC & Console Year in Review: 2025
The 2025 PC and Console Year in Review provides a comprehensive analysis of the global gaming landscape, focusing on market performance, consumer behavior, and development trends.
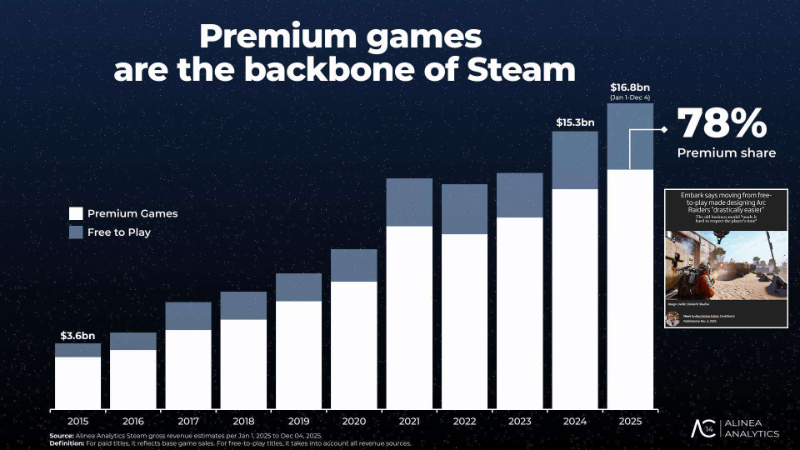
- Premium games dominate the market, accounting for 78% of Steam’s $16.8 billion total revenue in 2025.
- Cooperative gameplay is a primary driver of commercial success, with 11 of the top 20 highest-grossing titles featuring co-op mechanics.
- Indie developers contribute over 25% of Steam’s total revenue, with 'Triple-I' titles delivering exceptional return on investment.
How UGC, AI, & Cloud Are Transforming Gaming Report
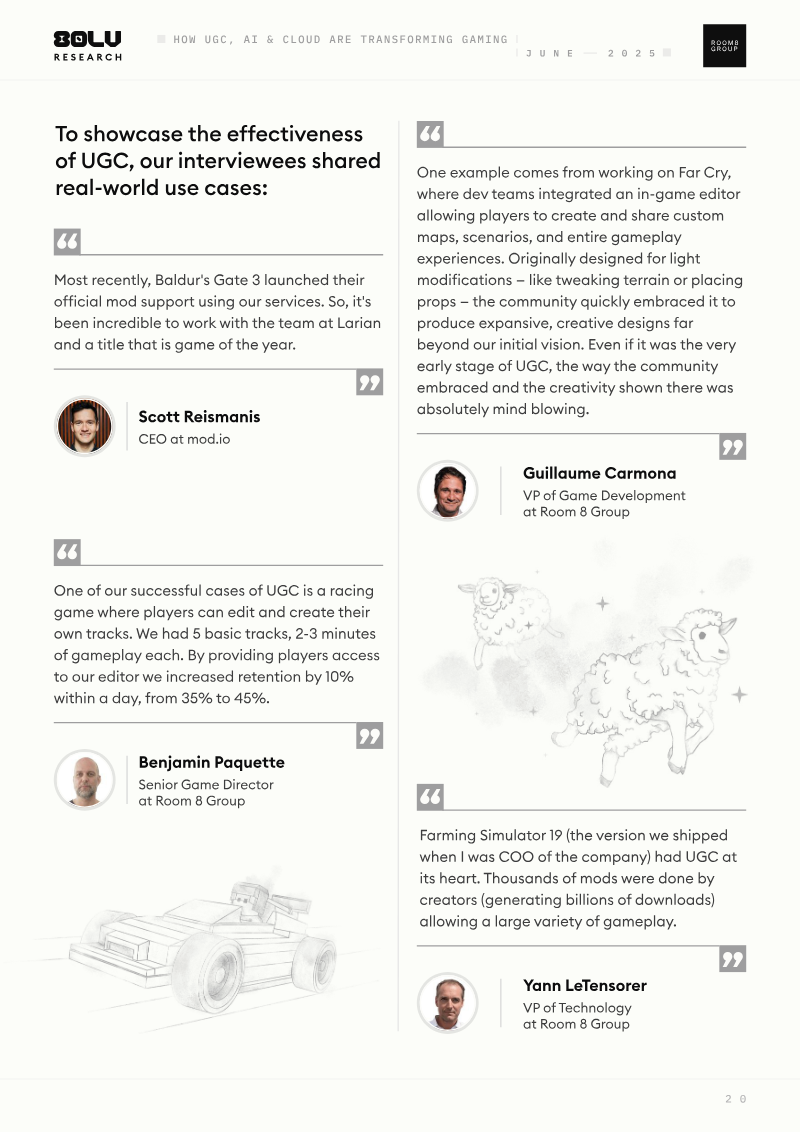
The report argues that user-generated content (UGC), artificial intelligence (AI) and cloud gaming are reshaping the industry by lowering entry barriers, democratizing creation and expanding cross-platform reach.
- Cloud gaming revenue grew from $1.1 billion in 2020 to $6.9 billion in 2024, with projections reaching $18.7 billion by 2027 and a trajectory to become the dominant play model within a decade.
- Cloud gaming subscribers have surged from 62.5 million to nearly 396 million over the last four years, while AI-driven development tools are projected to generate $4.2 billion by 2029.
- Indie developers are increasingly competitive, with indie releases on Steam generating $4 billion in 2024, a figure that now matches AAA revenue streams.
The Big Game Engine Report of 2025
The Big Game Engine Report 2025 examines the shifting landscape of game development technology, focusing on the transition from proprietary in-house tools to third-party public engines.
- The share of Steam releases powered by custom in-house engines plummeted from over 70% in 2012 to 13% in 2024.
- Custom engines have fallen below 50% of total unit sales for the first time, currently accounting for 42% of the market.
- Unity remains the volume leader, powering 51% of all Steam releases in 2024, primarily dominating the 'Tiny' and 'Small' categories under 100k units.
Tools & Services Survey: November 2024
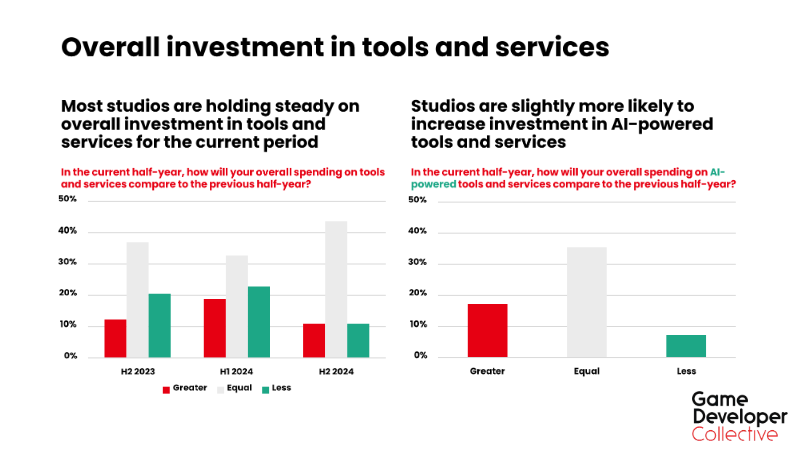
This analysis examines the evolving landscape of game development tools and services amidst a period of significant market volatility.
- Market sentiment is increasingly negative, with 55% of developers describing current conditions as 'bad' and 41% of studios reporting underperformance against expectations.
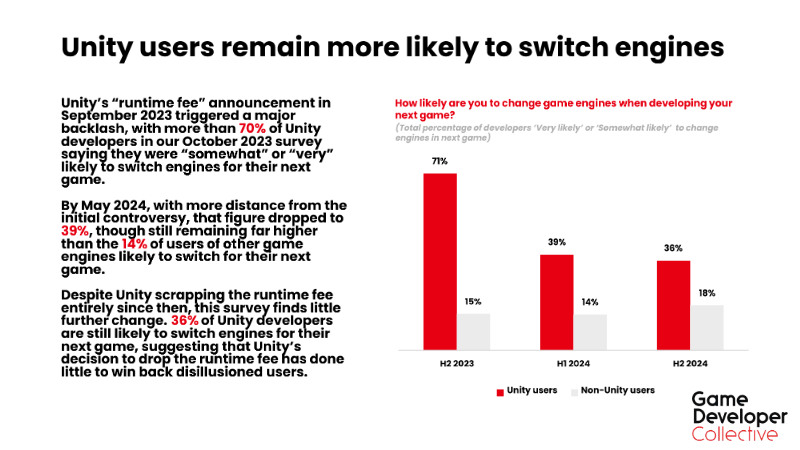
- Unity continues to lose market share following its 2023 runtime fee controversy, with 36% of its users still planning to switch engines compared to only 14% for competitors.
- Brand trust in Unity remains damaged, as only 30% of developers report being happy with the company despite the reversal of its controversial fee policy.
The State of Play: Summer 2024 Edition
The summer 2024 Xsolla analysis argues that the game-development ecosystem has entered a phase of unprecedented democratization, driven by low-cost engines, open-source tools and third-party services that lower technical and financial barriers for creators.
- Indie studios are capturing a larger share of the market, generating 29% of total Steam revenue in 2023 compared to 25% in 2018.
- Game development is becoming increasingly democratized as Unity usage grows by 8% year-over-year, Unreal grows by 10%, and Godot experiences a 69% surge.
- The edutainment sector is poised for significant expansion, with a projected compound annual growth rate of 65–75% through 2034.
The Largest Report on the Condition of the Polish Gamedev Industry: 2022/23
The Polish game development industry has established itself as a significant global player, characterized by a strong export orientation and a reliance on digital distribution platforms like Steam.
- The Polish game development sector has transitioned from a period of rapid growth between 2019 and 2020 to a current landscape characterized by a flattening trend in both employment and the formation of new studios.
- Industry sustainability is currently threatened by high market volatility, insufficient capitalization, and high staff attrition rates driven by unsustainable 'crunch' work cultures.
- Polish studios are increasingly adopting advanced production technologies, specifically Unreal Engine, photogrammetry, and AI, to improve narrative depth and operational efficiency.
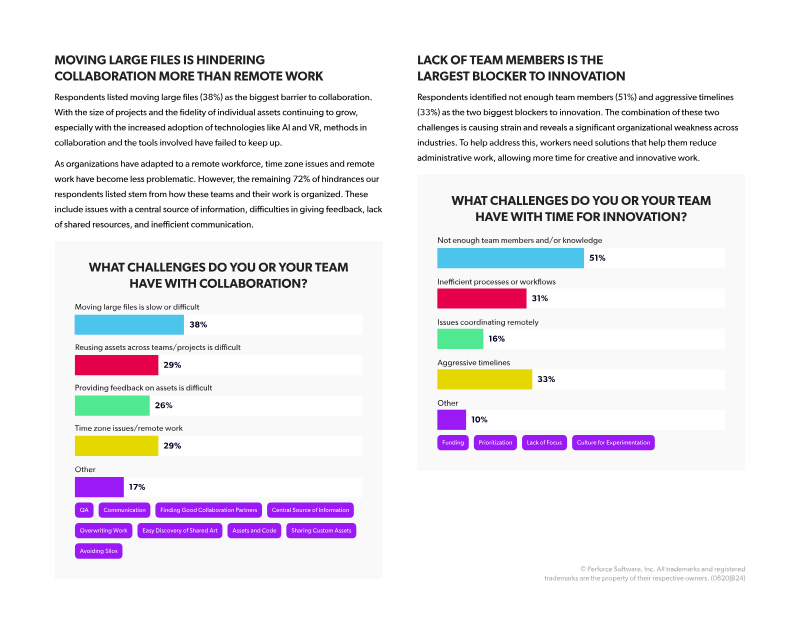
Perforce 2024 State of Game Technology Report
The report demonstrates that real-time 3D engines and advanced asset pipelines are now integral to more than half of organizations beyond traditional game development, spanning media, automotive, education and healthcare.
- Real-time 3D engines have expanded beyond gaming, with over 50% of organizations in media, automotive, education, and healthcare now integrating these technologies into their workflows.
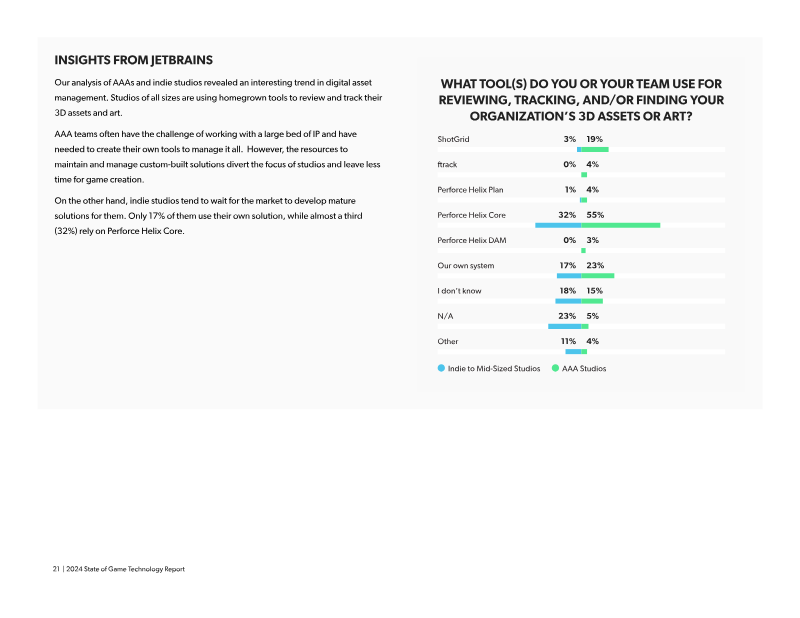
- Unreal Engine leads the market with 63% usage, followed by Unity at 47%, while Perforce Helix Core remains the primary version-control solution for 51% of firms.
- Generative AI adoption is widespread, with over 65% of respondents utilizing AI tools, led by ChatGPT at 47%, with indie studios showing higher adoption rates than AAA counterparts.
The Game Industry of Finland Report 2024
The 2024 overview of Finland’s game sector presents a comprehensive assessment of an industry that remains a global technology leader while confronting a tightening financing environment.
- Finland’s game industry currently employs approximately 4,300 individuals, representing about 3,800 full-time positions.
- A significant decline in private risk capital and publisher funding has forced studios to pivot toward B2B subcontracting, co-development agreements, and increased reliance on EU and national public R&D programs.
- The ecosystem remains anchored by major players like Supercell, which employs over 800 staff and has produced seven global hit titles, alongside diverse ventures like the mental-health game developer Soihtu DTx, which recently secured a $4.2 million seed round.
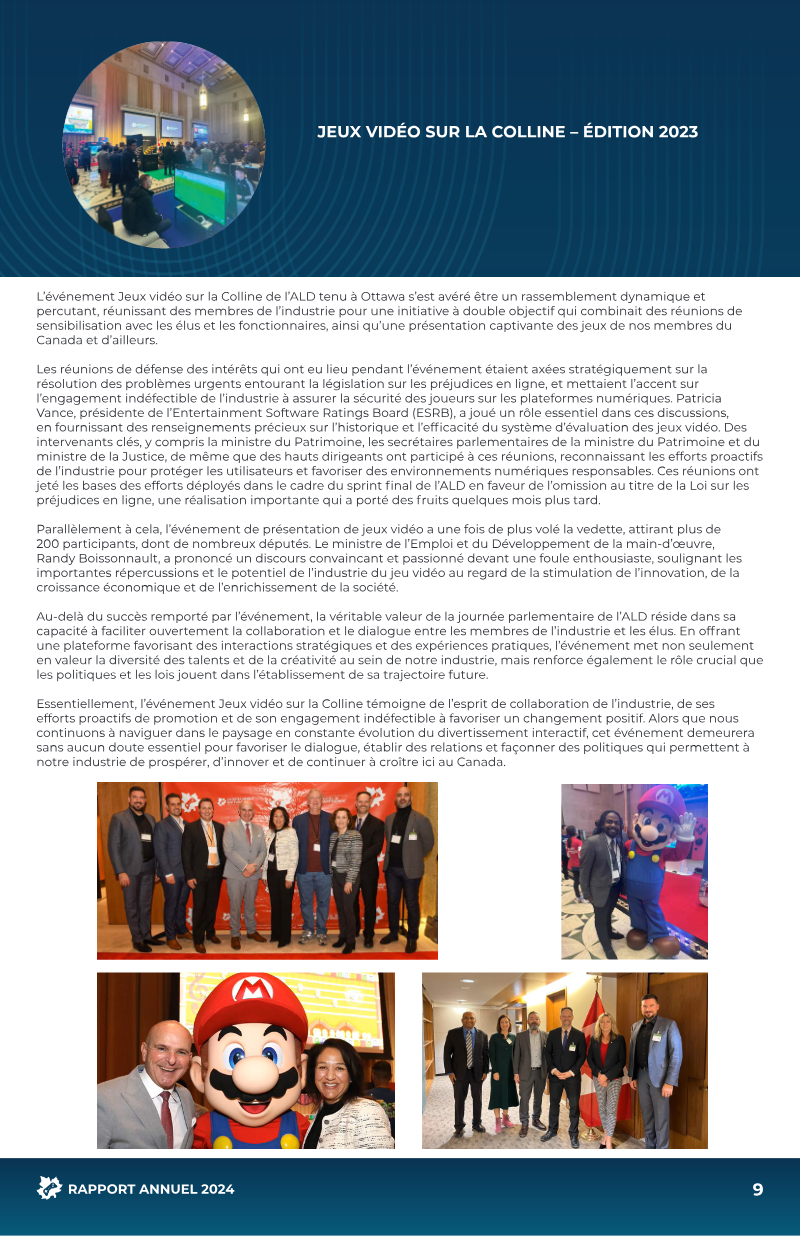
Association Canadienne du Logiciel de Divertissement Rapport Annuel 2024
The 2024 annual review presents a comprehensive assessment of Canada’s video-game sector, emphasizing its expanding regulatory influence, economic contribution and strategic diversification.
- The Canadian video game sector contributed $5.5 billion to the national GDP in 2024, supported by a resilient, virtual-first operational model.
- The industry successfully secured exemptions from the Streaming Act levy and the Online Harms Act, signaling significant growth in its regulatory and political influence.
- Major global publishers including Epic Games, Roblox, and Tencent joined the association, driving revenue beyond forecasts and expanding the sector's reach.