Time
Company
Documents about Time
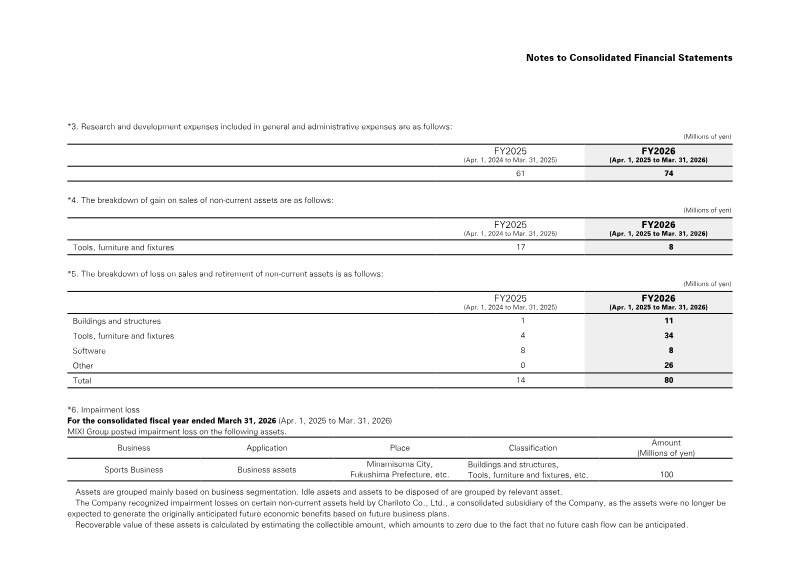
MIXI Integrated Report 2026
The MIXI Integrated Report 2026 details the company’s strategic transition into its "Third Founding" phase, a period defined by a pivot toward the "We-Time Economy."
- MIXI is prioritizing global expansion as a top management goal, noting that overseas sales accounted for only approximately 12% of total net sales in fiscal year 2026.
- The company is shifting its financial policy to return profits generated across all business segments to shareholders, moving away from a reliance on MONSTER STRIKE as the primary source of financial leverage.
- MIXI has introduced a medium-term 'Growth Strategy in the We-Time Economy,' focusing on creating economic value through shared experiences among families, friends, and fans.
PCF Group Investor Presentation: Trigon TMT & Gaming 2026
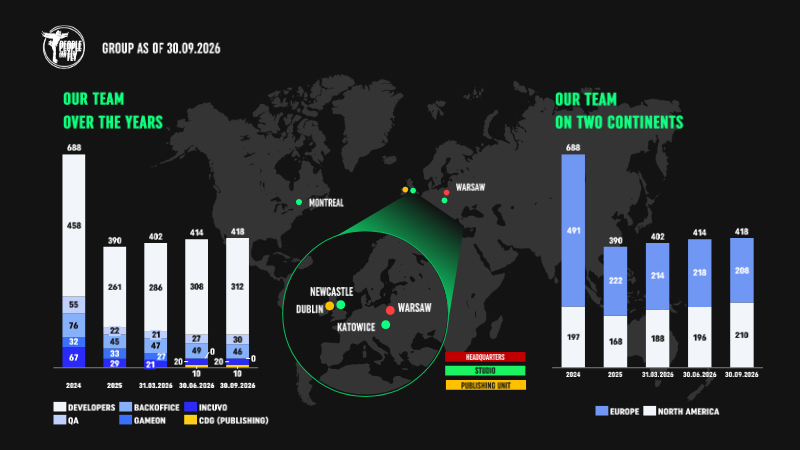
The PCF Group Investor Presentation for 2026 outlines the company’s strategic positioning, operational scale, and financial performance within the global video game industry.
- As of September 30, 2026, PCF Group employs 688 staff across studios in Warsaw, Montreal, Newcastle, and Katowice, with 288 developers dedicated to work-for-hire (WFH) projects.
- The company maintains four active WFH projects for major partners, including Microsoft (Maverick, Zulu/Bravo/Lima) and Krafton (Delta, Florence), with the Microsoft-partnered 'Gears of War: E-Day' achieving an 87/100 Xbox rating and 32,000 peak concurrent players.
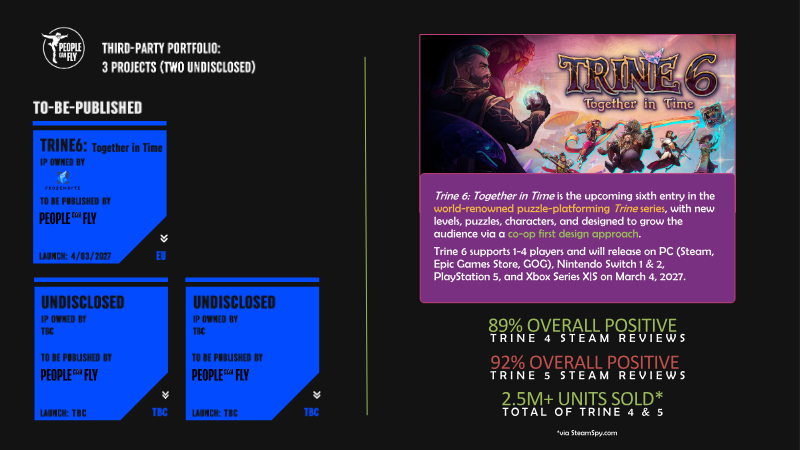
- The third-party publishing division is preparing to release 'Trine 6: Together in Time' on March 4, 2027, across PC, Nintendo Switch 1 & 2, PlayStation 5, and Xbox Series X|S.
Gaming and Esports in Vietnam: A New Arena for Brands
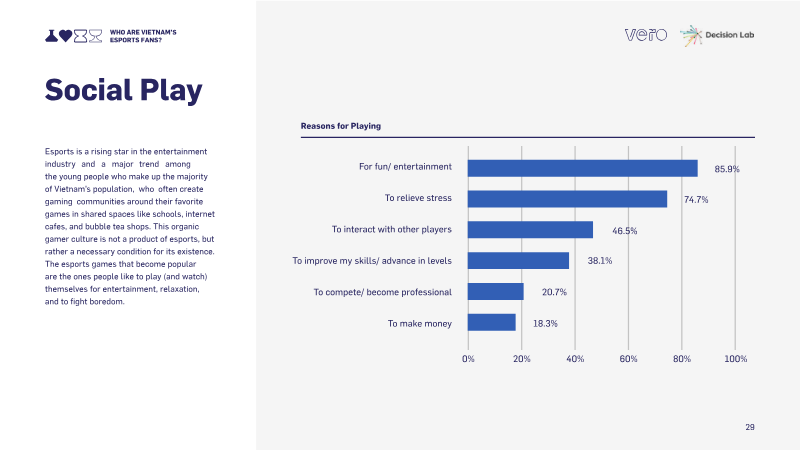
Vietnam’s gaming and esports landscape has evolved into a high-growth, culturally resonant channel for brands targeting the country’s youthful, tech-savvy population.
- Vietnam has the world's highest adult gamer rate at 85%, with a demographic where 70% of the population is under 25 and one-third of citizens are engaged in esports.
- Mobile gaming dominates the market, supported by high smartphone penetration and 4G coverage, with gamers typically spending 1–3 hours per session.
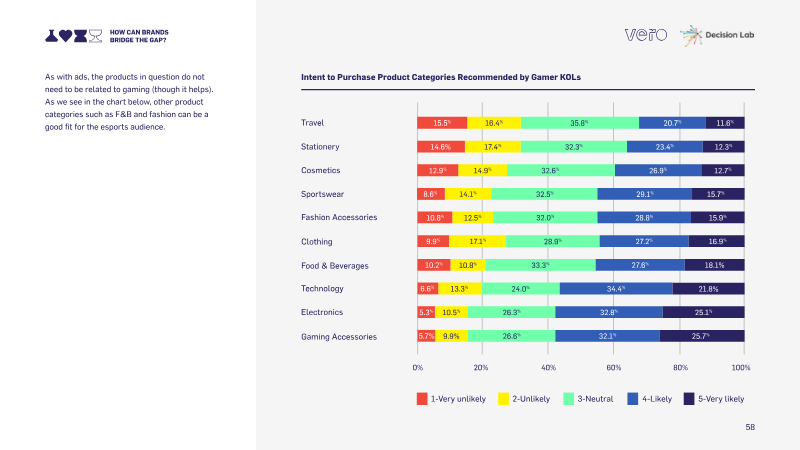
- Influencer marketing is highly effective, as 51% of gamers trust key opinion leader (KOL) recommendations and 42% report purchasing products endorsed by them.
Major Organizational, Operational and Portfolio Reset to Reclaim Creative Leadership and Restore Sustainable Growth
Ubisoft has initiated a major organizational and operational reset designed to reclaim creative leadership and restore sustainable growth in an increasingly selective AAA market.
- Ubisoft is targeting a €500 million reduction in fixed costs by March 2028 compared to FY23 levels to restore sustainable growth.
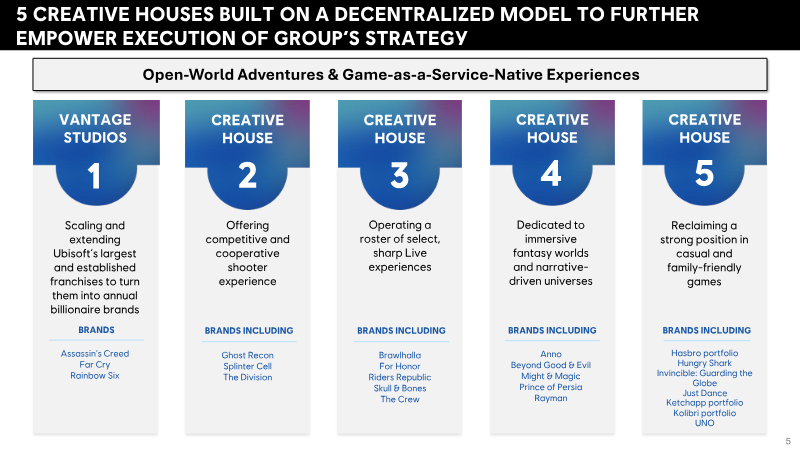
- The company is restructuring into five specialized Creative Houses to focus on core franchises like Assassin’s Creed, Far Cry, and Rainbow Six while improving operational agility.
- Ubisoft has canceled six projects, including the Prince of Persia: The Sands of Time remake and four unannounced titles, while extending development timelines for seven others to prioritize quality.
InvestGame Q4'24 Report (Unknown Time)
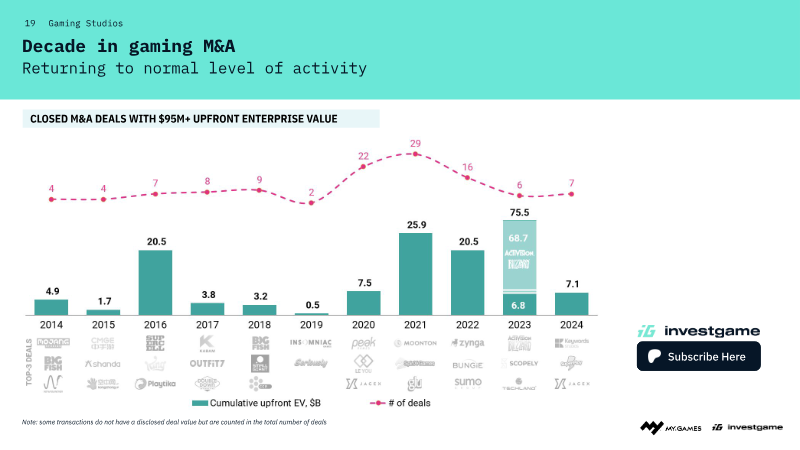
The gaming industry experienced a strategic shift in 2024, moving away from short-term financial arbitrage toward long-term, objective-driven transactions.
- The gaming industry is shifting toward long-term, objective-driven transactions, evidenced by a strong Q4 2024 M&A market and a 22% year-over-year increase in private investment funding.
- Venture capital is pivoting away from game development studios in favor of platform and technology startups, forcing corporate venture arms to become the primary source of studio financing.
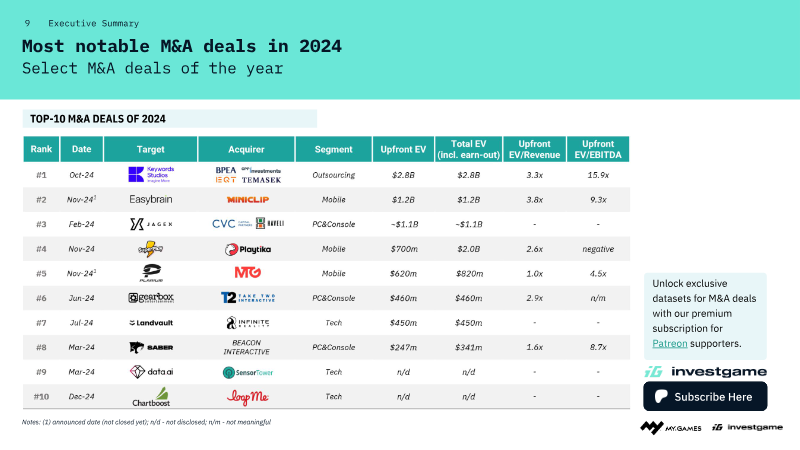
- The work-for-hire sector is seeing major consolidation, underscored by the $2.8 billion buyout of Keywords.
The State of Puzzle Games: 2023
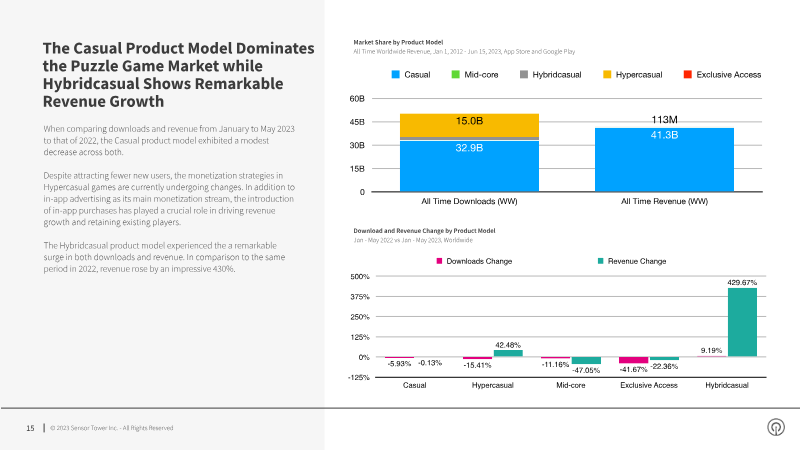
The puzzle game sector is undergoing a significant structural evolution, characterized by a shift in product models and monetization strategies.
- The hybridcasual model has become the primary industry growth driver, with revenue surging approximately 430% between early 2022 and early 2023.
- The Pair sub-genre experienced a significant shift toward hybridcasual monetization, which grew from 14.8% to 58.7% of its total revenue in just one year.
- Established sub-genres including Real-Time, Chain, and Bubble Shooter faced double-digit declines in both download volume and revenue throughout the 2022–2023 period.
Mobile Gaming Market Outlook 2022
The global mobile gaming landscape has entered a period of stabilization following pandemic-era surges, with quarterly downloads maintaining a steady baseline of 14 billion.
- The mobile gaming market is in a stabilization phase, with quarterly downloads holding at 14 billion despite a 6% year-over-year revenue decline to $21.2 billion in early 2022.
- Casual games dominate volume at 80% of all downloads, while Mid-Core titles remain the primary revenue driver, accounting for 60% of total player spending.
- The Asia-Pacific region is a critical economic force, generating 80% of global MMORPG revenue and 62% of Card Battler revenue.
Consumer Insights: Games and Esports 2022
The Consumer Insights: Games and Esports 2022 report provides a comprehensive analysis of global gaming behaviors, motivations, and market engagement.
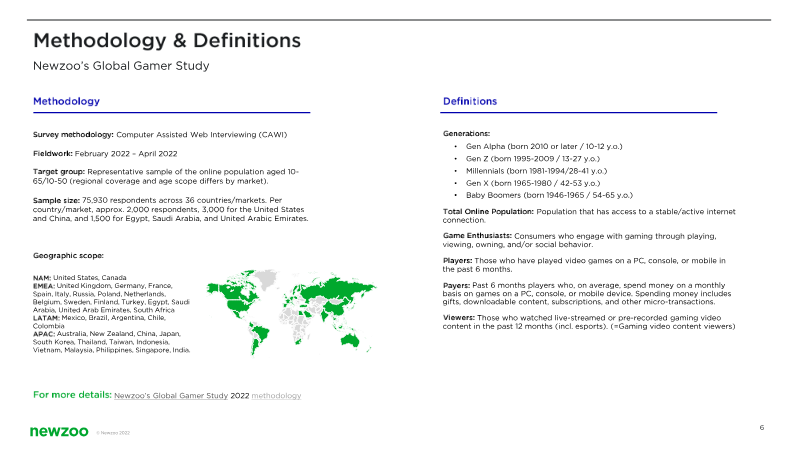
- The research is based on a global dataset of over 75,000 consumers across 36 international markets, covering North America, Europe, Latin America, the Middle East, and the Asia-Pacific region.
- Consumer spending is primarily driven by three factors: price sensitivity, the desire for exclusive content, and the need for social connectivity.
- Gaming engagement is categorized into distinct personas, with 'Time Fillers' and 'Mainstream Gamers' identified as the most prevalent segments.
Key Insights Into German Gamers
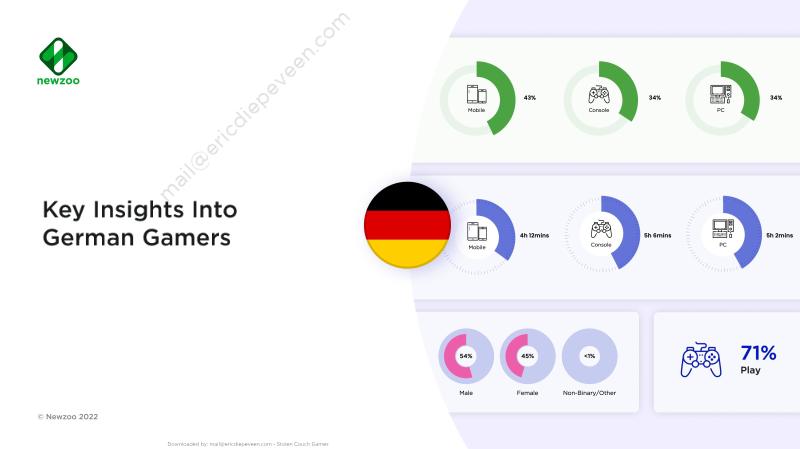
Germany represents a significant pillar of the global gaming industry, ranking as the largest games market in the European Union and the fifth largest worldwide by revenue.
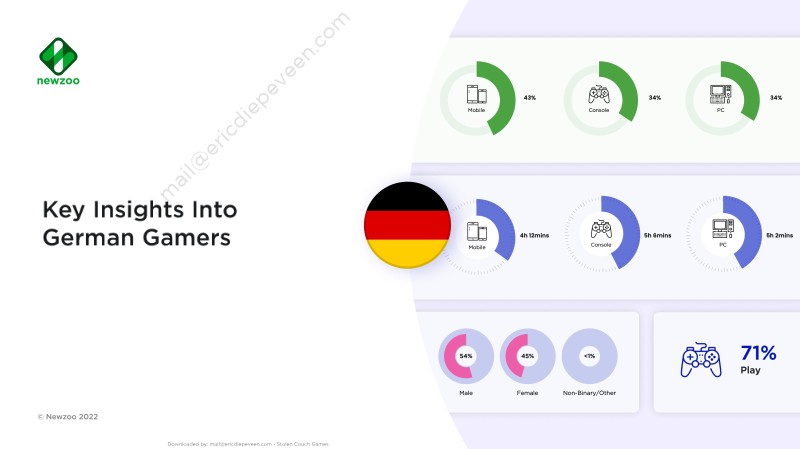
- Germany is the largest gaming market in the EU and the fifth largest globally, with 71% of the online population aged 10 to 65 identifying as game enthusiasts as of 2022.
- Mobile gaming has the highest market reach at 43%, though PC and console players demonstrate higher engagement with average weekly play times exceeding five hours.
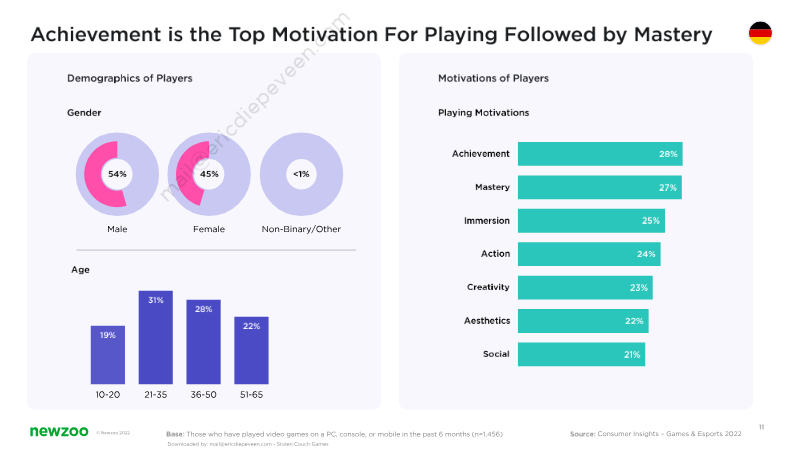
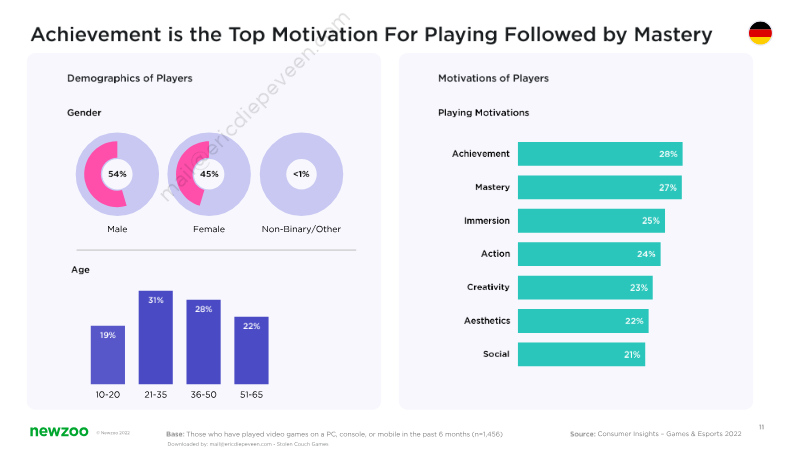
- The German gaming demographic is nearly gender-balanced at 52% male and 48% female, with the 21-35 age bracket serving as the largest segment at 31%.
Newzoo’s Global Gamer Study 2022
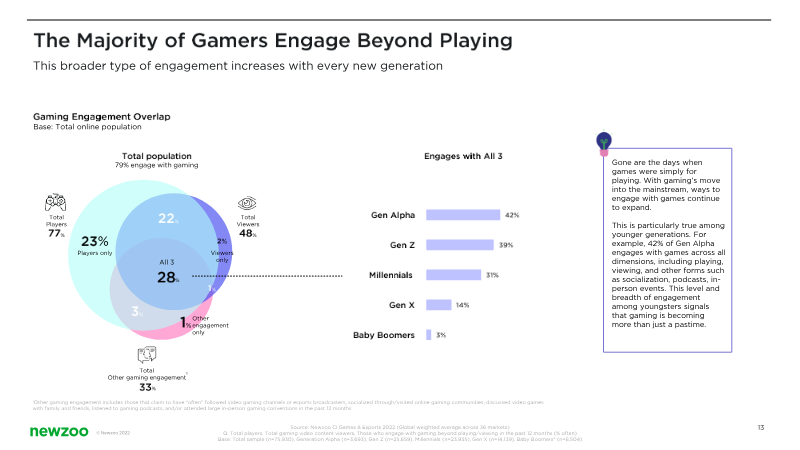
Gaming has evolved into a multi-dimensional entertainment ecosystem that extends far beyond traditional play, encompassing viewing, socializing, and content creation.
- Gaming has become a primary entertainment ecosystem for 79% of the global online population, with Gen Alpha prioritizing gaming over social media and streaming.
- The gaming sector reached a projected consumer spend exceeding $200 billion in 2023, with approximately 50% of Millennials, Gen Z, and Gen Alpha actively spending money on games.
- Gaming is increasingly used as a social platform, as 75% of players engage in game worlds for social interaction rather than playing the primary game mechanics.
The State of Mobile Gaming 2022: Market Trends and Top Titles in the U.S., Europe, and Asia
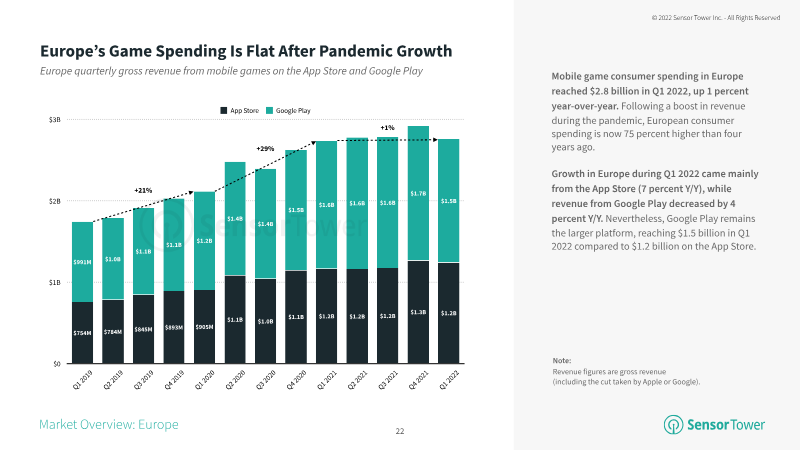
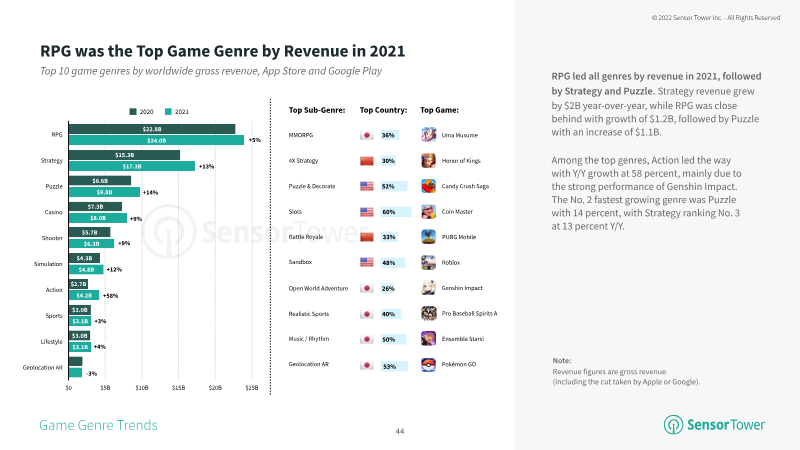
Global mobile gaming revenue experienced its first historical year-over-year decline in the first quarter of 2022, falling 6% to $21.2 billion.
- Global mobile gaming revenue declined 6% year-over-year in Q1 2022 to $21.2 billion, ending a period of pandemic-driven growth due to market stabilization and inflation.
- Consumer spending dropped 10% in the U.S. and 7% in Asia, while Google Play saw a 22% decrease in spending despite global downloads remaining resilient at 14 billion.
- Emerging markets are driving growth, led by India’s 73% increase in consumer spending and Turkey’s 36% revenue surge, which established it as Europe’s fastest-growing market.
Key Insights Into UK Gamers
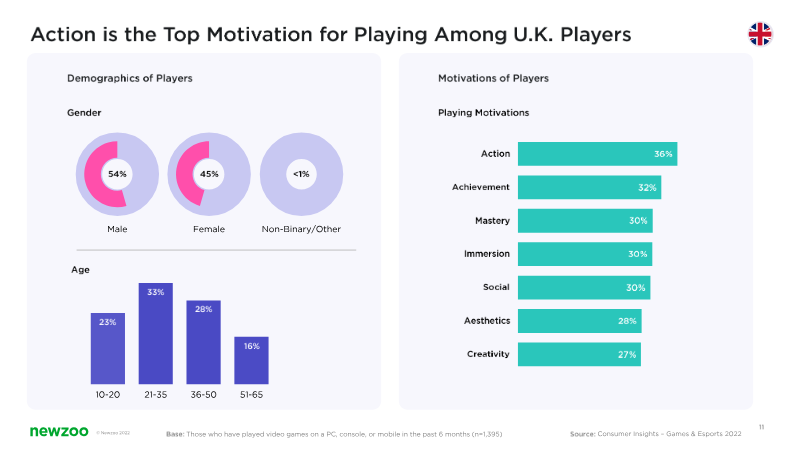
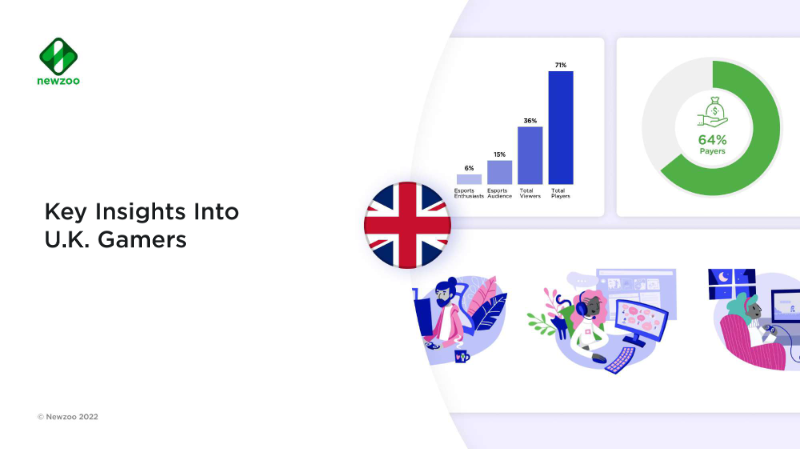
The United Kingdom represents a major global gaming hub, ranking as the sixth-largest market by revenue and tenth by player population as of late 2022.
- The UK is a major global gaming hub, ranking sixth in revenue and tenth in player population, with 71% of the population aged 10-65 identifying as game enthusiasts.
- Engagement is evenly split between active players (36%) and those who both play and view gaming video content (35%).
- Mobile gaming has the highest reach at 46%, followed by console (41%) and PC (29%), though PC and console users dedicate more time to gaming weekly.