Scopely
CompanyUnited States · Founded 2011
Documents about Scopely
Casual Games Report H1 2026: Growth Beneath the Still Surface
The casual gaming market maintained a stable valuation of $11 billion during the first half of 2026, characterized by a strategic shift from high-volume experimentation toward the refinement of established gameplay loops.
- The casual games market remained stagnant in H1 2026 with $11B in revenue, mirroring H1 2025 performance despite significant shifts in genre-specific growth.
- Merge-2 is the fastest-growing casual genre, nearly doubling its revenue to $1.2B in H1 2026 with a 20% year-over-year increase in downloads.
- Match-3 remains the largest puzzle subgenre at $2.4B, with Dream Games' 'Royal Kingdom' reaching the #3 market spot through a strategy of scaling limited titles and integrating diverse mini-game events.
Annual Report 2024: Savvy Games Group
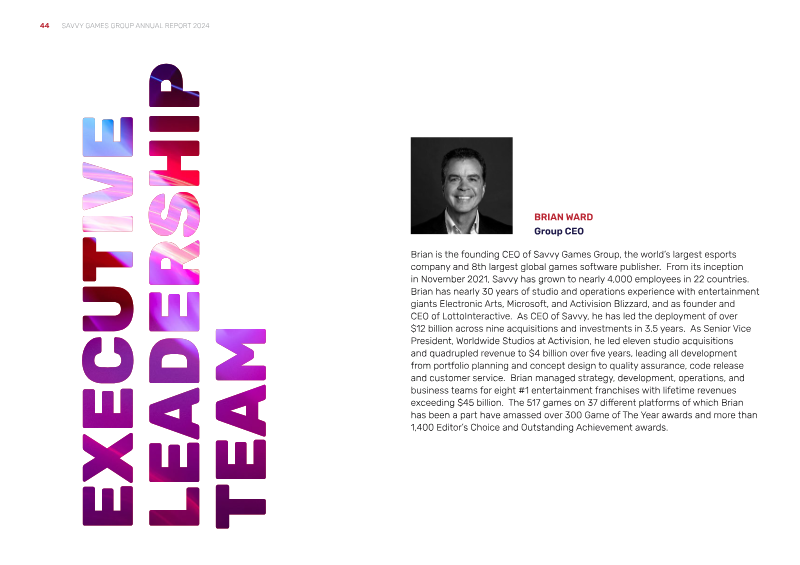
Savvy Games Group has established itself as a premier global force in interactive entertainment, currently ranking eighth worldwide by net revenue.
- Savvy Games Group ranks as the eighth-largest global gaming company by net revenue and serves as the primary vehicle for Saudi Arabia’s goal to contribute $13.3 billion to GDP and create 39,000 jobs by 2030.
- The organization has deployed over $12 billion in capital across nine major acquisitions since 2021 to scale its operations to nearly 4,000 employees across 22 countries.
- The ESL FACEIT Group holds a 40% share of the global esports market and engages more than 225 million users through platforms like the Esports World Cup.
The Great Mobile Reversal: Why Buyers Pay Billions for What VCs Abandoned
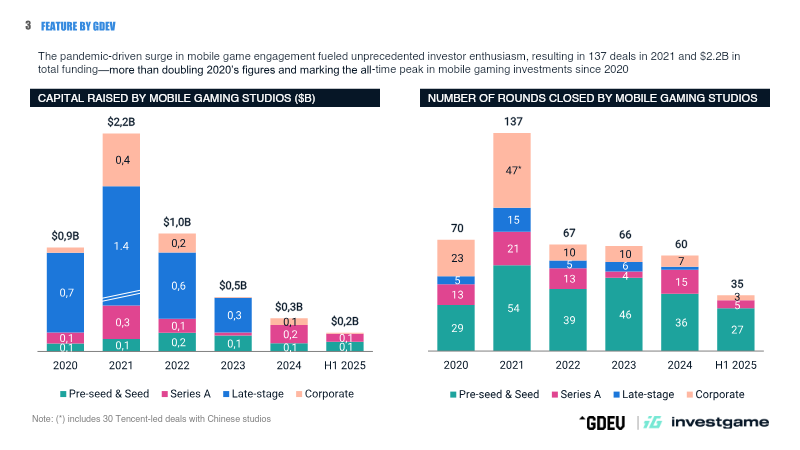
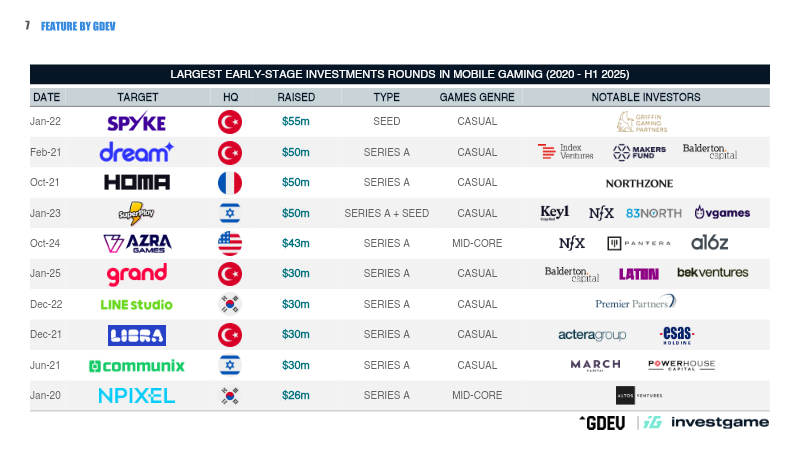
The analysis examines the evolution of mobile gaming investment and M&A activity from 2020 through the first half of 2025.
- Mobile gaming accounted for 61% of total gaming deal value (excluding ATVI) between 2020 and H1 2025, with strategic buyers and private equity firms driving nearly all deal volume in the first half of 2025.
- Strategic consolidation has replaced VC-led growth, highlighted by $7 billion in mobile M&A activity across six major deals, including Af’s $12.7 billion acquisition of 2yga and Scopely’s $4.9 billion purchase of GamesGroup.
- Venture capital interest has shifted heavily toward casual gaming, which now captures 65% of all deals due to its broader audience reach and faster iteration cycles.
Mobile Game Feature Impact Spotlight
Sensor Tower introduces Game IQ Deep Tags, a taxonomy of 70 specialized markers designed to analyze the impact of specific mobile game features on market performance.
- Strategic feature selection, rather than exhaustive feature adoption, is the primary driver of commercial success across the top 1,000 mobile games globally.
- In the hybridcasual segment, implementing in-app purchase (IAP) bundles correlates with a $1.77 increase in lifetime revenue per download.
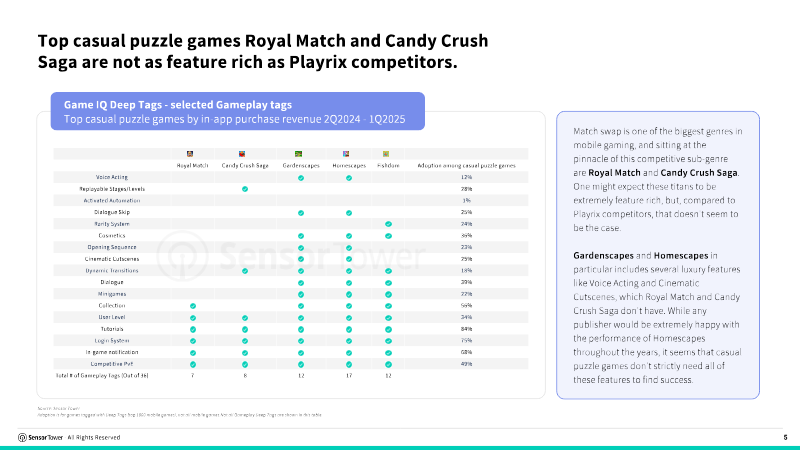
- Casual puzzle leaders like Royal Match and Candy Crush Saga maintain market dominance with lower feature density, proving that core gameplay often outweighs the addition of luxury elements like cinematic cutscenes.
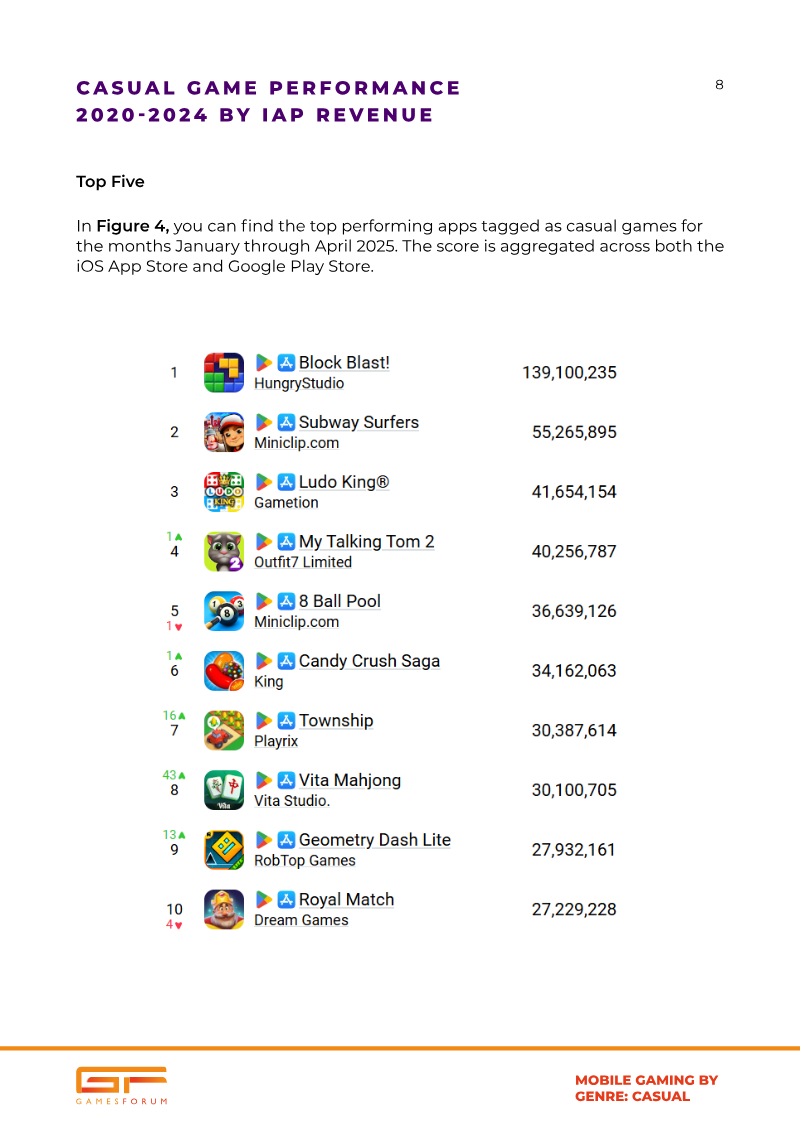
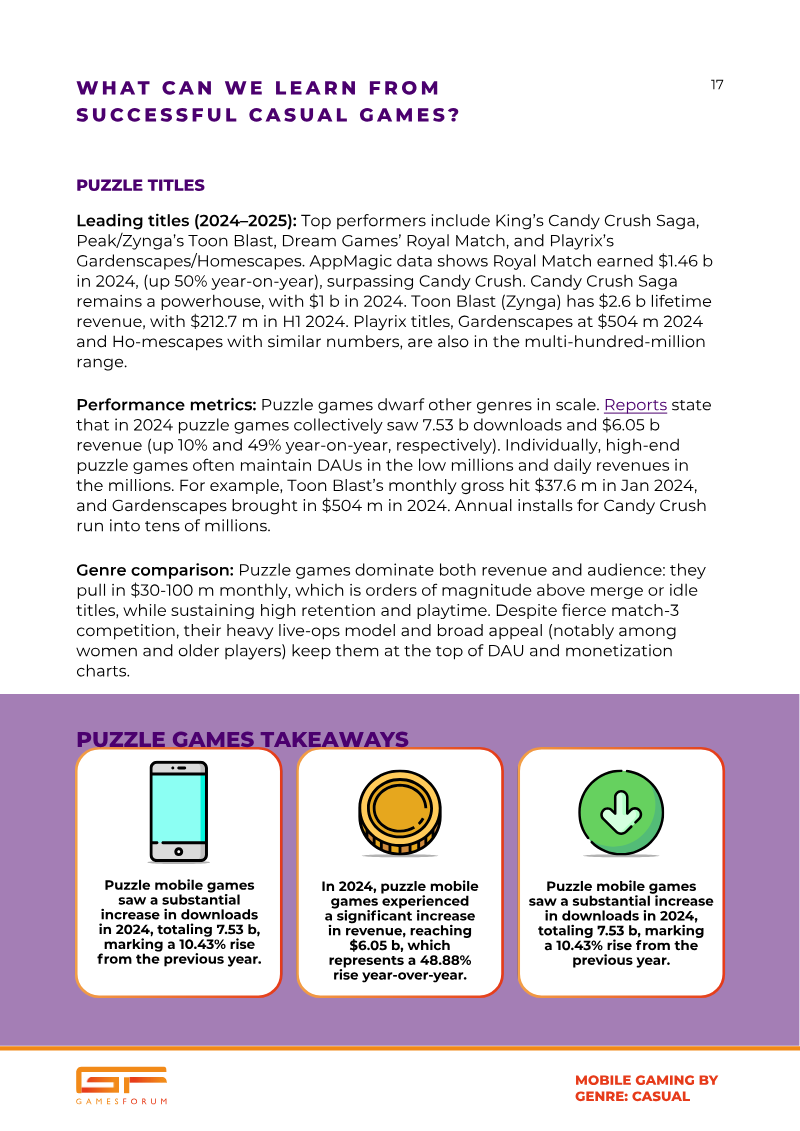
Mobile Gaming: Casual
The analysis demonstrates that casual mobile gaming has entered a phase of mature monetization and strategic diversification.
- Casual mobile gaming is shifting toward higher revenue per user, with IAP revenue projected to grow from $16.8 billion to $22.9 billion by the end of 2025 despite a fluctuating download volume.
- Market leaders demonstrate divergent monetization strategies: Royal Match ($540M) and Monopoly Go! ($431M) rely exclusively on IAPs, while Candy Crush Saga ($421M) successfully integrates advertising.
- Playrix’s portfolio approach, utilizing a suite of titles like Township and Gardenscapes, generated a combined $554 million, proving the effectiveness of hybrid monetization and established franchise management.
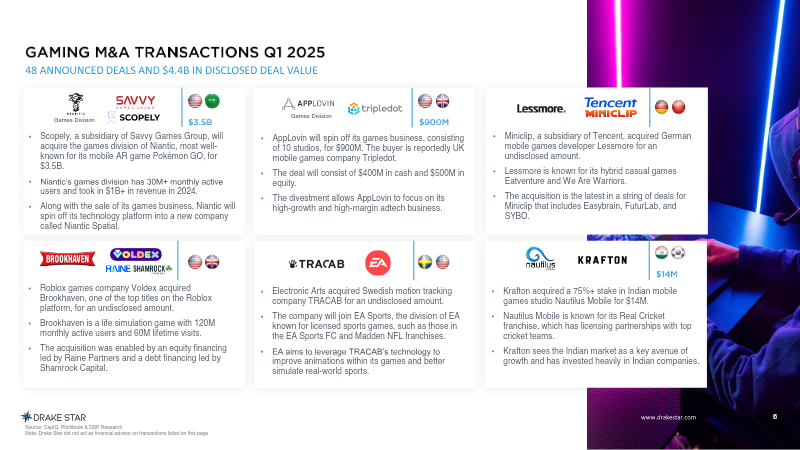
Global Gaming Report: Q1 2025
The global gaming industry experienced a significant resurgence in financial activity during the first quarter of 2025, marked by a substantial rebound in mergers, acquisitions, and private placements.
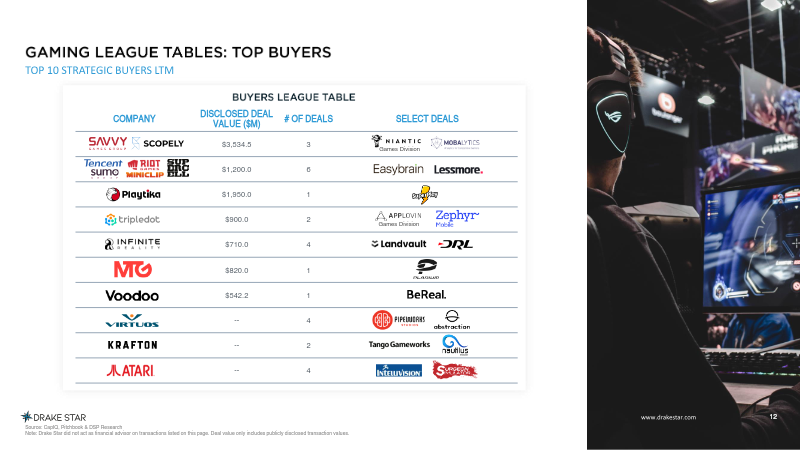
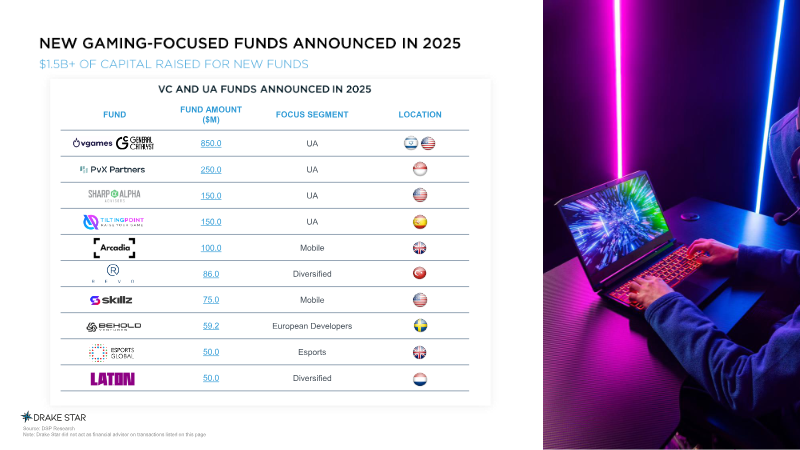
- The gaming industry saw a major financial rebound in Q1 2025, with $4.4 billion in M&A deal value across 48 transactions and $3.5 billion in private investment.
- NVIDIA has become a critical industry infrastructure pillar, achieving a 114% year-over-year revenue surge and a $2.6 trillion market capitalization.
- Private investment was anchored by a $3 billion funding round for Infinite Reality, which reached a $12.25 billion valuation.
Global Gaming Report 2025
The analysis focuses on the accelerating consolidation of the worldwide gaming ecosystem, emphasizing the unprecedented scale of mergers and acquisitions (M&A) and private-placement financing observed in the final quarter of 2025 and projecting a further surge into 2026.
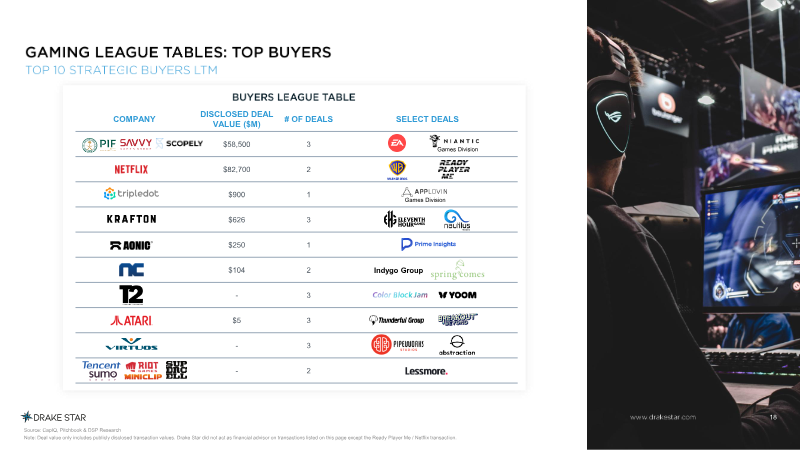
- The gaming M&A market reached a landmark $161 billion in total disclosed value across 759 announced deals in 2025.
- Netflix announced a major $82.7 billion acquisition of Warner Bros. and its gaming division, which triggered a hostile $108.4 billion bid for Warner Bros. Discovery by Paramount–Skydance.
- A consortium led by PIF completed a $55 billion leveraged buyout of Electronic Arts (EA) in September 2025.
Mobile Games in 2025: Trends & Strategies Supercharging Revenue Growth
The global mobile gaming market entered a phase of intensified monetization and efficiency in 2024, characterized by a 3.8% increase in consumer spending to $65.7 billion despite a 6.6% decline in total downloads.
- The mobile gaming market is shifting toward higher monetization efficiency, evidenced by a 3.8% increase in consumer spending to $65.7 billion despite a 6.6% decline in total downloads.
- Spending per download rose by 11.2% in 2024, as the industry prioritizes high-value user retention over the volume-based acquisition strategies of previous years.
- New game releases dropped by over 43%, yet top-tier titles are reaching the $1 million revenue milestone nearly twice as fast as they did in 2022.
Mobile Games Annual Investment Report: June 2024
The mobile games sector experienced a significant contraction in 2023, with total investment and merger and acquisition (M&A) activity falling to a four-year low.
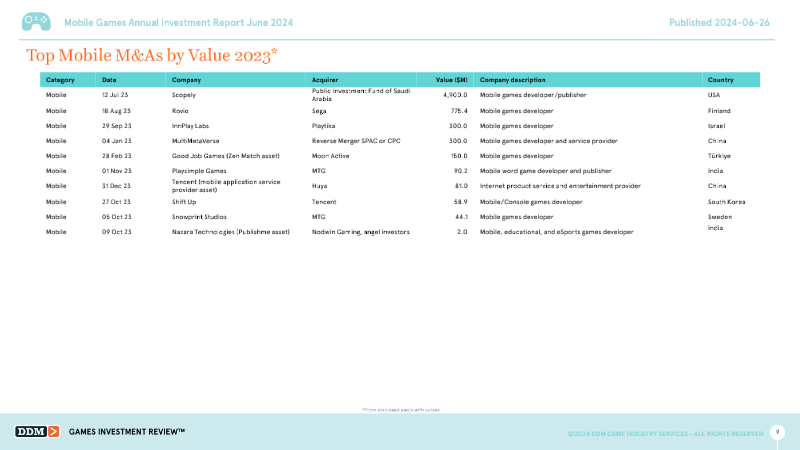
- Mobile gaming investment and M&A activity hit a four-year low in 2023, totaling $7.8 billion across 211 transactions, a 63% decline in value and 33% decrease in volume from 2022.
- M&A activity dominated the market with $6.7 billion across 32 deals, heavily bolstered by the Public Investment Fund of Saudi Arabia’s $4.9 billion acquisition of Scopely.
- Private investment in mobile gaming totaled $1.1 billion across 179 deals in 2023, reflecting a cooling market compared to the 2021 peak.
Landscape Shifts in IP Gaming: An Analysis of How the Competitive Landscape of IP in Gaming Has Shifted in 2023
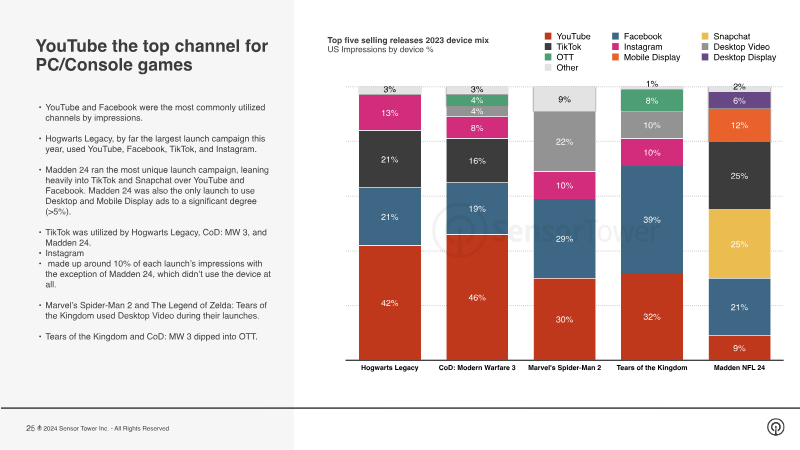
The global gaming landscape in 2023 was defined by the overwhelming commercial dominance of established intellectual properties, which accounted for every top launch on PC and console.
- Established intellectual properties dominated the 2023 market, accounting for every top-performing launch on both PC and console platforms.
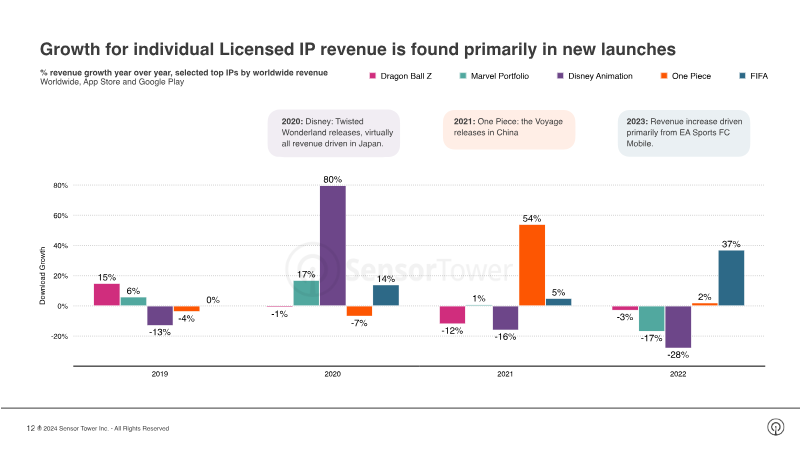
- Licensed mobile titles generated $16 billion in gross revenue in 2023, with Monopoly GO! reaching $1 billion in under seven months to drive Hasbro and Scopely to the top of industry rankings.
- Video game and anime IPs dominate the Asian market with a 70% share of downloads, while board game IPs saw a notable revenue surge in the United States.
Q1'23 Gaming Deals Report
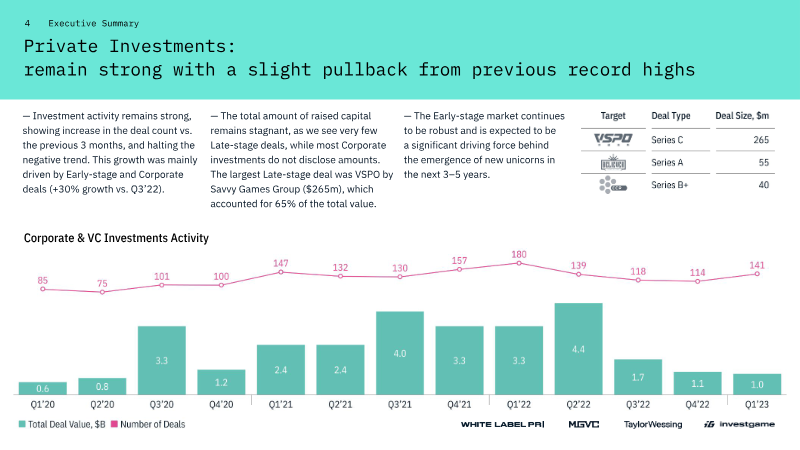
Analysis of the global video game industry’s financial activity in the first quarter of 2023 reveals a period of market correction and stabilization following previous record highs.
- M&A activity hit a multi-year low in Q1 2023 with only 43 closed deals totaling $11.4 billion, representing a 94% year-over-year decline in value.
- Private investment value plummeted 71% year-over-year to $3.3 billion across 141 deals, reflecting a broader market correction and stabilization.
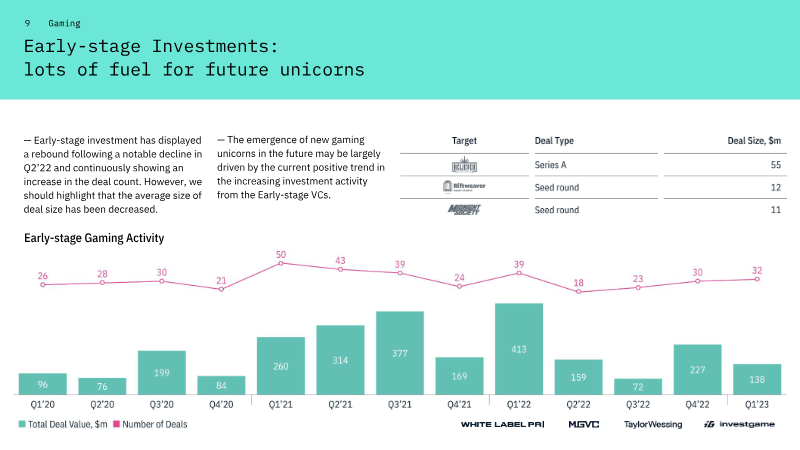
- The market is bifurcated, as early-stage venture capital remains robust while late-stage and public market activities are constrained by high interest rates and bearish sentiment.
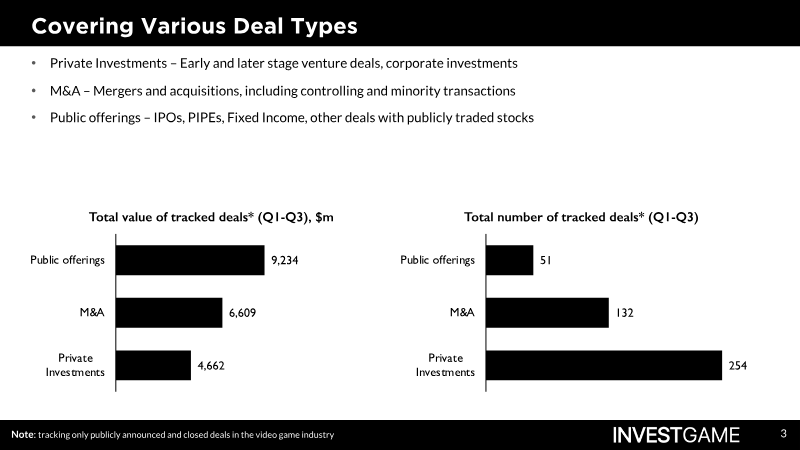
Q1‑Q3 2020: Recap of the Investment Activity in the Video Game Market
The first three quarters of 2020 saw the global gaming industry navigate significant volatility caused by the COVID-19 pandemic, ultimately demonstrating strong resilience and a rapid recovery in deal activity.
- The gaming industry demonstrated strong resilience in 2020, with a July rebound leading to 100 transactions worth approximately $2.78 billion in private investment.
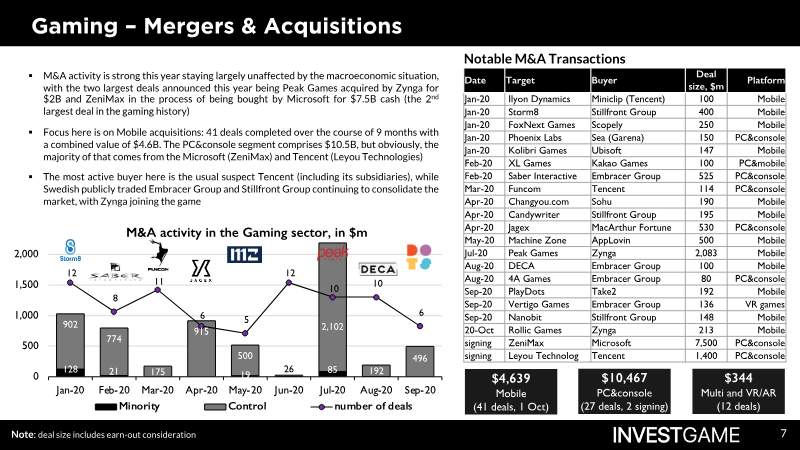
- M&A activity was significant, with the PC and console segment reaching $10.5 billion in value, largely driven by Microsoft’s $7.5 billion acquisition of ZeniMax.
- The mobile gaming segment led in deal volume with 41 transactions totaling $4.6 billion, supported by ongoing consolidation from strategic buyers like Tencent, Embracer Group, and Stillfront Group.