1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReport Digital Development Management
1 free read left. Create a free account for unlimited reading + AI research.
Create free accountReportDigital Development Management
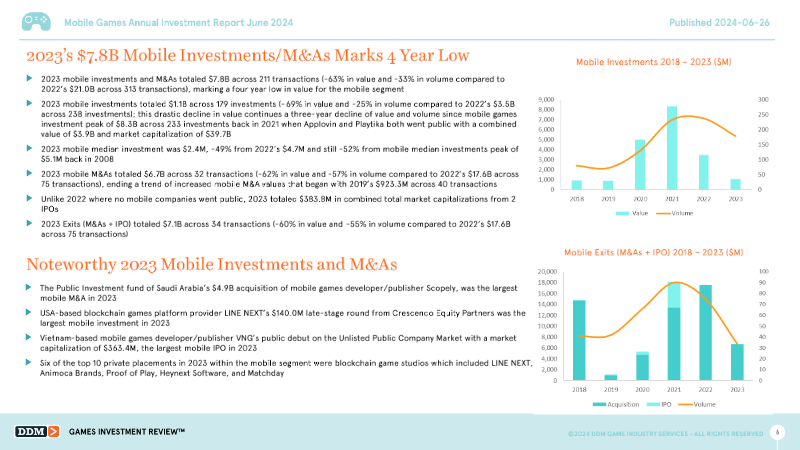
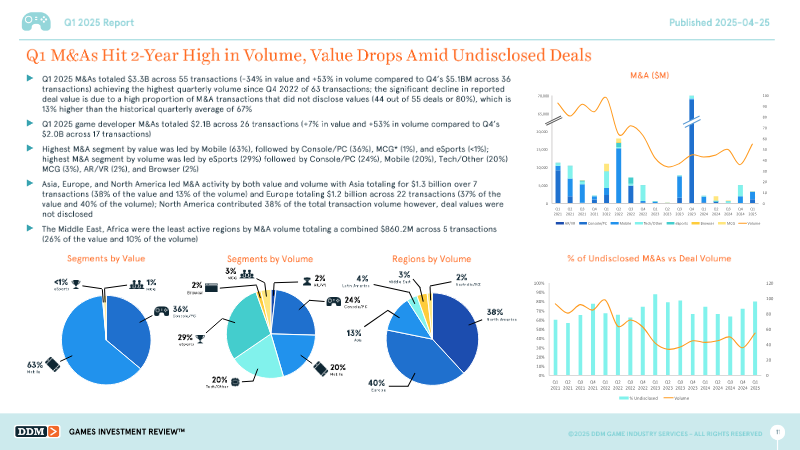
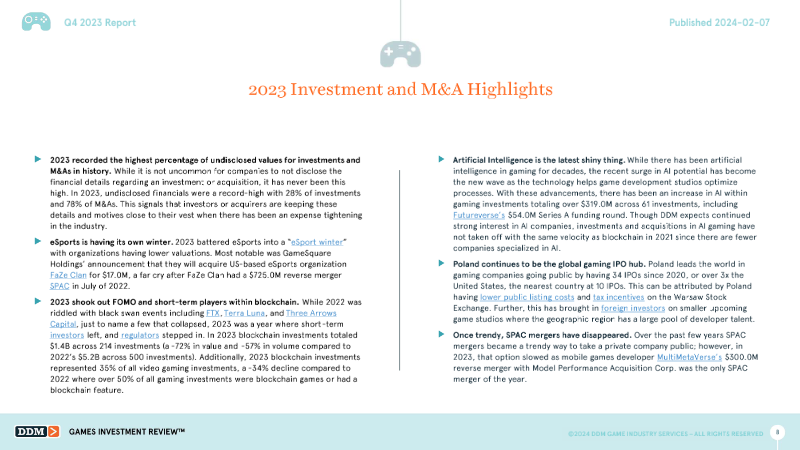
The sector recorded $7.8 billion across 211 transactions. This represents a 63% decline in value and a 33% decrease in volume from 2022.
The mobile games sector experienced a significant contraction in 2023, with total investment and merger and acquisition (M&A) activity falling to a four-year low. The industry recorded $7.8 billion across 211 transactions, representing a 63% decline in value and a 33% decrease in volume compared to the previous year. This downturn reflects a broader cooling of the market following the peak investment period of 2021, which saw $8.3 billion in mobile gaming investments alone.
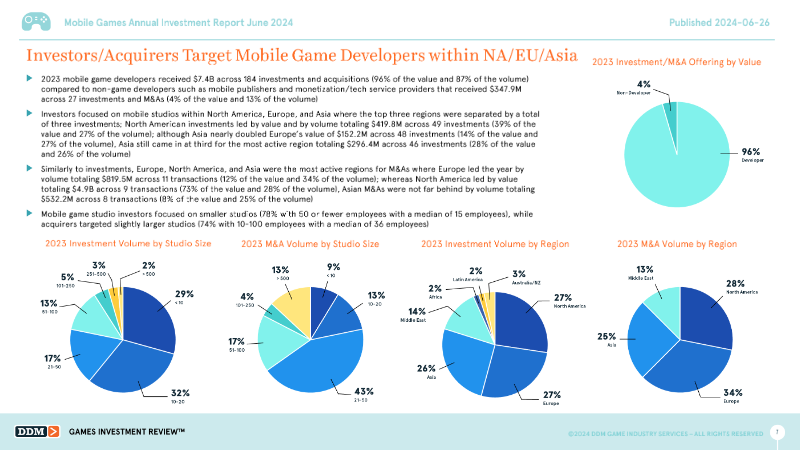
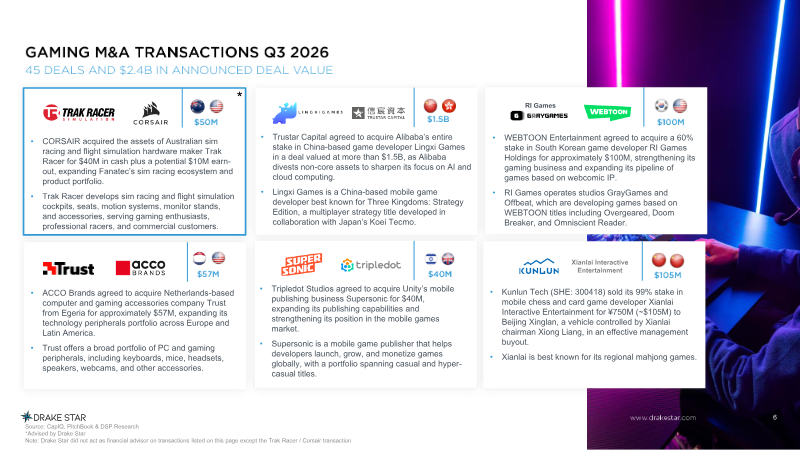
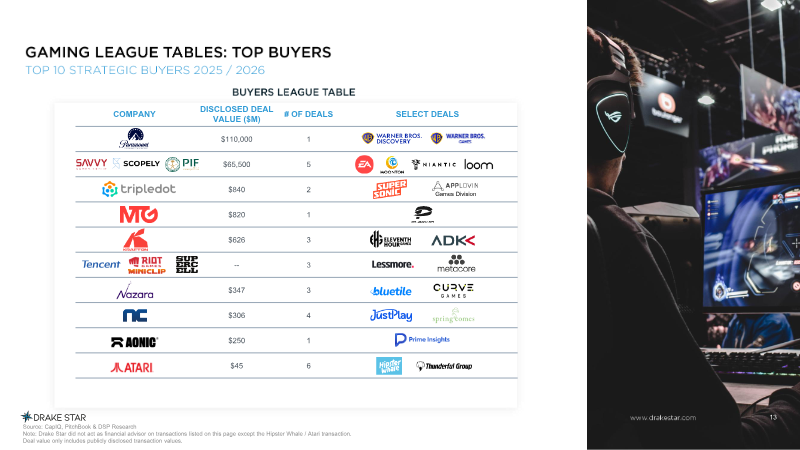
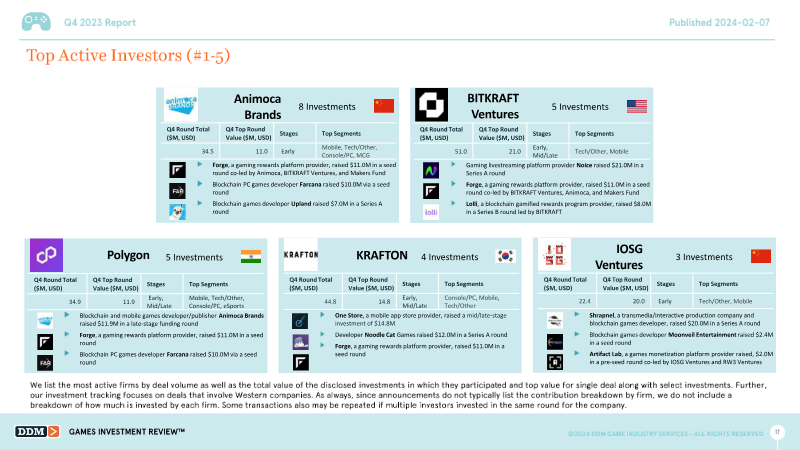
Key findings indicate that 2023 mobile investments totaled $1.1 billion across 179 deals, while M&A activity accounted for $6.7 billion across 32 transactions. The largest single M&A deal of the year was the Public Investment Fund of Saudi Arabia’s $4.9 billion acquisition of Scopely. Despite the overall decline, blockchain-focused studios remained a notable area of interest, representing six of the top ten private placements in the mobile segment. Geographically, North America led in total investment and M&A value, while Europe and Asia remained highly active in terms of transaction volume.
The data highlights a strategic shift in investor behavior, with a clear preference for smaller studios; the median size for investment targets was 15 employees, while acquirers targeted slightly larger entities with a median of 36 employees. The analysis relies on a proprietary database of transactions that have officially closed, excluding merely announced deals to ensure accuracy in measuring deployed capital. This research covers Western-focused investments across global regions, providing a granular view of the mobile gaming landscape from 2018 through 2023.
Digital Development Management · 2025
DDM · 2025
Digital Development Management · 2024
DDM · 2024
Digital Development Management · 2023
Deconstructor of Fun · 2024