Monetization reports and market data
Documents
How Consumers Engage with Games Today: Newzoo’s Global Gamer Study 2024
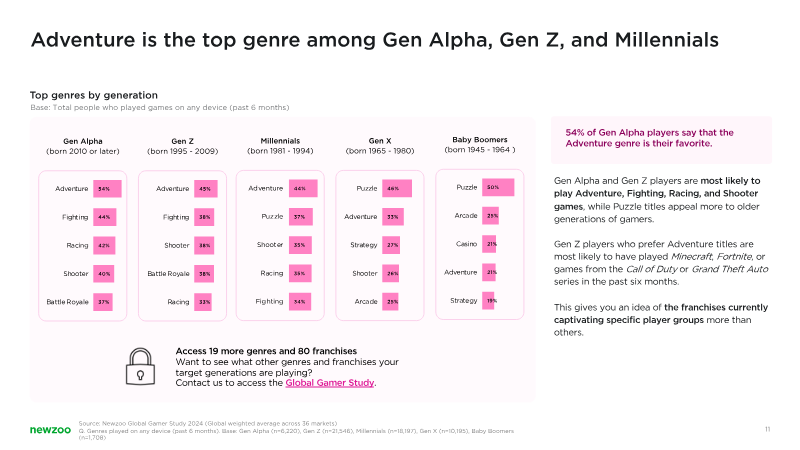
Gaming dominates contemporary culture, with eight in ten global consumers actively playing or engaging in related activities.
- Gen Z and Gen Alpha players spend an average of 5.2 hours per week gaming, surpassing their time spent on social media.
- Approximately 22% of Gen Z players spend $25 or more monthly on games, showing a strong preference for upfront payments compared to the free-to-play model favored by mobile gamers.
- One-third of PC/console gamers are 'new game seekers' who spend 7–8 hours weekly across multiple platforms and consistently invest over $25 monthly.
Sensor Tower Global Mobile Gaming Industry Outlook 2024
Global mobile gaming experienced a minor 2% year-on-year decline in in-app purchase revenue in 2023, totaling $76.7 billion.
- Global mobile gaming revenue reached $76.7 billion in 2023, a 2% year-on-year decline, but is projected to recover to $78 billion in 2024 and exceed $100 billion by 2028.
- Consumer spending is shifting toward casual and hybrid-casual models, with casual revenue growing 8% to $28.6 billion and hybrid-casual revenue surging 30% to over $2.1 billion.
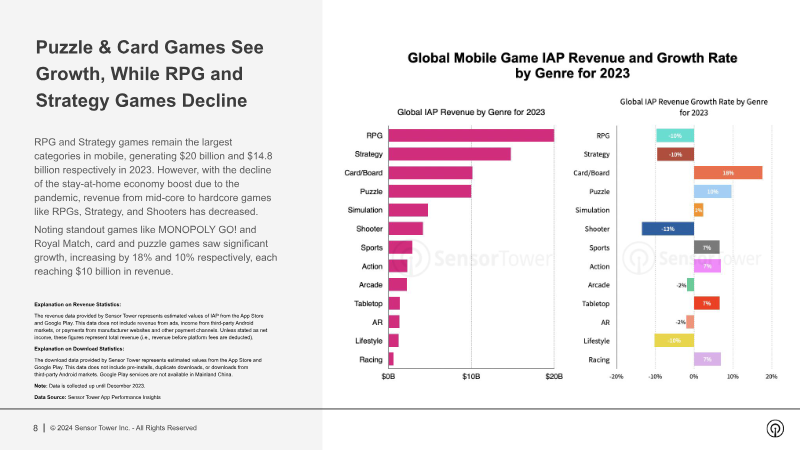
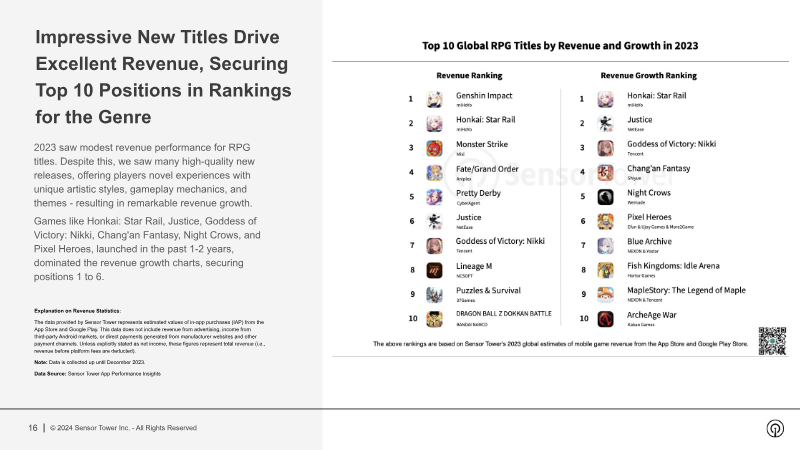
- Traditional high-revenue segments, specifically RPGs and Strategy games, experienced a 10% decline in 2023, though they remain the largest categories at $20 billion and $14.8 billion respectively.
Global Games Market Report
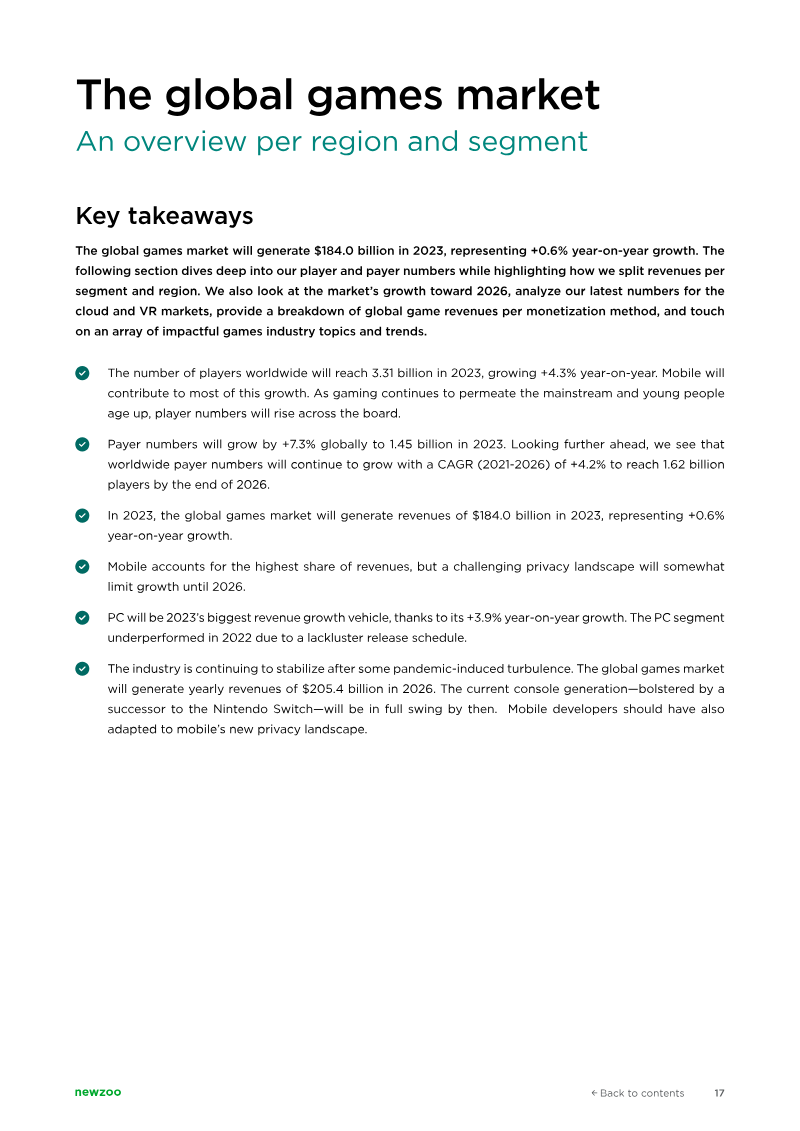
The global games market is entering a period of stabilization and renewed growth, with 2023 revenues projected to reach $184.0 billion.
- The global games market is projected to reach $184.0 billion in 2023, with a forecast to grow to $205.4 billion by 2026 supported by a 3.31 billion-person player base.
- Mobile gaming remains the largest revenue segment at $89.7 billion, though it is currently experiencing a 1.4% decline due to privacy-related challenges in user acquisition and monetization.
- PC and console gaming are the primary industry growth engines for 2023, driven by improved hardware supply and a strong pipeline of high-profile software releases.
State of Free to Play on Steam in 2024
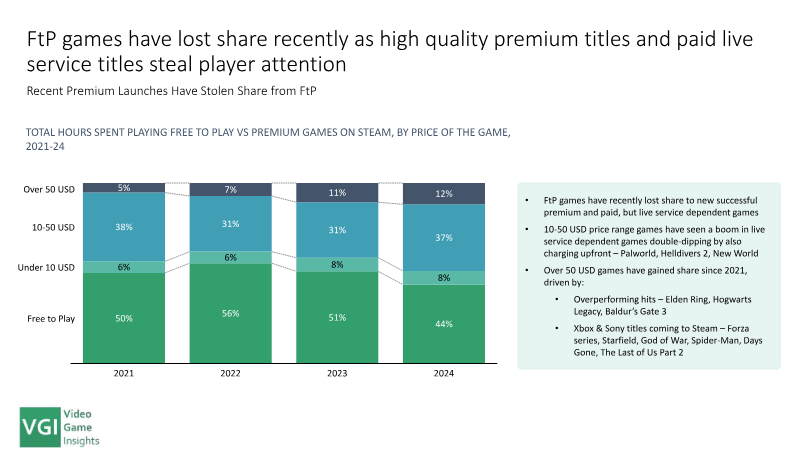
The analysis evaluates the free-to-play (FtP) segment on Steam, highlighting its dominant share of player engagement and the increasing difficulty for new titles to break through.
- Free-to-play (FtP) games dominate Steam engagement, accounting for 51% of total hours played in 2023 despite being outnumbered by premium releases.
- Market engagement is highly concentrated, with the top 25 FtP titles capturing 88% of all FtP activity and the top five titles holding nearly 60% of concurrent users.
- The FtP sector is stagnant for new entrants, as the top ten FtP games have a mean age of seven years and only two new titles have broken into that tier since 2021.
Mobile Growth and Monetization Report 2024
The 2024 mobile gaming landscape is defined by a strategic transition from volume-based user acquisition toward high-value retention and diversified monetization.
- Offerwalls significantly outperform rewarded video for non-paying users, generating $4.04 in monthly ad revenue per converter compared to $0.15 for rewarded video.
- Only 1.83% of mobile users convert to in-app purchases, but 29% of those converters become repeat buyers, with most transactions occurring within the first 30 days of installation.
- Strategic use of monthly currency sales can increase in-app purchase conversion rates by up to 46%.
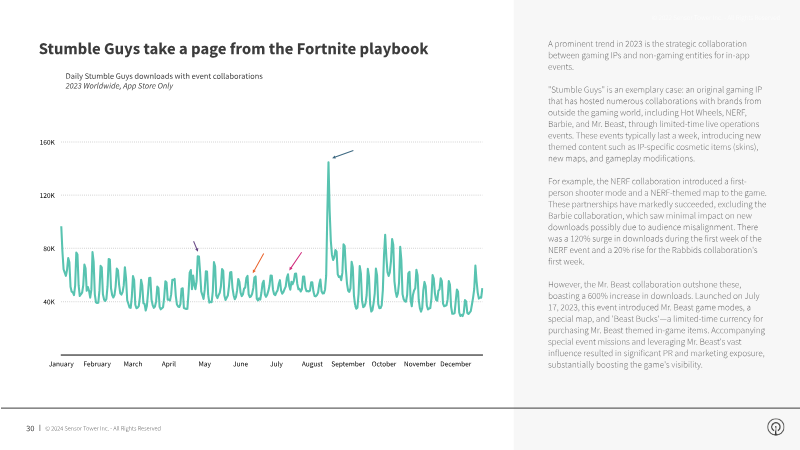
The State of Gaming 2024: An Analysis of the Current Mobile Gaming Market Trends
The global mobile gaming market underwent a significant correction in 2023, characterized by a 10% decline in worldwide downloads and a 2% drop in total revenue.
- The global mobile gaming market contracted in 2023, with a 10% decline in downloads and a 2% drop in total revenue due to rising user acquisition costs and post-pandemic habit stabilization.
- Player preferences shifted toward accessibility, resulting in an 8% revenue increase for Casual games and a 30% surge in the Hybridcasual segment, while Mid-core titles saw a 9% revenue decline.
- Publishers are pivoting to emerging markets to offset costs, with the Middle East, Europe, and Latin America seeing revenue growth of 8%, 7%, and 4% respectively.
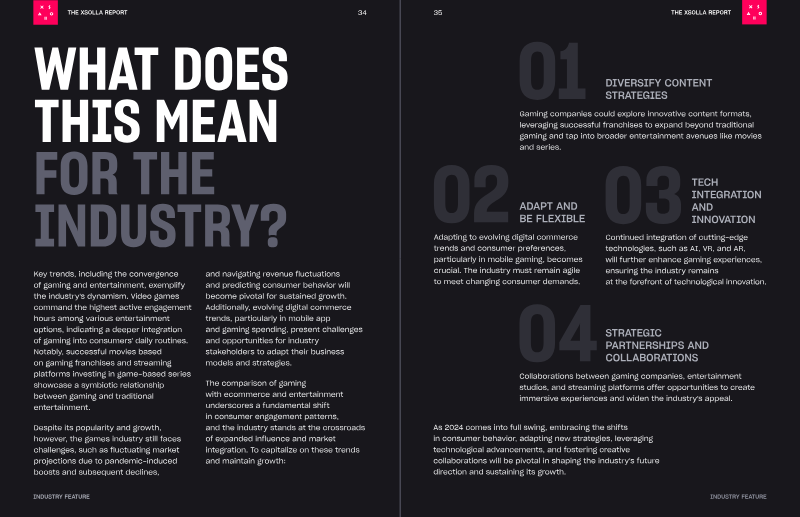
State of Play: Winter 2024
The analysis projects global gaming revenue to reach approximately $205.7 billion by 2026, up from $106.8 billion in 2023, reflecting an average annual growth rate of 3.9 percent.
- Global gaming revenue is projected to reach $205.7 billion by 2026, growing at an average annual rate of 3.9 percent from its 2023 baseline of $106.8 billion.
- Mobile gaming serves as the primary industry engine, with the sector expected to generate $111.4 billion in spend following 76.8 billion app downloads across iOS and Google Play in the first half of 2023.
- Consumer spending experienced high volatility in 2023, surging by 60 percent early in the year before stabilizing within a range of –10 percent to +20 percent.
Casual Gaming Apps Report 2024
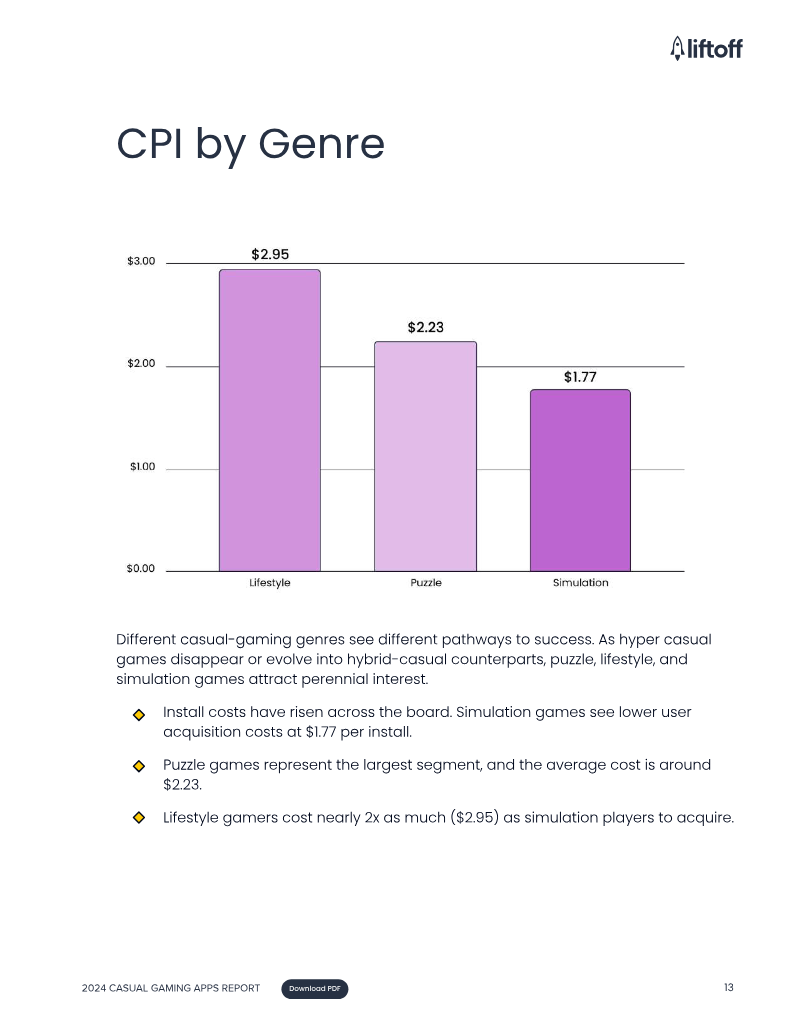
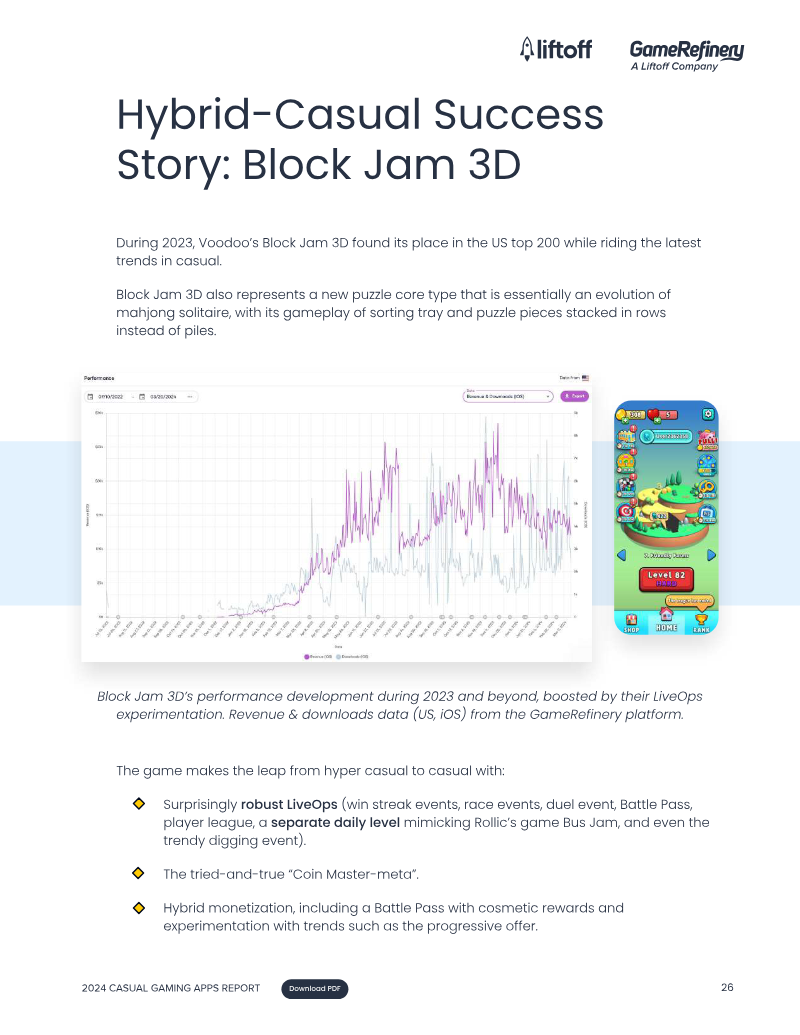
The mobile gaming landscape is currently defined by a strategic shift toward casual and hybrid-casual experiences, which serve as the primary engine for industry growth and user acquisition.
- Puzzle games now account for 37% of all mobile gaming installs as the industry shifts away from hyper-casual titles.
- Casual mechanics are increasingly vital for mid-core titles, currently driving 74% of their total installs.
- User acquisition costs on iOS remain significantly higher than Android, with a cost-per-install of $4.83 that is nearly eight times the rate on Android.
Mobile Ad Creative Index 2024
The Mobile Ad Creative Index provides a comprehensive analysis of performance benchmarks and emerging trends within the mobile advertising ecosystem.
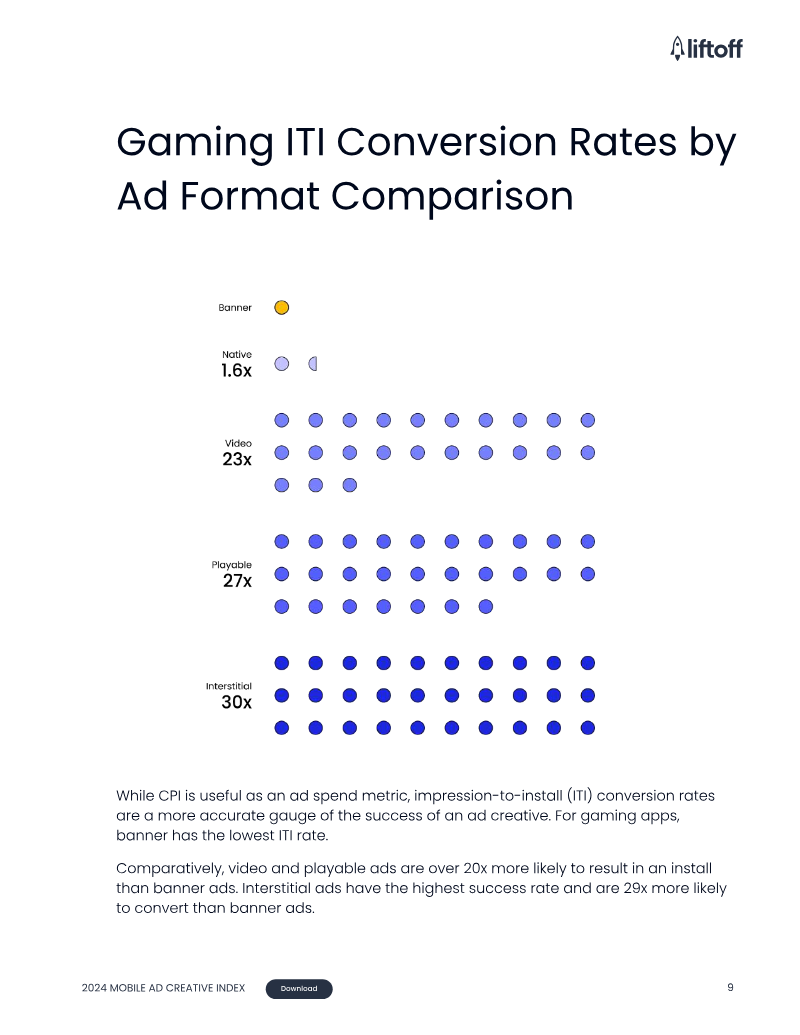
- High-engagement formats like video and playables outperform banners by 20 times in gaming installs, while finance sector interstitials are 18 times more effective at conversion.
- Long-form video ad spend grew by 245% year-over-year, and 'triple-page' ads combining video, playables, and end cards saw a 355% increase in investment.
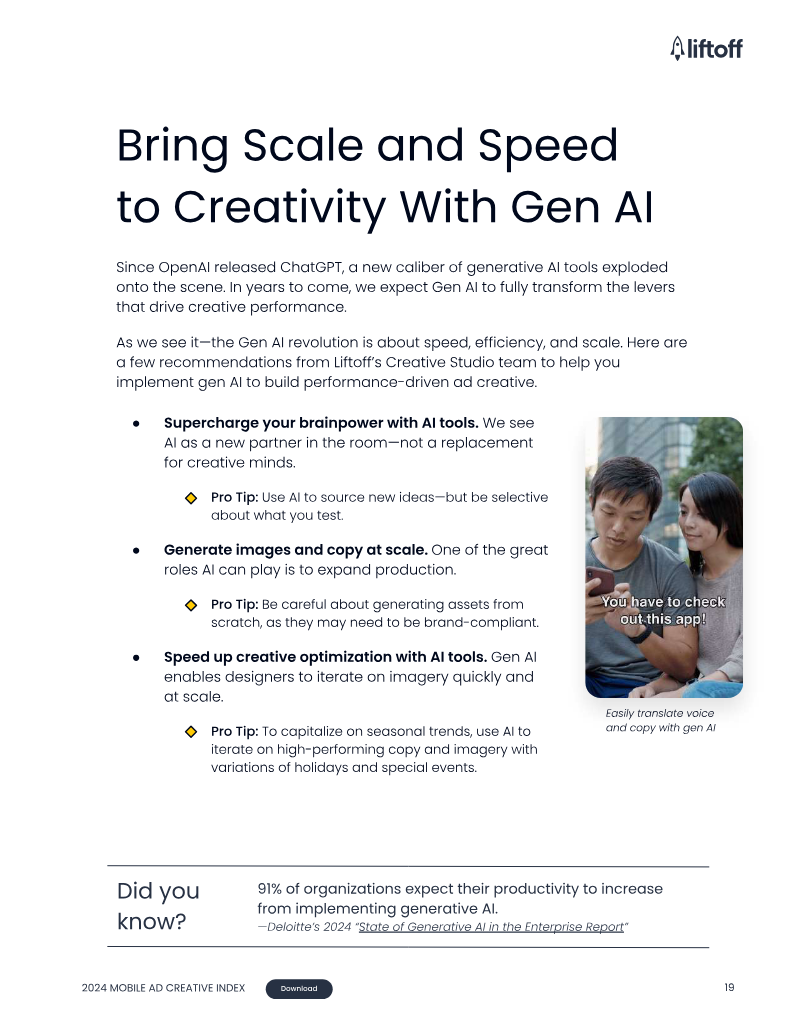
- Optimized user-generated content (UGC) ads achieve a 20% lower cost-per-install (CPI) compared to standard video creative.
Mobile Gaming Spender Report: Decoding Today’s Mobile IAP Spenders to Understand Motivations, Engagement
The 2024 Mobile Gaming Spender Report by Mistplay examines the evolving motivations, behaviors, and shifting financial priorities of mobile in-app purchase (IAP) spenders.
- Economic headwinds are driving a contraction in spending, with 32% of all mobile spenders and 41% of high-value spenders planning to reduce their in-game expenditures in 2024.
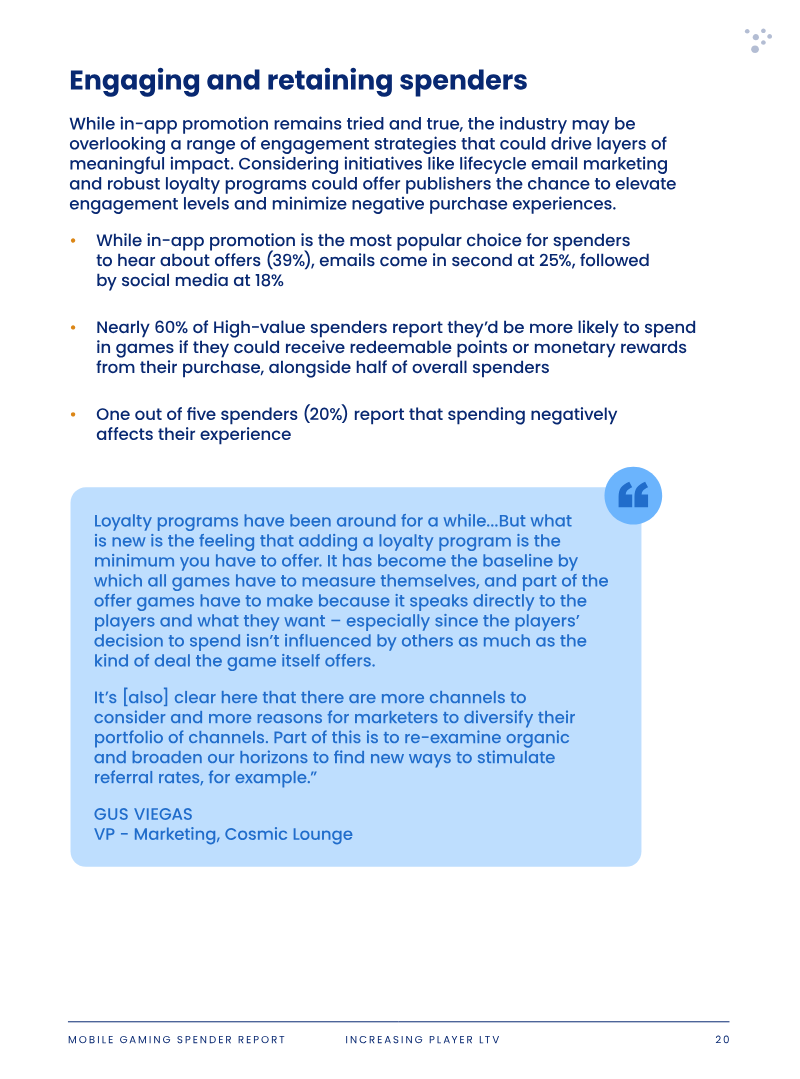
- Value-driven incentives are critical for retention, as 51% of spenders would increase their spending if they earned tangible rewards or points for their purchases.
- Loyalty programs and hyper-personalization are essential engagement tools, with 79% of spenders engaging with loyalty programs and 40% influenced by personalized offers.
The State of Gaming 2024
The global mobile gaming market underwent a significant correction in 2023, characterized by a 10% decline in downloads and a 2% dip in overall revenue.
- The global mobile gaming market contracted in 2023, with a 10% decline in downloads and a 2% dip in revenue due to rising user acquisition costs and post-pandemic habit stabilization.
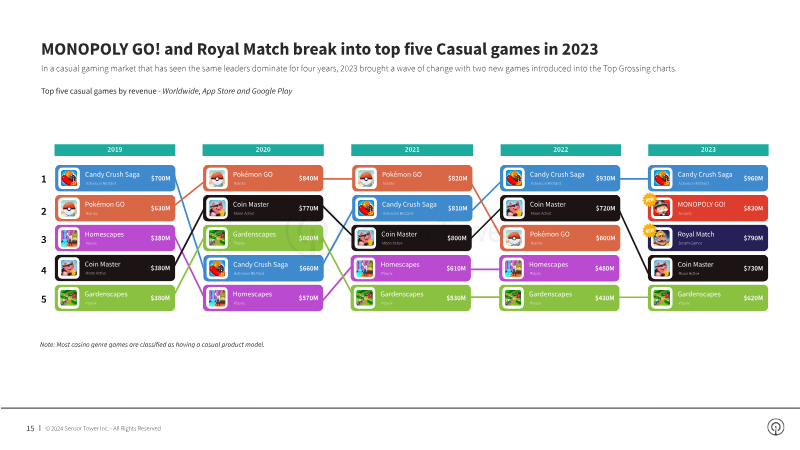
- Market segment preferences shifted significantly in 2023, as mid-core revenue fell by 9% while casual and hybrid-casual segments grew by 8% and 30%, respectively.
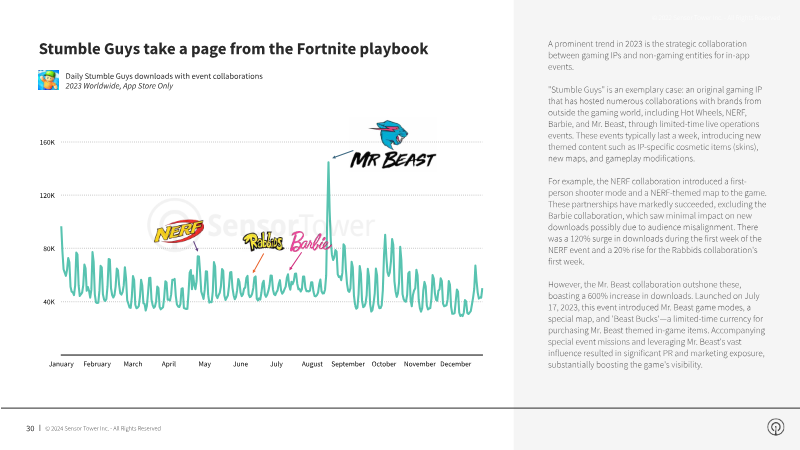
- Mobile advertising now accounts for 67% of global gaming ad spend, with marketing strategies increasingly relying on high-impact collaborations and transmedia IP to drive organic discovery.
State of Free-to-Play on Steam in 2024
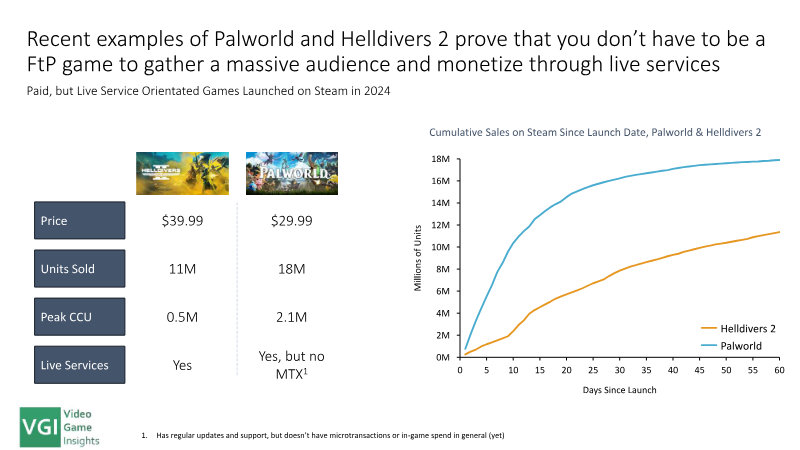
The free-to-play (F2P) market on Steam represents a dominant but increasingly consolidated segment of the PC gaming industry.
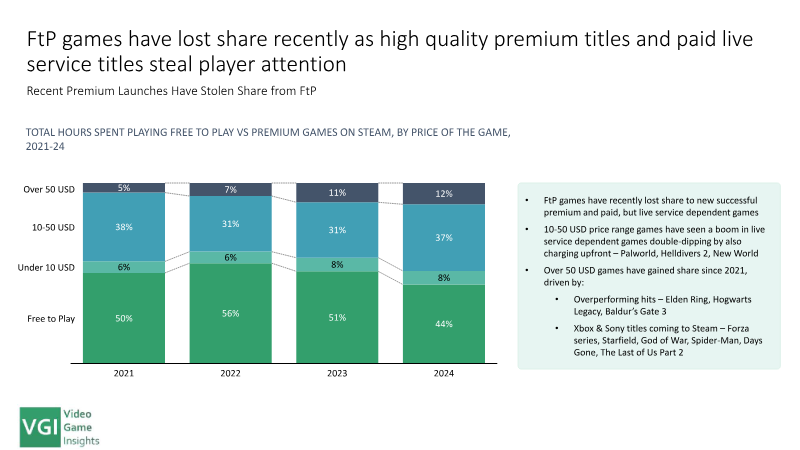
- Free-to-play titles dominate Steam engagement, accounting for 51% of all player hours despite representing only a small fraction of the platform's total game library.
- The F2P market is highly consolidated, with the top 25 titles capturing 88% of all F2P playtime.
- Market entry is increasingly difficult, as the average age of a top-ten F2P game is seven years, and only two new titles have successfully maintained a top-ten position over the last three years.