PC reports and market data
Documents
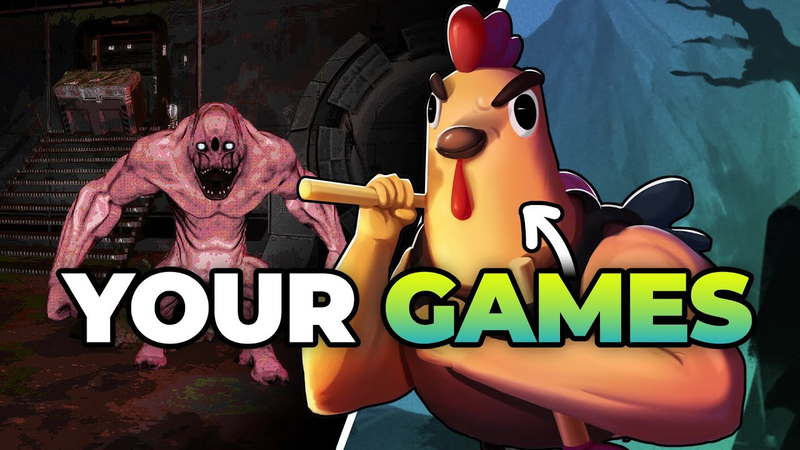
I Played YOUR Games (Indie Game Feedback)
The indie game showcase evaluates three distinct projects through live gameplay to provide constructive feedback on mechanics, visual design, and user experience.
- The physics-based platformer 'Chickens Don't Fly' emerged as the top performer, securing 58% of the community vote due to its addictive 'plunger' movement mechanic.
- Despite its popularity, 'Chickens Don't Fly' requires improved visual aesthetics and vertical environmental storytelling to better support its high-stakes gameplay.
- The cooperative game 'Treasure Hunters' received 25% of the vote, with feedback highlighting a need to resolve technical glitches and clarify gameplay objectives.
PC & Console Year in Review: 2025
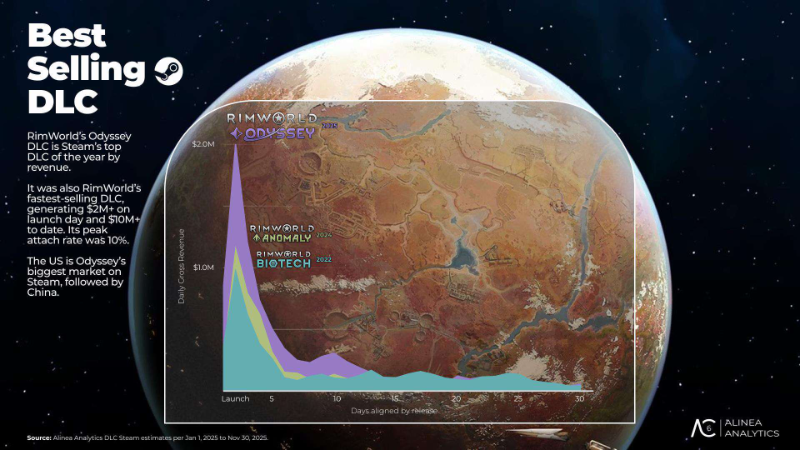
The 2025 PC and Console Year in Review provides a comprehensive analysis of the global gaming landscape, focusing on market performance, consumer behavior, and development trends.
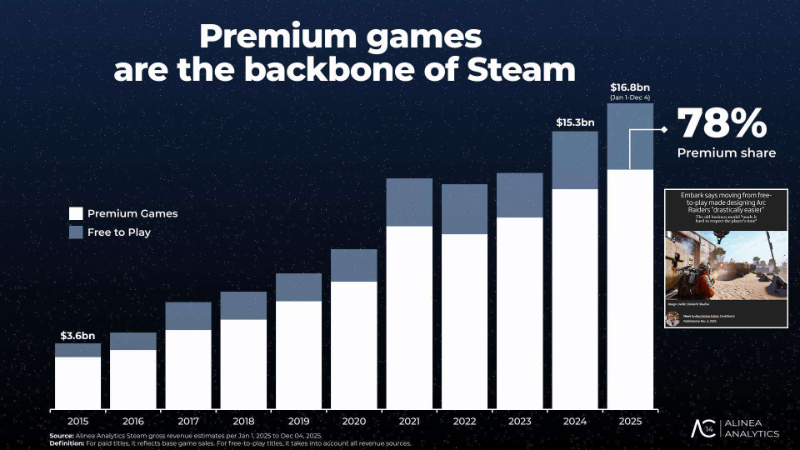
- Premium games dominate the market, accounting for 78% of Steam’s $16.8 billion total revenue in 2025.
- Cooperative gameplay is a primary driver of commercial success, with 11 of the top 20 highest-grossing titles featuring co-op mechanics.
- Indie developers contribute over 25% of Steam’s total revenue, with 'Triple-I' titles delivering exceptional return on investment.
The State of AAA Game Advertising: 2023 Review
The 2023 AAA game advertising landscape underwent a strategic pivot toward launch-focused campaigns, with new releases accounting for half of all top-tier spending.
- In 2023, AAA publishers shifted toward launch-focused campaigns, with new releases accounting for 50% of all top-tier advertising expenditure.
- While YouTube remains the primary advertising medium for PC and console games, publishers are increasingly diversifying their media mix by integrating Facebook, TikTok, and Instagram to target specific demographics.
- Strategic platform-based partnerships, such as deep Xbox branding and hardware collaborations, are now essential for anchoring major titles within broader ecosystem strategies.
The State of Video Gaming: 2025
The global video game industry is currently undergoing a structural correction following a decade of rapid expansion that concluded in 2021.
- The video game industry is undergoing a structural correction characterized by a 12% decline in real-term content spending following the post-2021 plateau of previous growth engines.
- Market polarization has intensified as AAA production budgets reach $500 million, causing revenue and engagement to concentrate within established franchises while crowding out new releases.
- Chinese developers have significantly expanded their global footprint, increasing their share of non-domestic content spending from 0.5% to 12.5% over the last 13 years.
The Importance of Wishlists in 2025: Do Wishlists Matter?
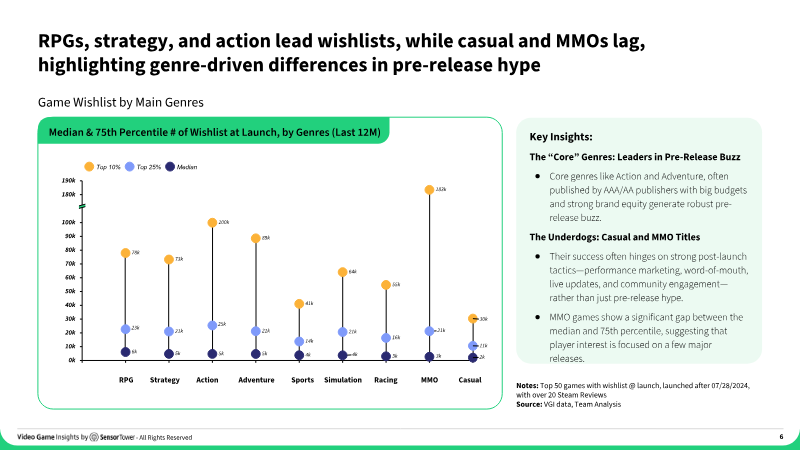
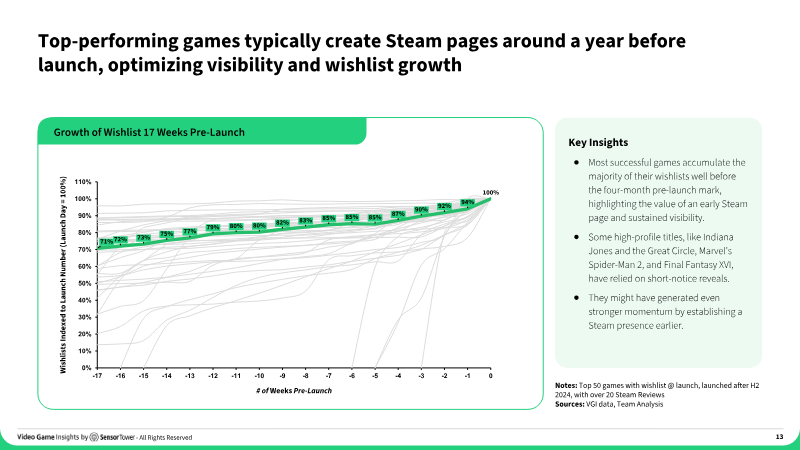
Steam wishlists serve as a critical metric for predicting commercial success in the video game industry, functioning as a primary indicator of pre-launch momentum.
- Steam wishlists are a primary indicator of commercial success, showing a 70% correlation between pre-launch counts and first-month unit sales.
- The 100,000-wishlist threshold is the critical benchmark required to reliably forecast a breakout performance for a new title.
- The vast majority of games launch with fewer than 10,000 wishlists, reflecting a highly top-heavy distribution of pre-launch momentum.
Key Insights into Shooter Games
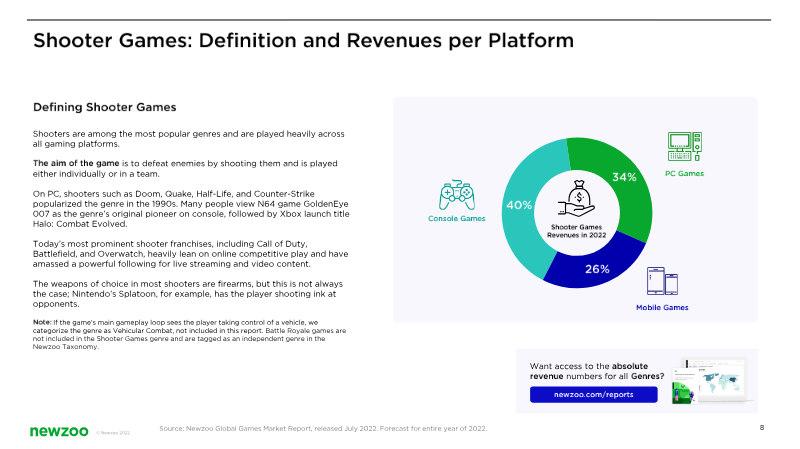
Shooter games represent the fifth highest-earning genre worldwide, generating approximately $2.24 billion in 2022 across all platforms.
- Shooter games generated approximately $2.24 billion in 2022 across 37 global markets, excluding China and India.
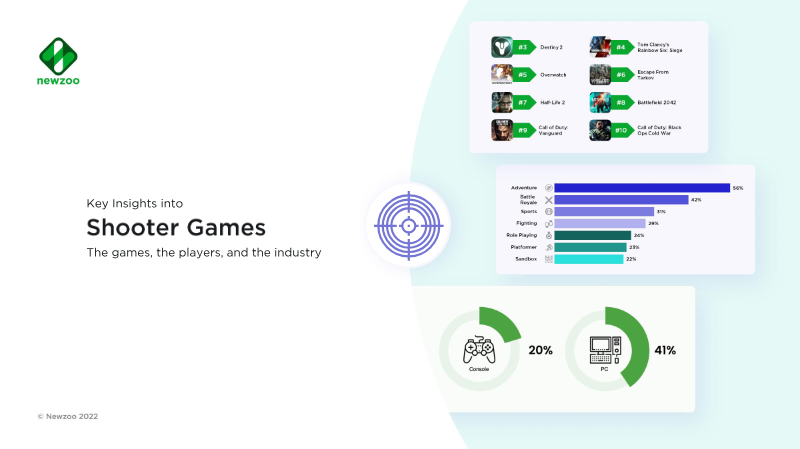
- Shooters are a dominant force on PC and console platforms, capturing 68% of monthly active users.
- Monetization in the genre is heavily driven by in-app purchases, which are experienced by 97% of shooter players, while advertising remains the least utilized revenue model.


China Game Industry Report 2025
The China Game Industry Report for 2025 presents a comprehensive assessment of the domestic and overseas gaming markets, highlighting sustained growth driven by youth protection initiatives, technological innovation, and cross-sector integration.
- Chinese self-developed mobile games generated US$20.455 billion in overseas revenue in 2025, marking a 10.23% year-on-year increase and the sixth consecutive year exceeding RMB 100 billion.
- The United States remains the primary overseas market for Chinese games, accounting for 32.31% of total export revenue, followed by Japan at 16.35% and South Korea at 9.15%.
- Strategy games (SLG) dominate the overseas market, capturing 49.97% of earnings, significantly outpacing shooters at 9.69% and RPGs at 9.39%.
The Big Game Engine Report of 2025
The Big Game Engine Report 2025 examines the shifting landscape of game development technology, focusing on the transition from proprietary in-house tools to third-party public engines.
- The share of Steam releases powered by custom in-house engines plummeted from over 70% in 2012 to 13% in 2024.
- Custom engines have fallen below 50% of total unit sales for the first time, currently accounting for 42% of the market.
- Unity remains the volume leader, powering 51% of all Steam releases in 2024, primarily dominating the 'Tiny' and 'Small' categories under 100k units.
State of Gaming & Influencer Marketing 2025
The global gaming industry has entered a period of stabilization, with 2024 revenues reaching $187.7 billion and a projected player base of 4 billion by 2027.
- The global gaming industry reached $187.7 billion in 2024, with mobile gaming remaining the dominant sector at $92.6 billion and the total player base projected to hit 4 billion by 2027.
- PC gaming is a primary growth driver, highlighted by Steam’s record $10.8 billion revenue in 2024 and indie game sales surpassing those of AA and AAA titles for the first time.
- Influencer marketing spending is projected to reach $32.55 billion by 2025, with a strategic shift toward niche engagement and nano-influencers who achieve engagement rates exceeding 10%.
The State of AAA Game Advertising: A Look Back on the Biggest Launches and Trends of the Past Year
The 2023 PC and console gaming landscape was defined by a strategic pivot toward new title launches, which commanded 50% of top advertising expenditures compared to only 20% the previous year.
- AAA advertising shifted heavily toward new title launches in 2023, which accounted for 50% of total ad spend compared to just 20% in the previous year.
- YouTube remains the dominant advertising channel at 35% of total spend, though marketing budgets are increasingly diversifying into TikTok, Instagram, and OTT services to leverage short-form video engagement.
- High-budget marketing is no longer the sole path to success, as titles like Lethal Company and PalWorld achieved millions of sales through viral gameplay and creator-driven interest with minimal ad investment.
Starfield: How It Achieved 10M Players
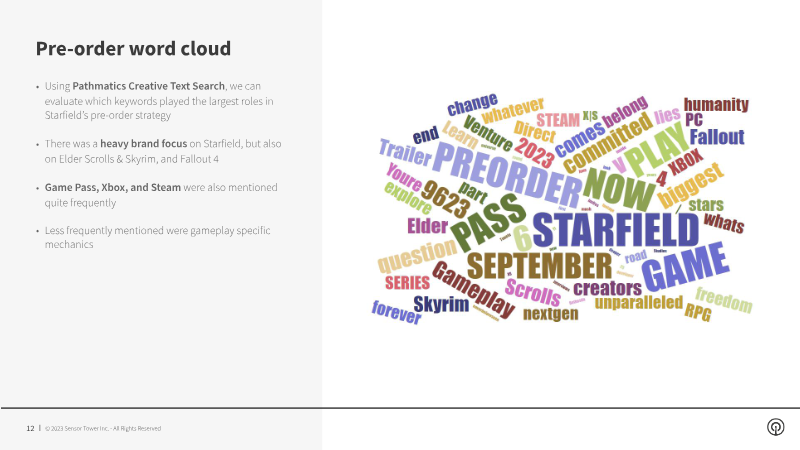
The marketing and commercial performance of Bethesda’s Starfield reflects a strategic evolution in digital promotion, transitioning from traditional trailer-based campaigns to a diversified, multi-channel approach.
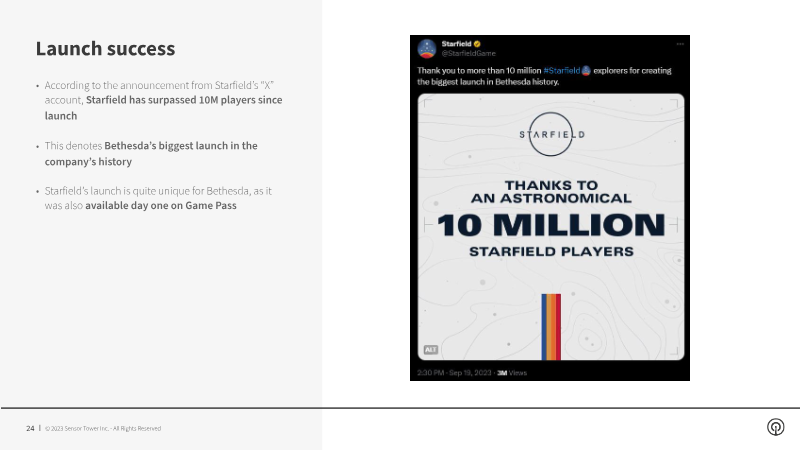
- Starfield reached 10 million players at launch, marking the largest release in Bethesda’s history despite a competitive RPG market.
- The marketing campaign utilized a $21.2 million advertising budget, the second-highest in the RPG category for 2023.
- Over one-third of the total advertising budget was allocated to Over-the-Top (OTT) streaming services, reflecting a strategic shift toward high-impact digital distribution.
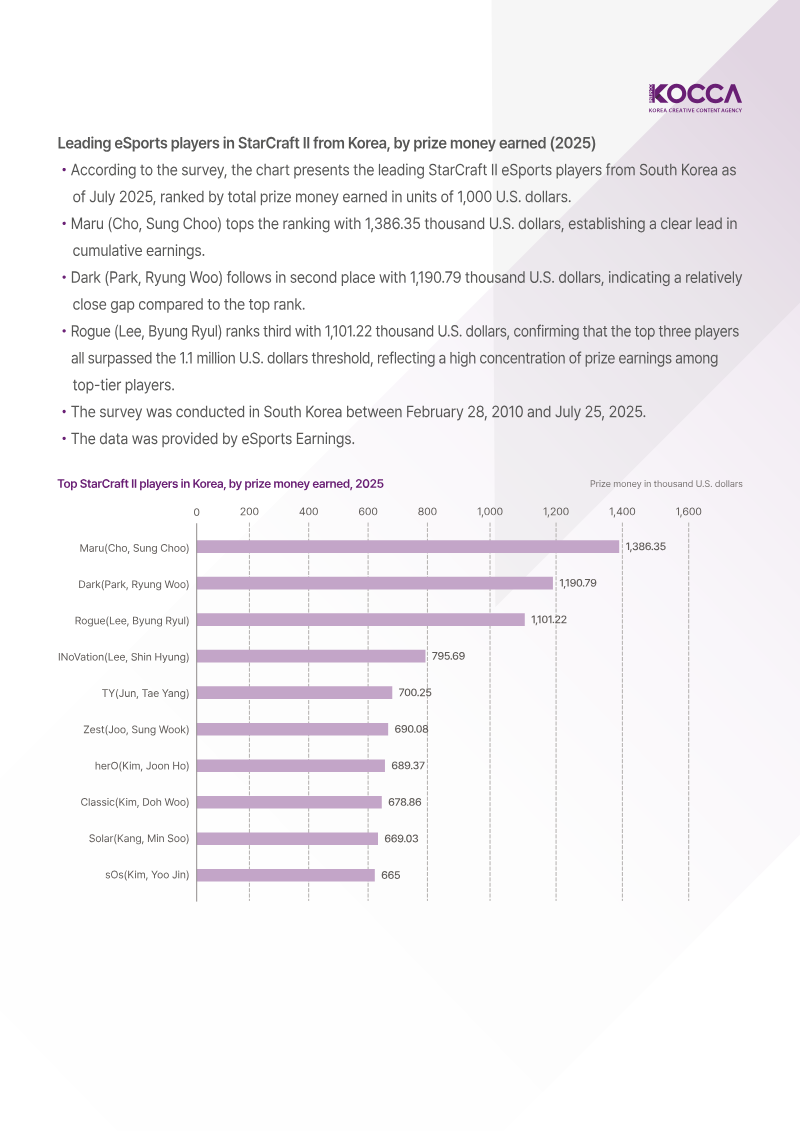
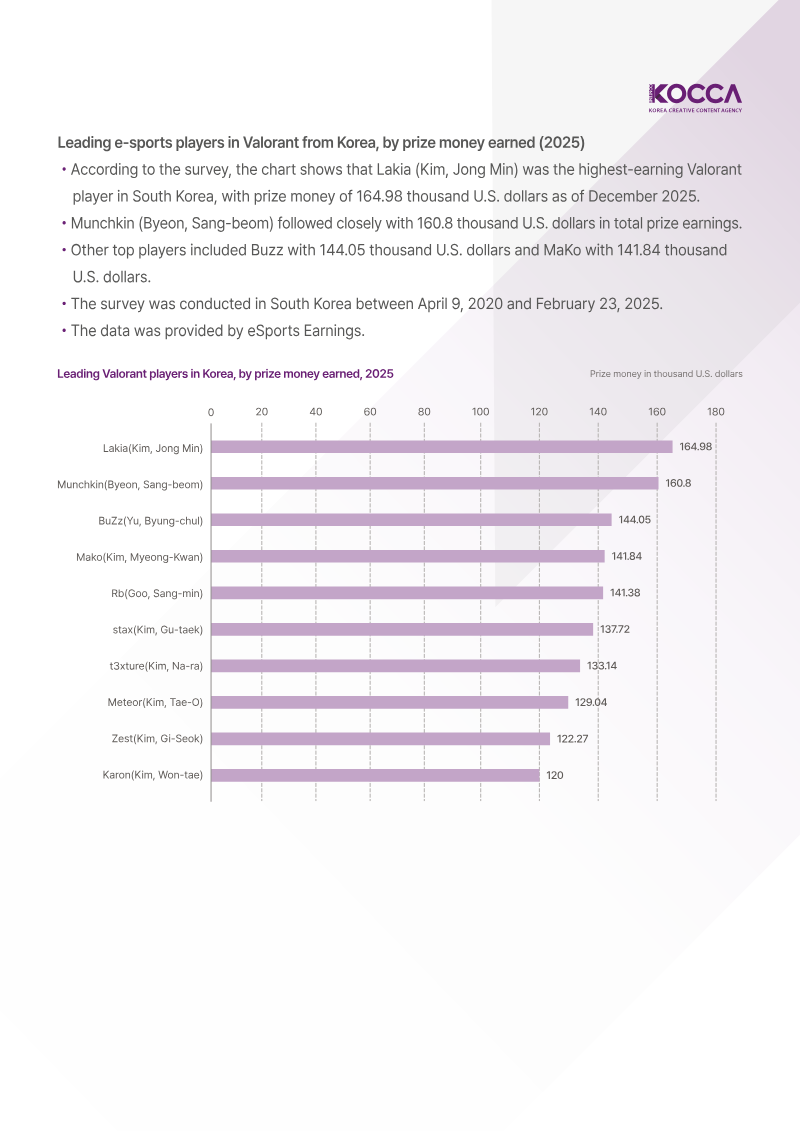
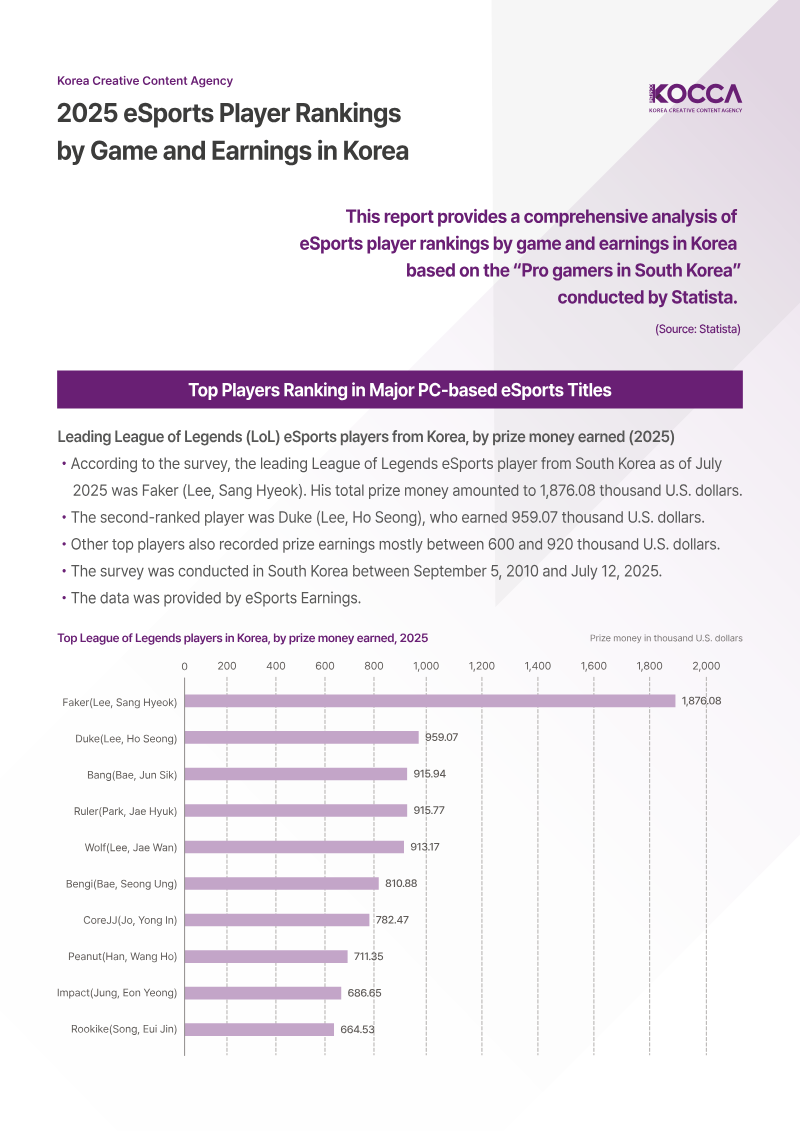
2025 eSports Player Rankings: By Game and Earnings in Korea
South Korea’s professional gaming landscape is characterized by a title-centered evaluation system where prize earnings are highly concentrated among elite players.
- League of Legends remains the most lucrative eSports title in South Korea, with top earner Lee Sang-hyeok (Faker) accumulating $1.88 million in prize money as of July 2025.
- Established titles offer significantly higher financial returns than newer games, as evidenced by StarCraft II leader Cho Sung-choo earning $1.39 million and PUBG leader Park Jung-young earning $1.25 million.
- Newer competitive titles show a substantial earnings gap compared to legacy games, with top Overwatch 2 player Choi Tae-min earning $375,450 and Valorant leader Kim Jong-min earning $164,980.