Mobile reports and market data
Documents
The State of Mobile Game Advertising 2021
This report analyzes U.S. mobile game advertising trends from Q1 2018 to Q2 2021, focusing on ad network performance, game genre advertising strategies, and creative trends across iOS and Android platforms.
- Gaming-centric networks including Chartboost, Unity, Adcolony, ironSource, and Vungle maintained over 90% share of voice (SOV) for mobile game advertising on iOS and Android throughout 2021.
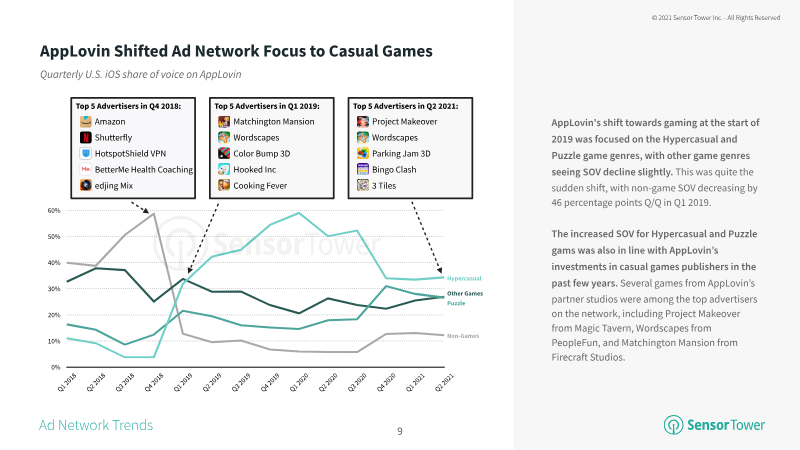
- AppLovin and MoPub aggressively pivoted toward hypercasual publishers, increasing their game SOV to approximately 90% on iOS and 80% on Android by early 2021.
- AdMob increased its focus on Google Play titles, raising its game SOV from 60% to 80% by Q2 2021.


An Analysis of IPs in U.S. Mobile Gaming
This report analyzes the impact of intellectual property (IP) on the U.S. mobile gaming market in 2020, comparing the performance of licensed versus non-IP titles across various genres and identifying top-performing IP types and games.
- Licensed IP titles represent only 9% of the U.S. mobile market but account for 23% of total player spending and 17% of all installs.
- Video game franchises are the primary drivers of IP revenue, contributing one-third of the total, followed by manga (13%), television (12%), and comics (10%).
- Action, shooter, and role-playing games rely most heavily on licensed IP, with these genres deriving 64%, 45%, and 47% of their respective revenues from such titles.


The State of Mobile Gaming: An Analysis of Mobile Gaming Market Trends and Top Titles in the U.S., Europe, and Asia
The mobile gaming market experienced substantial global growth, particularly during the pandemic, with consumer spending reaching an all-time high of over $22 billion in Q1 2021, a 25% year-over-year increase.
- The mobile gaming market is bifurcated between mature markets like the U.S., Japan, and China, which generate the bulk of global revenue, and emerging regions like India and Brazil, which drive the majority of download volume.
- Hyper-casual games are the fastest-growing segment, surging from 757 million installs in Q1 2018 to over 3.4 billion in Q1 2021, representing more than 30% of all mobile downloads.
- Freemium models are the industry standard, accounting for 99% of App Store revenue, while subscription models remain a minority, utilized by only 29% of top U.S. games.
Market Snapshot: Q2 2021 US, China & Japan
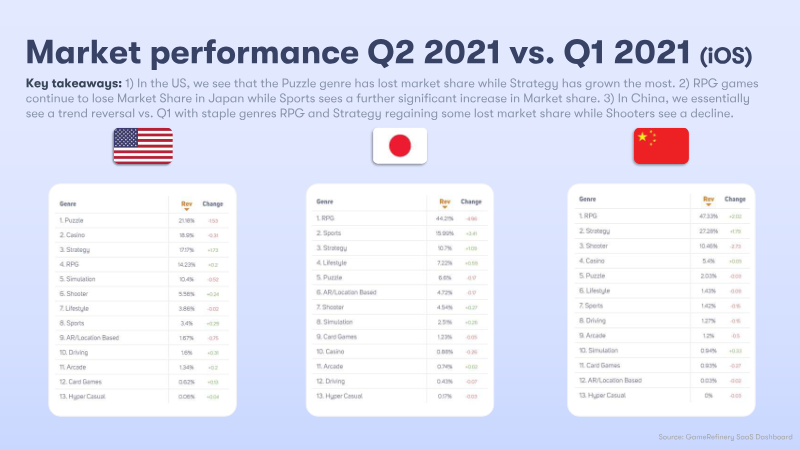
GameRefinery's Q2 2021 snapshot of the mobile games market covers iOS performance in the US, Japan and China, comparing Q2 against Q1 2021.
- Live-service feature updates increased by 37% year-over-year, with Strategy games leading the surge at 208% growth.
- Engagement tactics are shifting toward non-recurring live events and limited-time in-app purchase offers, which saw frequency increases of 143% and 122% respectively.
- In the US, the Strategy genre grew while the Puzzle genre declined, with Supercell emerging as a top-performing publisher.


Mobile Market Forecast: 2021-2025
Sensor Tower's forecast for 2021-2025 projects that global gross consumer spending on mobile apps will rise from $111B in 2020 to $270B by 2025, roughly 2.5x, while downloads grow from 143B to 230B.
- The global mobile application market is projected to reach $270 billion in consumer spending and 230 billion annual downloads by 2025.
- Non-game applications are rapidly gaining market share and are expected to account for nearly 50% of total spending by 2025.
- Non-game revenue is projected to surpass gaming revenue on the Apple App Store as early as 2024.


Store Intelligence Data Digest: Q4 2021
Sensor Tower's Q4 2021 digest assesses worldwide mobile app and game downloads across the App Store and Google Play, with regional breakdowns for the U.S., Europe, and Asia, and with full-year 2021 context.
- Global mobile app downloads reached 144.2 billion in 2021, with Q4 alone contributing 36.1 billion installs, a 2.7% year-over-year increase.
- Meta and Google maintained market dominance as the world’s top publishers, each surpassing 600 million downloads in the fourth quarter.
- Business app installs remained significantly elevated, more than doubling 2019 pre-pandemic levels, while Medical apps also sustained higher-than-normal activity.


Q1 2021: Store Intelligence Data Digest
Sensor Tower's Q1 2021 data digest examines worldwide mobile app and game downloads across the App Store and Google Play, with regional views of Asia, Europe, and the U.S.
- Global mobile app downloads rose 8.7% year-over-year to 36.6 billion in Q1 2021, driven by a 15.3% surge on Google Play that offset an 8.6% decline on the App Store.
- Hypercasual games dominated the U.S. market, accounting for 80% of the top 20 titles, with Join Clash 3D ranking as the most downloaded game globally.
- Finance category downloads in the U.S. and Europe grew by 34%, fueled by retail investing and cryptocurrency platforms like Robinhood, Coinbase, and Binance.


Store Intelligence Data Digest: Q4 2020
Sensor Tower's Q4 2020 digest documents how COVID-19 reshaped global mobile app and game demand, drawing on App Store and Google Play download and revenue data worldwide, in the U.S., and in Europe, with some U.K. and country-level detail.
- The global mobile app ecosystem reached 143 billion total downloads in 2020, a 23.8% year-over-year increase driven largely by pandemic-related shifts in consumer behavior.
- Business app downloads surged by 134% in 2020, highlighted by Zoom and Google Meet reaching 681 million and 331 million annual downloads respectively.
- Mobile gaming revenue exceeded $21 billion in Q4 2020, with social-oriented titles like Among Us driving engagement via 166 million quarterly downloads.


Social Casino Gaming Apps Report 2021
Social casino gaming expanded strongly during the pandemic, but the 2021 Liftoff and GameRefinery analysis argues that growth is coming alongside tougher competition and more demanding marketing economics.
- The social casino market is highly consolidated, with no new titles breaking into the top 200 rankings between August 2020 and August 2021.
- Market entry is increasingly expensive, with average cost-per-install reaching $7.21 and iOS acquisition costs more than double those of Android due to privacy tracking limitations.
- Battle pass mechanics experienced rapid adoption, with market penetration growing from 5% to 36% in a single year.


Gaming Spotlight 2021 Review
Mobile gaming is now the main engine of growth in digital games consumption, and cross-platform play is reshaping how the market competes.
- Mobile gaming is the dominant market force, with 2021 spending projected to be 3.1 times higher than that of home consoles.
- Global game downloads reached over 1 billion per week in Q1 2021, a 30% increase over pre-pandemic levels, while weekly spending grew 40% to $1.7 billion.
- Cross-platform functionality is a critical success factor, as evidenced by the performance of titles like Roblox and Genshin Impact that prioritize cross-play and cross-save features.
Mobile Game Genre Report: Role-Playing Games 2021
Role-playing games were the top-grossing mobile genre worldwide in 2020, generating roughly $18.5Bn, or 22.1% of global mobile game revenue.
- Mobile RPGs generated $18.5 billion in 2020, representing nearly 25% of total mobile gaming revenue.
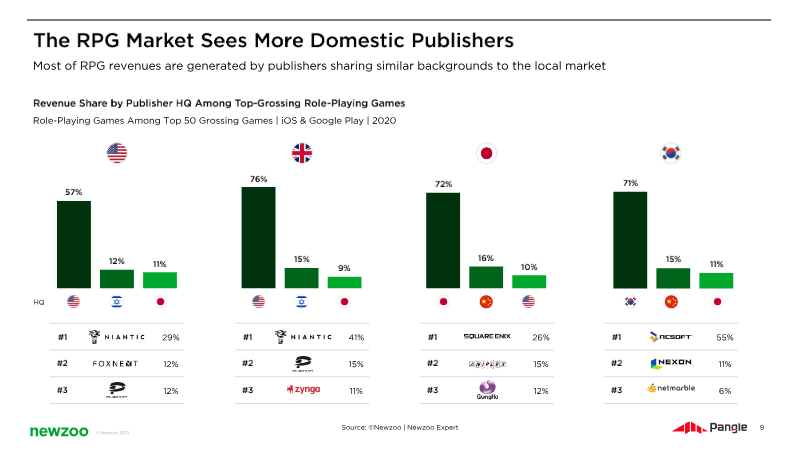
- The market is heavily concentrated in East Asia, with China, Japan, and South Korea accounting for over 70% of global RPG earnings.
- Approximately 50% of top-performing RPG titles rely on established intellectual properties, such as the Marvel franchise, to drive player acquisition and revenue.


Go Global Mobile Game: New Insights
Mobile gaming is settling into healthy growth after the pandemic highs, and Chinese-headquartered publishers are the clearest beneficiaries of that shift.
- China-headquartered publishers captured 23% of overseas mobile gaming consumer spend in H1 2021, achieving $8 billion in revenue and 47% year-over-year growth.
- Developers are increasingly adopting a hybridization strategy, integrating casual mechanics into core genres to broaden audience appeal and improve user engagement.
- The 4X March-Battle subgenre remains the leading driver of consumer spend in major markets like the United States and the United Kingdom.
Writers
Games and companies
Games