Market Analysis
Documents
2022 The Israeli Mobile Game Market Report
The Israeli mobile gaming sector has solidified its position as a premier global hub, characterized by a robust ecosystem of approximately 200 companies and 14,000 employees. Generating $9 billion in annual revenue, the industry has experienced extraordinary growth, with total earnings increasing by 760% since 2016. This expansion, accelerated by pandemic-era shifts in consumer behavior, is anchored by major developers such as Playtika, Plarium, and Moon Active, who maintain a strategic focus on the social, casual, and hyper-casual genres.
Despite this financial success, the advertising landscape underwent significant volatility in 2022. Total ad creatives declined by 17.8% year-over-year, even as the number of active advertisers grew by 4.2%. This contraction was most pronounced within the RPG segment, while casual and puzzle titles maintained dominance. A pivotal shift in platform strategy has emerged, with Android now capturing 70% of all mobile game advertising, a trend largely attributed to Apple’s IDFA privacy changes. Video content remains the industry standard, accounting for over 86% of all creative output.
Global marketing strategies have become increasingly localized to meet regional preferences, ranging from live-action influencer content in the United States to character-centric assets in Japan and high-fidelity technology showcases in South Korea. Furthermore, creative trends are evolving away from traditional failure-based hyper-casual tropes toward more positive, success-oriented gameplay. While the Israeli market continues to demonstrate immense scale and innovation, the industry faces ongoing structural challenges, specifically regarding the availability of venture funding and the persistent shortage of skilled human resources required to sustain long-term growth.
- The Israeli mobile gaming industry has grown by 760% since 2016, reaching $9 billion in annual revenue across a ecosystem of 200 companies and 14,000 employees.
- Android now accounts for 70% of all mobile game advertising, a shift driven by Apple’s IDFA privacy changes.
- Despite a 4.2% increase in the number of active advertisers, total ad creative volume declined by 17.8% in 2022, with the sharpest contraction occurring in the RPG segment.
- Video content remains the dominant advertising format, representing over 86% of all creative output in the industry.
- Major developers like Playtika, Plarium, and Moon Active continue to anchor the market by focusing on social, casual, and hyper-casual genres.
The State of Mobile Game and App Markets: H1 2022
The mobile app and gaming landscape underwent a significant strategic pivot during the first half of 2022, characterized by a transition from high-volume advertising to a quality-focused, data-driven methodology. Faced with rising user acquisition costs and the restrictive post-ATT environment, marketers reduced the total volume of mobile game creatives by nearly 30% year-over-year. This contraction reflects a broader industry shift toward precise traffic optimization, where performance metrics like Cost Per Purchase and In-App Purchase Return on Ad Spend have superseded raw install volume as the primary indicators of success.
Geographically, the United States remains the dominant market, commanding the highest share of traffic and the most expensive advertising costs. CPMs surged significantly during this period, rising 18% for mobile games and 64% for non-gaming applications. In response to these economic headwinds and privacy-related tracking limitations, advertisers have increasingly pivoted toward the Android ecosystem, which now hosts approximately 70% of mobile game creatives. Simultaneously, growth is being sought in emerging Tier-2 and Tier-3 markets to offset the saturation and high costs found in traditional Western strongholds.
To maintain performance, publishers are diversifying their acquisition channels, moving beyond traditional social media giants to include incentive-based traffic sources and search-driven discovery. App Store Optimization and Apple Search Ads have become critical components of visibility strategies, while the adoption of predictive analytics and first-party data collection allows developers to navigate the loss of IDFA-based targeting. By prioritizing user-generated content styles and optimizing opt-in prompts, which have reached success rates as high as 51% in certain hyper-casual segments, the industry is successfully recalibrating its approach to sustain long-term growth despite a challenging macroeconomic climate.
- Marketers reduced mobile game creative volume by nearly 30% year-over-year in H1 2022, shifting focus from raw install volume to performance metrics like Cost Per Purchase and In-App Purchase Return on Ad Spend.
- Advertising costs rose significantly, with CPMs increasing 18% for mobile games and 64% for non-gaming applications.
- Advertisers are increasingly prioritizing the Android ecosystem, which now accounts for approximately 70% of all mobile game creatives.
- To mitigate high costs and market saturation in the U.S., publishers are expanding into emerging Tier-2 and Tier-3 geographic markets.
- Publishers are diversifying beyond traditional social media channels, placing greater strategic emphasis on App Store Optimization, Apple Search Ads, and search-driven discovery.
Global Esports & Live Streaming Market Report 2022
The global esports and live streaming industry is undergoing a period of robust expansion, with total esports revenue projected to reach $1.38 billion in 2022 and an audience base of 532 million people. This growth trajectory is expected to continue, with market valuations potentially hitting $1.86 billion by 2025. While sponsorship remains the dominant revenue stream, accounting for nearly 60 percent of total earnings, the industry is actively diversifying its financial models. Organizations are increasingly pivoting toward direct-to-fan strategies, including digital merchandise, loyalty programs, and educational initiatives, to mitigate risk and transition toward sustainable, lifestyle-oriented business models.
The live streaming sector serves as a critical pillar of this ecosystem, with its audience projected to grow to 1.41 billion by 2025. Market dominance is currently split between major platforms like Twitch, YouTube Gaming, and Facebook Gaming, each leveraging distinct regional strengths. Twitch maintains a stronghold in Western PC and console markets, whereas YouTube and Facebook are capitalizing on the rapid proliferation of mobile gaming in emerging economies. These platforms are further evolving by integrating non-gaming content and interactive features to enhance user retention and broaden monetization opportunities.
Despite the positive outlook, the industry must navigate potential volatility stemming from shifting media consumption habits, evolving publisher investment strategies, and the lingering economic effects of the pandemic. Nevertheless, the sector remains highly attractive to stakeholders due to its core demographic of young, high-income professionals. As the market matures, the integration of co-streaming and the expansion into emerging regions—supported by localized platforms—will be essential for maintaining long-term growth and fostering deeper engagement with a global, digitally native audience.
- Global esports revenue is projected to reach $1.38 billion in 2022, with a total audience of 532 million, and is expected to grow to $1.86 billion by 2025.
- Sponsorship currently accounts for nearly 60% of total esports revenue, though organizations are shifting toward direct-to-fan models like digital merchandise and loyalty programs to improve financial sustainability.
- The live streaming audience is forecast to reach 1.41 billion by 2025, driven by the integration of non-gaming content and interactive features to boost user retention.
- Market dominance in live streaming is split between Twitch, which leads in Western PC and console markets, and YouTube Gaming and Facebook Gaming, which are capturing growth in mobile-first emerging economies.
- The industry remains highly attractive to stakeholders due to its core demographic of young, high-income professionals.
Consumer Insights: Games and Esports 2022
The Consumer Insights: Games and Esports 2022 report provides a comprehensive analysis of global gaming behaviors, motivations, and market engagement. The primary purpose of the research is to equip game developers, publishers, and industry stakeholders with actionable data to benchmark titles, understand player demographics, and identify growth opportunities across 36 diverse international markets. By examining over 100 key performance indicators, the analysis offers a granular view of how players interact with PC, console, and mobile platforms.
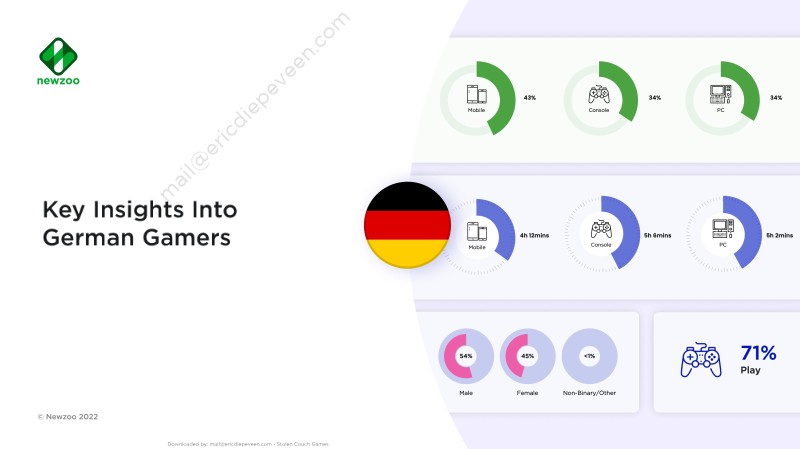
The research is underpinned by a robust methodology, drawing on survey data from over 75,000 consumers worldwide. The findings highlight distinct engagement patterns, such as the prevalence of specific gaming personas—notably Time Fillers and Mainstream Gamers—and the interplay between playing and viewing habits. For instance, data from the German market indicates that while playing remains the dominant activity, a significant portion of the population also engages with gaming video content and esports. Furthermore, the report identifies key drivers for consumer spending, noting that price sensitivity, the desire for exclusive content, and social connectivity are primary motivators for financial investment in games.
Covering a broad geographic scope that includes North America, Europe, Latin America, the Middle East, and the Asia-Pacific region, the report serves as a strategic tool for navigating the complex global gaming landscape. By synthesizing metrics such as monthly active users, daily active users, and lifetime player value, the analysis facilitates a deeper understanding of the motivations driving player behavior. Ultimately, the findings emphasize that a nuanced approach to audience segmentation and platform-specific engagement is essential for companies seeking to reach and retain diverse gaming populations in an increasingly competitive entertainment market.
- The research is based on a global dataset of over 75,000 consumers across 36 international markets, covering North America, Europe, Latin America, the Middle East, and the Asia-Pacific region.
- Consumer spending is primarily driven by three factors: price sensitivity, the desire for exclusive content, and the need for social connectivity.
- Gaming engagement is categorized into distinct personas, with 'Time Fillers' and 'Mainstream Gamers' identified as the most prevalent segments.
- Player behavior analysis utilizes over 100 key performance indicators, including monthly active users (MAU), daily active users (DAU), and lifetime player value (LPV).
- Engagement patterns in markets like Germany demonstrate that gaming video content and esports are significant activities that complement traditional gameplay.
Games, Esports, Live Streaming, Cloud and the Metaverse: 2022 Trends to Watch
The global gaming industry is currently undergoing a structural transformation characterized by the integration of emerging technologies and a pivot toward cross-platform accessibility. Central to this evolution is the expansion of cloud gaming, which serves as a critical bridge to overcome hardware constraints, allowing publishers to reach broader audiences on mobile devices and legacy consoles. Simultaneously, the metaverse is maturing into a robust commercial ecosystem, fueled by significant venture capital investment, the proliferation of virtual real estate, and the integration of digital fashion. These developments signal a broader industry shift toward enhanced creator-viewer interactivity and the adoption of Web3.0 business models.
Monetization strategies are diversifying as companies experiment with blockchain-based player trading and fan engagement tools, despite notable consumer resistance toward non-fungible tokens. This period is also defined by a surge in high-quality cross-media intellectual property adaptations and a crowded release calendar, which intensifies competition for consumer attention. Furthermore, regulatory and consumer pressures are forcing a transition toward more open app store ecosystems, challenging traditional distribution gatekeepers.
Within the esports sector, organizations are actively diversifying revenue streams by prioritizing mobile-first titles and leveraging co-streaming to maximize viewership reach. These trends, observed throughout 2022, reflect a strategic effort to sustain growth across global markets. By synthesizing market intelligence and tracking key performance metrics, the industry continues to navigate the complexities of digital transformation, balancing the pursuit of innovative monetization with the necessity of maintaining user trust in an increasingly interconnected virtual landscape.
- Cloud gaming is driving industry growth by bypassing hardware limitations, enabling publishers to deliver high-end experiences to mobile devices and legacy consoles.
- The metaverse is evolving into a commercial ecosystem supported by significant venture capital, virtual real estate markets, and digital fashion integration.
- Monetization models are shifting toward Web3.0 and blockchain-based player trading, despite ongoing consumer resistance to non-fungible tokens.
- Regulatory and consumer pressure is forcing a transition away from traditional app store gatekeepers toward more open distribution ecosystems.
- Esports organizations are prioritizing mobile-first titles and utilizing co-streaming strategies to diversify revenue and expand global viewership.
2022 Global White Paper on Mobile Advertising & Marketing
The 2022 global mobile gaming landscape underwent a significant transition toward quality and strategic refinement, characterized by a 2% decline in total advertisers and a 27.83% reduction in ad creatives during the first half of the year. This contraction in mature markets was offset by robust growth in emerging regions such as the Middle East, South America, and South Asia, where increasing smartphone penetration and young demographics present substantial expansion opportunities. The industry’s primary thesis centers on the necessity of localized, narrative-driven content and creative optimization to navigate a post-IDFA privacy environment that has increased advertising costs and shifted focus toward Android platforms.
While casual, puzzle, and simulation genres dominate download volumes, RPGs and strategy titles remain the primary revenue drivers, commanding the highest advertising costs with average CPMs reaching $21.58. Video remains the dominant creative format, accounting for over 86% of all advertisements, as marketers increasingly leverage dramatic storytelling and influencer-led content to boost engagement. Despite the industry’s fascination with emerging technologies, consumer sentiment remains grounded; only 16% of players express interest in NFT-based gaming, whereas up to 39% show interest in metaverse-integrated experiences. Most users continue to prioritize mobile games as accessible tools for relaxation and time-killing.
To sustain growth, publishers are pivoting toward programmatic channels, OEM integrations, and culturally relevant marketing strategies. Success in this competitive landscape requires a dual approach: maintaining high-frequency engagement through playable and video-based ads while simultaneously adapting to regional preferences, such as the demand for vernacular content in India or MOBA-focused titles in Southeast Asia. Ultimately, the market is moving away from broad-spectrum advertising toward highly targeted, immersive, and quality-focused campaigns that align with the core motivations of diverse global player bases.
- The mobile gaming market is shifting toward quality over volume, evidenced by a 2% decline in total advertisers and a 27.83% reduction in ad creatives during the first half of 2022.
- RPG and strategy titles remain the primary revenue drivers, commanding the highest advertising costs with average CPMs reaching $21.58.
- Video is the dominant advertising format, accounting for over 86% of all ad creatives as marketers prioritize dramatic storytelling and influencer-led content.
- Growth in mature markets is slowing, forcing publishers to expand into emerging regions like the Middle East, South America, and South Asia to capitalize on rising smartphone penetration.
- Consumer interest in gaming technology is polarized, with only 16% of players interested in NFTs compared to 39% expressing interest in metaverse-integrated experiences.
Data for Mobile Gaming 2022-2024
Mobile gaming maintains its position as the primary driver of industry expansion, fueled by widespread smartphone adoption and consistent engagement across both emerging and established markets. Between 2022 and 2024, the sector has demonstrated a clear trend where revenue growth consistently outpaces download volume on both iOS and Android platforms. This financial trajectory is increasingly supported by a strategic shift toward in-game advertising, which is currently outpacing traditional in-app purchases as a primary revenue stream.
Global market dynamics remain anchored by the United States, China, and Japan, which continue to serve as the most significant revenue generators. However, emerging markets are playing an increasingly critical role in the industry’s growth, particularly in regions like Brazil, where smartphone gaming penetration has surpassed 90% across all demographics. In these regions, player behavior is heavily influenced by free-to-play accessibility, narrative depth, and social recommendations. Furthermore, data from the U.S. and U.K. confirms that younger demographics prioritize smartphones over consoles and PCs, solidifying the mobile device as the central hub for modern gaming.
Despite the proliferation of available titles, the global player base exhibits a preference for focused engagement, with many users choosing to dedicate their time to a single game rather than managing multiple titles simultaneously. While market concentration among top-tier publishers remains stable, the rapid expansion of the advertising sector suggests a fundamental change in how developers monetize their audiences. Ultimately, the industry is transitioning toward a model that prioritizes long-term retention and diversified revenue streams over simple volume-based growth, ensuring that mobile gaming remains the most influential segment of the broader interactive entertainment landscape.
- Mobile gaming revenue growth is consistently outpacing download volume across iOS and Android platforms between 2022 and 2024.
- In-game advertising has overtaken traditional in-app purchases as the primary revenue stream for mobile developers.
- The United States, China, and Japan remain the dominant global revenue generators, while Brazil has reached over 90% smartphone gaming penetration across all demographics.
- Younger demographics in the U.S. and U.K. are increasingly prioritizing smartphones over consoles and PCs as their primary gaming platform.
- Player behavior is shifting toward focused engagement, with users increasingly dedicating their time to a single title rather than managing multiple games.
State of the Game Industry Report: 2022
The global game development landscape in 2022 reflects a period of significant structural and cultural transition. PC remains the primary development platform, while the PlayStation 5 maintains its position as the leading console choice. Conversely, mobile development has experienced a decade-long decline in developer interest. Emerging hardware like the Steam Deck and PlayStation VR2 continues to capture attention, yet the industry remains deeply skeptical of speculative technologies such as the metaverse, cryptocurrency, and NFTs. These concerns are rooted in anxieties regarding environmental sustainability, ethical business practices, and the long-term viability of blockchain-based models.
Workplace culture and labor dynamics have emerged as central themes, marked by a measurable improvement in work-life balance as 60 percent of developers now maintain a 40-hour work week or less. Despite this progress, the industry struggles with systemic issues, as a majority of studios have failed to adequately address internal reports of misconduct and toxicity. This environment has fueled a growing movement toward collective bargaining, with 55 percent of developers supporting unionization and nearly one-quarter of workplaces engaging in active discussions regarding labor organization.
The industry continues to prioritize accessibility, with a record 39 percent of developers integrating inclusive design features into their projects. However, broader efforts toward diversity and social activism remain inconsistent across various studios. Furthermore, the workforce remains predominantly male and early-career, highlighting a demographic imbalance that persists alongside ongoing tensions between developers and major platform holders. As evidenced by the 34 percent of developers who support Epic Games in its legal conflict with Apple, there is a clear desire for greater autonomy and a shift in the power dynamics that currently govern the digital distribution ecosystem.
- Labor organization is gaining significant momentum, with 55 percent of developers supporting unionization and nearly 25 percent of workplaces actively discussing collective bargaining.
- Work-life balance has improved, as 60 percent of developers now report working 40 hours per week or less.
- Despite progress in working hours, a majority of studios have failed to effectively address internal reports of workplace toxicity and misconduct.
- Developers are increasingly seeking autonomy from platform holders, evidenced by 34 percent of the industry supporting Epic Games in its legal battle against Apple.
- Accessibility is a growing priority, with 39 percent of developers incorporating inclusive design features into their projects.
Games, Esports, Live Streaming, Cloud and the Metaverse: 2022
The global gaming industry is undergoing a fundamental transformation characterized by the convergence of traditional media, high-fidelity content, and emerging Web3 technologies. The primary thesis posits that the sector is shifting toward an interconnected, cross-platform ecosystem where revenue diversification and creator-driven engagement models are essential for growth. While consumer skepticism persists regarding blockchain-based assets and NFTs, publishers are successfully navigating this transition by prioritizing mobile esports, co-streaming strategies, and efforts to circumvent restrictive app store ecosystems to foster deeper fan loyalty.
Technological infrastructure is evolving to support this expansion, with cloud-based solutions and Platform-as-a-Service models playing a critical role in mitigating hardware limitations. By integrating gaming experiences into smart TVs and leveraging cloud technology, companies are effectively broadening their reach to new demographics. Simultaneously, the metaverse has emerged as a significant focal point for venture capital and brand investment, as corporations increasingly utilize digital fashion and virtual real estate to capture the attention of younger, digitally native audiences.
Geographically, the market remains dominated by the Asia-Pacific region, which generates $88.2 billion in annual revenue, representing over half of the global total. North America follows with $42.6 billion, maintaining a strong position in the industry landscape. However, the long-term trajectory of the market is increasingly influenced by emerging territories in Latin America, the Middle East, and Africa. These regions are currently expanding at rates exceeding the global average, signaling a gradual decentralization of revenue and a more diverse, globalized future for the interactive entertainment sector.
- The Asia-Pacific region dominates the global gaming market with $88.2 billion in annual revenue, accounting for more than 50% of the total global share.
- North America remains a primary industry pillar, generating $42.6 billion in annual revenue.
- Emerging markets in Latin America, the Middle East, and Africa are currently experiencing growth rates that exceed the global average, signaling a shift toward market decentralization.
- Publishers are prioritizing mobile esports, co-streaming, and direct-to-consumer strategies to bypass restrictive app store ecosystems and increase fan loyalty.
- Cloud-based infrastructure and Platform-as-a-Service models are being used to overcome hardware limitations and expand reach through smart TV integration.
Gaming Deals Activity Report: H1 2022
The global gaming industry reached a record-breaking $113.6 billion in total deal value during the first half of 2022. This surge in valuation, driven primarily by a select group of high-profile mega-deals, occurred despite a broader contraction in the total volume of transactions. While public markets experienced a significant downturn resulting from macroeconomic instability and post-pandemic corrections, private investment remained resilient, contributing $4.6 billion to the sector. This activity underscores a strategic shift toward mobile-focused acquisitions and a maturation of the blockchain gaming space, which is currently pivoting away from speculative models toward more sustainable, content-driven development.
The scope of this analysis encompasses global closed and announced transactions across the gaming industry, excluding pure gambling and non-gaming blockchain entities. Within this landscape, the data reveals a persistent structural challenge regarding corporate governance and inclusivity, as 88% of company founders are identified as men. This lack of gender diversity remains a notable trend within the leadership ranks of the organizations securing capital.
Ultimately, the industry is navigating a period of transition characterized by a flight to quality and a focus on long-term project viability. Although the frequency of deals has declined compared to previous periods, the concentration of capital into large-scale acquisitions and strategic private investments suggests that institutional confidence in gaming remains high. The sector is effectively recalibrating, moving past the rapid expansion of the pandemic era toward a more disciplined investment environment that prioritizes established mobile platforms and robust, sustainable gaming ecosystems.
- The global gaming industry reached a record-breaking $113.6 billion in total deal value during the first half of 2022, driven by high-profile mega-deals despite a decline in overall transaction volume.
- Private investment remained resilient during H1 2022, contributing $4.6 billion to the sector despite broader public market downturns and macroeconomic instability.
- Investment strategies are shifting toward mobile-focused acquisitions and a maturation of the blockchain gaming sector, which is moving away from speculative models toward content-driven development.
- The industry is experiencing a 'flight to quality' as investors prioritize long-term project viability and sustainable ecosystems over the rapid, pandemic-era expansion.
- Corporate governance data reveals a significant lack of gender diversity, with 88% of company founders in the sector identified as men.
The Hyper-Casual Benchmark Report: Q3 2022
The hyper-casual mobile gaming sector experienced a notable escalation in acquisition costs during the latter half of 2022, characterized by rising median cost-per-install (CPI) rates across both Android and iOS platforms. By the fourth quarter of 2022, median CPI reached all-time highs of $0.20 on Android and $0.42 on iOS. This upward trend in acquisition spending was global, as no major market tracked by ad spend experienced a decrease in median CPI on Android, while iOS markets saw varied fluctuations, including a significant decrease in the United States and notable increases in France and Germany.
Retention metrics reveal a consistent performance advantage for iOS over Android across all tiers of game quality. For the top 2% of hyper-casual titles, iOS achieved a 45% Day 1 retention rate compared to 38% on Android, with Day 7 retention figures similarly favoring iOS at 19% versus 14%. This performance gap persists among the top 25% of games and the median cohort, where iOS maintains a higher percentage of returning players. These findings underscore a widening disparity between high-performing titles and average games, emphasizing the critical importance of engagement optimization in a landscape of increasing user acquisition costs.
The analysis draws upon data from over 100,000 games and one-third of the global mobile player base to establish these benchmarks. By segmenting performance by platform and geographic region, the data highlights the shifting economic landscape for developers and publishers. The findings suggest that while market saturation and rising costs present significant challenges, the ability to maintain player retention remains the primary differentiator between top-tier hyper-casual games and the broader market.
- Retention is the primary differentiator for success, with top-tier hyper-casual games significantly outperforming the median cohort as acquisition costs rise.
- Median cost-per-install (CPI) reached record highs in Q4 2022, hitting $0.20 on Android and $0.42 on iOS.
- iOS consistently outperforms Android in retention, with top-tier titles achieving 45% Day 1 retention on iOS compared to 38% on Android.
- Day 7 retention metrics show a persistent gap between platforms, with top-tier iOS titles retaining 19% of players versus 14% on Android.
- Rising acquisition costs are a global trend, as no major Android market tracked in the report experienced a decrease in median CPI during the period.

The State of Mobile Gaming: Market Trends and Top Titles in the U.S., Europe, and Asia 2022
The analysis demonstrates that the global mobile‑gaming market entered a contraction phase in early 2022, with revenue falling 6 % year‑over‑year and the first decline since 2019. The United States and Japan, historically dominant markets, experienced double‑digit drops in consumer spending—particularly a 22 % decline on Google Play in the U.S.—while emerging APAC regions such as India, Brazil, and Vietnam captured growing market share. Download volumes remained steady at roughly 14 billion worldwide; India retained the largest install base but is losing ground to Brazil, which is poised to overtake it.
Regional dynamics reveal divergent trends. Europe’s spending rose 18 % to $8.6 B, driven largely by hyper‑casual titles and rapid growth in Turkey (6 % YoY) and Poland (8 % YoY). In contrast, Asia’s revenue fell 7 % to $11.2 B, with China and Japan maintaining top positions but India’s spending accelerating despite lower monetisation rates. Genre‑level data shows a decline across the five largest categories, yet strategy games remain the strongest, generating over $4 B quarterly since late 2020. Hyper‑casual installs surged to 3.5 billion, accounting for 32.5 % of all downloads, while puzzle and arcade titles saw double‑digit revenue drops.
Monetisation strategies continue to evolve. Gacha mechanics dominate the mid‑core segment, often combined with season passes, subscriptions, or live‑ops to boost spend. Season passes have proven effective beyond shooters, doubling weekly revenue for titles such as Lords Mobile and revitalising legacy games like Hay Day. The data underscores the necessity of flexible, hybrid monetisation models—particularly in markets where overall genre revenues are contracting—to sustain profitability across diverse player bases.
- The global mobile gaming market experienced its first revenue decline since 2019, contracting 6% year-over-year in early 2022.
- Consumer spending in the U.S. and Japan saw double-digit drops, including a 22% decline on Google Play in the U.S., while emerging markets like Brazil and Vietnam gained significant share.
- Europe bucked the global trend with an 18% revenue increase to $8.6 billion, fueled by growth in Turkey and Poland and the popularity of hyper-casual titles.
- Hyper-casual games accounted for 32.5% of all global downloads, reaching 3.5 billion installs, while strategy games remained the highest-earning category with over $4 billion in quarterly revenue.
- Hybrid monetisation models are essential for profitability, as evidenced by the success of season passes in revitalizing legacy titles like Hay Day and boosting revenue for Lords Mobile.