Koei Tecmo
Game Co.173 documents
Japanese developer/publisher. Dynasty Warriors, Nioh, Dead or Alive, Atelier, Romance of the Three Kingdoms.
Documents

Financial7 pages
Consolidated Financial Results: FY2026 1st Quarter
The fiscal year 2026 first-quarter financial results for Koei Tecmo indicate a period of steady performance within the global interactive entertainment industry. The company reported quarterly sales of 17.37 billion yen, with operating profit reaching 5.41 billion yen. This performance reflects a profit margin of 31%, supported by a robust portfolio of console, PC, and mobile gaming assets. The entertainment segment remains the primary revenue driver, contributing 15.93 billion yen to the quarterly total, while amusement and real estate segments provide supplementary income.
Geographically, the company maintains a diversified revenue stream with a significant international presence. Overseas sales accounted for 42.5% of total revenue during the first quarter, with North America, Europe, and Asia collectively contributing to a balanced global footprint. The company’s strategic focus on digital distribution remains a core component of its business model, as evidenced by a 67.3% digital sales ratio for console and PC units during the quarter.
Operational data highlights a consistent investment in human capital, with the consolidated headcount reaching 3,015 employees. The company continues to leverage its established intellectual property, including major series such as Nobunaga’s Ambition, Dynasty Warriors, and the Atelier franchise. Future growth is supported by a pipeline of upcoming titles scheduled for release through early 2027, spanning multiple platforms including PlayStation 5, Xbox Series X|S, and next-generation Nintendo hardware. These results demonstrate a stable financial trajectory, characterized by disciplined cost management and a continued reliance on both in-house development and strategic IP licensing to sustain long-term market competitiveness.
- Koei Tecmo reported 17.37 billion yen in quarterly sales and 5.41 billion yen in operating profit, achieving a 31% profit margin for Q1 FY2026.
- The entertainment segment generated 15.93 billion yen, serving as the primary revenue driver alongside supplementary income from amusement and real estate.
- Digital distribution remains a critical revenue channel, accounting for 67.3% of total console and PC unit sales during the quarter.
- International markets are a major component of the business, with overseas sales representing 42.5% of total revenue across North America, Europe, and Asia.
- The company maintains a workforce of 3,015 employees and continues to prioritize its core intellectual property, including the Nobunaga’s Ambition, Dynasty Warriors, and Atelier franchises.
+1
Koei Tecmo
Financial9 pages
FY2025 Annual Data Appendix
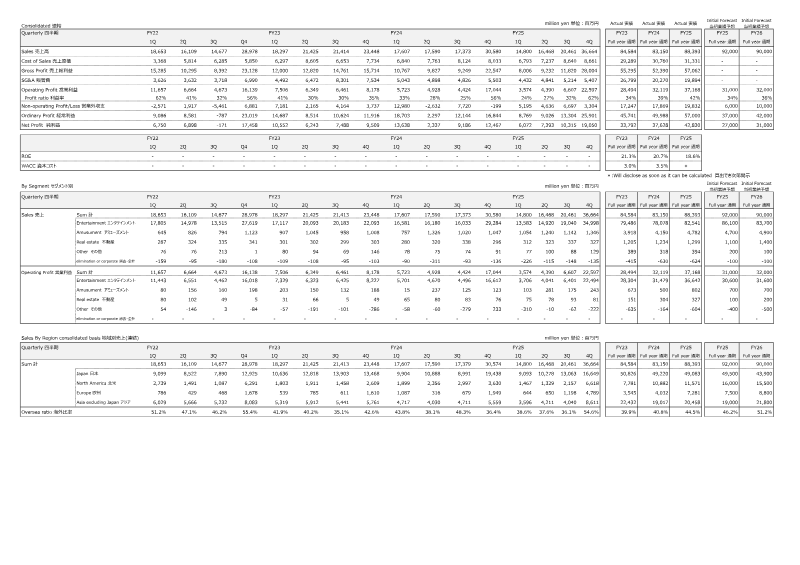
The FY2025 Annual Data Appendix presents a comprehensive financial and operational overview for the company’s entertainment, amusement, real‑estate, and other segments across FY22–FY26. Revenue trends show a decline in FY22 (¥18,653m) to a rebound in FY25 (¥36,664m), driven largely by the entertainment segment, which accounts for roughly 90 % of total sales. Gross profit margins fluctuate from 32 % in FY22 to a peak of 56 % in FY25, reflecting cost‑control efforts and higher digital sales. Operating profit follows a similar pattern, rising from ¥4,424m in FY22 to ¥32,119m in FY25, with a profit ratio stabilizing around 30–35 % after an initial dip. Net profit improves markedly, reaching ¥42,830m in FY25 from a loss of ¥171m in FY24. Return on equity climbs to 21.3 % by FY25, while the weighted average cost of capital is projected at 3.0–3.5 %.
Geographically, Japan remains the largest market (≈50 % of sales), but overseas revenue grows from 47 % in FY22 to 55 % by FY25, driven by North America and Europe. Digital sales dominate the entertainment portfolio, with a digital ratio exceeding 80 % in FY25 and a consistent increase in online/mobile units. Headcount expands modestly from 2,413 employees at FY22 Q1 to 2,835 by FY25 year‑end. Capital expenditures focus on real‑estate and equipment, totaling ¥24,555m in FY25, while depreciation costs rise to ¥1,999m. The appendix also lists major titles and upcoming releases across console/PC and online/mobile platforms, highlighting strategic IPs such as “Nobunaga’s Ambition,” “Dynasty Warriors,” and “Dead or Alive.” Overall, the data indicate a recovering profitability trajectory supported by digital expansion and strategic title releases.
- Revenue grew significantly from ¥18,653m in FY22 to ¥36,664m in FY25, with the entertainment segment contributing approximately 90% of total sales.
- Net profit reached ¥42,830m in FY25, marking a substantial recovery from the ¥171m loss recorded in FY24.
- Gross profit margins peaked at 56% in FY25, up from 32% in FY22, driven by effective cost-control measures and an increased mix of digital sales.
- Digital sales now account for over 80% of the entertainment portfolio, reflecting a strategic shift toward online and mobile platforms.
- Overseas revenue has surpassed domestic sales, growing from 47% in FY22 to 55% in FY25, with primary growth driven by North American and European markets.
Koei Tecmo
Financial24 pages
1st Half Financial Results: FY 2011
The first‑half financial results for the fiscal year ending March 2011 show a sharp decline in revenue and profitability compared with the same period in 2009. Net sales fell from ¥15,264 million to ¥11,069 million, a 27.5 % drop, while operating loss widened from ¥641 million to ¥1,656 million. Ordinary profit and net income also deteriorated, with ordinary loss increasing from ¥349 million to ¥1,097 million and net loss rising from ¥415 million to ¥571 million. The decline is largely attributed to a one‑time goodwill amortization expense of approximately ¥510 million incurred after the merger with Koei and acquisition of Koei Net Co., Ltd. The company’s operating segments reflected uneven performance: Game sales dropped by 16 % to ¥6,330 million, while Online and Media segments saw modest gains. Regional sales remained concentrated in Japan (85.5 %) with overseas sales accounting for 14.5 % of total revenue.
The consolidated plan for FY 2010 projects a modest 0.0 % change in total sales to ¥34,500 million, with operating profit expected to rise from a loss of ¥641 million in FY 2009 to a gain of ¥4,000 million. Ordinary profit and net income are projected to improve by 13.0 % and 7.8 %, respectively, largely driven by a projected operating profit of ¥4,000 million in the Game segment. The plan also outlines significant capital expenditures (¥1,685 million) and a shift in marketing focus toward overseas markets and social gaming.
Methodologically, the report relies on consolidated financial statements for the first half of FY 2010 and comparative figures from FY 2009, with adjustments noted for goodwill amortization. The document also includes strategic initiatives such as the launch of social games based on popular IPs, expansion into mobile and PC platforms, and the establishment of a Global Marketing Department to strengthen overseas presence.
- H1 FY2011 net sales fell 27.5% to ¥11,069 million, while operating losses widened significantly from ¥641 million to ¥1,656 million compared to the same period in 2009.
- The financial decline was primarily driven by a one-time goodwill amortization expense of ¥510 million resulting from the merger with Koei and the acquisition of Koei Net Co., Ltd.
- Game segment revenue dropped 16% to ¥6,330 million, though this was partially offset by modest growth in the Online and Media segments.
- The company remains heavily dependent on the Japanese market, which accounts for 85.5% of total revenue, leaving only 14.5% generated overseas.
- Management projects a turnaround for FY2010, targeting an operating profit of ¥4,000 million driven by the Game segment, despite a flat 0.0% growth projection for total sales.
+2
Koei Tecmo
Report1 pages
Financial Highlights: 1st Quarter of Fiscal Year Ending March 2011
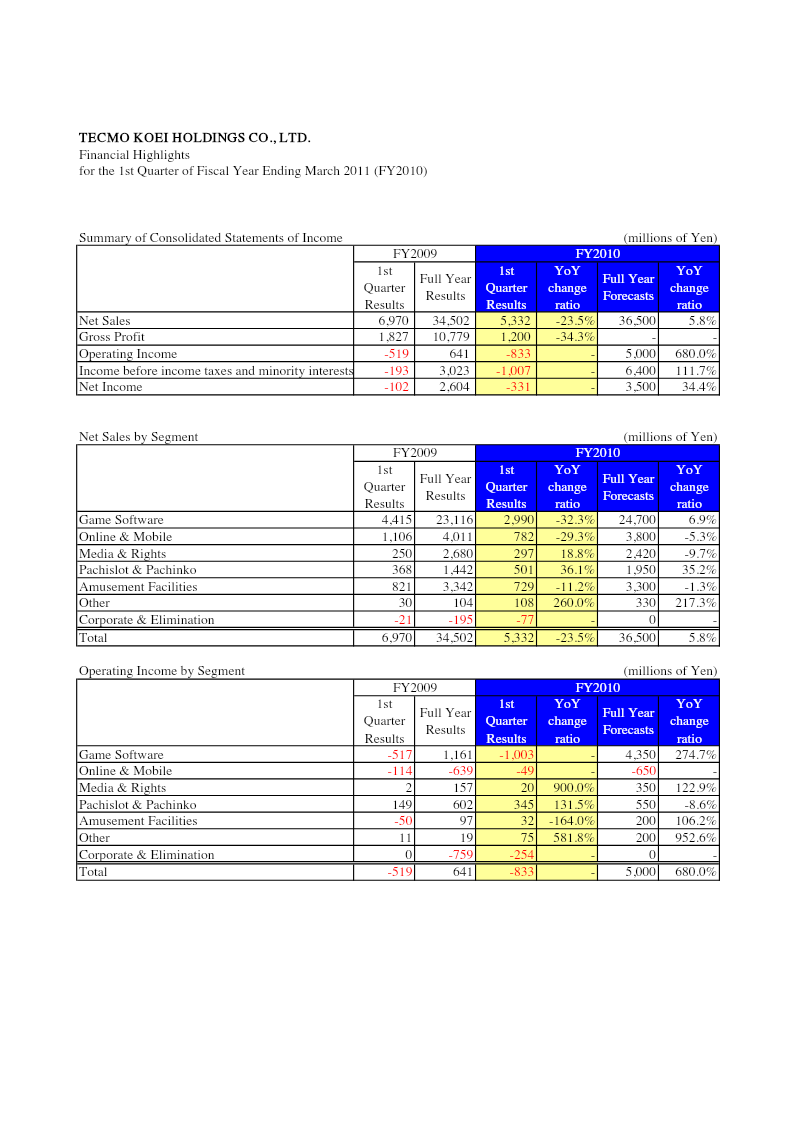
The financial highlights for the first quarter of fiscal year ending March 2011 reveal a mixed performance across Tecmo Koei Holdings’ operating segments. Net sales fell 23.5 % year‑over‑year to ¥34,502 million, driven mainly by declines in game software sales (−32.3 %) and online & mobile revenue (−29.3 %). In contrast, pachislot & pachinko sales rose 36.1 % to ¥1,442 million, while media & rights and amusement facilities experienced modest growth of 18.8 % and −11.2 %, respectively. The “Other” segment saw a sharp increase of 260 % to ¥104 million, though its absolute contribution remained small.
Operating income swung from a loss of ¥519 million in the same quarter of FY2009 to a profit of ¥641 million, an improvement of 1,160 million yen. This turnaround was largely attributable to game software operating income rising from a loss of ¥517 million to a profit of ¥1,161 million. Online & mobile income improved from a loss of ¥114 million to a profit of ¥639 million, while media & rights and pachislot & pachinko also posted gains. The “Other” segment’s operating income increased markedly, though its impact on total profitability was limited by the overall scale.
Net income shifted from a loss of ¥102 million to a profit of ¥2,604 million, reflecting the combined effect of stronger operating results and favorable tax treatment. Forecasts for the full year project net sales growth to 5.8 % and operating income to 680 %, indicating management’s expectation of a rebound in game software sales and continued strength in pachislot & pachinko. The analysis covers all business units within the company, with data expressed in millions of yen for FY2009 and FY2010, and includes year‑over‑year comparisons and forecasted full‑year figures.
- Tecmo Koei Holdings achieved a significant financial turnaround in Q1 FY2011, shifting from a ¥102 million net loss in the prior year to a ¥2,604 million profit.
- Operating income improved by ¥1,160 million year-over-year, moving from a ¥519 million loss to a ¥641 million profit, driven primarily by the game software and online & mobile segments.
- Total net sales for the quarter declined 23.5% year-over-year to ¥34,502 million, largely due to a 32.3% drop in game software sales and a 29.3% decrease in online & mobile revenue.
- The pachislot & pachinko segment bucked the downward trend in sales, recording a 36.1% increase to ¥1,442 million.
- Management projects a strong full-year recovery, forecasting 5.8% growth in net sales and a 680% increase in operating income.
Koei Tecmo
Financial34 pages
Financial Results: Fiscal Year Ended March 2011
FY 2009 FY 2010 YoY Change Amount Ratio Amount Ratio Amount Ratio Sales 34,502 100.0% 32,081 100.0% (2,421) (7.0%) Operating 641 1.9% 3,305 10.3% 2,664 415.5% This document contains statements regarding future objectives, beliefs and current expectations of Ordinary 3,023 8.8% 4,788 14.9% 1,765 58.4% Net Income 2,604...
- Despite a 7.0% decrease in sales to ¥32,081 million in FY 2010, the company achieved a significant 415.5% increase in operating profit to ¥3,305 million, and a 58.4% increase in ordinary profit to ¥4,788 million, alongside a 5.3% rise in net income to ¥2,741 million.
- The company projects strong growth for FY 2011, planning a 9.1% increase in sales to ¥35,000 million, a 51.3% increase in operating profit to ¥5,000 million, and a 31.3% increase in net income to ¥3,600 million.
- Game Software remains the largest segment, contributing ¥21,594 million in sales and ¥2,336 million in operating profit in FY 2010, though its sales decreased from ¥23,116 million in FY 2009.
- Overseas sales units grew by 12.5% in FY 2010, with North America increasing by 10.7% and Europe by 41.4%, while Japan's sales units decreased by 7.7%.
- The company plans to double growth in the social gaming sector by leveraging well-known IPs (e.g., Dynasty Warriors, Nobunaga's Ambition) and expanding globally through partnerships with providers like DeNA, GREE, Tencent, and Facebook.
+1
Koei Tecmo
Financial34 pages
Fiscal Year Ending March 2012: 1st Half Financial Results
Term ended Sep.2010 Term ended Sep.2011 YoY Change Amount Ratio Amount Ratio Amount Ratio Sales 11,069 100.0% 13,635 100.0% 2,566 23.2% Operating △ 1,656 △15.0% 712 5.2% 2,368 - Ordinary △ 1,097 △9.9% 862 6.3% 1,959 - Net Income △ 571 △5.2% 412 3.0%...
- For the first half of FY2011 (ending Sep. 2011), the company achieved a significant turnaround, moving from an operating loss of △1,656 million Yen in Sep. 2010 to an operating profit of 712 million Yen, and net income of 412 million Yen (up 983 million Yen YoY).
- Sales increased by 23.2% year-over-year to 13,635 million Yen for the first half of FY2011, driven primarily by the Game Software segment (8,906 million Yen) and Online & Mobile segment (2,835 million Yen).
- The Online & Mobile segment showed strong growth, with sales increasing from 1,803 million Yen in Sep. 2010 to 2,835 million Yen in Sep. 2011, and operating profit rising from △16 million Yen to 524 million Yen.
- The company plans to double sales from the social gaming sector, aiming for 3 billion Yen in FY2011 compared to 1.2 billion Yen in FY2010, by expanding titles and leveraging existing IP.
- Sales units in Japan increased by 57.8% to 1,610 thousand units in the first half of FY2011, while overseas sales units decreased by 46.8% to 750 thousand units, largely due to a 70.8% drop in North America.
+1
Koei Tecmo
Financial34 pages
Financial Results: Fiscal Year Ended March 2012
Achieved the highest sales and profit ever! FY2011 YoY Amount Ratio Amount Ratio Amount Ratio Sales 32,081 100.0% 35,525 100.0% 3,444 10.7% Operating 3,305 10.3% 5,758 16.2% 2,453 74.2% Ordinary 4,788 14.9% 7,472 21.0% 2,684 56.1% This document...
- TECMO KOEI HOLDINGS achieved its highest ever sales and profit in FY2011, with sales reaching 35,525 million Yen (10.7% increase year-over-year) and net income at 4,640 million Yen (69.3% increase year-over-year).
- The company projects continued growth for FY2012, forecasting sales of 39,000 million Yen (9.8% increase) and operating profit of 7,000 million Yen (21.6% increase).
- Game Software was the largest contributor to sales in FY2011 at 24,883 million Yen, while Online & Mobile showed strong operating profit at 1,034 million Yen.
- Overseas sales of units decreased by 15.8% in FY2011, primarily due to declines in North America (-31.9%) and Europe (-15.1%), despite a 125.8% increase in Asia.
- TECMO KOEI plans to launch a major title globally in September 2012, targeting one million sales, and will focus on expanding collaborations and reviewing low-profitability projects.
Koei Tecmo
Report1 pages
Financial Highlights: Fiscal Year Ending March 2011
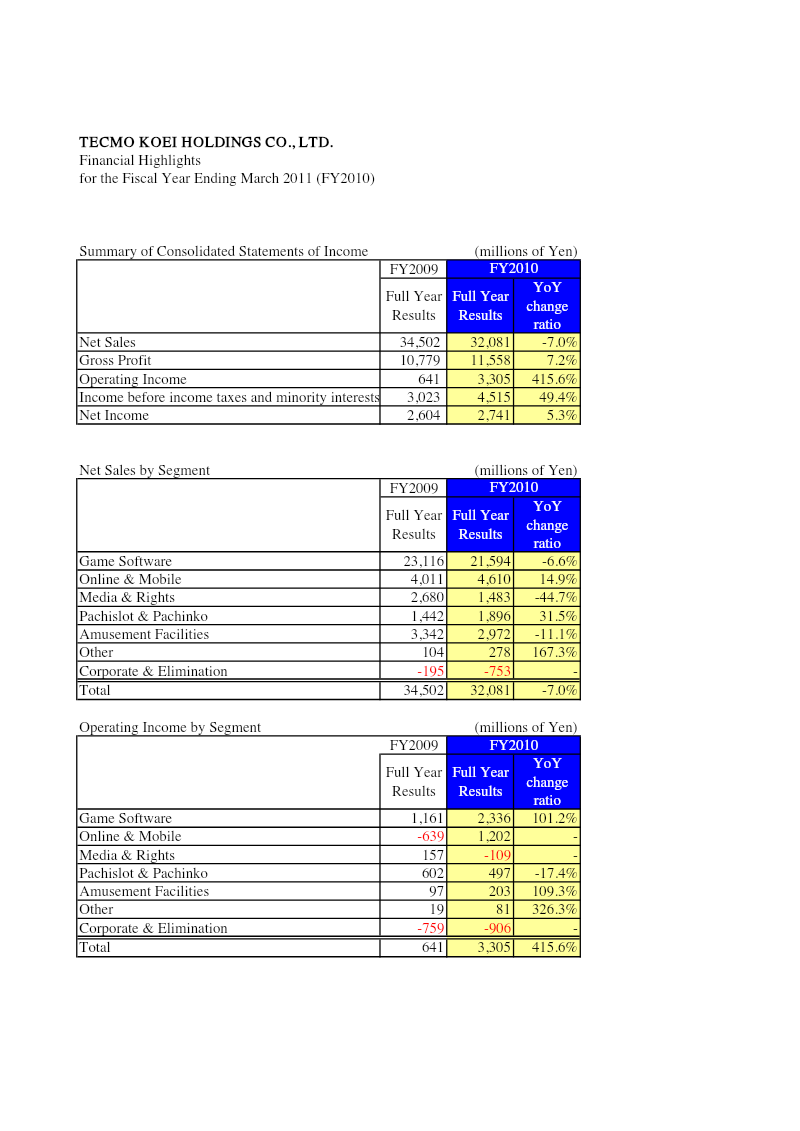
Financial highlights for the fiscal year ending March 2011 show a mixed performance for Tecmo Koei Holdings. Net sales fell 7 % to ¥32,081 million from ¥34,502 million in FY2009, driven mainly by declines in game software sales (‑6.6 %) and media & rights revenue (‑44.7 %). Conversely, online & mobile sales grew 14.9 %, and pachislot & pachinko revenue increased 31.5 %. The “Other” segment, largely comprising new or restructured businesses, surged 167.3 % to ¥278 million.
Operating income expanded dramatically by 415.6 %, rising from ¥641 million to ¥3,305 million. This surge was largely due to a 101.2 % jump in game software operating income and a 109.3 % increase in amusement facilities, offset by declines in pachislot & pachinko (‑17.4 %) and media & rights (negative contribution). The “Other” segment contributed a 326.3 % increase in operating income, reflecting successful new initiatives.
Income before taxes and minority interests grew 49.4 % to ¥4,515 million, while net income increased modestly by 5.3 % to ¥2,741 million. The company’s profitability improved despite lower sales volumes, largely through cost efficiencies and higher-margin segments.
The analysis covers Japan‑based operations for FY2010, using consolidated financial statements. Data are presented in millions of yen, with year‑over‑year comparisons highlighting key segment shifts and overall profitability trends.
- Tecmo Koei Holdings achieved a 415.6% surge in operating income to ¥3,305 million for the fiscal year ending March 2011, despite a 7% decline in net sales to ¥32,081 million.
- Profitability improved significantly through cost efficiencies and high-margin performance, resulting in a 49.4% increase in income before taxes and minority interests to ¥4,515 million.
- The core game software segment saw a 6.6% decline in sales but experienced a 101.2% jump in operating income, indicating a shift toward more profitable operations.
- Revenue diversification efforts showed mixed results, with online & mobile sales growing 14.9% and pachislot & pachinko revenue rising 31.5%, though the latter saw a 17.4% decline in operating income.
- The 'Other' business segment, focused on new initiatives, demonstrated strong growth with a 167.3% increase in sales to ¥278 million and a 326.3% rise in operating income.
+1
Koei Tecmo
Report1 pages
Financial Highlights: 1st Quarter of the Fiscal Year Ending March 2012
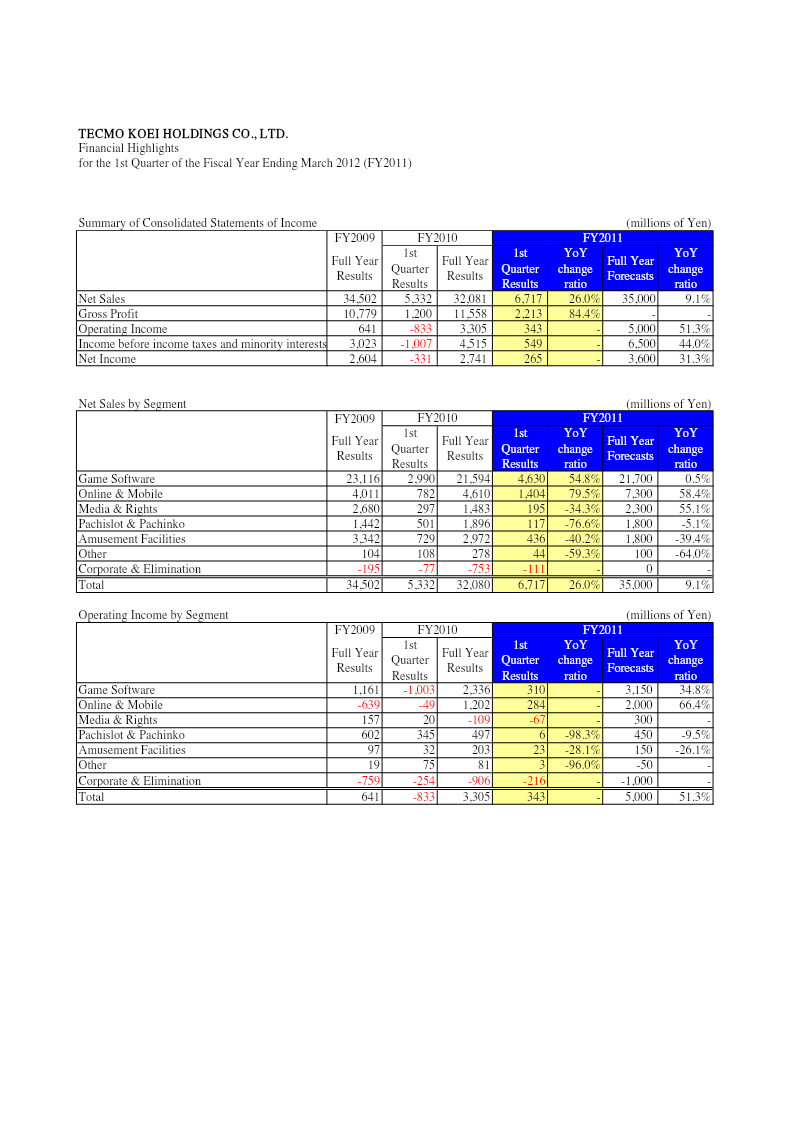
The financial highlights present Tecmo Koei Holdings’ performance for the first quarter of fiscal year 2011, ending March 31, 2012. Net sales rose 26 % year‑over‑year to ¥34.5 billion, driven primarily by the Game Software segment, which generated ¥23.1 billion in sales and contributed a 54.8 % increase from the previous year’s first quarter. Online & Mobile sales also grew strongly, up 79.5 % to ¥4.6 billion, while Media & Rights and Pachislot & Pachinko segments declined sharply by 34.3 % and 76.6 %, respectively. Amusement Facilities sales fell 40.2 %. Corporate and elimination items offset gains, resulting in a net income of ¥2.6 billion, up 31.3 % from the prior year’s first quarter.
Operating income improved markedly to ¥641 million, a 51.3 % increase from the prior year’s first quarter, largely due to gains in Game Software (¥1.16 billion) and Online & Mobile (¥1.20 billion). However, the Media & Rights segment posted a loss of ¥109 million, and Pachislot & Pachinko’s operating income fell 98.3 % to ¥497 million, reflecting a significant downturn in that business line.
The report covers Japan‑based operations across five core segments—Game Software, Online & Mobile, Media & Rights, Pachislot & Pachinko, and Amusement Facilities—over the first quarter of FY2011. Data are presented in millions of yen, with year‑on‑year comparisons and forecasts for the full fiscal year. The methodology relies on consolidated financial statements, with no explicit survey or sampling details disclosed. Overall, the company experienced robust growth in its core gaming and online divisions, offset by declines in traditional gambling‑related businesses.
- Tecmo Koei Holdings reported a 26% year-over-year increase in net sales to ¥34.5 billion and a 31.3% rise in net income to ¥2.6 billion for the first quarter of the fiscal year ending March 2012.
- The Game Software segment was the primary growth driver, generating ¥23.1 billion in sales—a 54.8% increase compared to the same period in the previous year.
- The Online & Mobile segment experienced significant expansion, with sales rising 79.5% to ¥4.6 billion and contributing ¥1.20 billion to operating income.
- Operating income for the company reached ¥641 million, a 51.3% improvement year-over-year, bolstered by strong performance in the gaming and online divisions.
- The Pachislot & Pachinko segment suffered a major downturn, with sales falling 76.6% and operating income declining by 98.3% to ¥497 million.
+1
Koei Tecmo
Report1 pages
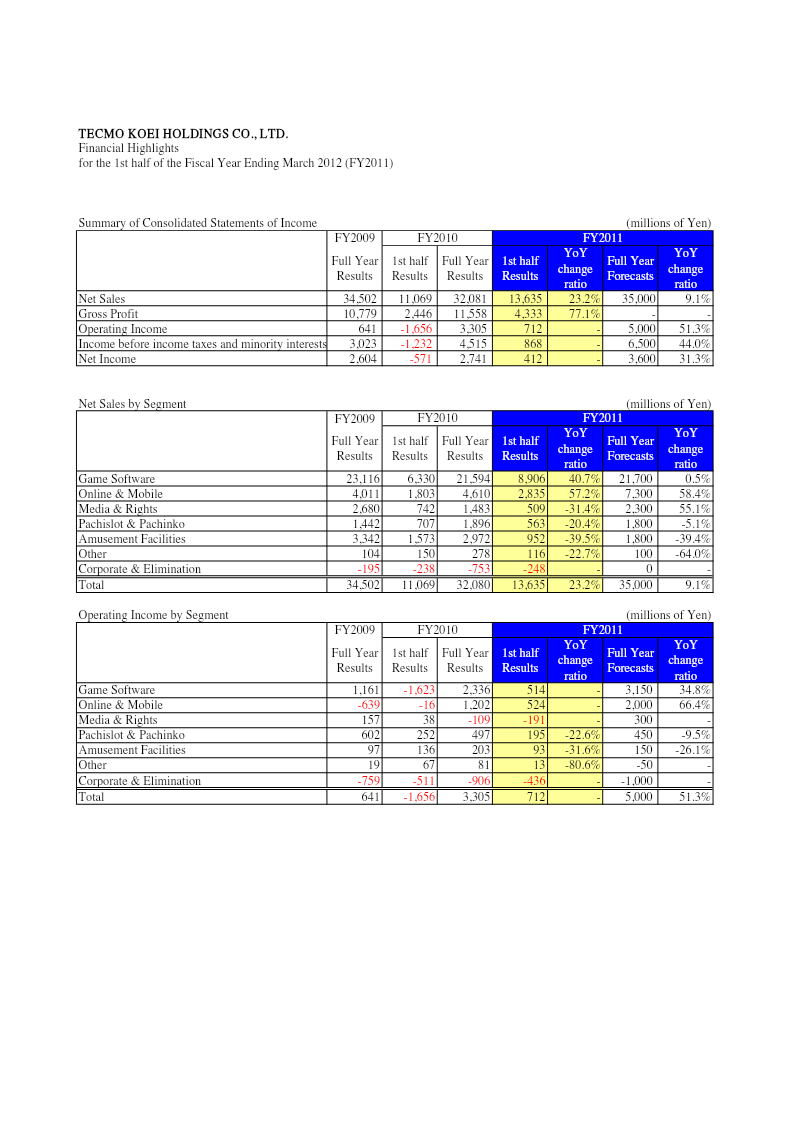
Financial Highlights: 1st Half of Fiscal Year Ending March 2012
Financial highlights for the first half of fiscal year ending March 2012 reveal a mixed performance across Tecmo Koei Holdings’ business segments. Net sales rose 23.2 % year‑over‑year to ¥11,069 million, driven primarily by growth in Game Software (40.7 % increase) and Online & Mobile (57.2 % increase). Media & Rights, Pachislot & Pachinko, Amusement Facilities, and Other segments all experienced declines ranging from 20.4 % to 39.5 %. Corporate and elimination items contributed a net negative of ¥753 million, offsetting gains in other areas.
Operating income for the period was ¥641 million, a sharp improvement from a loss of ¥1,656 million in the same period a year earlier. The recovery was largely due to Game Software (+34.8 %) and Online & Mobile (+66.4 %). However, Media & Rights, Pachislot & Pachinko, Amusement Facilities, and Other segments remained unprofitable or posted modest gains. Corporate and elimination costs again weighed heavily on profitability.
Net income increased to ¥412 million, up 31.3 % from a loss of ¥571 million in the prior year’s first half, reflecting stronger operating performance and reduced tax expenses. Forecasts for the full year indicate a modest 9.1 % increase in net sales to ¥35,000 million and a target operating income of ¥5,000 million.
The analysis draws on consolidated financial statements for the first half and full year of FY2011, comparing them to FY2009 and FY2010 figures. Data are presented in millions of yen, with year‑over‑year changes expressed as percentages. The report covers all business segments within the company’s geographic scope, primarily Japan and related international operations.
- Tecmo Koei Holdings returned to profitability in the first half of fiscal year 2012, reporting ¥412 million in net income compared to a ¥571 million loss in the same period the previous year.
- Operating income reached ¥641 million, a significant turnaround from the ¥1,656 million loss recorded in the first half of the prior fiscal year.
- Net sales grew 23.2% year-over-year to ¥11,069 million, fueled by strong performance in the Game Software segment (+40.7%) and the Online & Mobile segment (+57.2%).
- Non-core business segments, including Media & Rights, Pachislot & Pachinko, and Amusement Facilities, underperformed with revenue declines ranging from 20.4% to 39.5%.
- Corporate and elimination costs remained a significant financial drag, contributing a net negative of ¥753 million to the period's results.
Koei Tecmo
Financial33 pages
Fiscal Year Ending March 2013: 1st Half Financial Results
The fiscal year ending March 2013 saw the company report consolidated net sales of 13.7 billion yen, a 6.3 % increase from the previous year’s 13.6 billion yen, driven largely by a 73.6 % rise in overseas sales to 2.9 billion yen versus 1.8 billion yen in FY2012. Domestic sales grew modestly by 8.2 % to 10.9 billion yen, while the overseas segment expanded from 1.8 billion to 2.9 billion yen, reflecting a strategic emphasis on international markets.
Operating profit rose from 1.2 billion yen to 1.3 billion yen, a 6.5 % year‑over‑year gain, while ordinary profit increased from 1.0 billion to 1.2 billion yen, a 4.0 % rise. Net income reached 13.7 billion yen, up 5.2 % from the prior year’s 13.6 billion yen, after accounting for a one‑time goodwill amortization of approximately 700 million yen following the Koei–Tecmo merger. The company’s expenses‑to‑sales ratio improved from 26.0 % to 23.8 %, indicating tighter cost control.
Segment analysis shows software and game sales as the largest contributors, with online and mobile gaming growing rapidly; social games were highlighted for high‑profitability projects such as “Hyakuman nin no Nobunaga no Yabou.” The company’s strategy for FY2013 focuses on expanding new platform titles, strengthening collaboration projects, and reducing costs to enhance profitability. The report covers Japan and overseas markets across the fiscal year, using consolidated financial statements and segment performance data to illustrate growth trends and strategic priorities.
- Consolidated net sales for the first half of FY2013 reached 13.7 billion yen, representing a 6.3% year-over-year increase.
- Overseas sales were the primary growth driver, surging 73.6% to 2.9 billion yen compared to 1.8 billion yen in the previous fiscal year.
- Operating profit grew by 6.5% to 1.3 billion yen, while net income rose 5.2% to 13.7 billion yen despite a 700 million yen one-time goodwill amortization charge related to the Koei–Tecmo merger.
- Operational efficiency improved as the company reduced its expenses-to-sales ratio from 26.0% to 23.8%.
- Domestic sales saw modest growth of 8.2%, reaching 10.9 billion yen.
+2
Koei Tecmo
Report1 pages
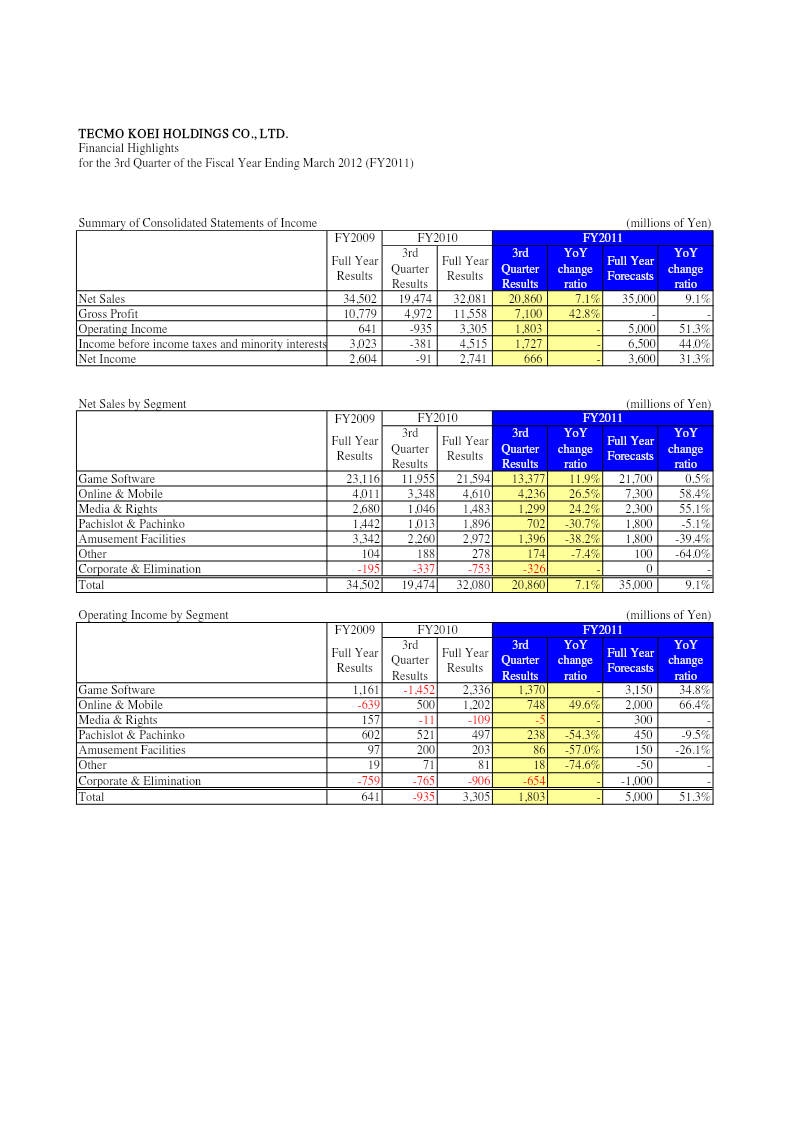
Financial Highlights: 3rd Quarter of the Fiscal Year Ending March 2012
The financial highlights for the third quarter of fiscal year 2011 (ending March 2012) show a modest improvement in consolidated performance compared with the same period in 2010. Net sales rose by 7.1 % to ¥32,080 million from ¥29,974 million in the prior year’s third quarter. Gross profit increased 42.8 % to ¥11,558 million, while operating income surged 51.3 % to ¥3,305 million, reflecting stronger profitability across most business segments.
Segment analysis reveals that Game Software sales grew 11.9 % to ¥21,594 million, contributing the largest share of operating income (¥2,336 million). Online & Mobile sales expanded 26.5 % to ¥4,610 million and generated a positive operating income of ¥1,202 million after a loss in the previous year. Media & Rights sales increased 24.2 % to ¥1,483 million but produced a modest operating profit of ¥157 million. Pachislot & Pachinko and Amusement Facilities sales both declined sharply (−30.7 % and −38.2 %, respectively), resulting in lower operating contributions of ¥497 million and ¥203 million. The Other segment saw a 7.4 % sales rise but remained a small contributor to operating income.
Overall, the company’s forecasted full‑year net sales for FY2011 were set at ¥35,000 million, a 9.1 % increase over the prior year’s full‑year figure. Operating income forecasts were raised to ¥5,000 million, reflecting a 51.3 % year‑over‑year improvement. The data derive from consolidated financial statements covering all business segments in Japan, with figures reported in millions of yen.
- Consolidated net sales for Q3 of the fiscal year ending March 2012 rose 7.1% to ¥32,080 million, while operating income surged 51.3% to ¥3,305 million.
- The Game Software segment remains the primary driver of profitability, growing 11.9% to ¥21,594 million in sales and contributing ¥2,336 million in operating income.
- The Online & Mobile segment achieved a turnaround, growing 26.5% to ¥4,610 million in sales and generating ¥1,202 million in operating income after posting a loss in the prior year.
- Pachislot & Pachinko and Amusement Facilities segments experienced significant declines, with sales falling 30.7% and 38.2% respectively.
- Full-year forecasts for FY2011 were updated to ¥35,000 million in net sales, representing a 9.1% year-over-year increase.
+1
Koei Tecmo