Funding reports and market data
Documents
Believer’s $55M Series A / Exits in Gaming / Gen AI Playtesting Workflow
Generative artificial intelligence is fundamentally reshaping game development workflows by automating labor-intensive processes such as quality assurance, playtesting, and content iteration.
- Believer secured $55 million in Series A funding to prioritize the development of expansive, long-term transmedia IP over standalone titles.
- Studios are increasingly using generative AI to automate labor-intensive tasks like playtesting and quality assurance, converting verbal feedback into actionable project management tickets.
- The gaming industry is shifting its business model away from quarterly performance metrics toward building games as lifestyle platforms that foster enduring audience engagement.
Sequoia Capital India on Investing in Indian Gaming Market
Sequoia Capital India maintains a bullish long-term outlook on the Indian gaming market, identifying it as a nascent but rapidly expanding sector.
- The Indian gaming market has experienced a 400 to 500 percent growth in size over recent years, leading Sequoia Capital India to project the emergence of a billion-dollar domestic game title within the next decade.
- Investment strategy prioritizes high-quality studios, esports, and distribution platforms, specifically targeting founders who demonstrate sustainable unit economics and long-term product-market fit over aggressive, cash-burning growth.
- While the market has seen a correction in valuations from the 2020 and 2021 peaks, the environment remains competitive and healthy for high-quality teams.
Venture Debt 101
Venture debt has matured into a $29 billion financial sector, functioning as a strategic, non-dilutive capital tool for startups that have already achieved product-market fit.
- Venture debt has evolved into a $29 billion financial sector that provides non-dilutive capital to startups that have already achieved product-market fit.
- Unlike venture equity, which targets binary outcomes, venture debt is a lower-beta instrument structured as a three-year amortizing loan designed to extend operational runway and accelerate growth.
- Venture debt is positioned senior to equity in the capital structure and is intended for high-margin, scalable enterprises rather than as a rescue mechanism for insolvent firms.
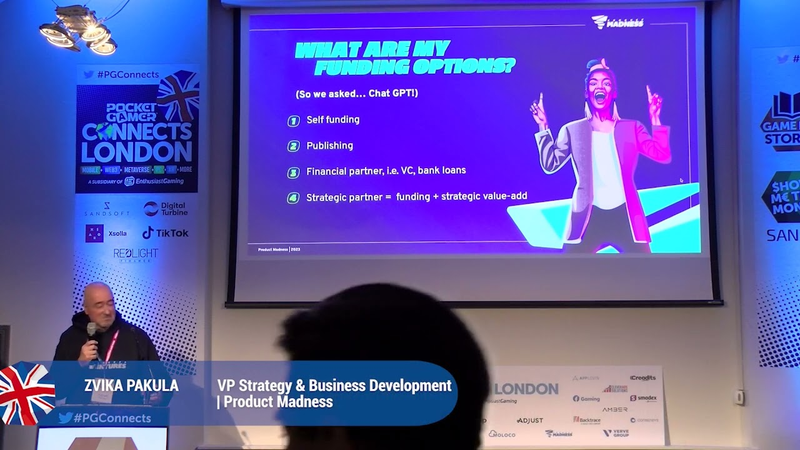
Funding Early Stage Gaming - Zvika Pakula, Product Madness
Securing funding for early-stage gaming ventures requires a strategic, realistic approach that balances creative vision with market data.
- Early-stage founders must prioritize building prototypes that generate actionable KPIs rather than attempting to develop a full-scale product prematurely.
- Achieving meaningful market share in the current gaming landscape requires planning for user acquisition costs that can reach 15 to 20 million dollars.
- Development cycles for genres such as social casino, RPG, or casual gaming typically span one to two years, requiring a long-term strategic approach to funding.
Raising Capital in 2023: State & Evolution of Sources of Sources of Financing for Developers.
The gaming industry is currently navigating a significant financial reset characterized by a decline in venture capital investment and a shift in market expectations.
- The gaming industry has shifted from speculative venture capital funding to a model prioritizing rigorous product quality, data-driven metrics, and sustainable business models.
- Institutional investors are increasingly de-prioritizing founder pedigree in favor of objective performance indicators, specifically acquisition, retention, engagement, and monetization data.
- Developers are moving toward alternative financing models, such as debt financing and strategic partnerships, to secure capital while avoiding the equity dilution associated with traditional venture capital.
Aktualizacja Strategii Nowe Otwarcie: Polska
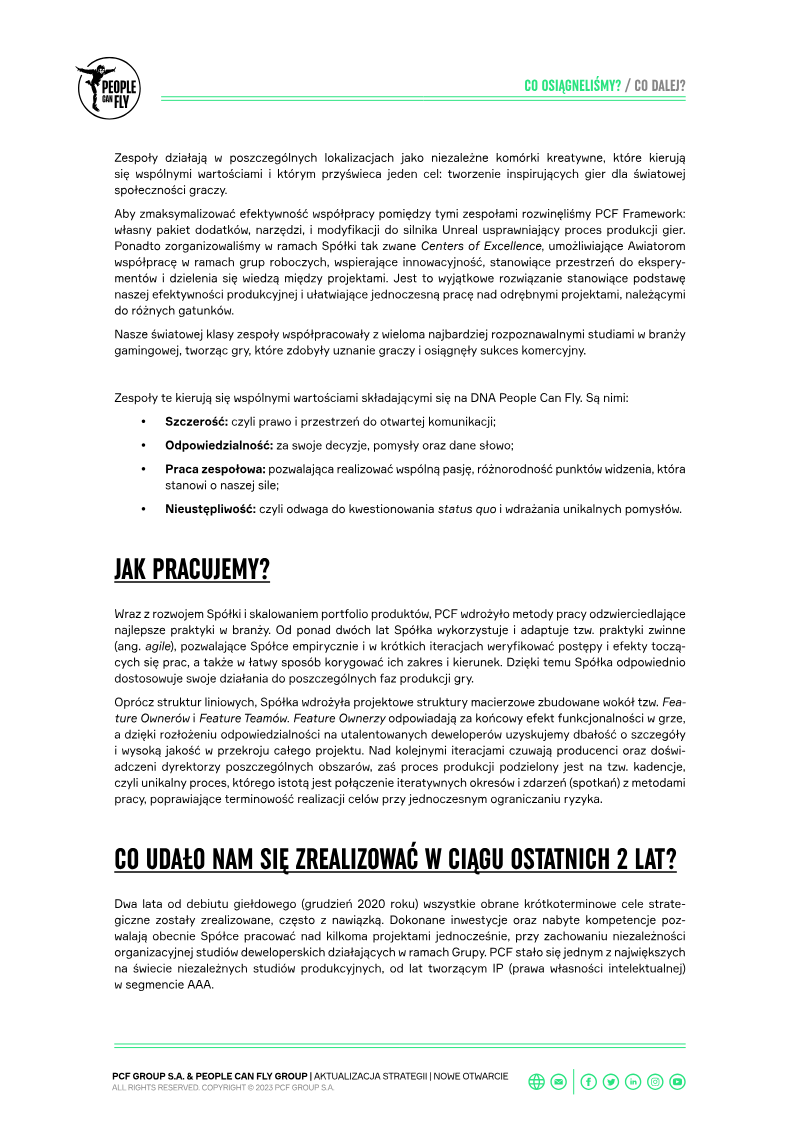
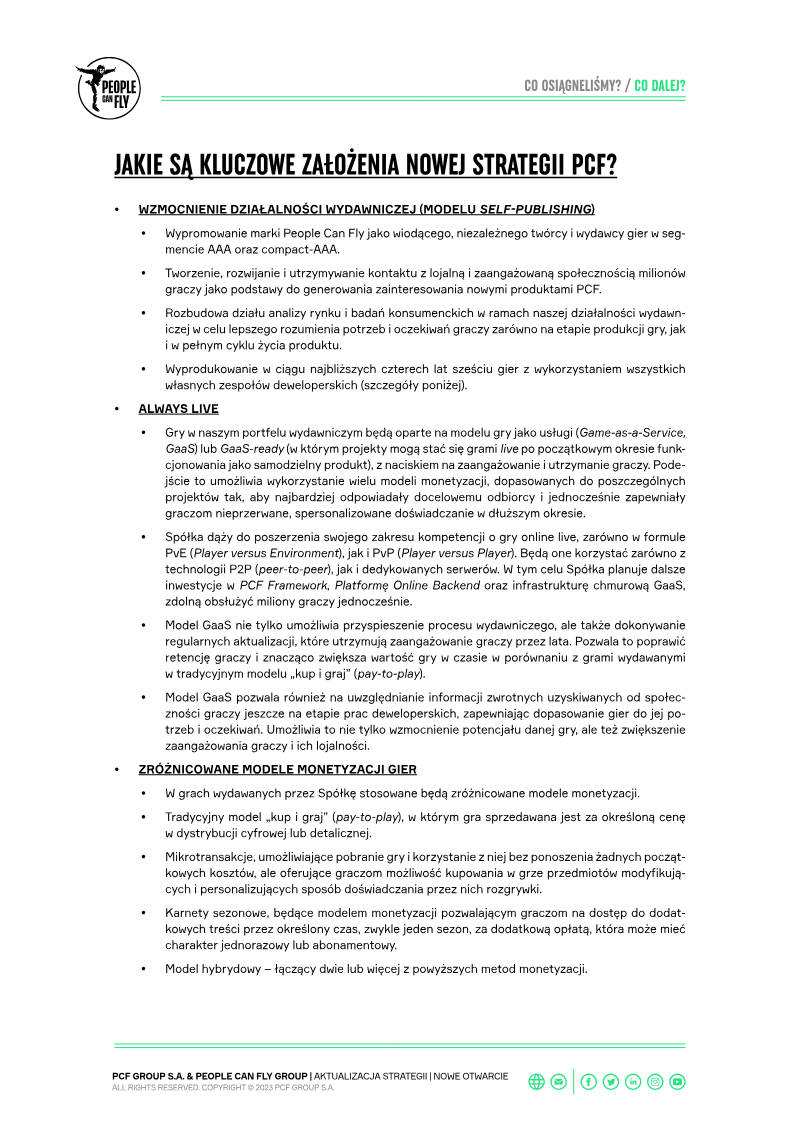
People Can Fly’s strategic update, issued on 31 January 2023, outlines a transformation from a single-title studio into a multi-project, globally distributed developer and emerging self-publisher.
- People Can Fly aims to generate at least 3 billion PLN in combined revenue between 2023 and 2027 through a portfolio of six new releases.
- The studio is transitioning from a single-title developer to a multi-project, self-publishing entity capable of simultaneous AAA production.
- The development pipeline includes the AAA work-for-hire title Gemini (2026), three self-funded AAA projects (Dagger, Bifrost, and Victoria) slated for 2025-2026, and various compact-AAA and VR titles.
Moritz Baier-Lentz: The State of Gaming VC - Naavik Gaming Podcast
Lightspeed Venture Partners has established a comprehensive investment strategy to navigate the evolving gaming landscape, leveraging $18 billion in assets to support studios, platforms, and infrastructure technologies.
- Lightspeed Venture Partners manages $18 billion in assets and has deployed over $300 million across more than 30 gaming investments, supporting companies from seed-stage to pre-IPO.
- Early-stage gaming valuations are projected to decline by 30% to 50%, prompting investors to prioritize lean operations and profitability over deal volume.
- Startups are advised to maintain at least 24 months of runway and focus on achieving tangible market milestones rather than relying on speculative capital.
H1 2023 Gaming Deals Report: Navigating Turbulence
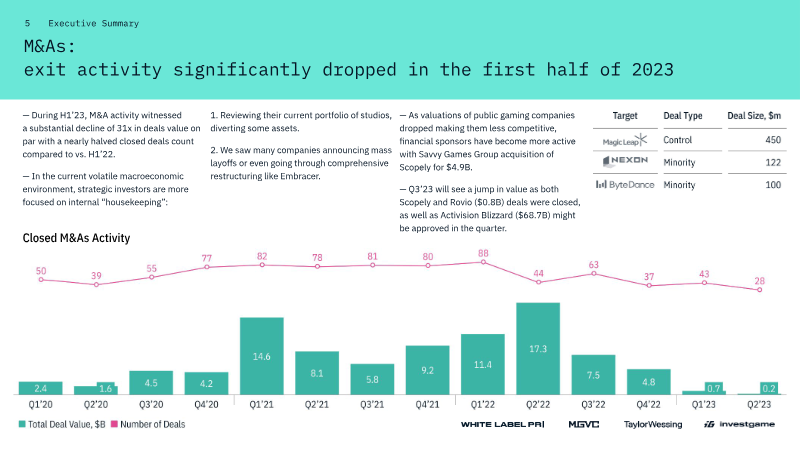
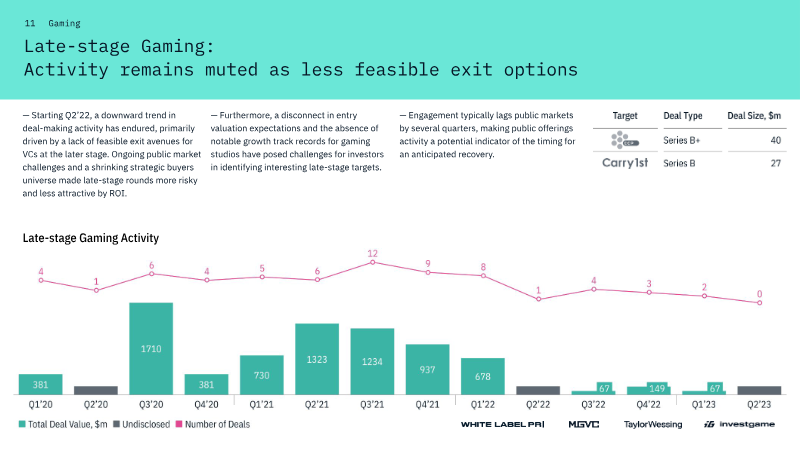
The gaming industry experienced a significant contraction in deal-making activity during the first half of 2023, characterized by a challenging macroeconomic environment and a cooling of investor sentiment.
- H1 2023 saw a significant contraction in gaming deal-making, with private investments falling to $1.5 billion across 239 deals compared to the same period in 2022.
- M&A activity experienced a sharp decline as strategic investors prioritized internal restructuring and portfolio management over new acquisitions.
- Public offerings remained largely stagnant throughout the first half of 2023 due to unfavorable market conditions and necessary valuation corrections.
Q1 2023 Gaming Deals Report: Cooling Off After Years of Blistering Growth
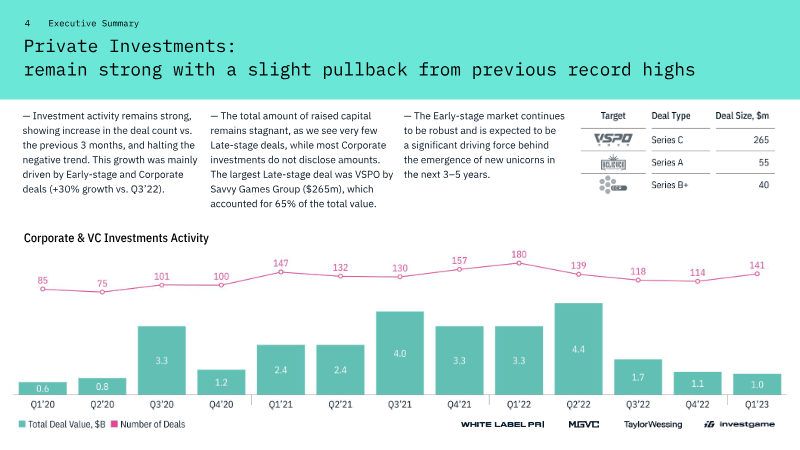
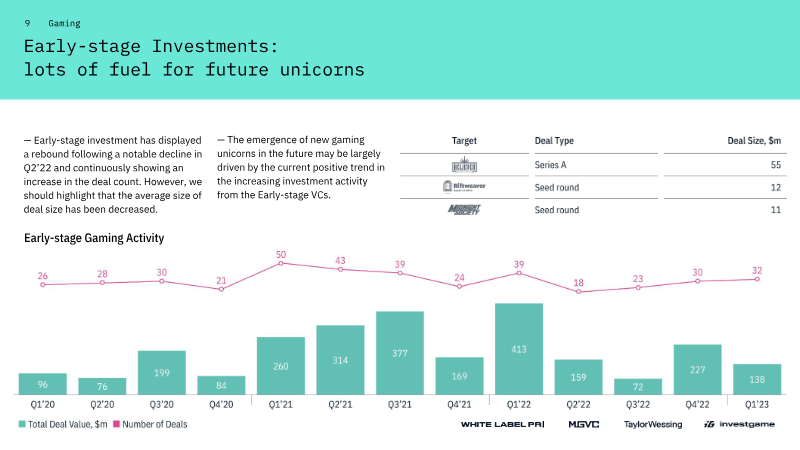
The gaming industry experienced a significant cooling period in the first quarter of 2023, characterized by a sharp decline in deal activity across private investments, mergers and acquisitions (M&A), and public offerings.
- Q1 2023 marked a significant industry-wide cooling period, characterized by a sharp decline in private investments, M&A activity, and public offerings compared to previous years of rapid growth.
- M&A activity hit a low point in Q1 2023, recording approximately half the volume seen in previous years.
- Late-stage funding has stalled significantly, with only two closed transactions recorded throughout the entire first quarter.
2023 European Video Games Industry Insight Report
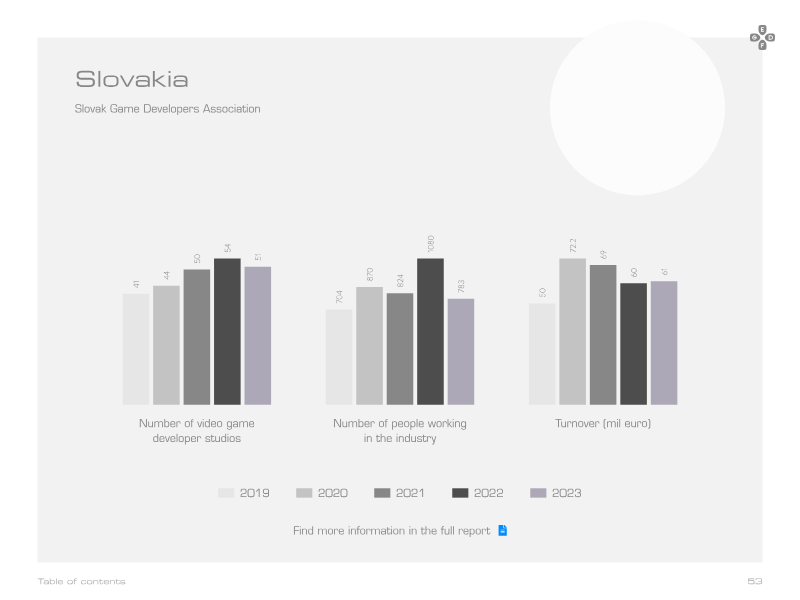
The European video games industry demonstrated remarkable resilience throughout 2023, maintaining a robust ecosystem despite a broader global market downturn.
- In 2023, the EU was home to 5,900 game developer studios.
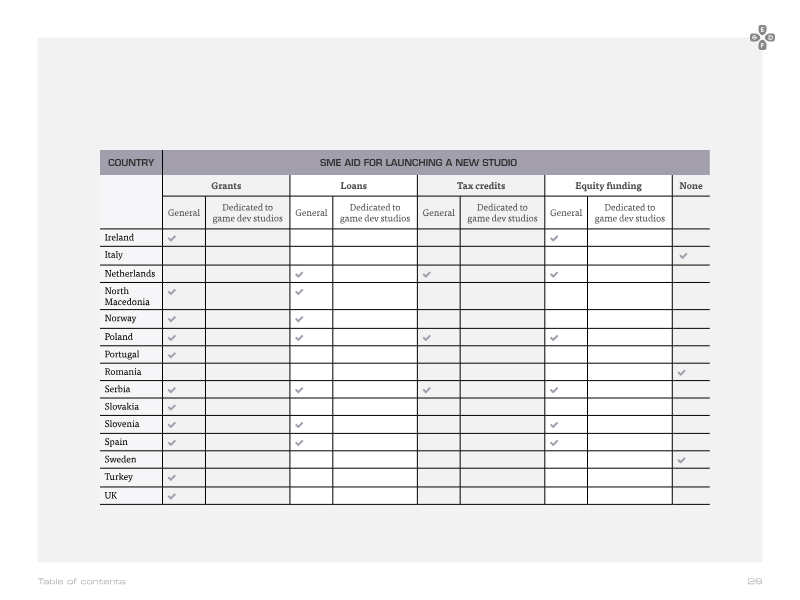
- Public funding plays a crucial role in financing new game studios and supporting research and development across Europe.
- Each European country exhibits unique platform preferences for game development.
Ayudas AEVI Innovación: Edición 2023
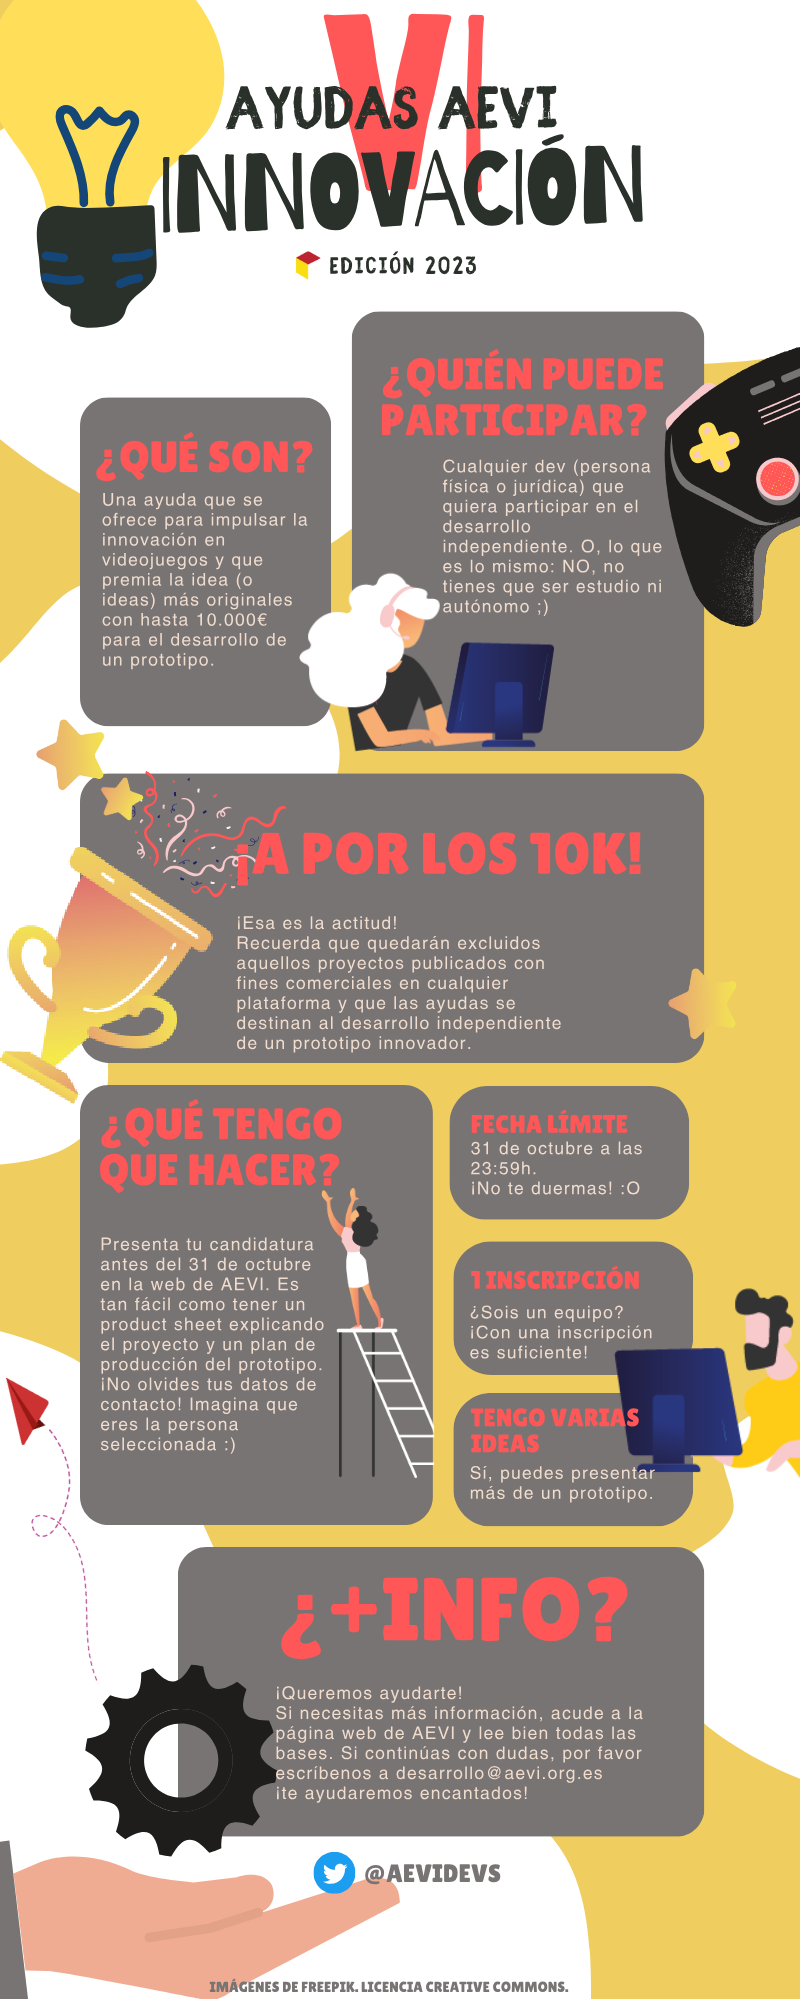
The AEVI Innovation program for 2023 offers financial support of up to €10,000 to independent developers—both individuals and legal entities—who wish to create an innovative prototype in the video-game sector.
- The AEVI Innovation program provides financial grants of up to €10,000 to support the development of innovative video game prototypes.
- Applications must be submitted by the deadline of 31 October at 23:59 via the official AEVI website.
- Eligible projects must be non-commercial and cannot have been previously published on any platform.
New World for Gaming Startups in 2023 | Jason Chapman, Konvoy Ventures & Josh Lu, a16z
The gaming startup landscape in 2023 is defined by a significant contraction in late-stage financing, with Series B and C deal activity plummeting by 47% and 67% respectively.
- Late-stage gaming financing has contracted significantly, with Series B deal activity dropping by 47% and Series C activity falling by 67%.
- Startup valuations have undergone a major correction of 40% to 55%, forcing founders to prioritize capital efficiency and extend financial runways into 2025.
- Investors are shifting toward a 'flight to quality' strategy, favoring teams with deep expertise and metric-driven product development over speculative ventures.