Key insights
7 slides
The setting
Gaming deal-making contracted in a challenging macroeconomic environment.
The first half of 2023 brought a significant contraction in gaming deal-making activity. Investor sentiment cooled, and high-value exits and late-stage investments stalled.
Key number
Private investments fell to $1.5 billion across 239 deals.
Private investments in gaming fell to $1.5 billion across 239 deals in H1 2023. This represented a substantial decrease in both volume and value compared to H1 2022.
What changed
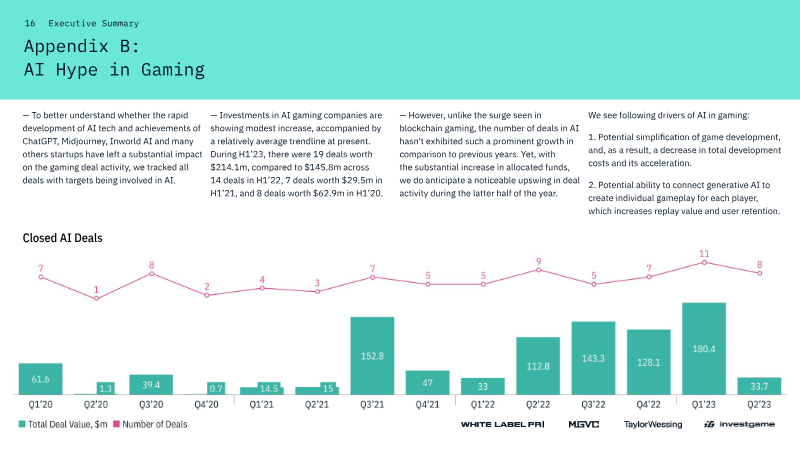
M&A activity declined as strategic investors prioritized internal restructuring.
M&A activity experienced a sharp decline in H1 2023. Strategic investors shifted focus toward internal housekeeping and portfolio management over new acquisitions.
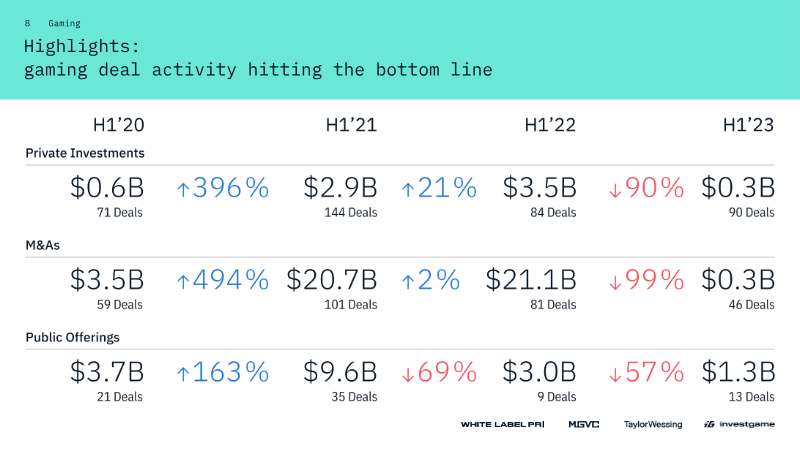
Page 5 of the report| Category | H1'20 | H1'21 | H1'22 | H1'23 |
|---|---|---|---|---|
| Private Investments | 0.6 | 2.9 | 3.5 | 0.3 |
| M&As | 3.5 | 20.7 | 21.1 | 0.3 |
| Public Offerings | 3.7 | 9.6 | 3 | 1.3 |
What changed
Public offerings remained largely stagnant due to unfavorable market conditions.
Public offerings remained largely stagnant throughout the first half of 2023. Companies increasingly opted to postpone listings due to unfavorable market conditions and valuation corrections.
Page 6 of the reportQ1'200.3
Q2'204.6
Q3'204.7
Q4'206.1
Q1'218.7
Q2'218.5
Q3'214.2
Q4'213.1
What changed
The industry shifted focus from aggressive growth to profitability and cost optimization.
The gaming industry shifted its primary focus from aggressive growth strategies to profitability, cost optimization, and sustainable business models. Companies prioritized internal restructuring over aggressive expansion.
What changed
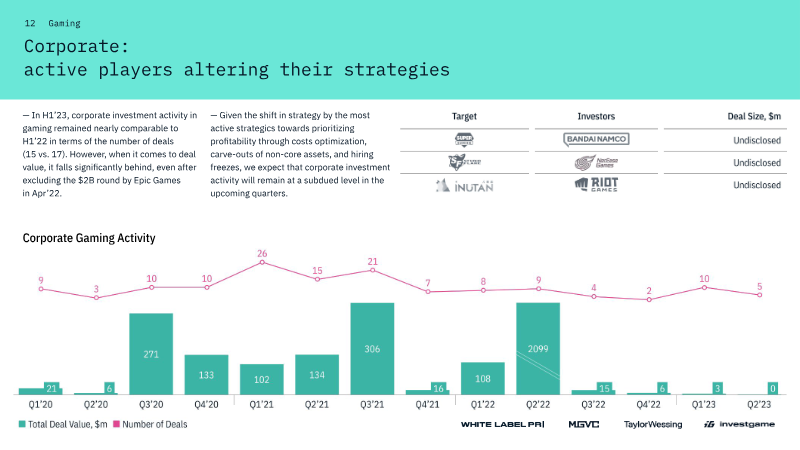
Artificial intelligence emerged as a potential catalyst for future deal activity.
Artificial intelligence has emerged as a potential catalyst for future deal activity despite broader macroeconomic headwinds. The report identifies emerging interest in AI as a potential driver for future deal activity.
What changed
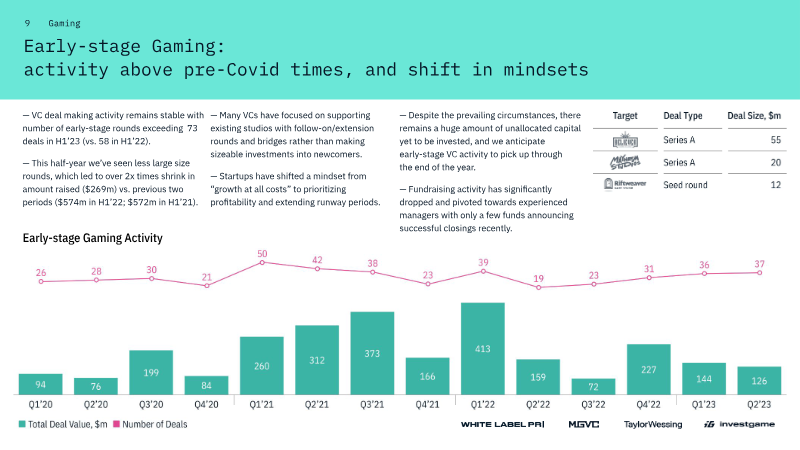
Early-stage venture capital remains the most resilient segment of the market.
Early-stage venture capital remains the most resilient segment of the gaming market. Startups are increasingly abandoning 'growth at all costs' mentalities in favor of sustainable business models.
1 / 7
Ask AI about this report
Comments