Report12 pages
The Rise and Reset of Sweden's $19B Gaming Capital Machine
The analysis demonstrates that Sweden’s gaming sector has evolved into a $19 billion capital ecosystem, with 1,100 companies and 202 firms engaging in tracked transactions since 2014. Sweden contributes roughly 20 % of Steam’s projected 2025 gross revenue, and its developers produced five of the platform’s global top‑10 bestsellers in 2024–25. Capital flows have shifted from early‑stage seed rounds to late‑stage growth and acquisition deals, reflecting a maturation of the pipeline. Private investment rebounded in 2024 after a pullback; late‑stage rounds now dominate, with Aonic’s $157 million growth round and Arrowhead’s $80 million investment illustrating investor preference for studios with proven commercial traction. Early‑stage deal counts have normalized from 2021’s peak, indicating a steady but active pipeline.
M&A activity peaked in 2021–22, with ESL’s $1.05 billion sale to Savvy marking the cycle’s apex; subsequent deals have become more selective. Three transactions—King ($5.9 billion), Mojang ($2.5 billion), and ESL ($1.05 billion)—account for 93 % of total M&A value, underscoring the premium paid by global acquirers for Sweden’s IP and engineering talent. Public market activity has shifted from equity‑fueled growth to defensive debt financing; Embracer’s $4.4 billion raised through fixed income and PIPE in 2020–22 exemplifies this trend. Capital concentration is high, with the top ten private rounds comprising over $495 million of an $811 million total.
The data, sourced from InvestGame and market‑cap records through December 2025, cover Sweden’s entire gaming industry—mobile, PC & console, VR/AR, esports, and platforms—from 2014 to the present. Methodology includes tracking VC rounds, public offerings, PIPEs, and M&A transactions across all segments. The findings illustrate a resilient ecosystem that has transitioned from early‑stage bootstrapping to mature, high‑value capital flows driven by proven studios and strategic consolidation.
- Sweden’s gaming sector has matured into a $19 billion ecosystem comprising 1,100 companies, with Swedish developers producing five of Steam’s global top-10 bestsellers in 2024–25.
- Swedish studios contribute approximately 20% of Steam’s projected 2025 gross revenue, cementing the country's status as a dominant global gaming hub.
- M&A activity is highly concentrated, with three major deals—King ($5.9 billion), Mojang ($2.5 billion), and ESL ($1.05 billion)—accounting for 93% of the total transaction value.
- Investment trends have shifted toward late-stage growth, evidenced by significant 2024 capital injections such as Aonic’s $157 million round and Arrowhead’s $80 million investment.
- Capital concentration remains high, as the top ten private funding rounds account for $495 million of the $811 million total tracked investment.
+3
InvestGame
Report5 pages
East vs. West: Monetization Trends
The study examines how mobile gaming spending patterns differ between Eastern and Western markets, focusing on frequency of purchases, average spend per transaction, and motivational drivers. Findings reveal that Eastern gamers purchase in‑app items more often than Western players; 35 % of East spend frequently versus 36 % in the West, with a higher proportion of occasional and rare spenders in the West. When it comes to transaction size, Eastern users tend to pay more per purchase: 76 % spend over $10 compared with only 42 % of Western users, while a smaller share of East spend under $5 (30 %) versus 8 % in the West. Motivational analysis shows that Western gamers prioritize value and bundles, whereas Eastern players are more attracted to exclusivity, limited‑time items, new offers, and character acquisition. The research covers key markets in Asia—Korea and Japan—and Western regions including the United States, United Kingdom, and broader Europe. Data were collected through a survey of mobile gamers across these regions, with sample sizes sufficient to compare spending behaviors and motivations. The report concludes that monetization strategies should be tailored regionally: value‑based bundles may resonate better in the West, while exclusive content and limited editions could drive higher spend in Eastern markets.
- Eastern mobile gamers demonstrate a significantly higher propensity for large transactions, with 76% of purchases exceeding $10 compared to only 42% in Western markets.
- Western mobile gamers are more likely to make small-scale purchases, with 8% of spenders in the West opting for transactions under $5, contrasted with 30% in the East.
- Monetization strategies in the West should prioritize value-based bundles, as these resonate more effectively with the purchasing preferences of Western players.
- Eastern markets, specifically Korea and Japan, show a stronger consumer preference for exclusivity, limited-time offers, and character acquisition.
- Purchase frequency remains relatively balanced across regions, with 35% of Eastern gamers and 36% of Western gamers identified as frequent spenders.
+5
Mistplay
Whitepaper41 pages
What Good Are AI NPCs?: Lessons from a Large-scale Player Study
The study demonstrates that generative AI‑driven non‑player characters can deliver deeply engaging, emotionally resonant gameplay. In a 122‑hour experiment with 68 participants, the “Dead Meat” demo achieved high immersion scores—97 % UES reward and 94 % focused attention—while keeping mental demand low (NASA‑TLX scores of 64.7 for demand and 52.7 for performance). Qualitative interviews consistently cited the NPCs’ human‑like dialogue and narrative depth as key contributors to player enjoyment.
Quantitative data confirm widespread satisfaction: 96 % of players rated overall enjoyment as high, and 90 % praised the creative freedom afforded by the open‑ended design. Subscale analysis of the GUESS instrument revealed that 60 % achieved a top score for Creative Freedom, 65 % for Personal Gratification, and 80 % for Play Engrossment. Thematic coding identified freedom of expression, challenge‑driven motivation, and immersive conversation as primary drivers of satisfaction, indicating that the game successfully balances agency with sufficient guidance.
Player behavior analysis uncovered seven distinct strategic approaches—such as “Good Cop/Bad Cop” interrogation, “Rule Bender End Justifies the Means,” and “Smart Arse” manipulation—often combined within a single session. Participants responded equally to voiced and text‑based NPCs, and the 20‑minute session length encouraged replayability through role‑playing different characters. Although the brief duration limited long‑term insight, emergent strategies were viewed as a feature rather than a flaw. Future research will explore how authorial adjustments influence player responses across demographic groups, reinforcing the potential of AI NPCs to enrich narrative gameplay on a broad scale.
- Generative AI NPCs drive high player engagement, with 97% of participants reporting high immersion and 96% rating their overall enjoyment as high.
- The integration of AI NPCs maintains a balance between agency and guidance, as evidenced by 80% of players achieving top scores for play engrossment and 90% praising the creative freedom of the open-ended design.
- Cognitive load remains manageable during AI-driven interactions, with participants reporting NASA-TLX mental demand scores of 64.7 and performance scores of 52.7.
- Players adopt diverse, emergent interaction strategies, including interrogation, manipulation, and rule-bending, which suggests that AI NPCs support complex, role-playing-heavy gameplay.
- Player satisfaction is consistent across communication formats, as participants responded equally well to both voiced and text-based AI NPC interactions.
+2
University of Bristol
Report22 pages
The 2026 State of Web Gaming Report: A Study of Developer and Gamer Perceptions
The study demonstrates that web gaming has evolved from a niche, low‑quality outlet into a central discovery and revenue engine for the industry. Across 2,000 gamers and 400 developers surveyed in 2026, data reveal that 62 % of players discover new titles via the web and 53 % spend more than $50 monthly on games, underscoring a highly engaged, high‑spending audience. Ninety percent of players find games online, yet only 53 % of studios plan to port mobile titles to browsers within a year, highlighting a perception gap between consumer enthusiasm and developer adoption.
Web games thrive in an attention‑saturated media environment because they are short, low‑friction, and can be updated instantly to capture cultural moments. More than half of players listen to music or watch shows while gaming, and 38 % use social media simultaneously, positioning web games as a complementary entertainment layer. Developers cite discoverability (46 %) and gateway potential to other platforms (44 %) as key strengths, while rapid iteration and zero‑install access drive engagement and revenue. Monetisation maturity remains a barrier, yet the medium’s ability to reach players at the top of the purchase funnel is clear.
The data also show that web gaming no longer represents a low‑quality channel; 92 % of players rate HTML5 titles as high quality, and 37 % play multiple times a day. Web platforms drive discovery for 62 % of players, and high‑spending consumers are increasingly found online. Consequently, developers who omit web distribution risk missing a growing, engaged, and monetisable audience that now sits at the forefront of the purchase funnel.
- Web gaming is a significant discovery channel: 62% of web gamers have downloaded or purchased a game after discovering it on the web, and 53% of developers see it as a means to reach new players.
- Web gamers are highly engaged and valuable: 37% play multiple times per day, 86% play at least a few times a week, and 53% spend over $50 on gaming purchases monthly.
- Developers are increasingly embracing web gaming, with 27% planning to port mobile games to browsers in the next 12 months, and 56% agreeing it's a growing channel.
- There's a disconnect between some developer perceptions and reality: 32% of developers believe web gaming is a 'low-quality channel' despite 92% of consumers rating HTML5 web games as 'quite' or 'very' high quality.
- Web gaming offers low-friction access and high convenience, with 71% of respondents reporting stable or increasing web gaming time relative to social media, and 58% playing because games are free.
+1
PokiJun 2026
Report64 pages
Oświadczenie dotyczące zrównoważonego rozwoju: Polska 2025
The statement establishes MTG’s commitment to a comprehensive sustainability agenda for 2025, integrating environmental stewardship, social responsibility and robust governance across its entire value chain. The company’s board maintains a 29 % female composition, and ESG oversight is embedded in the audit/ESG committee with executive pay linked to performance. Science‑Based Targets drive a 46.2 % reduction in Scope 1–2 GHG emissions by 2031 and a 20‑point rise in the S&P Global CSA score by 2027, while a 5 % executive pay linkage to ESG outcomes reinforces accountability.
Operationally, MTG targets Scope 1–3 emissions through energy‑efficiency upgrades, renewable procurement and low‑carbon digital services. Climate risks are quantified via IEA/IPCC scenarios, revealing significant temperature rises in India, Israel and Spain but no severe droughts or flooding; indirect Scope 3 emissions dominate the materiality assessment. The company’s 2031 decarbonisation roadmap aligns with EU Fit for 55, and a 40 % GHG cut in scopes 1–2 and 25 % in scope 3 by 2030 is monitored annually against a 2024 baseline.
Human‑capital strategies emphasize flexible work, DE&I, health and safety, and AI‑driven productivity. Annual engagement surveys, performance reviews (93 % participation) and a 22.7 % gender‑pay gap are tracked, with no discrimination incidents reported. Governance frameworks address anti‑corruption, whistleblowing and cyber‑security, while data privacy is upheld through GDPR‑compliant DPIAs, “privacy by design” and age‑gating mechanisms for digital titles.
Geographically, the focus spans Poland with operations in India, Israel and Spain; temporally, the scope covers 2025 with forward‑looking targets to 2031. The statement aligns with CSRD/ESRS requirements, mapping disclosures and ensuring compliance across environmental, social and governance dimensions.
- MTG has committed to a 46.2% reduction in Scope 1–2 greenhouse gas emissions by 2031, with a 2030 target of a 40% cut in Scopes 1–2 and 25% in Scope 3 against a 2024 baseline.
- Executive accountability is reinforced by linking 5% of executive pay to ESG performance outcomes, overseen by a board committee with 29% female representation.
- The company aims to increase its S&P Global CSA score by 20 points by 2027 while aligning its decarbonization roadmap with the EU Fit for 55 framework.
- Materiality assessments indicate that indirect Scope 3 emissions are the primary environmental impact, with climate risk modeling identifying potential temperature rises in India, Israel, and Spain.
- Human capital management includes tracking a 22.7% gender pay gap and maintaining a 93% participation rate in annual performance reviews, with no reported discrimination incidents.
Modern Times Group
Presentation16 pages
AI in MTG: Moving Beyond Theory
The document argues that artificial intelligence has become a strategic asset in mobile game development, transforming every phase of the lifecycle from ideation to live operations. It claims that AI enables teams to prototype, test, and launch content at a fraction of the time previously required, citing examples such as concept‑art generation in days instead of months and single‑person prototype teams that reduce sunk costs. The thesis emphasizes that the combination of trillions of player data points, world‑class creative teams, evergreen intellectual property, and AI as a workflow enabler creates a competitive moat that is difficult to scale for rivals.
Key findings include a 99 % cost reduction in marketing asset creation, an 80 % time saving on influencer spotlights, and a 75 % reduction in analyst turnaround times when querying data through AI agents. The document reports that five new games launched in 2026 adopted an “AI‑first” approach, allowing rapid iteration and simultaneous development of specialized content. It also highlights that AI agents can analyze A/B tests, suggest optimizations, and generate localized UGC‑style assets to lower CPI and improve player engagement.
The scope covers the global mobile gaming market, focusing on mid‑core titles with large player bases. Methodology is implied through internal tooling: 50+ AI platforms (e.g., Claude, Cursor, ComfyUI) and BigQuery‑based agents that process terabytes of data daily. The analysis suggests that AI integration not only accelerates production but also democratizes data insights, freeing analysts to tackle higher‑level strategic questions.
- Adopting an 'AI-first' development approach enabled the launch of five new mobile games in 2026, facilitating rapid iteration and simultaneous production of specialized content.
- AI integration has achieved significant operational efficiencies, including a 99% reduction in marketing asset costs and an 80% time saving on influencer spotlight production.
- Data analysis turnaround times have been reduced by 75% by utilizing AI agents to query large-scale datasets, allowing analysts to focus on high-level strategy.
- AI tools, including Claude, Cursor, and ComfyUI, have transformed production timelines, enabling concept art generation in days rather than months.
- The combination of AI-driven workflows, proprietary player data, and evergreen intellectual property creates a significant competitive moat in the mid-core mobile gaming market.
+2
Modern Times Group
Report57 pages
2026 Live Ops Competitive Intelligence Playbook
Optimizing Live Ops execution requires a disciplined, five-step analytical framework that moves beyond simple feature replication toward strategic, data-backed product decisions. By leveraging competitive intelligence tools to monitor event cadence, mechanics, and performance metrics, developers can effectively benchmark their titles against both direct and aspirational competitors. The primary objective is to transition from viewing individual mechanics as isolated features to implementing a cohesive, multi-layered calendar structure that drives player engagement across short, medium, and long-term horizons.
Across the puzzle, strategy, and casino genres, standard features such as tournaments, milestone rewards, and gacha wheels have become industry table stakes. Maintaining a competitive advantage now depends on the sophisticated sequencing of these events to foster social competition, create artificial urgency, and funnel player spending toward climactic moments. In the 4X strategy sector, successful titles utilize disciplined, multi-week cycles that escalate from solo challenges to server-wide competition. Meanwhile, the casino segment increasingly relies on specialized rolling offers and seasonal cycles to sustain momentum and maximize revenue spikes.
The scope of these strategies extends beyond in-game mechanics to include broader ecosystem shifts, such as the adoption of direct-to-consumer web stores to bypass platform fees and improve margins. Because the gaming landscape evolves rapidly, competitive intelligence must function as an ongoing, iterative process rather than a static assessment. Developers who prioritize a holistic system of player-agency mechanics and continuous monitoring are better positioned to maintain market parity and drive sustainable growth in an increasingly crowded global mobile market.
- In the puzzle genre, milestone rewards are the most frequent event type in 2026, with Tasty Travels launching four such events between March and May 2026.
- Royal Match drives weekend revenue spikes primarily through Live Ops-induced monetization and conversion increases, rather than growth in DAU, downloads, or time spent.
- For casino slot titles, '1+Free' offers generate the highest average release revenue impact, despite 'Rolling Offers' being the most prevalent specialized offer type used by 9 of 12 analyzed games.
- Sprint goal tournaments are the second most trending event mechanic in 2026, with Gossip Harbor and Tasty Travels actively deploying them throughout March and April.
- Merge events have become a key trend in match-swap games, with titles like Royal Match, Matching Story, Piggy Kingdom, and Matchington Mansion adopting the mechanic in 2026.
+4
Sensor TowerMay 2026
Report32 pages
Conversion Drivers in Videogames: Q1 2026
Marketing strategy and community sentiment serve as the primary determinants of conversion performance in the global video game industry as of early 2026. While pricing models like free-to-play and premium structures influence baseline metrics, the efficacy of acquisition campaigns depends more heavily on the alignment between marketing channels and specific player decision-making behaviors. Traditional last-click attribution models frequently undervalue high-funnel awareness efforts, necessitating a shift toward incrementality testing and extended retargeting windows to accurately capture the impact of early-stage engagement.
Player decision cycles vary significantly across industry segments, dictated largely by the social and cooperative dynamics inherent in different genres. Multiplayer and massively multiplayer online titles require longer conversion windows due to the complexity of social coordination, whereas single-player experiences benefit from strategies that emphasize urgency and individual-driven processes. Consequently, marketing efforts for multiplayer games should prioritize social proof and sustained community engagement, while single-player titles gain more traction through direct, time-sensitive calls to action.
Game quality and public perception act as critical multipliers for conversion, particularly within the premium sector. High Steam review scores, specifically those reaching the highest sentiment tiers, can nearly triple conversion rates for premium titles, whereas free-to-play conversion remains largely indifferent to such metrics. Because premium games involve extended evaluation periods, marketers must maintain consistent community-focused sentiment management to protect long-term conversion potential. By tailoring acquisition strategies to these distinct genre-based behaviors and moving beyond simplistic attribution, publishers can better optimize campaign performance and maximize player acquisition efficiency.
- Marketing execution is the primary driver of performance, with conversion rates for F2P games varying by 371x across different ad networks, dwarfing the 35% baseline advantage F2P titles hold over Premium games.
- Last-click attribution models undervalue upper-funnel awareness channels like YouTube, as 50% of the most popular demand-generating ad networks are not effectively captured by last-click metrics.
- Premium games priced above $40 require nearly twice the conversion window of mid-tier titles, and players take 27% longer to convert on Premium titles (141 hours) compared to F2P titles (111 hours).
- Steam review scores significantly impact Premium game performance, where moving from a 'Mixed' to 'Very Positive' rating can nearly triple conversion rates, whereas review scores show no measurable impact on F2P conversion.
- Multiplayer games exhibit longer decision cycles, taking 2.5x longer to convert than single-player titles, with MMO players requiring a median of 49.5 hours to convert compared to 21 hours for shooter players.
+3
GamesightMay 2026

Report57 pages
Digital Market Index: Q1 2026
The global digital economy experienced a significant structural transition during the first quarter of 2026, characterized by a pivot away from traditional mobile gaming toward generative artificial intelligence and short-form entertainment. While global in-app purchase revenue climbed 9.3% to $43.5 billion, this growth was primarily fueled by non-gaming sectors. Mobile gaming faced a notable contraction, with downloads falling 12% year-over-year, even as puzzle titles maintained their status as a primary revenue anchor. Conversely, the generative AI sector surged by 174%, signaling a shift in consumer engagement as users increasingly migrate from web-based interfaces to dedicated mobile applications.
Geographically, the market landscape is bifurcating between mature and emerging economies. The United States market exhibited signs of cooling, recording its lowest revenue growth rate at 3.5%, while India and Indonesia emerged as primary drivers of download volume. Despite the slowdown in U.S. consumer spending, the digital advertising sector remained resilient, growing 15% to $48 billion. This expansion was heavily supported by a 31% increase in software-related ad spend, as advertisers aggressively reallocated budgets from linear television toward targeted digital channels and retail media networks.
Retail media continues to evolve beyond the dominance of Amazon, with platforms like Walmart and Target capturing significant share by leveraging offsite social channels. This trend is particularly pronounced in essential categories such as personal care and food and beverages. As the industry matures, the competitive landscape for generative AI has also become more distributed, with market share spreading across multiple platforms like Gemini and Claude. These findings reflect a broader trend of digital consolidation, where mobile-first engagement and AI-driven utility define the current trajectory of the global digital marketplace.
- Global in-app purchase (IAP) revenue reached $43.5 billion in Q1 2026, marking 9% year-over-year growth and the 13th consecutive quarter of positive performance.
- US digital ad spend grew 15% year-over-year to $48 billion in Q1 2026, with Reddit emerging as the fastest-growing channel at 89% year-over-year growth.
- US mobile IAP revenue growth slowed to an all-time low of 3% year-over-year, recording two consecutive quarters of decline from its $15.1 billion peak.
- Generative AI advertising spend in the US surged to over $430 million in Q1 2026, more than triple the amount spent in Q1 2025, contributing to a 31% year-over-year increase in software ad spend.
- Retail media ad impressions in the US declined 3% year-over-year to 156 billion, driven by a 14% drop in Amazon impressions, even as Amazon maintained over 88 billion impressions and 4x the scale of Walmart.
+3
Sensor TowerMay 2026

Report63 pages
Why Players Play: The Psychology Behind Mobile Games
Mobile game development relies on the strategic alignment of product features with fundamental human psychological drivers to maximize player retention and monetization. By integrating core motivations such as mastery, curiosity, and social connection with defensive psychological triggers like loss aversion and the fear of missing out, developers create highly sticky ecosystems. The primary thesis posits that long-term success in the mobile sector is not merely a product of gameplay quality, but the result of a deliberate, evidence-based architecture that increases the perceived cost of player attrition.
The industry utilizes a sophisticated framework known as the Motivation Wheel to categorize game events and align them with specific business objectives, such as increasing average revenue per user or extending session duration. This approach sequences positive reinforcement—such as visible progress and reward systems—with negative motivators that compel action. By layering these mechanics, developers effectively transform natural session exit points into persistent hooks. Features like battle passes, streaks, and time-limited events leverage the sunk cost fallacy, shifting the player’s primary motivation from intrinsic enjoyment to a defensive necessity to protect accumulated progress.
This analytical approach to game design is prevalent across the global mobile gaming market, focusing on the intersection of behavioral psychology and product management. By systematically engineering these psychological deficits, developers ensure that engagement remains high even after the initial novelty of a game fades. Ultimately, the integration of these mechanics serves to minimize guesswork in product planning, allowing studios to foster deep, long-term player investment through the calculated application of urgency, social pressure, and the psychological weight of digital achievement.
- Social connection is the most effective retention mechanic because it creates a switching cost that prevents players from moving to competitors, as they cannot transfer their clan or community identity.
- Win streaks are the most powerful ARPU-driving mechanic because they simultaneously leverage progress, near-miss tension, loss aversion, urgency, and social pressure.
- Visible progress is essential for casual games; players require concrete proxies like progress maps, star counts, or numerical growth to feel a sense of competence and reward.
- Retention can be extended at natural session 'exit points' by using time-limited boosters or curiosity-driven teasers to convert a sense of completion into a new hook.
- Urgency and FOMO are most effective when the time-limited window is restricted to 5–20% of the total event duration, forcing players to choose between missing out or playing harder.
+3
Sensor TowerMay 2026
Report15 pages
Vietnam Domestic Gaming Industry Report: 2025
The Vietnamese mobile gaming market represents a significant growth sector in Southeast Asia, reaching a valuation of approximately $825 million in 2025. With an estimated 54 to 58.5 million mobile gamers and a year-on-year revenue growth rate of 9.16%, the market is characterized by high engagement, with users averaging 2.5 hours of daily gameplay. The industry is supported by a robust digital infrastructure, serving 79.8 million internet users, and is projected to exceed $1 billion in annual revenue by 2030.
Market performance is dominated by specific genres, with MMORPGs leading at 23.12% of total revenue, followed by team battle and 4X strategy games. Payment ecosystems are heavily localized, with e-wallets, bank transfers, and domestic card schemes—primarily through the NAPAS network—accounting for the vast majority of transactions. This preference for local financial infrastructure necessitates strategic partnerships for international entities seeking to enter the region.
Regulatory compliance remains the most critical barrier to entry for foreign developers. Under Decree No. 147/2024/ND-CP, all game distribution requires a formal license, and foreign companies must operate through a local legal entity or a licensed domestic publisher. Mandatory requirements include strict KYC identity verification, a 180-minute daily playtime limit for minors, and the physical hosting of server systems within Vietnam. Furthermore, upcoming advertising regulations effective in 2026 will mandate shorter, user-friendly ad formats, prompting a shift toward rewarded ads and enhanced in-app purchase strategies. To navigate these complexities, stakeholders are increasingly relying on local advisory and publishing ecosystems to manage licensing, legal documentation, and market-specific operational requirements.
- The Vietnamese mobile gaming market reached $825 million in 2025, growing 9.16% year-on-year with 54 million mobile gamers and 4.9 billion annual downloads.
- Foreign developers cannot publish directly and must partner with a local entity or establish a local office to comply with Decree No. 147/2024/ND-CP, which mandates local server hosting and 100% player KYC via mobile numbers.
- MMORPGs are the dominant revenue driver at 23.12% of the market, followed by Team Battle (17.05%) and 4X Battle (15.05%) genres.
- Payment infrastructure is heavily localized, with 86% of transactions utilizing local schemes and 31% of users preferring e-wallets, while card payments account for 27%.
- New advertising regulations effective February 15, 2026, will restrict ad formats by requiring one-tap close buttons and capping skip-wait times at 5 seconds, forcing a shift toward rewarded ads and IAP-focused monetization.
+1
Ocean Entertainment GroupMay 2026
Report33 pages
State of the LATAM Games Industry 2026
Latin America has solidified its position as a formidable force in the global gaming landscape, transitioning from a peripheral source of cost-effective labor to a sophisticated hub of creative innovation and live service expertise. Driven by massive, mobile-first player populations in Brazil and Mexico, the region is increasingly defined by high levels of community engagement and a thriving esports culture. While economic challenges such as currency volatility and limited infrastructure persist, the industry is successfully pivoting toward sustainable, long-term business models that prioritize authentic, socially integrated experiences over traditional, short-term monetization strategies.
The regional ecosystem is characterized by a strategic shift toward self-publishing and advanced Live Ops, supported by a deep pool of engineering talent that is increasingly utilizing artificial intelligence to enhance production efficiency. Although major hubs like Brazil and Mexico anchor the market, smaller nations such as Argentina and Ecuador are gaining international visibility through indie innovation and strategic global partnerships. This evolution reflects a broader maturation of the industry, where developers are moving beyond simple localization to address the specific technological and cultural nuances of individual domestic markets.
Success within this territory requires a departure from standardized global frameworks in favor of localized strategies that account for unique payment preferences and regional economic constraints. Despite systemic hurdles regarding access to specialized venture capital and user acquisition, the region offers significant growth potential for developers who commit to long-term engagement. By fostering trust and prioritizing accessibility, the Latin American gaming sector is effectively countering the stagnation currently impacting global mobile markets, establishing itself as a vital, influential player in the international creative economy.
- Brazil and Mexico serve as the region's primary anchors, with Brazil driving engagement across all platforms and Mexico acting as a commercial gateway for global publishers.
- Mexico's gaming industry generated $1.27 billion in revenue in 2024, with mobile and tablet devices accounting for 72% of all gaming activity.
- Brazil hosts a robust ecosystem of over 1,000 developers, while indie game creation in Mexico grew by 30% year-over-year in 2023.
- Successful regional studios like Chile-based TinyBytes have achieved significant scale, with over 100 million downloads and $40 million in lifetime gross revenue from titles like Massive Warfare.
- Growth in the LATAM market is frequently driven by localized payment methods, such as PIX in Brazil and OXXO in Mexico, which are essential for reducing friction in price-sensitive, mobile-first economies.
+3
GamesBeatMay 2026
Report6 pages
CESA Game Industry Report 2025: Launch Seminar Report
The CESA Game Industry Report 2025 Launch Seminar, held in Tokyo on February 20, 2026, served as a platform to analyze the evolving landscape of the Japanese gaming sector. The event introduced the updated 2025 industry report, which features expanded data sets and enhanced international market research to better support the global expansion of Japanese firms. The seminar aimed to address industry needs for technical knowledge sharing, talent development, and cross-sector networking among corporate and academic stakeholders.
Key findings highlight a significant shift toward the integration of generative AI, with approximately half of domestic game companies now utilizing these tools within their development pipelines. While internal production workflows show high adoption rates, industry experts noted a more cautious approach regarding AI-generated content visible to end-users. Legal discussions emphasized the importance of navigating copyright frameworks, specifically distinguishing between AI learning and generation phases, while balancing innovation with intellectual property risks.
Government representatives from the Ministry of Economy, Trade and Industry and the Agency for Cultural Affairs outlined strategic support for the content industry, targeting 20 trillion yen in overseas sales by 2033. Policy initiatives focus on multi-year funding, tax incentives, and robust talent development programs to ensure long-term competitiveness. Furthermore, legal experts underscored the increasing complexity of global regulatory environments, noting that Japanese companies must proactively manage diverse international requirements regarding data privacy, monetization, and rating systems. By synthesizing perspectives from government, legal, and development sectors, the seminar emphasized that strategic investment and regulatory compliance are essential for the sustainable growth of Japan’s gaming industry in a globalized market.
- The Japanese government has set a strategic target to reach 20 trillion yen in overseas content industry sales by 2033.
- Approximately 50% of domestic game companies have integrated generative AI into their internal development pipelines.
- Industry adoption of generative AI remains bifurcated, with high usage in production workflows but a cautious, risk-averse approach toward AI-generated content delivered to end-users.
- Legal frameworks are currently prioritizing the distinction between AI learning and generation phases to mitigate intellectual property risks while fostering innovation.
- Government policy initiatives to support industry competitiveness include multi-year funding, tax incentives, and dedicated talent development programs.
CESA – Computer Entertainment Supplier's Association
Report39 pages
Bilan du Marché Français: 2025
The French video game market demonstrated significant resilience in 2025, generating €5.856 billion in total revenue, a 2.9% increase over the previous year. This performance marks the second-highest in the industry’s history, solidifying its position as a cornerstone of the national cultural economy. Growth was primarily fueled by a rebound in console hardware sales and a record-breaking 11% surge in the mobile sector, which reached €1.792 billion. The market maintains a balanced ecosystem, with consoles commanding a 44% share, followed by mobile at 31% and PC gaming at 26%.
Software remains the primary revenue driver, accounting for over two-thirds of the total market. While physical game sales faced a double-digit decline, this was effectively mitigated by the expansion of digital content, including microtransactions and downloadable content. Electronic Arts emerged as the leading publisher across console and PC platforms, while the mobile landscape remains almost entirely dominated by free-to-play models, which now represent 94% of mobile revenue.
The industry’s reach expanded to 40.2 million players, characterized by a maturing demographic where adults comprise 88% of the base. High engagement levels persist, with 76% of players gaming on a weekly basis and a growing trend toward cross-platform usage. Alongside this growth, there is a heightened emphasis on responsible gaming. Parental involvement has reached new heights, with 67% of parents actively monitoring gaming habits through PEGI classifications and standardized parental control tools. This commitment to safety, supported by organizations like the SELL and events such as Paris Games Week, ensures that the industry continues to thrive as a mature, socially responsible, and culturally significant sector within France.
- The French video game market reached €5.856 billion in 2025, a 2.9% year-over-year increase and the second-highest revenue in the industry's history.
- Mobile gaming experienced an 11% surge to reach €1.792 billion, with free-to-play models accounting for 94% of that sector's total revenue.
- Market share is distributed across consoles (44%), mobile (31%), and PC (26%), with software sales—driven by digital content and microtransactions—comprising over two-thirds of total revenue.
- The player base has expanded to 40.2 million people, 88% of whom are adults, with 76% of all players engaging with games on a weekly basis.
- Physical game sales suffered a double-digit decline in 2025, necessitating a shift toward digital distribution and downloadable content strategies.
+3
SELL – Syndicat des Éditeurs de Logiciels de Loisirs
Report9 pages
ESG Fact Sheet: FY 2023/24
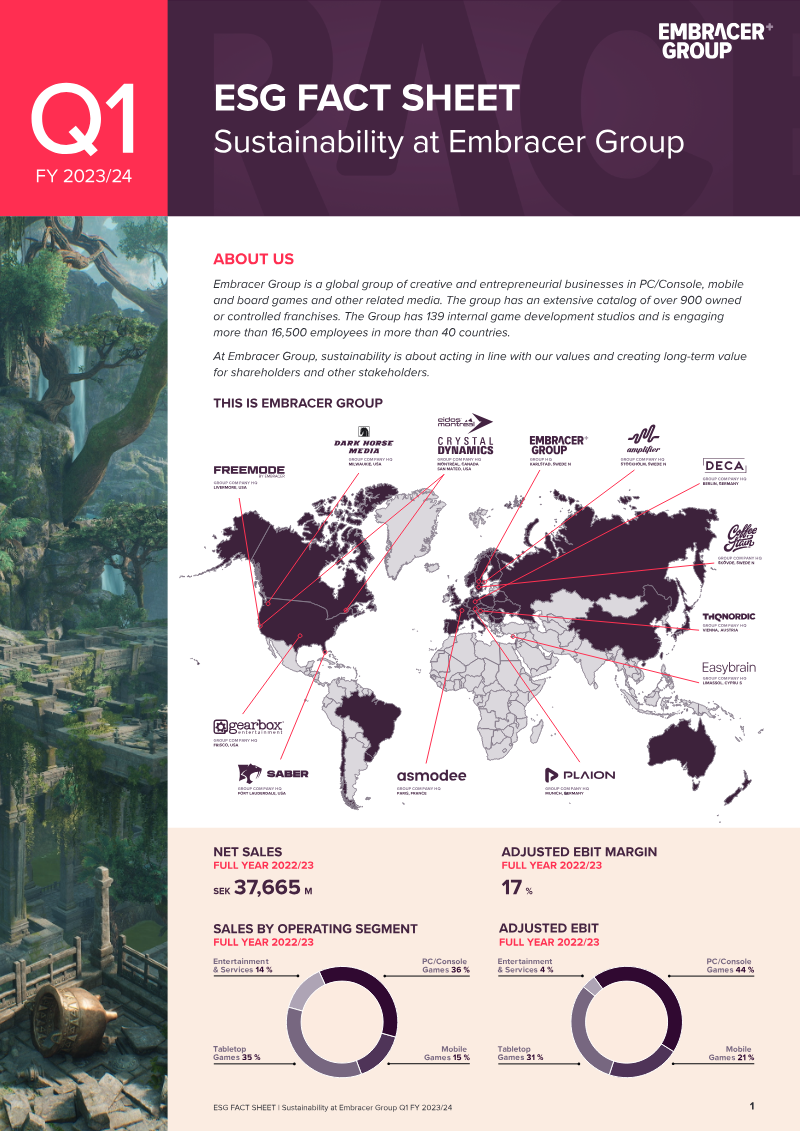
Embracer Group’s FY 2023/24 ESG Fact Sheet outlines the company’s sustainability framework, titled Smarter Business, which focuses on three core pillars: Great People, Solid Work, and Our Planet. Operating across more than 40 countries with 139 internal studios, the organization aims to integrate ethical governance and long-term value creation into its global operations. The company’s sustainability strategy is supported by 16 group policies and 12 guidelines, with oversight provided by the Audit and Sustainability Committee and an internal Ambassador Group.
Key performance indicators for the 2022/23 financial year highlight both progress and areas for development. Within the Great People pillar, the company reported a 26% female representation rate and an employee satisfaction score (eNPS) of +29. To foster leadership diversity, the board has committed to doubling the number of female managing directors and studio heads by 2025. Regarding environmental impact, the company has conducted a comprehensive greenhouse gas inventory, reporting total emissions of 687,102 tCO2e. The firm has aligned its climate strategy with the Paris Agreement, targeting a 45% reduction in carbon emissions by 2030 compared to a 2021/22 baseline.
The company utilizes a structured methodology for tracking progress, including annual global employee surveys and standardized sustainability due diligence during acquisitions. Furthermore, the organization actively participates in industry-wide initiatives such as the UN Global Compact, Women in Games, and PlayCreateGreen. By integrating these partnerships with internal training programs on privacy and ethics, the company seeks to manage operational risks while promoting digital well-being and accessibility across its portfolio of over 900 franchises.
- Embracer Group has committed to a 45% reduction in total carbon emissions by 2030, using the 2021/22 financial year as its baseline.
- The company reported total greenhouse gas emissions of 687,102 tCO2e for the 2022/23 financial year.
- Female representation across the organization stands at 26%, with a board-level mandate to double the number of female managing directors and studio heads by 2025.
- The organization maintains an employee satisfaction score (eNPS) of +29 across its 139 internal studios.
- Sustainability oversight is managed through 16 group policies and 12 guidelines, with governance provided by an Audit and Sustainability Committee and an internal Ambassador Group.
+3
Embracer Group
Report45 pages
Corporate Responsibility Report 2013
Modern Times Group (MTG) maintains a comprehensive corporate responsibility strategy centered on media integrity, employee welfare, environmental stewardship, and ethical business governance. During the 2013 fiscal year, the organization prioritized digital development and the protection of young audiences, achieving recognition in the Dow Jones Sustainability Europe Index. With a workforce of 3,361 employees and net sales reaching 14,129 MSEK, the company leveraged its extensive media reach to contribute over 42 million TSEK in combined financial and media-time donations to charitable causes, most notably through the Reach for Change social entrepreneurship foundation.
Operational performance in 2013 reflected a mix of progress and systemic challenges. Environmental efforts yielded a strong score of 88 out of 100 in the CDP report, supported by energy-efficient infrastructure and carbon disclosure initiatives, despite a 7% rise in total carbon emissions linked to corporate expansion. Internally, the company implemented rigorous anti-bribery policies and updated editorial standards. However, workforce metrics revealed persistent disparities, including a gender pay gap where female remuneration averaged 70% of male earnings, alongside a decline in return-to-work rates following parental leave.
The reporting process, conducted in accordance with GRI G4 Core standards and independently assured by Ethos International, identified customer data integrity and child protection as the most material issues for the business. While the company successfully established a new Corporate Responsibility Advisory Group to oversee governance, auditors noted significant limitations in existing data collection systems. Future strategic objectives focus on harmonizing human resources data, improving supply chain management, and refining internal reporting mechanisms to better track labor and training metrics across the company’s global operations.
- MTG achieved 14,129 MSEK in net sales while contributing 42 million TSEK in financial and media-time donations, primarily through the Reach for Change foundation.
- The company reported a significant gender pay gap in 2013, with female remuneration averaging only 70% of male earnings.
- MTG earned a score of 88 out of 100 in the CDP environmental report, though total carbon emissions increased by 7% due to corporate expansion.
- Materiality assessments identified customer data integrity and child protection as the primary strategic risks for the business.
- The organization maintained a workforce of 3,361 employees while experiencing a decline in return-to-work rates following parental leave.
+1
Modern Times Group
Report13 pages
Modern Responsibility Report 2008
The Modern Times Group (MTG) 2008 Modern Responsibility Report outlines the company’s strategic commitment to integrating social, environmental, and ethical considerations into its international broadcasting and entertainment operations. The primary thesis posits that sustainable and responsible business practices are essential for long-term commercial success and community development. By formalizing its corporate responsibility program, which was originally introduced in 2004, the company seeks to maximize the positive influence of its media platforms while minimizing potential negative societal impacts.
The report covers MTG’s diverse operations across 30 countries, including Scandinavia, the Baltics, Central and Eastern Europe, Africa, and North America. The company’s business segments—Viasat Broadcasting, MTG Radio, Online, and Modern Studios—reach an audience of 125 million viewers and over three million daily radio listeners. Key performance data for 2008 highlights significant charitable engagement, with the company donating 78 million Swedish krona in airtime and helping to raise 56 million Swedish krona for various social causes. Environmental initiatives included the implementation of a strict travel policy, the adoption of energy-efficient office practices, and the calculation of carbon emissions for operations in Scandinavia and the UK, which totaled 4,223 tonnes of CO2.
Methodologically, the report relies on internal data collection, including employee training metrics, carbon footprint calculations based on the Greenhouse Gas Protocol, and stakeholder engagement feedback. The company maintains a workforce of 2,810 employees, with 46% of staff receiving formal training through the internal MTG Academy in 2008. Governance is managed by senior leadership, supported by a central coordinator and local ambassadors, with a newly established committee tasked with overseeing future objectives. The report serves as a foundational disclosure of the company’s commitment to transparency, with plans to expand reporting scope and data collection systems in subsequent years.
- MTG formalized its corporate responsibility program in 2008 to integrate ethical and environmental standards across its broadcasting operations in 30 countries.
- The company reached an audience of 125 million viewers and over three million daily radio listeners through its Viasat Broadcasting, radio, online, and studio segments.
- MTG contributed 78 million Swedish krona in airtime and facilitated the raising of 56 million Swedish krona for various social causes during 2008.
- Carbon emissions for operations in Scandinavia and the UK totaled 4,223 tonnes of CO2, tracked using the Greenhouse Gas Protocol.
- The company employed 2,810 staff members in 2008, with 46% of the workforce completing formal training through the internal MTG Academy.
Modern Times Group
Report52 pages
Modern Responsibility Report 2011
MTG’s 2011 corporate responsibility strategy centers on integrating ethical business practices, environmental stewardship, and social engagement across its operations in 39 countries. By aligning its governance with the Global Reporting Initiative framework and securing a position in the FTSE4Good Index, the company demonstrates a commitment to transparency and high-level sustainability standards. The primary objective is to balance commercial success with a robust social mandate, ensuring that broadcasting and production activities contribute positively to the diverse markets in which the company operates.
Operational performance in 2011 was marked by the successful achievement of 14 out of 15 short-term sustainability goals. Environmental efforts proved particularly effective, as the company exceeded its carbon reduction target by achieving a 6% decrease in emissions per employee through enhanced energy efficiency and facility management. Simultaneously, the company prioritized internal governance by updating anti-bribery and corruption policies and ensuring 100% employee participation in regulatory training. Workforce development was further bolstered by the launch of the Modern People career platform and expanded training through the MTG Academy, which aims to address gender representation in management and foster professional growth.
Social impact remains a core pillar of the company’s mission, evidenced by significant charitable contributions and community-focused programming. In 2011, the company donated 146 million SEK in airtime and raised 37 million SEK for health and welfare initiatives. Beyond financial support, the company utilized its media reach to promote social cohesion through projects like the United for Peace football tournament. Furthermore, the organization maintained a strong focus on consumer protection, particularly regarding child safety in digital and traditional media, while increasing accessibility through expanded subtitling services. These combined efforts reflect a comprehensive approach to corporate citizenship that emphasizes both internal compliance and external community development.
- MTG achieved 14 out of 15 short-term sustainability goals in 2011 while maintaining its position in the FTSE4Good Index and aligning with Global Reporting Initiative standards.
- The company exceeded its carbon reduction target by achieving a 6% decrease in emissions per employee through improved energy efficiency and facility management.
- MTG donated 146 million SEK in airtime and raised 37 million SEK for various health and welfare initiatives during the 2011 fiscal year.
- Internal governance was strengthened by updating anti-bribery and corruption policies and achieving 100% employee participation in regulatory training.
- Workforce development efforts included the launch of the Modern People career platform and expanded training via the MTG Academy to improve gender representation in management.
+1
Modern Times Group
Report24 pages
Modern Responsibility Report 2010
MTG’s 2010 Modern Responsibility initiative establishes a comprehensive framework for integrating economic, environmental, and social accountability across its global media operations. Spanning 33 countries, the company’s strategy centers on four pillars: responsible business conduct, broadcasting integrity, employee relations, and community engagement. By adopting the Global Reporting Initiative framework and conducting a formal materiality analysis, the organization has aligned its internal governance with stakeholder priorities, specifically emphasizing anti-corruption, regulatory compliance, and fair employment practices.
Operational performance in 2010 reflects a dual focus on professional development and social impact. The company invested heavily in human capital through the MTG Academy, which emphasizes leadership and sales training, while simultaneously promoting diversity and female representation in management. Beyond internal operations, the company leveraged its media influence to drive social change, donating 111 million SEK in airtime to charitable causes and launching foundations such as MTG United for Peace and Playing for Change. These efforts underscore a commitment to using broadcasting platforms to support disaster relief, cancer research, and youth development.
Environmental stewardship remains a critical, albeit challenging, area of focus. Total climate impact reached approximately 15,000 tons of CO2e in 2010, driven largely by business travel and facility energy consumption. Despite a 36 percent increase in travel-related emissions, the company has implemented rigorous mitigation strategies, including the adoption of ISO 14001 standards and a mandate to reduce CO2 emissions per employee by 5 percent by early 2012. Through the integration of green training for 59 percent of its staff and the expansion of video conferencing, the organization seeks to balance its international growth with a measurable reduction in its corporate carbon footprint.
- MTG established a 2010 corporate responsibility framework across 33 countries, utilizing the Global Reporting Initiative to prioritize anti-corruption, regulatory compliance, and fair employment.
- The company donated 111 million SEK in airtime to charitable causes in 2010, supporting initiatives like MTG United for Peace and Playing for Change.
- MTG’s total climate impact reached approximately 15,000 tons of CO2e in 2010, with business travel-related emissions increasing by 36 percent.
- To mitigate environmental impact, the company mandated a 5 percent reduction in CO2 emissions per employee by early 2012 and provided green training to 59 percent of its staff.
- Human capital investment in 2010 focused on leadership and sales training through the MTG Academy, alongside efforts to increase female representation in management.
+1
Modern Times Group
Report42 pages
Modern Responsibility Report 2009
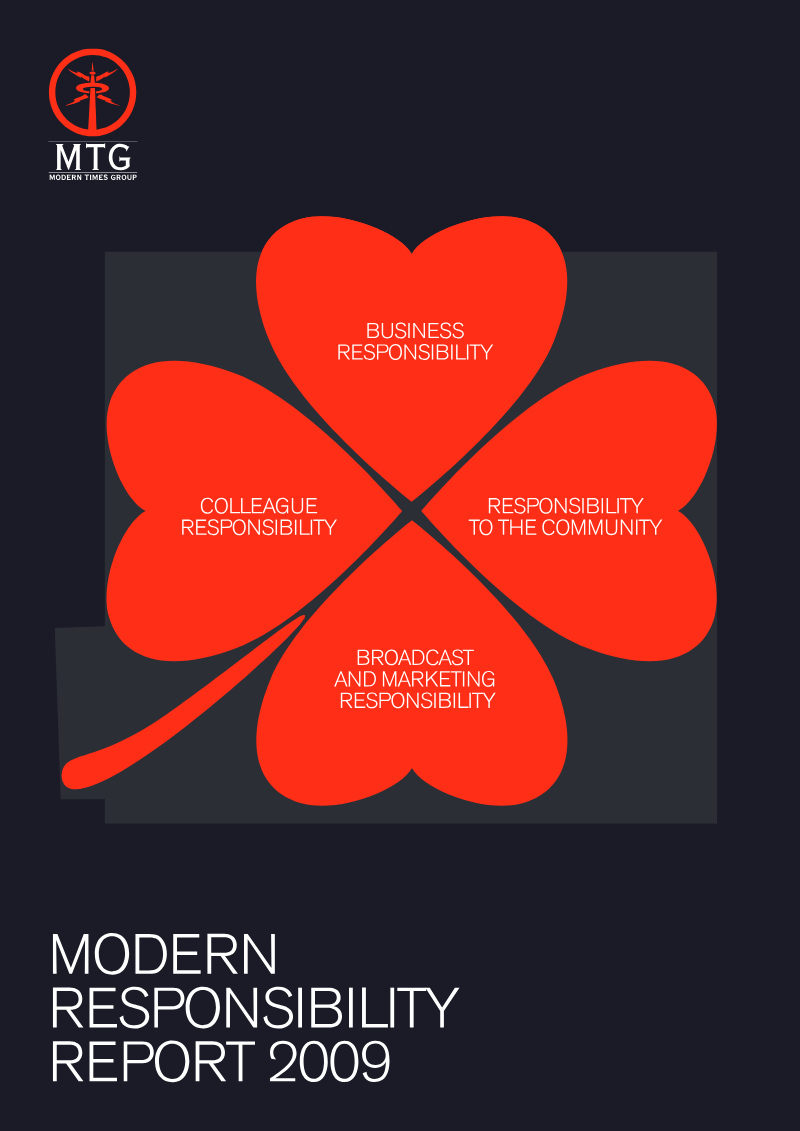
Modern Times Group (MTG) maintains a comprehensive commitment to integrating corporate responsibility into its broadcasting and entertainment operations across 31 countries. The primary objective of its 2009 strategic framework is to ensure sustainable business growth through rigorous governance, ethical conduct, and social accountability. By formalizing environmental policies and establishing a structured oversight committee, the company seeks to balance its commercial objectives with its impact on society and the environment, even amidst the challenging economic climate of the late 2000s.
Operational performance is anchored by a robust governance model that emphasizes transparency, fair competition, and strict adherence to a global code of conduct. Key initiatives include the implementation of a whistleblower policy, mandatory compliance training, and the protection of minors through regulated content and parental controls. The company’s focus on human capital is evidenced by the MTG Academy, which provided training to 81 percent of permanent staff, and a diverse workforce spanning 38 nationalities. These efforts are supported by internal audits and key performance indicators designed to enhance the measurability of ethical and social initiatives.
Environmental stewardship remains a central pillar of the company’s strategy, with carbon footprint audits now covering operations in 19 countries. In 2009, the organization recorded a total climate impact of approximately 13,000 tons of CO2e, prompting investments in energy-efficient infrastructure and reduced travel requirements. Beyond internal reductions, the company leverages its media platforms to drive social change, notably through the "Playing for Change" initiative and the donation of airtime to support environmental and social causes. By aligning its broadcasting reach with philanthropic goals, the company reinforces its position as a responsible stakeholder in the global media landscape.
- MTG established a formal corporate responsibility framework in 2009 to integrate governance, ethical conduct, and social accountability across its broadcasting operations in 31 countries.
- The company recorded a total climate impact of approximately 13,000 tons of CO2e in 2009, leading to the implementation of carbon footprint audits across 19 countries and investments in energy-efficient infrastructure.
- Human capital development was prioritized through the MTG Academy, which provided training to 81 percent of the company's permanent staff.
- MTG maintains a diverse workforce representing 38 nationalities, supported by a governance model that includes mandatory compliance training and a formal whistleblower policy.
- The company utilizes its media reach for philanthropic purposes, specifically through the 'Playing for Change' initiative and the donation of airtime to support social and environmental causes.
+1
Modern Times Group