Peak
GameBy Landcrab
Documents about Peak
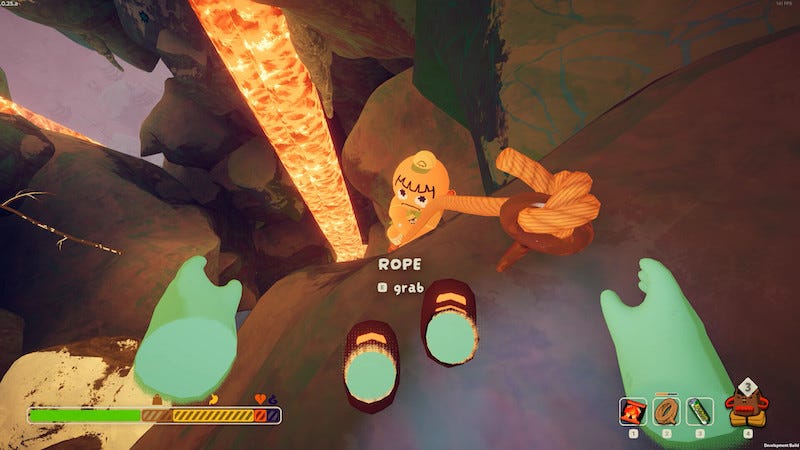
How Peak Sold 4.5m Copies in Less than a Month
The co-op mountain climbing game Peak achieved significant commercial success, selling 4.5 million copies within its first month of release following a June 16, 2025, launch.
- The co-op game Peak sold 4.5 million copies within one month of its June 16, 2025, launch, despite having fewer than 30,000 wishlists pre-release.
- Peak maintained approximately 100,000 daily concurrent users on Steam by leveraging a lean development model focused on a single intuitive mechanic: a damageable stamina bar.
- The game achieved viral growth through high 'watchability' and a strategic $5–$8 price point, prioritizing post-release momentum over traditional pre-release marketing.
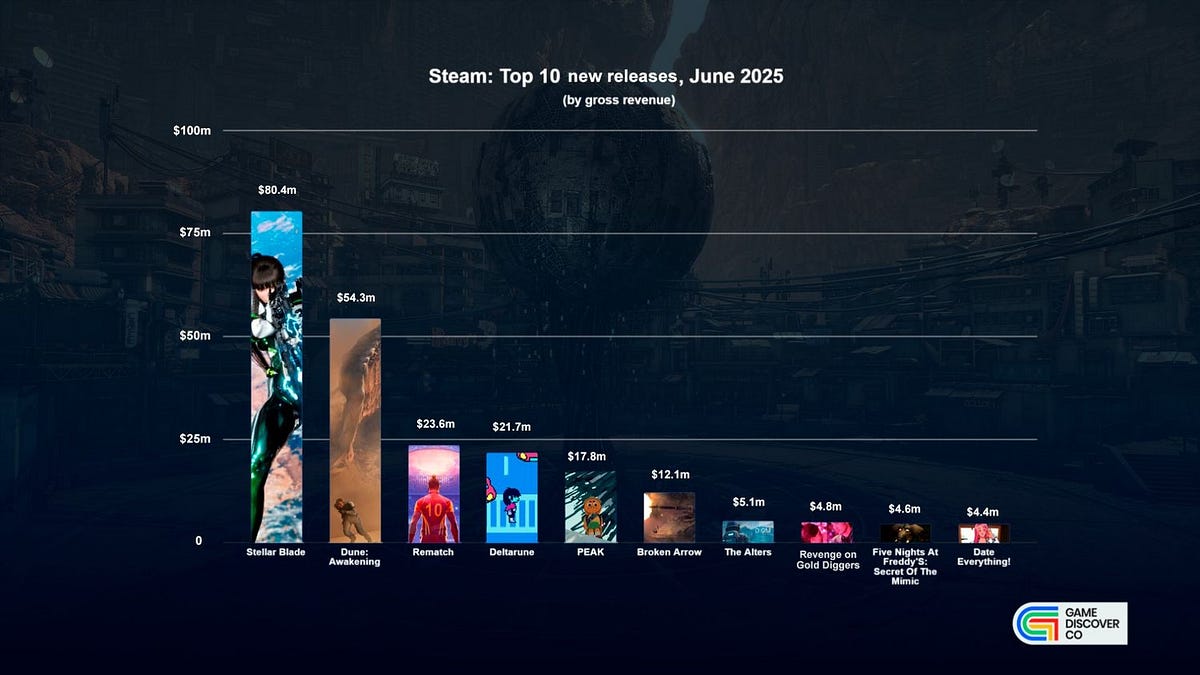
Steam's Top New Games for June 2025
The analysis of Steam’s performance in June 2025 highlights the platform's top-grossing and highest-selling new releases, while providing broader context on industry trends.
- Stellar Blade dominated June 2025 new releases with $80.4 million in gross revenue and a peak of 192,000 concurrent users, bolstered by strong performance in the Chinese market.
- Counter-Strike 2 maintained its position as the platform's top-grossing title, generating an estimated $134 million in monthly revenue.
- The co-op climbing game Peak achieved the highest unit volume among new releases, selling approximately 2.9 million units due to high casual virality.
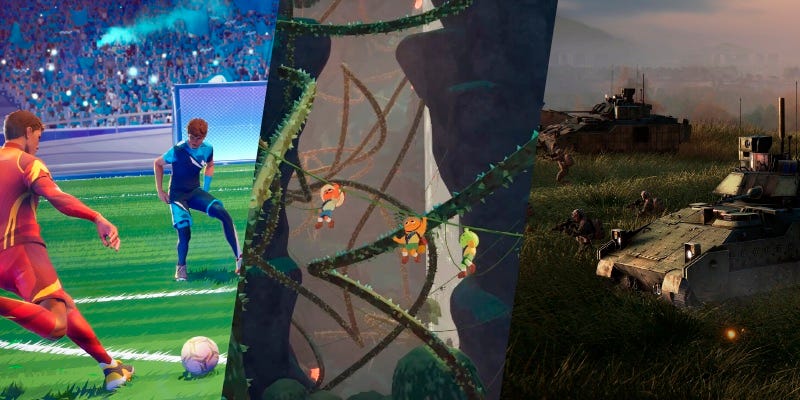
Rematch, Peak, Broken Arrow Top Big Week for Steam Debuts
The gaming industry is currently navigating a period of market stabilization, characterized by a plateau in consumer electronics adoption and a strategic shift toward predictable, long-term revenue streams.
- Sony is pivoting away from an aggressive AAA live-service strategy to focus on franchise engagement and upselling, following the PlayStation 5's generation of $136 billion in revenue and $13 billion in profit.
- PlayStation Plus higher-tier subscriptions grew from 30% to 38% of the total subscriber base between 2022 and 2024, signaling a shift toward more durable, recurring revenue streams.
- Console adoption in the UK has reached 40% and VR penetration stands at 10%, reflecting a mature market phase where no new major hardware form factors have emerged since 2020.
Supercell Investments: A Creative Community or a Missed Opportunity?
Supercell’s recent rebranding of its investment arm, now known as Supercell Investments, serves as the focal point for an analysis of the company’s decade-long venture capital strategy.
- Supercell’s investment arm has failed to act as a strategic growth driver, missing significant opportunities during the 2016–2022 mobile gaming bull market.
- The company has executed only one acquisition, Space Ape, while passing on major industry players such as Peak, Small Giant, and Playrix.
- Supercell’s portfolio of approximately 20 investments is heavily skewed toward early-stage studios, with only three investments directed toward tech infrastructure.
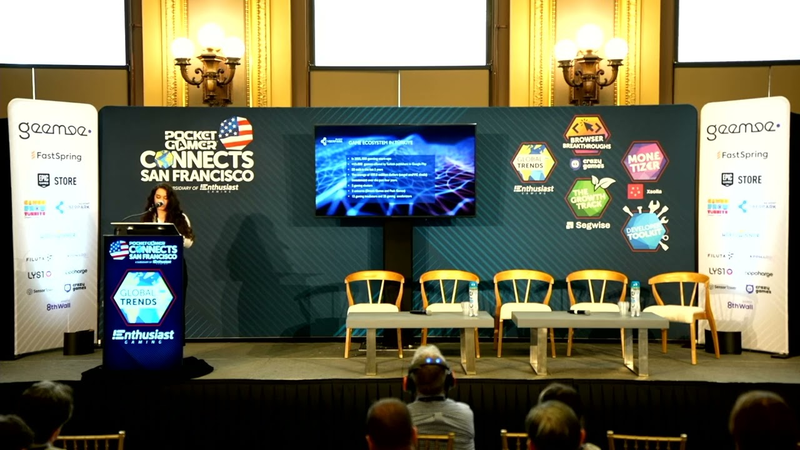
Session: Türkiye’s Game Development Boom – A New Hub For Innovation & Investment - Irmak Tamgac.
The Turkish gaming ecosystem has evolved into a globally competitive hub for innovation and investment, characterized by a self-sustaining cycle of talent development and high-value exits.
- Türkiye’s gaming ecosystem has matured into a global hub, currently hosting over 815 gaming startups and producing more than 13,000 games on Google Play.
- The sector has seen significant high-value exits, most notably Zynga’s acquisition of Peak Games for $1.8 billion in 2020 and subsequent acquisitions of Rollic Games, cementing Türkiye's status as a major player with two gaming unicorns.
- The industry is diversifying beyond its traditional mobile and hyper-casual roots, evidenced by the breakout success of PC titles like 'Liar's Bar' and 'Supermarket Simulator' on Steam.
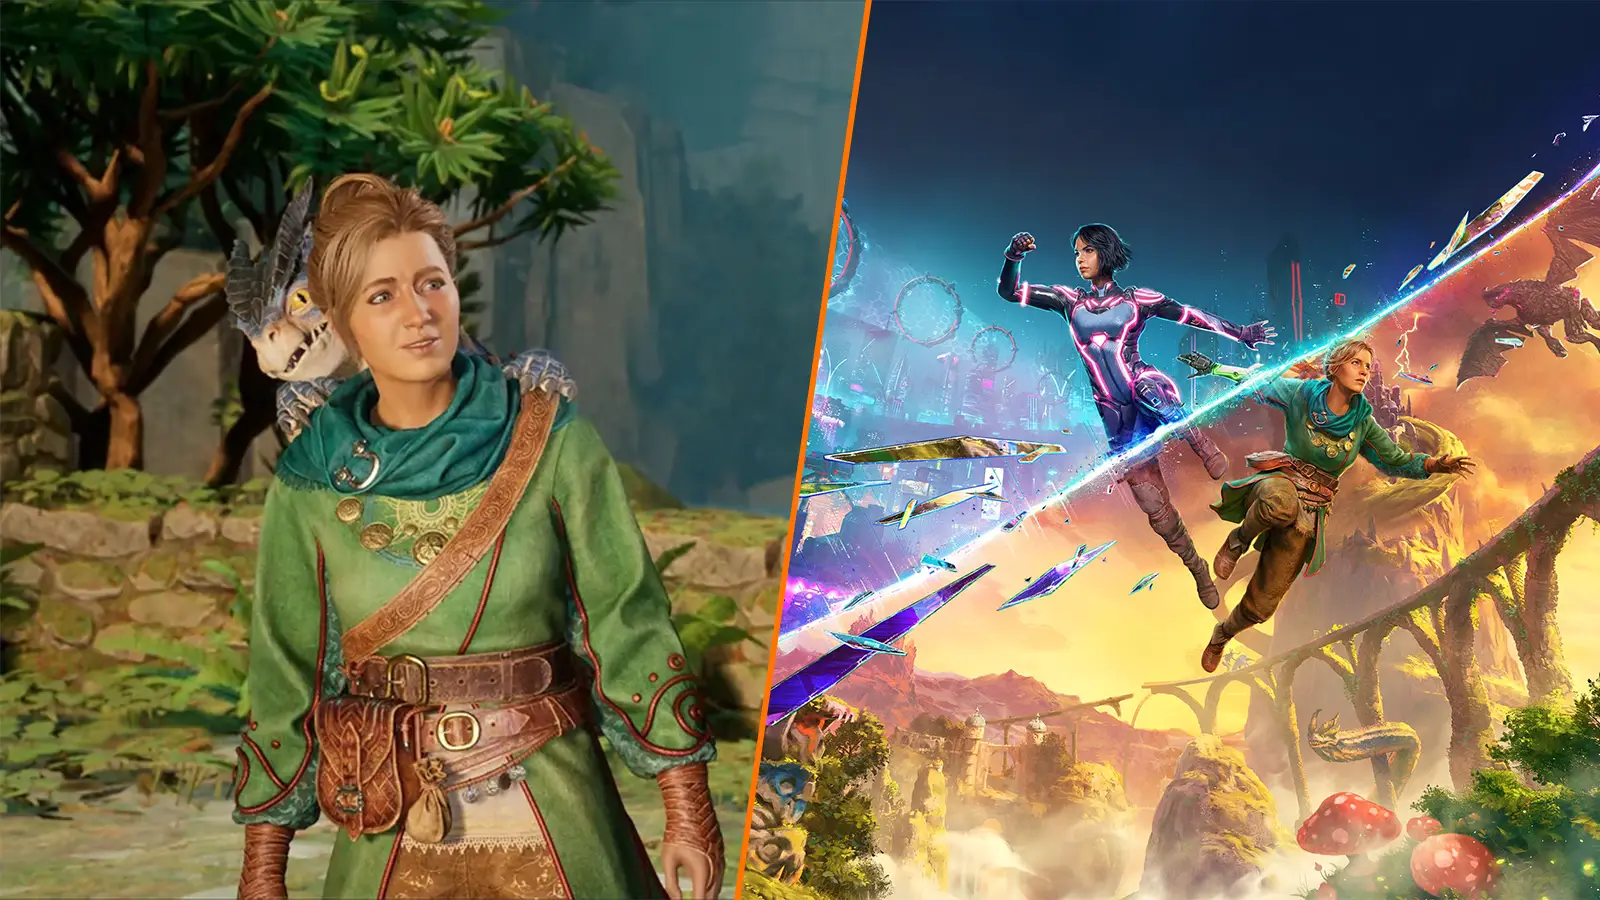
Split Fiction Becomes EA’s Second-Biggest Steam Launch, Triples It Takes Two’s Peak Player Count
Hazelight Studios’ latest co-op title, Split Fiction, has achieved a significant commercial milestone following its March 6, 2025, release on Steam.
- Hazelight Studios' 'Split Fiction' achieved a peak of 254,756 concurrent players on Steam following its March 6, 2025, launch.
- The game ranks as EA's second-biggest Steam launch of all time, trailing only the free-to-play title Apex Legends.
- Split Fiction's peak player count is more than triple the 71,039 record set by the developer's previous title, It Takes Two.
Five Years of the Rising Gaming Empire: Turkiye
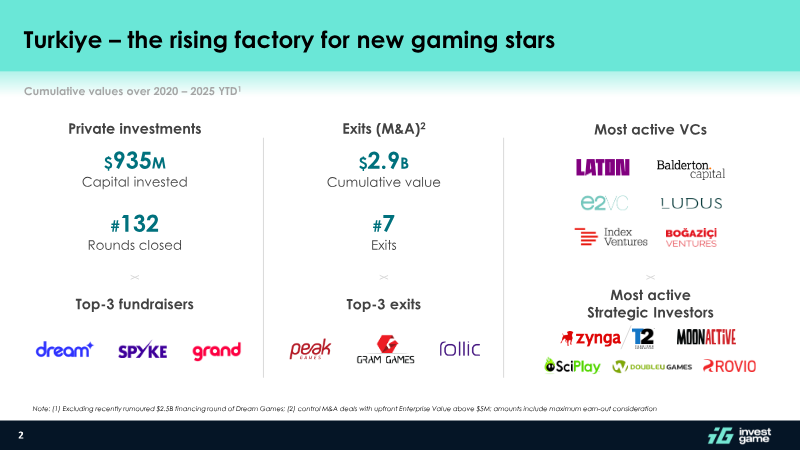
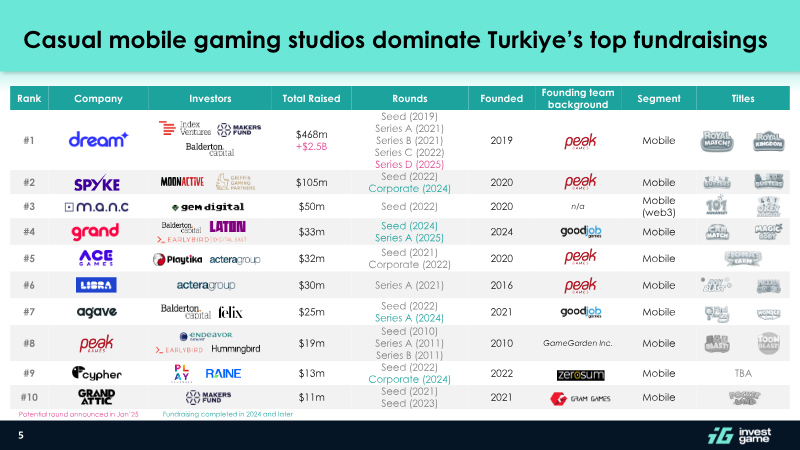
Turkiye has emerged as a significant global hub for game development, characterized by a rapid surge in entrepreneurship and capital investment over the last five years.
- Turkiye’s gaming sector generated $2.9 billion in cumulative M&A exit value between 2020 and 2025, driven by major acquisitions like Peak Games ($2.1 billion) and Gram Games ($250 million).
- The ecosystem secured $935 million in private investment across 132 rounds from 2020 to early 2025, representing 5.8% of global gaming venture capital and corporate deal volume.
- Investment activity peaked in 2022 with $441 million raised, establishing a trend of high-value fundraising for mobile-focused studios such as Dream Games.


Mobile Gaming M&A Playbook: How to Identify and Target High‑Growth Gaming Companies
The playbook outlines a systematic approach for mobile gaming publishers and investors to identify, evaluate, and acquire high-growth developers.
- The mobile gaming market is projected to reach $138 billion by 2025, driving significant M&A activity as publishers seek to diversify portfolios and acquire new talent and intellectual property.
- High-profile acquisitions demonstrate the scale of industry consolidation, including Zynga’s $2 billion purchase of Peak Games and EA’s $2.1 billion acquisition of Glu Mobile.
- Effective target identification requires a data-driven approach using platforms like Sensor Tower to track specific genre trends, revenue trajectories, and regional market share.
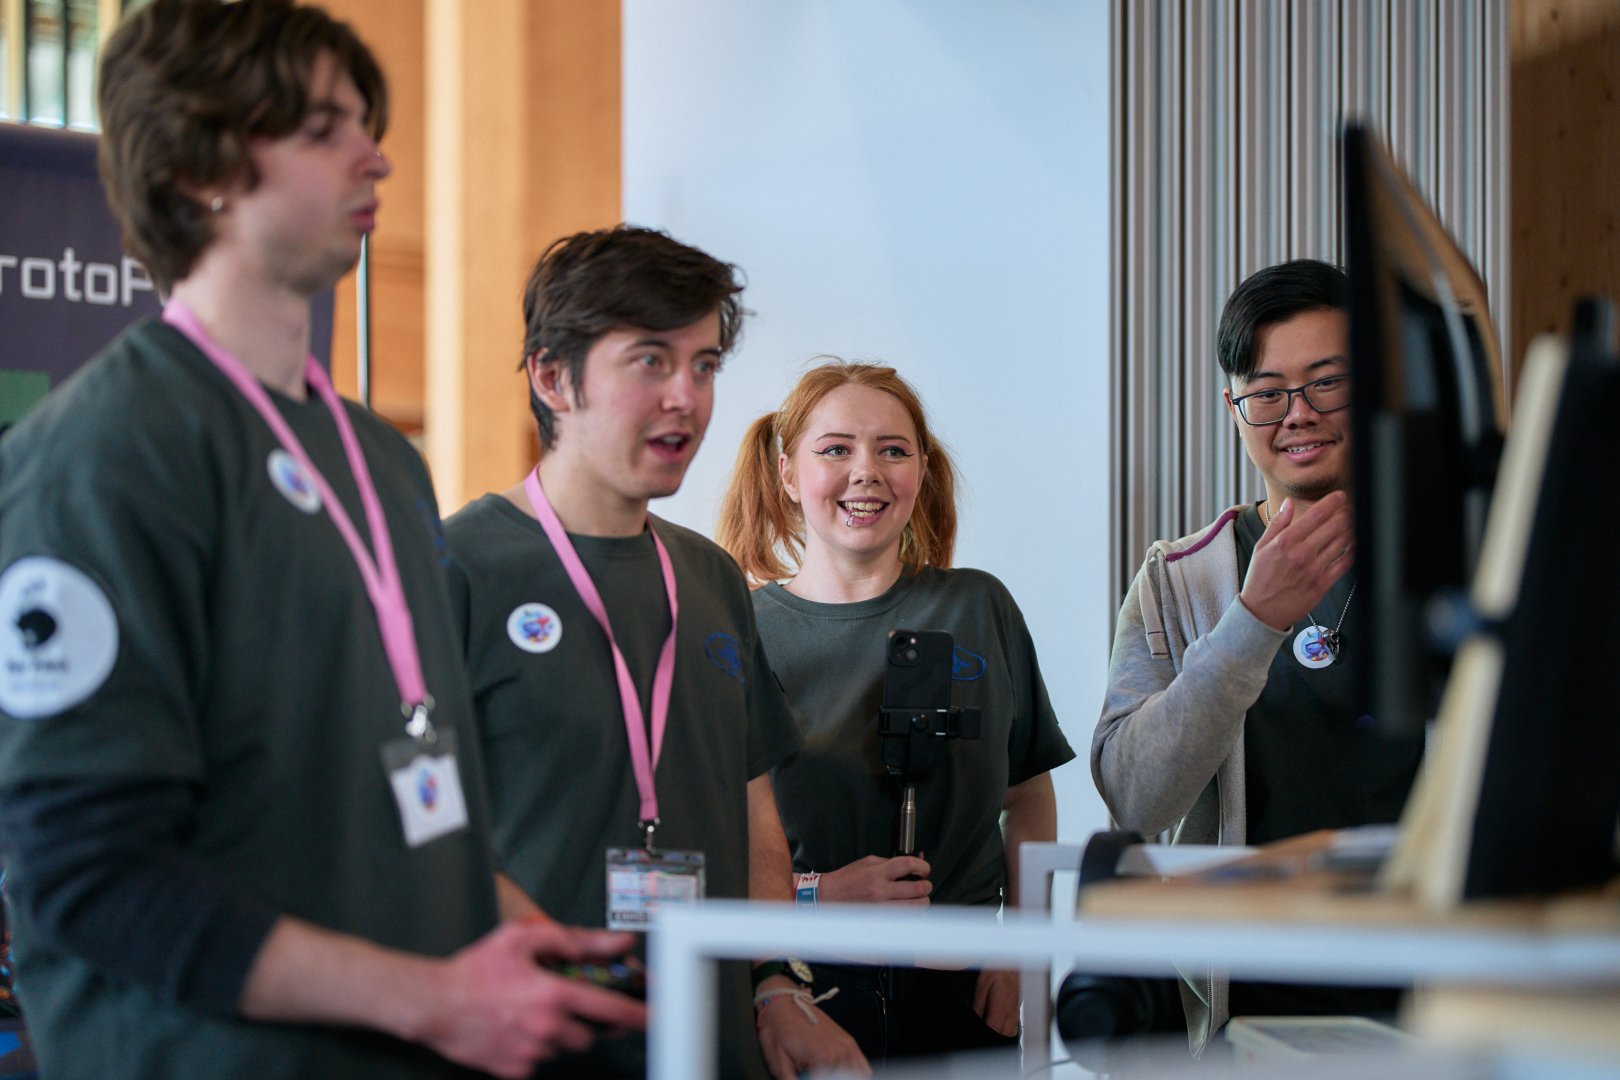
A Year in Review: 2024
The 2024 annual review for the UK Games Fund highlights a year of significant growth and operational success within the UK’s early-stage games development ecosystem.
- The UK Games Fund operates a tiered grant structure, including a Content Fund offering up to £150,000 to support growth-oriented studios and a Prototype Fund for early-stage projects.
- The 2024 Tranzfuser programme saw a record-breaking number of applications, resulting in the selection of 19 graduate-led teams for the summer-long initiative.
- From the 2024 Tranzfuser cohort, four teams received direct funding for commercial game development, while three teams were selected for the 2025 DunDev residential programme.
Top Casual Games Publishers of 2024
The mobile gaming landscape in 2024 remains dominated by the casual games segment, with Scopely emerging as the leading publisher by net in-app purchase revenue.
- Scopely emerged as the top casual games publisher by net in-app purchase revenue in 2024, generating $1.63 billion between January and November.
- Playrix ($1.53 billion), King ($1.28 billion), and Dream Games ($1.25 billion) followed Scopely to round out the top four highest-earning casual publishers.
- The success of 'Monopoly Go!' was the primary driver for Scopely's top ranking, with the title having grossed over $3 billion globally to date.
TWIG #310 Can Royal Kingdom Reach the Peak? Who Wins the War of the You Giants?
The gaming industry is currently navigating a period of strategic recalibration, characterized by a shift toward iterative product development and the struggle to translate traditional intellectual property into digital success.
- Subscription models like Microsoft’s Game Pass are currently functioning as loyalty programs for existing users rather than effective engines for new market acquisition.
- Mobile developers are shifting toward iterative product development, exemplified by Royal Kingdom’s attempt to evolve the match-three genre through midcore-lite mechanics and intensified content treadmills.
- The gaming industry is facing significant operational friction, specifically regarding the difficulty of maintaining mentorship and team cohesion within hybrid work environments.
The Streaming Stats Behind Influencer Marketing
Effective influencer marketing in the live-streaming sector requires navigating a vast landscape of data to identify meaningful insights rather than mere noise.
- Effective influencer marketing requires moving beyond simple viewership counts to analyze five core data categories: Viewership, Coverage, Fanbase, Cost-Benefit, and Chat Analysis.
- Unique Registered Viewers (URVs) provide a more accurate measure of audience size than raw viewership by eliminating double-counting of users across multiple streams.
- Aggregated Peak Viewership is a critical metric for multi-platform campaigns, such as the launch of the Silent Hill 2 Remake, as it accounts for regional distribution and platform-specific release timing.
Companies behind it
As the documents state it.