Peak
GameBy Landcrab
Documents about Peak
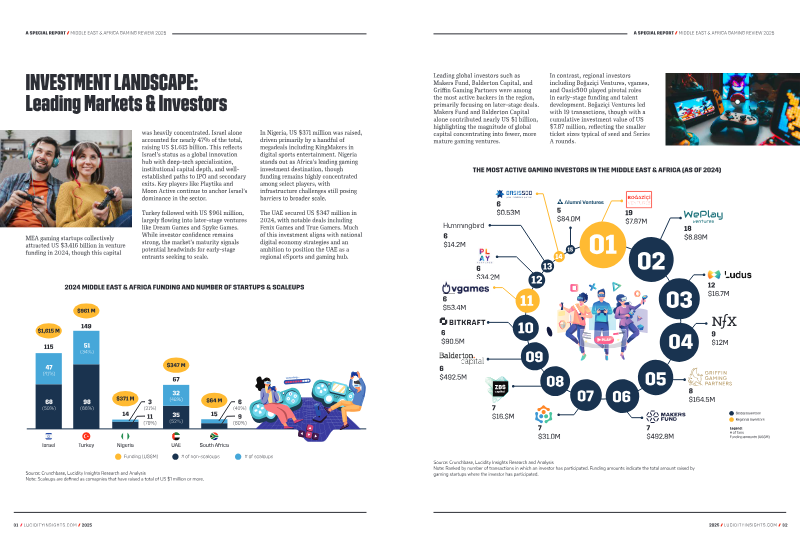
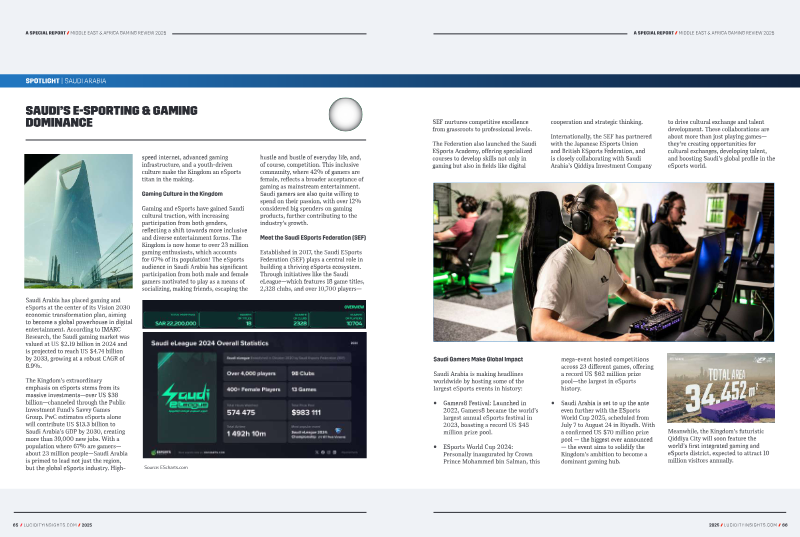
Middle East & Africa Gaming Review 2025
The Middle East and Africa gaming landscape is poised for rapid expansion, with market value projected to rise from US $7.4 billion in 2024 to over US $19.4 billion by 2033, reflecting an 11% CAGR driven largely by mobile-first adoption and a vibrant startup ecosystem.
- The Middle East and Africa gaming market is projected to grow from $7.4 billion in 2024 to over $19.4 billion by 2033, representing an 11% CAGR driven by mobile-first adoption.
- Investment is highly concentrated, with Israel leading at nearly $1 billion raised across 146 startups, followed by Turkey at $961 million and Nigeria at $371 million.
- Turkey has established itself as a 'unicorn factory' through major deals, including Peak Games’ $1.8 billion acquisition and Dream Games’ $2.6 billion capital raise.
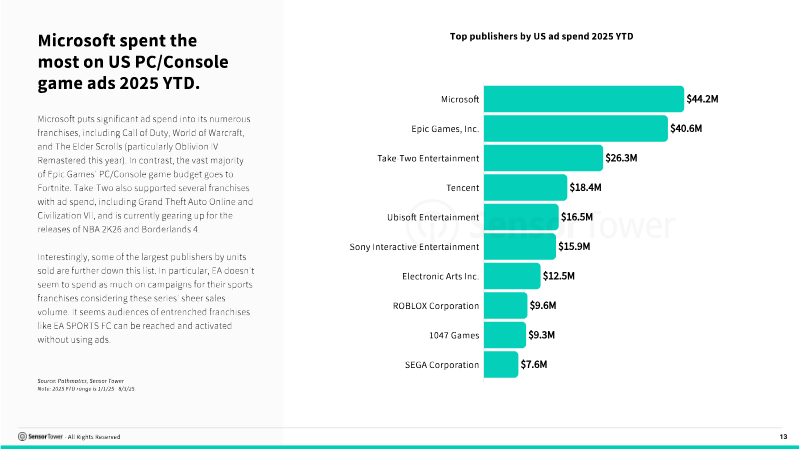
PC/Console Gaming Index: 2025
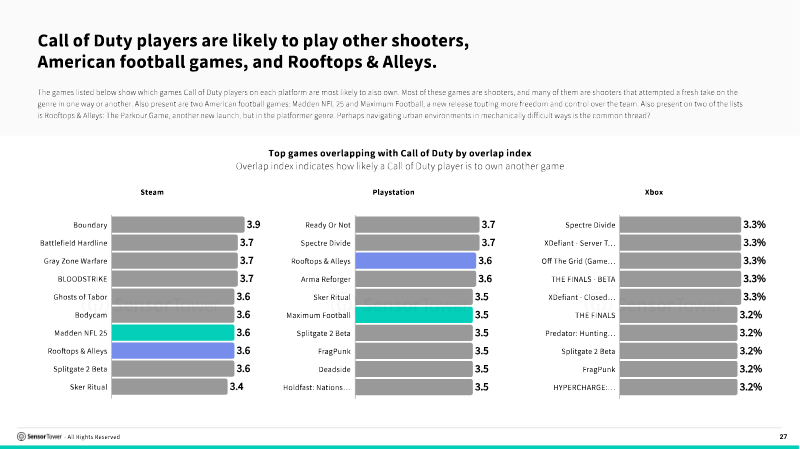
The 2025 PC/Console Gaming Index demonstrates that action titles dominate the market, with approximately 262 million downloads year-to-date.
- Steam remains the dominant platform for PC/console gaming, generating approximately 450 million downloads year-to-date, which is nearly four times the volume of PlayStation.
- Monetization strategies are platform-specific: 79% of Steam downloads and 83% of PlayStation downloads are premium, while 39% of Xbox downloads are free-to-play, largely driven by Game Pass.
- Indie and AA developers drive the majority of the 262 million action-genre downloads, with indie titles accounting for 60% of total downloads on Steam.


Mobile Gaming M&A Playbook: How to Identify and Target High‑Growth Gaming Companies
The playbook outlines a systematic approach for mobile gaming publishers and investors to identify, evaluate, and acquire high-growth developers.
- The mobile gaming market is projected to reach $138 billion by 2025, driving significant M&A activity as publishers seek to diversify portfolios and acquire new talent and intellectual property.
- High-profile acquisitions demonstrate the scale of industry consolidation, including Zynga’s $2 billion purchase of Peak Games and EA’s $2.1 billion acquisition of Glu Mobile.
- Effective target identification requires a data-driven approach using platforms like Sensor Tower to track specific genre trends, revenue trajectories, and regional market share.
Q2'24 Gaming Deals Report: Gradual Recovery
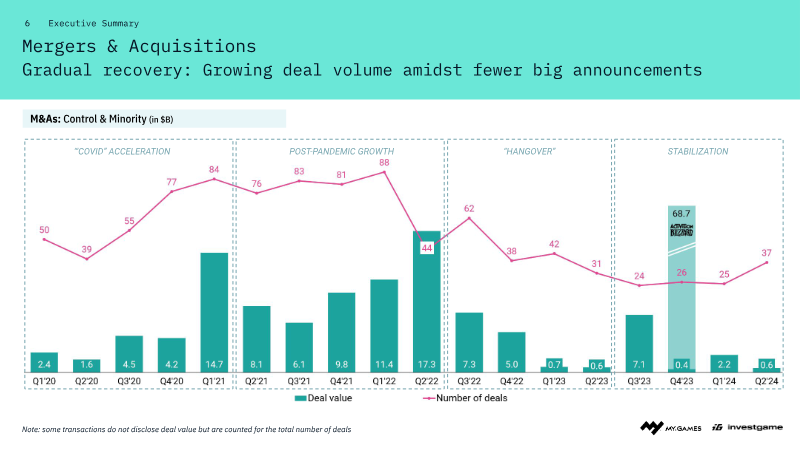
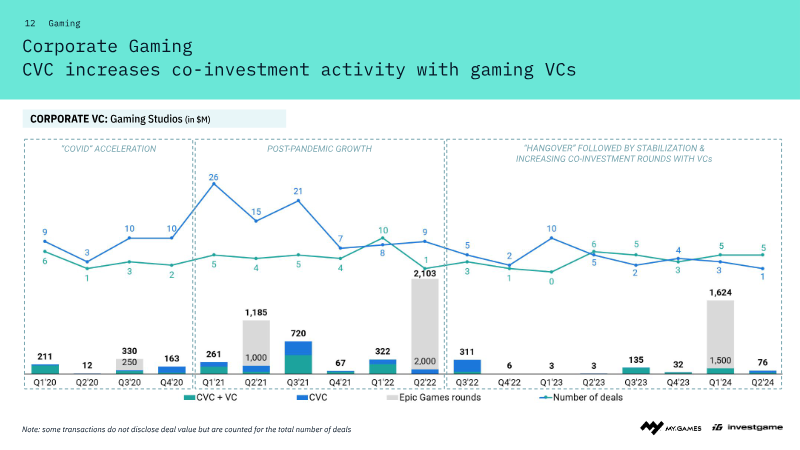
The second quarter of 2024 gaming industry analysis highlights a period of sustained activity in early-stage venture capital and a growing market for independent and mid-sized titles.
- Steam full-game sales grew 27% year-over-year in Q2 2024, driven primarily by strong performance from independent and mid-sized titles.
- Asia led global early-stage investment with $320 million across 28 deals, while North America dominated late-stage venture capital with $239 million across seven deals.
- BITKRAFT was the most active early-stage investor by volume with 18 rounds, while a16z Games led in total deal value with $124 million invested.
Mobile Game Market Review: November 2023
This market review analyzes mobile gaming trends and performance for November 2023, focusing on the United States and Chinese markets.
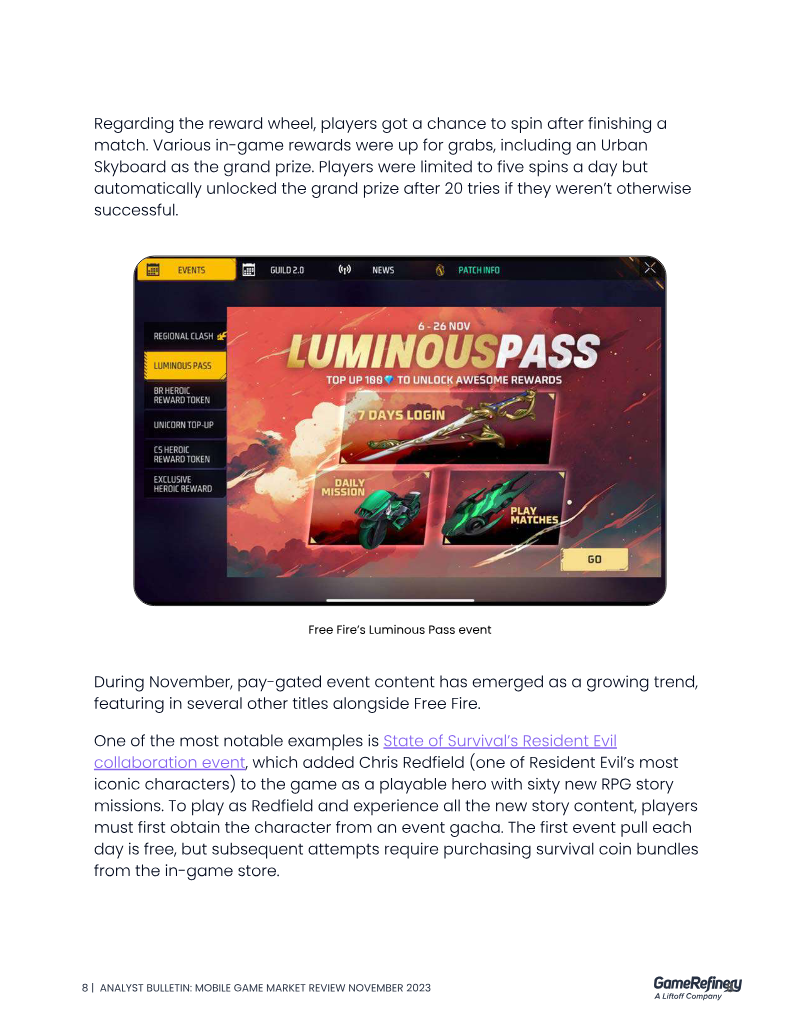
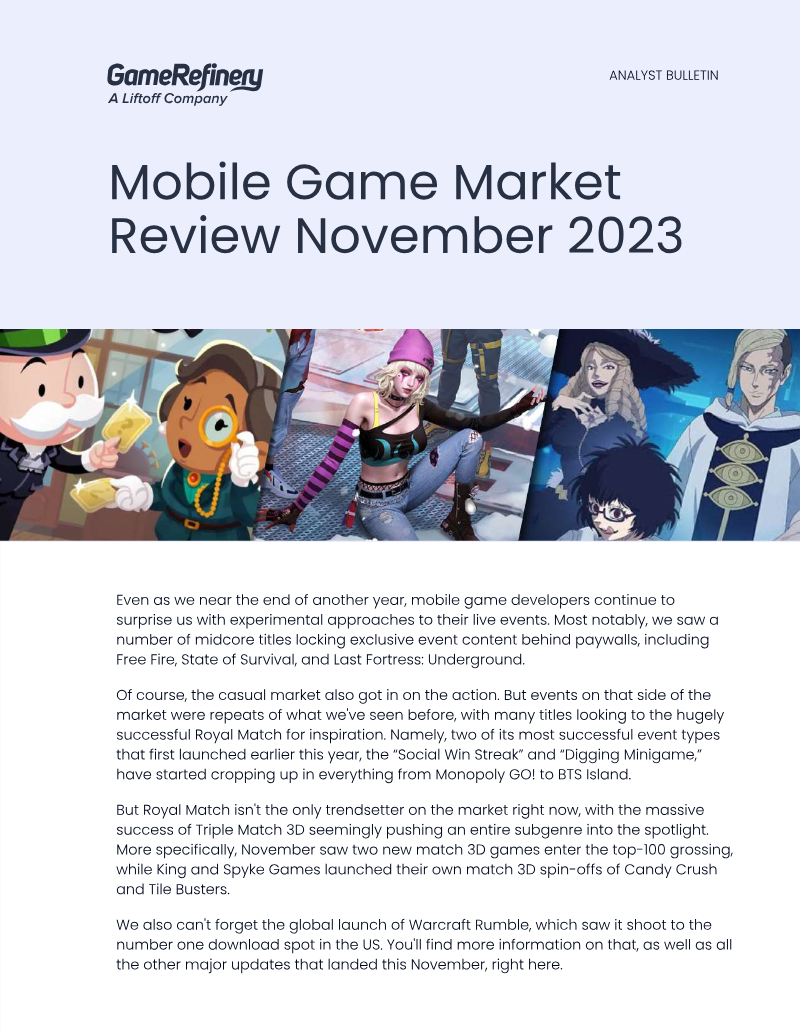
- Midcore mobile titles are increasingly gating core event gameplay and story missions behind paywalls, as seen in Free Fire’s Luminous Pass and State of Survival’s Resident Evil collaboration.
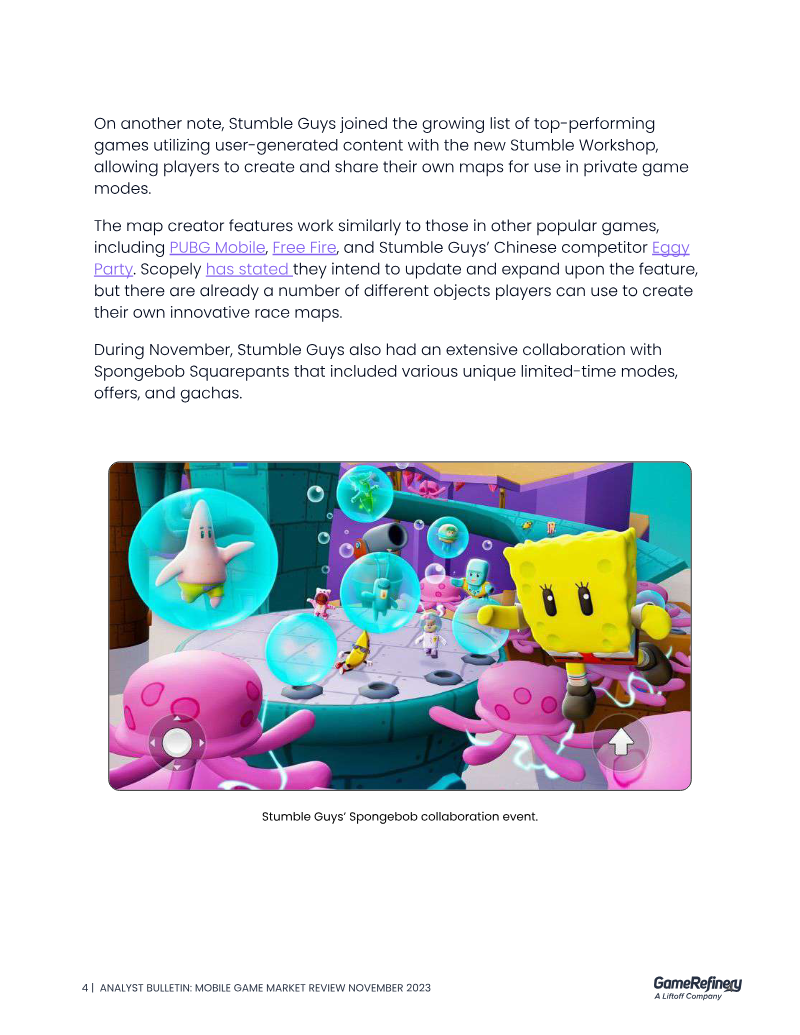
- The casual gaming sector is experiencing widespread mechanical imitation, specifically the adoption of 'Social Win Streak' and 'Digging Minigame' features by major titles like Monopoly GO! and Matchington Mansion.
- The 3D match subgenre is seeing rapid expansion and increased competition from industry leaders, with King and Peak launching Candy Crush 3D and Match Factory to challenge the success of Triple Match 3D.
Peak Play: Trends in East Asian Videogame Streaming H1 2023
The East Asian videogame livestreaming market is a mature and culturally distinct ecosystem where competitive esports serve as the primary engine for audience engagement.
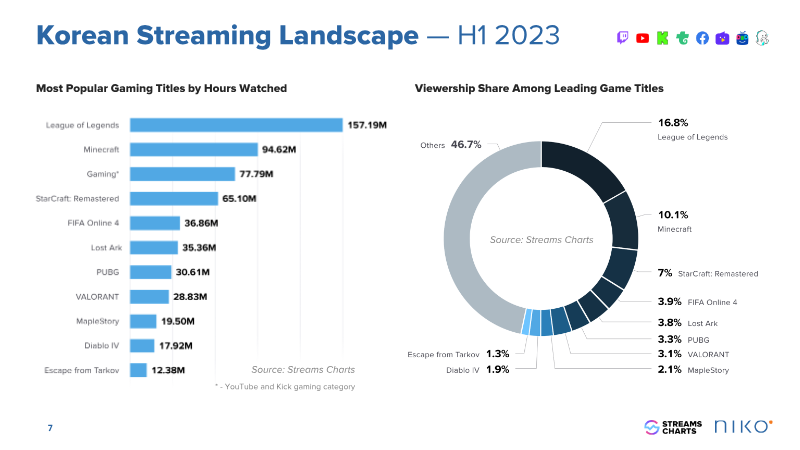
- Competitive esports, specifically MOBA and Battle Royale titles, drive over 50% of total viewership in the East Asian streaming market.
- Honor of Kings remains the dominant force in China with 5.67 billion views, while VALORANT and Apex Legends lead in Japan and Korea with over 100 million hours watched each.
- Key Opinion Leaders and VTubers are significant market drivers, contributing up to 15% of total viewership for major titles and successfully revitalizing older games.
Investment Activity Report Q1–Q3 2020
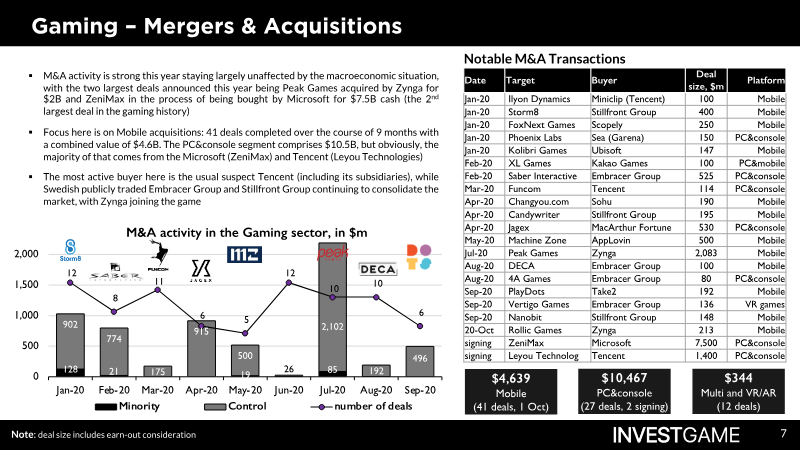
The report documents investment activity in the global gaming industry from January to September 2020, covering mobile, PC & console, multiplatform, VR/AR, cloud-native and esports segments.
- The global gaming industry saw $27.5 billion in total deal value across 1,000 transactions during the first nine months of 2020, with gaming-specific deals accounting for $15.3 billion.
- M&A activity was defined by large-scale consolidation, led by Microsoft’s $7.5 billion acquisition of ZeniMax and Zynga’s $2 billion purchase of Peak Games, with Tencent, Zynga, and Microsoft collectively exceeding $11 billion in deal value.
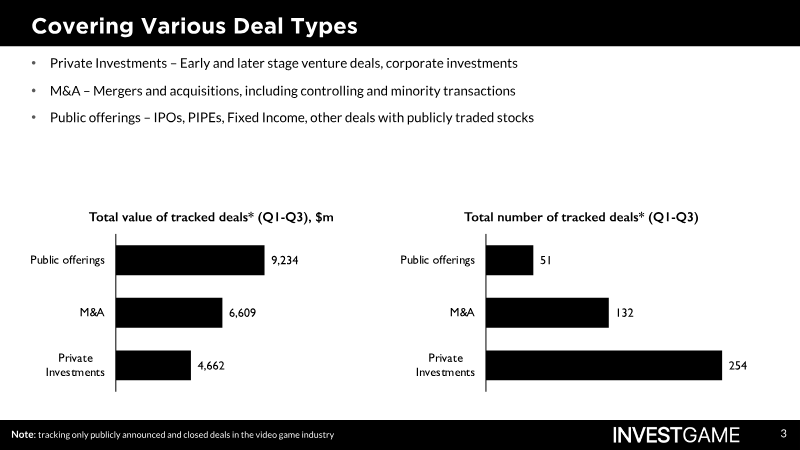
- Public offerings were the primary driver of capital, generating $9.2 billion from 51 IPOs and PIPEs, while private venture investments contributed $4.7 billion across 254 rounds.
Companies behind it
As the documents state it.