Activision
CompanyUnited States
Documents about Activision
Global Gaming Report Q1 2022
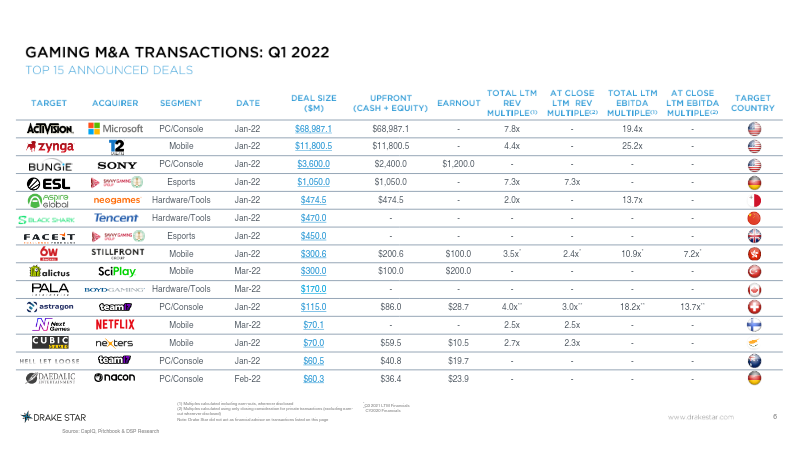
The global gaming industry experienced a historic surge in financial activity during the first quarter of 2022, recording a record-breaking $98.7 billion in total deal value.
- The global gaming industry reached a record $98.7 billion in total deal value in Q1 2022, surpassing the total deal value of the entire previous year.
- Industry consolidation was driven by major acquisitions, including Microsoft’s $68.9 billion purchase of Activision Blizzard and Take-Two’s $11.8 billion acquisition of Zynga.
- Strategic M&A activity is currently focused on cross-platform diversification, with PC and console giants aggressively acquiring mobile gaming expertise and established intellectual property.
Gaming Deals Activity Report: Q1–Q3 2022
The gaming investment landscape in the first three quarters of 2022 reflects a significant market correction following a record-breaking 2021.
- The $124.5 billion total deal value for Q1–Q3 2022 is heavily skewed by Microsoft’s $69 billion acquisition of Activision Blizzard, masking a broader market cooling driven by macroeconomic instability and regulatory pressure.
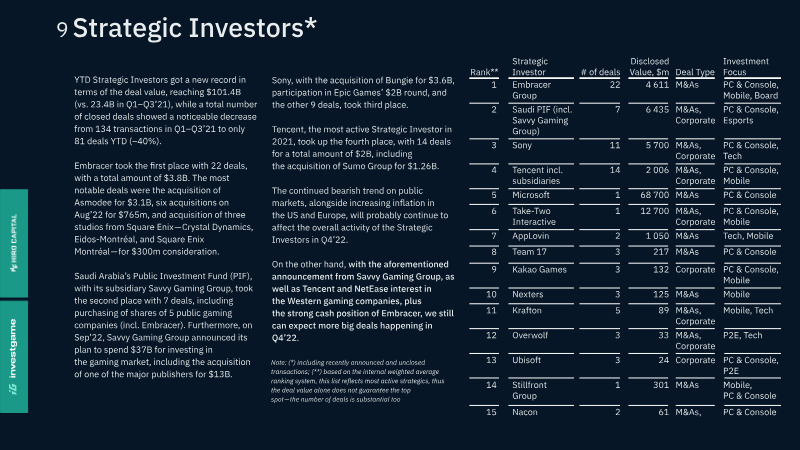
- Strategic M&A activity reached a record $101.4 billion despite a 40% decline in the number of closed transactions, with major activity led by Embracer Group, Sony, and Saudi Arabia’s Public Investment Fund.
- Public offerings have nearly collapsed to their lowest point since early 2020, with deal values shrinking fivefold compared to 2021 levels.
Casual Puzzle Category Review 2021
The casual puzzle market experienced a period of significant expansion and structural transformation between 2020 and mid-2021, characterized by a 17% increase in monthly revenue and a surge in successful new releases.
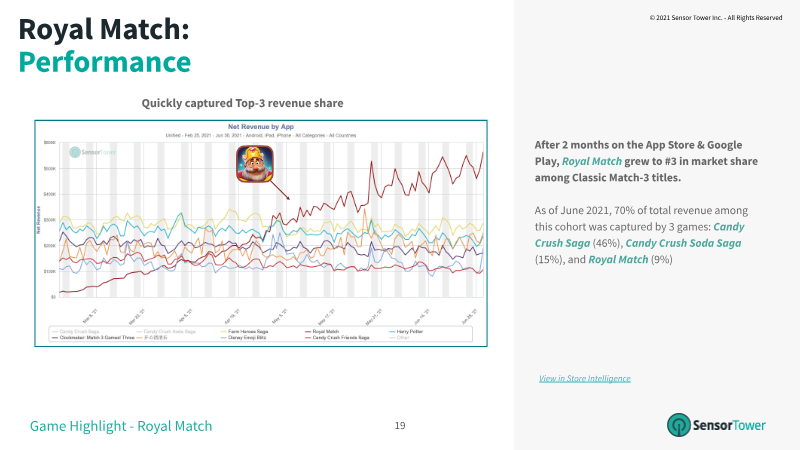
- The Puzzle & Decorate sub-genre has overtaken Classic Match-3 as the primary revenue driver, led by titles like Project Makeover and Royal Match that utilize narrative-driven 3D customization.
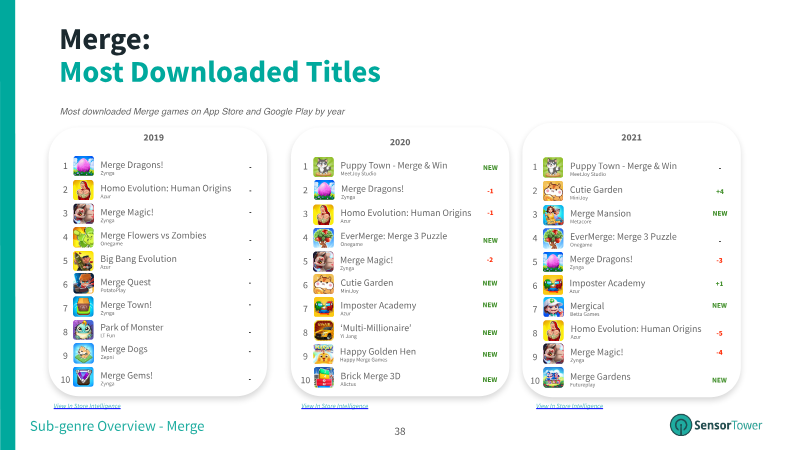
- The Merge sub-genre is the fastest-growing segment, achieving a 498% four-year compound annual growth rate and a 44% revenue increase over 18 months.
- Market consolidation remains high in the Puzzle & Decorate segment, where Playrix and AppLovin control 88% of total downloads and revenue.
French Market Report: 2019
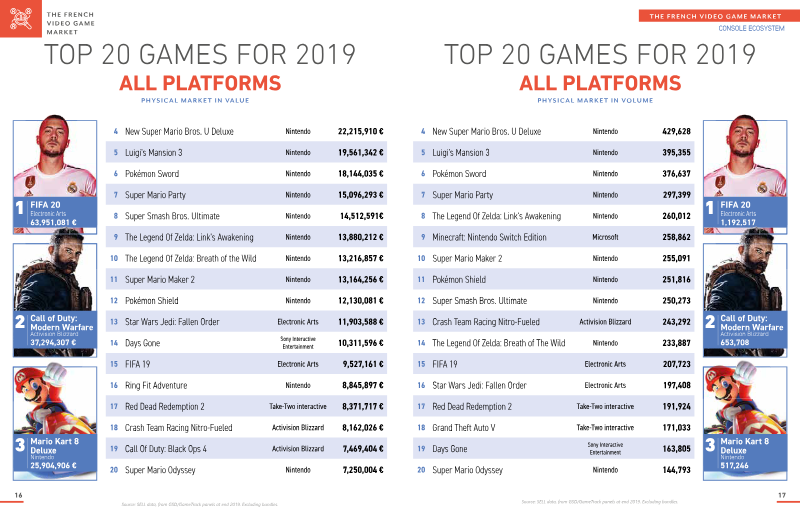
The French video game market achieved a total turnover of 4.8 billion euros in 2019, reflecting a mature and deeply integrated entertainment sector.
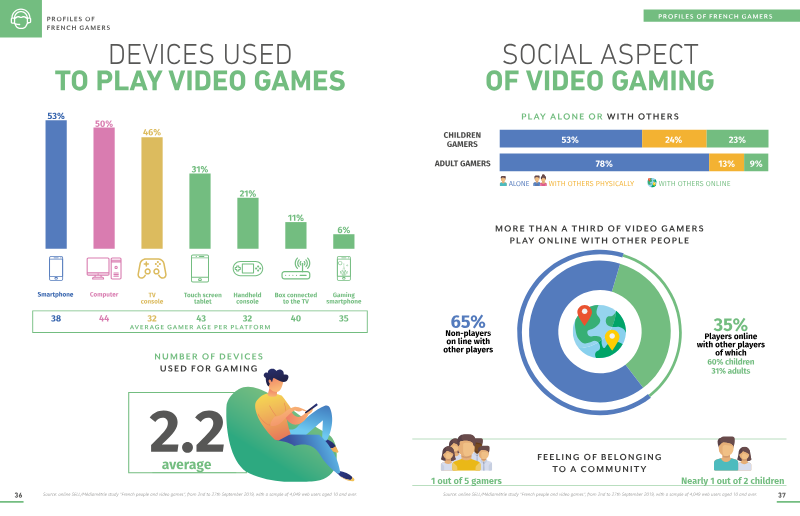
- The French video game market reached a total turnover of 4.8 billion euros in 2019, driven by strong software performance despite a contraction in hardware sales.
- Gaming is a mainstream activity in France, with 71 percent of the population participating and an average player age of 40.
- Mobile gaming is a primary engine for industry growth and engagement, led by titles such as Mario Kart Tour and Clash of Clans.
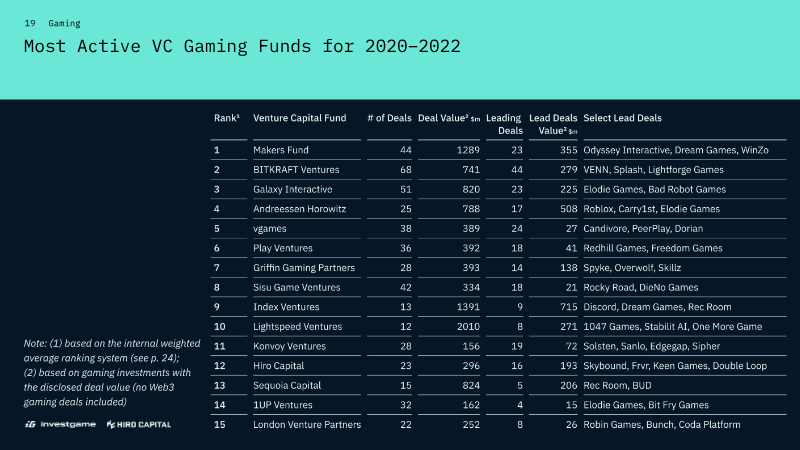
The Most Exciting Time in the Gaming Industry: 2020–2022
The analysis demonstrates that the gaming sector experienced a pronounced surge in deal activity between 2020 and 2022, with private equity investments peaking at $12 billion in 2021 before receding to $10.1 billion the following year.
- The gaming industry experienced a massive investment peak in 2021, with M&A reaching $41 billion, private equity hitting $12 billion, and public offerings peaking at $24.5 billion.
- Market activity cooled significantly by 2022, with public offerings collapsing to $4.6 billion and late-stage transaction values dropping four-and-a-half-fold to $0.9 billion in early 2023.
- Strategic acquisitions remain a primary driver of industry value, with the top 15 M&A deals—led by Microsoft’s purchases of Activision Blizzard and ZeniMax—accounting for approximately 80% of total announced deal value.
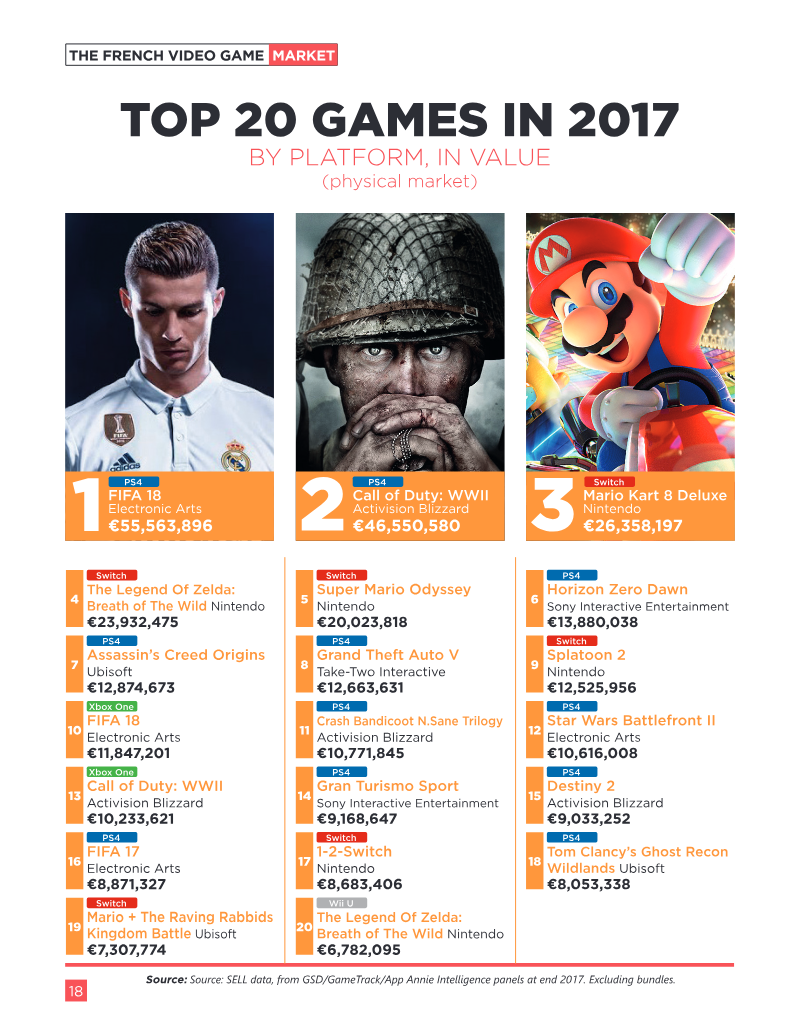
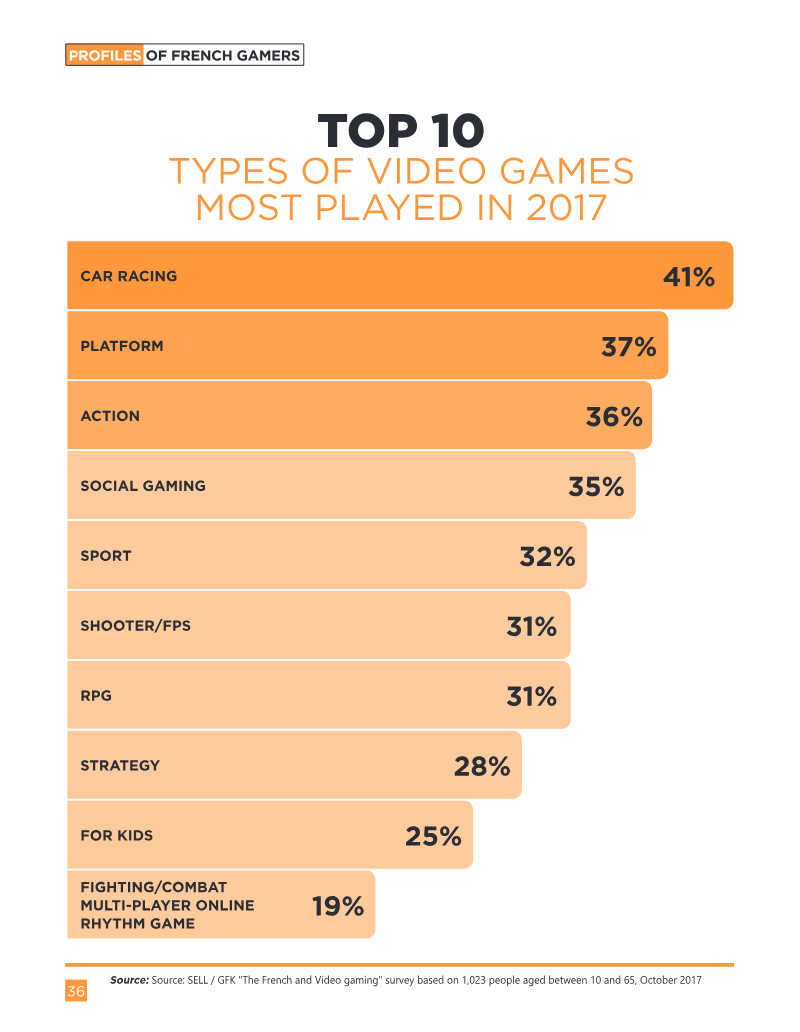
2017 Figures: The French Video Game Market
The French video game market reached a historic milestone in 2017, generating 4.3 billion euros in total turnover and achieving a record growth rate of 18 percent.
- The French video game market reached 4.3 billion euros in 2017, marking a record 18 percent growth rate.
- Consoles dominated the market with 56 percent of total value, driven by a 20 percent increase in software turnover and a 46 percent surge in digital sales.
- Digital distribution is the primary revenue driver for PC gaming, accounting for 95 percent of its software income.
Essential Video Game News: France (October 2017)
The French video game industry demonstrated robust economic health in 2016, achieving a total turnover of €3.46 billion.
- The French video game industry achieved a total turnover of €3.46 billion in 2016, representing a 4% annual growth rate.
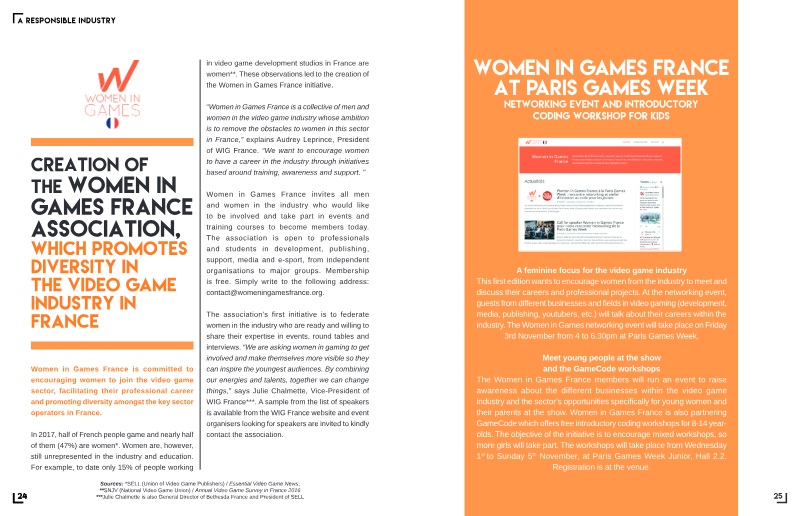
- Women comprise 47% of the French gaming population, yet they represent only 15% of the industry's professional workforce.
- The Women in Games France initiative is actively working to address the gender employment gap through professional development, networking, and technical workshops.
The Mobile Gaming Landscape 2015
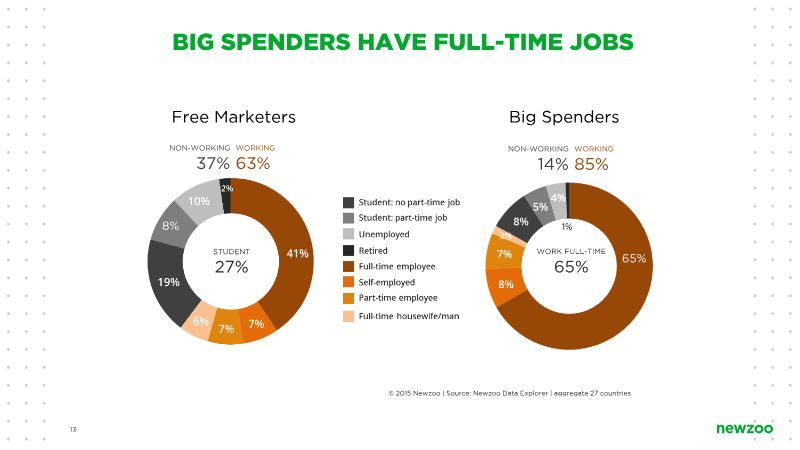
The global mobile gaming market underwent a transformative expansion in 2015, surpassing $30 billion in total revenue as the industry transitioned from isolated platform silos toward a unified, cross-platform consumption model.
- The global mobile gaming market surpassed $30 billion in revenue in 2015, driven by a transition toward unified, cross-platform ecosystems.
- High-profile industry consolidation, such as Activision Blizzard’s acquisition of King, marks a shift toward integrated gaming business models.
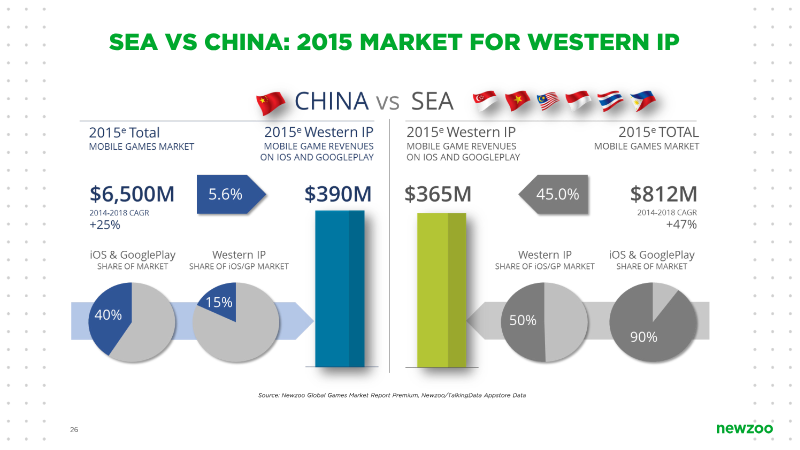
- The Chinese market remains distinct and highly competitive, requiring developers to navigate a fragmented Android ecosystem and numerous local app stores dominated by Tencent and NetEase.
Dossier de Prensa: España 2014
AEVI was created in 2014 to replace aDeSe and to serve as the unified voice of Spain’s video-game ecosystem, encompassing publishers, developers, distributors and related agents.
- AEVI was established in 2014 as the unified industry body representing companies controlling over 90% of Spain’s video game distribution market, including major publishers like Sony, Nintendo, Microsoft, and Ubisoft.
- Spain is a top-five European and top-ten global gaming market with 19 million players, generating €762 million in total consumer spending during 2013.
- The 2013 market revenue comprised €401 million in software, €275 million in hardware, and €86 million in accessories, with physical sales declines slowing to 7%.
Nordic Game Solutions Report: 2010
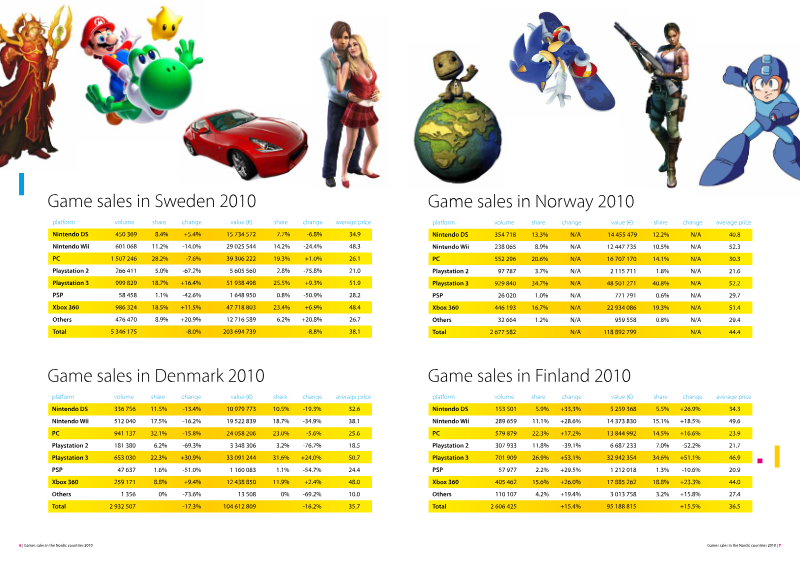
The 2010 Nordic gaming market underwent a pivotal structural transformation characterized by a 6.3 percent decline in traditional physical retail sales alongside a robust 158 percent surge in digital distribution, particularly within the PC sector.
- The Nordic gaming market saw a major structural shift in 2010, marked by a 6.3 percent decline in physical retail sales and a 158 percent surge in digital distribution.
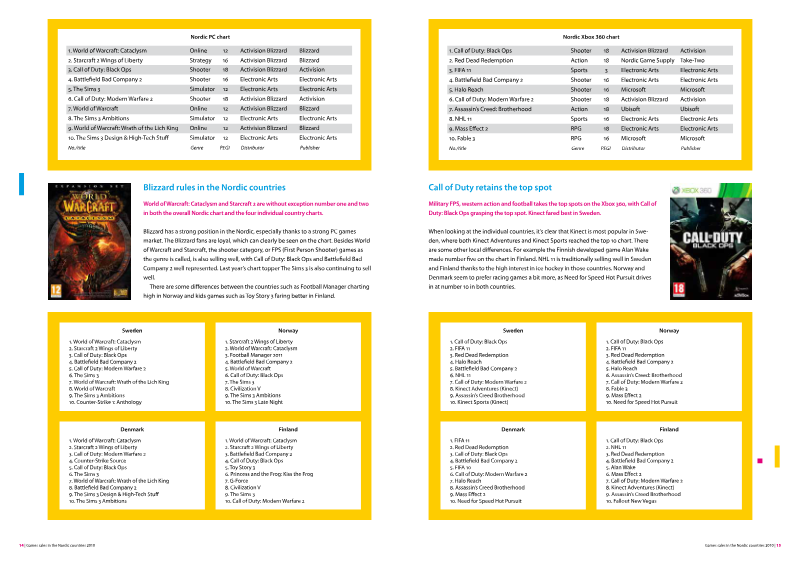
- Activision Blizzard dominated the 2010 regional market, with Call of Duty: Black Ops as the top-selling title and World of Warcraft and Starcraft anchoring the PC sector.
- Consumer preferences shifted away from legacy hardware like the PlayStation 2 toward contemporary platforms including the PlayStation 3, Xbox 360, and Wii.
The Alumni Effect: Studios Founded by Ex-Activision, Blizzard, and King Employees
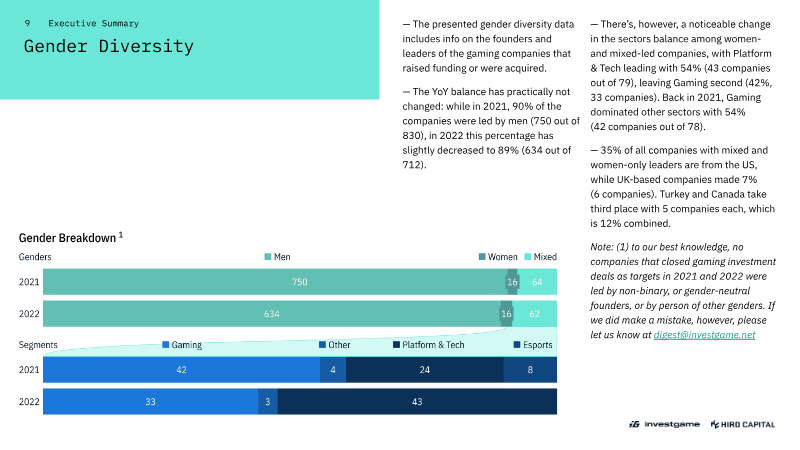
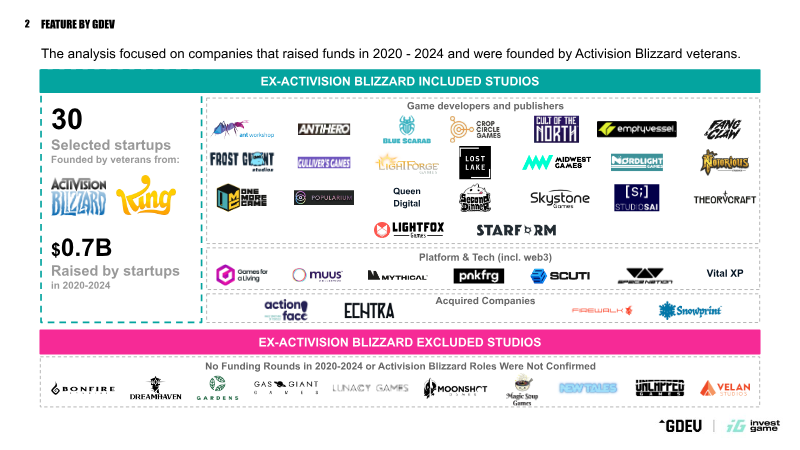
The analysis examines venture capital activity directed toward studios founded by former Activision Blizzard employees between 2020 and 2024.
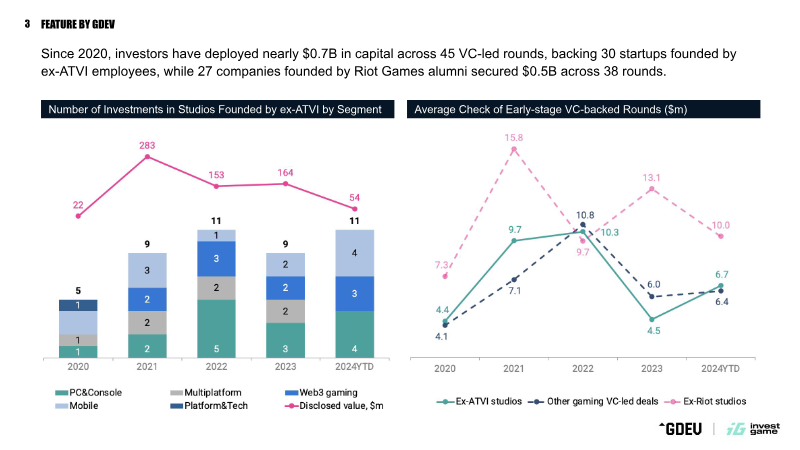
- Between 2020 and 2024, 30 studios founded by former Activision Blizzard employees secured approximately $0.7 billion in venture capital across 45 funding rounds.
- Ex-Activision studios demonstrate a 'first-round momentum' effect, being roughly four times more likely than peer startups to secure a second round of financing within the same calendar year.
- Investor confidence in alumni teams peaked in 2021, when 43% of ex-Activision studios raised a subsequent round compared to only 9% of broader gaming startups.
Q4 2023 Gaming Industry Report: Global & MENAP Outlook
The Q4 2023 Gaming Industry Report presents a global market that expanded to $212 billion, with the MENAP region contributing $2.8 billion and experiencing a 30% quarter-over-quarter rise in both gamers and investment activity.
- The global gaming market reached $212 billion in Q4 2023, with M&A activity surging to $68.7 billion, a 769% increase primarily driven by the Activision-Blizzard acquisition.
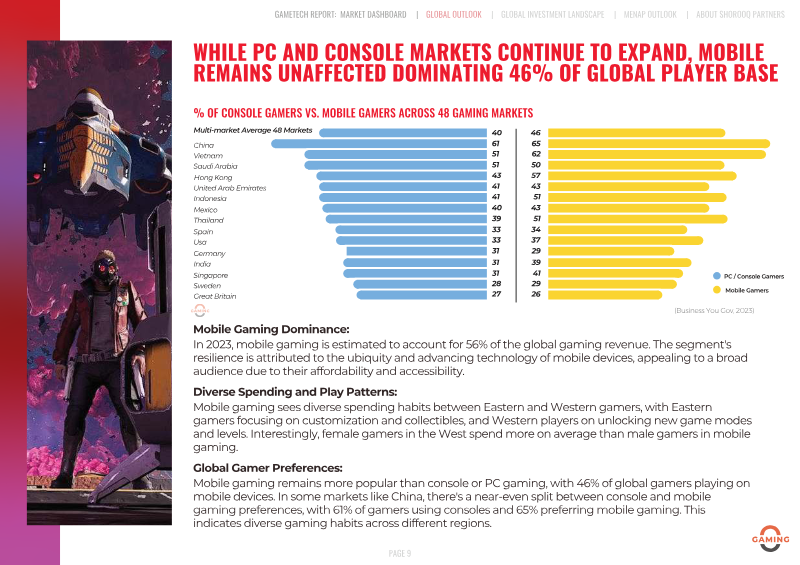
- Mobile gaming remains the industry's primary platform, capturing 46% of the global player base, while indie PC titles have grown to represent approximately 30% of total revenue.
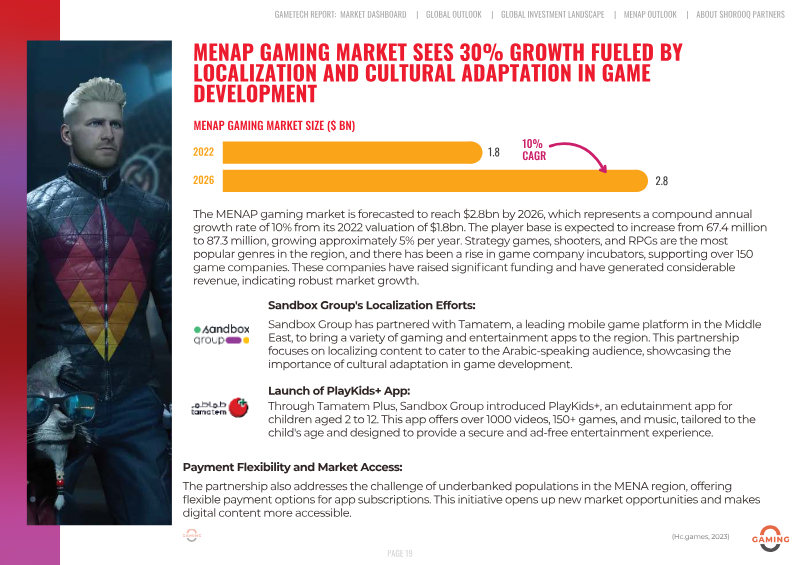
- The MENAP region is a key growth area, contributing $2.8 billion to the market and recording a 30% quarter-over-quarter increase in both gamer population and venture capital investment.