Report39 pages
Bilan du Marché Français: 2025
The French video game market demonstrated significant resilience in 2025, generating €5.856 billion in total revenue, a 2.9% increase over the previous year. This performance marks the second-highest in the industry’s history, solidifying its position as a cornerstone of the national cultural economy. Growth was primarily fueled by a rebound in console hardware sales and a record-breaking 11% surge in the mobile sector, which reached €1.792 billion. The market maintains a balanced ecosystem, with consoles commanding a 44% share, followed by mobile at 31% and PC gaming at 26%.
Software remains the primary revenue driver, accounting for over two-thirds of the total market. While physical game sales faced a double-digit decline, this was effectively mitigated by the expansion of digital content, including microtransactions and downloadable content. Electronic Arts emerged as the leading publisher across console and PC platforms, while the mobile landscape remains almost entirely dominated by free-to-play models, which now represent 94% of mobile revenue.
The industry’s reach expanded to 40.2 million players, characterized by a maturing demographic where adults comprise 88% of the base. High engagement levels persist, with 76% of players gaming on a weekly basis and a growing trend toward cross-platform usage. Alongside this growth, there is a heightened emphasis on responsible gaming. Parental involvement has reached new heights, with 67% of parents actively monitoring gaming habits through PEGI classifications and standardized parental control tools. This commitment to safety, supported by organizations like the SELL and events such as Paris Games Week, ensures that the industry continues to thrive as a mature, socially responsible, and culturally significant sector within France.
- The French video game market reached €5.856 billion in 2025, a 2.9% year-over-year increase and the second-highest revenue in the industry's history.
- Mobile gaming experienced an 11% surge to reach €1.792 billion, with free-to-play models accounting for 94% of that sector's total revenue.
- Market share is distributed across consoles (44%), mobile (31%), and PC (26%), with software sales—driven by digital content and microtransactions—comprising over two-thirds of total revenue.
- The player base has expanded to 40.2 million people, 88% of whom are adults, with 76% of all players engaging with games on a weekly basis.
- Physical game sales suffered a double-digit decline in 2025, necessitating a shift toward digital distribution and downloadable content strategies.
+3
SELL – Syndicat des Éditeurs de Logiciels de Loisirs
Report1 pages
Monthly Declaration Report: Nacon March 2023
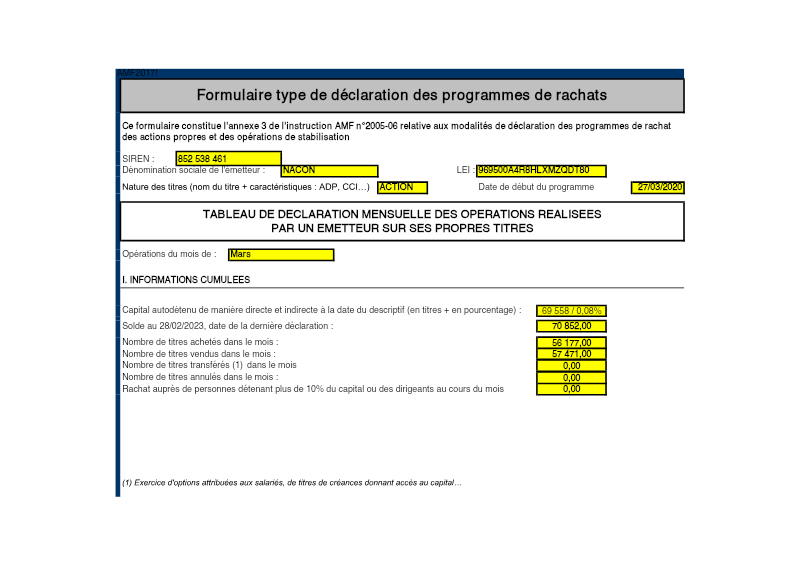
The monthly declaration for Nacon, filed with the AMF on March 2023, documents the company’s share‑buyback activity for the month of March. The report confirms that Nacon’s self‑held equity, both direct and indirect, stood at 69 558 shares (0.08 % of issued capital) as of the declaration date, slightly below the 70 852 shares reported at the end of February. During March, the issuer purchased 56 177 shares and sold 57 471 shares, resulting in a net sale of 1 294 shares. No transfers or cancellations occurred during the month, and no buybacks were executed from shareholders holding more than 10 % of capital or from directors.
The declaration follows the AMF instruction 2005‑06 and is filed under form type 2017, which requires monthly reporting of all transactions involving the issuer’s own shares. The data are presented in a table that lists cumulative information, including the number of shares bought and sold within the month, as well as any transfers or cancellations. The report covers only the period of March 2023 and pertains exclusively to Nacon’s equity securities. No additional methodology or external data sources are disclosed, as the declaration relies on internal transaction records maintained by the issuer.
- As of March 31, 2023, Nacon held 69,558 shares in treasury, representing 0.08% of its total issued capital.
- Nacon executed a net reduction of 1,294 shares in its treasury holdings during March 2023.
- Total market activity for the month consisted of 56,177 shares purchased and 57,471 shares sold.
- Treasury share holdings decreased slightly from the 70,852 shares reported at the end of February 2023.
- There were no share cancellations or transfers recorded during the month of March.
Nacon
Report3 pages
Strong Growth of Profitability: 2019/20 Full Year Results
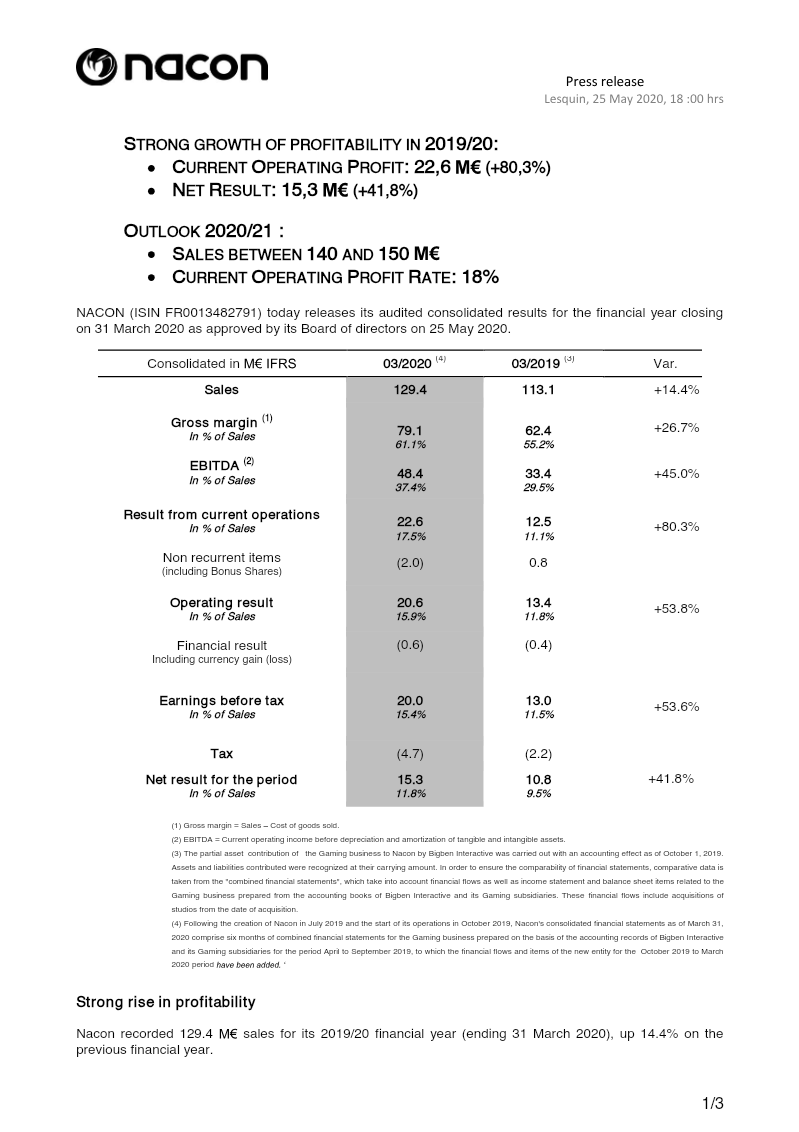
Nacon reported a robust 2019/20 fiscal year, with sales rising to €129.4 million—an increase of 14.4% from the prior year—and a gross margin expanding to 61.1 % of sales, up 26.7 percentage points largely due to a surge in digital game revenue (48.9 million €). EBITDA climbed 45.0% to €48.4 million, representing 37.4 % of sales, while current operating income surged 80.3% to €22.6 million (17.5 % of sales). After accounting for non‑recurring bonus share expenses and a modest financial loss, net profit reached €15.3 million, up 41.8% and translating to €0.18 per share.
The balance sheet strengthened markedly: shareholders’ equity rose from €67.5 million to €187.6 million, driven by a €103 million capital increase following the March 2020 IPO. Cash stood at €110.9 million, and net debt turned negative at €42.8 million after excluding IFRS‑16 lease liabilities.
Geographically, Nacon operates in 100 countries with a workforce of over 510 employees across eight studios. The company’s outlook for FY 2020/21 projects sales between €140–150 million and a current operating margin near 18%, building on its “NACON 2023” strategy to accelerate growth in both games and accessories. Planned investments target AA‑grade titles, studio acquisitions, 5G cloud gaming, and Game‑as‑a‑Service models, while premium accessory development—highlighted by the RIG™ headset acquisition—aims to broaden market reach. The board reaffirmed financial targets for FY 2022/23, anticipating sales of €180–200 million and a current operating margin above 20%.
- Nacon achieved a 14.4% increase in annual sales to €129.4 million, with net profit rising 41.8% to €15.3 million.
- Profitability metrics improved significantly, as EBITDA climbed 45.0% to €48.4 million and current operating income surged 80.3% to €22.6 million.
- The company’s balance sheet was strengthened by a March 2020 IPO that raised €103 million, resulting in a net cash position of €42.8 million.
- Gross margin expanded by 26.7 percentage points to 61.1% of sales, driven primarily by a surge in digital game revenue to €48.9 million.
- Management projects FY 2020/21 sales between €140–150 million with an operating margin near 18%.
+2
Nacon
Report303 pages
Universal Registration Document: 2019/2020
Société anonyme governed by a Board of Directors with share capital of €84,908,919 Registered office: 396/466, Rue de la Voyette, CRT 2, 59273 Fretin, France Registration number: 852 538 461 RCS Lille Métropole UNIVERSAL REGISTRATION DOCUMENT This universal registration document was approved on 7 July by the Autorité des Marchés Financiers (“AMF”) as the competent authority in respect of regulation (EU) 2017/1129.
- NACON, a video game company, reported significant financial growth, with revenue increasing from €95.568 million in 2017/18 to €129.427 million in 2019/20, and recurring operating income rising from €3.728 million to €22.620 million over the same period.
- NACON's gross margin improved substantially, from 41.7% in 2017/18 to 61.1% in 2019/20, indicating increased profitability per sale.
- The company capitalised R&D costs for games, amounting to €30.1 million in 2018/19 and €32.8 million in 2019/20, and benefited from a French video game tax credit (CIJV) of €3.0 million in 2019/20 due to an increase from 20% to 30% of development expenditure.
- NACON has a broad editorial positioning through recent studio acquisitions, including Cyanide (cycling simulations, RPGs), Kylotonn Racing and RaceWard (racing games), Eko Software (Action/RPG, Hack’n Slash, team sports), and Spiders (RPG and action games).
- NACON focuses on digital sales due to their elimination of manufacturing and inventory costs, improved publisher margins, and increased visibility through commercial campaigns with platforms like Steam, Epic Store, PlayStation Store, Xbox Live, and Nintendo eShop.
+2
Nacon
Report3 pages
2019/20 Annual Sales Report
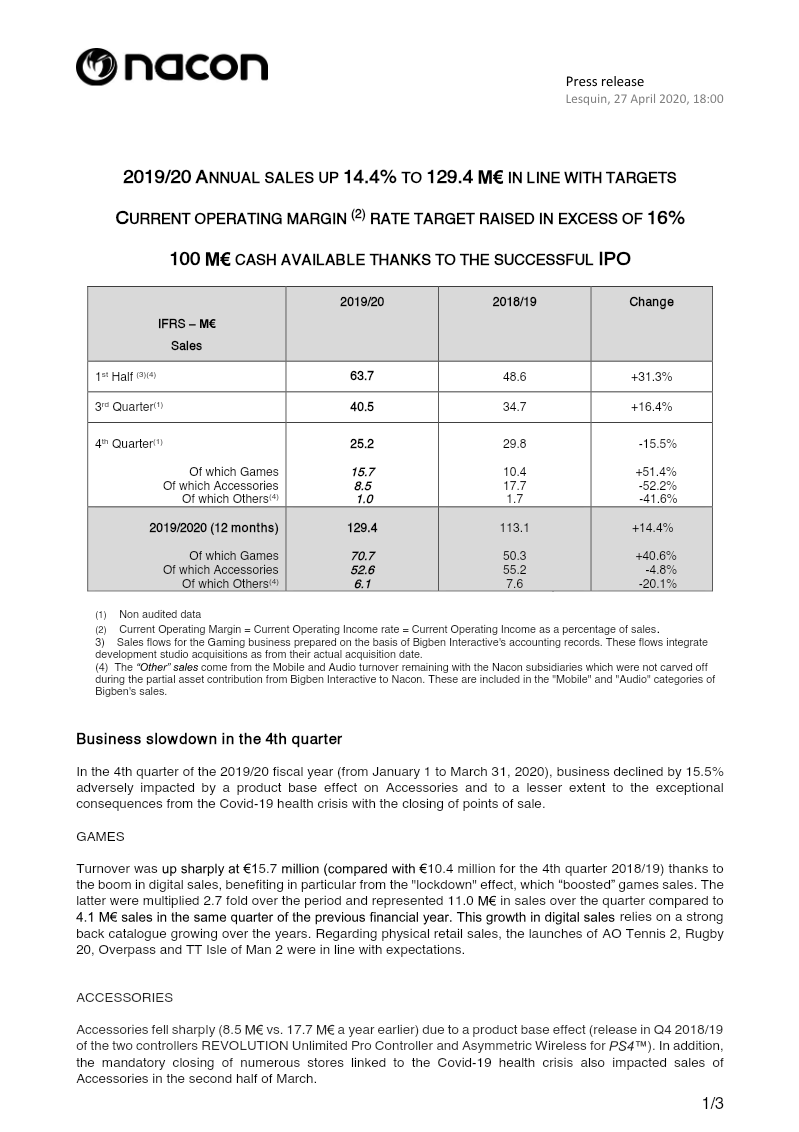
Nacon reported a 14.4 % increase in annual sales, reaching €129.4 million for the 2019/20 fiscal year, in line with its IPO guidance of €127–133 million. Total revenue rose from €113.1 million in 2018/19, driven largely by a 40.6 % jump in game sales to €70.7 million, while accessory revenue fell 4.8 % to €52.6 million and other categories declined 20.1 %. Digital game sales surged, accounting for 69 % of game revenue versus 41 % the previous year, a trend amplified by lockdown‑induced consumer behaviour. The fourth quarter saw a 15.5 % drop in overall sales, largely due to a product‑base effect on accessories and temporary store closures from the COVID‑19 crisis, though game sales remained robust.
Operating performance improved, with a current operating margin target of 16 % raised above expectations thanks to higher digital margins. Cash reserves stood at €100 million following a successful IPO that raised €109 million in March 2020, ensuring liquidity for the upcoming fiscal year. Nacon maintains its “NACON 2023” plan, targeting €180–200 million in sales and a margin above 20 % for FY 2022/23. The company projects continued momentum in Q1 2020/21, with new game releases and expanded headset distribution through a partnership with Poly (Plantronics Inc.). Operations have largely shifted to telework, and procurement has returned to normal levels. The company’s 16 subsidiaries operate across 100 countries, supporting a workforce of nearly 450 employees.
- Nacon reported a 14.4% increase in annual sales to €129.4 million for the 2019/20 fiscal year, meeting its IPO guidance range of €127–133 million.
- Game sales grew by 40.6% to €70.7 million, with digital channels accounting for 69% of that revenue compared to 41% in the previous year.
- Accessory revenue declined by 4.8% to €52.6 million, contributing to a 15.5% drop in overall Q4 sales due to store closures and product-base effects.
- The company raised its current operating margin target to 16% due to higher margins from digital game sales.
- Following a March 2020 IPO that raised €109 million, Nacon holds €100 million in cash reserves to ensure liquidity.
+4
Nacon
Report2 pages
FY 2020/21 Sales Results: Nacon
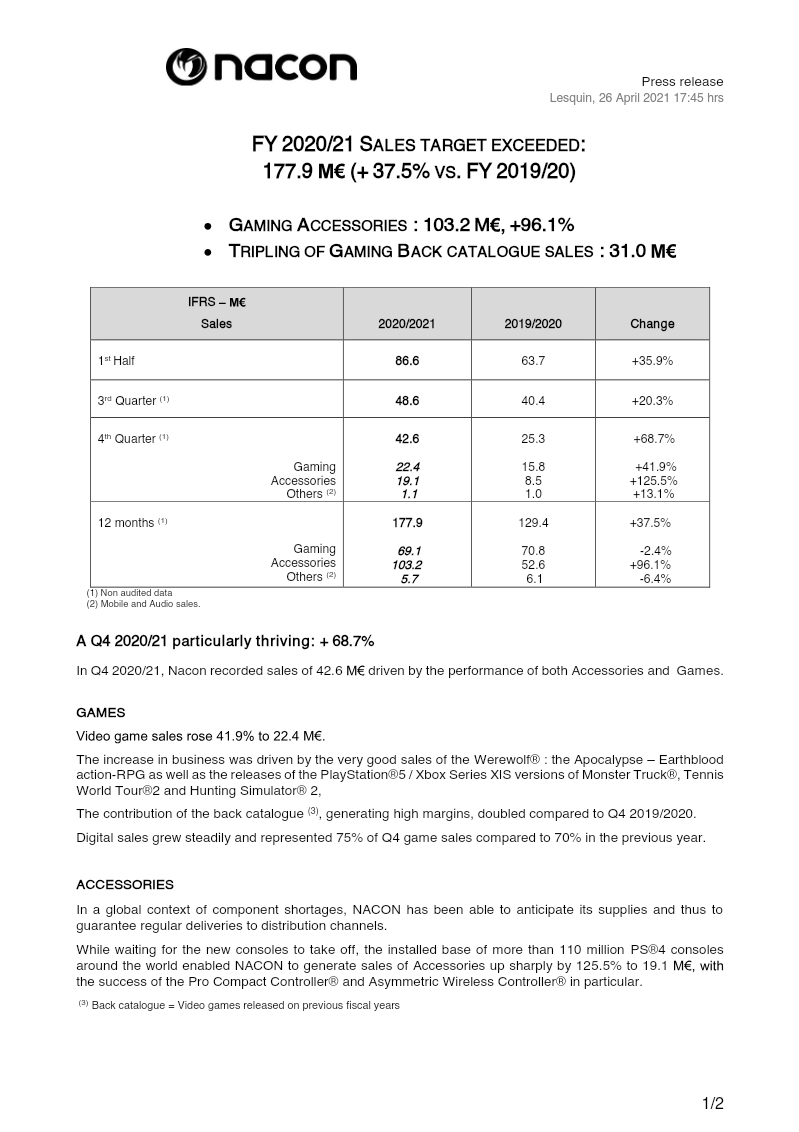
Nacon reported FY 2020/21 sales of €177.9 million, a 37.5 % increase over the previous fiscal year and surpassing the revised target of €160–170 million. Gaming revenue remained flat at €69.1 million, while accessories sales surged to €103.2 million, up 96.1 %. The accessories boom was driven by premium RIG® headsets, licensed controllers, and new Xbox Series X|S accessories launched late in the year. Back‑catalogue game sales tripled to €31 million, contributing high margins and offsetting a slight decline in overall game sales. Digital game sales rose to 75 % of Q4 revenue, up from 70 % the prior year.
Quarterly performance highlighted a strong fourth quarter: €42.6 million in sales, a 68.7 % increase over Q4 2019/20, with gaming and accessories both outperforming. The company’s strategy, outlined during its March 2020 IPO, included acquisitions of Neopica, Passtech Games, and BigAnt Studios, expansion into the U.S. market with RIG® accessories, and a licensing agreement with Microsoft for Xbox Series X|S. These moves are expected to lift sales and operating margins in FY 2022/23 and 2023/24.
Nacon confirmed a 18 % operating income rate for FY 2020/21 and plans to revise its 2023 guidance upward. The company operates globally, with a distribution network in 100 countries and over 510 employees across 17 subsidiaries.
- Nacon achieved FY 2020/21 sales of €177.9 million, representing a 37.5% year-over-year increase that exceeded the company's revised target of €160–170 million.
- Accessories sales were the primary growth driver, surging 96.1% to €103.2 million due to the success of RIG® headsets, licensed controllers, and new Xbox Series X|S hardware.
- Back-catalogue game sales tripled to €31 million, providing high-margin revenue that offset a slight decline in overall gaming segment sales, which remained flat at €69.1 million.
- Digital distribution continues to grow, accounting for 75% of Q4 revenue compared to 70% in the prior year.
- The company reported an 18% operating income rate for the fiscal year and plans to revise its 2023 guidance upward based on recent performance.
+2
Nacon
Report2 pages
FY 2020/21 Annual Results: Nacon
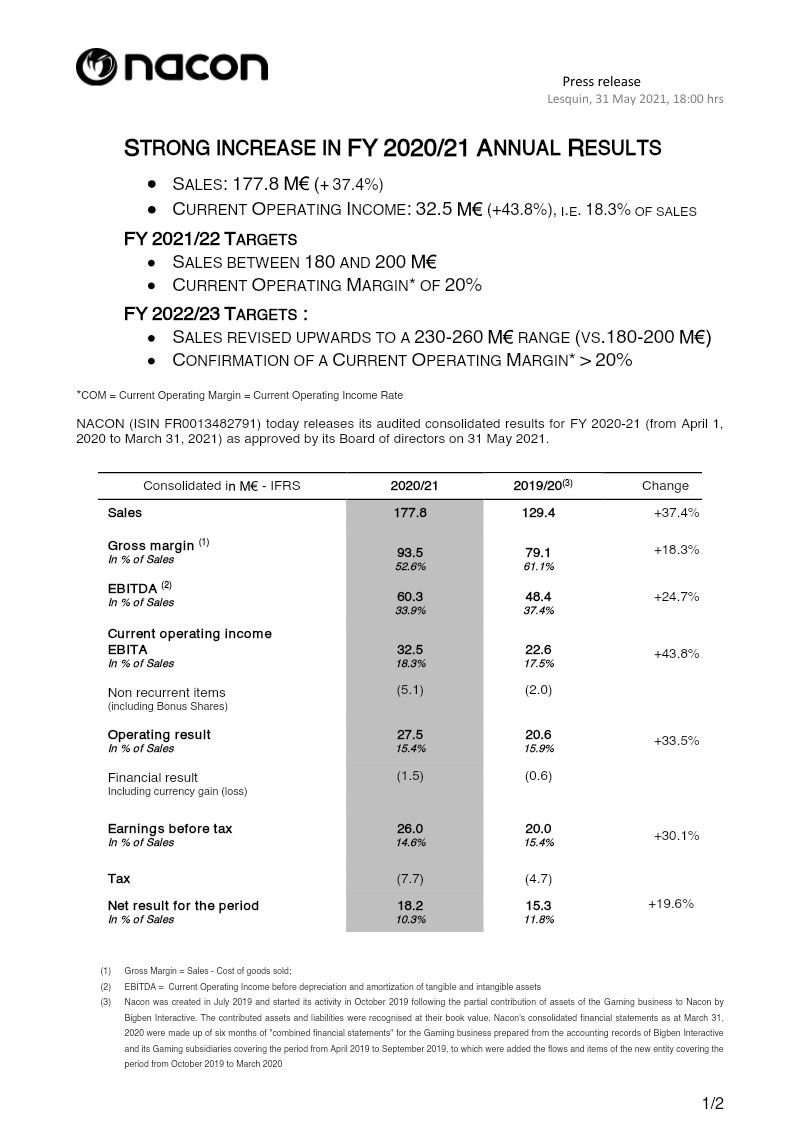
Nacon reported a robust FY 2020/21 performance, with sales rising 37.4 % to €177.8 million and current operating income increasing 43.8 % to €32.5 million, representing 18.3 % of sales. Gross margin improved to 52.6 % from 61.1 %, while EBITDA grew 24.7 % to €60.3 million (33.9 % of sales). Net profit reached €18.2 million, up 19.6 %, after accounting for a €5.1 million bonus‑share expense, a €1.5 million financial charge and €7.7 million in tax. Operating cash flow surged 146 % to €55.7 million, sufficient to cover CAPEX of €56.4 million and bank repayments, leaving cash and equivalents at €96.7 million.
The company attributes growth to premium accessories, successful U.S. expansion, and a tripling of back‑catalogue sales. Forecasts for FY 2021/22 have been raised to €180–200 million in sales with a 20 % operating margin, driven by digital catalogues and new titles such as RIMS Racing and Blood Bowl 3. For FY 2022/23, sales targets are further increased to €230–260 million, maintaining a margin above 20 %, supported by studio acquisitions and high‑profile releases like The Lord of the Rings.
Nacon, listed on Euronext Paris (ISIN FR0013482791), operates through 18 subsidiaries and a distribution network covering 100 countries, employing over 600 staff. The board has opted to retain earnings for reinvestment rather than distribute a dividend in FY 2020/21.
- Nacon achieved strong FY 2020/21 growth with sales rising 37.4% to €177.8 million and current operating income increasing 43.8% to €32.5 million.
- Operating cash flow surged 146% to €55.7 million, supporting a year-end cash position of €96.7 million despite €56.4 million in capital expenditures.
- The company raised its FY 2021/22 sales guidance to €180–200 million with a 20% operating margin, followed by an increased FY 2022/23 target of €230–260 million.
- Growth drivers for the fiscal year included strong performance in premium accessories, successful U.S. market expansion, and a tripling of back-catalogue sales.
- Future revenue growth is anchored by upcoming titles including 'RIMS Racing', 'Blood Bowl 3', and 'The Lord of the Rings', alongside ongoing studio acquisitions.
+2
Nacon
Report2 pages
Q3 2020/21 Sales: 48.7 M€, + 20.3%
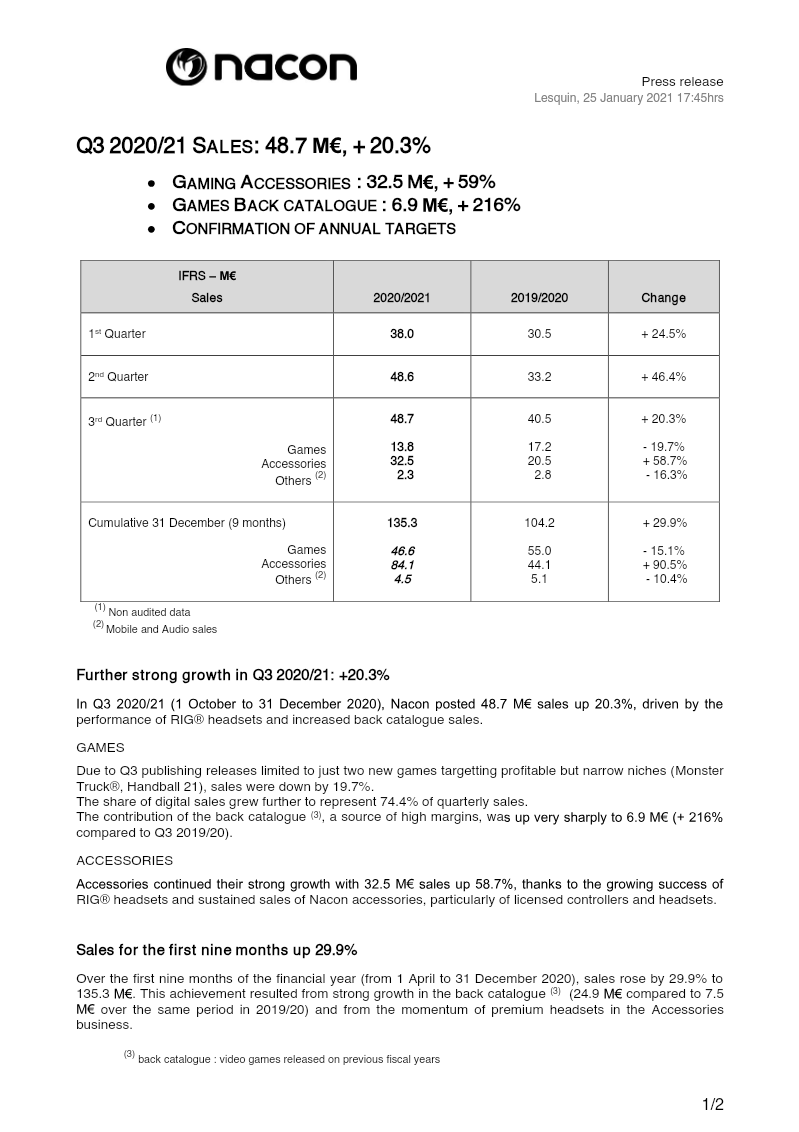
Nacon reported Q3 2020/21 sales of €48.7 million, a 20.3 % increase over the same period in 2019/20, driven primarily by a surge in gaming accessories and back‑catalogue sales. Accessories grew 58.7 % to €32.5 million, largely due to the RIG® headset line and licensed controller sales, while back‑catalogue revenue jumped 216 % to €6.9 million, reflecting high‑margin older titles. Game sales fell 19.7 % to €13.8 million, with only two new releases (Monster Truck® and Handball 21) and a digital sales share of 74.4 %. Other revenue, mainly mobile and audio, declined 16.3 % to €2.3 million.
Cumulative sales for the first nine months rose 29.9 % to €135.3 million, with accessories contributing a 90.5 % increase and back‑catalogue sales up 24.9 million versus €7.5 million in the prior year. The company projects Q4 growth, citing upcoming releases such as Werewolf® : The Apocalypse – Earthblood and new console versions of Monster Truck®, Tennis World Tour 2, and Hunting Simulator 2. Digital sales, back‑catalogue momentum, and a robust order book for RIG® headphones are expected to sustain the upward trajectory.
Nacon confirms its annual target of €160–170 million in sales with an 18 % operating margin, and it has announced the acquisition of Australian studio Big Ant to strengthen its sports‑game portfolio. No dividend will be paid in 2020/21, as funds are earmarked for studio acquisitions and development. The company maintains a 2023 plan targeting €180–200 million in sales with an operating margin above 20 % for 2022/23.
- Nacon reported Q3 2020/21 sales of €48.7 million, a 20.3% year-over-year increase, bringing cumulative nine-month sales to €135.3 million.
- Growth was driven by a 58.7% surge in accessories revenue to €32.5 million and a 216% increase in back-catalogue sales to €6.9 million.
- New game sales declined 19.7% to €13.8 million during the quarter, reflecting a light release schedule of only two titles.
- The company confirmed its annual fiscal target of €160–170 million in sales with an 18% operating margin, while maintaining a long-term 2022/23 goal of €180–200 million in sales.
- Nacon acquired Australian studio Big Ant to bolster its sports-game portfolio and will forgo a dividend payment to prioritize capital for acquisitions and development.
+2
Nacon
Report315 pages
Universal Registration Document 2020/2021
Société anonyme governed by a Board of Directors with share capital of €84,908,919 Registered office: 396/466, Rue de la Voyette, CRT 2, 59273 Fretin, France Registration number: 852 538 461 RCS Lille Métropole UNIVERSAL REGISTRATION DOCUMENT This universal registration document was approved on 6 July 2021 by the Autorité des Marchés Financiers (“AMF”) as the competent authority in respect of regulation (EU) 2017/1129.
- Nacon, a gaming company, had its Universal Registration Document approved by the AMF on July 6, 2021, valid until July 5, 2022.
- Nacon amortizes game development costs for new games released from April 1, 2020, over a four-year period using the diminishing balance method, reflecting market digitalization and extended game lifespans.
- Nacon's strategy involves a balanced game lineup across four genres (racing, sports, action/adventure, simulations), including high-budget and lower-cost games, and both existing and new IPs, to mitigate risk and ensure long-term profitability.
- Nacon has nearly 30 years of experience in the third-party accessories market, with a strong European presence for 20 years, supported by subsidiaries across major European countries and exclusive global distributors.
- Nacon's staff turnover increased slightly from 12.9% at March 31, 2020, to 13.3% at March 31, 2021, despite an active HR policy focused on recruitment, training, retention, and an attractive workplace culture.
+1
Nacon
Report32 pages
Interim Financial Report: First Half 2020/21
INTERIM FINANCIAL REPORT FOR THE SIX MONTHS ENDED 30 SEPTEMBER 2020 – NACON SIX MONTHS ENDED 30 SEPTEMBER 2020 SIX MONTHS ENDED 30 SEPTEMBER 2020 TABLE OF CONTENTS 2 1. STATEMENT BY THE PERSON RESPONSIBLE 3 2.
- NACON's net income significantly increased by 46.7% to €9.6 million in the first half of 2020/21, up from €6.5 million in the first half of 2019/20.
- Recurring operating income for NACON rose by 47.4% to €15.7 million in the first half of 2020/21, compared to €10.7 million in the prior year, driven by increased revenue, reduced external expenses, and controlled personnel costs.
- Consolidated revenue for NACON grew by 35.9% to €86.6 million in the first half of 2020/21, with gaming accessories revenue more than doubling from €23.6 million to €51.6 million, now representing 60% of total revenue.
- NACON acquired 100% of Belgian development studio Neopica Srl on October 19, 2020, a studio known for developing around 60 games including Hunting Simulator 1 & 2 and FIA European Truck Racing Championship.
- NACON's EBITDA reached €30.4 million in the first half of 2020/21, representing 35.1% of revenue, up from €23.5 million (37.0% of revenue) in the first half of 2019/20.
+2
Nacon
Report2 pages
Strong Increase in Profitability in 1st Half: Fiscal Year 2020/21
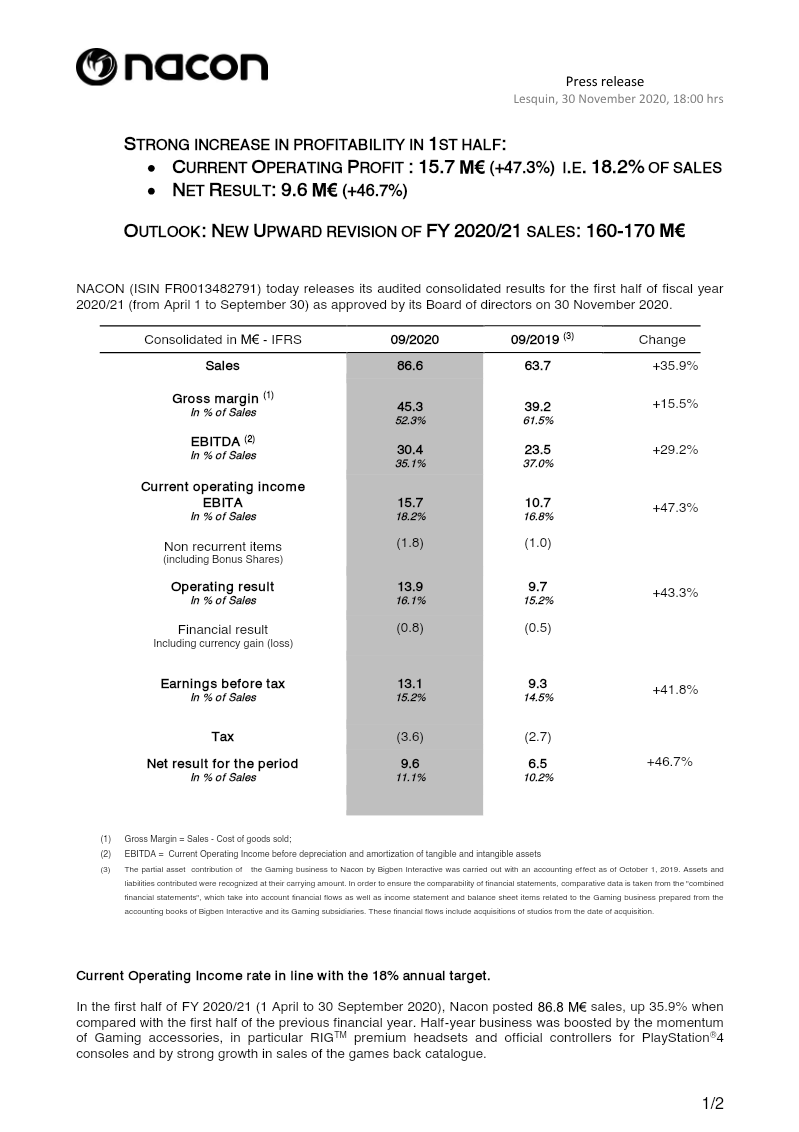
Nacon reports a strong first‑half performance for fiscal year 2020/21, with sales rising 35.9 % to €86.6 million and gross margin improving from 39.2 % to 45.3 %. Current operating income (COI) increased by 47.3 % to €15.7 million, representing 18.2 % of sales and meeting the company’s annual COI target of 18 %. Net profit for the period reached €9.6 million, up 46.7 % from €6.5 million in the prior year’s first half, after accounting for €1.8 million in bonus‑share expenses and €0.8 million in net financial costs.
Operating cash flow surged to €34.1 million, enabling the group to self‑finance €25.9 million of capital expenditure and generate an €8.2 million free cash flow. Net cash at 30 September stood at €50.7 million, up from €42.8 million in March 2020, despite a €5 million increase in CAPEX and loan repayments.
The growth is attributed to momentum in gaming accessories—particularly premium headsets and official PlayStation 4 controllers—and a robust back‑catalogue of games. Nacon projects continued sales acceleration in the second half, driven by dual‑generation console support (PS 4/5, Xbox One/Xbox Series), digital sales expansion, and releases of next‑gen titles such as WRC 9 and Tennis World Tour 2. Consequently, the company has revised its FY 2020/21 sales target upward to €160–170 million and maintains an 18 % COI goal. For FY 2022/23, Nacon targets sales of €180–200 million with a COI exceeding 20 %. The data derive from audited consolidated IFRS statements covering April–September 2020, with comparative figures adjusted for the 2019 acquisition of Bigben Interactive’s gaming assets.
- Nacon reported a 35.9% increase in H1 2020/21 sales to €86.6 million, with net profit rising 46.7% to €9.6 million.
- Current operating income (COI) grew 47.3% to €15.7 million, hitting the company's 18% annual margin target ahead of schedule.
- The company raised its FY 2020/21 sales guidance to €160–170 million, while setting a long-term FY 2022/23 target of €180–200 million with a COI exceeding 20%.
- Operating cash flow reached €34.1 million, resulting in a net cash position of €50.7 million as of September 30, 2020.
- Growth was driven by strong performance in gaming accessories, specifically premium headsets and PlayStation 4 controllers, alongside a robust back-catalogue of games.
+1
Nacon
Report2 pages
2021-22 Annual Sales: Audited Consolidated Results
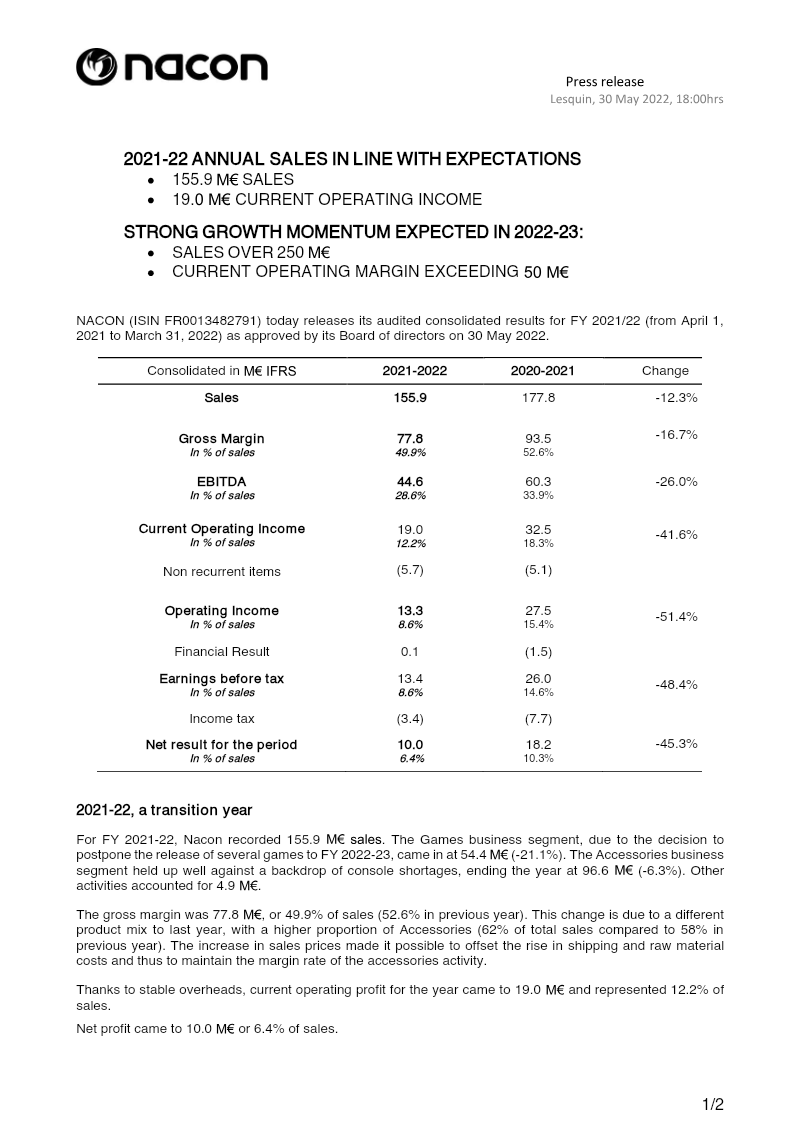
Nacon’s audited consolidated results for the fiscal year ending 31 March 2022 show sales of €155.9 million, a decline of 12.3 % from the previous year’s €177.8 million, driven largely by a 21.1 % drop in the Games segment after postponing several releases to FY 2022‑23. The Accessories segment, however, remained resilient amid global console shortages, recording €96.6 million in sales (down 6.3 %) and contributing a higher proportion of revenue (62 % versus 58 % previously). Gross margin fell to €77.8 million (49.9 % of sales) from €93.5 million (52.6 %) due to the altered product mix, though price increases offset rising shipping and raw‑material costs. EBITDA contracted 26 % to €44.6 million (28.6 % of sales), and current operating income dropped 41.6 % to €19.0 million (12.2 % of sales). Net profit fell 45.3 % to €10.0 million (6.4 % of sales).
The balance sheet reflects significant investment activity: shareholders’ equity rose to €228.4 million, new bank debt of €52.5 million was issued at sub‑1 % interest, and net debt remained low at €10.4 million. Working capital increased by €8.7 million due to higher inventories, while operating cash flow reached €32.4 million and intangible CAPEX totaled €57.4 million. Over the past two years, Nacon has invested over €100 million in game development and acquired nine studios, expanding its pipeline to 46 titles from 33.
Management projects a sharp rebound in FY 2022‑23, targeting sales above €250 million and a current operating margin exceeding €50 million, supported by new releases such as Vampire: The Masquerade®‑Swansong and The Lord of the Rings Gollum. The company will continue external growth through studio acquisitions, notably Midgar Studio and Daedalic Entertainment.
- Nacon reported FY 2021-22 sales of €155.9 million, a 12.3% decline from the previous year, primarily due to a 21.1% drop in the Games segment following the postponement of several titles.
- Management projects a significant rebound for FY 2022-23 with a sales target exceeding €250 million and an operating margin above €50 million, driven by releases like 'Vampire: The Masquerade – Swansong' and 'The Lord of the Rings: Gollum'.
- Net profit fell 45.3% to €10.0 million, while current operating income dropped 41.6% to €19.0 million, reflecting the impact of the altered product mix and increased operational costs.
- The Accessories segment proved resilient despite global console shortages, generating €96.6 million in sales and increasing its share of total revenue to 62%.
- Nacon has aggressively expanded its development pipeline to 46 titles, supported by over €100 million in development investment and the acquisition of nine studios, including Midgar Studio and Daedalic Entertainment, over the past two years.
+2
Nacon
Report2 pages
FY 2021/22 Annual Sales: A Transition Year
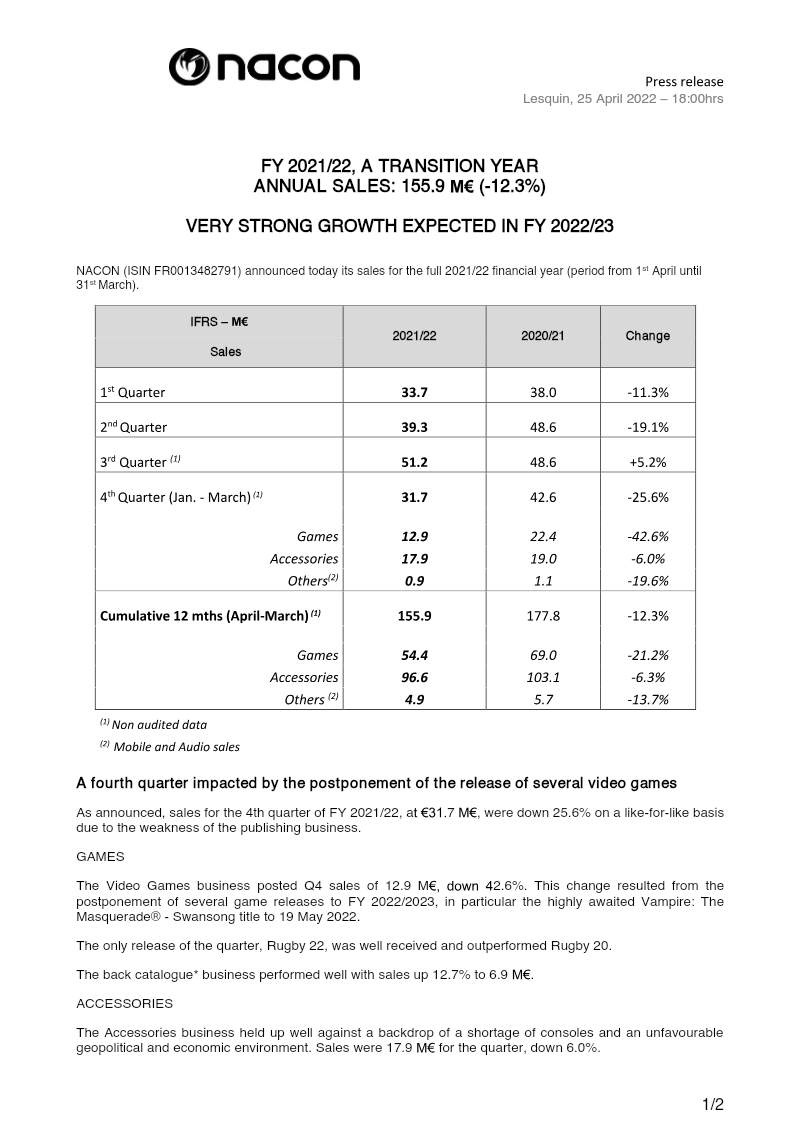
Nacon reported FY 2021/22 sales of €155.9 million, a 12.3 % decline from the previous year’s €177.8 million. The drop was driven mainly by a 25.6 % fall in fourth‑quarter sales to €31.7 million, largely due to postponed game releases such as Vampire: The Masquerade® – Swansong. Game sales for the year fell 21.2 % to €54.4 million, while accessories declined 6.3 % to €96.6 million; mobile and audio sales also contracted by 13.7 %. The back‑catalogue segment performed modestly better, up 12.7 % to €6.9 million.
Quarterly performance showed a sharp decline in Q1 (€33.7 M) and Q2 (€39.3 M), a modest rebound in Q3 (€51.2 M, +5.2 %), and a significant drop in Q4 (€31.7 M). The company’s operating income for the year is projected between €17 million and €19 million, reflecting the weaker Q4 results.
Looking ahead to FY 2022/23, Nacon anticipates a strong rebound driven by a robust game pipeline—including titles such as Vampire: The Masquerade® – Swansong, Zorro The Chronicles, and Tour de France 2022—and expects sales between €250 million and €300 million with an operating margin above 20 %. The strategy includes further external growth through acquisitions of Midgar Studio and Daedalic Entertainment to enhance internal development capabilities.
The figures cover global operations across 20 subsidiaries, with a workforce of over 700 employees and distribution in more than 100 countries. The data are presented under IFRS, with non‑audited figures for the fourth quarter and a note that mobile and audio sales are included in the “Others” category.
- Nacon reported FY 2021/22 sales of €155.9 million, representing a 12.3% year-over-year decline from €177.8 million.
- The company projects a significant recovery for FY 2022/23, targeting sales between €250 million and €300 million with an operating margin exceeding 20%.
- Annual game sales fell 21.2% to €54.4 million, while accessories declined 6.3% to €96.6 million.
- The sharp 25.6% drop in Q4 sales to €31.7 million was primarily attributed to the postponement of key titles like Vampire: The Masquerade – Swansong.
- Nacon is pursuing external growth through the acquisitions of Midgar Studio and Daedalic Entertainment to bolster internal development capabilities.
+1
Nacon
Report2 pages
Return to Growth for Q3 2021-22: Confirmation of 2021/22 & 2022/23 Targets
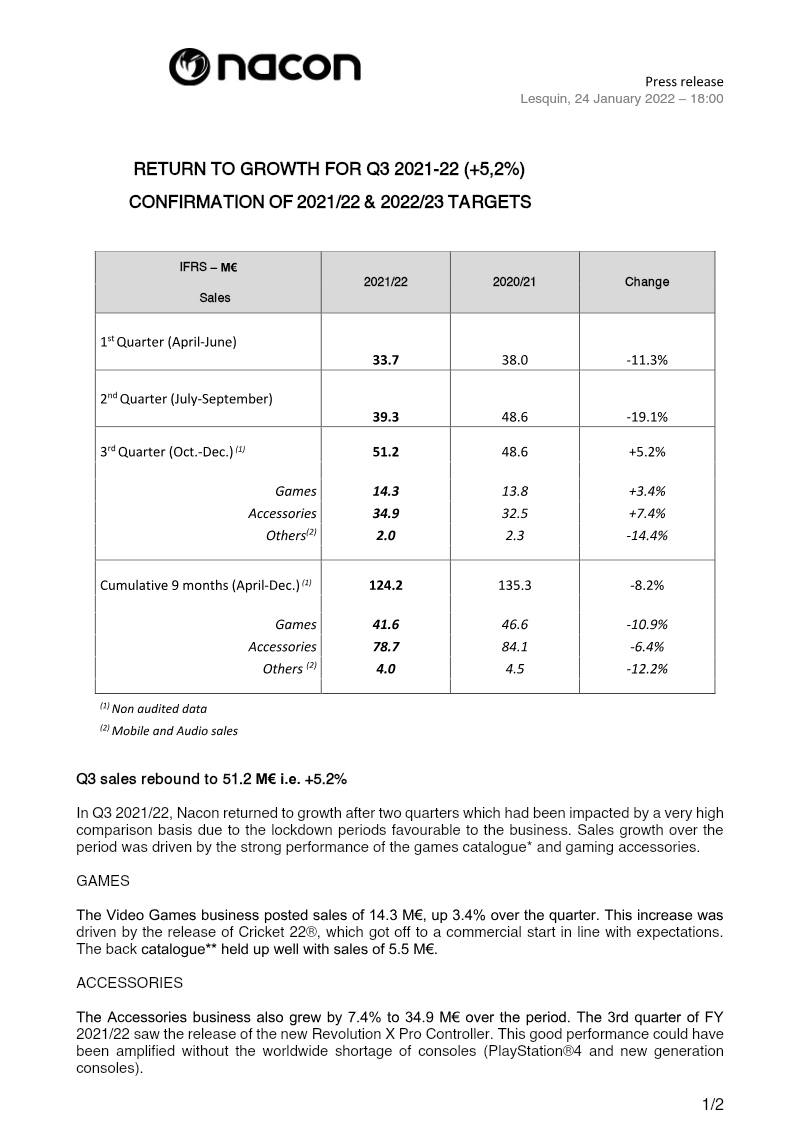
Nacon reported a rebound in Q3 2021/22, with sales rising 5.2 % to €51.2 million after two quarters of decline driven by a high comparison base from lockdown‑related demand spikes. The growth was led by the games catalogue, which generated €14.3 million (+3.4 %) and a strong back‑catalogue contribution of €5.5 million, while accessories grew 7.4 % to €34.9 million thanks to the launch of the Revolution X Pro Controller, though global console shortages limited further upside. Other segments, including mobile and audio sales, contracted by 14.4 % to €2.0 million.
Cumulative sales for the first nine months fell 8.2 % to €124.2 million, with games down 10.9 % and accessories down 6.4 %. Nacon confirmed its FY 2021/22 targets of €150–180 million in sales and an operating income near €20 million. For FY 2022/23, the company projects a robust publishing pipeline of over 15 titles—including high‑profile releases such as Vampire: The Masquerade® – Swansong—and anticipates sales of €250–300 million with an operating margin above 20 %. The strategy includes selective acquisitions to strengthen the catalogue and position Nacon as a leading player in the global video‑game market. The outlook is based on continued demand for both new releases and established titles, with accessories sales expected to benefit from ongoing headset and controller launches across major console platforms.
- Nacon projects significant growth for FY 2022/23, targeting sales of €250–300 million and an operating margin exceeding 20%.
- Q3 2021/22 sales rebounded by 5.2% to €51.2 million, ending two consecutive quarters of decline.
- The company confirmed its FY 2021/22 targets of €150–180 million in sales and an operating income near €20 million, despite a 8.2% decline in cumulative nine-month sales to €124.2 million.
- Accessories growth of 7.4% to €34.9 million was driven by the Revolution X Pro Controller launch, though performance was constrained by global console shortages.
- The games catalogue contributed €14.3 million in Q3, supported by a strong back-catalogue performance of €5.5 million.
+2
Nacon
Report30 pages
Interim Financial Report: First Half 2021/22
INTERIM FINANCIAL REPORT FOR THE SIX MONTHS ENDED 30 SEPTEMBER 2020 – NACON SIX MONTHS ENDED 30 SEPTEMBER 2021 SIX MONTHS ENDED 30 SEPTEMBER 2021 TABLE OF CONTENTS 2 1> STATEMENT BY THE PERSON RESPONSIBLE .3 2> BUSINESS REPORT 4 2.1 Key events in the first half of 2021/22 ...
- NACON's revenue for the first half of 2021/22 decreased by 15.7% to €73.0 million, down from €86.6 million in the same period last year, primarily due to a decline in accessories sales and fewer new video game releases.
- Net income for the first half of 2021/22 significantly dropped by 60.4% to €3.8 million, compared to €9.6 million in the prior year, while recurring operating income fell by 46.3% to €8.4 million.
- The company acquired two development studios in the first half of 2021/22: Big Ant Holding Pty Ltd (known for sports franchises) in May 2021 for €18 million plus potential earn-outs, and Crea-ture Studios Inc (skateboarding games) in July 2021.
- NACON has adjusted its 2021/22 guidance, reducing expected revenue to €150-180 million and recurring operating income to around €20 million, citing delayed game releases.
- Conversely, guidance for 2022/23 has been increased, with expected revenue of €250-300 million and a recurring operating margin of over 20%.
+2
Nacon
Report3 pages
HY 1 2021/22 Consolidated Results: Impacted by an Unfavourable Basis Comparison
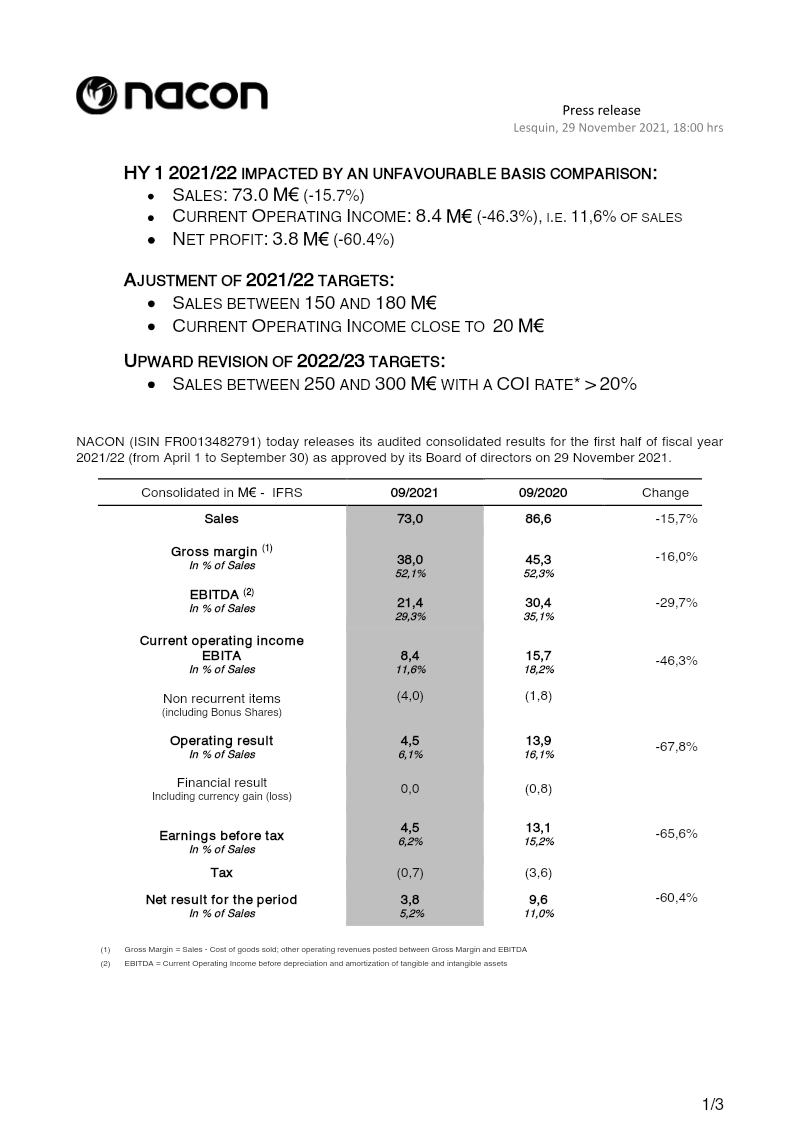
Nacon released audited consolidated results for the first half of fiscal year 2021/22, reporting sales of €73.0 million, a 15.7 % decline from the comparable period in 2020/21. Gross margin fell to €38.0 million (52.1 % of sales) and EBITDA dropped 29.7 % to €21.4 million (29.3 % of sales). Current operating income fell 46.3 % to €8.4 million, representing 11.6 % of sales, while net profit contracted 60.4 % to €3.8 million (5.2 % of sales). The decline is attributed mainly to a weaker editorial portfolio—video‑game sales fell 16.9 % to €27.3 million—and a high comparison basis for accessory sales, which decreased 15.1 % to €43.7 million.
The balance sheet remained solid, with shareholders’ equity at €219.0 million and cash reserves of €62.6 million, reflecting recent studio acquisitions and catalogue development. Working‑capital requirements increased by €2.5 million due to inventory build‑up, while operating cash flow reached €17.7 million and investment outflows rose to €45.6 million.
In response, Nacon revised its 2021/22 targets downward (sales €150–180 million; current operating income near €20 million) and lifted 2022/23 expectations (sales €250–300 million; operating‑income rate >20 %). The company postponed several high‑profile releases to 2022/23, citing a need for additional development time to enhance quality. The acquisition of Ishtar Games was completed on 25 November 2021, expanding Nacon’s studio portfolio. The outlook highlights a strong editorial pipeline for 2022/23, with over fifteen new titles and continued growth of the back‑catalogue.
- Nacon reported a 15.7% decline in HY 2021/22 sales to €73.0 million, with net profit contracting 60.4% to €3.8 million compared to the previous year.
- The company lowered its 2021/22 financial targets, now projecting sales of €150–180 million and current operating income near €20 million.
- Performance was impacted by a 16.9% drop in video-game sales to €27.3 million and a 15.1% decline in accessory sales to €43.7 million.
- Nacon postponed several high-profile titles to fiscal year 2022/23 to prioritize development quality, while simultaneously raising its 2022/23 sales guidance to €250–300 million.
- The balance sheet remains stable with €219.0 million in shareholders’ equity and €62.6 million in cash reserves, despite investment outflows rising to €45.6 million.
+1
Nacon
Report2 pages
1st Half Year 2021/22 Sales
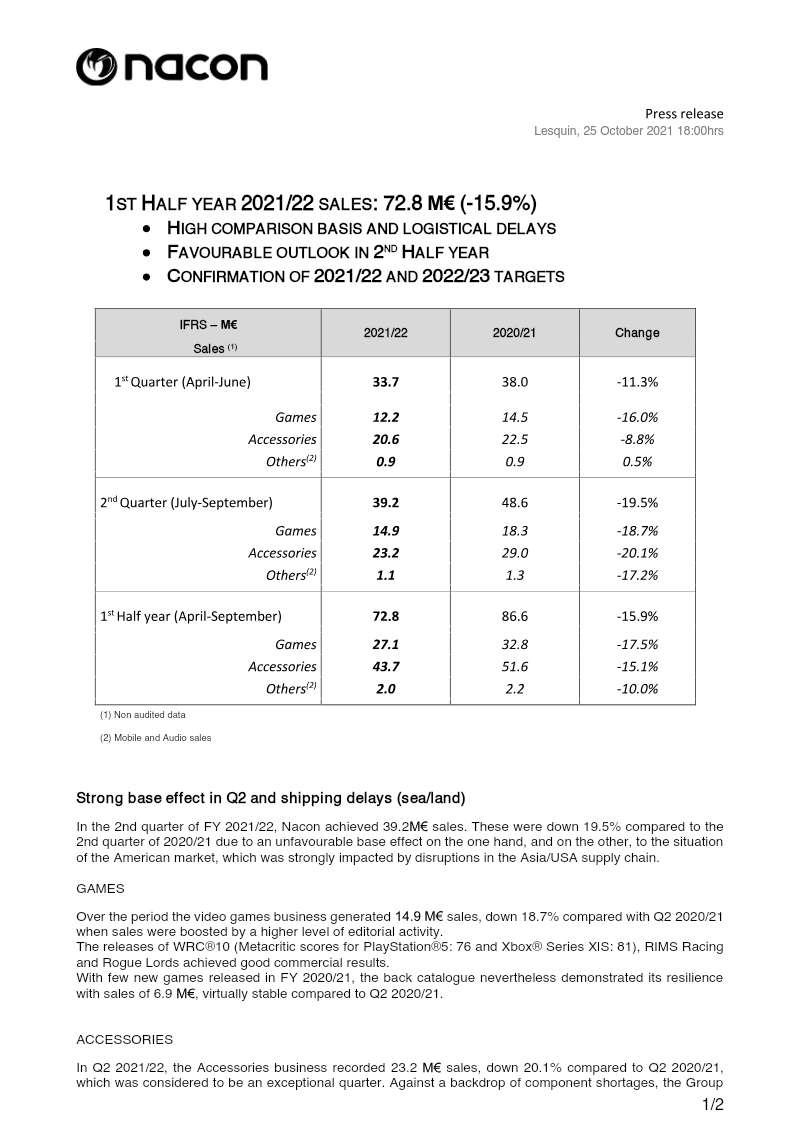
Nacon reported first‑half sales of €72.8 million in FY 2021/22, a decline of 15.9 % versus €86.6 million in the same period of FY 2020/21. The drop reflects a strong comparison base and logistical delays, particularly in the United States where supply‑chain disruptions affected shipments of PlayStation 4 and Xbox consoles. Games sales fell 18.7 % to €14.9 million, while accessories declined 20.1 % to €23.2 million; the “others” segment, comprising mobile and audio sales, saw a 17.2 % reduction to €1.1 million.
Quarterly performance mirrored the overall trend: Q2 sales of €39.2 million were 19.5 % lower than Q2 FY 2020/21, driven by a weaker base and shipping constraints. The company highlighted resilient back‑catalogue performance in games, with €6.9 million in sales that remained stable despite fewer new releases.
Looking ahead, Nacon expects a rebound in the second half of FY 2021/22, citing an expanded game slate—including Cricket 22, Rugby 22, Blood Bowl 3, Train Life, Hotel Life and the narrative RPG Vampire: The Masquerade – Swansong—and new accessories such as the Revolution X Pro controller. Management reaffirmed FY 2021/22 revenue targets of €180–200 million and a 20 % operating margin, while projecting FY 2022/23 sales of €230–260 million with a similar margin.
The company’s methodology relies on non‑audited IFRS data, covering global sales across 100 countries through its 20 subsidiaries and a network of distributors. Nacon’s strategy includes continued acquisitions of development studios, initiated in 2018, to expand its intellectual property portfolio and support future growth.
- Nacon reported first-half sales of €72.8 million for FY 2021/22, representing a 15.9% decline compared to the same period in the previous fiscal year.
- Management reaffirmed full-year revenue targets of €180–200 million with a 20% operating margin, projecting growth to €230–260 million for FY 2022/23.
- Sales performance across all segments declined, with games down 18.7% to €14.9 million, accessories down 20.1% to €23.2 million, and the 'others' segment down 17.2% to €1.1 million.
- The revenue drop was attributed to a strong comparison base from the previous year and supply-chain disruptions in the U.S. that delayed PlayStation 4 and Xbox console shipments.
- Despite fewer new releases, Nacon’s back-catalogue games remained resilient, contributing €6.9 million in stable sales.
+1
Nacon
Report311 pages
Universal Registration Document: 2021/2022
Société anonyme governed by a Board of Directors with share capital of €86,321,932 Registered office: 396/466 rue de la Voyette, CRT 2, 59273 Fretin, France Registration number: 852 538 461 RCS Lille Métropole UNIVERSAL REGISTRATION DOCUMENT Including the 2021/22 annual financial report This universal registration document (URD) was filed on 22 June 2022 with the Autorité des Marchés Financiers (“AMF”) as the competent authority in respect of regulation (EU) 2017/1129, without prior approval in ...
- Nacon's Video Games sales slowed significantly in 2021/22, down 21.2% to €54.4 million, primarily due to the postponement of four games, including "Vampire: The Masquerade®– Swansong" and "Blood Bowl 3®".
- Nacon has established key partnerships, including a long-standing relationship with Sony for premium and entry-level controllers, and a new major partnership with Microsoft (signed July 2020) for officially licensed Xbox accessories, which is expected to accelerate international Accessories business growth.
- Nacon's Accessories business experienced a slight dip in 2021/22 revenue compared to the previous year, which had a high base due to strong contributions from the first-time consolidation of RIG® premium headsets and lockdowns in the United States.
- Nacon invests heavily in R&D, particularly for its Nacon® brand accessories, leading to 70 registered patents for the Revolution controller alone and a perceived multi-year lead over competitors in technology.
- Nacon faces strong competition in attracting and retaining highly qualified technical personnel in France and abroad, necessitating an active human resources policy focused on recruitment, training, and retention through initiatives like professional databases, internships, and internal/external structures.
+2
Nacon
Report2 pages
Q1 2021/22 Sales: 33.7 M€
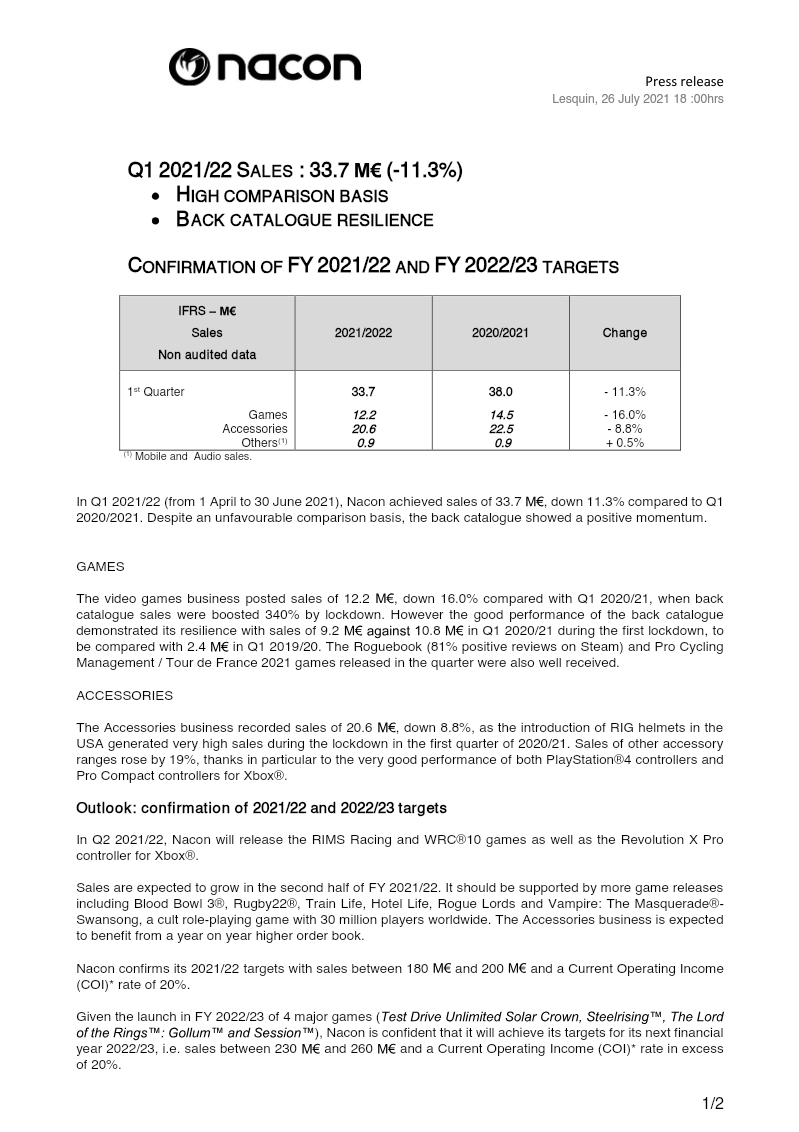
Nacon reported first‑quarter sales of €33.7 million for the period 1 April to 30 June 2021, a decline of 11.3 % versus the same quarter in 2020‑21. The drop reflects an unfavorable comparison basis, yet back‑catalogue performance remained resilient with €9.2 million in sales compared to €10.8 million during the initial lockdown, and a substantial 340 % lift in back‑catalogue revenue that quarter. Game sales fell 16 % to €12.2 million, while accessories declined 8.8 % to €20.6 million; the accessories segment benefited from a 19 % rise in non‑RIG helmet ranges, notably PlayStation 4 and Xbox® controllers. Mobile and audio sales remained flat at €0.9 million.
The company confirmed its 2021‑22 and 2022‑23 targets, projecting total annual sales of €180–200 million with a current operating income (COI) margin of 20 %. For FY 2022‑23, Nacon aims for €230–260 million in sales and a COI margin above 20 %, supported by four major game launches (Test Drive Unlimited Solar Crown, Steelrising™, The Lord of the Rings™: Gollum™, and Session™). Second‑half growth is expected from additional titles such as Blood Bowl 3®, Rugby22®, Train Life, Hotel Life, Rogue Lords, and Vampire: The Masquerade®‑Swansong. Nacon’s integrated structure—comprising 11 development studios, publishing of AA titles, and premium hardware design—underpins its strategy to leverage synergies across a global distribution network covering 100 countries. The company, listed on Euronext Paris, employs over 600 staff and operates through 16 subsidiaries.
- Nacon reported Q1 2021/22 sales of €33.7 million, representing an 11.3% decline compared to the same period in the previous fiscal year.
- The company maintained its financial guidance, targeting €180–200 million in sales for FY 2021-22 and €230–260 million for FY 2022-23, both with a current operating income margin of at least 20%.
- Segment performance saw game sales fall 16% to €12.2 million and accessories decline 8.8% to €20.6 million, though non-RIG helmet ranges and console controllers grew by 19%.
- Back-catalogue sales reached €9.2 million, showing resilience despite a difficult comparison against the previous year's lockdown-driven 340% revenue surge.
- Future growth is anchored by four major upcoming releases: Test Drive Unlimited Solar Crown, Steelrising, The Lord of the Rings: Gollum, and Session.
+3
Nacon
Report2 pages
Q4 2022-23 Sales and Annual Sales: FY 2022-23
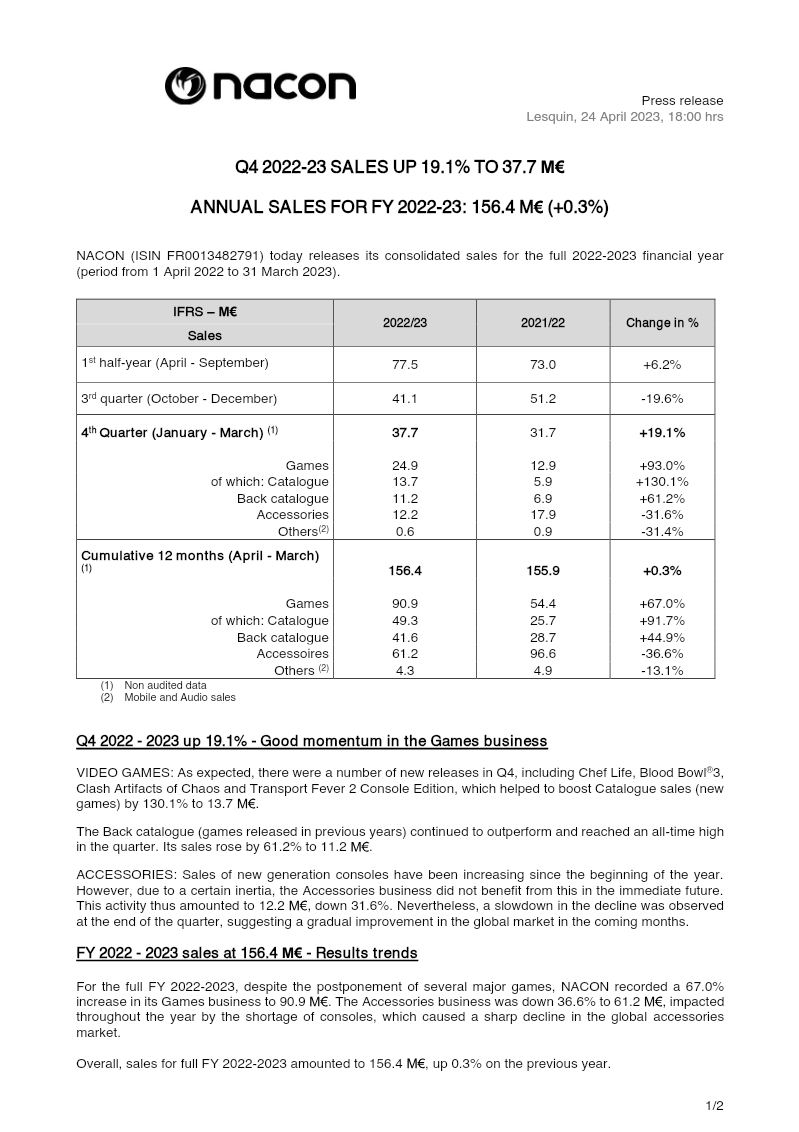
NACON reported consolidated sales for the fiscal year 1 April 2022 to 31 March 2023, with total revenue of €156.4 million, a marginal increase of 0.3 % over the prior year. Quarterly performance showed a strong rebound in Q4, where sales rose 19.1 % to €37.7 million after a 19.6 % decline in Q3. The Games segment dominated the growth, increasing by 67.0 % to €90.9 million for the full year; new‑catalogue sales surged 93.0 % to €24.9 million, driven by releases such as Chef Life and Transport Fever 2 Console Edition. Back‑catalogue sales also expanded, reaching an all‑time high of €11.2 million in Q4 and growing 61.2 % year‑over‑year. Accessories revenue fell 36.6 % to €61.2 million, largely due to a global console shortage that dampened demand for new‑generation hardware; however, the decline slowed in Q4, suggesting a potential rebound. Other categories, including mobile and audio sales, contracted 13.1 % to €4.3 million.
The company anticipates a decline in operating income before IFRS2 for FY 2023‑24 but expects overall operating and net income to rise. Management projects a robust publishing pipeline with roughly twenty titles slated for release, including high‑profile games such as The Lord of the Rings: Gollum and RoboCop: Rogue City. The back‑catalogue is expected to continue benefiting from the mechanical effect of new releases, while accessories sales should recover as console supply normalizes and new product offerings expand. NACON’s outlook remains positive, underscoring confidence in continued growth across its video‑game and accessories businesses.
- NACON reported total annual revenue of €156.4 million for FY 2022-23, representing a marginal 0.3% increase over the previous fiscal year.
- The Games segment drove growth with a 67.0% annual increase to €90.9 million, bolstered by a 93.0% surge in new-catalogue sales from titles like Chef Life and Transport Fever 2 Console Edition.
- Accessories revenue declined 36.6% to €61.2 million for the year, primarily attributed to global console shortages, though the segment showed signs of a Q4 recovery.
- After a 19.6% decline in Q3, NACON experienced a strong Q4 rebound with total sales rising 19.1% to €37.7 million.
- Back-catalogue sales reached an all-time high of €11.2 million in Q4, contributing to a 61.2% year-over-year growth for that category.
+2
Nacon