Investment reports and market data
Documents
MTG Capital Markets Day 2025
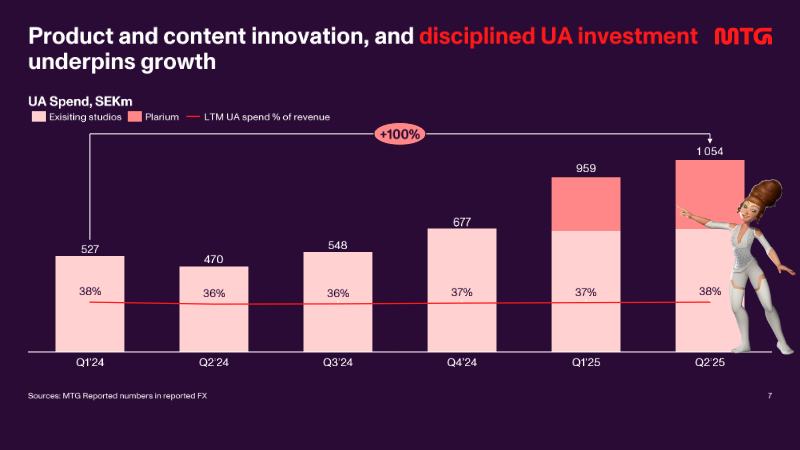
MTG’s 2025 Capital Markets Day presentation outlines a strategic roadmap for sustained growth, operational efficiency, and value creation within the global mobile gaming sector.
- MTG has achieved an LTM revenue of approximately SEK 6.1 billion as of Q2 2025, following the acquisition of Plarium which doubled the company's size.
- The company is targeting medium-term organic revenue growth of 3% to 7% and an adjusted EBITDA margin exceeding 24%.
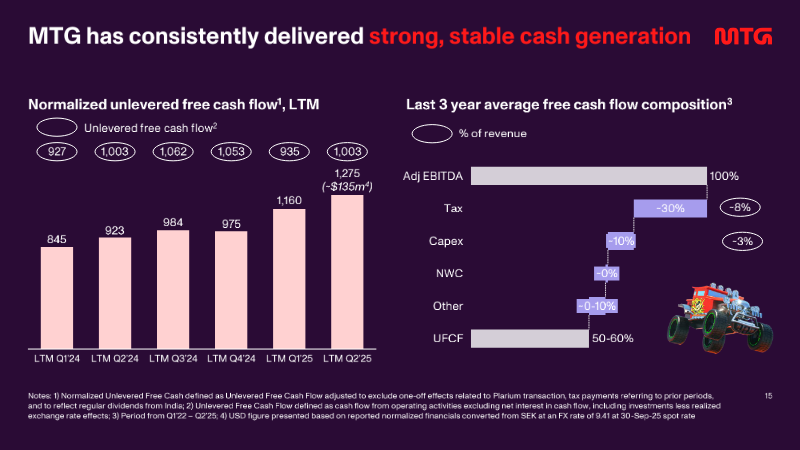
- MTG generated SEK 1.275 billion in normalized unlevered free cash flow and has launched a new SEK 400 million share repurchase program.
Acquisition: Versus Evil and Red Cerberus
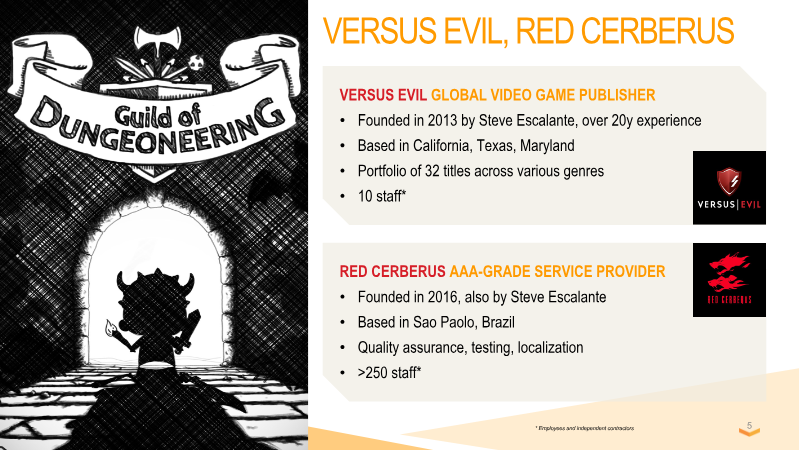
TinyBuild Inc. has finalized the acquisition of Versus Evil, a global video game publisher, and Red Cerberus, a Brazil-based AAA-grade service provider.
- TinyBuild Inc. acquired publisher Versus Evil and service provider Red Cerberus for a total maximum consideration of $31.3 million, consisting of $12.5 million in upfront cash and up to $18.8 million in deferred share-based payments.
- The acquisition is projected to be marginally accretive in 2021 and approximately 10% accretive to earnings in 2022.
- The combined entities generated $12 million in revenue with an EBITDA loss of $0.2 million during the 2020 fiscal year.
Konami Group Report: Fiscal 2022
The Konami Group Fiscal 2022 report outlines a period of record-breaking financial performance and strategic organizational evolution.
- Konami achieved record-high financial results for fiscal 2022, with total revenue reaching ¥299.5 billion (a 9.9% increase) and profit attributable to owners of the parent rising 69.9% to ¥54.8 billion.
- Operating profit saw a significant 103.6% year-on-year increase to ¥74.4 billion, while business profit grew 25.2% to ¥80.3 billion.
- The Digital Entertainment segment saw strong performance driven by mobile and console titles, including the launch of 'Yu-Gi-Oh! MASTER DUEL,' which surpassed 30 million downloads within three months of its January 2022 release.
2023 M&A Outlook: Post-Pandemic Boom
The 2023 M&A Outlook provides a strategic assessment of the technology mergers and acquisitions landscape following the record-breaking activity of 2021 and the subsequent market cooling in 2022.
- Strategic necessity is driving a shift toward consolidation in 2023, as mature corporations prioritize acquiring disruptive, value-add companies to maintain innovation despite macroeconomic volatility.
- The market has shifted toward an 'M&A barbell effect,' where investors avoid early-stage, cash-burning startups and high-valuation unicorns in favor of companies with sustainable revenue and cash flow growth.
- While 2023 deal volume will not reach the record-breaking levels seen in 2021, robust deal flow is expected to persist due to significant dry powder held by private equity firms and large-cap corporations.
Video Game Market Update: Q3 2026
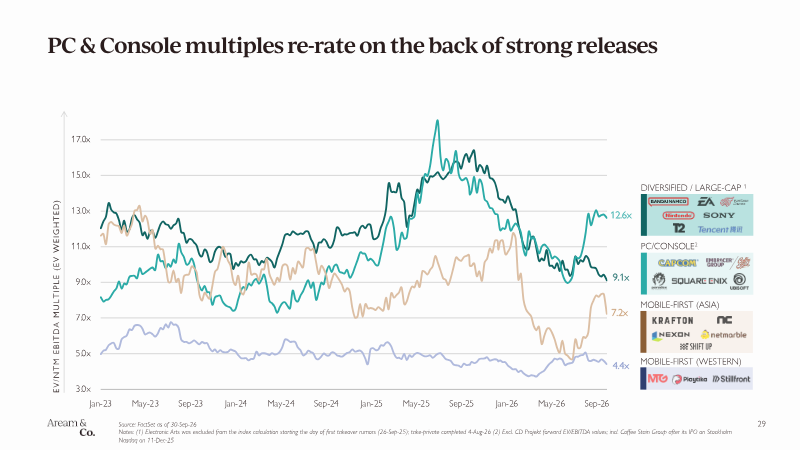
The global video game industry experienced a period of significant structural divergence during the third quarter of 2026.
- The global video game industry saw a $57.8 billion surge in M&A activity in Q3 2026, driven primarily by the $55 billion take-private acquisition of Electronic Arts.
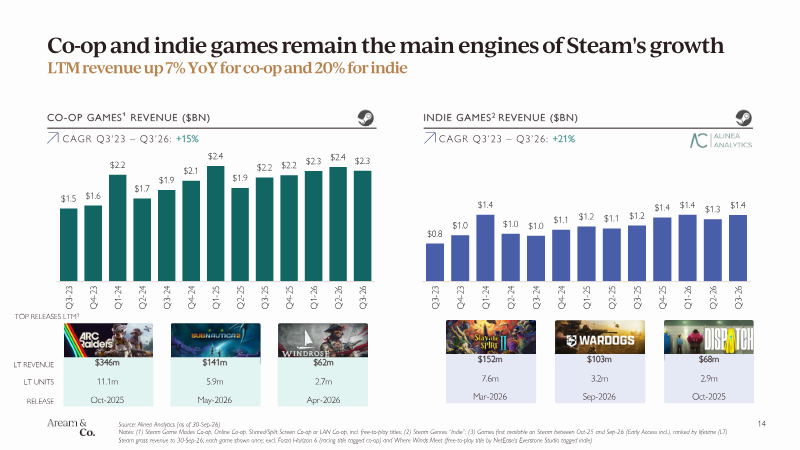
- Market performance was structurally divergent, with double-digit revenue growth on Steam contrasting against year-over-year declines of 12% in the console segment and 7% in mobile.
- Investment capital is shifting toward late-stage rounds and AI-driven firms, while seed-stage funding has dropped to a five-year low.
Global Video Gaming: The State of Play, 2025
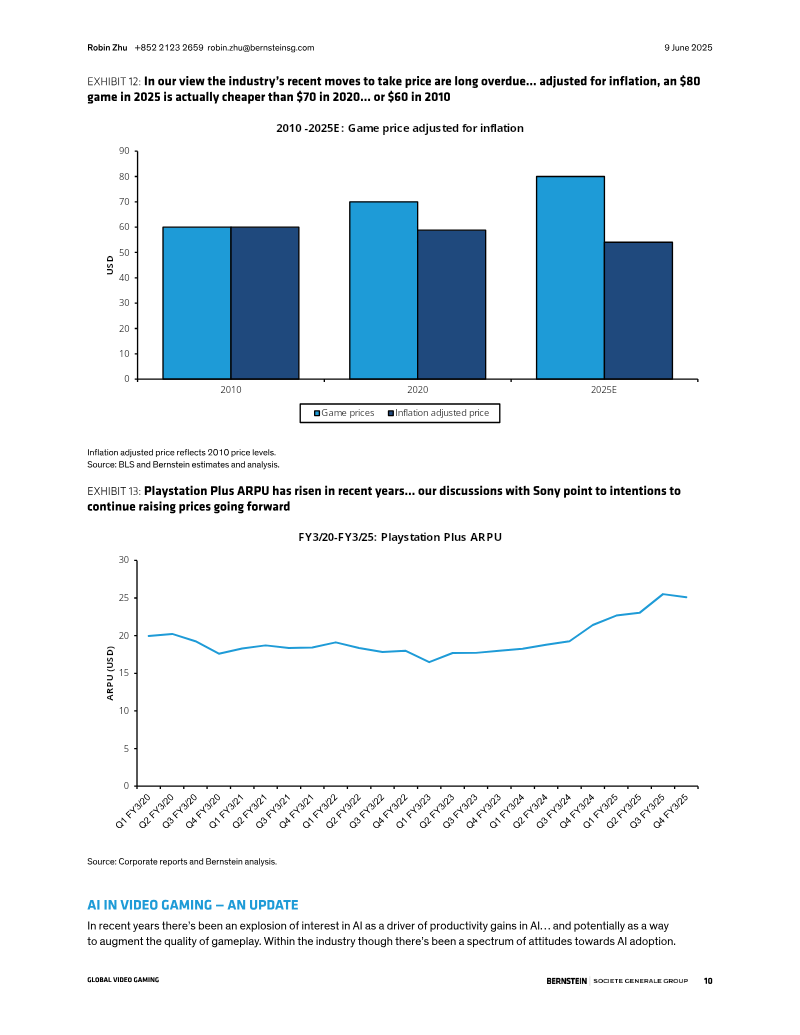
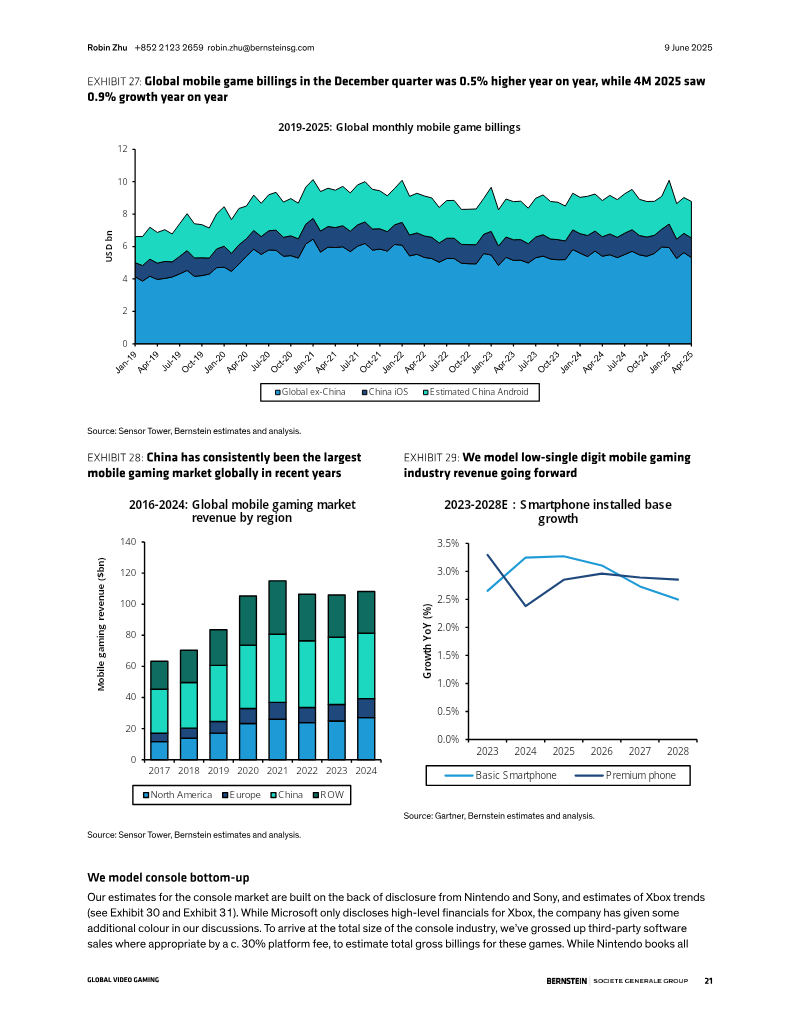
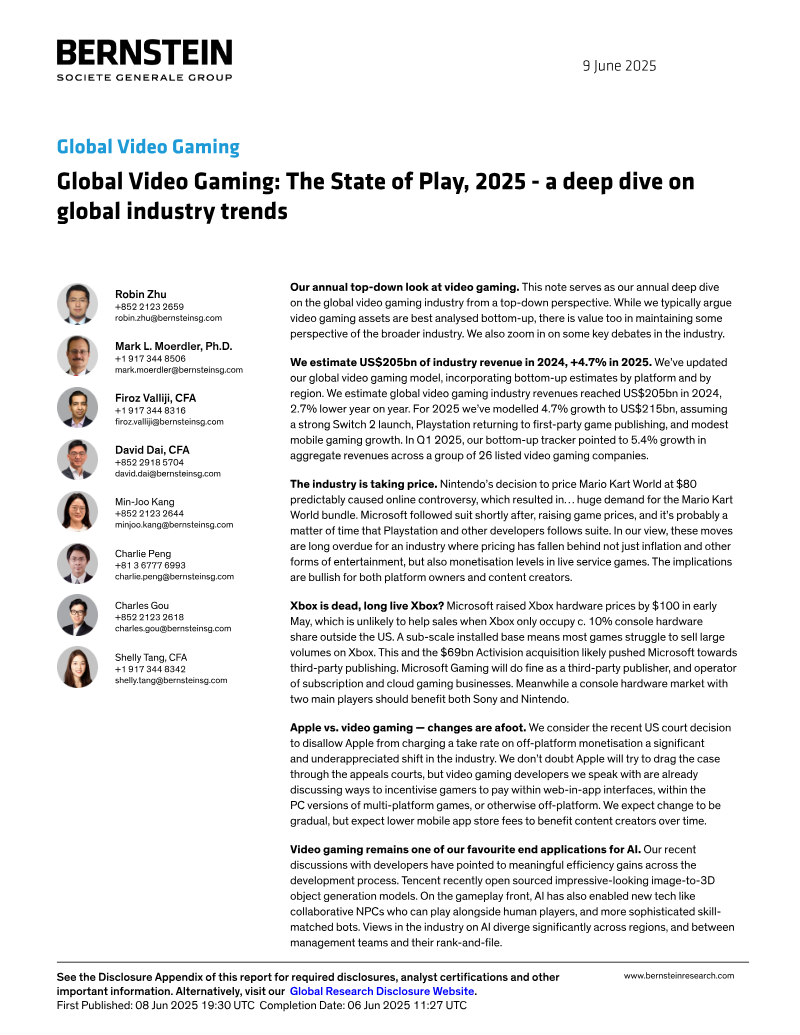
The global video gaming industry is entering a phase of stabilization and renewed growth, with total revenue projected to reach US$215 billion in 2025, representing a 4.7% increase following a 2.7% decline in 2024.
- The global video gaming industry is projected to reach $215 billion in revenue in 2025, marking a 4.7% recovery following a 2.7% decline in 2024.
- Major industry players are shifting from hardware-centric models to software-led growth, exemplified by Microsoft’s pivot toward third-party publishing and the expansion of Game Pass and cloud services.
- The PC gaming ecosystem, led by Steam, has emerged as a primary driver of industry expansion, offsetting the recalibration occurring within the console market.
Global Gaming Report Q1 2026
The global gaming industry experienced a complex start to 2026, characterized by a sharp divergence between high-level strategic consolidation and broader market volatility.
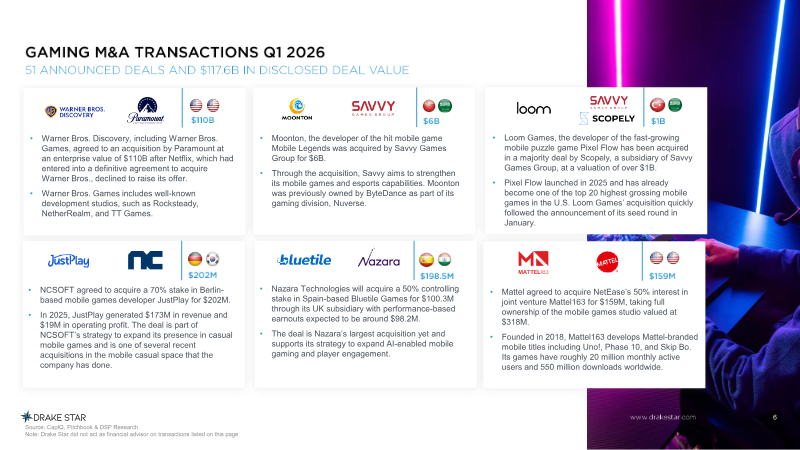
- M&A activity reached a 15-month peak in Q1 2026 with 51 transactions totaling over $100 billion, headlined by the Paramount acquisition of Warner Bros. Discovery and Savvy Games Group's purchase of Moonton.
- Private financing remained steady with $785 million raised across 106 deals, showing a clear investor preference for AR/XR hardware and infrastructure over traditional software.
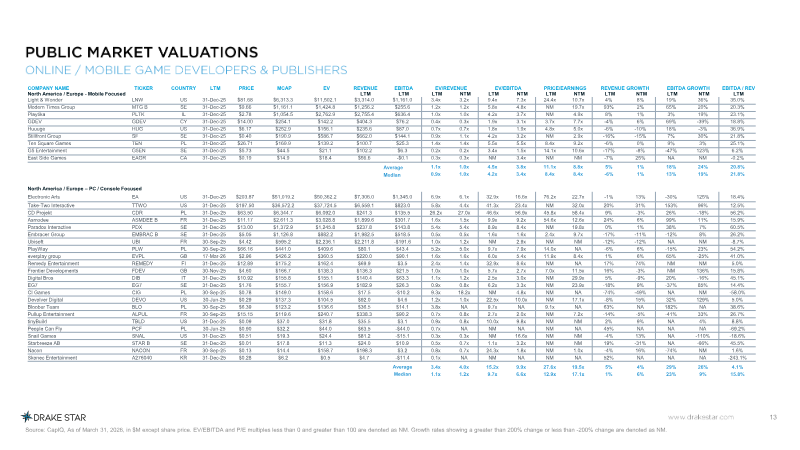
- The Drake Star Gaming Index declined by 1.8 percent, driven by market weakness in Western regions and the mobile gaming sector.
Gaming's Renaissance: From Ancient Origins to Digital Domination
The gaming and eSports industry has entered a phase of robust recovery, transitioning from a post-pandemic adjustment period to a trajectory of sustained long-term growth.
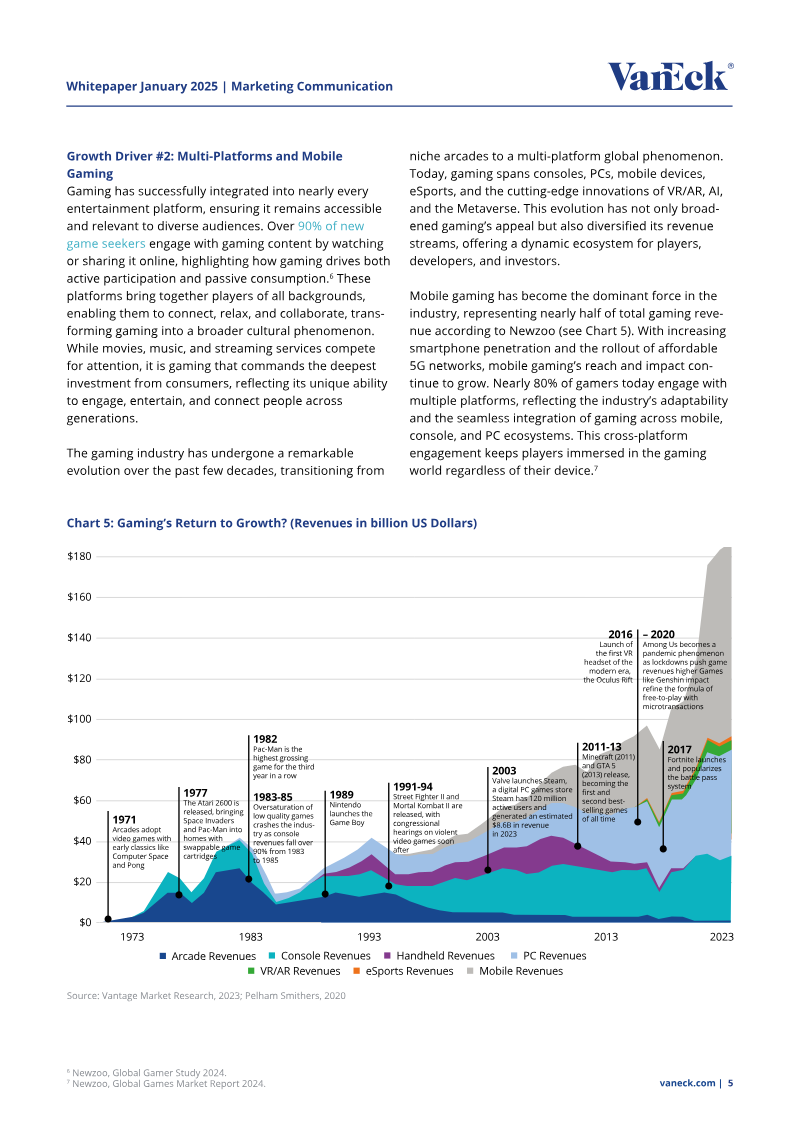
- The gaming and eSports industry is projected to reach $257 billion in annual revenue by 2028, reflecting a sustained 6% annual growth rate.
- The global gamer population reached 3.42 billion in 2024, cementing the sector's transition from a niche market to a pillar of global entertainment.
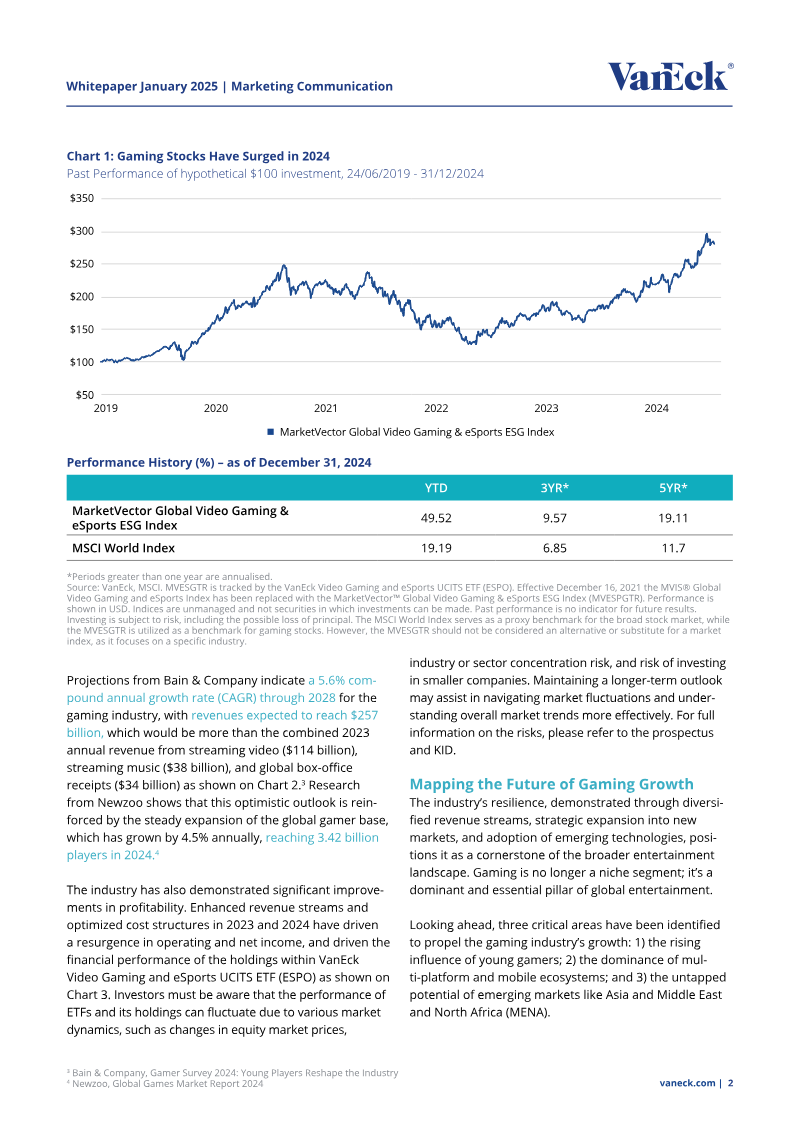
- Investor confidence in the sector has surged, with the MarketVector Global Video Gaming & eSports ESG Index recording a 49.5% increase in 2024.
Video Game Market Update: Q2 2026
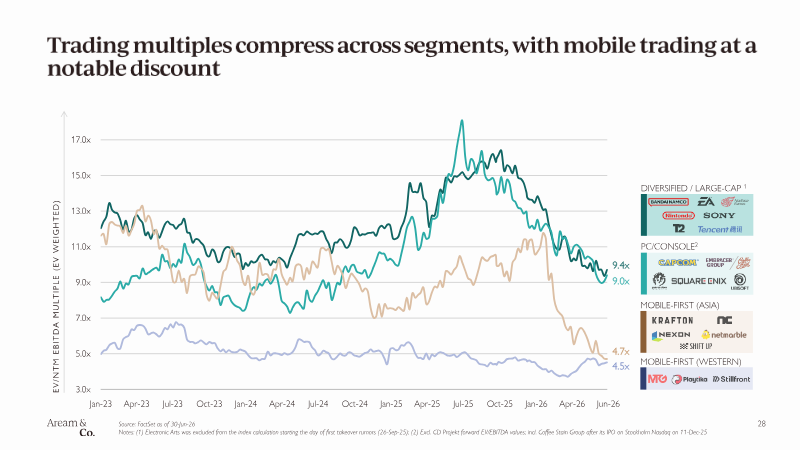
The global video game industry experienced a period of divergent performance during the second quarter of 2026, characterized by a resilient PC sector and a stagnant console market.
- Private investment in the gaming sector surged sixfold year-over-year to $3.1 billion, with capital increasingly shifting away from content development toward infrastructure, AI, adtech, and immersive hardware.
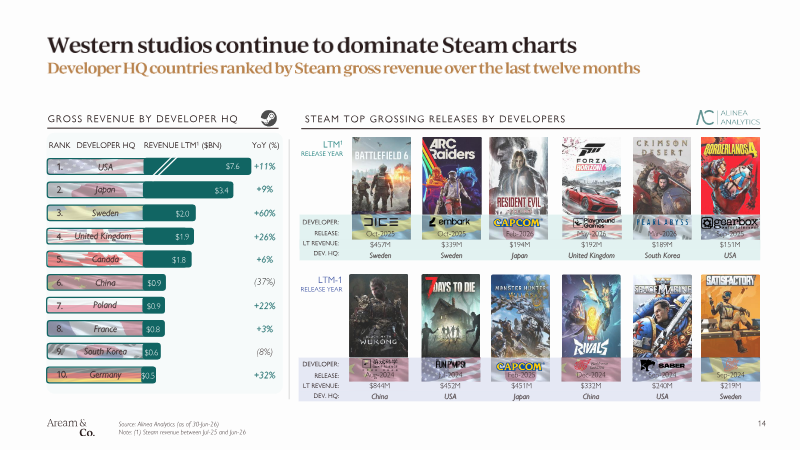
- The PC sector remains a primary growth driver with Steam recording a 13 percent year-over-year revenue increase, while the console market remains stagnant as Switch 2 gains offset declines in PlayStation and Xbox hardware.
- Mobile gaming is facing a downturn, evidenced by a 4 percent contraction in gross revenue and a 12 percent decline in new installs, with top charts remaining stagnant due to a reliance on legacy titles.
Is There a Shift from Content to Tech Startups Among Gaming VCs?
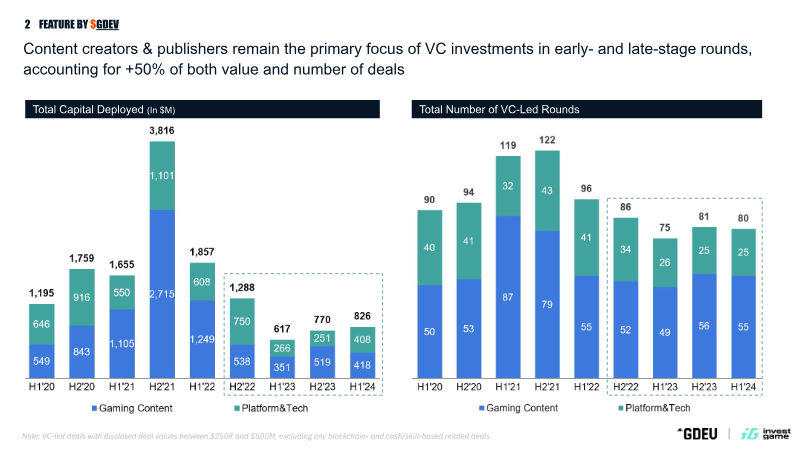
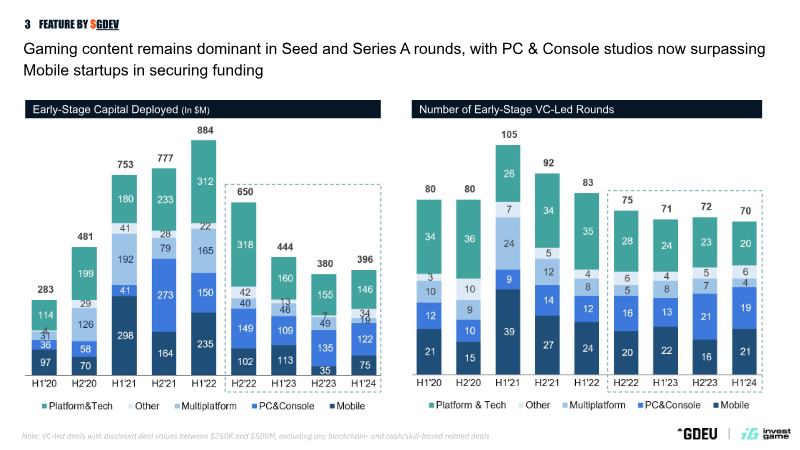
The analysis examines venture capital activity in the gaming sector from 2020 to early 2024, focusing on whether investment priorities are shifting from traditional content creation and publishing toward technology-driven startups.
- Content creators and publishers remain the primary focus of gaming VC, accounting for over half of all capital deployed (approximately $1.76 billion) and the majority of deal volume across all stages.
- Gaming-focused VC funds, including VENTURES, BEHOLD Venture, and Lightspeed Lvp., significantly increased their activity between 2020 and H1 2024, with capital deployed rising from $1.3 billion to over $2.4 billion.
- The number of VC-led funding rounds grew substantially from 67 in early 2020 to 289 by H1 2024, reflecting an overall increase in investment activity.
Europe’s Gaming Consolidators: The Magnificent Seven Post-M&A Rush
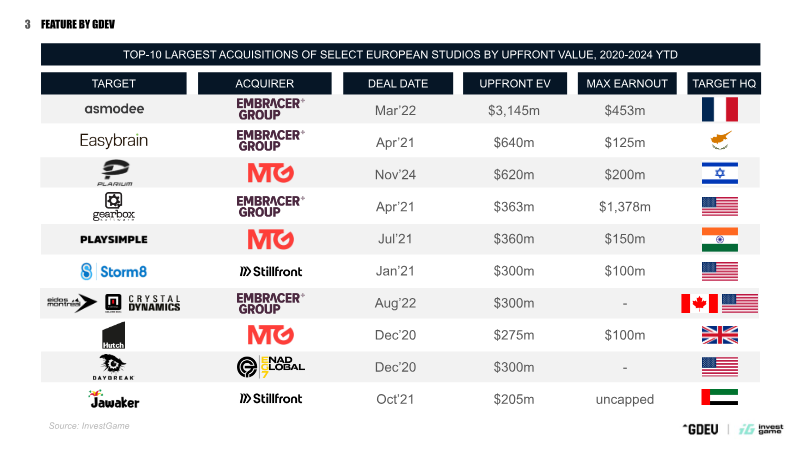
The analysis examines the surge of M&A activity among European gaming publishers between 2020 and 2024, highlighting a capital deployment of $19 billion across more than 140 deals.
- Between 2020 and 2024, seven major European gaming consolidators deployed $19 billion across over 140 deals, with mienn Easybrain Group accounting for 78 deals totaling $14.1 billion.
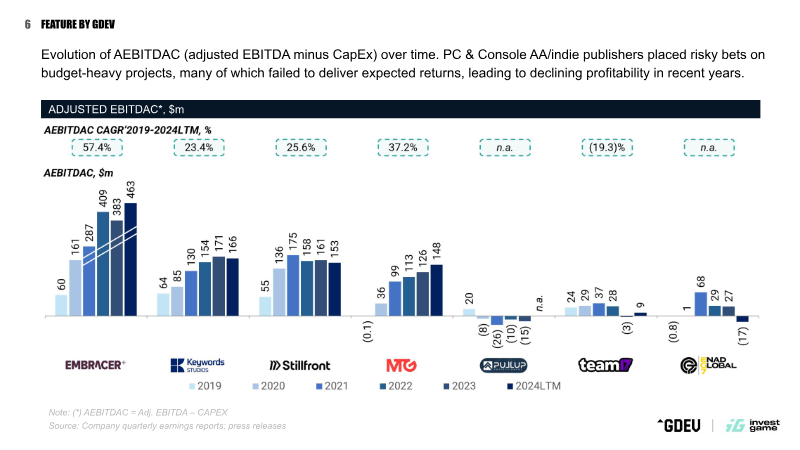
- Aggressive inorganic growth strategies failed to deliver sustainable shareholder value, as evidenced by a market cap collapse from a $25.5 billion peak in April 2021 to approximately $5.4 billion.
- Share prices for the primary acquirers corrected significantly, falling 30–70% from December 2019 levels as valuation multiples contracted from highs of 30× EV/NTM revenue.
The Alumni Effect: Studios Founded by Ex-Activision, Blizzard, and King Employees
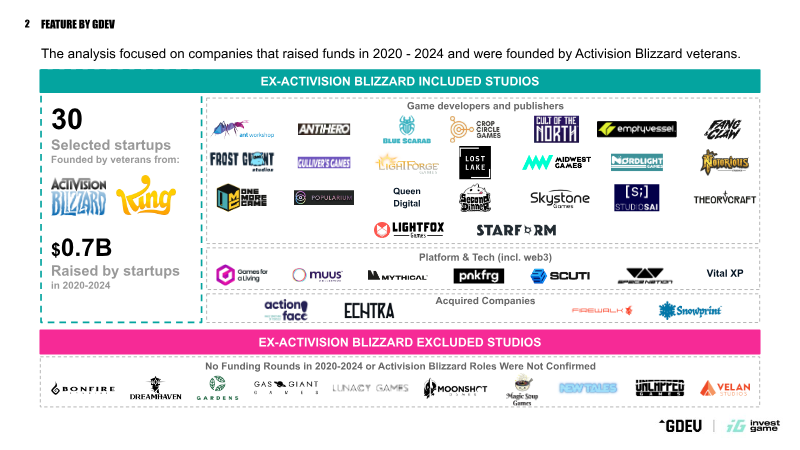
The analysis examines venture capital activity directed toward studios founded by former Activision Blizzard employees between 2020 and 2024.
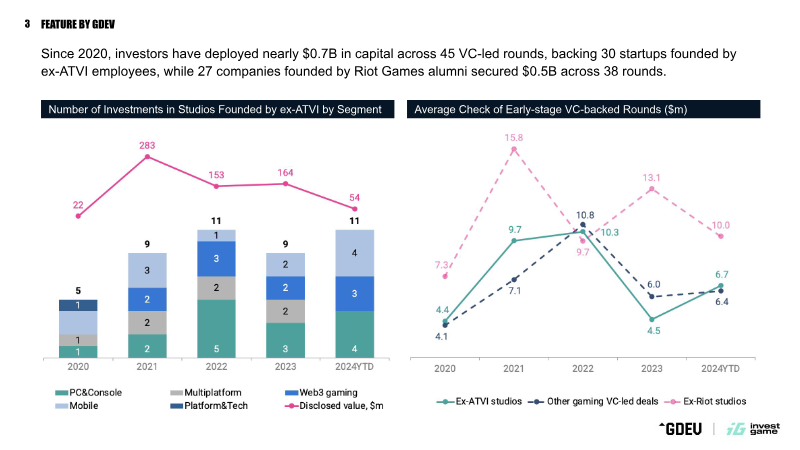
- Between 2020 and 2024, 30 studios founded by former Activision Blizzard employees secured approximately $0.7 billion in venture capital across 45 funding rounds.
- Ex-Activision studios demonstrate a 'first-round momentum' effect, being roughly four times more likely than peer startups to secure a second round of financing within the same calendar year.
- Investor confidence in alumni teams peaked in 2021, when 43% of ex-Activision studios raised a subsequent round compared to only 9% of broader gaming startups.