Global reports and market data
Documents
2023 M&A Outlook: Post-Pandemic Boom
The "2023 M&A Outlook: Post-Pandemic Boom" report, authored by Gregory Bedrosian of Drake Star, analyzes the trajectory of technology mergers and acquisitions following the "great acceleration" observed during the COVID-19 pandemic.
- Strategic necessity is driving a shift toward consolidation in 2023, as mature corporations prioritize acquiring disruptive, value-add companies to maintain innovation despite macroeconomic volatility.
- The market has shifted toward an 'M&A barbell effect,' where investors avoid early-stage, cash-burning startups and high-valuation unicorns in favor of companies with sustainable revenue and cash flow growth.
- While 2023 deal volume will not reach the record-breaking levels seen in 2021, robust deal flow is expected to persist due to significant dry powder held by private equity firms and large-cap corporations.
Video Game Market Update: Q3 2026
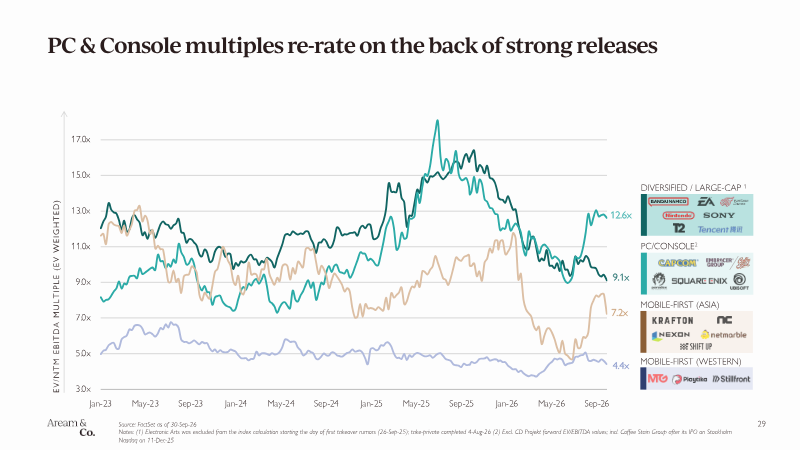
The "Video Game Market Update: Q3 2026" provides a comprehensive overview of the global video game industry's performance and trends during the third quarter of 2026, with some data extending to a trailing twelve-month (LTM) period.
- The global video game industry saw a $57.8 billion surge in M&A activity in Q3 2026, driven primarily by the $55 billion take-private acquisition of Electronic Arts.
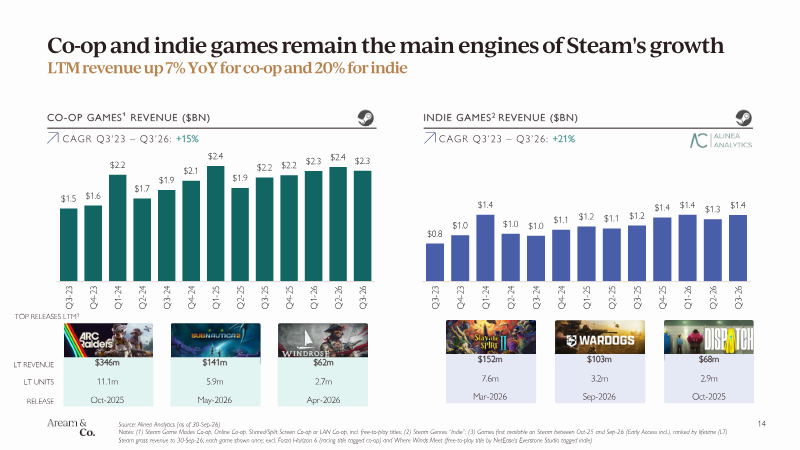
- Market performance was structurally divergent, with double-digit revenue growth on Steam contrasting against year-over-year declines of 12% in the console segment and 7% in mobile.
- Investment capital is shifting toward late-stage rounds and AI-driven firms, while seed-stage funding has dropped to a five-year low.
Korea's Game Exports: Reading Beyond the Aggregate Numbers
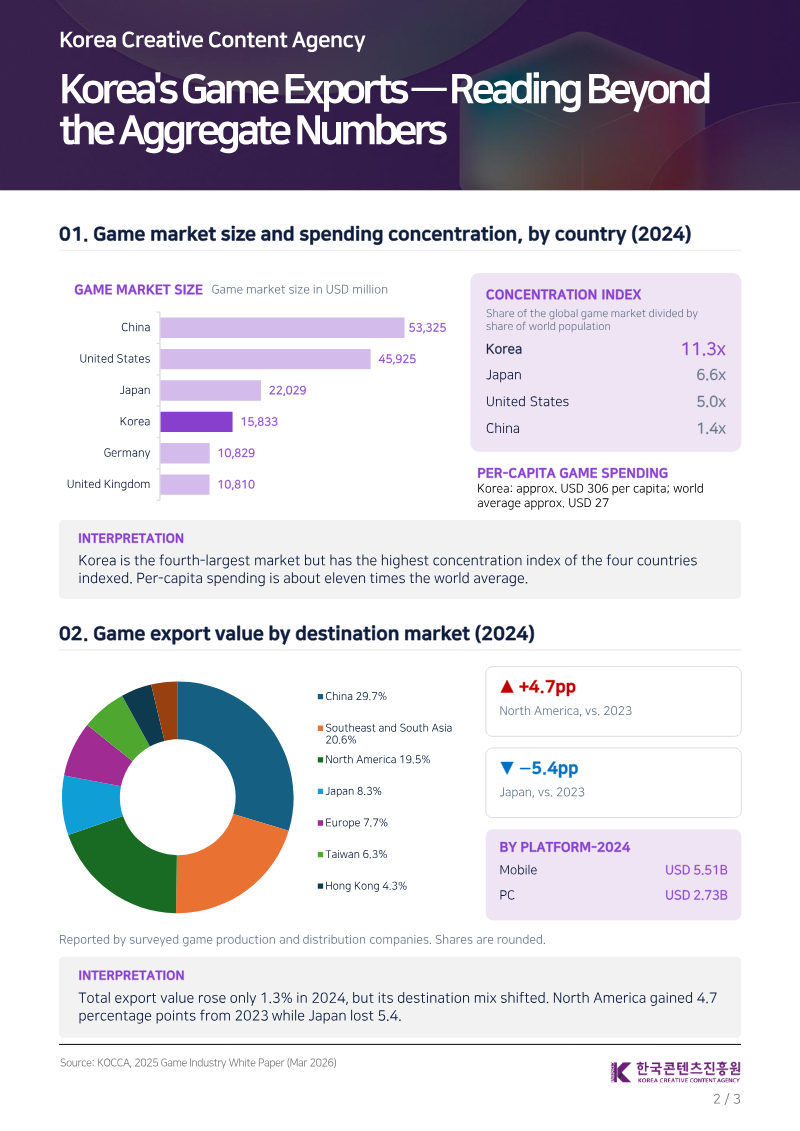
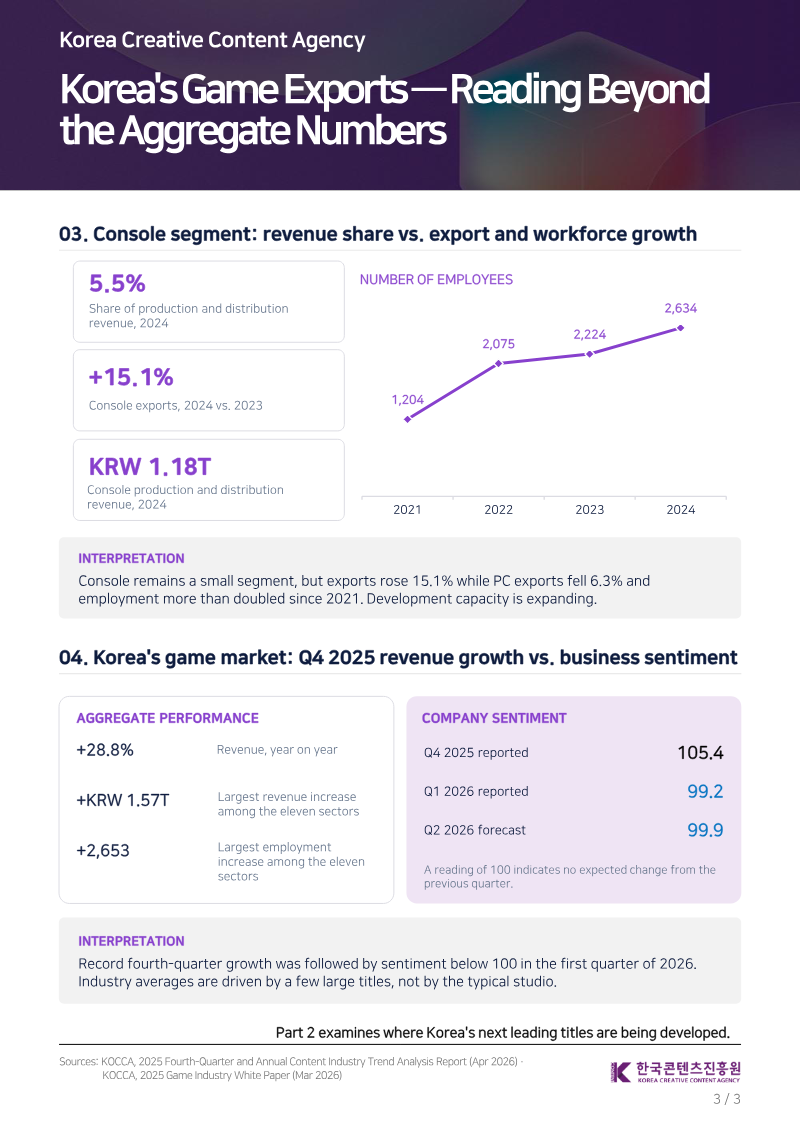
Korea's game industry posted strong aggregate results in 2025, but those figures mask a concentration in a small number of large titles, so overseas buyers should evaluate developers at the title and studio level rather than relying on industry averages.
- The South Korean game industry generated USD 8.60 billion in exports in 2025, representing 57.7% of the nation's total content export value.
- Console game exports grew by 15.1% in 2024, supported by a workforce that has more than doubled since 2021 as studios pivot development capacity.
- Mobile gaming remains the primary revenue driver, accounting for USD 5.51 billion of the industry's export total.
Global Gaming Report 2025
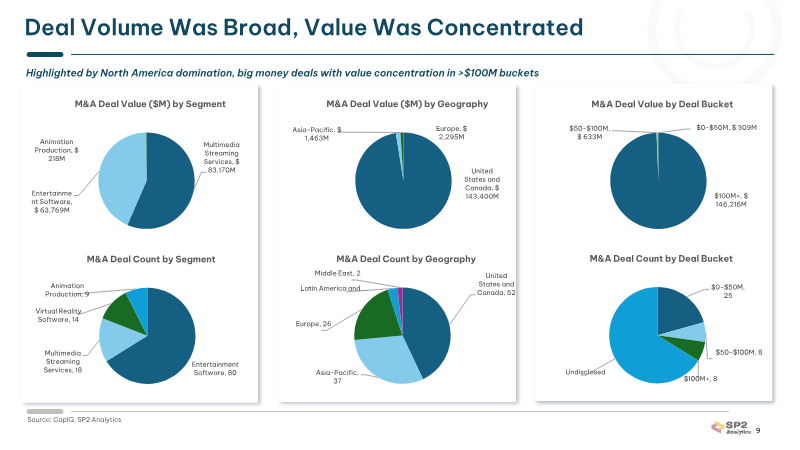
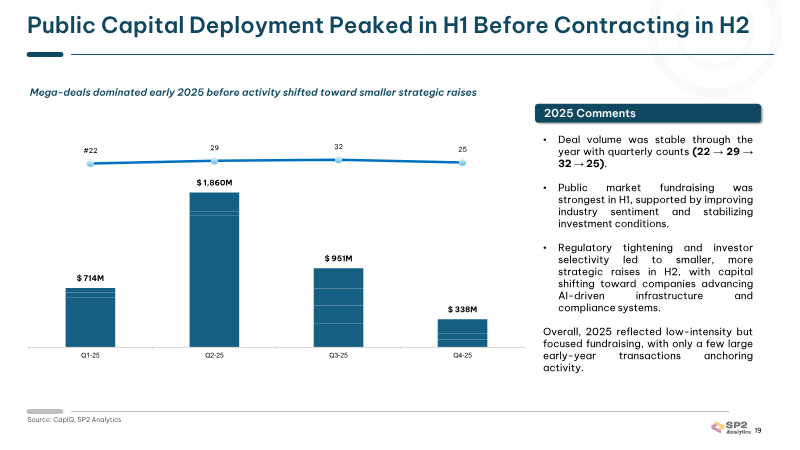
The "Global Gaming Report 2025" provides a comprehensive overview of the gaming industry's financial landscape in 2025, focusing on M&A, private placement, and public market activities.
- The gaming industry saw $147 billion in M&A activity in 2025, headlined by the $83 billion Netflix-Warner Bros. merger and the $55 billion take-private acquisition of Electronic Arts.
- Market valuation is increasingly driven by platform ownership and IP aggregation, with top-tier strategic players now commanding EV/EBITDA multiples exceeding 25x.
- Capital deployment has become highly concentrated, with private placement rounds for AI-driven simulation and development tools consistently exceeding $100 million per transaction.
Global Gaming Report Q1 2026
The "Global Gaming Report Q1 2026" provides a comprehensive analysis of the global gaming industry's financial and market performance during the first quarter of 2026, offering insights into investment trends, public market valuations, and regional dynamics.
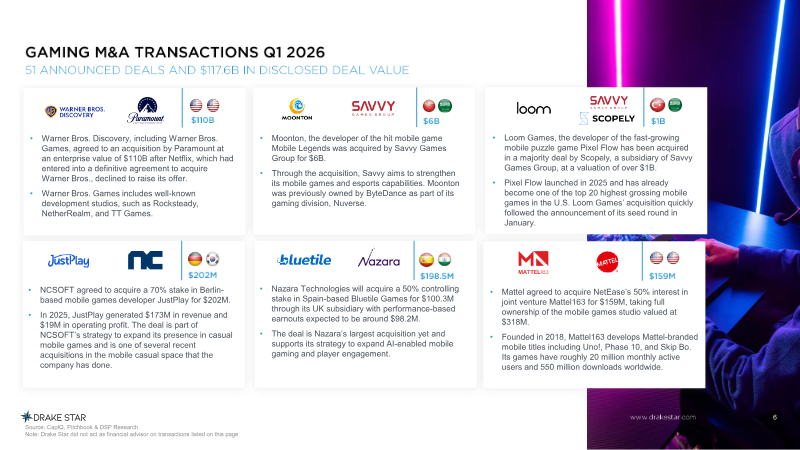
- M&A activity reached a 15-month peak in Q1 2026 with 51 transactions totaling over $100 billion, headlined by the Paramount acquisition of Warner Bros. Discovery and Savvy Games Group's purchase of Moonton.
- Private financing remained steady with $785 million raised across 106 deals, showing a clear investor preference for AR/XR hardware and infrastructure over traditional software.
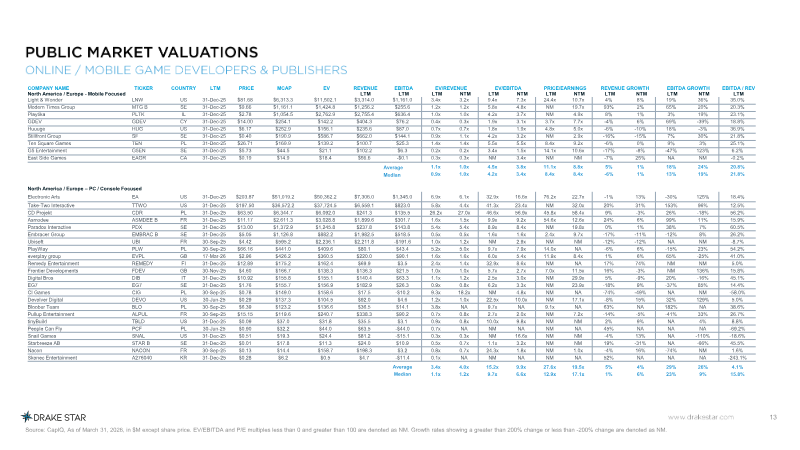
- The Drake Star Gaming Index declined by 1.8 percent, driven by market weakness in Western regions and the mobile gaming sector.
State of the Industry 2019: Mental Health in the Game Industry
The "State of the Industry 2019: Mental Health in the Game Industry" document comprehensively examines the significant mental health challenges prevalent within the global game development sector, primarily focusing on the period leading up to 2019.
- Systemic organizational failures, specifically the normalization of chronic overwork known as crunch, are the primary drivers of a pervasive mental health crisis and burnout among game developers.
- Job instability caused by frequent layoffs and a lack of professional security creates a high-stress environment that threatens the long-term sustainability of the industry workforce.
- Exclusionary workplace cultures—characterized by harassment and microaggressions toward women, LGBTQ+ individuals, people of color, and neurodivergent employees—stifle team creativity and degrade the quality of game content.
Gaming Trendz to Watch in 2025 and Beyond: Comprehensive Player Support Strategies
This executive brief, "Gaming Trendz to Watch in 2025 and Beyond: Comprehensive Player Support Strategies," analyzes key trends shaping the video game industry and proposes strategies for player support.
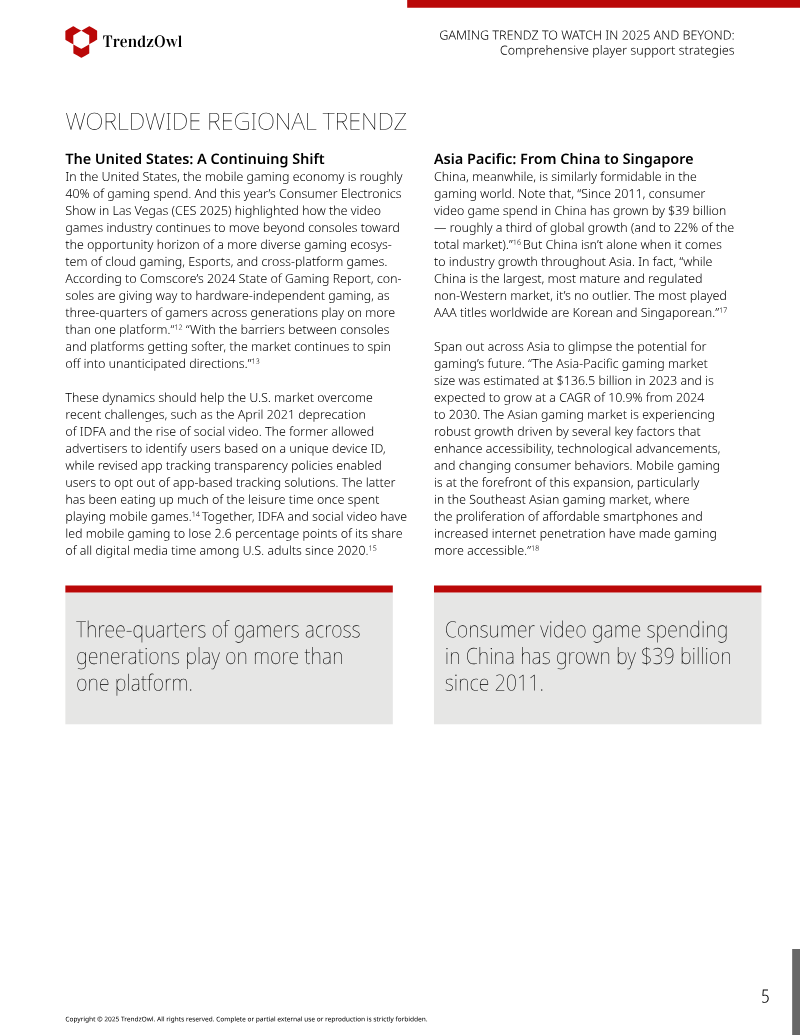
- The gaming industry is shifting toward a mobile-first, hardware-independent model, with mobile gaming now capturing 55% of the total market share.
- Providing a diverse range of contact options for player support increases customer loyalty by 41%.
- The Asia-Pacific region is projected to maintain a 10.9% compound annual growth rate through 2030, while Africa’s market is expanding six times faster than the global average.
State of the Industry Report 1999
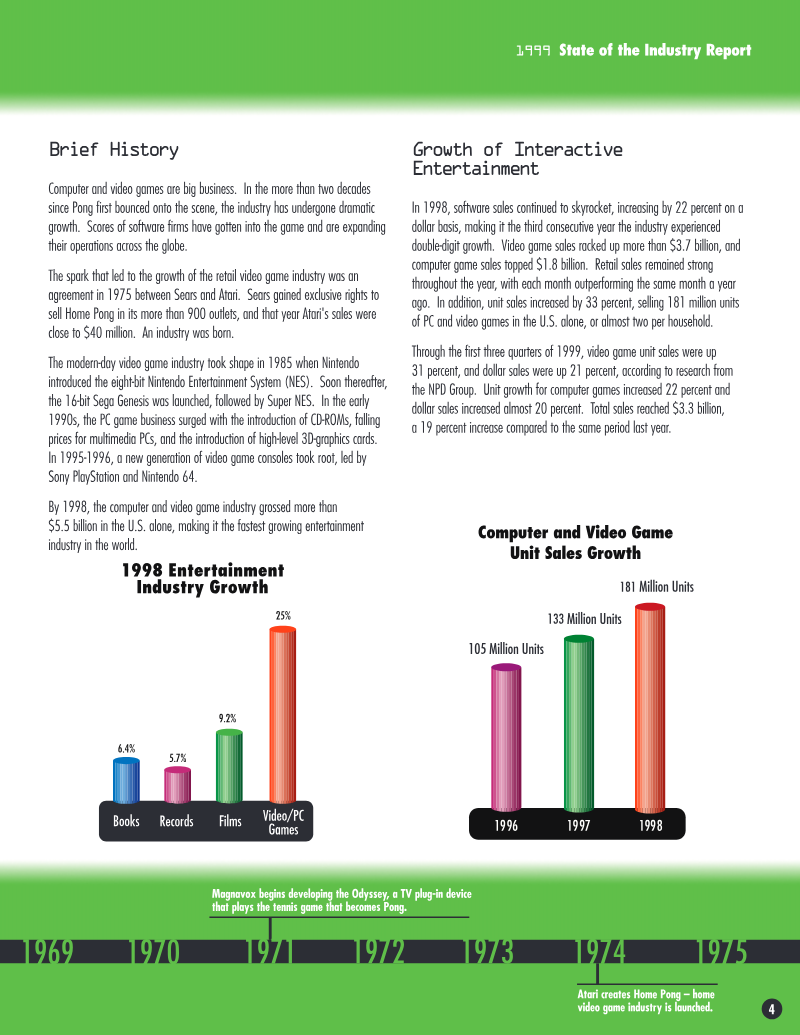
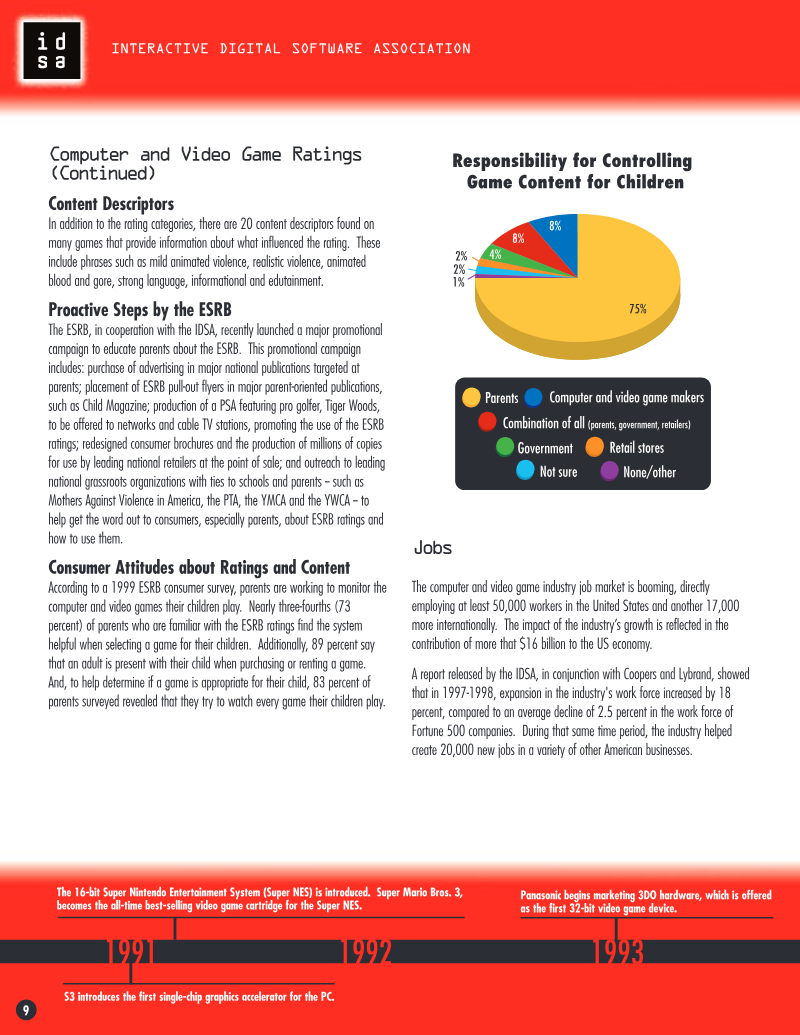
The 1999 State of the Industry Report, published by the Interactive Digital Software Association (IDSA), provides an overview of the computer and video game industry's growth, demographics, economic impact, and challenges as of 1999.
- The U.S. interactive entertainment industry reached $5.5 billion in sales by 1998, marking three consecutive years of double-digit growth and positioning software revenue to rival motion picture box office receipts by the end of 1999.
- The industry is a significant economic driver, directly employing 50,000 workers in the U.S. and contributing over $16 billion to the national economy.
- Gaming has shifted to a mainstream adult demographic, with individuals aged 18 or older now comprising 69 percent of PC players and 54 percent of console players.
Q3 2015 Data Digest
This Q3 2015 data digest provides an analysis of the iOS app market, focusing on downloads, revenue, top publishers, and advertising insights.
- Gaming remains the dominant App Store category, generating over 20 times the revenue of the next leading category.
- Clash of Clans maintained its lead in Q3 2015, though Game of War significantly narrowed the revenue gap in the U.S. market.
- Aggressive advertising on the Facebook network, particularly using high-production image and video assets, shows a strong correlation with increased revenue for gaming and lifestyle apps like those from ContextLogic.
The State of Card Battler Mobile Games 2021: An Analysis of the Card Battler Sub-Genre
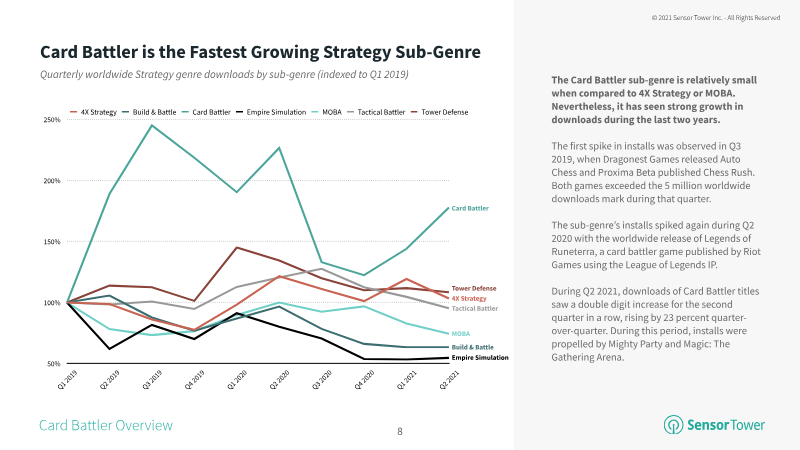
This analysis provides an overview of the mobile card battler sub-genre, examining its market landscape, top titles, and growth opportunities globally and specifically within the U.S. market.
- The United States has become a critical growth market for card battlers, accounting for 27% of global player spending in the first half of 2021.
- U.S. card battlers exhibit a revenue-per-download (RPD) nearly double the worldwide average and are experiencing the fastest RPD growth among all strategy sub-genres.
- The market is currently dominated by established 'forever franchises' such as Yu-Gi-Oh! Duel Links and Hearthstone, alongside successful new entrants like Magic: The Gathering Arena.
An Analysis of Download Sources on Apple's App Store 2021
This report analyzes the sources of first-time app downloads on Apple's App Store, covering trends between 2018 and 2020, and segmenting data by app characteristics, categories, and time since launch.
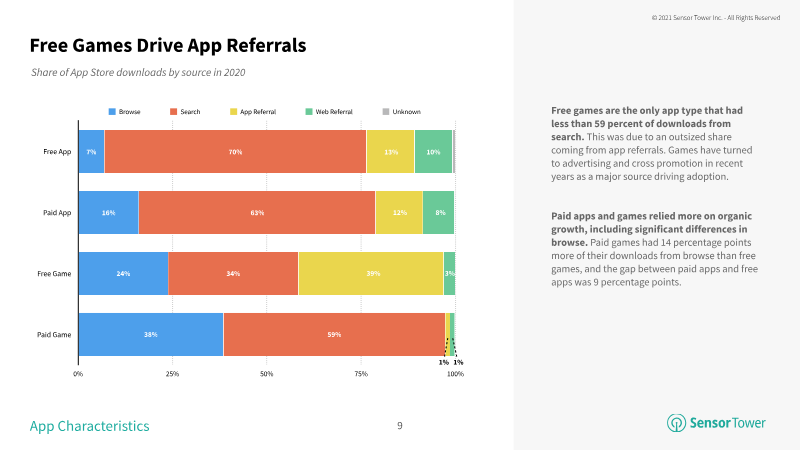
- Search is the primary discovery mechanism for the App Store, accounting for 59% of all first-time downloads in 2020.
- Non-game applications rely heavily on search for user acquisition, with 70% of their total downloads originating from this channel.
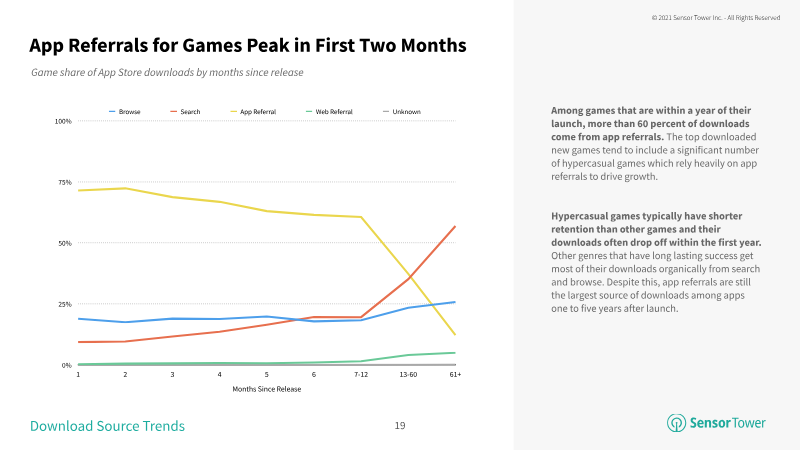
- App referrals for games grew from 26% in 2018 to 38% in 2020, driven largely by the hypercasual genre's reliance on cross-promotion.
Live-Streaming Trends Report: Q1 2026
The "Live-Streaming Trends Report: Q1 2026" provides a comprehensive analysis of the global live-streaming landscape during the first quarter of 2026, examining platform performance, content consumption patterns, and emerging industry trends.
- Live-streaming reached 17 billion hours watched in Q1 2026, with TikTok Live accounting for nearly 50% of total volume.
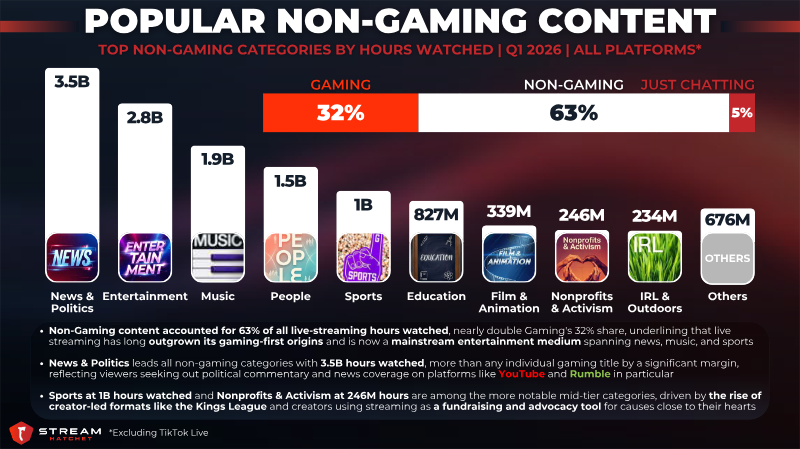
- Non-gaming content now dominates the ecosystem, representing 63% of total viewership with News and Politics as the leading category.
- Gaming engagement is shifting away from traditional esports structures toward mobile-friendly, community-centric, and creator-led events.