Game Development reports and market data
Documents
Southeast Asia Game Industry Report 2021
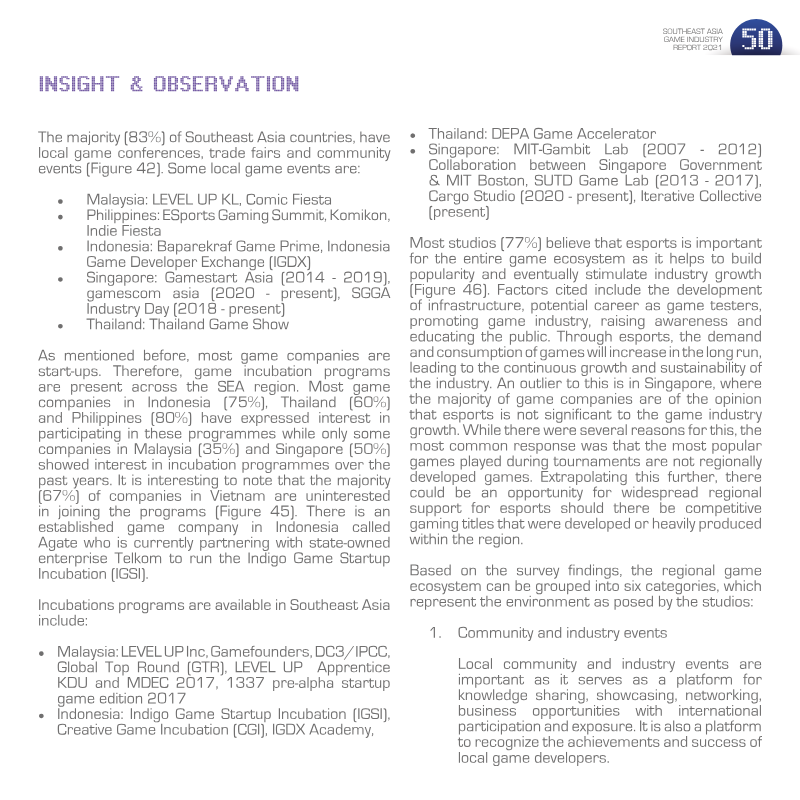
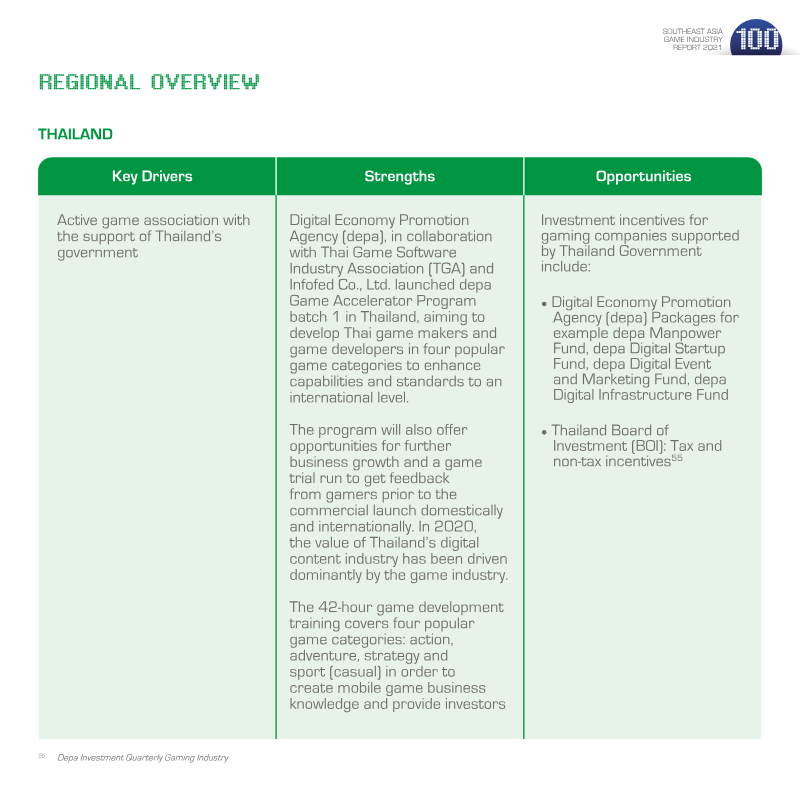
The Southeast Asia Game Industry Report 2021, produced by the Malaysia Digital Economy Corporation, assesses the maturity, workforce, funding environment, and growth potential of the region's game sector across six countries: Malaysia, Indonesia, the Philippines, Singapore, Thailand, and Vietnam.
- The Southeast Asia game market was valued at US$4.4 billion, about 70% of it from mobile, serving roughly 650 million people, with active gamers rising from 126 million in 2014 to 255 million in 2020.
- The sector is structurally small: most companies are young, locally owned, and employ fewer than eleven people, and most firms grow revenue at around 6% or less year on year, with Indonesia showing the strongest expansion.
- Talent acquisition is a persistent constraint, as most entry-level hires need three to six months of practical training and women make up a small share of staff at many firms; the Philippines is the notable exception where talent access is considered easy.
Malaysia Game Development Industry Talent Economics Report 2024
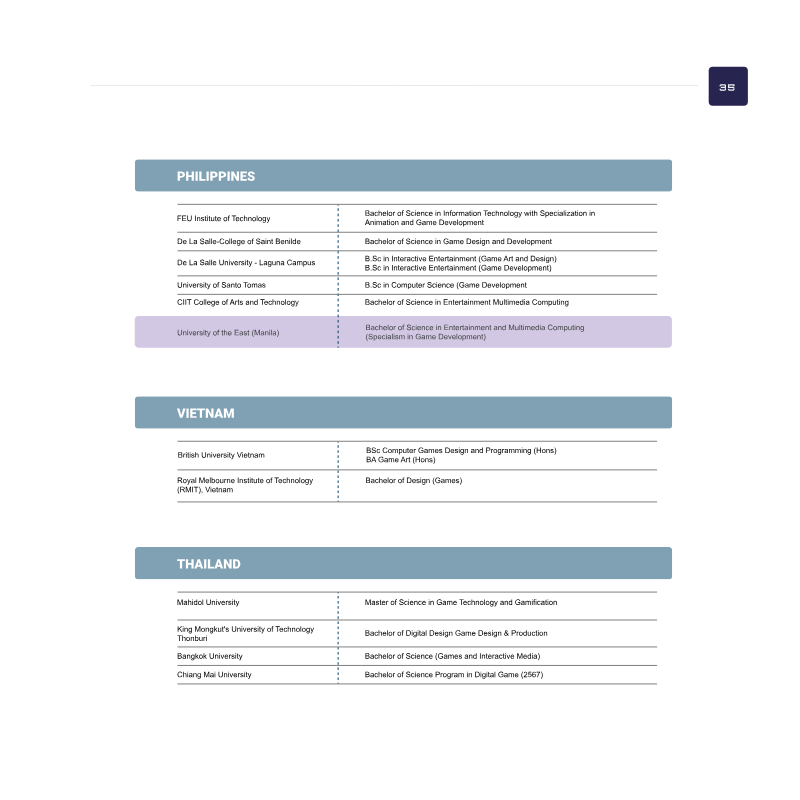
The Malaysia Game Development Industry Talent Economics Report 2024 examines the human capital underpinning Southeast Asia's game development sector, with Malaysia as its primary focus and benchmarks drawn from Indonesia, Singapore, Germany, Saudi Arabia, and China.
- Southeast Asia's game workforce is concentrated in art and outsourcing-driven roles, while demand is shifting toward programming, live-operations, marketing, and original IP development.
- Malaysian game developers earn an average of USD 1,275, far below Singapore's USD 9,176 but well above Indonesia's USD 516, and Malaysian salaries across most specializations trail regional averages.
- Malaysian salaries rise steadily with experience, from about USD 739 for those with under a year to USD 3,553 at ten-plus years, with game programmers leading both entry-level and long-term pay growth.
Costa Rica's Videogame Industry Catalog 2023
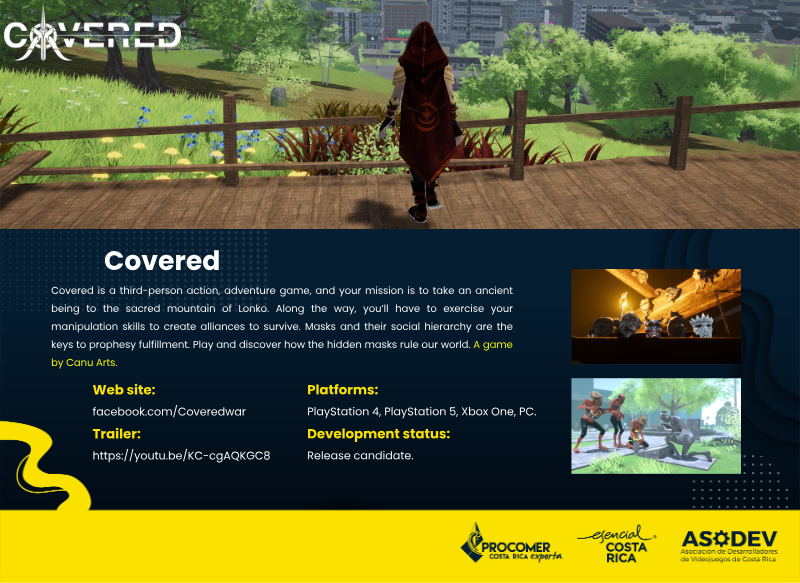
Costa Rica's Videogame Industry Catalog 2023 presents a directory-style overview of the country's game development sector, positioning it as a growing hub of more than twenty studios that export services and original intellectual property, primarily to the United States, Europe, and Asia.
- Costa Rica's videogame sector is presented as a growing hub of more than twenty studios that export services and original intellectual property, mainly to the United States, Europe, and Asia.
- The catalog, produced with support from ASODEV and PROCOMER, aims to make Costa Rican developers visible to publishers, investors, and outsourcing clients.
- The country's main selling points for international partners are its education-based talent pool and its near-shore advantages.
Argentine Videogame Industry
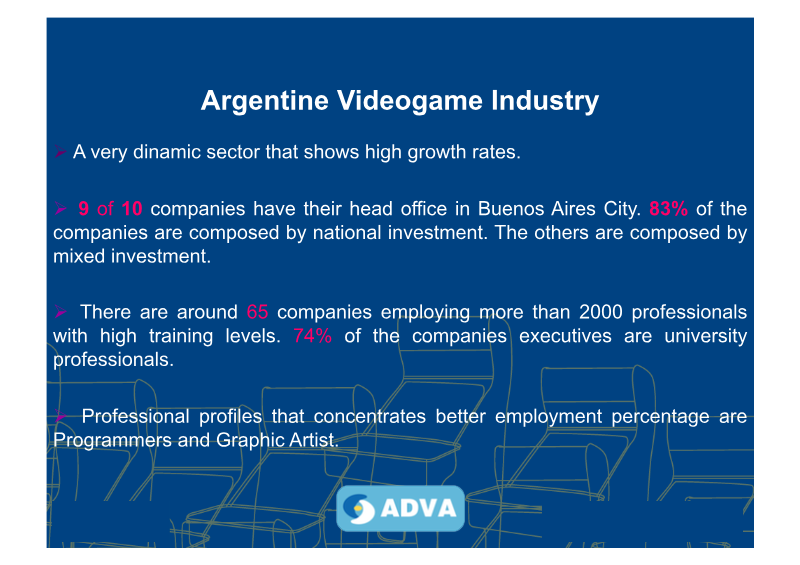
The Argentine Videogame Industry overview, produced by the Argentine Game Developers Association (ADVA), presents a picture of a fast-growing, export-oriented sector centered on Buenos Aires.
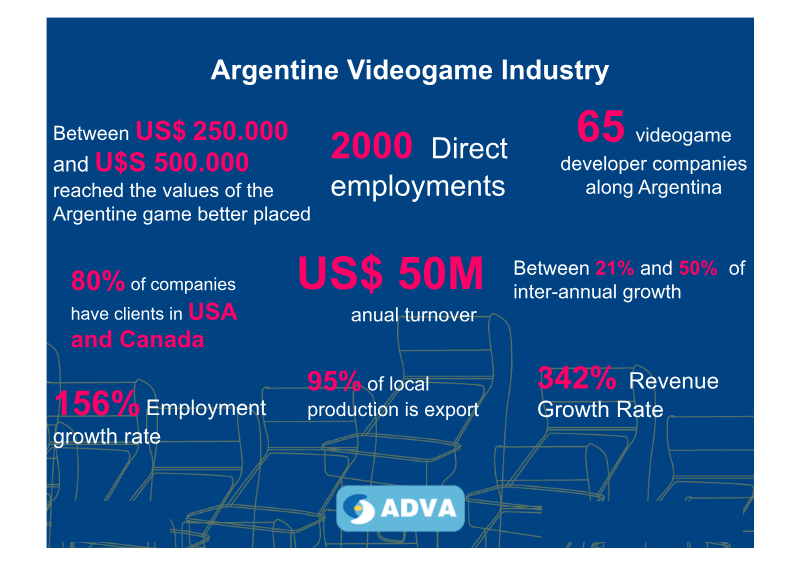
- Argentina's videogame industry comprises roughly 65 companies employing more than 2,000 professionals, with programmers and graphic artists making up the largest share of jobs.
- Between 2006 and 2011, sector revenues grew 156 percent and employment more than doubled, with 2012 projections anticipating nearly 50 percent revenue growth and a 34 percent rise in on-site workers.
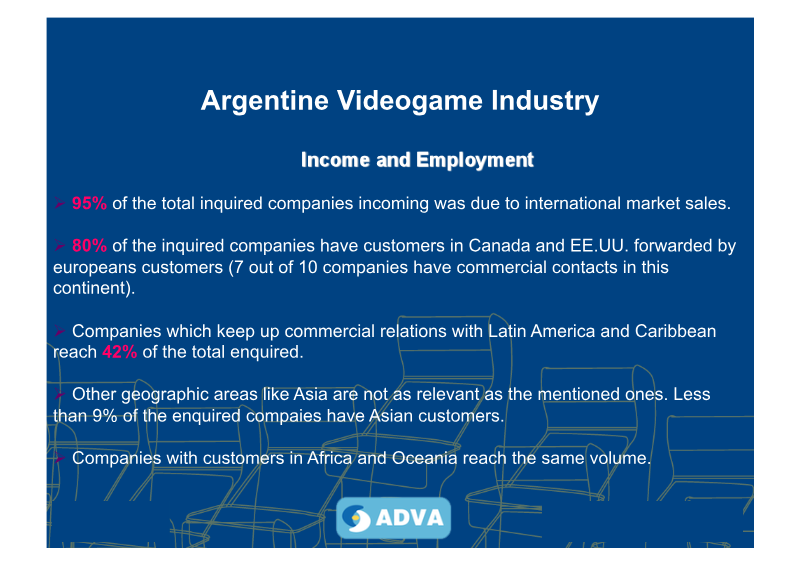
- Exports account for 95 percent of sector sales, with 80 percent of surveyed companies serving clients in the United States and Canada, often through European intermediaries.
The Videogames Sector in Argentina
The Netherlands Enterprise Agency's June 2022 brief on Argentina's videogame sector presents an overview of the country's market, industry structure, key institutions, and intellectual property considerations, with an emphasis on identifying opportunities for complementarity with the Dutch games industry.
- Argentina's videogame market is estimated at USD 495–500 million in annual sales and is among the largest in Latin America, with up to 20 million gamers in a population of roughly 45 million.
- The Argentine games sector employs about 1,950 professionals and generated roughly USD 87 million in 2020, with approximately 77% of output exported mainly to the United States, Canada, and Europe.
- Statista projects Argentine video game revenue of USD 672 million in 2022 and a compound annual growth rate of 11.35% through 2026.
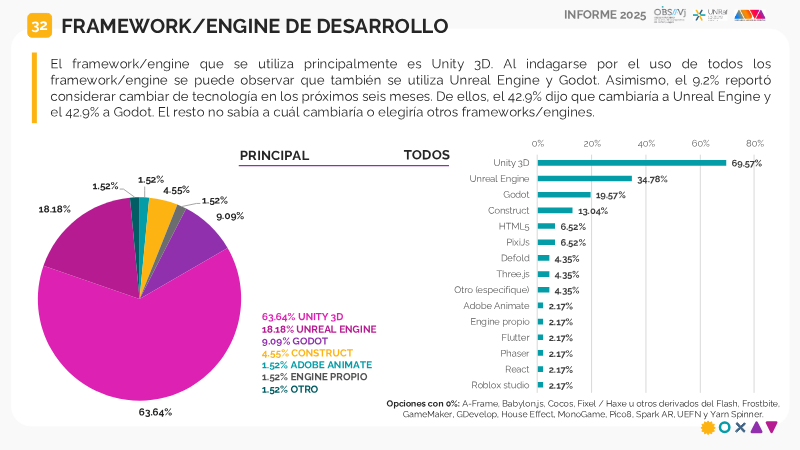
Observatorio de la Industria Argentina de Videojuegos: Informe 2025
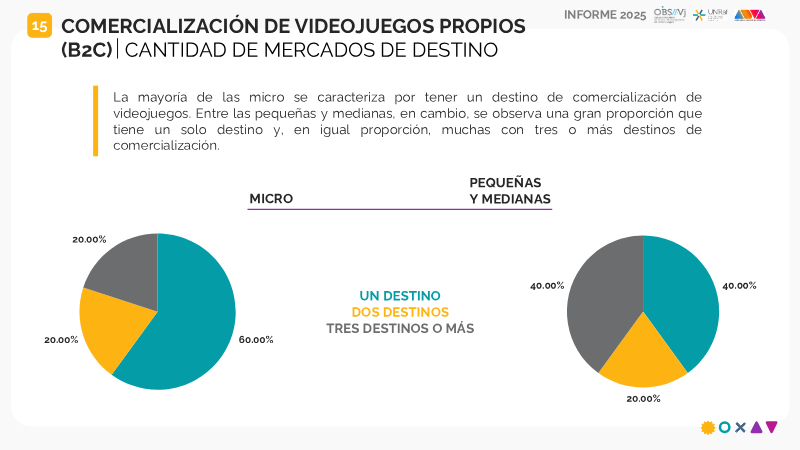
Argentina's video game industry, as profiled in the 2025 Observatorio report, is a sector built largely on very small enterprises.
- The industry is overwhelmingly made up of small enterprises: micro firms make up 55% and small firms 34% of respondents, based on 76 voluntary responses covering 2024 activity.
- Argentina's video game sector is concentrated geographically, with 38% of companies in the Autonomous City of Buenos Aires and 20% in Santa Fe.
- The sector is estimated at U$S 87.3 million and employs approximately 1,432 workers, with programmers as the most common role.
The Funding Landscape of the Swiss Game Industry 2026
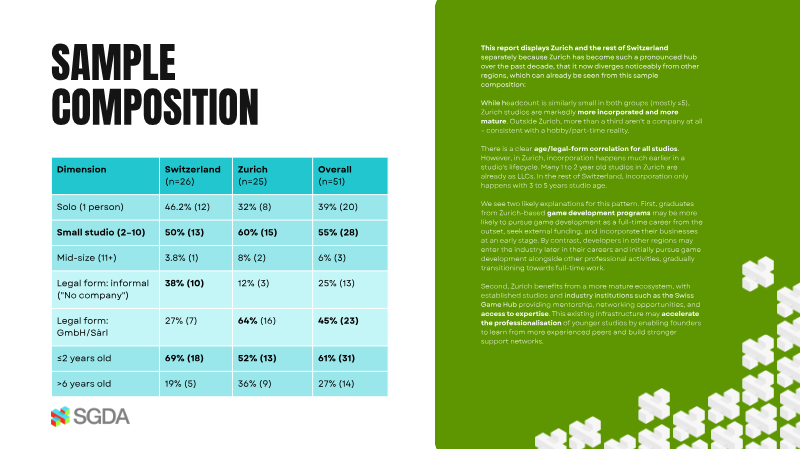
The SGDA's 2026 preliminary study examines how Swiss game studios are funded, drawing on a voluntary nationwide survey conducted between April and May 2026 that received responses from 51 studios, split between Zurich (25) and the rest of Switzerland (26).
- The SGDA's 2026 study, based on a voluntary survey of 51 Swiss game studios (25 in Zurich, 26 elsewhere) conducted April–May 2026, concludes that the Swiss industry is internationally respected but small and under-capitalised, with sustained production-stage funding as the decisive missing element.
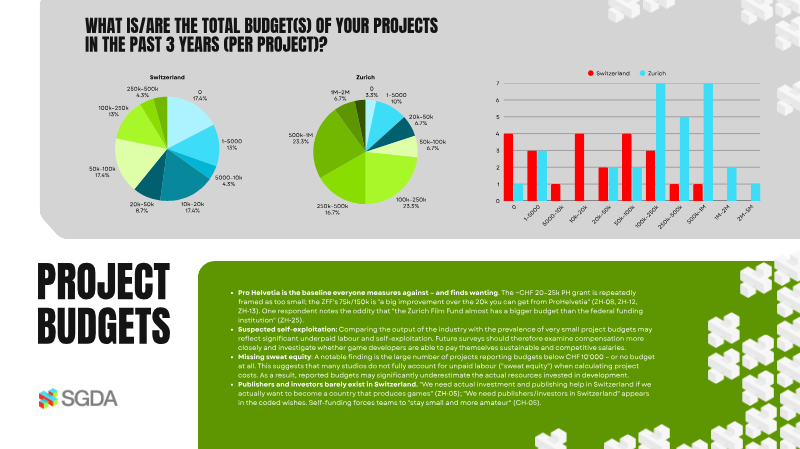
- Zurich studios are far better resourced than those elsewhere in Switzerland: 64% are incorporated as GmbH or Sàrl versus 27% outside the canton, and the median project budget is CHF 275k compared with CHF 30k.
- Zurich studios receive a median of 15% of their budgets from public support, while studios outside Zurich receive none, as most cantons offer no support for games at all.
eGames Lab Research Midterm Report 2023-2024
The eGames Lab Research Midterm Report 2023-2024 presents the progress of a national research and development cluster spanning Madeira, Lisbon, Évora, and the Azores, with a total investment of roughly €30 million, of which about €20.2 million is directed to R&D.
- The eGames Lab is a national R&D cluster across Madeira, Lisbon, Évora, and the Azores with roughly €30 million total investment, of which about €20.2 million goes to R&D, involving 22 public and private entities and researchers from nine nationalities.
- The cluster aims to move six product areas (blockchain, VR/AR, health and green games, AI storytelling, pre-market ecosystems, and process innovation) from technology readiness levels 3-4 to 5-7, with the goals of diversifying Portugal's tourism-dependent economy and retaining young talent.
- Ongoing work is organized into five pillars: interactive storytelling, process innovation, VR for health, transformational games, and AI/LLM-based development, with projects on food waste reduction, climate-related energy games, and financial literacy.
Lithuanian Games Industry Report 2019
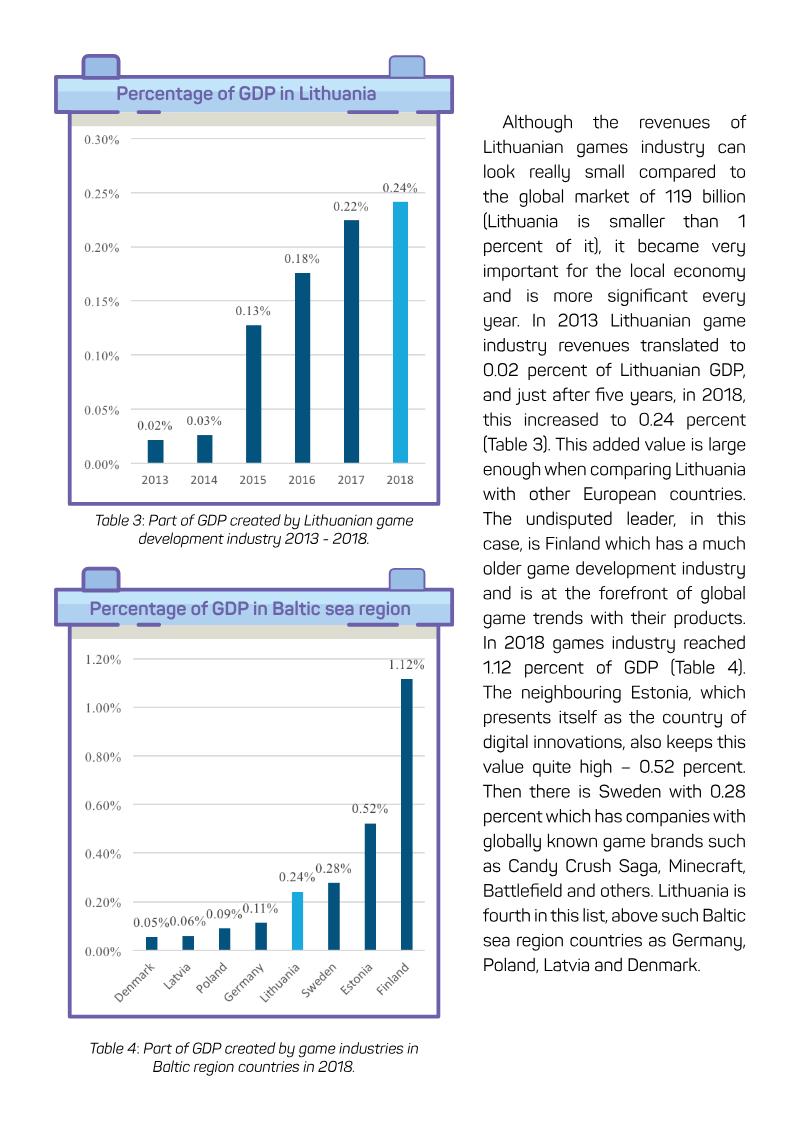
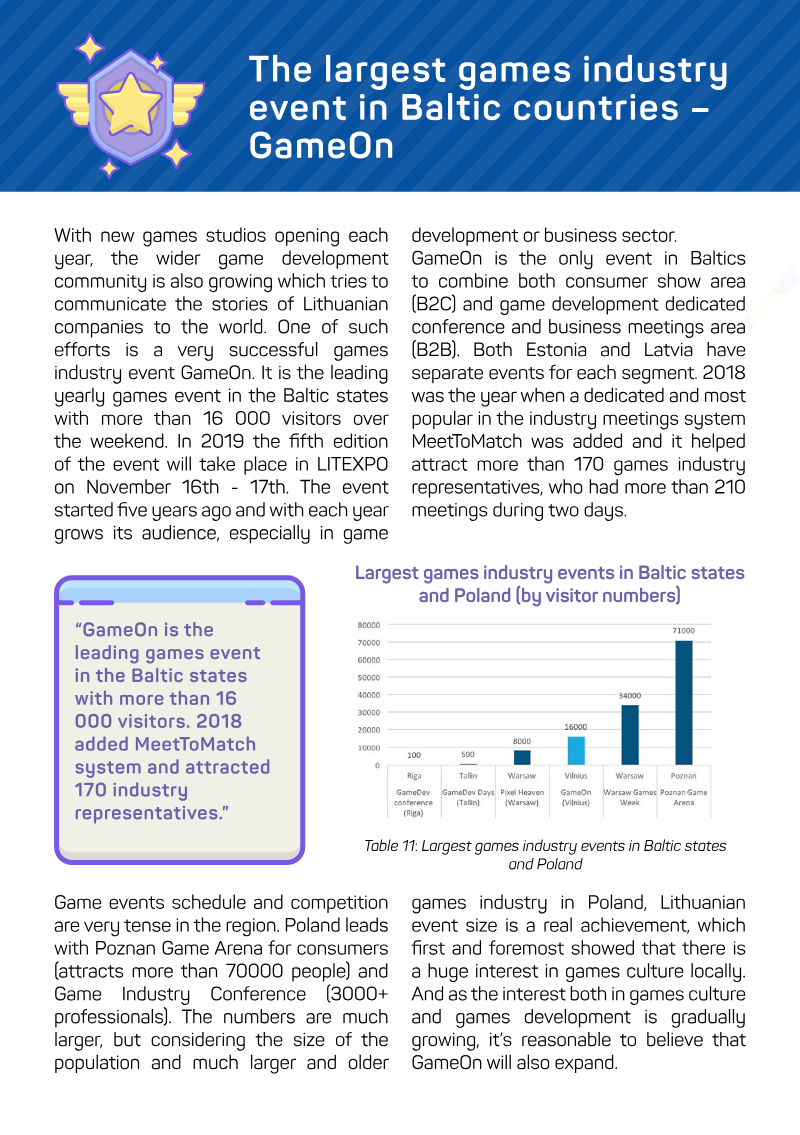
Lithuania's game development sector expanded rapidly between 2013 and 2018, with industry turnover rising from €7.63 million to €115 million and the sector's share of GDP climbing from 0.02% to 0.24%.
- Lithuania's game development turnover grew from €7.63 million in 2013 to €115 million in 2018, lifting the sector's share of GDP from 0.02% to 0.24%, driven mainly by mobile games and consolidation rather than a surge in company count (43 to 47 between 2014 and 2019).
- Revenue per employee rose from €35.7 thousand in 2014 to €163.5 thousand in 2018, while employment peaked at 774 in 2018 before stalling in 2019 amid a shortage of skilled IT professionals.
- The industry is dominated by very small studios: 79% employ fewer than ten people and 90% earn under €2 million annually, though the largest firms generate most of the revenue.
Games Industry in Lithuania
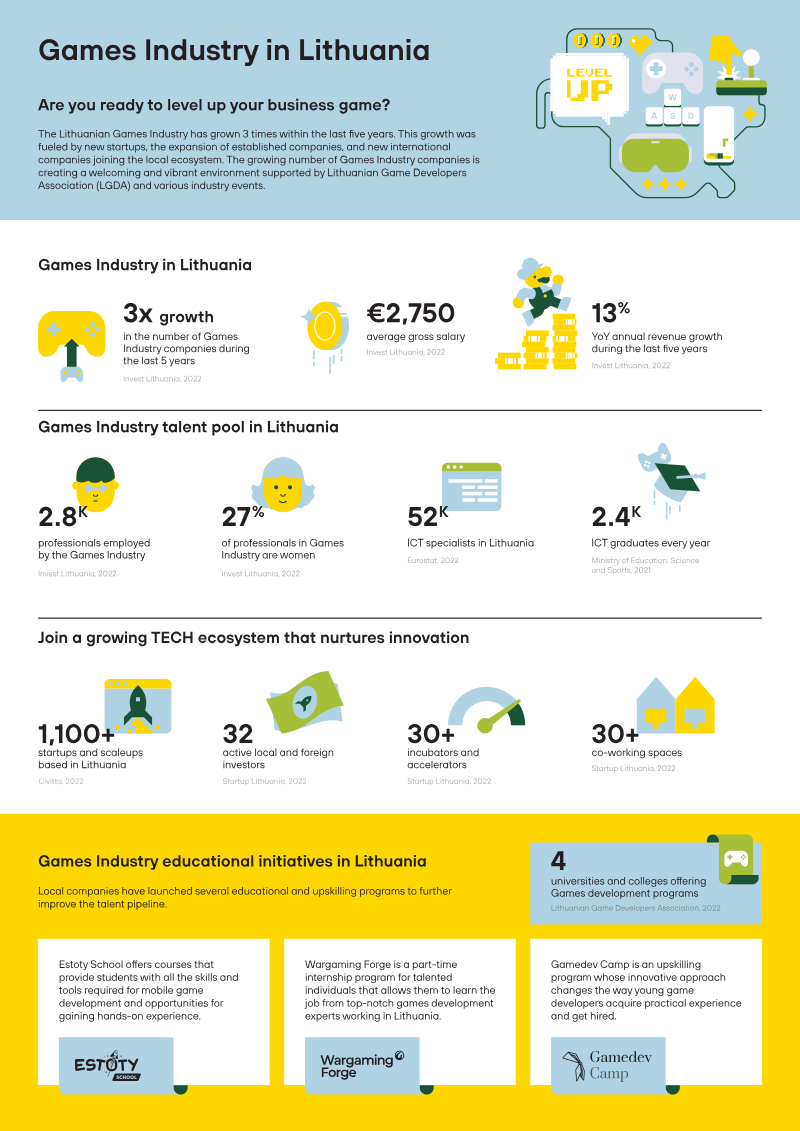
Lithuania's games industry has grown threefold over the past five years, driven by new startups, expansion of established studios, and international companies entering the local ecosystem.
- Lithuania's games industry has grown threefold over the past five years, driven by new startups, expansion of established studios, and international companies entering the local ecosystem.
- The games sector employs about 2,800 professionals, 27% of them women, with an average gross salary of €2,750, and annual revenue has grown 13% year over year.
- The broader ICT talent base includes roughly 52,000 specialists, with around 2,400 ICT graduates produced each year.
The Games Sector in Ireland: An Action Plan for Growth
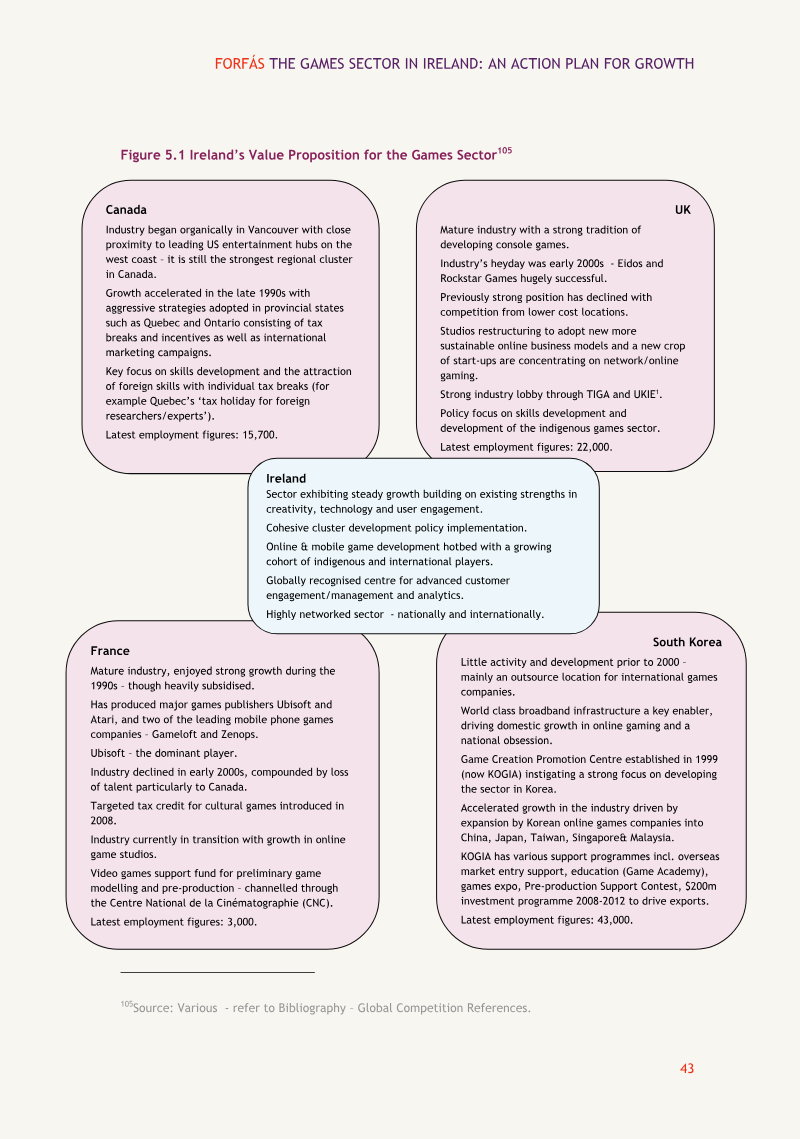
Forfás's action plan for Ireland's games sector argues that the industry is growing rapidly and that Ireland can become a global games hub for the 21st century, but only if policy is deliberately redesigned to capture the opportunity.
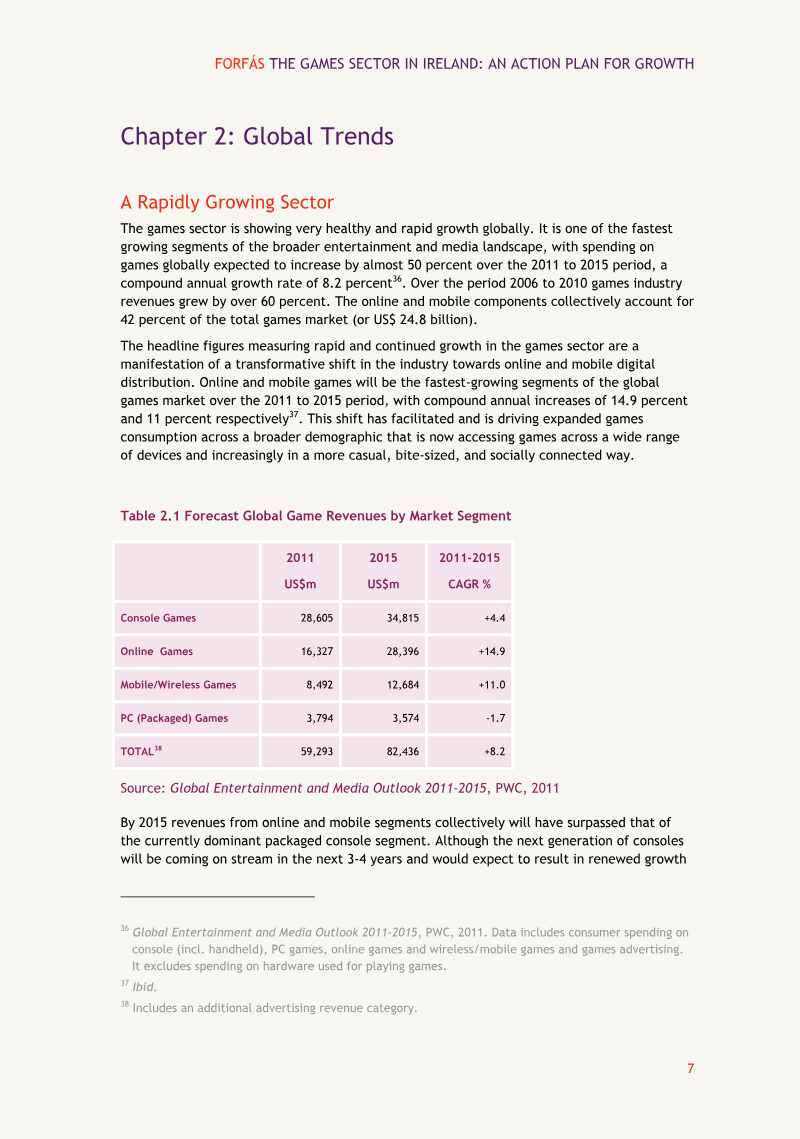
- Global games revenues are forecast to grow from US$59.3bn in 2011 to US$82.4bn by 2015, with online (14.9% CAGR) and mobile (11.0% CAGR) segments overtaking packaged console games.
- Ireland's core games employment has grown fivefold since 2004 to just over 2,000 people in 2011, with a target of 4,500 by 2014.
- Foreign-owned firms account for roughly 90% of Ireland's games jobs, concentrated in customer support, localisation, and game servicing, while indigenous firms are mostly micro-firms focused on development.
The Game Industry of Estonia 2021
The Game Industry of Estonia 2021 surveys the state of Estonia's game development sector during 2021, drawing on company data, interviews conducted between November 2021 and February 2022, and an examination of education, support organizations, and community activity.
- Estonia's game industry grew 20.69% in 2021, with taxable turnover rising from €40.0 million in 2020 to €50.4 million, after 2020 had already surpassed 2019 levels, signalling sustained momentum despite the pandemic.
- The sector is highly concentrated: ZA/UM alone generated €20.7 million of the €50.4 million total, while other notable performers included Creative Mobile, Gamecan, Zaum Studio, and Ringtail (acquired by Magic Media in June 2021).
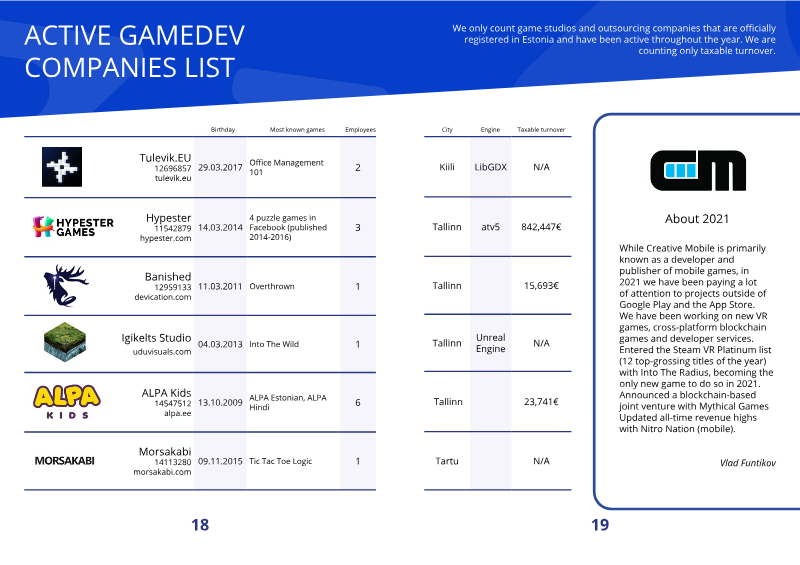
- The industry is dominated by very small firms, with 76% of its 41 active companies employing one to five people, and the sector overall employs roughly 300 people.