
Report25 pages
South East Asian Mobile Game Market Insights 2024
Mobile game downloads across Southeast Asia grew by 3.4 % in the first half of 2024, reaching 4.2 billion installs, with Google Play accounting for 91 % of the volume. In‑app purchase revenue rose by 3.4 % to $1.16 billion, a slight decline of 3 % from the previous half‑year; Google Play contributed 57 % of total revenue. From January to August, mid‑core genres such as simulation, arcade, puzzle and lifestyle led download growth (11 %–14 %), while sports titles experienced a 39 % revenue surge, representing 9 % of total IAP income. Strategy and RPG games dominated downloads (47 %) but saw modest revenue declines of 3 %–9 %.
Indonesia remains the largest market, with a 10 % download increase and 41 % of regional downloads; Thailand follows as the highest‑earning country, adding $400 million in revenue. The top ten download leaders are dominated by Garena Free Fire, Mobile Legends: Bang Bang and Roblox, with Garena Free Fire maintaining a 54 % growth rate. In revenue terms, Mobile Legends: Bang Bang leads with $1.16 billion, followed by eFootball™ 2024 and Garena Free Fire; Roblox and Coin Master also show strong growth, with Roblox’s revenue rising 90 %.
The case study of Honor of Kings illustrates rapid penetration after its Southeast Asian launch in June 2024, achieving a 175 % month‑over‑month spike in Indonesia and capturing the top download spot in July. By August, Honor of Kings generated $1.7 billion in IAP revenue for the period and accounted for 51 % of its global downloads from Indonesia alone. The report relies on Sensor Tower’s estimated download and IAP data from the App Store and Google Play, excluding pre‑installs, duplicate downloads, ad revenue, third‑party sales, and direct developer payments.
- Southeast Asia's mobile game market saw 4.2 billion installs in H1 2024, a 3.4% increase, while in-app purchase (IAP) revenue reached $1.16 billion, a 3.4% year-over-year rise but a 3% decline from the previous half-year.
- Indonesia is the region's largest market by volume, accounting for 41% of total downloads with 10% growth, while Thailand leads in profitability, contributing $400 million in IAP revenue.
- Google Play remains the dominant platform in the region, capturing 91% of total download volume and 57% of total IAP revenue.
- While strategy and RPG titles command 47% of downloads, they experienced revenue declines of 3%–9%, whereas sports titles saw a significant 39% revenue surge, now representing 9% of total IAP income.
- Honor of Kings demonstrated rapid market penetration following its June 2024 launch, capturing the top download spot in July and generating 51% of its global downloads from Indonesia by August.
+1
Sensor TowerJan 2024

Report33 pages
State of Game Technology Report 2024
The report demonstrates that game technology is increasingly permeating non‑traditional sectors, with half of surveyed teams employing real‑time 3D engines beyond game development. This cross‑industry diffusion is accompanied by persistent funding constraints and collaboration bottlenecks, notably slow file transfers, remote coordination difficulties, and asset feedback challenges. The data reveal a trend toward consolidating toolsets to enhance productivity amid economic uncertainty and the rise of remote work.
Engine usage remains dominated by Unreal Engine (63 %) while Unity follows at 47 %; Godot is gaining traction mainly among indie developers. Version control practices show Perforce Helix Core leading (51 %) with widespread adoption of Git‑based solutions, though Google Drive remains a common secondary storage option.
Asset management practices differ markedly between AAA and indie studios. Custom‑built solutions are common in both, yet 23 % of AAA teams and 17 % of indie studios rely on them, diverting resources from core development. Indie teams more frequently use Perforce (55 %) compared to AAA studios (3 %). Generative AI adoption is high, with 65 % of respondents using an organizational AI tool; ChatGPT leads at 47 %, especially among indie/mid‑size studios (50 % versus 26 % in AAA). Other AI tools such as Midjourney, DALL‑E, and GitHub Copilot also see notable usage.
Cloud infrastructure is embraced by nearly half of respondents (49 %), with AWS leading at 30 % and Azure at 18 %; hybrid cloud adoption remains minimal (6 %).
Talent acquisition trends underscore a premium on specialized experience (≈95–100 %) and continuous learning ability (≈71–82 %), while presentation skills and portfolio strength, though important, receive comparatively lower emphasis. These findings highlight a shift toward adaptable, skill‑rich talent pools across highly technical industries.
- Real-time 3D engines are expanding beyond gaming, with 50% of surveyed teams now applying this technology to non-traditional sectors.
- Generative AI adoption is widespread, with 65% of organizations utilizing AI tools, led by ChatGPT at 47% usage, particularly among indie and mid-size studios.
- Unreal Engine remains the market leader at 63% usage, followed by Unity at 47%, while Perforce Helix Core dominates version control at 51%.
- Cloud infrastructure adoption has reached 49%, with AWS holding a 30% market share compared to 18% for Azure.
- Asset management remains inefficient, as 23% of AAA studios and 17% of indie teams divert core development resources to maintain custom-built solutions.
+2
PerforceJan 2024
Report44 pages
Annual Report 2024
Thunderful Group’s 2024 Annual Report documents a decisive pivot toward a pure gaming focus, achieved through divestment of non‑gaming assets and a 20 % workforce reduction. The restructuring tightened the balance sheet, halving interest‑bearing net debt and leaving a modest cash position of SEK 29.6 million, yet it also produced a sharp decline in operating performance: net revenue fell 23.8 % to SEK 292.8 million and adjusted EBITA swung to a loss of SEK 383.9 million, largely due to cost‑cutting and the transition to higher‑margin publishing and co‑development activities.
The global gaming market grew modestly in 2024, reaching USD 187.7 billion with a 5 % rise in the player base to 1.5 billion, projected to reach 1.67 billion by 2027. Thunderful’s strategy targets a 3.1 % CAGR in the PC segment, high‑quality titles priced USD 10–30, and external project investments capped at EUR 2 million. The company has reorganised into Publishing and Co‑development & Services segments to optimise resource allocation, lower fixed costs through third‑party publishing, and balance riskier internal IP development with predictable service revenue.
Governance remains robust: a board‑led risk framework, annual review of a Zero‑tolerance Code of Conduct, and an anonymous whistleblowing function reinforce ethical standards. Executive remuneration is tightly linked to long‑term value, with fixed salaries capped at 30 % variable pay and share‑based incentives that could dilute equity by up to 4.65 % if fully exercised. Despite a net loss of SEK 887.5 million in 2024, the Group’s operating profit rose 57 % to SEK 292.8 million, signalling a turnaround post‑restructuring.
Financially, the Group’s liquidity is constrained; total assets fell from SEK 3.15 billion to SEK 772.9 million, and net cash turned negative. Impairments of over SEK 444 million on goodwill and other intangibles, coupled with significant restructuring costs, underpin the negative operating margin of –46.9 %. The company’s exposure to foreign‑exchange, interest‑rate and liquidity risks remains moderate but requires ongoing monitoring. Overall, the report presents a company in transition, balancing aggressive cost discipline and strategic realignment against a challenging financial backdrop.
- Thunderful Group reported a net loss of SEK 887.5 million in 2024, driven by SEK 444 million in asset impairments and significant restructuring costs that resulted in an operating margin of -46.9%.
- The company executed a major strategic pivot toward a pure gaming focus, involving a 20% workforce reduction and the divestment of non-gaming assets to halve interest-bearing net debt.
- Net revenue declined 23.8% to SEK 292.8 million, while adjusted EBITA fell to a loss of SEK 383.9 million as the firm transitioned toward higher-margin publishing and co-development models.
- Thunderful has reorganized into two core segments—Publishing and Co-development & Services—to balance high-risk internal IP development with predictable service revenue and lower fixed costs.
- The company’s financial position remains constrained, with total assets dropping from SEK 3.15 billion to SEK 772.9 million and a modest cash position of SEK 29.6 million.
+1
ThunderfulJan 2024

Report32 pages
Gaming Report 2024: Meet the Moment – How Gamers Are Changing the Game
The report demonstrates that the global video‑game market reached $196 billion in 2023 and is expected to grow at roughly 6 % per year through 2028. Growth is driven by a youthful demographic—80 % of players aged 2‑18—who devote nearly one third of their entertainment time to gaming. These gamers increasingly engage in immersive, cross‑platform ecosystems that combine social interaction, co‑creation and real‑world extensions of game IP. Their spending per hour can be up to five times higher when they participate in multiple activities, underscoring the commercial value of integrated experiences.
Key findings reveal that 70 % of players use multiple devices and 90 % desire a single consolidated marketplace, with half willing to pay for it. Publishers are therefore urged to develop device‑agnostic platforms, strengthen direct relationships with players and employ data‑driven marketing. In the mobile sector, an 80 % failure rate after three years contrasts sharply with a 10–25 % failure rate in software and retail, highlighting the need for highly targeted paid performance marketing, rigorous A/B testing and tight alignment across development, finance and marketing teams. Long‑term acquisition and retention strategies, coupled with generative AI for ad creation and optimization, are identified as critical success factors.
Operating models at leading studios are shifting toward standardised core tools, autonomous entrepreneurial teams with clear milestones and strategic embedding of generative AI. Talent attraction now demands a comprehensive package that includes purpose, competitive pay, work‑life balance, learning paths and ESG commitments to remain competitive with the broader tech industry. The report’s thesis is that understanding diverse gamer segments, delivering interoperable cross‑platform experiences and investing in data‑driven, AI‑enhanced operations are essential for capturing the rapidly expanding, monetarily active gaming audience.
- The global video game market reached $196 billion in 2023 and is projected to grow at an annual rate of approximately 6% through 2028.
- Engagement in immersive, cross-platform ecosystems is highly lucrative, as players spend up to five times more per hour when participating in multiple activities rather than gaming alone.
- Mobile game titles face an 80% failure rate after three years, necessitating rigorous A/B testing, targeted performance marketing, and tight alignment between development and finance teams.
- Consumer demand for platform interoperability is high, with 90% of players desiring a single consolidated marketplace and 50% willing to pay for such a service.
- Youth aged 2–18 represent 80% of the player base and dedicate nearly one-third of their total entertainment time to gaming.
+1
Bain & CompanyJan 2024
Report35 pages
How Consumers Engage with Games Today: Newzoo’s Global Gamer Study 2024
Gaming dominates contemporary culture, with eight in ten global consumers actively playing or engaging in related activities. The study identifies a highly engaged, high‑spending cohort—particularly Gen Alpha and Gen Z players—who devote an average of 5.2 hours per week to gaming, outpacing social media use. These younger generations also participate in content viewing and community interaction, favoring adventure‑type titles that deliver trend‑driven experiences.
Gen Z’s motivations center on expansive open worlds (66–73%) and deep storytelling (65–68%), with optional tasks, high‑speed action, competitive duels (71%) and cooperative goals (68%) also prominent. Their average daily playtime on PC/console is 2.1 hours, and 22 % spend $25 or more monthly, demonstrating a willingness to pay upfront. In contrast, mobile players prefer free‑to‑play models and lower spend levels.
A significant segment of PC/console gamers—about one third—are “new game seekers.” They spend 7–8 hours weekly, often across two or three platforms, and are predominantly Gen Z (42%) and Baby Boomers. These players allocate over $25 monthly on average, favor adventure, fighting, shooter, racing and battle‑royale titles with high graphics fidelity and survival themes. They consume gaming media at a rate exceeding 90 % and show strong loyalty to franchise titles such as Call of Duty, FIFA, and Roblox.
The findings underscore that Gen Alpha and Gen Z represent a sizable, spend‑capable audience for expansive, socially driven experiences. Simultaneously, the new‑game‑seeker cohort highlights opportunities for high‑quality, cross‑genre titles that appeal to both younger and older demographics across PC, console, and mobile platforms.
- Gen Z and Gen Alpha players spend an average of 5.2 hours per week gaming, surpassing their time spent on social media.
- Approximately 22% of Gen Z players spend $25 or more monthly on games, showing a strong preference for upfront payments compared to the free-to-play model favored by mobile gamers.
- One-third of PC/console gamers are 'new game seekers' who spend 7–8 hours weekly across multiple platforms and consistently invest over $25 monthly.
- Gen Z motivations are driven by open-world environments (66–73%), deep storytelling (65–68%), competitive duels (71%), and cooperative goals (68%).
- New game seekers are predominantly Gen Z (42%) and Baby Boomers who show high loyalty to major franchises like Call of Duty, FIFA, and Roblox.
+1
NewzooJan 2024

Report12 pages
Inside Gaming: It's Personal!
The report examines how video games increasingly serve as a platform for personal identity and self‑expression, noting that nearly two thirds of gamers feel they can be more authentic while playing. It argues that this trend fuels a 30 % rise in time spent gaming among those who view games as a space for true self‑presentation, compared with previous years. The analysis draws on a global survey of 5,000 entertainment and gaming consumers and proprietary first‑party data from Fandom for 2024. Findings highlight that in‑game customization is the most powerful driver of self‑expression, with 76 % of players citing character personalization as a key tool; gamertags and usernames follow at 48 %, while communication features, signatures, emblems, emotions, and gestures each attract between 30‑35 % of respondents. The study also identifies a disconnect: many gamers believe they can be authentic online yet perceive their in‑person gamer persona as distinct from their real‑life personality. Brands are encouraged to bridge this gap by creating opportunities that translate virtual identity into physical expression—such as cosplay collaborations, cosmetic product lines, or skill‑building experiences that mirror in‑game achievements. The report covers a global audience across all major gaming segments, focusing on the 2024 period and emphasizing actionable insights for marketers seeking to align brand experiences with gamers’ desire for authenticity.
- Nearly two-thirds of gamers report feeling more authentic while playing than in their daily lives, a sentiment that has driven a 30% increase in time spent gaming among those who view these platforms as spaces for self-presentation.
- In-game character customization is the primary driver of self-expression for 76% of players, significantly outpacing other features like usernames (48%) and communication tools or emotes (30–35%).
- Fandom’s 2024 data indicates a psychological disconnect where gamers maintain distinct online personas that they perceive as separate from their real-life identities.
- Marketers can capitalize on the desire for authenticity by creating physical-world extensions of virtual identities, such as cosplay collaborations, branded cosmetic lines, or skill-building programs that mirror in-game achievements.
- These insights are based on a 2024 global survey of 5,000 entertainment and gaming consumers, combined with proprietary first-party data from Fandom.
+2
FandomJan 2024
Report44 pages
Digital Market Index: Q1 2024
Global consumer spending on mobile applications reached a record $45 billion in the first quarter of 2024, reflecting a 9.5% year‑over‑year increase that was largely driven by the iOS ecosystem, which grew 11.5% versus a 5.3% rise on Google Play. Despite this surge in spend, total app downloads fell 3.5%, marking the third consecutive quarterly decline since Q1 2021; nevertheless, iOS maintained its highest quarterly download volume since 2020. Entertainment and productivity categories led the spend growth, each expanding over 30% YoY, while gaming spending rebounded on iOS but remained flat on Google Play.
Hyper‑casual games continued to dominate the download landscape, with racing and action titles generating the largest volumes. Conversely, casual sub‑genres such as arcade and simulation experienced double‑digit declines. TikTok remained the top spender globally, generating more than $1.2 billion in revenue and outpacing YouTube by a wide margin, while emerging short‑form drama apps—ReelShort, DramaBox, and ShortMax—entered the top ten for both revenue and download growth. In mobile gaming, “Monopoly GO” set a new quarterly spend record of $770 million, surpassing the previous $765 million benchmark and standing alone as a title to exceed $600 million in a single quarter.
Retail‑media advertising in the United States was led by Walmart and Target, which together delivered over 18 billion impressions in Q1 2024. Specialized retailers such as Chewy and Home Depot captured significant niche shares, with personal care emerging as the top category overall—driven by Ulta and Sephora. Walmart dominated food, beverages, and consumer packaged goods, while Target excelled in shopping, household supplies, and baby & toddler segments. Co‑branded partnerships—including Chewy × Purina, Walmart × Unilever, and Target × Apple—generated hundreds of millions of impressions, underscoring the strategic value of retailer‑brand collaborations in expanding digital ad reach.
- Global mobile app spending reached a record $45 billion in Q1 2024, a 9.5% year-over-year increase driven primarily by an 11.5% growth in the iOS ecosystem.
- Total app downloads declined by 3.5%, marking the third consecutive quarterly drop, even as iOS achieved its highest download volume since 2020.
- Monopoly GO set a new mobile gaming record with $770 million in quarterly spend, becoming the only title to surpass $600 million in a single quarter.
- Entertainment and productivity apps led category growth with over 30% year-over-year increases, while TikTok maintained its position as the top-earning app with $1.2 billion in revenue.
- Short-form drama apps including ReelShort, DramaBox, and ShortMax emerged as top performers in both revenue and download growth during Q1 2024.
+1
Sensor TowerJan 2024
Report33 pages
Perforce 2024 State of Game Technology Report
The report demonstrates that real‑time 3D engines and advanced asset pipelines are now integral to more than half of organizations beyond traditional game development, spanning media, automotive, education and healthcare. The primary drivers are the demand for high‑quality visual tools that can be reused across projects and the need to streamline workflows amid increasingly complex, remote‑enabled teams. Funding constraints, collaboration bottlenecks—particularly large‑file transfer—and limited staffing emerge as the top challenges.
Collaboration pain points persist, with 31 % of studios citing slow large‑file transfer and 38 % reporting remote coordination issues. Unreal Engine dominates usage at 63 %, while Unity follows at 47 %. Perforce Helix Core leads version‑control adoption (51 %) across industries, with GitHub and GitLab trailing. These figures underscore the necessity of robust pipelines that support rapid asset sharing, remote teamwork and efficient version control.
Asset management practices vary by studio size: AAA studios largely build custom tools (≈ 19 %) to handle extensive IP libraries, diverting resources from core development; indie and mid‑size studios rely more on market solutions, with 32 % using Perforce Helix Core and only 17 % developing in‑house tools. Generative AI is widely adopted, with over 65 % of respondents using an AI tool—ChatGPT being the most common (47 %). Indie studios adopt AI more aggressively than AAA studios, and usage patterns differ by industry. Cloud development is also prevalent: 49 % run cloud servers, led by AWS (30 %) and Azure (18 %), while hybrid or on‑premises setups are rare.
Hiring priorities across gaming, media, education, engineering and automotive sectors emphasize specialized experience (91–100 %) and strong portfolios (75–94 %). General cross‑functional skills such as rapid learning and presentation abilities are valued but to a lesser extent (54–82 %). The data indicate that firms prioritize deep technical expertise and demonstrable work, reflecting a continued focus on specialized knowledge across all sectors.
- Real-time 3D engines have expanded beyond gaming, with over 50% of organizations in media, automotive, education, and healthcare now integrating these technologies into their workflows.
- Unreal Engine leads the market with 63% usage, followed by Unity at 47%, while Perforce Helix Core remains the primary version-control solution for 51% of firms.
- Generative AI adoption is widespread, with over 65% of respondents utilizing AI tools, led by ChatGPT at 47%, with indie studios showing higher adoption rates than AAA counterparts.
- Collaboration remains a significant bottleneck, as 31% of studios struggle with slow large-file transfers and 38% report ongoing issues with remote team coordination.
- Cloud infrastructure is the industry standard for development, with 49% of organizations utilizing cloud servers, primarily through AWS (30%) and Azure (18%).
Perforce SoftwareJan 2024
Report30 pages
Gaming Industry Report: Q4 2023
The global gaming industry reached a market valuation of $184 billion in 2023, representing a modest year-over-year growth of 0.6%. Despite this stability, the sector experienced a significant contraction in investment activity, with venture funding falling 33% quarter-over-quarter in Q4 to $308 million. This decline reflects a broader normalization of capital flows to pre-pandemic levels, as the industry shifts away from the high-growth, speculative environment of 2021 and 2022.
Key industry trends in late 2023 were defined by regulatory and operational restructuring. A landmark legal verdict against Google established that its app store practices constituted an illegal monopoly, forcing potential shifts in how developers distribute content and process payments. Simultaneously, major players like ByteDance began retreating from gaming divisions, while the industry at large grappled with approximately 10,500 layoffs. These workforce reductions were driven by a heightened focus on operational efficiency, the prioritization of high-retention projects, and the consolidation of assets following major mergers and acquisitions.
Geographically, North America remains the primary hub for venture capital, though the industry maintains a global footprint with significant activity in Asia and Europe. While venture funding and M&A deal volumes have stabilized, public gaming stocks demonstrated resilience, with leading exchange-traded funds outperforming broader market indices by year-end. Looking forward, the industry is projected to maintain a compound annual growth rate of 3.5% through 2029, supported by the continued integration of user-generated content platforms and advancements in developer tools that emphasize productivity and cost-effective scaling.
- The global gaming industry reached a $184 billion valuation in 2023, reflecting a modest year-over-year growth of 0.6%.
- Venture funding for the gaming sector dropped 33% quarter-over-quarter in Q4 2023 to $308 million, signaling a return to pre-pandemic capital levels.
- Approximately 10,500 industry layoffs occurred in 2023 as companies prioritized operational efficiency, asset consolidation, and high-retention projects.
- A landmark legal verdict against Google ruled its app store practices an illegal monopoly, potentially forcing significant changes to content distribution and payment processing.
- The industry is projected to maintain a 3.5% compound annual growth rate through 2029, driven by user-generated content and productivity-focused developer tools.
+2
KonvoyJan 2024
Presentation5 pages
Slovak Game Industry Infographic 2024
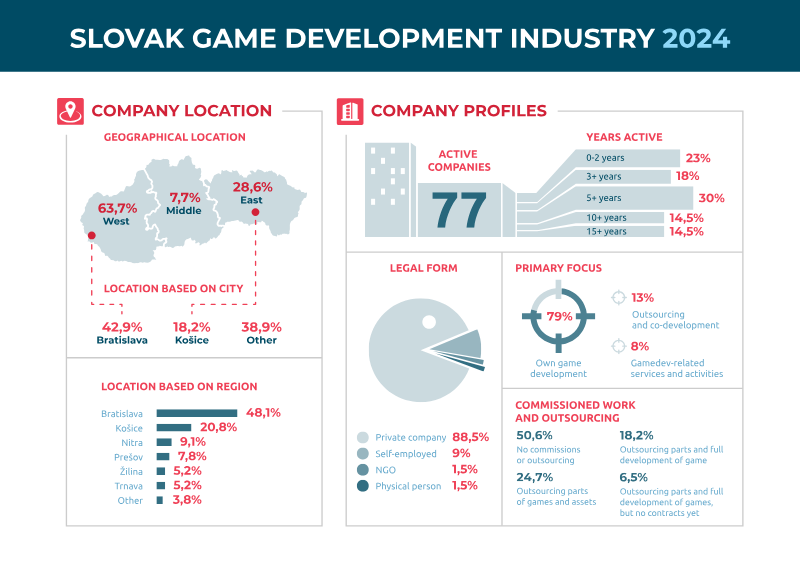
The 2024 Slovak Game Industry report provides a comprehensive overview of the nation’s game development sector, detailing its economic performance, workforce composition, and operational landscape as of December 31, 2024. The industry is characterized by a mix of established firms and newer entrants, with a primary focus on own-game development, which accounts for nearly 43% of activities, followed by outsourcing and co-development services. Geographically, the industry is concentrated in Bratislava and Košice, reflecting the urban centralization of technical talent and infrastructure.
Financially, the sector generated a total turnover of approximately 67.8 million euros in 2024, with a high degree of market concentration; the top 10% of companies account for over 83% of this revenue. The workforce consists of 982 employees with a median age of 30 to 35. While the industry remains male-dominated, women represent nearly 20% of the workforce, primarily in visual arts and marketing roles. Foreign talent is a significant component of the ecosystem, comprising 11.6% of the total headcount, with employees largely sourced from Poland, Ukraine, and Czechia. Remote work is highly prevalent, with 91% of companies offering some form of home office or fully remote arrangements.
Development trends show a strong preference for PC platforms, which serve as the primary target for both released and in-development titles. Self-funding remains the dominant financial model for projects, utilized by 80.5% of companies, while public funding and international publishers play secondary roles. Despite the industry's growth, stakeholders identify a need for improved state support, specifically requesting tax incentives, increased R&D funding, and more effective mechanisms for hiring foreign professionals. The report highlights a sector that is technically mature but actively seeking structural improvements to enhance its international competitiveness and sustainability.
- The Slovak game industry generated 67.8 million euros in total turnover in 2024, with high market concentration where the top 10% of companies account for over 83% of total revenue.
- The sector employs 982 professionals with a median age of 30–35, and while male-dominated, women comprise nearly 20% of the workforce, primarily in visual arts and marketing.
- Self-funding is the primary financial model for 80.5% of companies, indicating a reliance on internal capital over public funding or international publishing deals.
- Development activity is heavily focused on PC platforms and concentrated geographically in Bratislava and Košice, with 43% of industry output dedicated to own-game development.
- Remote work is standard practice in the sector, with 91% of companies offering either hybrid or fully remote work arrangements.
Slovak Game Developers AssociationJan 2024
Report78 pages
Netherlands Games Monitor 2024
AUTHORS SPECIAL THANKS TO Manuel Kerssemakers (Abbey Christel van Grinsven APPLIED Games) Arjan Terpstra Bowie Derwort (Game Tailors) Laurens Rutten (CoolGames Matthijs Dierckx Michaël Bas (&ranj) & Dutch Games Association) Roger ter Heide (Improvive) Tuur Hendrikx (Sonic Picnic) RESEARCH CHAPTER 1 ...
- The Dutch games industry employed 4,291 people by the end of 2023, a decline of 269 persons compared to 2021, with employment decreasing by 3% per year between 2021 and 2023, though revenue increased by an average annual rate of 10.5% to €763 million.
- The percentage of female workers in the Dutch games industry is rising, reaching 23.2% currently, aligning with broader European and North American industry averages.
- Applied games studios are adopting generative AI faster than entertainment studios, using or testing it for localization, dialogue, training content, and audio, with clients open to custom AI-enabled solutions, while entertainment studios are more hesitant due to potential player backlash.
- The Greater Amsterdam urban region remains the primary hub for the Dutch games industry, offering nearly 1,800 jobs by the end of 2023, and notably continued to grow employment between 2021 and 2023 despite an overall industry decline.
- There are 41 game education programs in the Netherlands, similar to 2022, primarily focusing on programming or game art, with a majority of courses having around 40% of students stating they will never use AI for finished assets.
+2
Dutch Games AssociationJan 2024
Report25 pages
Sensor Tower Global Mobile Gaming Industry Outlook 2024
Global mobile gaming experienced a minor 2% year-on-year decline in in-app purchase revenue in 2023, totaling $76.7 billion. Despite this slight contraction, the market remains 22% larger than pre-pandemic levels in 2019. Projections indicate a recovery to $78 billion in 2024, with a long-term growth trajectory expected to surpass $100 billion by 2028 at an average annual growth rate of 6.8%. These findings are based on Sensor Tower App Performance Insights, covering the App Store and Google Play across major global markets including the United States, China, Japan, and South Korea.
The industry is currently defined by a shift in consumer spending from mid-core and hardcore titles toward casual and hybrid-casual models. Casual game revenue grew 8% to $28.6 billion in 2023, now accounting for 38% of the global market. Hybrid-casual games showed the most aggressive growth, increasing 30% to exceed $2.1 billion. In contrast, traditional high-revenue genres like RPGs and Strategy games both saw 10% revenue declines as the pandemic-era stay-at-home boost faded. Despite these drops, RPGs and Strategy remain the largest individual segments, generating $20 billion and $14.8 billion respectively.
Geographically, the United States remains the largest market at $22.2 billion, followed by the Chinese iOS market at $15.1 billion. While the Japanese and South Korean markets saw declines of 13% and 7% respectively, specific titles defied broader trends. MONOPOLY GO! and Royal Match emerged as major drivers in the casual sector, with the former generating $1.2 billion and the latter surpassing Candy Crush Saga in monthly revenue. In the mid-core space, new entrants like Honkai: Star Rail and Whiteout Survival achieved significant growth, particularly in APAC markets, by utilizing innovative themes and integrated gameplay mechanics.
- Global mobile gaming revenue reached $76.7 billion in 2023, a 2% year-on-year decline, but is projected to recover to $78 billion in 2024 and exceed $100 billion by 2028.
- Consumer spending is shifting toward casual and hybrid-casual models, with casual revenue growing 8% to $28.6 billion and hybrid-casual revenue surging 30% to over $2.1 billion.
- Traditional high-revenue segments, specifically RPGs and Strategy games, experienced a 10% decline in 2023, though they remain the largest categories at $20 billion and $14.8 billion respectively.
- The United States remains the top global market with $22.2 billion in revenue, followed by the Chinese iOS market at $15.1 billion.
- Casual titles like MONOPOLY GO!, which generated $1.2 billion, and Royal Match, which surpassed Candy Crush Saga in monthly revenue, are currently driving market growth.
+2
Sensor TowerJan 2024
Report4 pages
Company Profiles: Slovakia 2024
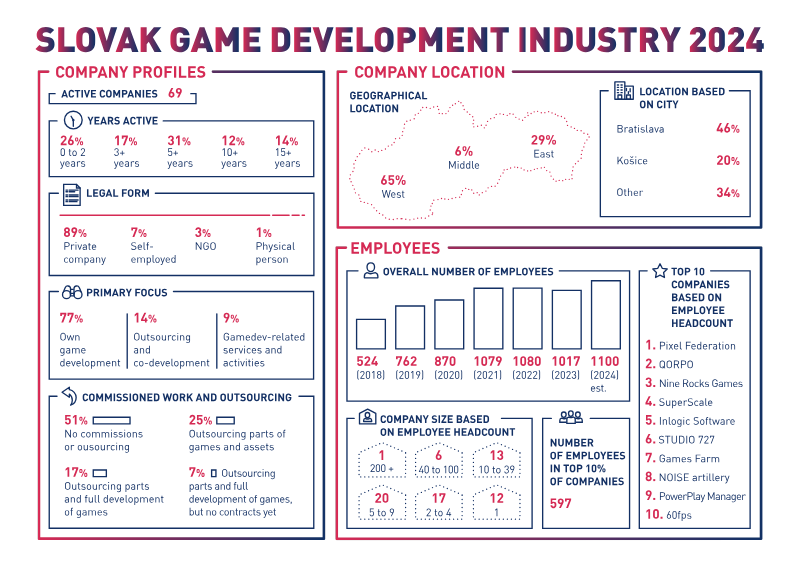
The Slovak game development industry in 2024 is characterized by a stable ecosystem of 69 active companies, primarily concentrated in the western region of the country, particularly Bratislava. The sector is dominated by private companies, with 77% focusing on original game development rather than outsourcing. While the industry experienced a slight contraction in headcount during 2023, it is projected to rebound to approximately 1,100 employees by the end of 2024. The workforce is relatively young, with a median age of 31, and women represent 21% of the total labor force, primarily occupying roles in graphic arts and marketing.
Financial data indicates a mature but concentrated market. The overall industry turnover for 2023 reached over 70 million EUR, a figure expected to remain stable through 2024. However, wealth is highly centralized, with the top 10% of companies—led by major players like Pixel Federation and Nine Rocks Games—accounting for 83.5% of total revenue. Funding remains largely internal, as 65.2% of projects are self-funded, though public funding supports roughly one-third of the industry.
Technologically, PC remains the primary development platform, utilized by 72.5% of developers, followed by mobile and console platforms. Despite the industry's creative success, developers face significant hurdles in recruitment, particularly for programming and game design roles. To foster future growth, industry stakeholders express a strong desire for increased state support, specifically in the form of R&D funding, tax incentives, and improved educational infrastructure to streamline the employment of both domestic and foreign talent.
- The Slovak game industry is highly concentrated, with the top 10% of companies—including Pixel Federation and Nine Rocks Games—generating 83.5% of the sector's 70 million EUR annual turnover.
- The industry consists of 69 active companies, 77% of which focus on original game development rather than outsourcing services.
- After a slight contraction in 2023, the workforce is projected to reach approximately 1,100 employees by the end of 2024, with a median age of 31 and 21% female representation.
- Financial independence is the industry standard, as 65.2% of projects are self-funded, while public funding supports approximately one-third of the market.
- PC remains the dominant development platform, utilized by 72.5% of Slovak studios, followed by mobile and console platforms.
+1
Swiss Game Developers AssociationJan 2024
Report52 pages
Global Games Market Report
The global games market is entering a period of stabilization and renewed growth, with 2023 revenues projected to reach $184.0 billion. This recovery follows a post-pandemic correction and is supported by a massive player base of 3.31 billion people worldwide. While the industry faces macroeconomic pressures and shifting privacy regulations, long-term forecasts remain positive, with total revenues expected to climb to $205.4 billion by 2026. This trajectory is fueled by the maturation of the current console generation, the expansion of the middle class in emerging markets, and the increasing influence of transmedia strategies that drive engagement across multiple entertainment formats.
Market dynamics are shifting significantly across different platforms and regions. Mobile gaming remains the largest revenue segment at $89.7 billion, yet it is currently experiencing a 1.4% decline as privacy policies complicate user acquisition and monetization, particularly within the RPG genre. In contrast, the PC and console segments are the primary growth engines for 2023, benefiting from a steady supply of hardware and a robust slate of high-profile releases. Geographically, the Asia-Pacific region maintains its dominance, accounting for 46% of global revenue, even as regulatory hurdles in China slow its immediate growth. Meanwhile, significant capital infusions, such as Saudi Arabia’s $38 billion investment through Savvy Games Group, are reshaping the competitive landscape.
Technological and structural transformations are further defining the industry's future. Generative AI is emerging as a pivotal tool for managing the rising costs of AAA development, though its adoption is tempered by concerns over copyright and workforce impact. Revenue models have transitioned almost entirely to digital formats, with physical sales becoming negligible in the PC market and live-service models dominating console engagement. As the industry evolves, the rise of cloud gaming and handheld "complementary devices" like the Steam Deck are expanding how and where players interact with content, ensuring the market remains resilient despite shifting regulatory and economic conditions.
- The global games market is projected to reach $184.0 billion in 2023, with a forecast to grow to $205.4 billion by 2026 supported by a 3.31 billion-person player base.
- Mobile gaming remains the largest revenue segment at $89.7 billion, though it is currently experiencing a 1.4% decline due to privacy-related challenges in user acquisition and monetization.
- PC and console gaming are the primary industry growth engines for 2023, driven by improved hardware supply and a strong pipeline of high-profile software releases.
- The Asia-Pacific region continues to dominate the global market with 46% of total revenue, despite regulatory headwinds currently impacting growth in China.
- Large-scale capital investments, such as the $38 billion commitment from Saudi Arabia’s Savvy Games Group, are actively reshaping the competitive landscape.
+1
NewzooJan 2024
Report6 pages
GungHo Online Entertainment Business Report Vol. 42
GungHo Online Entertainment’s business report outlines a strategic transition from a Japan-centric mobile focus toward a diversified global entertainment model. The primary thesis centers on leveraging established intellectual properties, specifically Puzzle & Dragons and the Ragnarok series, to anchor international expansion while developing new console and PC titles for a worldwide audience.
Financial data indicates a significant shift in revenue composition, with the overseas sales ratio rising steadily to reach 64.1% by late 2024. While consolidated net sales saw a decline from 125.3 billion yen in 2023 to 103.6 billion yen in 2024, the group maintained a strong capital-to-asset ratio of 75.9%. Performance in the first half of 2025 shows net sales of 50.5 billion yen and an operating profit of 5.0 billion yen. To enhance shareholder value, the company revised its return policy in February 2025, committing to a consolidated dividend payout ratio of 30% or more and executing substantial share cancellations.
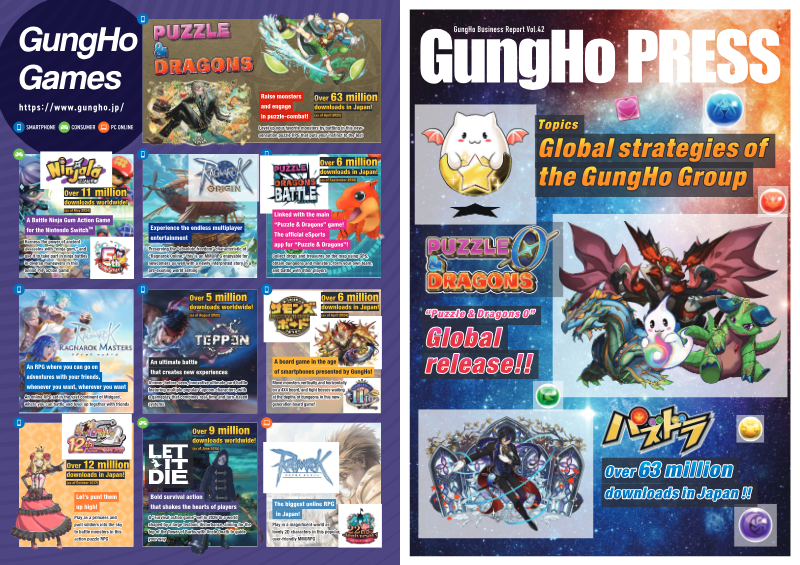
The report highlights the longevity of core titles, noting that Puzzle & Dragons celebrated its 13th anniversary with over 63 million downloads in Japan. To sustain this momentum, the group released Puzzle & Dragons 0 in May 2025 across 150 countries in 11 languages. Simultaneously, the Ragnarok IP, managed by subsidiary Gravity Co., Ltd., has grown from 5 billion yen in annual sales in 2008 to approximately 50 billion yen, driven by mobile expansions in Asia and new initiatives in Latin America.
Future growth is targeted through multi-platform development and the revitalization of existing series. Key projects include the redevelopment of the survival action title Deathverse: Let It Die and the release of the Lunar Remastered Collection. By focusing on original IPs for consoles and PC—areas where the group can demonstrate technical expertise—GungHo aims to establish brand recognition in Western markets where it was previously less known.
- GungHo has successfully pivoted to a global business model, with overseas sales now accounting for 64.1% of total revenue as of late 2024.
- Consolidated net sales declined from 125.3 billion yen in 2023 to 103.6 billion yen in 2024, though the company maintains a strong capital-to-asset ratio of 75.9%.
- The Ragnarok IP, managed by subsidiary Gravity Co., Ltd., has scaled significantly, growing from 5 billion yen in annual sales in 2008 to approximately 50 billion yen today.
- To sustain the 13-year-old Puzzle & Dragons franchise, the company launched Puzzle & Dragons 0 in May 2025 across 150 countries in 11 languages.
- The company is shifting focus toward console and PC development to build Western brand recognition, with key projects including the Lunar Remastered Collection and the redevelopment of Deathverse: Let It Die.
GungHo Online EntertainmentJan 2024
Report16 pages
State of Free to Play on Steam in 2024
The analysis evaluates the free‑to‑play (FtP) segment on Steam, highlighting its dominant share of player engagement and the increasing difficulty for new titles to break through. In 2023, FtP games accounted for 51 % of total hours played on the platform, despite premium titles comprising the majority of releases. Engagement is highly concentrated: the top 25 FtP titles generate 88 % of all FtP activity, the top 10 capture roughly 70 %, and the top five hold nearly 60 % of concurrent users (CCU). Counter‑Strike 2 and Dota 2 continue to lead the charts, with eight of the ten highest‑CCU games in 2023 being FtP, while only one premium title (Rust) appears in the list.
The market shows signs of compression as high‑quality premium and paid‑live‑service games erode FtP share. Between 2021 and 2024, premium titles priced $10‑$50 grew from 31 % to 37 % of total playtime, and flagship releases such as Elden Ring and Hogwarts have boosted the over‑$50 segment. Nonetheless, FtP titles remain older on average; the top ten FtP games have a mean age of seven years, and only two new entries (Call of Duty Warzone and Naraka: Bladepoint) have entered the top‑ten
- Free-to-play (FtP) games dominate Steam engagement, accounting for 51% of total hours played in 2023 despite being outnumbered by premium releases.
- Market engagement is highly concentrated, with the top 25 FtP titles capturing 88% of all FtP activity and the top five titles holding nearly 60% of concurrent users.
- The FtP sector is stagnant for new entrants, as the top ten FtP games have a mean age of seven years and only two new titles have broken into that tier since 2021.
- FtP titles maintain a massive presence in the top-tier charts, occupying eight of the ten highest concurrent-user spots in 2023, with Counter-Strike 2 and Dota 2 leading the segment.
- Premium titles are successfully eroding FtP market share, with games priced between $10 and $50 increasing their share of total playtime from 31% to 37% between 2021 and 2024.
+1
Video Game InsightsJan 2024
Report13 pages
Behind the Screens: The Salary Stats in Gamedev
This research, conducted by 80 Level in January 2024, examines the global compensation landscape and financial well-being of professionals within the video game development industry. Based on a survey of over 1,000 respondents from the 80 Level Research panel and reader base, the study analyzes how geography, years of experience, and specific job roles influence annual income and purchasing power.
The findings reveal a highly stratified industry where nearly 40% of developers earn less than $40,000 annually, while only 11% exceed the $150,000 mark. Geographic location serves as a primary driver of these disparities; for instance, 36% of U.S.-based professionals earn over $150,000, whereas 54% of surveyed developers in India earn under $9,999. In Europe, the majority of professionals in the UK, Germany, and Sweden fall within the $30,000 to $79,999 range. The data also highlights a significant "cost of living" gap, noting that while 16.6% of the workforce can afford all discretionary purchases, 24.4% earn enough for a car but remain unable to afford a residence.
Experience levels further dictate earning potential, with 74% of interns earning under $9,999, while 24% of Directors and Leads exceed $150,000. The analysis of specific roles shows that Creative Directors and Software Developers generally occupy higher salary segments compared to Artists and Game Designers. Notably, the study identifies a segment of "struggling" C-level executives (19%), likely representing founders of small indie studios who face financial instability despite their titles. The research concludes that while the industry offers high-earning potential at senior levels in Western hubs, a substantial portion of the global workforce operates under significant financial constraints.
- The game development industry is highly stratified, with nearly 40% of professionals earning under $40,000 annually and only 11% earning more than $150,000.
- Geography is a primary driver of income disparity, evidenced by 36% of U.S.-based professionals earning over $150,000 compared to 54% of developers in India earning under $9,999.
- Financial instability is prevalent, as 24.4% of the workforce can afford a car but cannot afford a residence, while only 16.6% can afford all discretionary purchases.
- Experience correlates strongly with compensation, as 74% of interns earn under $9,999, whereas 24% of Directors and Leads earn over $150,000.
- Creative Directors and Software Developers generally command higher salaries than Artists and Game Designers.
+1
80 LevelJan 2024
Report27 pages
Games Market Trends to Watch in 2024
The global games market in 2024 is characterized by a period of stabilization and strategic restructuring following the post-pandemic correction. While the industry saw a revenue decline in 2022, recovery began in 2023 and is expected to continue through 2024, driven largely by the expanding install base of current-generation consoles like the PlayStation 5 and Xbox Series X|S. Despite this growth, the year is defined as a lean period for many companies as they navigate high interest rates, reduced investment capital, and a highly competitive landscape where a small number of titles dominate the majority of player engagement.
Key findings indicate a significant shift in business models and platform strategies. While live-service games remain the primary revenue drivers, the market is experiencing oversaturation, leading many developers to return to premium, finite gaming experiences. Growth in multi-game subscription services is expected to slow as they face competition from free-to-play social platforms like Fortnite and Roblox. Additionally, mobile developers are increasingly diversifying by bringing their titles to PC to combat rising user acquisition costs and stricter privacy regulations. Major hardware and distribution shifts are also anticipated, including the launch of a new Nintendo console and the introduction of an Xbox mobile store on Android.
The scope of this analysis covers global market trends across PC, console, and mobile segments, with revenue forecasting extending through 2026. The methodology combines internal market data and analyst perspectives with a survey of gaming executives and industry experts from companies such as Ubisoft, Iron Galaxy Studios, and Savvy Games Group. Emerging technologies like generative AI are identified as tools for increasing production efficiency, though they are not expected to transform game development at scale within the immediate calendar year. Overall, the industry is moving toward risk-reduction strategies, focusing on established intellectual properties and cross-platform accessibility to maintain stability.
- The global games market is in a period of stabilization and recovery throughout 2024, supported by the growing install base of current-generation consoles like the PlayStation 5 and Xbox Series X|S.
- Developers are increasingly pivoting back to premium, finite gaming experiences to counter the oversaturation of the live-service market.
- Mobile developers are expanding to PC platforms to mitigate the impact of rising user acquisition costs and stricter privacy regulations.
- Growth in multi-game subscription services is expected to decelerate as they face direct competition from free-to-play social platforms such as Fortnite and Roblox.
- The industry is preparing for significant infrastructure shifts, including the anticipated launch of a new Nintendo console and the introduction of an Xbox mobile store on Android.
+1
NewzooJan 2024
Report46 pages
The State of Gaming 2024: An Analysis of the Current Mobile Gaming Market Trends
The global mobile gaming market underwent a significant correction in 2023, characterized by a 10% decline in worldwide downloads and a 2% drop in total revenue. This downturn was primarily fueled by escalating user acquisition costs and a post-pandemic stabilization of consumer habits. While the broader market contracted, a distinct shift toward casualization occurred, evidenced by an 8% increase in Casual game revenue and a 30% surge in the Hybridcasual segment. Conversely, Mid-core titles faced a 9% revenue decline, signaling a transition in player preferences toward more accessible experiences.
Geographic performance diverged sharply as publishers pivoted toward emerging markets to mitigate rising costs in established territories. While the Asian market saw a 6% revenue contraction, the Middle East, Europe, and Latin America experienced revenue growth of 8%, 7%, and 4% respectively, despite falling download numbers. This regional resilience was often driven by high-profile intellectual properties, such as the success of Monopoly GO! in Europe and the expansion of Netflix’s gaming portfolio, which saw a 194% increase in downloads through the integration of major franchises like Grand Theft Auto.
Strategic adaptations in 2023 focused on maximizing player lifetime value through Live Ops events and transmedia collaborations. Mobile gaming now commands 67% of global digital advertising spend, with marketing strategies increasingly segmented by platform; YouTube and TikTok serve as primary hubs for core gamers, while Facebook and Pinterest remain vital for reaching casual female audiences. To combat the challenges of the current landscape, the industry has embraced low-cost user-generated content and external subscription models, leveraging recognizable IP to bridge the gap between gaming and broader entertainment media.
- The global mobile gaming market contracted in 2023, with a 10% decline in downloads and a 2% drop in total revenue due to rising user acquisition costs and post-pandemic habit stabilization.
- Player preferences shifted toward accessibility, resulting in an 8% revenue increase for Casual games and a 30% surge in the Hybridcasual segment, while Mid-core titles saw a 9% revenue decline.
- Publishers are pivoting to emerging markets to offset costs, with the Middle East, Europe, and Latin America seeing revenue growth of 8%, 7%, and 4% respectively.
- High-profile intellectual property is a primary growth driver, evidenced by the success of Monopoly GO! in Europe and a 194% surge in Netflix gaming downloads following the integration of franchises like Grand Theft Auto.
- Mobile gaming now accounts for 67% of global digital advertising spend, with marketing strategies increasingly segmented by platform, such as using YouTube and TikTok for core gamers and Facebook and Pinterest for casual female audiences.
+1
Sensor TowerJan 2024
Report39 pages
Art Direction in Game Remakes: An Analysis of 7 Case Studies
The pursuit of a successful game remake requires a delicate equilibrium between honoring the original creative spirit and meeting the heightened technical expectations of modern audiences. Analysis of high-profile titles released through 2024, including Metroid Prime Remastered and Resident Evil 4, indicates that critical and fan reception serves as the primary metric for quality, often superseding raw financial performance. Developers find the most success when they rebuild visual assets from scratch, leveraging contemporary lighting and 3D environments to recreate the atmospheric immersion that original technical constraints once limited.
Modernization strategies vary based on the age and mechanical relevance of the source material. While some titles benefit from subtle control refinements, others require a total overhaul of core systems to remain viable. Capcom’s approach to the Resident Evil series exemplifies this by replacing dated tank controls and fixed cameras with fluid 3D movement and strategic lighting. Similarly, Square Enix transitioned the static backgrounds and turn-based combat of Final Fantasy VII into expansive environments and action-oriented hybrid systems. These shifts demonstrate that adhering to the "pillars of experience" is more vital than preserving obsolete functional elements.
Ultimately, the most effective remakes prioritize the recreation of a specific feeling or "spirit" over mere resolution increases. While visual fidelity must be modernized to maintain immersion, gameplay adjustments should be handled selectively to avoid alienating the core fanbase. Industry leaders like Nintendo and specialized external development partners emphasize that leveraging modern hardware to amplify a game's original intent is the most reliable path to critical acclaim. By focusing on atmospheric depth and evolved control schemes, developers can ensure that classic titles resonate with both nostalgic players and new audiences within the current AAA landscape.
- Successful remakes prioritize the recreation of a game's original 'spirit' and atmospheric intent over simple increases in visual resolution.
- Critical and fan reception serves as the primary metric for quality in modern remakes, often outweighing raw financial performance.
- Developers achieve the highest success by rebuilding visual assets from scratch to leverage contemporary lighting and 3D environments, overcoming the technical constraints of original releases.
- Modernization strategies must distinguish between preserving 'pillars of experience' and replacing obsolete functional elements, such as Capcom’s transition from fixed cameras to fluid 3D movement in Resident Evil 4.
- Square Enix’s approach to Final Fantasy VII demonstrates that transitioning from static backgrounds and turn-based combat to expansive, action-oriented systems can effectively modernize legacy titles.
+1
Room 8 GroupJan 2024