The Game
Game
Documents about The Game
The Game Incubation Landscape in Europe: Appraisal of the BSR in the European Context
The European game incubation landscape functions as a critical pillar of regional economic development, operating primarily through a mix of public subsidies, academic partnerships, and private-sector initiatives.
- The Baltic Sea Region (BSR) has 24 game-focused incubators and accelerators, with half located in Sweden (6) and Finland (6). Nearly 40% (9) of these programs were established in the last three years, indicating a recent trend.
- Most BSR incubation programs prioritize supporting regional ecosystem development and university students/alumni.
- Governments are crucial for fostering an environment where incubator capacity-building initiatives can thrive, by adopting laws and regulations that promote research, development, and entrepreneurship.
The Game Industry of Poland: 2020
The Polish game development industry has matured into a significant global powerhouse, characterized by a diverse ecosystem of over 440 studios and a workforce of approximately 9,710 full-time professionals.
- The Polish game industry has over 440 studios and companies, with 43 of them listed on the Warsaw Stock Exchange (12 on the main floor, 31 on NewConnect).
- Between 2017 and 2020, over 120 studios closed down while over 160 new ones were established, indicating a high variability in the sector, though the rapid growth observed before 2017 has slowed.
- 11 bit studios, founded in 2009 by former Metropolis studio members, developed 'This War of Mine' (the first video game on Poland's official school reading list) and 'Frostpunk', and has 140 employees.
The Game Industry of Finland 2015
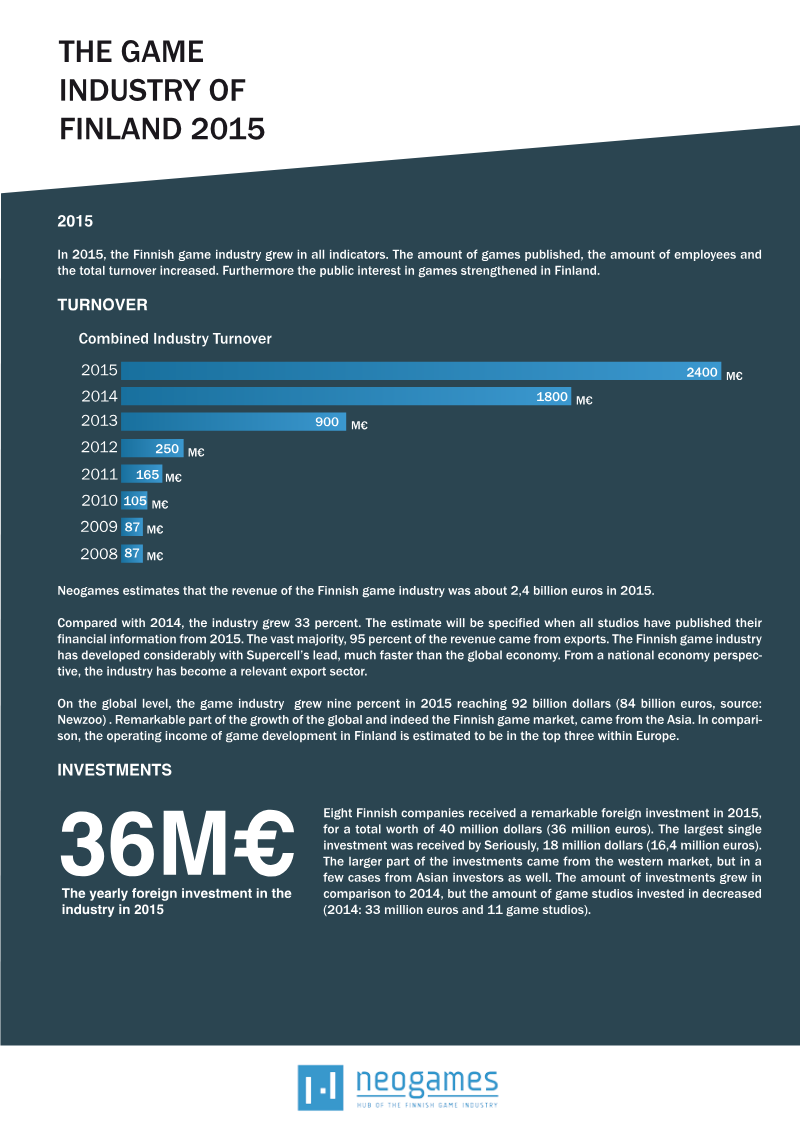
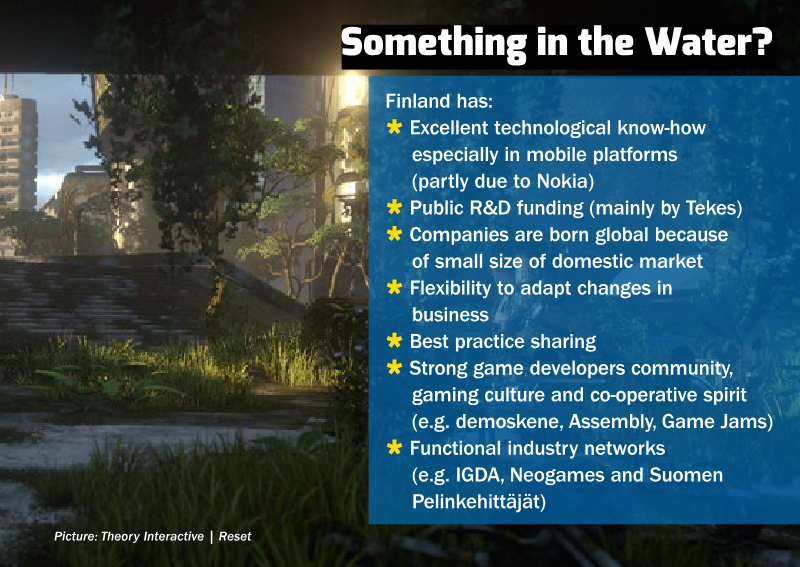
The Finnish game industry experienced significant expansion throughout 2015, characterized by robust growth in turnover, employment, and output.
- The Finnish game industry generated 2.4 billion euros in turnover in 2015, marking a 33 percent year-over-year growth that solidified the country as a top-three European hub for game development.
- Exports are the primary economic driver for the sector, accounting for 95 percent of total industry revenue.
- The industry employed 2,700 professionals across 290 active companies, with the majority of talent and operations concentrated in the Helsinki metropolitan area.
The Game Industry of Finland: 2014
The Finnish game industry underwent a period of extraordinary expansion between 2008 and 2013, transforming into a cornerstone of the national economy.
- Between 2008 and 2013, the Finnish game industry's core development revenue grew from €87 million to an estimated €900 million, with a total economic impact exceeding €2 billion.
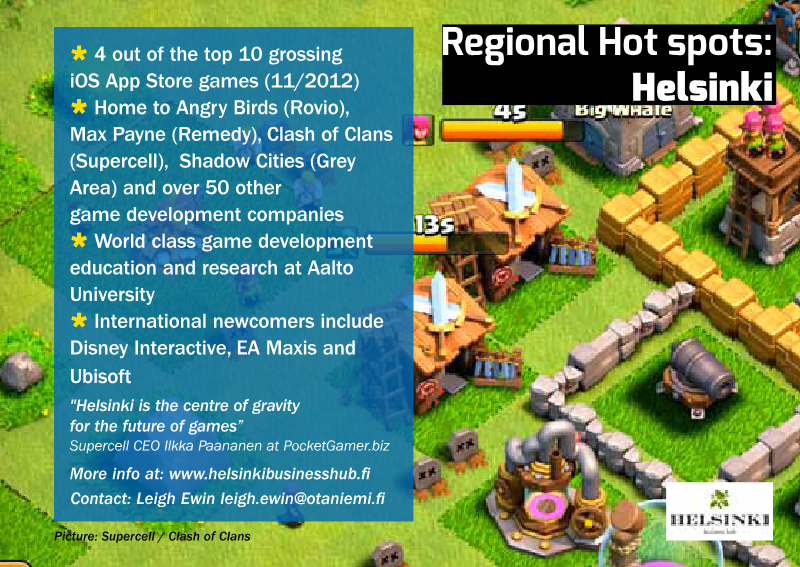
- Finland has established itself as a premier global hub for mobile game development, characterized by a highly scalable digital product ecosystem and a focus on high-growth export markets.
- The industry is supported by a network of over 200 companies, including major international players such as Rovio and Remedy alongside a robust community of independent studios.
The Game Industry of Finland: 2013
The Finnish game industry experienced a period of rapid expansion between 2009 and 2013, establishing itself as a significant global player.
- The Finnish game industry experienced explosive financial growth, with core turnover rising from 87 million euros in 2009 to an estimated 800 million euros in 2013.
- The sector achieved a compound annual growth rate of 39.5% between 2004 and 2013, significantly outperforming the global game market.
- By the end of 2013, the industry comprised over 180 companies, with more than 50% of these entities founded within the previous two years.
Game Developer Index 2009: Sweden
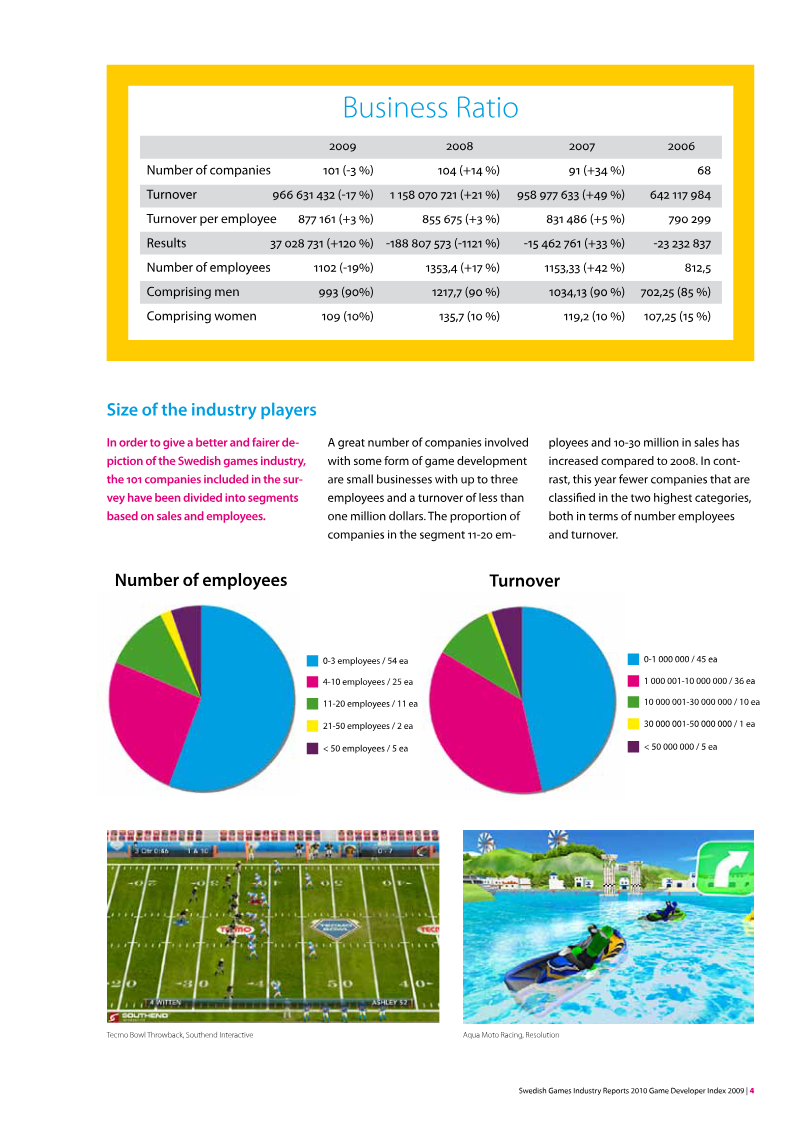
The Game Developer Index 2009 provides a comprehensive financial and operational overview of the Swedish game development industry.
- The Swedish game industry experienced a 19 percent decline in employment and a 17 percent decrease in total turnover during 2009 due to the broader economic downturn.
- The sector is highly concentrated, with the five largest companies accounting for over 60 percent of both total industry employment and total turnover.
- Despite the overall revenue decline, the industry improved its operational efficiency, marking the third consecutive year of rising turnover per employee.
Game Developer Index: Sweden 2008
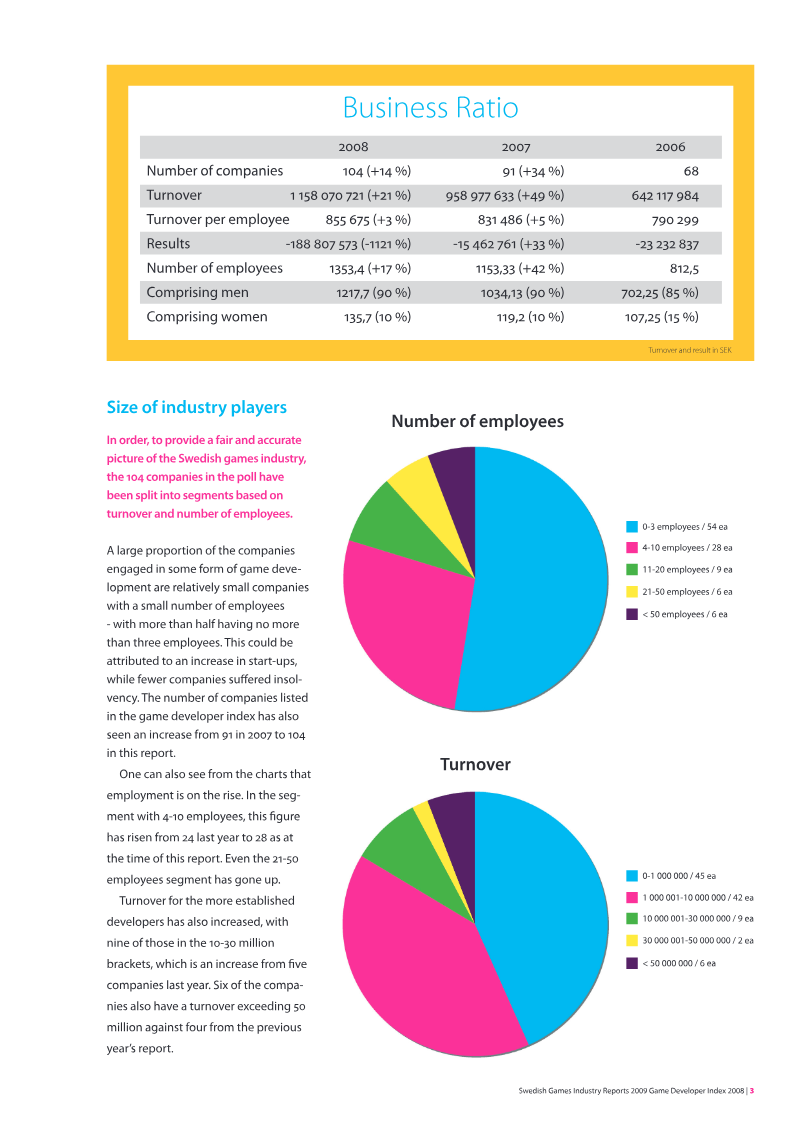
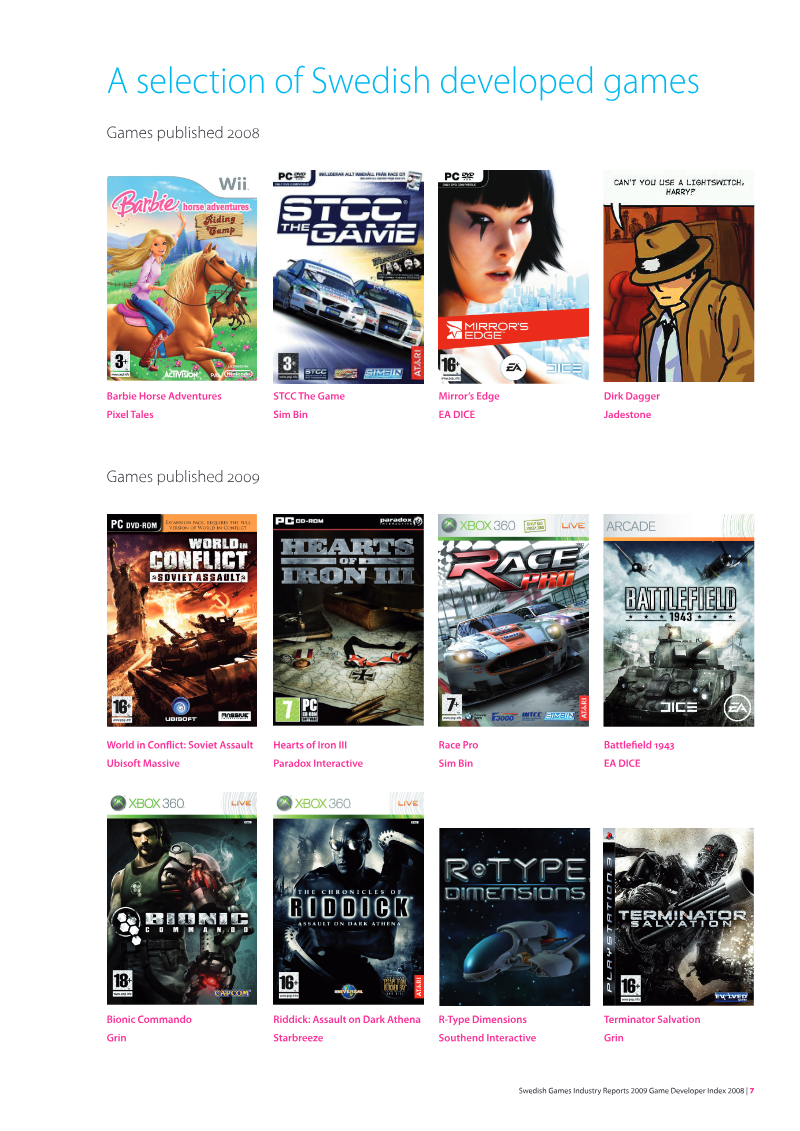
The Game Developer Index 2008 provides a comprehensive financial and operational overview of the Swedish computer game development industry.
- The Swedish game industry experienced significant growth in 2008, recording a 21 percent increase in turnover and a 17 percent rise in employment.
- Industry activity is highly polarized, with the five largest companies generating 64.2 percent of total turnover and accounting for 52.2 percent of total employment.
- Despite individual successes, the industry reported an aggregate negative financial outcome in 2008, driven by high costs for large-scale console development and the presence of many pre-revenue startups.
Companies behind it
As the documents state it.