Battle Royale
Game
Documents about Battle Royale
Vietnam Game Industry Monthly Report: May 2026
The Vietnam Game Industry Monthly Report for May 2026 provides a comprehensive analysis of the mobile gaming landscape, highlighting a shift in market dynamics from pure volume-based acquisition to a focus on operational depth and regulatory compliance.
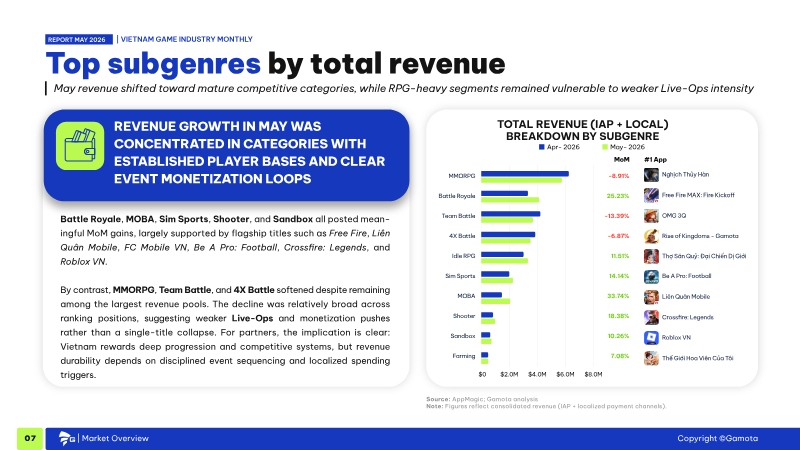
- Vietnam's mobile IAP revenue grew by 3.13% MoM in May 2026, driven by strong monetization in long-lifecycle genres like Battle Royale, MOBA, and Sim Sports rather than new user acquisition.
- Midcore total revenue reached its highest level between January and May 2026, rising 4.44% MoM as established titles like Free Fire MAX, Liên Quân Mobile, and Roblox VN leveraged recurring Live-Ops and event-based spending.
- New game success in Vietnam is increasingly dependent on cultural fit, with titles featuring wuxia/xianxia settings, football fandom, or nostalgic IP—such as Giang Hồ Kỳ Ngộ and Total Football VNG—outperforming generic Western fantasy products.
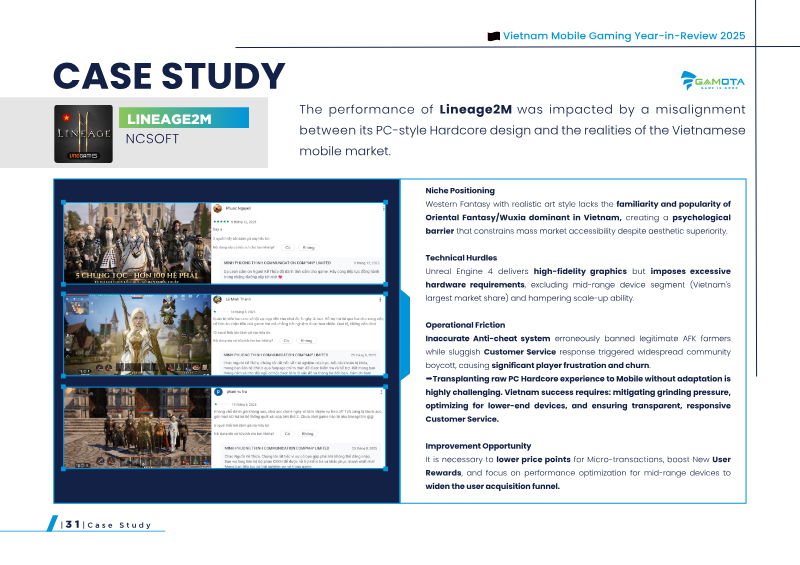
Vietnam Mobile Gaming Year-in-Review 2025
The Vietnamese mobile gaming market is undergoing a fundamental transition in 2025, moving away from high-volume download strategies toward a model defined by sustainable monetization and operational maturity.
- The Vietnamese mobile gaming market is projected to reach $825 million in annual revenue in 2025 as it shifts from high-volume downloads to a focus on sustainable monetization.
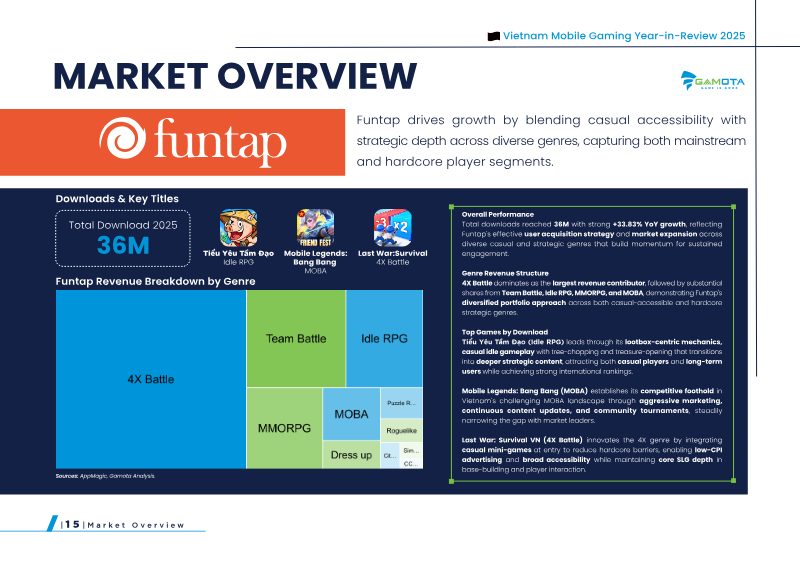
- Market dominance is currently held by midcore and hardcore genres, specifically MMORPGs, 4X strategy, and team-based battle games, as casual titles struggle with user conversion.
- Success in the region requires strict adherence to Decree 147 and the establishment of robust local licensing partnerships to navigate the complex regulatory environment.
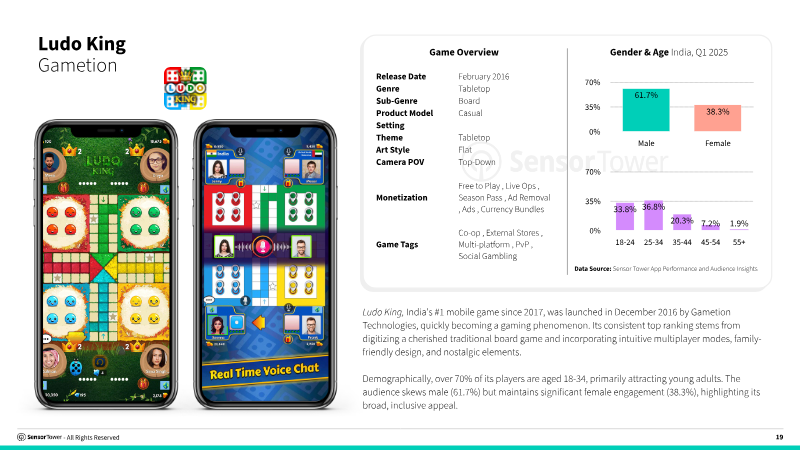
Sensor Tower India: Mobile Game Market Insights 2025
India is positioned as the world’s largest mobile-gaming market, with 8.45 billion downloads recorded in FY 2024-25 yet only $400 million in in-app purchase (IAP) revenue, underscoring a pronounced monetization gap despite high engagement.
- India is the world's largest mobile-gaming market by volume, recording 8.45 billion downloads in FY 2024-25 but generating only $400 million in in-app purchase (IAP) revenue.
- Monetization is heavily concentrated in competitive, engagement-heavy genres including Shooter, Casino, and Strategy (4X), while high-volume downloads are driven by casual Simulation, Arcade, and Tabletop titles.
- The player base is predominantly male (86%) and aged 18-34 (77%), though lifestyle titles represent a unique segment for attracting female gamers.
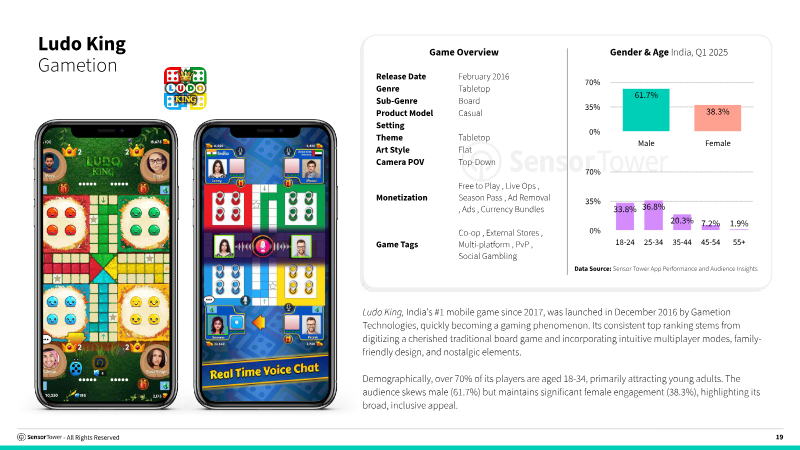
Mobile Game Market Insights: India 2025
India is the world’s largest mobile gaming market by volume, reaching 8.45 billion downloads in the 2024-25 fiscal year.
- India is the world's largest mobile gaming market by volume, recording 8.45 billion downloads in the 2024-25 fiscal year.
- Despite high download volume, in-app purchase revenue is limited to $400 million, though it is growing at 8.5% year-over-year due to increased digital payment adoption and high-value iOS spenders.
- Revenue is heavily concentrated in core competitive genres, with Battle Royale titles like Garena Free Fire and Battlegrounds Mobile India accounting for 50% of total market earnings.
Mobile Games Report: H1 2024
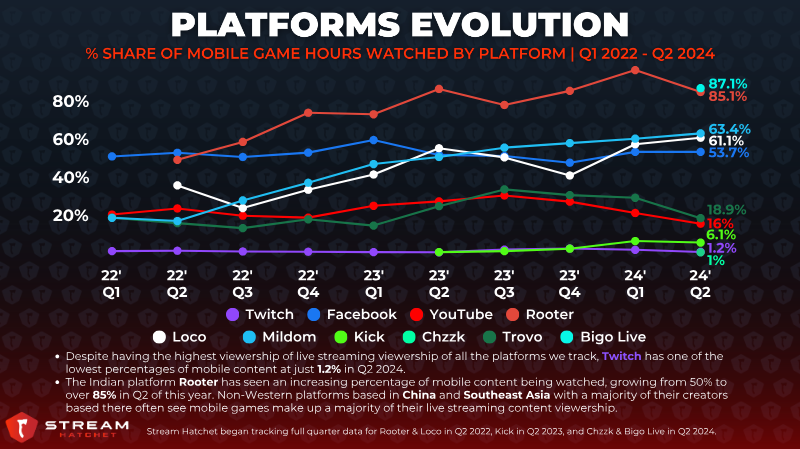
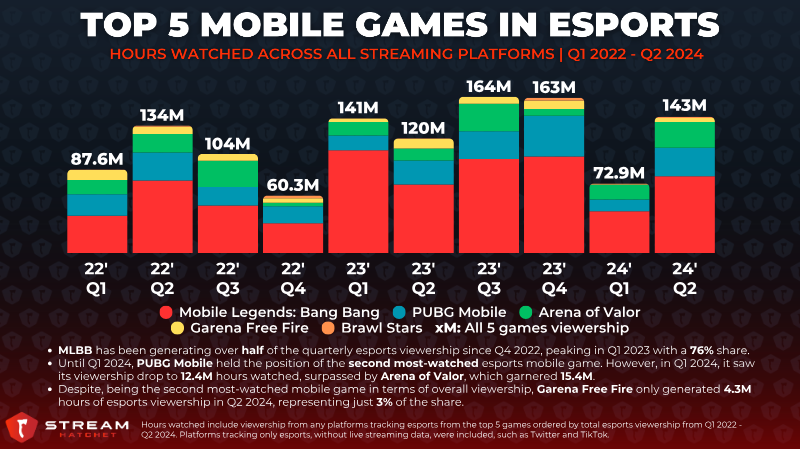
The mobile gaming live-streaming landscape experienced a period of stabilization during the first half of 2024, following a post-pandemic decline in general viewership.
- YouTube Gaming dominates the mobile sector with 69% of total mobile hours watched and 77% of mobile esports viewership, driven largely by audiences in India and Indonesia.
- Mobile esports is the primary growth engine for the sector, experiencing a 52% increase in hours watched between 2022 and 2023 and now accounting for nearly half of all mobile gaming viewership.
- Mobile gaming live-streaming viewership showed resilience in H1 2024 with a 4% year-over-year increase, despite mobile games representing only 7% of total live-streaming hours in Q2 2024.
2023 Yearly Live Streaming Trends Report
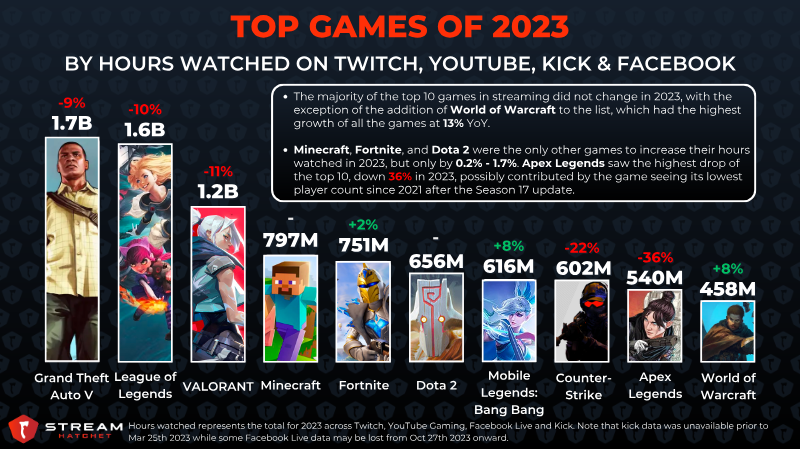
The global live streaming market entered a period of stabilization in 2023, reaching 38.3 billion hours watched with the lowest volatility recorded since 2020.
- The global live streaming market stabilized at 38.3 billion hours watched in 2023, characterized by Twitch's 4.9% decline and YouTube Gaming's 11% growth.
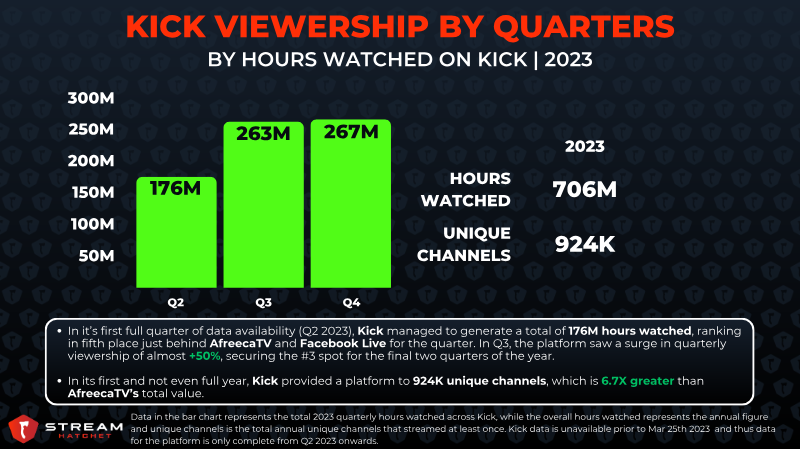
- Kick emerged as the third-largest Western streaming platform within its first year, hosting nearly one million unique channels and displacing Facebook.
- Esports viewership grew 9% year-over-year to 2.5 billion hours, with co-streaming now driving nearly 30% of total esports consumption.
State of Mobile 2024
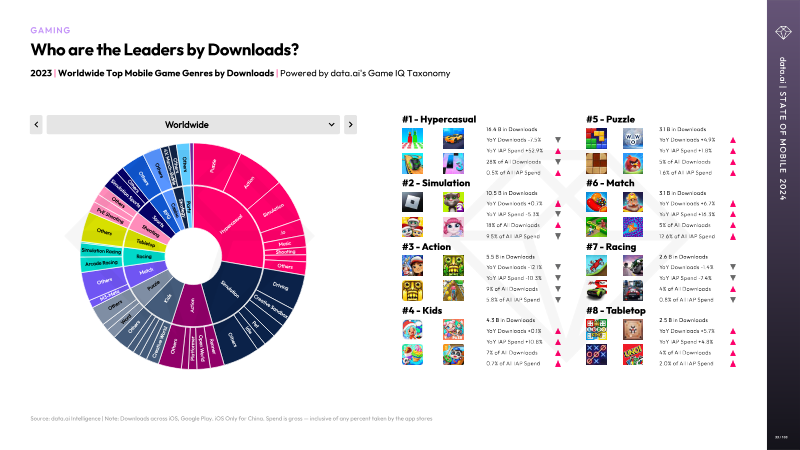
The global mobile economy experienced a significant recovery in 2023, with consumer spending rising 3% to $171 billion and daily engagement surpassing five hours per user in leading markets.
- The global mobile economy grew 3% to $171 billion in 2023, supported by a $362 billion advertising market projected to exceed $400 billion in the coming year.
- Mobile gaming spending contracted by 2% as the industry consolidated around established high-fidelity IPs and social multiplayer genres, though titles like Monopoly GO and Honkai: Star Rail proved that high-quality debuts remain viable.
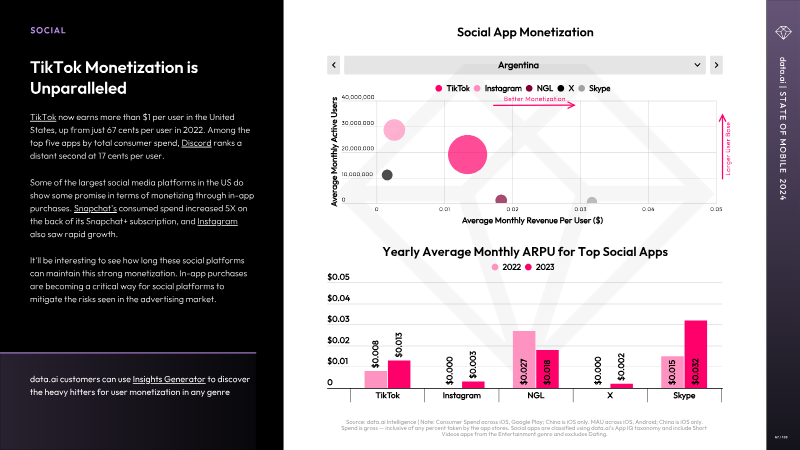
- Non-gaming apps reached a record $64 billion in consumer spend, highlighted by TikTok becoming the first non-game app to surpass $10 billion in lifetime revenue.
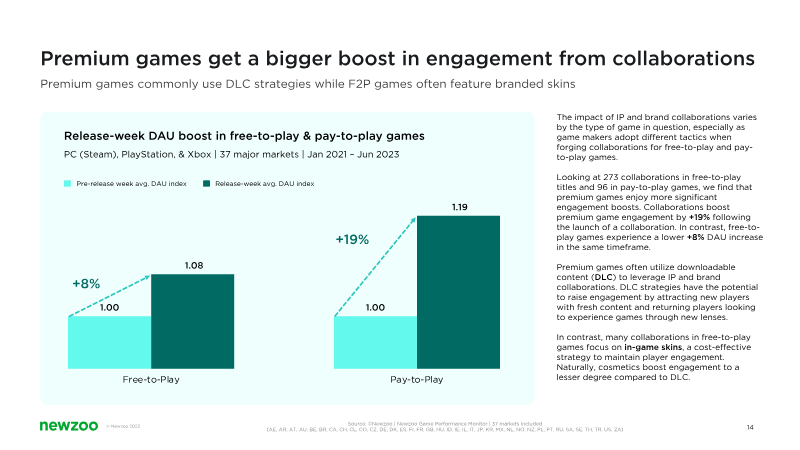
How IP and Brand Collaborations Level Up Games
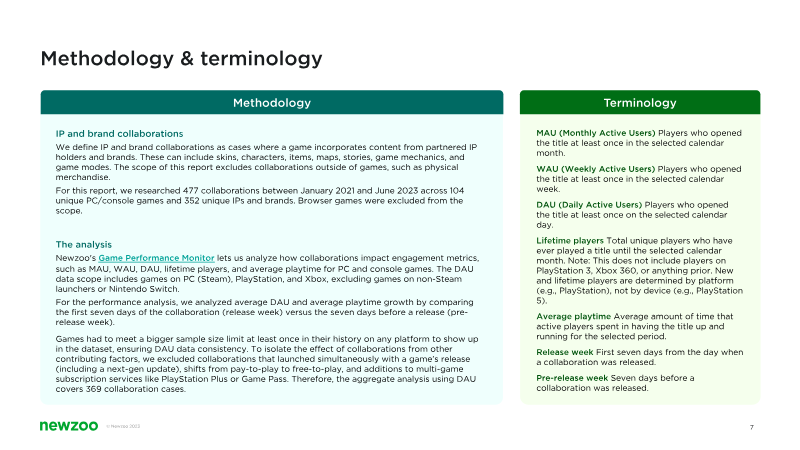
IP and brand collaborations serve as a critical strategic lever for boosting player engagement and revenue in the modern games market.
- Aligning in-game collaborations with external transmedia marketing, such as theatrical film releases, can drive DAU increases of up to 120%.
- IP collaborations generate an average 11% increase in daily active users (DAU) during the first week of launch, with engagement typically peaking between the fourth and fifth days.
- Premium games see a 19% average DAU boost from collaborations, significantly outperforming free-to-play titles, which see an 8% increase due to a heavier reliance on cosmetic-only content.


Five Key Mobile Game Genres in Asia and MENA
The bulletin delivers a data-driven assessment of the five most influential mobile game genres in Asia and MENA for 2022, combining a 9,000-respondent survey from Niko Partners with AppMagic’s analytics of Apple and Google Play stores.
- RPG titles are the dominant market force, generating 50% more revenue than the other four top genres combined and achieving the highest monetization score of 7.7.
- Puzzle games command the largest download volume and highest engagement score of 6.0, though they suffer from low monetization and minimal esports relevance.
- Battle Royale games lead the market in esports influence with a score of 9.5, despite generating the lowest total revenue among the five genres.
How Different Generations Engage with Video Games Today
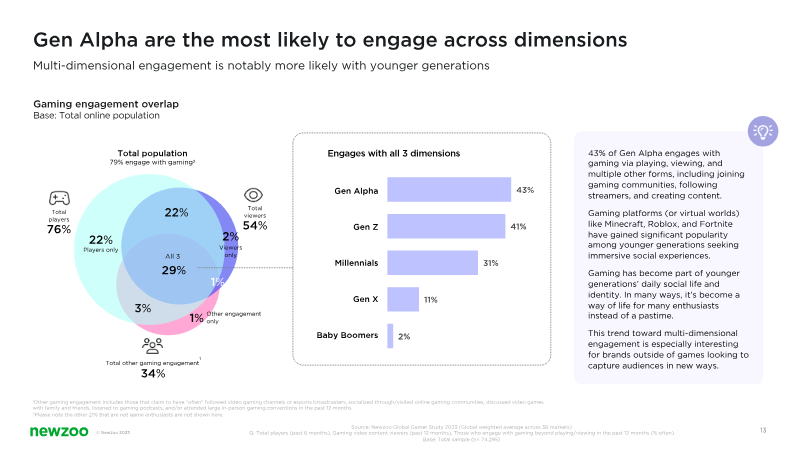
Gaming has evolved into the primary entertainment medium for younger generations, with 94% of Gen Alpha identifying as game enthusiasts.
- Gaming has become the primary entertainment medium for younger generations, with 94% of Gen Alpha identifying as game enthusiasts.
- Approximately 60% of younger players invest in games, driven by a preference for social immersion and genres like Adventure and Battle Royale.
- 70% of younger players are 'player-viewers' who consume gaming content for social connection, whereas older generations use such content primarily for information like reviews and tutorials.
Peak Play: Trends in East Asian Videogame Streaming H1 2023
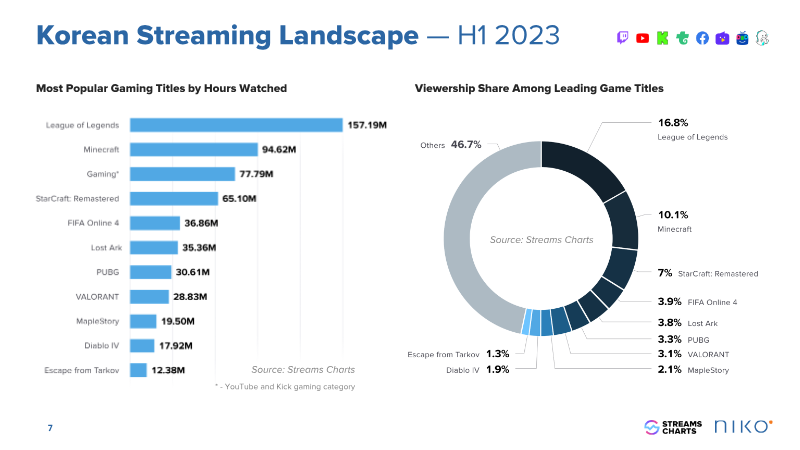
The East Asian videogame livestreaming market is a mature and culturally distinct ecosystem where competitive esports serve as the primary engine for audience engagement.
- Competitive esports, specifically MOBA and Battle Royale titles, drive over 50% of total viewership in the East Asian streaming market.
- Honor of Kings remains the dominant force in China with 5.67 billion views, while VALORANT and Apex Legends lead in Japan and Korea with over 100 million hours watched each.
- Key Opinion Leaders and VTubers are significant market drivers, contributing up to 15% of total viewership for major titles and successfully revitalizing older games.
Rapporto sugli Esports in Italia: 2019
The Italian esports landscape experienced significant professionalization in 2019, characterized by a burgeoning audience of 1.2 million individuals.
- The Italian esports market reached 1.2 million viewers in 2019, with 350,000 avid fans engaging with competitive content on a daily basis.
- Twitch emerged as a primary engagement hub, recording a 32% increase in esports-related discussions during the 2019 period.
- The audience is primarily composed of males aged 16 to 40, with the highest concentrations of enthusiasts residing in the Lombardy and Lazio regions.