Global
Documents
How to Build an Effective Offer System in Your Game
A well‑designed in‑game offer system is presented as the most potent driver of lifetime value and average revenue per paying user. By integrating a limited set of synergistic offer types—login bonuses, triggered prompts, endless streams, “1 + X” bundles, battle‑passes, stamp‑cards, and curated bundles—and optimizing their frequency, timing, pricing, segmentation, and economic balance, developers can achieve conversion rates as high as ninety‑six percent on login offers and lift repeat‑purchase value by roughly twenty percent through endless offers.
Conversion is shown to be a function of repeated exposure rather than a single impression; players typically require about seven viewings before taking action. The most effective moments to surface offers are at login, during “out‑of‑currency” events, after level failures, or in high‑momentum gameplay phases. A dynamic, tiered pricing ladder that escalates after each purchase and regresses after periods of inactivity—exemplified by a seven‑tier structure ranging from under one dollar to ninety‑nine dollars—enables precise alignment with player spend propensity while avoiding both under‑monetization of high‑potential users and alienation of low‑spenders.
Segmentation must extend beyond basic recency and frequency metrics to incorporate geographic tier, acquisition source quality, and player progression. Lower‑tier regions demand adjusted price ladders and reduced offer frequency, whereas high‑quality acquisition channels justify more complex bundles. Early‑game players respond best to inexpensive, simple offers, while mid‑ and late‑game users can be presented with higher‑value packages. Anchoring the entire shop around a stable, low‑priced entry pack establishes a reference point that shapes perceived value across all offers.
Collectively, these principles apply to mobile and casual games operating globally, reflecting current industry practices and data from recent case studies. Implementing the outlined framework promises measurable improvements in monetization efficiency, player satisfaction, and overall revenue performance.
- A tiered pricing ladder ranging from under $1 to $99, which escalates after purchases and regresses during inactivity, allows for precise alignment with individual player spend propensity.
- Conversion is driven by repeated exposure, with players typically requiring seven viewings of an offer before completing a purchase.
- Strategic implementation of a limited set of offer types can drive conversion rates as high as 96% on login offers and increase repeat-purchase value by approximately 20% through endless offers.
- Effective offer surfacing relies on high-intent moments, specifically at login, during out-of-currency events, after level failures, or during high-momentum gameplay.
- Player segmentation must incorporate geographic tier, acquisition source quality, and progression stage to adjust price ladders and offer frequency for different user profiles.
2026 Predictions: Trends in Gen AI, Gaming & Digital Ad Spend
The forecast outlines how generative‑AI, short‑form video and evolving ad formats will reshape the digital economy by 2026. It argues that AI‑driven applications will move from a niche category to a core revenue engine, rivaling traditional paid‑media traffic and reshaping user‑acquisition dynamics across mobile, web and gaming. The analysis draws on Sensor Tower’s app‑store, advertising and web‑traffic datasets, applying its App IQ and Game IQ taxonomies to the top publishers, the 1,000 most‑visited U.S. sites and the leading Steam releases, with historical data through December 2025 and forward projections to 2026.
Generative‑AI apps are projected to generate more than $10 billion in worldwide in‑app‑purchase revenue, achieve 7.2 billion downloads and capture 43 billion hours of usage in 2026—an 82 % year‑over‑year increase that will place the genre among the top five for downloads, revenue and engagement. Short‑drama vertical video is forecast to overtake traditional OTT streaming in download volume, securing roughly 80 % of downloads and closing the IAP gap to 20 % of OTT’s share, driven by rapid adoption in markets such as India, Indonesia and Brazil. Meanwhile, U.S. digital ad spend will total $20 billion, with image‑based creatives outpacing video growth (35 % versus 15 % YoY) as social platforms, especially Meta’s Reels, shift budgets toward static formats.
On the web, generative‑AI traffic will surpass paid sources on more than half of the top 1,000 U.S. sites by the end of 2026, up from 37 % in late 2025,
- Generative AI apps will become a top-five category by 2026, generating over $10 billion in IAP revenue, 7.2 billion downloads, and 43 billion hours of usage, representing an 82% year-over-year growth.
- By the end of 2026, generative AI traffic will surpass paid sources on more than 50% of the top 1,000 U.S. websites, up from 37% in late 2025.
- Short-drama vertical video is projected to overtake traditional OTT streaming in download volume, capturing roughly 80% of total downloads with rapid adoption in India, Indonesia, and Brazil.
- U.S. digital ad spend will reach $20 billion in 2026, with image-based creatives growing at 35% year-over-year, significantly outpacing the 15% growth rate of video formats.
- Social platforms, specifically Meta’s Reels, are shifting advertising budgets away from video toward static, image-based formats.
2025 Report on Marketing Trends of Productivity Apps
The report analyzes global marketing activity for productivity apps during the first half of 2025, drawing on a dataset of over 1.6 billion ad creatives from more than 80 channels across 80+ countries. It shows that the total pool of mobile app (non‑game) advertisers fell 17.8 % YoY to an average of 107 k per month, while new advertiser share rose to 11.7 %. In the productivity‑app segment, active advertisers declined 6 % YoY to about 8.9 k per month, yet the proportion of new entrants exceeded 30 % after Q2. Regional analysis indicates Europe and North America remain the largest markets, but both experienced declines in advertiser counts; Oceania shows the highest creatives per advertiser. Category‑level data reveal business & office apps hold 14.4 % of advertisers, whereas entertainment apps dominate creative volume at 32.7 %. Platform performance data highlight Meta, Google, and TikTok as the top three channels for cross‑platform campaigns; Google delivers the highest conversion rates, Meta offers AI‑enhanced targeting, and TikTok provides cost‑efficient Gen Z engagement with a CPM of $3.2. Creative format insights show video and playable ads outperform static creatives, with TikTok favoring short native videos (15–60 s) and Meta using a mix of carousel and video. The report recommends a cross‑platform strategy that prioritizes video and playable formats, leverages AI for rapid creative iteration, and tailors messaging to include social proof, urgency, and lifestyle integration. The data were collected from January to June 2025 through sampling of global ad channels, with statistical forecasting and industry interviews used for analysis.
- The productivity app sector saw a 6% year-over-year decline in active advertisers to 8.9k per month, though new entrants surged to over 30% of the market share following Q2 2025.
- Meta, Google, and TikTok remain the primary channels for cross-platform campaigns, with Google leading in conversion rates and TikTok offering cost-efficient Gen Z engagement at a $3.2 CPM.
- Video and playable ads consistently outperform static creatives, with TikTok favoring 15–60 second native videos and Meta utilizing a combination of carousel and video formats.
- While business and office apps account for 14.4% of productivity advertisers, entertainment apps dominate the broader market creative volume at 32.7%.
- The total pool of non-game mobile app advertisers dropped 17.8% year-over-year to 107k per month, despite a 11.7% increase in the share of new advertisers.
H1 2025 AIGC Mobile App Marketing Analysis
The analysis demonstrates that while the global pool of active AI‑advertisers has contracted by 35–45 % in H1 2025, the remaining players are compensating with a markedly higher creative output—an 84 % increase to an average of 416 monthly creatives per advertiser. Video advertising dominates the landscape, with 84 % of all ads and more than half of inventory in 15‑30 second formats. Geographic patterns reveal that Europe and North America maintain the largest advertiser volumes, yet exhibit lower creative density than Japan and South Korea, which show the fastest growth rates. Market saturation appears to be driving these firms toward intensified brand exposure through increased creative frequency, even as overall advertiser participation declines.
Meitu’s financial results corroborate the commercial potency of AI‑driven features. Revenue rose 12.3 % to RMB 1.8 billion, largely propelled by a 45.2 % jump in AI‑powered imaging and design subscriptions to RMB 1.35 billion, while advertising income grew modestly by 5 %. The company’s flagship AI applications—“AI Wardrobe,” “WHEE,” and “Wink”—secured top positions in App Store charts across more than twelve countries, underscoring the role of AI enhancements in global user acquisition and subscription monetization.
The broader ecosystem of AI‑powered mobile apps, including chatbots, development tools, and educational platforms, continues to enjoy strong monthly active user figures and high stickiness. However, product overlap creates fierce competition, making clear positioning and precise subscription pricing essential for successful global expansion. Rapid overseas success is achievable when apps tailor local marketing strategies to regional preferences. These conclusions are drawn from SocialPeta’s extensive dataset of 1.6 billion advertising data points, sampled across 80+ channels and regions from January 2024 to June 2025.
- The number of active AI-advertisers in the mobile market contracted by 35–45% in H1 2025, while the remaining players increased their creative output by 84% to an average of 416 monthly creatives per advertiser.
- Meitu’s revenue grew 12.3% to RMB 1.8 billion in H1 2025, driven primarily by a 45.2% surge in AI-powered imaging and design subscriptions, which reached RMB 1.35 billion.
- Video advertising currently dominates the AI mobile landscape, accounting for 84% of all ads, with over half of inventory utilizing 15–30 second formats.
- Japan and South Korea are experiencing the fastest growth in creative density for AI-advertisers, outpacing the larger but less dense markets of Europe and North America.
- Meitu’s flagship AI applications—AI Wardrobe, WHEE, and Wink—achieved top-tier App Store rankings in over twelve countries, demonstrating the effectiveness of AI features in global user acquisition.
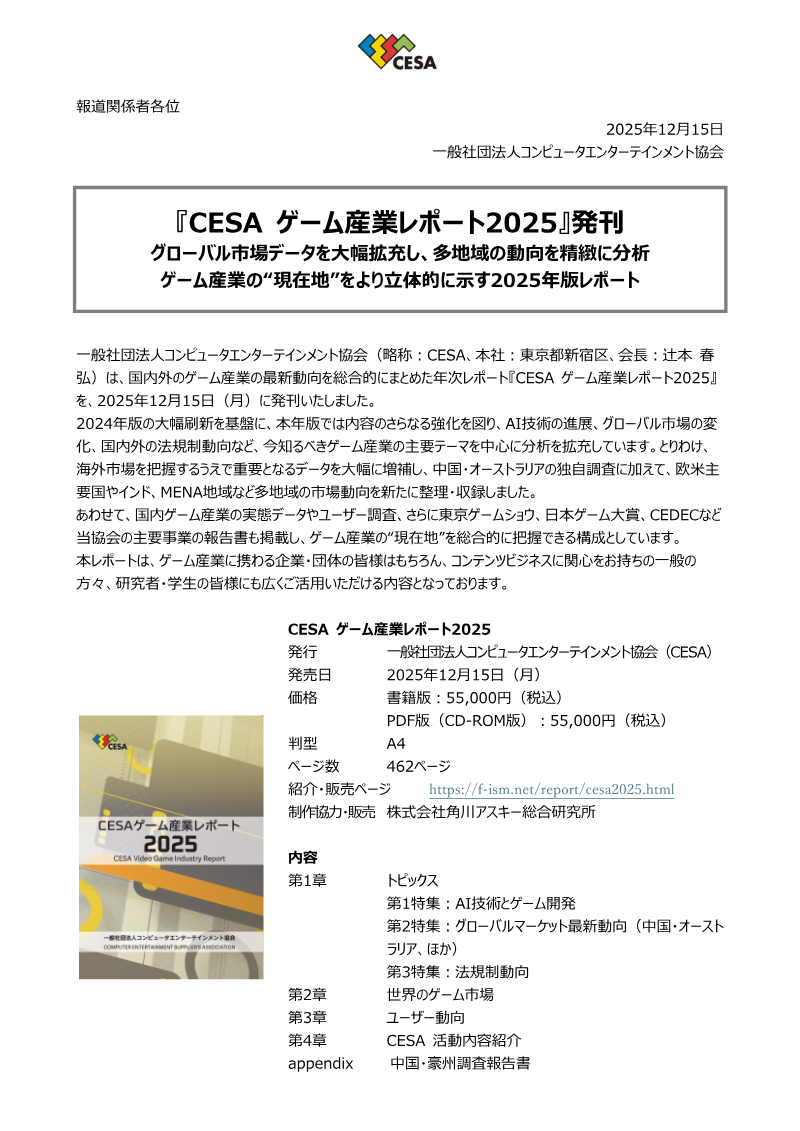
CESA Game Industry Report 2025
The 2025 CESA Game Industry Report presents a comprehensive assessment of the current state of the video‑game sector, emphasizing three strategic themes: the impact of artificial‑intelligence technologies on development, the latest dynamics of the global market, and emerging regulatory issues. By expanding data coverage to include China, Australia, major Western economies, India and the MENA region, the analysis offers a multidimensional view of both domestic and international trends.
Global game‑content revenue reached 31.042 trillion yen in 2024, marking a 5.0 % year‑on‑year increase. Mobile games accounted for 18.433 trillion yen, roughly 60 % of total sales, and grew 6.0 % versus the prior year. PC titles posted the strongest platform growth over the past four years, expanding 59.7 % and overtaking console share, while console revenue showed modest contraction. In Japan, the total gaming population stood at 5.475 million in 2024, a slight decline from 5.553 million; mobile users fell 1.8 %, PC users rose 0.5 %, and console users decreased 0.7 %, with expectations of a rebound following the anticipated Switch 2 launch.
Employment estimates indicate approximately 200 000 individuals work across the Japanese gaming ecosystem. Core developers, publishers and hardware manufacturers employ between 58 000 and 83 000 people, while ancillary sectors—such as visual production, middleware, peripherals, retail and media—constitute the remainder of the workforce.
The findings derive from CESA’s own surveys, expert interviews and user studies conducted in China and Australia, supplemented by industry‑wide data sources and event reports (Tokyo Game Show, Japan Game Awards, CEDEC). The methodology blends desk research with primary fieldwork to deliver a layered, data‑rich portrait of the industry’s structure, growth drivers and regulatory landscape.
- Global game content revenue reached 31.042 trillion yen in 2024, representing a 5.0% year-on-year increase.
- Mobile gaming remains the dominant sector, generating 18.433 trillion yen—roughly 60% of total global sales—with a 6.0% annual growth rate.
- PC gaming has experienced significant momentum, expanding 59.7% over the last four years to overtake console market share.
- Console revenue saw a modest contraction in 2024, though the Japanese market anticipates a rebound following the expected launch of the Switch 2.
- The Japanese gaming population experienced a slight decline to 5.475 million users in 2024, driven by a 1.8% drop in mobile users and a 0.7% decrease in console users.
2025 Media & Entertainment Industry Predictions Report
The analysis projects that artificial intelligence will be the primary catalyst for change across the media and entertainment landscape in 2025, enhancing human talent rather than replacing it. Streaming services continue to dominate revenue streams, with global SVOD and AVOD income projected to surpass $165 billion despite a fragmented market of over 200 platforms. Consumer churn and escalating content costs drive consolidation, leading to bundled or aggregated subscription models that are expected to account for 60–70 % of purchases in mature markets. Traditional multichannel pay‑TV providers are forecast to lose half their U.S. subscriber base, falling below 50 million users, prompting a shift toward “stream‑hub” offerings that combine broadband with multiple streaming services at competitive prices. Video multichannel distributors such as YouTube TV are projected to peak and then decline due to rising costs, live‑sports migration to direct‑to‑consumer services, and intensified OTT competition.
Cloud gaming is set for a 44 % CAGR through 2030, driven by faster broadband, AI‑enhanced virtualization, and new commercial models. Console and PC sales are expected to wane as consumers redirect spending toward streaming devices, with subscription‑based monetization replacing one‑time purchases. The sector’s growth hinges on resolving commercial model constraints, particularly the need for more attractive storefront incentives to unlock mass adoption and realize a $64 billion market by 2030.
In creative media, firms will increasingly deploy proprietary large‑language models while navigating intellectual property risks and regulatory frameworks such as the EU AI Act. Eight core governance building blocks—risk management, training oversight, compliance, testing, and incident response—are identified as essential for mitigating AI‑related challenges. Retail media and search are undergoing rapid transformation, with retailers partnering with streaming and social platforms to manage fragmented ecosystems, privacy rules, and AI‑driven formats. Generative AI is eroding Google’s dominance by enabling conversational, multimodal search experiences from competitors like OpenAI, Perplexity, Amazon, and TikTok. Consequently, Google’s share of search advertising is projected to decline modestly worldwide (from 57 % to 55 %) and in the U.S. (51 % to 48 %), as shoppable content, live shopping, and AI query volume shift revenue toward alternative platforms. Marketers will adapt by optimizing for AI‑generated summaries, voice, and visual search to align with evolving consumer behavior.
- Global SVOD and AVOD revenue is projected to exceed $165 billion in 2025, with 60–70% of subscriptions in mature markets expected to shift toward bundled or aggregated models to combat churn.
- Traditional U.S. pay-TV providers are forecast to lose half their subscriber base, dropping below 50 million users as the industry pivots to 'stream-hub' models that bundle broadband with multiple streaming services.
- Cloud gaming is projected to grow at a 44% CAGR through 2030, reaching a $64 billion market as subscription-based monetization increasingly replaces traditional one-time hardware purchases.
- Google’s global search advertising market share is expected to decline from 57% to 55% by 2025, as conversational AI competitors like OpenAI, Perplexity, and TikTok capture revenue through multimodal and shoppable search formats.
- Artificial intelligence will serve as a primary industry catalyst in 2025, with firms required to implement eight core governance building blocks—including risk management and compliance—to navigate IP and regulatory challenges like the EU AI Act.
Esports is Shaping the Future of Live Entertainment
Esports is rapidly evolving into a mainstream live‑entertainment sector, with viewership surpassing 100 million hours and prize pools doubling since 2018. The industry’s growth outpaces traditional sports, registering a 10 % year‑over‑year increase while leagues such as the NFL and NBA stagnate. Core titles—League of Legends, CS:GO, Mobile Legends: Bang Bang, Dota 2 and Valorant—concentrate 70 % of total viewing hours, yet an estimated $2.5 billion in untapped gamer audiences remains available, underscoring significant scalability potential.
Geographically, governments across France, Denmark, China and Japan are investing in infrastructure, tax incentives and athlete support, while the International Esports Federation seeks Olympic recognition. Sponsorship penetration has reached 45 % of non‑gaming brands, and universities now offer esports scholarships, indicating a blending of traditional sports support structures with the unique dynamics of game publishers. However, media‑rights monetisation remains constrained by fragmented licensing arrangements.
The absence of a unified regulatory body creates volatility for players; games and prize pools can collapse abruptly, as seen with Fortnite and Heroes of the Storm. Coordinated regulation, career pathways, post‑career support and state investment are identified as essential for legitimising esports as a sustainable profession. In sum, the sector demonstrates explosive growth and high engagement among younger, tech‑savvy audiences, but requires cohesive governance and media‑rights frameworks to unlock its full economic potential.
- Esports is outperforming traditional sports with a 10% year-over-year growth rate, while viewership has surpassed 100 million hours and prize pools have doubled since 2018.
- Five core titles—League of Legends, CS:GO, Mobile Legends: Bang Bang, Dota 2, and Valorant—account for 70% of total viewing hours, yet $2.5 billion in gamer audiences remains untapped.
- Non-gaming brand sponsorship has reached 45% penetration, supported by emerging institutional structures like university scholarships and government investments in infrastructure and tax incentives.
- The lack of a unified regulatory body and fragmented media-rights licensing remain the primary barriers to long-term economic stability and monetization.
- The industry faces significant volatility, as evidenced by the abrupt collapse of prize pools and professional ecosystems for titles like Fortnite and Heroes of the Storm.
The Power of Play: Exploring the Growing Gaming Market
The Indian gaming market is projected to reach ₹8.6 billion by 2027, expanding at a 28 % CAGR from FY20‑23, while the global market is expected to hit $340 billion. A recent 28 % GST on total deposits—up from an 18 % tax on gross gaming revenue—has pressured real‑money gaming (RMG) firms to diversify geographically, slowed revenue growth, and triggered layoffs. These developments have spurred calls for tax reforms that align with international standards. Despite the fiscal headwinds, segments such as esports, indie studios, and mobile casual games continue to grow, with blockchain, AR/VR, and generative AI identified as high‑growth opportunities.
Indian online gaming firms are responding to the GST amendment and broader market dynamics by absorbing or passing on tax costs, consolidating through acquisitions, and diversifying into new genres such as hyper‑casual games and esports. RMG now accounts for approximately 82 % of India’s gaming revenue, yet monetization remains weak relative to download volumes; only 10 % of global gaming funding reaches Indian startups. These strategic shifts aim to improve unit economics and capture higher‑spending segments.
Investment activity underscores the sector’s resilience. Casual mobile games remain the most attractive category, with recent Indian titles raising between $1 M and $8.5 M in seed to Series A rounds, while blockchain‑based mobile titles have attracted a combined $396 M. The next three to four years are expected to be driven by AR/VR integration, generative AI, competitive multiplayer mobile titles, and blockchain‑enabled gameplay. Major venture funds—including Accel, Sequoia, and Lightspeed—are actively backing the full value chain, reflecting strong institutional confidence in the industry’s expansion.
- The Indian gaming market is projected to reach ₹8.6 billion by 2027, growing at a 28% CAGR, while the global market is expected to hit $340 billion.
- A shift to a 28% GST on total deposits has pressured real-money gaming (RMG) firms, leading to layoffs, revenue slowdowns, and a strategic push toward geographic and genre diversification.
- RMG currently dominates the Indian market, accounting for approximately 82% of total gaming revenue, though monetization remains low relative to total download volumes.
- Blockchain-based mobile titles have secured $396 million in funding, while casual mobile games continue to attract seed to Series A rounds between $1 million and $8.5 million.
- Institutional confidence remains high, with major venture funds including Accel, Sequoia, and Lightspeed actively investing across the gaming value chain.
Leveling Up for the New Reality: The Gaming Report
The report examines the global gaming market’s evolution from 2017 to 2028, highlighting a post‑pandemic correction that has shifted growth expectations from double‑digit rates to modest expansion. Global revenue by type rose 1 % CAGR (2017–2023), with mobile, PC, and console segments contributing $1.2 trillion in 2023; cloud/VR sales remain niche but are projected to grow at 5 % CAGR (2023–2028). Emerging platforms such as cloud AR/VR and user‑generated content show market sizes of $939 million (2024) to $1.75 billion (2028), yet infrastructure constraints limit mass adoption.
Development economics reveal a widening gap: AAA development budgets increased 360 % (2012–2023 average) while sales and marketing costs rose 220 %, yet the number of AAA titles released fell by 73 %. Mobile publishers mirror this trend, with development costs up 54–92 % and releases declining. Console revenues are projected to outpace AAA budgets, with a 5 % CAGR in development spending versus 8 % in console revenue growth (2017–2028). Survey data indicate that most publishers expect to maintain or modestly increase budgets, with only 5–10 % planning reductions.
Monetization shifts are pronounced in consoles: subscription services and premium digital sales will dominate, while mobile revenue increasingly relies on in‑app advertising (up to 31 % of mobile share). Consumer willingness to accept ads varies by platform, with over half of core PC/console gamers open to advertising in premium titles. Geographic analysis shows Chinese players exhibit the highest willingness to pay, and emerging‑economy gamers spend more time playing than their developed‑economy counterparts. Age segmentation reveals younger cohorts favor action/adventure, whereas older players gravitate toward puzzles and casual games. The report concludes that technological advances, particularly generative AI, may enable cost efficiencies but will likely be leveraged to fund larger, higher‑quality titles rather than reduce overall budgets.
- AAA development budgets surged 360% between 2012 and 2023, while the volume of AAA title releases dropped by 73%, signaling a shift toward fewer, more expensive productions.
- Global gaming revenue grew at a 1% CAGR from 2017 to 2023, reflecting a post-pandemic correction that has moved the industry from double-digit growth to modest expansion.
- Mobile revenue is increasingly driven by in-app advertising, which now accounts for up to 31% of the segment's total share.
- While cloud and VR remain niche, they are projected to grow at a 5% CAGR through 2028, with emerging platforms like cloud AR/VR and user-generated content expected to reach $1.75 billion in market size by 2028.
- Console revenue is projected to grow at an 8% CAGR through 2028, outpacing the 5% CAGR in development spending for the same period.
Predictions for the Digital Economy in 2026
The analysis projects a rapid expansion of the digital economy through 2026, driven primarily by generative AI applications and vertical video formats. Generative‑AI apps are expected to generate more than $10 billion in in‑app purchase revenue by 2026, with downloads projected to reach 4 billion and user engagement exceeding 43 billion hours. The genre will climb into the top five mobile categories across downloads, revenue, and time spent, surpassing established sectors such as shopping and movies. Short‑drama vertical video is forecast to overtake traditional OTT streaming in global downloads, narrowing the revenue gap and capturing 40 % of time spent by 2026.
Digital advertising spending is shifting back toward image‑based creatives, with a 35 % year‑over‑year increase in image ad spend and a projected acceleration of this trend by 2026, especially within social channels where Reels and similar formats dominate. Meanwhile, generative AI traffic to the top 1,000 U.S. websites is projected to rise by more than 130 % YoY, reaching a point where half of these sites receive higher traffic from AI than paid sources by the end of 2026.
Mobile game acquisition costs remain high, and the market is trending toward smaller, ad‑native titles that can monetize efficiently. Steam releases are accelerating, with 2025 already breaking records for new titles, indicating a shift toward faster, lower‑budget development cycles. Overall, the report underscores a digital landscape increasingly shaped by AI‑driven content and streamlined monetization models across mobile, web, and gaming sectors.
- Generative AI applications are projected to reach $10 billion in in-app purchase revenue, 4 billion downloads, and 43 billion hours of user engagement by 2026, becoming a top-five mobile category.
- Short-drama vertical video is forecast to surpass traditional OTT streaming in global downloads and capture 40% of total user time spent by 2026.
- By the end of 2026, half of the top 1,000 U.S. websites are expected to receive more traffic from generative AI than from paid sources, with AI-related traffic rising over 130% year-over-year.
- Digital advertising is shifting back toward image-based creatives, evidenced by a 35% year-over-year increase in image ad spend that is expected to accelerate through 2026.
- The gaming market is trending toward smaller, ad-native mobile titles to combat high acquisition costs, while Steam is seeing record-breaking release volumes driven by faster, lower-budget development cycles.
Square Enix Next: That Excitement Once Again
Square Enix’s recent performance review exposes a persistent decline in revenue growth and profitability over the past three years, with operating income falling 32 % and ROE dropping 61 %. The downturn is driven primarily by weak margins in both high‑definition (HD) and small‑dungeon (SD) game segments, excessive portfolio fragmentation, sub‑optimal product design and promotion, and escalating development costs. While the MMO licensing arm remains the sole growth driver (+11 %), overall gaming revenue has slipped, with HD and SD titles declining 4 % and 5 % respectively. Operating margins for these segments hover around 35–40 %, noticeably higher than the industry average of 28 % but still lagging behind competitors, indicating inefficiencies that are not being adequately addressed.
The company’s medium‑term “Reboots” plan offers only high‑level directions without concrete key performance indicators or quantitative targets. Critical gaps include a lack of clear business‑portfolio strategy, insufficient disclosure on non‑core business rationales, and no defined mechanisms for monitoring progress or maximizing shareholder value. Capital allocation disclosures are similarly weak: cost‑of‑capital calculations, ROE and ROIC targets, and hurdle rates are absent, while share‑buyback authorization remains unused despite a sharp price decline. SG&A costs exceed peer norms by 5–6 ppt, driven largely by an oversized sales force, further eroding profit margins.
Geographically, SD game revenue is almost entirely domestic; the Japanese market has contracted 2 % annually since 2020, and overseas growth remains only 3 %. The company’s global SD strategy is inert, with a 7 % overseas expansion rate falling short of projected growth and flagship titles such as FFVII Ever Crisis deriving 70 % of revenue from Japan. Non‑core Amusement and Publishing businesses are undervalued, with a significant conglomerate discount relative to peers and declining sales and margins. Limited cross‑synergy between game and publishing arms further hampers value creation.
In summary, Square Enix faces a multifaceted challenge: declining core game performance, weak strategic direction and KPI setting, high SG&A costs, and an underperforming non‑core portfolio. Addressing these issues through tighter cost control, clearer performance metrics, aggressive overseas expansion, and potential portfolio optimization is essential to restore corporate value and achieve sustainable growth.
- Square Enix has experienced a significant financial decline over the past three years, marked by a 32% drop in operating income and a 61% decrease in return on equity (ROE).
- Core gaming segments are underperforming, with HD and SD game revenues falling 4% and 5% respectively, while MMO licensing remains the only growth driver at +11%.
- Operating margins for HD and SD segments remain inefficient at 35–40%, and SG&A costs exceed industry norms by 5–6 percentage points due to an oversized sales force.
- The company's 'Reboots' medium-term plan lacks concrete KPIs, quantitative targets, and clear capital allocation strategies, such as defined hurdle rates or ROIC goals.
- Square Enix’s SD game revenue is heavily reliant on the contracting Japanese market, with flagship titles like 'FFVII Ever Crisis' generating 70% of their revenue domestically.
Video Gaming Report 2026: How Platforms Are Colliding and Why This Will Spark the Next Era of Growth
The global video game industry is currently transitioning from a post-pandemic period of stagnation toward a new era of growth defined by the convergence of hardware-agnostic ecosystems and decentralized distribution. The primary thesis posits that the industry is evolving into a collection of independent, platform-agnostic environments where traditional barriers—such as closed app store models—are being dismantled in favor of direct-to-consumer web stores and alternative distribution channels. This shift is designed to improve developer margins and provide greater control over monetization strategies, including tiered pricing and subscription models, to better serve a price-sensitive global player base.
Technological and creative innovation serves as the catalyst for this transformation, with Generative AI accelerating development cycles and the expansion of user-generated content (UGC) fostering deeper intergenerational engagement. Cloud gaming is projected to become a cornerstone of this evolution, with revenues expected to reach $18.3 billion by 2030. These advancements, while promising, necessitate a strategic pivot toward robust content curation and the resolution of complex intellectual property challenges. As games increasingly function as community-driven platforms, stakeholders must prioritize engagement over legacy hardware dependencies to remain competitive.
A significant opportunity for expansion lies in the correction of a persistent monetization imbalance. Although gaming commands 12.5% of total media consumption time, it currently captures only 3% of global advertising spend. By integrating sophisticated advertising models alongside AI-driven development and UGC, the industry is positioned to capture this latent value. Ultimately, the future of the sector depends on the successful navigation of market saturation through strategic windowing and the adoption of flexible, multiplatform ecosystems that prioritize community-led discovery and long-term player retention.
- The industry is shifting toward platform-agnostic ecosystems and direct-to-consumer distribution to bypass traditional app store fees and improve developer margins.
- Gaming currently accounts for 12.5% of global media consumption time but captures only 3% of total advertising spend, representing a significant opportunity for revenue growth.
- Cloud gaming is projected to reach $18.3 billion in revenue by 2030, serving as a critical infrastructure component for the industry's transition.
- Generative AI and user-generated content are being leveraged to accelerate development cycles and drive deeper intergenerational player engagement.
- Future competitiveness depends on moving away from legacy hardware dependencies toward community-driven platforms that prioritize long-term retention.