Global
Documents
Cross-Platform Gaming: Bridging Mobile and PC/Console 2025
The global gaming landscape in 2025 is defined by a strategic synergy between the accessibility of mobile platforms and the immersive depth of PC and console ecosystems. Mobile serves as the primary engine for discovery and user acquisition, generating over 52 billion annual downloads and $82 billion in in-app purchase revenue. Meanwhile, PC and console platforms, led by storefronts like Steam, anchor brand loyalty and drive high-value engagement through seasonal peaks and premium content. By leveraging mobile’s massive reach to feed into high-fidelity ecosystems, publishers maximize total franchise growth and ensure long-term revenue stability.
Publishers are increasingly bridging these distinct markets through four primary models: companion apps, "lite" versions for mass-market discovery, adapted experiences, and full cross-platform progression. Success stories such as the EA SPORTS FC companion app, which reached 78 million downloads, demonstrate how mobile accessibility sustains franchise loyalty. Furthermore, titles like PUBG Mobile and Delta Force illustrate that mobile engagement frequently drives corresponding spikes in PC player activity. This interconnectedness is particularly effective for RPGs and Shooters, which utilize unified ecosystems and shared progression to significantly increase player lifetime value and retention.
Ultimately, a successful cross-platform strategy balances high-volume mobile genres, such as Simulation and Puzzle, with the prestige and monetization intensity of blockbuster PC and console releases. Adapting complex intellectual properties into accessible mobile formats allows franchises to capitalize on broader cultural trends, as seen with the resurgence of the Fallout brand. By treating mobile as a discovery engine and PC/console as the anchor for brand identity, publishers can effectively navigate the global market to capture both broad audiences and high-spending core players.
- Mobile platforms function as the primary discovery engine for the gaming industry, generating over 52 billion annual downloads and $82 billion in in-app purchase revenue.
- Publishers maximize franchise growth by using mobile to feed into high-fidelity PC and console ecosystems, which anchor brand loyalty and drive high-value engagement.
- Cross-platform progression and unified ecosystems are most effective for RPG and Shooter titles, significantly increasing player lifetime value and retention.
- Companion apps are a proven strategy for sustaining franchise loyalty, evidenced by the EA SPORTS FC companion app reaching 78 million downloads.
- Mobile engagement frequently correlates with increased player activity on PC, as demonstrated by titles like PUBG Mobile and Delta Force.
Digital Market Index: Q3 2025
Global mobile app consumer spending reached a record $43.2 billion in the third quarter of 2025, representing an 11.3% year-over-year increase. This growth was primarily fueled by a 20% surge in non-game revenue, particularly from Generative AI tools which generated $1.5 billion during the period. While total global downloads remained stable at 37.6 billion, a clear divergence emerged between sectors; non-game downloads grew by 5.5%, while gaming installs continued a post-pandemic decline. Geographically, the United States maintained its market leadership with $15 billion in revenue, though Brazil emerged as the fastest-growing major market with a 29% revenue increase. India simultaneously reached a two-year high in downloads, surpassing 6.5 billion.
The digital advertising landscape saw significant expansion, with U.S. spend rising 12% to $35.9 billion. Social media remains the dominant channel, capturing 72% of the market, but mobile app advertising is the fastest-growing segment at 42% year-over-year. Within specific industries, the gaming sector entered the top five spending categories for the first time following a 28% increase in investment. Strategic shifts were also evident in the insurance and consumer goods sectors, where companies like Geico and Procter & Gamble executed massive quarterly spending spikes to capitalize on premium fluctuations and seasonal demand.
Retail media has become a critical pillar of the digital economy, dominated heavily by Amazon. Generating over 80 billion impressions, Amazon’s reach surpassed the combined total of the next thirty major retailers. Outside of Amazon's ecosystem, retail media impressions grew 7% year-over-year, though performance was inconsistent across platforms; Target and Best Buy saw double-digit growth while Walmart experienced a decline. Personal care remains the most competitive retail category, driven by high-volume co-branded partnerships between major manufacturers and established retail platforms.
- Global mobile app consumer spending reached a record $43.2 billion in Q3 2025, an 11.3% year-over-year increase driven by a 20% surge in non-game revenue.
- Generative AI tools emerged as a significant revenue driver, contributing $1.5 billion to the mobile app market during the third quarter.
- U.S. digital advertising spend rose 12% to $35.9 billion, with mobile app advertising identified as the fastest-growing segment at 42% year-over-year.
- Gaming sector investment in digital advertising grew by 28%, securing its position as a top-five spending category for the first time.
- Amazon dominates the retail media landscape with over 80 billion impressions, exceeding the combined total of the next thirty major retailers.
Digital Marketing Index Report: Q4 2025
The analysis evaluates global digital‑marketing dynamics for the final quarter of 2025, emphasizing shifts in channel performance, the rise of generative‑AI as a discovery source, and the concentration of retail‑media reach among dominant platforms. Growth patterns reveal a stark regional divide: India stands alone among the five largest markets as the only one posting positive overall change, while other leading economies recorded declines or stagnation.
In the United States, retail‑media impressions expanded 13 percent quarter‑over‑quarter to reach 123 billion, with Amazon accounting for the entire volume and delivering more than six times the impressions generated by Walmart. This concentration underscores Amazon’s expanding role as the primary conduit for retail‑media exposure in North America. Across the same period, generative‑AI referrals, although still representing less than one percent of total traffic, surged dramatically—up 133 percent year‑over‑year in the United States, United Kingdom and France, and 126 percent in Canada. The rapid acceleration signals that chat‑based assistants such as ChatGPT, Claude and Gemini are emerging as significant discovery engines despite their modest share of overall visits.
Conversely, traditional organic search experienced the only decline among major acquisition channels, falling four percent year‑over‑year. Paid advertising, email marketing and other performance‑driven tactics continued to post gains, reinforcing a broader transition toward paid and AI‑augmented pathways for user acquisition. The findings collectively illustrate a digital‑marketing ecosystem increasingly dominated by platform‑centric retail media and AI‑driven referral mechanisms, while legacy search channels lose ground in mature markets.
- India was the only major global market to record positive overall digital marketing growth in Q4 2025, while other leading economies experienced stagnation or decline.
- Generative AI referrals surged by 133% year-over-year in the US, UK, and France, signaling their emergence as significant discovery engines despite currently accounting for less than 1% of total traffic.
- US retail-media impressions grew 13% quarter-over-quarter to 123 billion, with Amazon capturing the entire volume and delivering six times the impressions of Walmart.
- Traditional organic search was the only major acquisition channel to decline in Q4 2025, falling 4% year-over-year.
- Digital marketing strategies are shifting toward paid advertising and AI-augmented pathways as legacy search channels lose market share in mature economies.
Video Game Market Update: Q3 2025
The global video game industry experienced a notable resurgence in growth during the third quarter of 2025, driven by a rebound in mobile in-app purchases and robust performance across PC and console platforms. The launch of the Nintendo Switch 2 served as a primary catalyst for console sector strength, reinforcing the enduring value of established intellectual property. While the broader capital markets faced significant headwinds, characterized by multi-year lows in public fundraising and subdued early-stage venture activity, the industry’s transaction landscape was defined by high-value consolidation. The $55 billion public takeover of Electronic Arts stands as the definitive event of the period, signaling a strategic shift toward large-scale mergers and acquisitions as the primary mechanism for growth.
Market dynamics currently favor established entities, with diversified publishers and PC and console developers commanding significant valuation premiums due to their proven profitability and market stability. This environment has concentrated investment power among a select group of firms. BITKRAFT emerged as the most active participant in the early-stage ecosystem over the past twelve months, leading the sector with 16 deals totaling $113 million. Alongside other prominent investors like Bessemer Venture Partners and Menlo Ventures, these firms continue to deploy capital despite the broader contraction in private investment.
Ultimately, the industry is transitioning into a phase of maturity where scale and intellectual property ownership are paramount. While early-stage funding remains constrained, the surge in total transaction value through megadeals indicates that institutional confidence remains high for proven assets. The current landscape suggests a bifurcated market where high-growth, established publishers attract significant capital, while smaller, early-stage ventures face a more challenging environment for securing liquidity and growth funding.
- The $55 billion public takeover of Electronic Arts highlights a strategic shift toward large-scale consolidation as the primary driver of industry growth in Q3 2025.
- The launch of the Nintendo Switch 2 acted as a major catalyst for console sector strength, reinforcing the market value of established intellectual property.
- The global video game industry saw a Q3 2025 resurgence fueled by a rebound in mobile in-app purchases and strong performance across PC and console platforms.
- BITKRAFT led the early-stage investment ecosystem over the past twelve months with 16 deals totaling $113 million, despite a broader contraction in private venture activity.
- The market is currently bifurcated, with diversified publishers and established developers commanding valuation premiums while smaller, early-stage ventures face significant liquidity and funding challenges.
2025 Global Games Market Report
The global games market is entering a period of moderate maturation, with total revenue projected to reach $188.8 billion in 2025, a 3.4% increase over the previous year. The industry now serves 3.6 billion players, reflecting a 4.4% year-over-year expansion. While mobile gaming maintains its dominance, accounting for $103.0 billion or 55% of total revenue, console gaming is poised for the strongest growth at 5.5%, reaching $45.9 billion. PC gaming remains a stable pillar with $39.9 billion in revenue. Despite the growth in player counts, average spend per payer is experiencing a slight decline, signaling a strategic pivot toward maximizing engagement and retention within saturated markets rather than relying solely on aggressive monetization.
Strategic success in this environment increasingly depends on long-tail engagement and the effective management of post-launch content. Data indicates that releasing single-player titles during the second quarter yields 34% higher engagement compared to the saturated holiday season. Furthermore, simultaneous multi-platform launches significantly outperform staggered releases, and titles exiting Early Access after a six-month window demonstrate superior acquisition results. Developers are also increasingly leveraging remakes and remasters to mitigate rising development costs, while user-generated content platforms like Roblox continue to expand as foundational ecosystems for daily active users.
Geographically, the market continues to diversify, with Latin America emerging as a notable growth region projected to reach $8.3 billion, driven primarily by mobile adoption. The industry’s analytical framework, which focuses on consumer spending on software and services, highlights that player attrition typically stabilizes after 12 weeks. Consequently, long-term commercial viability is now inextricably linked to aligning content updates and discounting strategies with this post-launch retention curve, ensuring that community support remains as critical as initial sales performance.
- The global games market is projected to reach $188.8 billion in 2025, a 3.4% year-over-year increase, driven by a player base that has expanded to 3.6 billion people.
- Mobile gaming remains the industry leader with $103.0 billion in revenue (55% of the total), while console gaming is expected to see the highest growth rate at 5.5%, reaching $45.9 billion.
- Average spend per player is declining, forcing a strategic shift toward long-tail engagement and retention rather than aggressive monetization in saturated markets.
- Releasing single-player titles in the second quarter yields 34% higher engagement than holiday-season launches, and simultaneous multi-platform releases consistently outperform staggered strategies.
- Developers are increasingly utilizing remakes and remasters to offset rising production costs, while platforms like Roblox are becoming essential ecosystems for maintaining daily active users.
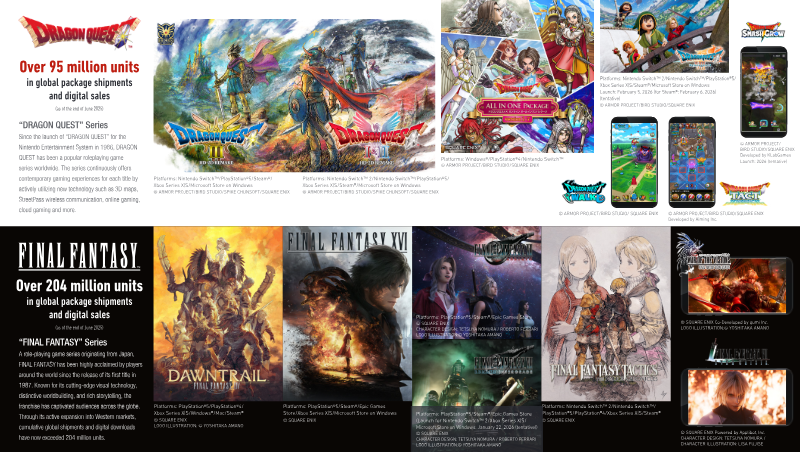
Square Enix Special Feature: Erdrick Trilogy Reimagined
The Dragon Quest franchise continues to expand its global footprint, reaching over 95 million units in total shipments and digital sales as of June 2025. A central focus of the current release strategy is the reimagining of the foundational Erdrick Trilogy through HD-2D remakes. Dragon Quest I & II HD-2D Remake is scheduled for a February 5, 2026, launch on a wide array of platforms, including the Nintendo Switch 2, PlayStation 5, Xbox Series X|S, and PC via Steam and the Microsoft Store. This multi-platform approach reflects a broader commitment to utilizing contemporary technology to modernize classic role-playing experiences for a global audience.
Beyond the core Dragon Quest series, the broader portfolio demonstrates significant market penetration across several flagship intellectual properties. The Final Fantasy franchise has surpassed 204 million units globally as of mid-2025, supported by the ongoing expansion of Final Fantasy XIV: Dawntrail and the continued rollout of Final Fantasy VII Rebirth across various ecosystems. Additionally, the Kingdom Hearts series, a collaborative effort with Disney, has achieved over 38 million units in sales, with new entries currently in development for unspecified launch windows.
The strategic roadmap emphasizes cross-platform accessibility and the revitalization of legacy content. By targeting next-generation hardware like the Nintendo Switch 2 alongside established consoles and PC storefronts, there is a clear intent to maximize reach across diverse geographic markets. This strategy is complemented by a robust pipeline of mobile and niche titles, including Dragon Quest Tact and various entries in the Bravely Default and Octopath Traveler series, ensuring a steady cadence of content across the role-playing game segment through 2026.
- The Dragon Quest I & II HD-2D Remake is scheduled for release on February 5, 2026, across Nintendo Switch 2, PlayStation 5, Xbox Series X|S, and PC.
- The Dragon Quest franchise has reached 95 million units in total shipments and digital sales as of June 2025.
- The Final Fantasy franchise has surpassed 204 million units globally as of mid-2025, driven by Final Fantasy XIV: Dawntrail and Final Fantasy VII Rebirth.
- Square Enix is prioritizing a cross-platform strategy that targets next-generation hardware alongside established consoles and PC storefronts to maximize global market reach.
- The Kingdom Hearts series has achieved over 38 million units in sales, with new entries currently in development.
Global Gaming Report Q3 2025
The third quarter of 2025 underscores the continued premium placed on hardware and platform players within the global gaming ecosystem, as investors assign a wide spectrum of valuation multiples that reflect divergent growth narratives and market positioning. Enterprise‑valued firms such as Dell and HP trade near a 1‑times EV/EBITDA ratio, indicating modest expectations for earnings expansion, while high‑growth entities like Nvidia and AppLovin command multiples exceeding 25‑times, with the latter reaching 42.8‑times, highlighting the market’s appetite for cutting‑edge processing power and mobile advertising integration. Across the board, most companies in the segment posted double‑digit year‑over‑year revenue increases, confirming robust demand for both traditional PC hardware and emerging cloud‑based gaming services.
Equity performance further illustrates the split between established hardware manufacturers and platform‑centric developers. Roblox delivered the strongest year‑to‑date appreciation at 136.9%, driven by expanding user engagement and monetization initiatives, while Unity recorded a 77‑percent gain, reflecting its pivotal role in cross‑platform development tools and the growing adoption of real‑time 3D content. These returns contrast sharply with the more muted trajectories of hardware‑only firms, suggesting that investors are rewarding firms that blend hardware capabilities with scalable software ecosystems.
Overall, the data portray a gaming market in which valuation is increasingly tied to the ability to integrate hardware performance with platform services, and where growth‑oriented companies enjoy markedly higher multiples and stock appreciation. The findings span a global landscape, covering major North American, European, and Asian players, and focus on the quarter ending September 2025, offering a snapshot of valuation dynamics and performance trends that are likely to shape strategic investment decisions throughout the remainder of the year.
- Investors are heavily favoring platform-centric companies over traditional hardware manufacturers, with high-growth firms like AppLovin and Nvidia commanding EV/EBITDA multiples exceeding 25x, compared to roughly 1x for legacy hardware firms like Dell and HP.
- Roblox led equity performance with a 136.9% year-to-date appreciation, driven by successful user engagement and monetization strategies.
- Unity recorded a 77% year-to-date gain, underscoring the market's high valuation of cross-platform development tools and real-time 3D content adoption.
- AppLovin reached a 42.8x EV/EBITDA multiple, reflecting strong market confidence in the integration of mobile advertising with gaming ecosystems.
- Most gaming companies reported double-digit year-over-year revenue growth in Q3 2025, confirming sustained demand across both PC hardware and cloud-based gaming services.
Digital Market Index: Q2 2025
The global digital landscape reached a significant milestone in the second quarter of 2025, as in-app purchase revenue hit a record $40 billion. This period marked a historic structural shift in the mobile economy, with non-gaming applications accounting for 52% of total consumer spending, surpassing mobile games for the first time. While total downloads stabilized at 37 billion, the market displayed clear signs of maturation; gaming downloads contracted by 6.8% year-over-year, while AI-driven productivity tools and short-drama streaming platforms emerged as the primary engines of growth. The United States maintained its position as the premier revenue market at $15 billion, though emerging regions such as Brazil and various African nations are increasingly vital for download volume and monetization expansion.
Within the gaming sector, Strategy titles overtook RPGs as the highest-grossing category, achieving a 23% year-over-year increase. However, the most significant individual performance came from ChatGPT, which became the fastest application to reach one billion downloads and secured a position among the top five global revenue earners. This surge in AI utility was mirrored in the advertising sector, where U.S. digital ad spend rose 12% to $34 billion. Major technology firms including Microsoft, Google, and Adobe significantly increased their marketing budgets to promote AI integrations like Copilot, contributing to a landscape where social media maintains a 72.5% share of total ad spend.
Retail media has solidified its role as a critical advertising channel, with U.S. impressions rising 29% to 65 billion across various retailers. Despite this broad growth, Amazon remains the undisputed leader in the space, generating nearly 80 billion impressions and outperforming all other tracked retailers combined. These findings are supported by expanded tracking capabilities across key Asian markets and diverse digital channels, though the data specifically excludes certain year-over-year Amazon metrics due to recent tracking implementation. Overall, the quarter reflects a pivot toward high-utility AI applications and a diversifying advertising ecosystem dominated by social and retail platforms.
- In Q2 2025, non-gaming applications surpassed mobile games for the first time, accounting for 52% of the record $40 billion in total in-app purchase revenue.
- Global mobile gaming downloads contracted by 6.8% year-over-year, while Strategy titles replaced RPGs as the highest-grossing gaming category with a 23% increase.
- ChatGPT became the fastest application to reach one billion downloads and secured a top-five position in global revenue, signaling a major shift toward AI-driven utility.
- U.S. digital ad spend rose 12% to $34 billion, driven by increased marketing budgets from firms like Microsoft, Google, and Adobe to promote AI integrations.
- Retail media continues to expand, with U.S. impressions rising 29% to 65 billion, though Amazon remains the dominant leader with nearly 80 billion impressions.
The State of PC Game Distribution
The study aims to map the contemporary PC game distribution ecosystem and evaluate whether Steam functions as a de‑facto monopoly, while outlining alternative channels, associated risks, and growth opportunities for developers and publishers. It positions Steam’s dominance against emerging storefronts, physical media, and gray‑market platforms, offering strategic guidance for navigating a fragmented market beyond 2025.
Steam’s market power is evident: 2024 revenue reached $10.8 billion and concurrent active users rose from 25.4 million in 2021 to 40.5 million by September 2025. Eighty‑eight percent of surveyed studios report that Steam delivers over 75 % of their revenue, with 37 % relying on it for more than 90 %. Consequently, 72 % of respondents view Steam as a monopoly and 53 % express concern over this reliance. Nonetheless, diversification is growing—48 % have launched titles on the Epic Games Store, a similar share on the Xbox PC store, while 10 % and 8 % have used GOG and itch.io respectively. Physical releases persist, with 32 % of developers still issuing boxed copies and 72 % of consumers indicating a continued appetite for them.
Alternative distribution via e‑stores (e.g., Humble, Fanatical) and marketplaces (e.g., G2A, Kinguin) is gaining traction: 38 % of developers sell through e‑stores and 30 % through marketplaces. Seventy‑five percent anticipate at least a 10 % revenue uplift from these channels, and 80 % expect them to become
- Steam maintains a dominant market position, generating $10.8 billion in 2024 revenue with concurrent users increasing from 25.4 million in 2021 to 40.5 million by September 2025.
- Developer reliance on Steam is extreme, with 88% of studios deriving over 75% of their revenue from the platform and 37% relying on it for more than 90%.
- Despite 72% of developers labeling Steam a monopoly, diversification is underway, with 48% of studios utilizing the Epic Games Store and the Xbox PC store for distribution.
- Alternative distribution channels are gaining significant traction, as 38% of developers now sell through e-stores like Humble or Fanatical, and 30% utilize marketplaces like G2A or Kinguin.
- Financial projections for alternative channels are optimistic, with 75% of developers anticipating at least a 10% revenue uplift and 80% expecting these platforms to become increasingly vital.
Mobile Game Feature Impact Spotlight
Sensor Tower introduces Game IQ Deep Tags, a taxonomy of 70 specialized markers designed to analyze the impact of specific mobile game features on market performance. These tags are categorized into gameplay, monetization, engagement, and social elements, providing developers with a framework to benchmark competitor roadmaps and identify high-value feature sets. The analysis covers the top 1,000 mobile games globally from Q2 2024 through Q1 2025, a segment representing 16 billion downloads and $67 billion in consumer spend.
The findings reveal that feature density does not always correlate with market dominance. In the casual puzzle genre, titans like Royal Match and Candy Crush Saga utilize fewer luxury features, such as voice acting or cinematic cutscenes, compared to competitors like Gardenscapes, suggesting that core gameplay often outweighs feature volume. Conversely, in the mid-core RPG and strategy sectors, comprehensive monetization and engagement systems are standard. For instance, Age of Empires Mobile demonstrates high revenue per download by utilizing nearly all available monetization tags, while top RPGs leverage IP collaborations and recurring task systems to maximize player retention and session length.
The research identifies significant growth opportunities in the hybridcasual segment, where features like in-app purchase (IAP) bundles remain underutilized despite correlating with a $1.77 increase in lifetime revenue per download. Additionally, portfolio analysis of top publishers like Tencent, Scopely, and King shows a universal prioritization of login systems to track player data, while specific mechanics like "monetized retries" remain niche to casual puzzle specialists. Ultimately, the data suggests that strategic feature implementation, rather than exhaustive adoption, is the primary driver of commercial success across different mobile gaming verticals.
- Strategic feature selection, rather than exhaustive feature adoption, is the primary driver of commercial success across the top 1,000 mobile games globally.
- In the hybridcasual segment, implementing in-app purchase (IAP) bundles correlates with a $1.77 increase in lifetime revenue per download.
- Casual puzzle leaders like Royal Match and Candy Crush Saga maintain market dominance with lower feature density, proving that core gameplay often outweighs the addition of luxury elements like cinematic cutscenes.
- Mid-core strategy titles, such as Age of Empires Mobile, maximize revenue per download by utilizing a comprehensive suite of monetization tags.
- Top publishers including Tencent, Scopely, and King universally prioritize login systems to track player data, while mechanics like 'monetized retries' remain niche to the casual puzzle genre.
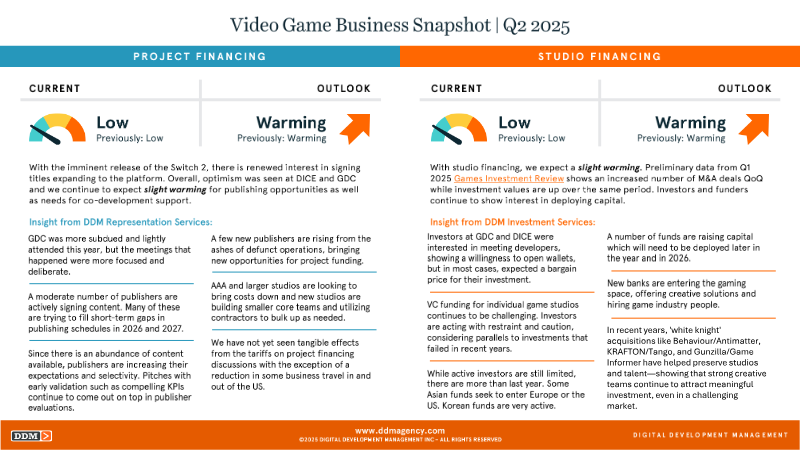
Video Game Business Snapshot: Q2 2025
The second quarter of 2025 highlights a strategic shift in the video game industry’s mergers and acquisitions landscape, characterized by a rise in rescue-style investments often referred to as white knight acquisitions. These transactions involve established global entities stepping in to acquire studios or media outlets that might otherwise face closure or significant downsizing. Notable examples include KRAFTON’s acquisition of Tango Gameworks, Behaviour Interactive’s absorption of Antimatter, and Gunzilla Games’ involvement with Game Informer. These moves suggest that despite broader economic volatility and a contraction in traditional venture capital, high-quality creative talent and established intellectual properties remain highly valuable assets for diversified gaming conglomerates.
The current market environment reflects a transition where strategic preservation is prioritized over speculative growth. Large-scale publishers are increasingly focused on securing proven development teams to bolster their long-term pipelines, viewing these acquisitions as opportunities to integrate specialized expertise at a time when independent sustainability is difficult. This trend underscores a broader industry sentiment that while the capital market remains challenging, the underlying value of experienced human capital continues to drive significant deal flow. These developments indicate that the industry is moving toward a more consolidated but stable structure, where the survival of key creative hubs is facilitated by the strategic interests of larger market players.
- Q2 2025 is defined by a surge in 'white knight' acquisitions, where major conglomerates are purchasing studios facing closure or downsizing to preserve creative talent and intellectual property.
- Notable rescue acquisitions this quarter include KRAFTON’s purchase of Tango Gameworks, Behaviour Interactive’s absorption of Antimatter, and Gunzilla Games’ involvement with Game Informer.
- The industry is shifting away from speculative growth toward strategic preservation, as large publishers prioritize securing proven development teams to stabilize long-term production pipelines.
- Despite a contraction in traditional venture capital and broader economic volatility, experienced human capital remains a high-value asset driving deal flow.
- The current market environment is trending toward a more consolidated industry structure, where the survival of independent creative hubs is increasingly dependent on the strategic interests of larger market players.
Q2 2025 Gaming Ad Snapshot
The snapshot presents a mid‑year overview of mobile gaming advertising activity, emphasizing the scale of creative assets, audience composition, and platform performance in the second quarter of 2025. Leveraging MarketIQ’s ad‑intelligence engine, which indexes more than three billion ads, the analysis groups campaigns by image, video, and playable formats to surface benchmark performance and creative inspiration for marketers. A core finding is the gender split of the active audience, with males accounting for roughly 61 % and females 38.5 %, while an insignificant 0.8 % remain unclassified. Google Ads dominates the network landscape, followed by Facebook Ads, reflecting the primary channels through which gaming promotions are delivered.
Creative trends highlighted include senior‑focused Mahjong titles, free‑to‑play shooters, and swipe‑based games, illustrating a diversification of themes and monetisation cues such as “No Wifi Needed” and “Get Free Robux.” Campaign metrics reveal a typical lifecycle of 13 million impressions expanding to 47 million, underscoring the rapid scaling potential of high‑performing assets. The data set draws from approximately 250 000 active campaign ads, providing a robust sample for benchmarking.
Overall, the snapshot underscores the importance of data‑driven creative optimisation in mobile gaming, recommending that advertisers exploit MarketIQ’s extensive repository to identify top‑performing formats, refine copy, and align with the prevailing gender distribution and platform preferences observed in Q2 2025.
- Google Ads and Facebook Ads remain the dominant platforms for mobile gaming promotion in Q2 2025.
- The active mobile gaming audience is composed of 61% males, 38.5% females, and 0.8% unclassified users.
- High-performing mobile gaming ad assets demonstrate rapid scaling, with impressions growing from an average of 13 million to 47 million over their lifecycle.
- The Q2 2025 analysis is based on a robust sample size of approximately 250,000 active campaign ads indexed from a total repository of over three billion ads.
- Current creative trends in mobile gaming emphasize diverse themes including senior-focused Mahjong titles, free-to-play shooters, and swipe-based mechanics.