Rise
Company
Documents about Rise
Rise of the Player-Fan: The Growing Opportunity of Mobile Esports in Asia
Mobile esports has emerged as a primary driver of player engagement and revenue across Asia, signaling a shift from traditional PC and console dominance to a mobile-first competitive landscape.
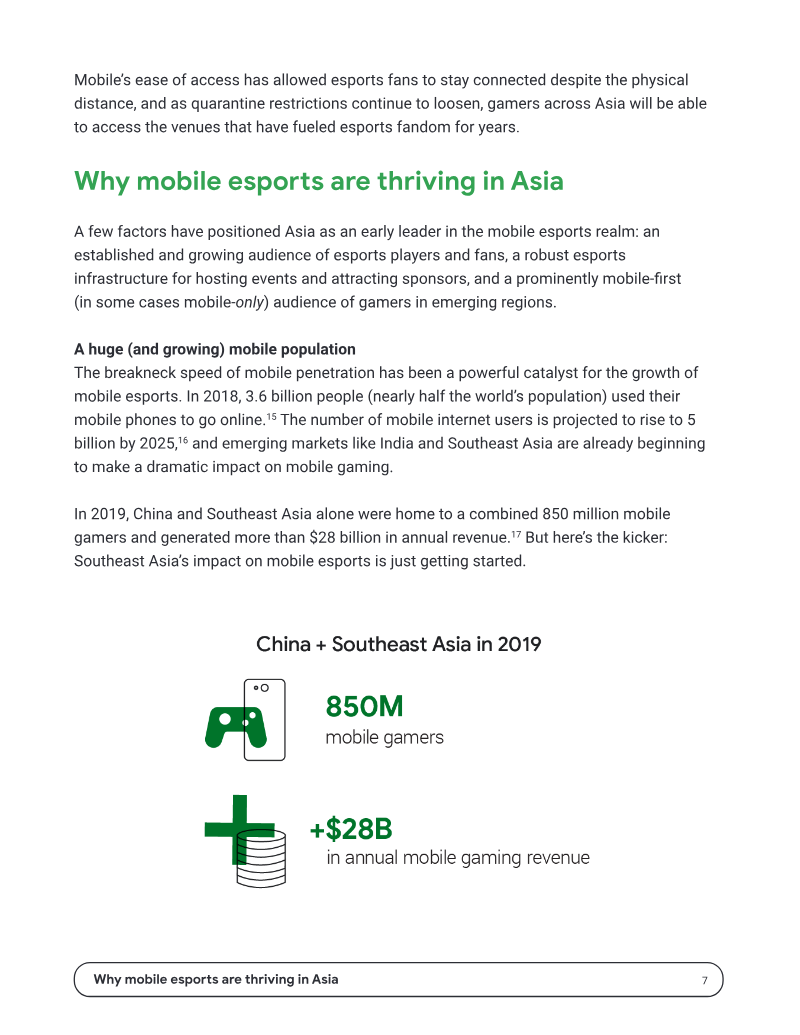
- Asia dominates the global mobile esports landscape, accounting for 68% of the $19.5 billion in total global mobile esports revenue generated in 2019.
- China is the world's largest esports market with 350 million fans, while Southeast Asia experienced a 244% surge in tournament prize values between 2018 and 2019.
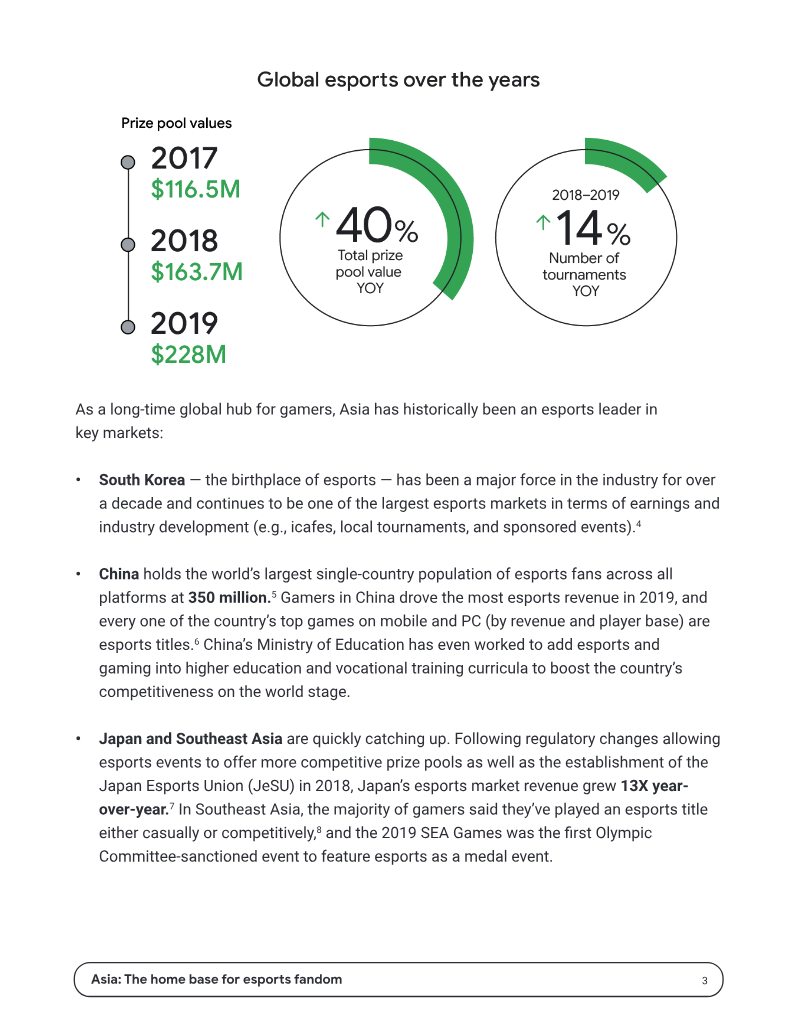
- Global esports prize pools grew by 40% between 2017 and 2019, reaching a total valuation exceeding $228 million.
The Rise of Battle Royale: An Overview of the Hottest Game Genre
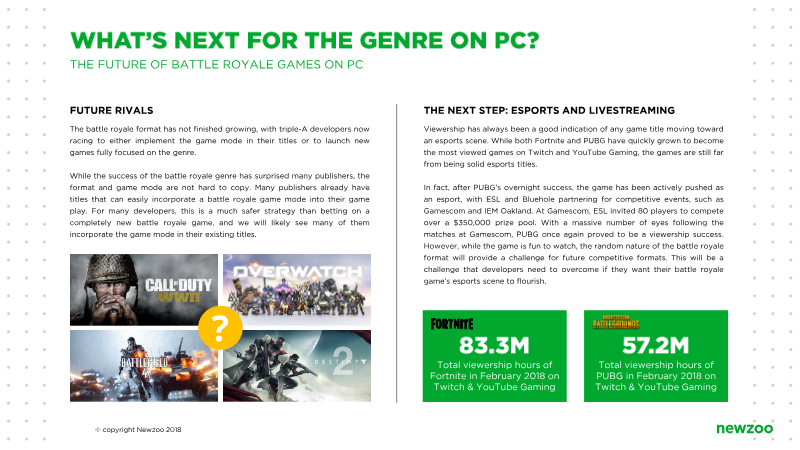
The battle royale genre has emerged as a dominant force in the global gaming industry, characterized by a unique blend of survival, exploration, and last-man-standing mechanics.
- The battle royale genre has achieved mainstream dominance by distilling survival and shooter mechanics into a highly replayable, spectator-friendly format.
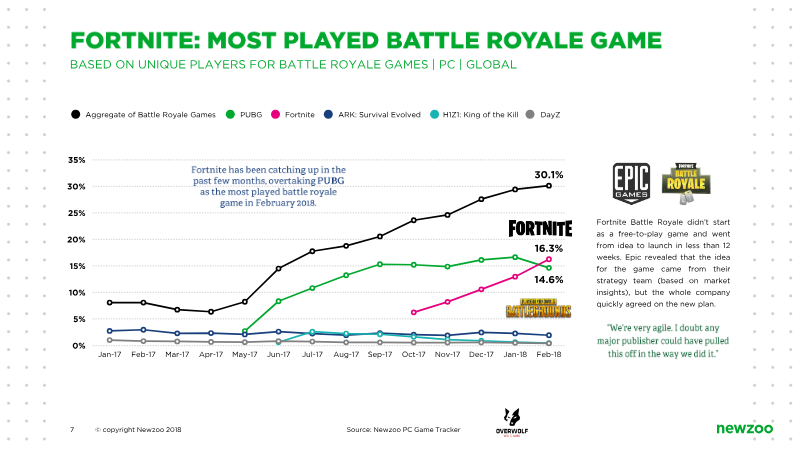
- PUBG and Fortnite serve as the genre's primary anchors, with PUBG maintaining a strong foothold in Asian markets through partnerships with Tencent, while Fortnite captures a broader Western audience via a free-to-play model and cross-platform integration.
- The mobile sector is a primary growth driver, led by publishers like NetEase and Tencent who have successfully launched mobile-optimized versions of major titles to capitalize on mobile-first gaming cultures.
The Rise of the Financial Kingmakers: Private Equity’s $21B+ Bet on Gaming
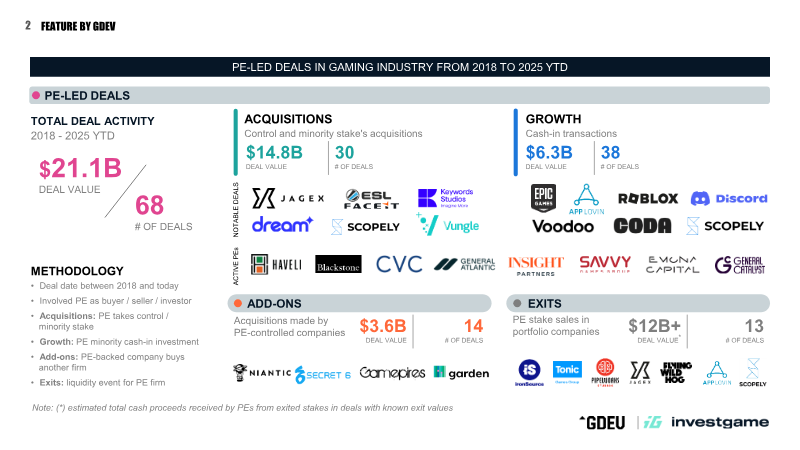
The analysis demonstrates that private equity (PE) has increasingly positioned itself as a decisive force in the gaming sector, channeling more than $21 billion into acquisitions and growth investments from 2018 through the first half of 2025.
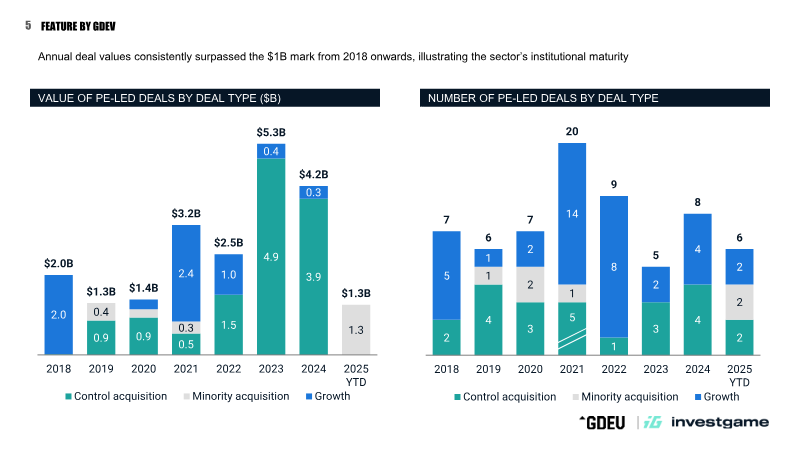
- Private equity firms deployed over $21 billion into the gaming sector between 2018 and mid-2025, with annual deal values consistently surpassing $1 billion.
- Control acquisitions represent the primary investment strategy, accounting for approximately 60% of total capital deployed in the sector.
- Content creation studios holding strong IP portfolios are the most targeted assets, securing 42 of the 68 total private equity-led deals identified.
The Rise and Reset of Sweden's $19B Gaming Capital Machine
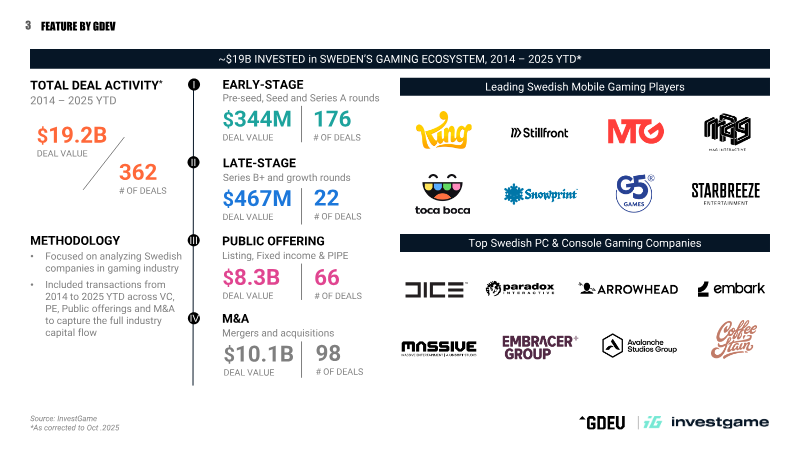
The analysis demonstrates that Sweden’s gaming sector has evolved into a $19 billion capital ecosystem, with 1,100 companies and 202 firms engaging in tracked transactions since 2014.
- Sweden’s gaming sector has matured into a $19 billion ecosystem comprising 1,100 companies, with Swedish developers producing five of Steam’s global top-10 bestsellers in 2024–25.
- Swedish studios contribute approximately 20% of Steam’s projected 2025 gross revenue, cementing the country's status as a dominant global gaming hub.
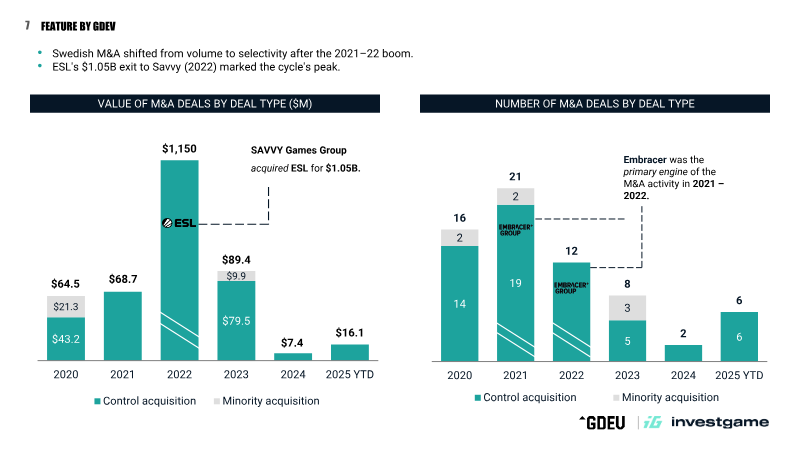
- M&A activity is highly concentrated, with three major deals—King ($5.9 billion), Mojang ($2.5 billion), and ESL ($1.05 billion)—accounting for 93% of the total transaction value.