FunPlus
Documents about FunPlus
Week in Mobile Games E33 - Destiny: Rising heads to mobile and Unity's charm offensive
The mobile gaming industry is currently navigating a period of significant structural and strategic realignment.
- Genshin Impact has solidified its market dominance by surpassing $5 billion in mobile revenue within the Chinese market.
- Bungie and NetEase have partnered to develop Destiny: Rising, a strategic entry into the mobile shooter market, though analysts express skepticism regarding its potential for global blockbuster success.
- Unity is attempting to rebuild developer trust by launching Unity 6 and formally canceling its controversial runtime fee following a period of significant internal layoffs.
Softlaunch Sonar #5: More Whiteout survival-like games coming!
The mobile gaming landscape is currently defined by a rapid cycle of iteration and cross-genre hybridization.
- Major Chinese developers including Century Games, FunPlus, and 37Games are aggressively diversifying their portfolios by expanding from 4X strategy into casual genres like puzzle, merge, and renovation.
- The mobile market is seeing a surge in 'Whiteout Survival-like' 4X strategy titles, characterized by high-frequency development cycles and rigorous testing of themes and user interfaces.
- Developers are increasingly integrating complex PC-inspired mechanics, such as roguelike inventory management systems, into mobile tower defense and RPG titles to improve long-term engagement.
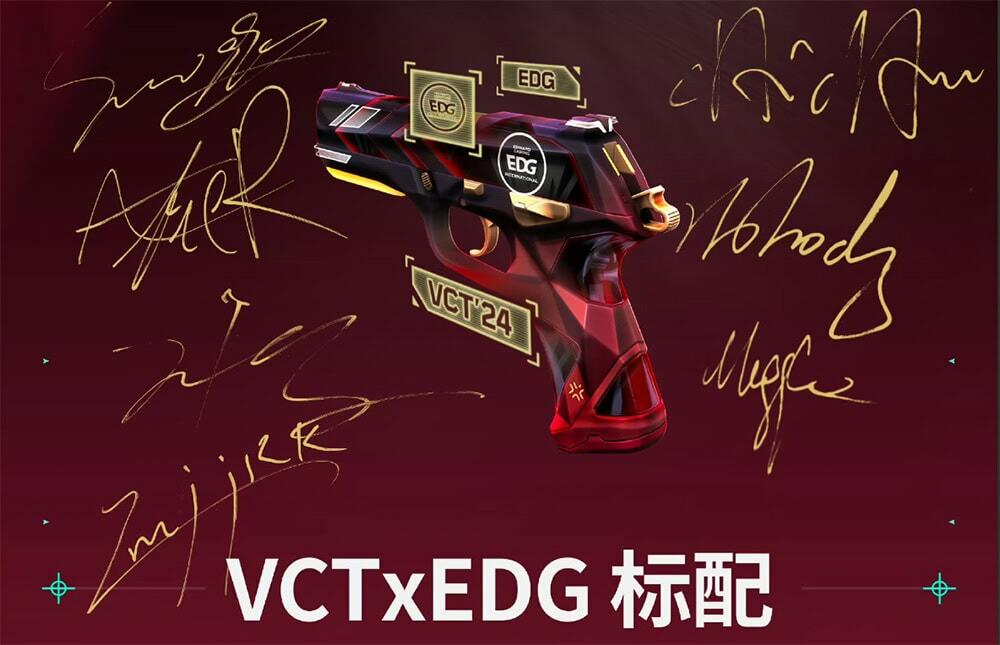
Edward Gaming Generates $690K in Revenue From Valorant Weapon Skins
A recent four-hour live commerce event on the Chinese platform Douyin demonstrated the significant monetization potential of digital goods within the esports sector.
- A four-hour Valorant live commerce event on Douyin generated approximately $1.98 million in total revenue from the sale of over 100,000 team-branded weapon skins.
- Edward Gaming (EDG) led all participating teams with 78,000 units sold, resulting in approximately $690,000 in revenue.
- Bilibili Gaming (BLG) secured the second-highest sales volume with 12,000 units, generating approximately $107,000.
Fireside Chat: Thriving in the State of Survival: Affan Butt & Andy Zong
FunPlus founder and CEO Andy Zhong reflects on his 14-year tenure in the gaming industry, detailing the company’s evolution from a small startup to a global organization with 2,000 employees.
- FunPlus has scaled from a small startup to a global organization with 2,000 employees over its 14-year history.
- Strategy games are shifting from niche, core-focused titles to hybrid experiences that integrate mechanics from casual genres like tower defense to expand their addressable market.
- The company is diversifying its growth strategy by moving beyond traditional performance marketing through cross-platform expansion and mobile-first development.
2023's Winners and Losers: By the Numbers
The mobile gaming industry experienced a period of significant volatility throughout 2023, characterized by shifting market leaders and widespread revenue declines.
- Mihoyo, Scopely, and Dream Games emerged as the primary industry winners in 2023, driven by the successful launches of Honkai: Star Rail, Monopoly Go, and Royal Match.
- Supercell dropped out of the top ten grossing publishers for the first time in 2023, with annual earnings falling by an estimated $200 million.
- Zynga maintained a top-ten position despite a year-on-year in-app purchase (IAP) revenue decline of $230 million, while FunPlus experienced a similar magnitude of revenue loss.
Mercedes-Benz Korea Sponsors T1 Entertainment & Sports
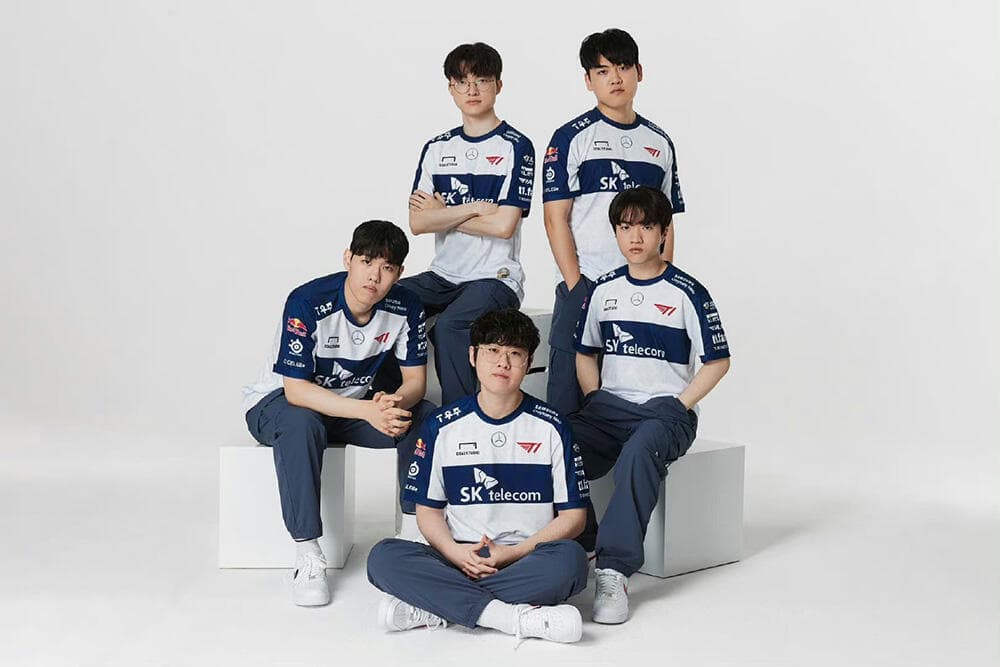
Mercedes-Benz Korea has entered into a sponsorship agreement with the South Korean esports organization T1 Entertainment & Sports.
- Mercedes-Benz Korea has signed a sponsorship deal with the esports organization T1 Entertainment & Sports, marking the brand's first partnership with a South Korean esports team.
- The agreement effectively ends the previous partnership between T1 and BMW, which had been in place since April 2020.
- As part of the new deal, the Mercedes-Benz logo will be prominently displayed on the center of T1 team jerseys, debuting at the League of Legends Mid-Season Invitational in London (May 2–21, 2023).
Market Wire: February 6, 2023
The February 6, 2023, industry update provides a critical analysis of the current state of the video game market, focusing on the challenges facing AAA development, the characteristics of high-revenue mobile titles, and the strategic rationale behind recent mobile game shutdowns.
- AAA game development faces a profitability crisis as titles require massive player bases to succeed while competing for limited attention, leading to a significant decline in market value for companies like Ubisoft, whose stock fell from 82.40€ in January 2021 to 18.59€ by January 2023.
- Industry experts suggest a shift toward 'AA' tier games or the 'Rockstar model' of hyper-successful, long-term engagement titles as potential solutions to the current AAA development challenges.
- EA CEO Andrew Wilson attributed the shutdown of Apex Legends Mobile to a failure to translate complex, team-based gameplay to mobile and an inability to retain casual users, rather than a lack of cross-platform connectivity.
What Kind of Mobile Games Can Generate More Than $1 Billion in Revenue?
The analysis investigates the characteristics of mobile titles that have surpassed a cumulative $1 billion in revenue, drawing on data from PocketGamer and SocialPeta.
- Nearly 60 mobile games have surpassed $1 billion in cumulative revenue, with 4X strategy games emerging as the most dominant genre, accounting for nine of these titles.
- Chinese developers are a major force in the billion-dollar club, responsible for 21% of all qualifying titles and specifically dominating the 4X strategy genre through studios like FunPlus.
- High-revenue games require massive marketing scale, averaging 47,000 unique creatives per title, with video ads comprising 95% of the advertising mix for top performers like 'Rise of Kingdoms'.
Game Industry M&A in 2022
The video discussion examines the evolving landscape of mergers and acquisitions within the global video game industry as of early 2022.
- The game industry is experiencing a structural shift in M&A, moving away from mid-tier consolidation toward a bifurcated strategy focused on both larger-scale acquisitions and smaller-scale targets.
- High-profile industry consolidation, exemplified by Microsoft’s acquisition of Activision and Take-Two’s acquisition of Zynga, reflects the ongoing pressure on major companies to drive growth through M&A.
- The supply of 'easy' mid-tier acquisition targets has largely dried up after a five-year bull run in industry M&A activity.
Game Industry M&A in 2022 and Beyond! Miniclip, Drake Star Partners, & FunPlus Weigh In
The global gaming industry is undergoing a period of rapid, transformative consolidation, characterized by a shift toward platform-centric strategies and the pursuit of established intellectual property.
- The gaming industry is shifting toward a 'fewer, bigger, better' investment strategy, exemplified by major acquisitions like Microsoft’s purchase of Activision Blizzard and Take-Two’s acquisition of Zynga.
- Total deal values in the gaming sector are projected to reach $150 billion in 2022, though this growth is being tempered by cooling public markets and increased regulatory scrutiny.
- Rising user acquisition costs and mobile privacy changes are forcing companies to prioritize platform-centric strategies and the acquisition of established intellectual property.
2021 Predictions: Contenders Throwdown for Supercell's Mid-Core Crown
The mobile strategy gaming sector experienced a significant transformation in 2020, generating $5 billion in net revenue and achieving a 21% increase in in-app purchase growth.
- Lilith is positioned to surpass Supercell in global mid-core revenue by the end of Q1 2021, driven by strong performance in its strategy portfolio and upcoming title launches.
- Supercell has experienced five consecutive years of revenue decline, with its 2020 growth largely dependent on the China launch of Brawl Stars, which saw a 90% drop in monthly run-rate shortly after release.
- The 4X strategy sub-genre remains the largest in the mid-core category, generating $3.3 billion in revenue with 31% year-over-year growth and accounting for one-third of the total mid-core market.
2019 Predictions: There Is a Billion to be Made in the Wake of Machine Zone
The mobile strategy game market, a critical segment of the mid-core genre, is undergoing a significant transition as established leaders face decline and new publishers capture market share.
- The 4X strategy subcategory represents a high-value opportunity, with IGG’s Lords Mobile generating over €350M in 2018 and demonstrating that integrating RPG mechanics into 4X gameplay can successfully expand the genre's audience.
- Machine Zone lost its dominant market position following the launch of Final Fantasy, allowing competitors like FunPlus and IGG to capture significant market share through superior live operations and portfolio-based strategies.
- FunPlus achieved growth by building a 4X platform that utilizes reskins of its hit title King of Avalon, proving that theme and art style are the primary differentiators for user acquisition and marketability in a genre where core features are often similar.