A significant acquisition anchored the M&A figures.
A single large investment heavily influenced the total.
This single investment represented the vast majority of the funding in private placement markets.
This shift aims to drive long-term scalability rather than traditional content production. Technological integration is a primary driver of industry strategy.
These major industry players are focusing on AI-driven efficiency to secure competitive advantages.
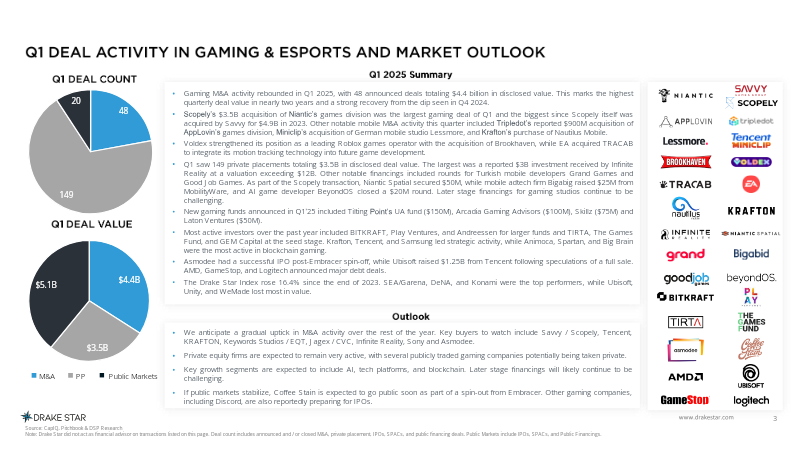
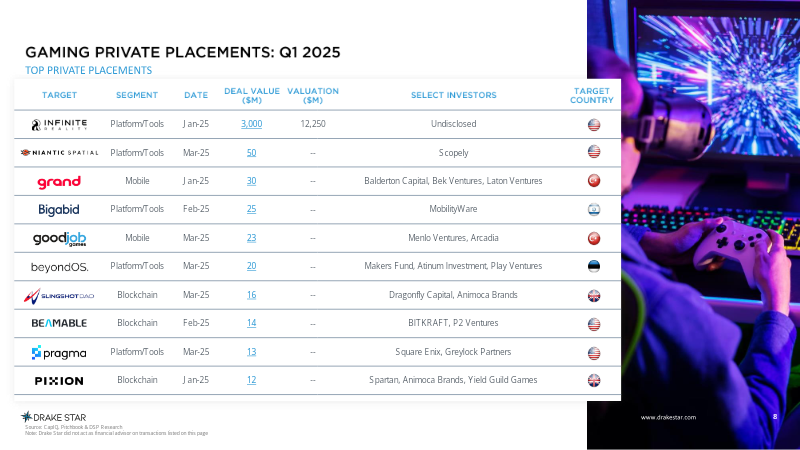
The global gaming industry experienced a robust recovery in the first quarter of 2025, characterized by a resurgence in capital deployment and strategic consolidation. Total merger and acquisition activity reached $4.4 billion across 48 deals, anchored by the significant $3.5 billion acquisition of Niantic’s games division by Scopely. Simultaneously, private placement markets remained active, recording $3.5 billion in funding across 149 deals, heavily influenced by a $3 billion investment in Infinite Reality. These figures signal a stabilizing market environment, though later-stage studio financing continues to face structural headwinds.
Technological integration remains a primary driver of industry strategy, with generative artificial intelligence and machine learning serving as focal points for product development and audience targeting. Major strategic players and venture capital firms, including Bitkraft, Tencent, and Krafton, are prioritizing investments in tech platforms and blockchain infrastructure to secure long-term growth. This shift reflects a broader industry trend where value is increasingly concentrated in platform-agnostic tools and AI-driven efficiency rather than traditional content production alone.
Market performance during this period exhibited significant divergence across segments. While the Drake Star Gaming Index posted a 16.37% return, individual outcomes varied drastically, with hardware and platform-oriented companies like NVIDIA and AppLovin commanding superior valuation multiples compared to smaller developers. Mobile-focused entities continue to navigate complex growth trajectories, and while some firms achieved triple-digit gains, others faced substantial declines. Ultimately, the industry is transitioning toward a model where valuation is increasingly tethered to technological scalability and platform dominance rather than purely creative output.