Player Demographics reports and market data
Documents
Japan Market Report 2025
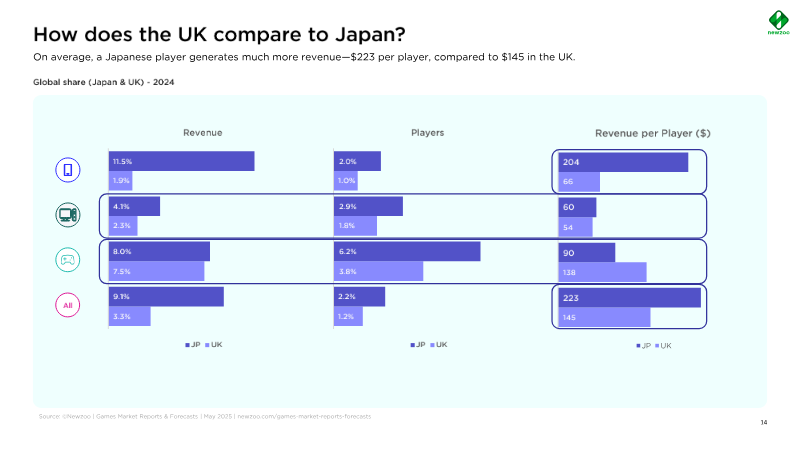
The Japanese games market represents a unique and highly lucrative landscape, accounting for 9.1% of global games revenue despite containing only 2.2% of the global player base.
- Japan generates 9.1% of global games revenue from only 2.2% of the global player base, with an average revenue per user of $223 compared to $145 in the UK.
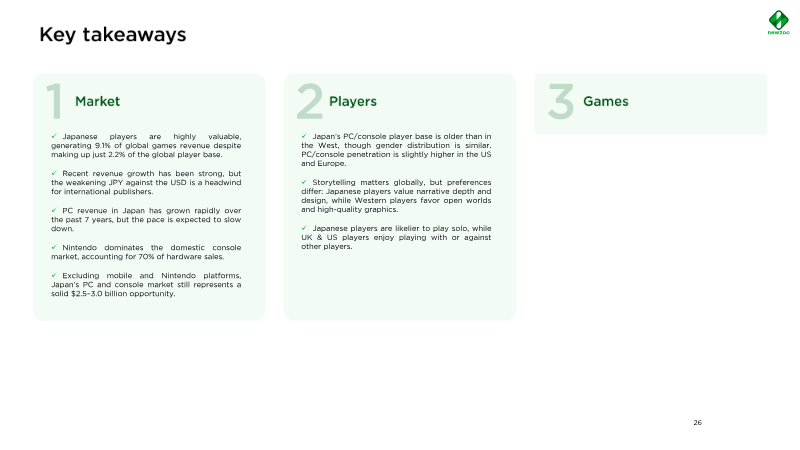
- International stakeholders have a $2.5 to $3.0 billion market opportunity when excluding mobile and Nintendo platforms, which currently command 70% of console hardware dominance.
- Japanese gamers prioritize narrative depth, character design, and solo play, contrasting with Western preferences for open worlds, high-end graphics, and competitive multiplayer.
Global Games Forecasts 2025-2031
The analysis projects that the worldwide video-game market has entered a mature phase, with revenue expected to reach $236.9 billion in 2025 and to climb modestly to $280.1 billion by 2031.
- The global video-game market has entered a mature phase, with revenue projected to grow from $236.9 billion in 2025 to $280.1 billion by 2031 at a modest annual rate of 4–5 percent.
- Asia-Pacific remains the dominant market, accounting for 53 percent of the 1.53 billion global gamers in 2024 and showing the highest regional penetration at 13 percent.
- In-game spending, which currently accounts for 68 percent of software revenue, is expected to experience a slight decline to 67 percent by 2031 due to live-service market oversaturation.
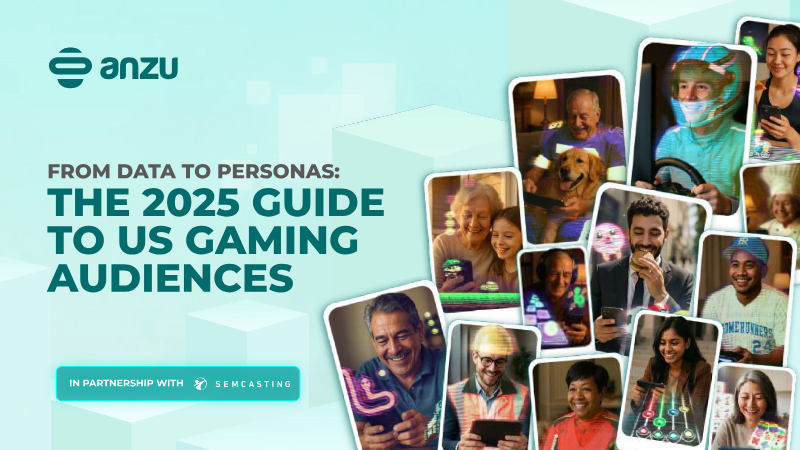
The 2025 Guide to US Gaming Audiences: From Data to Personas
The 2025 United States gaming landscape reflects a profound demographic shift, moving away from the outdated stereotype of the isolated young male toward a mainstream, diverse population nearly evenly split by gender.
- The US gaming audience is now gender-balanced and financially stable, with significant segments earning between $51,000 and over $250,000 in net worth.
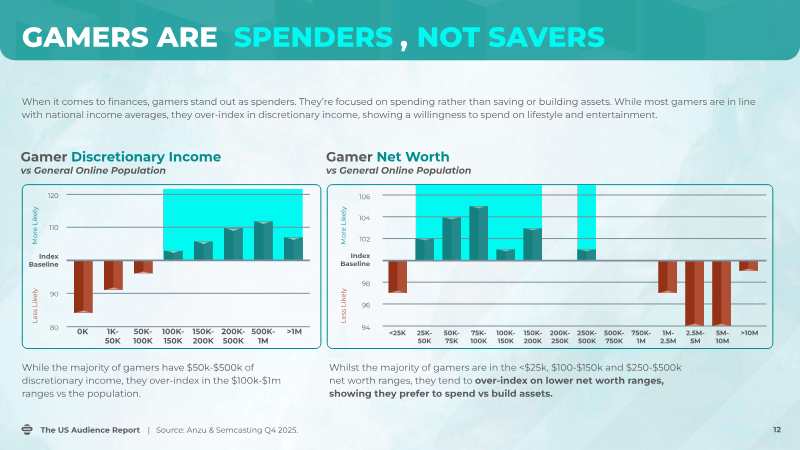
- Modern gamers prioritize immediate lifestyle quality and discretionary spending over long-term asset accumulation, frequently investing in premium groceries and convenience services.
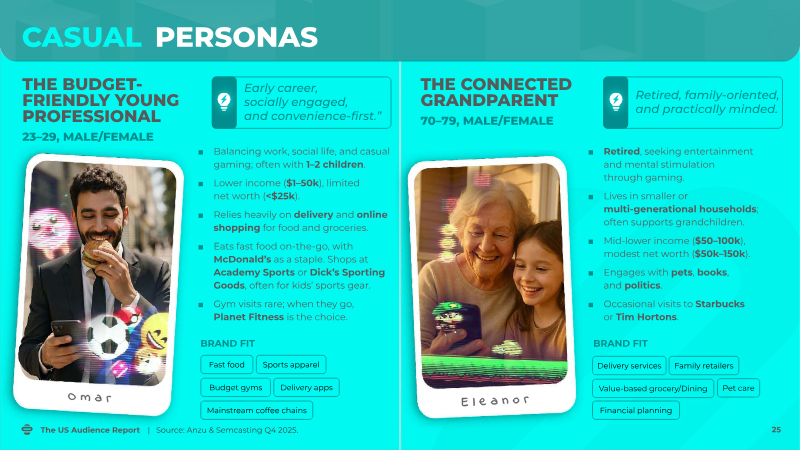
- Gaming is primarily a social and familial activity rather than a solitary pursuit, with consumer habits heavily influenced by multi-generational household dynamics.
10 Major Trends to Watch in Asia & MENA
The video game industry across Asia and the Middle East and North Africa (MENA) is undergoing a period of significant transformation as of 2025, driven by shifting player demographics and evolving monetization strategies.
- Asia and MENA are the primary engines of global gaming growth, driven by a mobile-first audience and a rising middle class with increased discretionary income.
- Government-backed investments in Saudi Arabia and the UAE are rapidly establishing these nations as central hubs for international esports and game development infrastructure.
- Market success in these regions now requires hyper-localization and the adoption of innovative payment ecosystems that bypass traditional storefront limitations.
What Does the Monetization Landscape Look Like for Video Games in MENA?
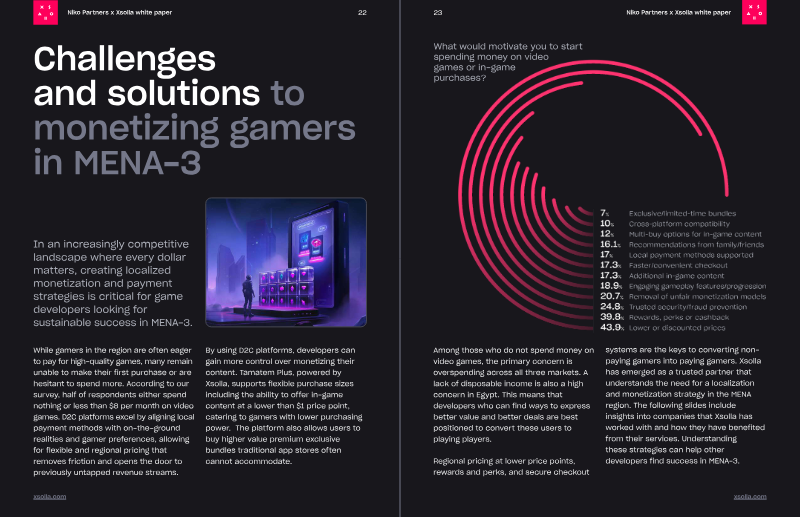
The video game industry in the MENA-3 region—comprising Saudi Arabia (KSA), the United Arab Emirates (UAE), and Egypt—is experiencing rapid expansion driven by a young, tech-savvy population and significant government investment.
- The MENA-3 gaming market (KSA, UAE, Egypt) generated $2 billion in player spending in 2024 and is projected to grow to over $2.7 billion by 2028.
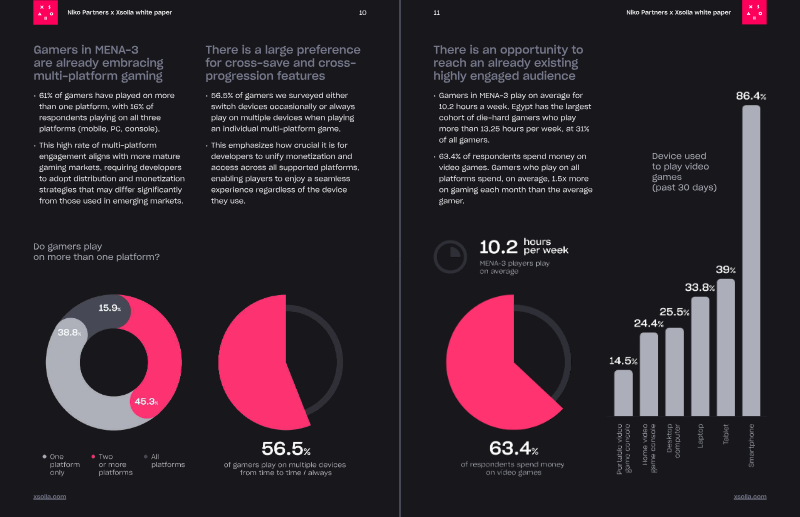
- Payment infrastructure is a major barrier, as 67% of the regional population lacks access to traditional credit or debit cards, necessitating the integration of local payment networks like Mada in Saudi Arabia and Fawry in Egypt.
- Direct-to-consumer (D2C) web shops are essential for bypassing 30% app store fees, with 53% of paying gamers in the region already utilizing official game websites for purchases.
Mobile Games in 2025: Trends & Strategies Supercharging Revenue Growth
The global mobile gaming market entered a phase of intensified monetization and efficiency in 2024, characterized by a 3.8% increase in consumer spending to $65.7 billion despite a 6.6% decline in total downloads.
- The mobile gaming market is shifting toward higher monetization efficiency, evidenced by a 3.8% increase in consumer spending to $65.7 billion despite a 6.6% decline in total downloads.
- Spending per download rose by 11.2% in 2024, as the industry prioritizes high-value user retention over the volume-based acquisition strategies of previous years.
- New game releases dropped by over 43%, yet top-tier titles are reaching the $1 million revenue milestone nearly twice as fast as they did in 2022.
Souls‑likes: From Niche to Mainstay
The analysis charts the evolution of the souls-like subgenre from a niche curiosity to a mainstream pillar of the video-game market, emphasizing the decisive role of APAC developers and Chinese players in shaping its commercial trajectory.
- The souls-like genre has shifted from indie-dominated to AAA-led, with AAA and AA publishers now accounting for over 70% of estimated units sold on Steam.
- Chinese gamers represent approximately 47% of the global souls-like audience, significantly outpacing the United States at 15% and Germany at 5%.
- APAC developers have surged to control roughly 80% of the genre's development share as of 2025, building on a foundation established by Japanese studios.
Games Industry in 2025
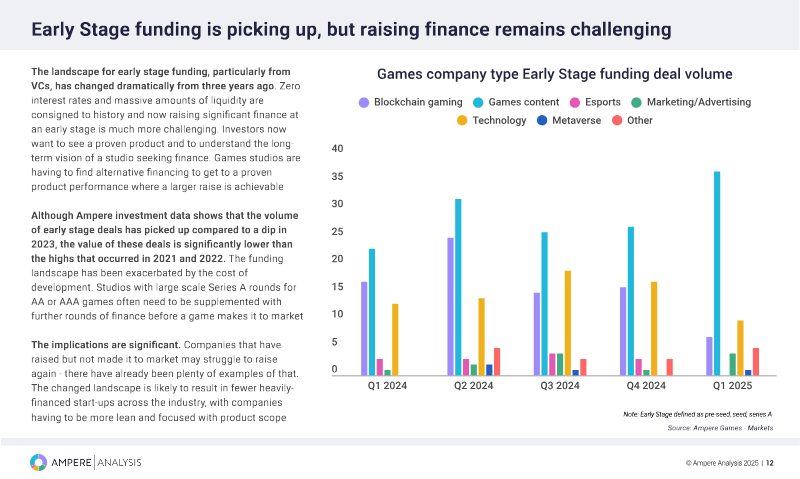
The global games content and services market reached a record $199.4 billion in 2024, a 3.5% year-on-year increase that surpassed pandemic-era peaks.
- The global games market reached $199.4 billion in 2024, but growth is projected to slow to 0.9% in 2025 due to the delay of Grand Theft Auto VI into 2026.
- In-game spending now drives 77% of total industry revenue, while physical media is expected to decline to just 2% of the market by 2026.
- The launch of the Nintendo Switch 2 in 2025 is expected to create a $7–8 billion content opportunity with significant potential for increased in-game monetization.
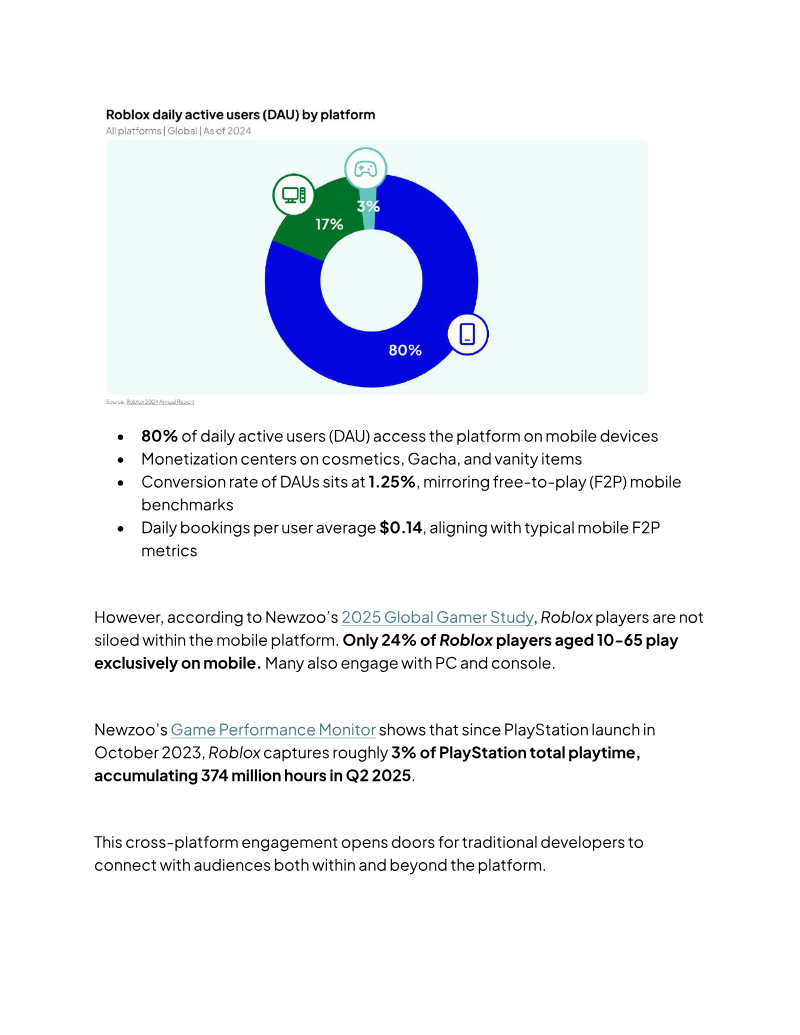
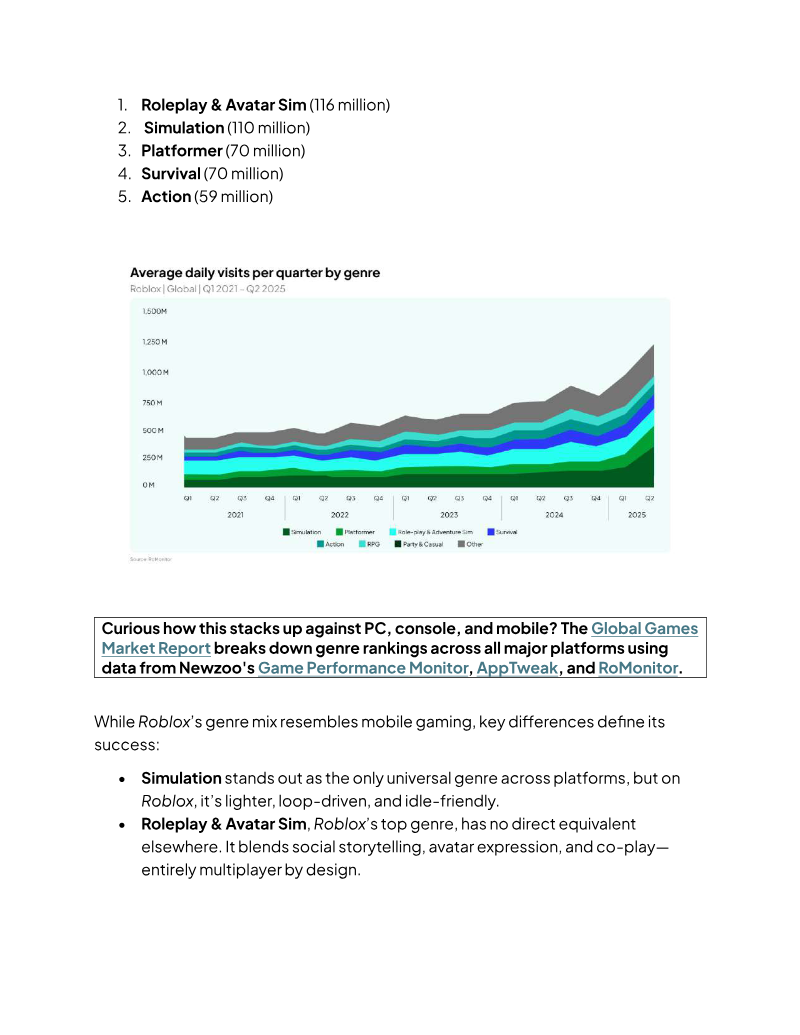
Roblox as a Strategic Growth Platform: What Developers Need to Know
Roblox has evolved from a youth-centric gaming site into a massive entertainment ecosystem and creator economy, boasting nearly 112 million daily active users and distributing over $300 million to creators in a single quarter.
- Roblox has scaled to 112 million daily active users and distributed over $300 million to creators in a single quarter, functioning more like a social media platform than a traditional gaming engine.
- The 13+ demographic is the platform's fastest-growing segment, increasing by 54% year-over-year and bringing higher spending power to the ecosystem.
- Success on the platform is driven by cultural fluency and rapid iteration rather than graphical fidelity, with discovery algorithms favoring native platform knowledge over traditional production cycles.
Spelutvecklarindex 2024: Sweden
Sweden’s video-game sector continued to expand in 2023 despite a constrained credit environment, with domestic turnover rising 6.4% to 34.6 billion SEK and reaching 90.4 billion SEK when foreign subsidiaries are included.
- Sweden's video-game sector grew domestic turnover by 6.4% to 34.6 billion SEK in 2023, with total turnover reaching 90.4 billion SEK when including foreign subsidiaries.
- The industry reached a record 1,010 development firms, an 8% increase, while domestic employment grew by 8% to 9,089 staff despite a 4% decline in the overseas workforce.
- High-profile M&A activity remained significant, highlighted by Embracer’s €4.9 billion sale of Gearbox to Take-Two and EQT’s €28.7 billion acquisition of Keywords Studios.
Video Games in European Schools: Results from the Games in Schools 2023-2024 Research Project
The Games in Schools 2023-2024 research project provides a comprehensive analysis of the integration of video games into formal education across 26 European countries.
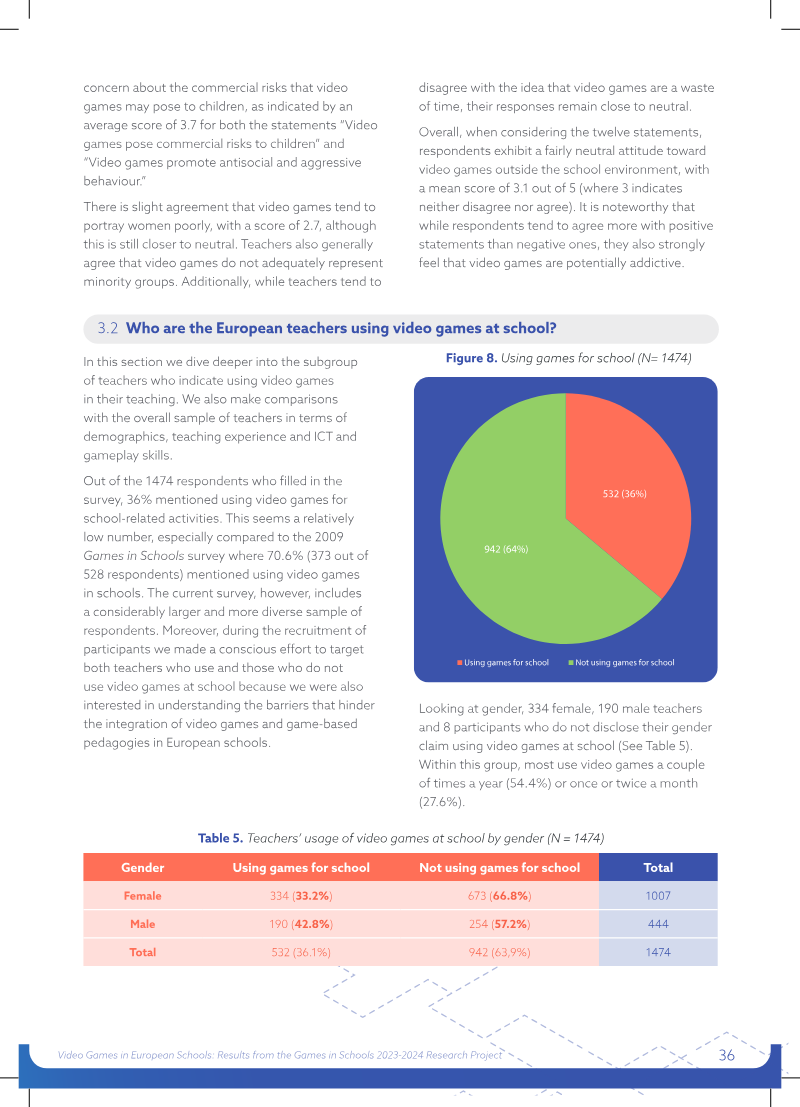
- While 53% of Europeans play video games and the industry exceeds €25 billion in annual revenue, only 36% of surveyed teachers currently use games in the classroom, with 63% explicitly requesting more professional training.
- Teachers who do integrate games report significant improvements in student motivation, problem-solving, and psychological capital, noting particular efficacy for special-needs, low-performing, and female students.
- The primary barriers to adoption include a lack of curriculum-aligned titles, insufficient hardware and broadband infrastructure, and parental concerns regarding screen time and data privacy.
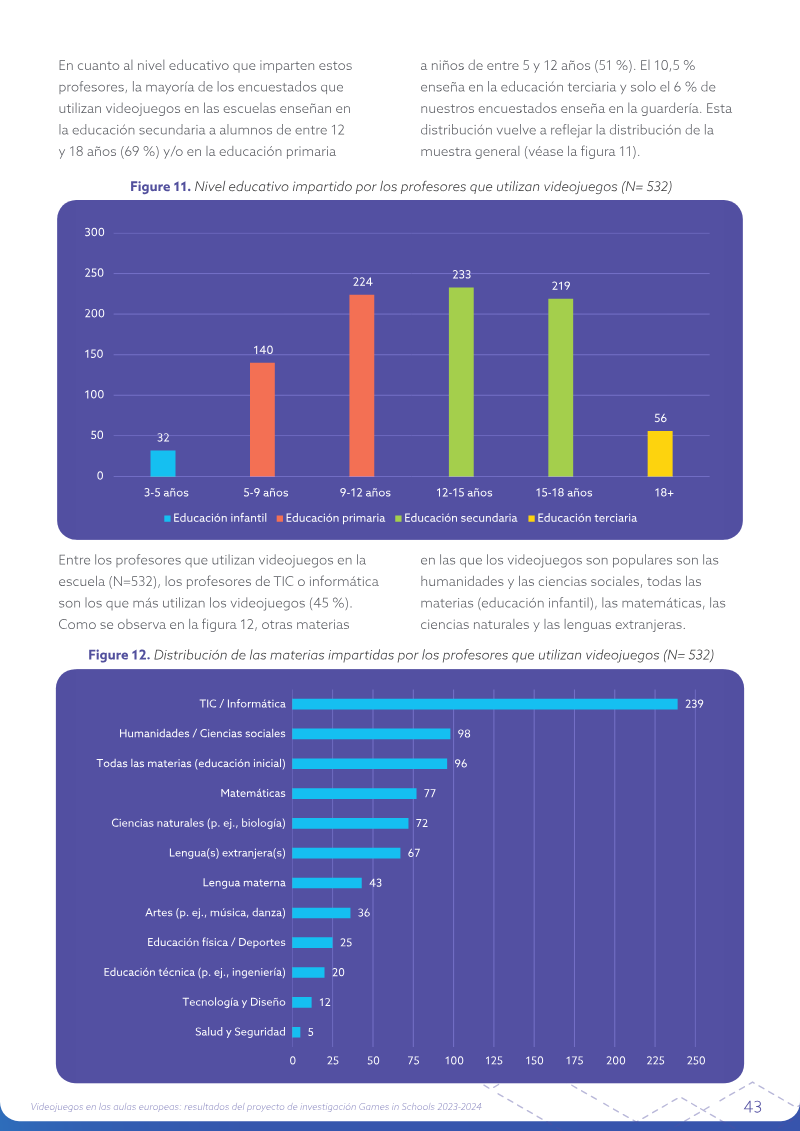
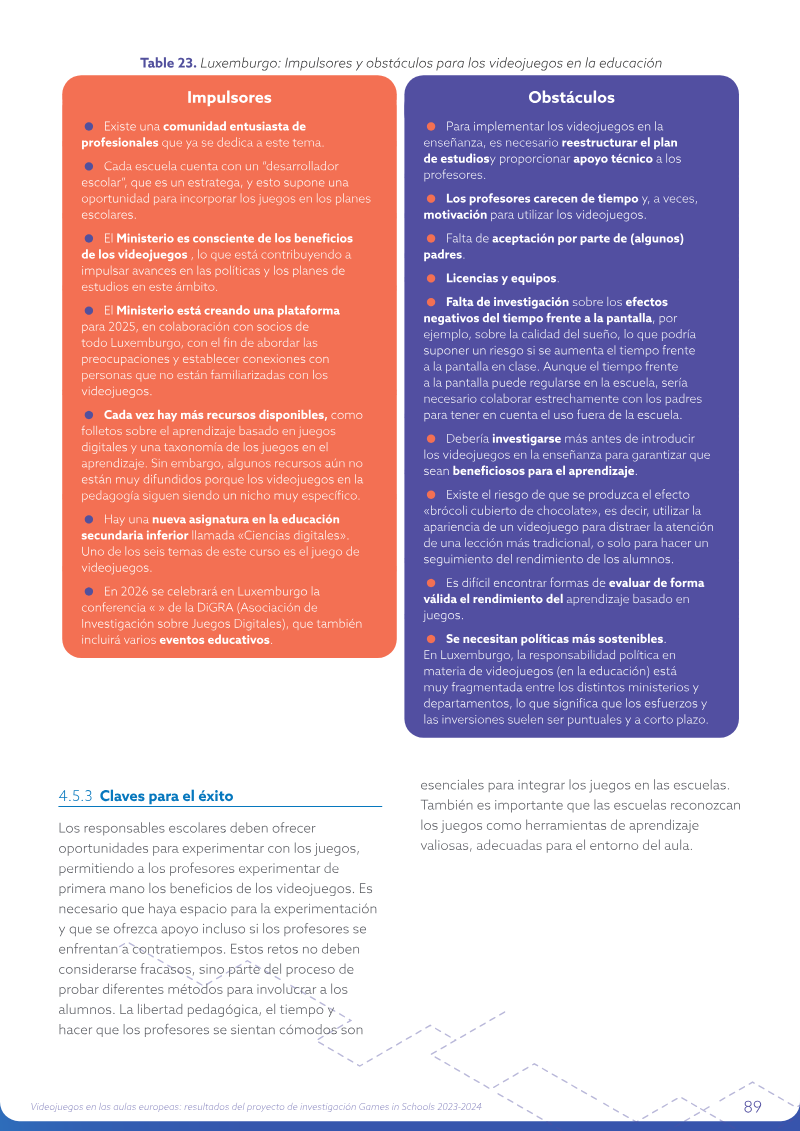
Videojuegos en Aulas Europeas: Resultados del Proyecto de Investigación 'Juegos en las Escuelas 2023-2024'
The study evaluates how video-games are being integrated into European primary and secondary classrooms and argues that, while games hold clear potential to enhance motivation, cognition and 21st-century competencies, systematic support is still required to translate research into widespread practice.
- 36% of the 1,474 European teachers surveyed currently integrate video games into their lessons, with over half of those users employing them regularly.
- The primary barriers to adoption are the difficulty of finding age-appropriate, curriculum-aligned, and GDPR-compliant games (45%) and technical limitations such as inadequate hardware or internet access (42%).
- Teacher digital competence has risen to a self-reported 7.7/10 since the 2009 baseline, supported by more positive attitudes and increased backing from school leadership.