Mergers & Acquisitions reports and market data
Documents
Kadokawa Integrated Report 2025
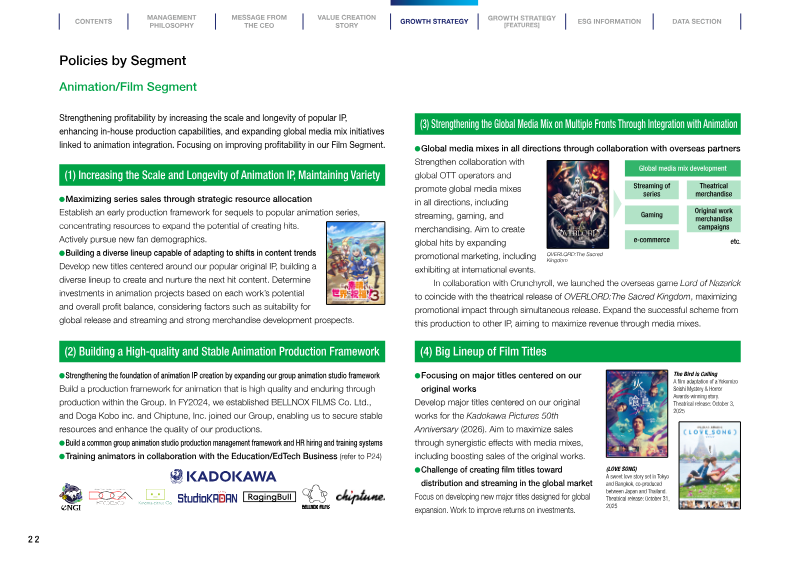
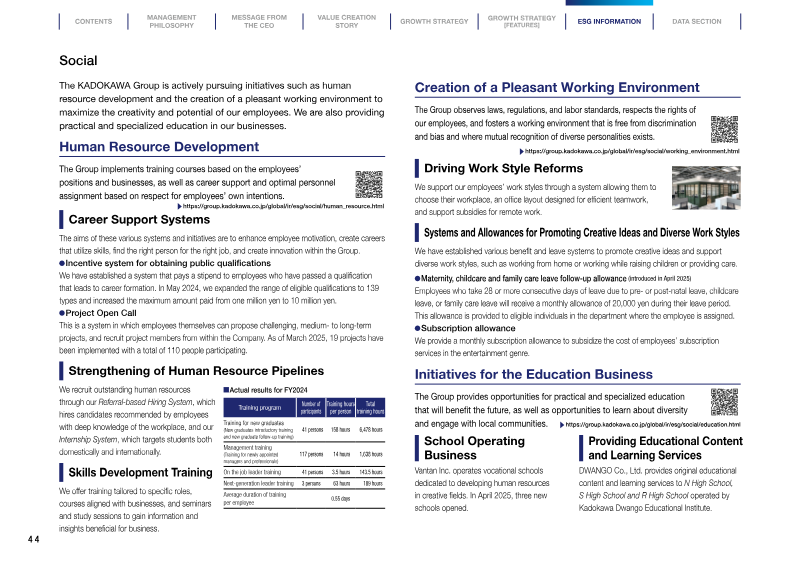
The KADOKAWA Group’s 2025 strategy centers on a Global Media Mix model, which seeks to maximize the lifetime value of intellectual property by integrating publishing, animation, gaming, and education.
- The Kadokawa Group utilizes a 'Global Media Mix' strategy that converts intellectual property (IP) across books, animation, and games, supported by an archive of over 130,000 titles and the creation of 5,500 new titles annually.
- FromSoftware, a key subsidiary, has achieved significant commercial success with the 'Elden Ring' franchise, which has shipped over 30 million units worldwide, alongside the 'Shadow of the Erdtree' expansion exceeding 10 million units.
- The company is aggressively expanding its digital manga presence, notably through the 'KADOCOMI' portal, which reached 1.5 million cumulative downloads and 722 serialized titles as of August 2025.
Acquisition: Versus Evil and Red Cerberus
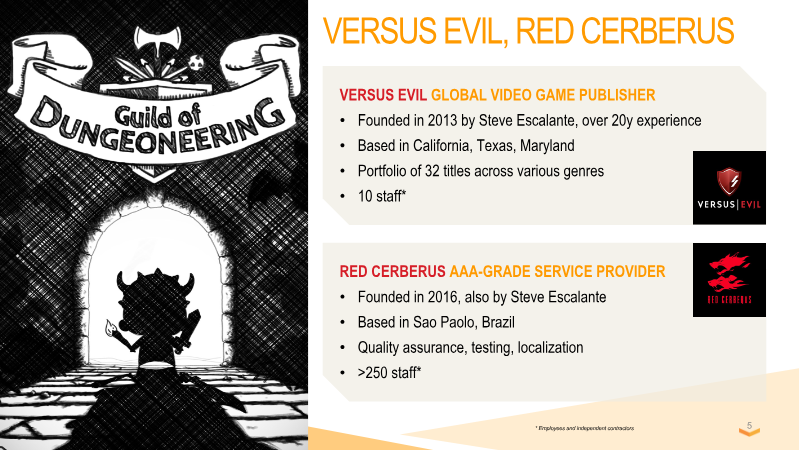
TinyBuild Inc. has finalized the acquisition of Versus Evil, a global video game publisher, and Red Cerberus, a Brazil-based AAA-grade service provider.
- TinyBuild Inc. acquired publisher Versus Evil and service provider Red Cerberus for a total maximum consideration of $31.3 million, consisting of $12.5 million in upfront cash and up to $18.8 million in deferred share-based payments.
- The acquisition is projected to be marginally accretive in 2021 and approximately 10% accretive to earnings in 2022.
- The combined entities generated $12 million in revenue with an EBITDA loss of $0.2 million during the 2020 fiscal year.
2023 M&A Outlook: Post-Pandemic Boom
The 2023 M&A Outlook provides a strategic assessment of the technology mergers and acquisitions landscape following the record-breaking activity of 2021 and the subsequent market cooling in 2022.
- Strategic necessity is driving a shift toward consolidation in 2023, as mature corporations prioritize acquiring disruptive, value-add companies to maintain innovation despite macroeconomic volatility.
- The market has shifted toward an 'M&A barbell effect,' where investors avoid early-stage, cash-burning startups and high-valuation unicorns in favor of companies with sustainable revenue and cash flow growth.
- While 2023 deal volume will not reach the record-breaking levels seen in 2021, robust deal flow is expected to persist due to significant dry powder held by private equity firms and large-cap corporations.
Global Gaming Report Q1 2026
The global gaming industry experienced a complex start to 2026, characterized by a sharp divergence between high-level strategic consolidation and broader market volatility.
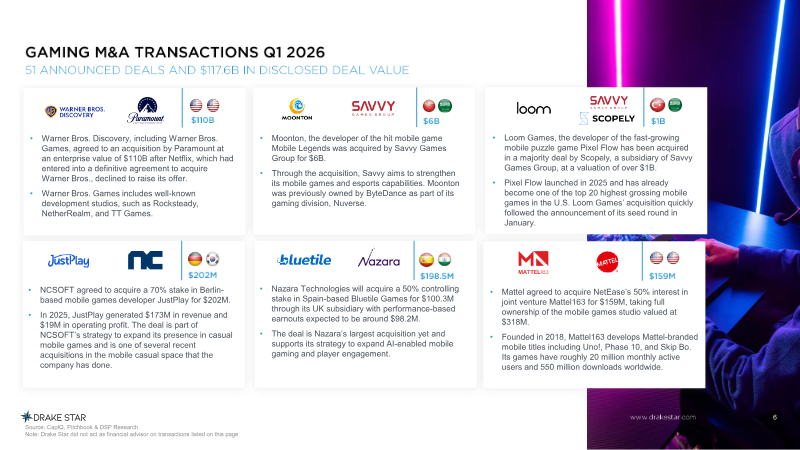
- M&A activity reached a 15-month peak in Q1 2026 with 51 transactions totaling over $100 billion, headlined by the Paramount acquisition of Warner Bros. Discovery and Savvy Games Group's purchase of Moonton.
- Private financing remained steady with $785 million raised across 106 deals, showing a clear investor preference for AR/XR hardware and infrastructure over traditional software.
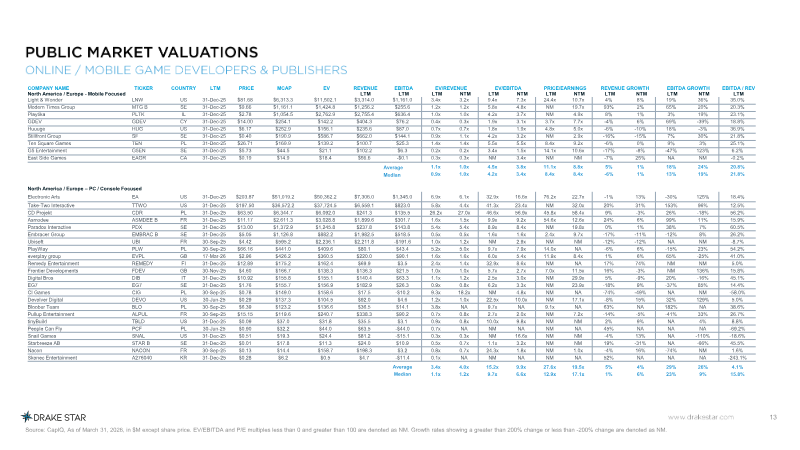
- The Drake Star Gaming Index declined by 1.8 percent, driven by market weakness in Western regions and the mobile gaming sector.
Video Game Market Update: Q2 2026
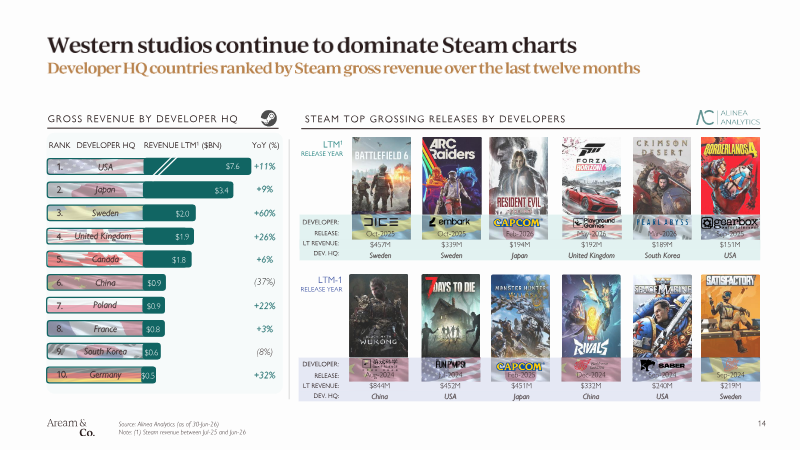
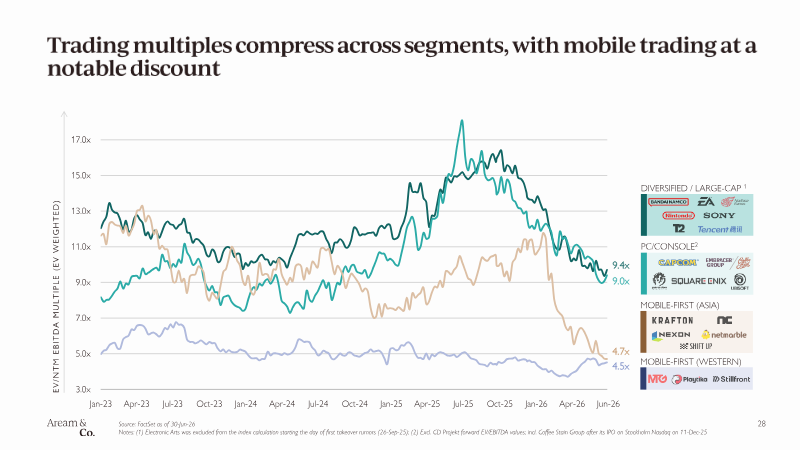
The global video game industry experienced a period of divergent performance during the second quarter of 2026, characterized by a resilient PC sector and a stagnant console market.
- Private investment in the gaming sector surged sixfold year-over-year to $3.1 billion, with capital increasingly shifting away from content development toward infrastructure, AI, adtech, and immersive hardware.
- The PC sector remains a primary growth driver with Steam recording a 13 percent year-over-year revenue increase, while the console market remains stagnant as Switch 2 gains offset declines in PlayStation and Xbox hardware.
- Mobile gaming is facing a downturn, evidenced by a 4 percent contraction in gross revenue and a 12 percent decline in new installs, with top charts remaining stagnant due to a reliance on legacy titles.
Is There a Shift from Content to Tech Startups Among Gaming VCs?
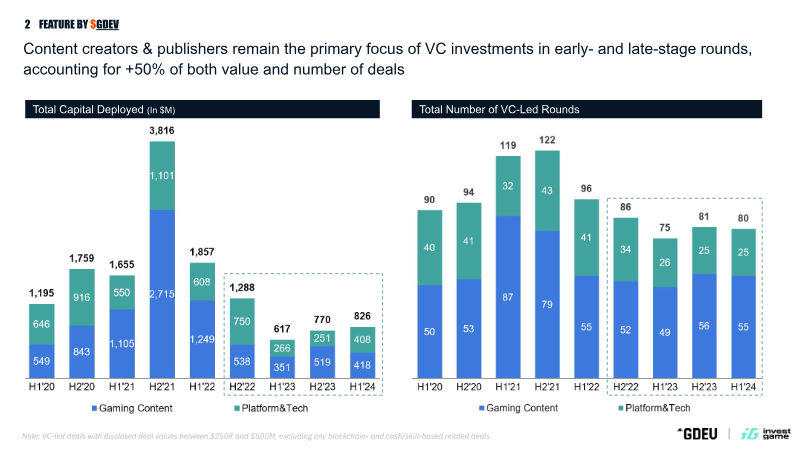
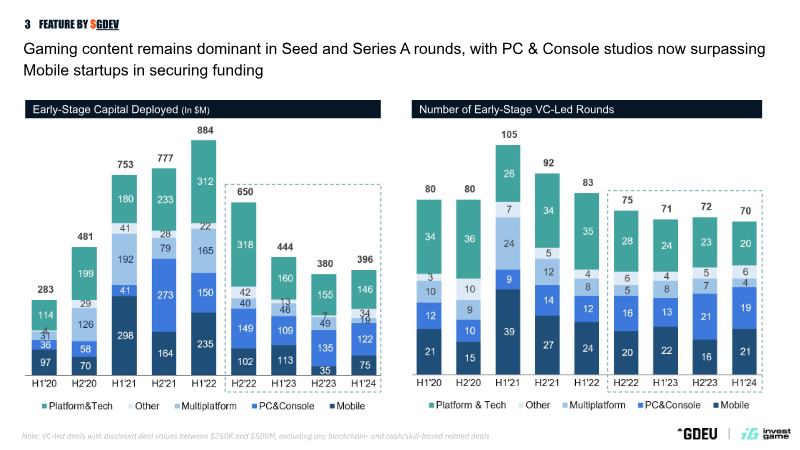
The analysis examines venture capital activity in the gaming sector from 2020 to early 2024, focusing on whether investment priorities are shifting from traditional content creation and publishing toward technology-driven startups.
- Content creators and publishers remain the primary focus of gaming VC, accounting for over half of all capital deployed (approximately $1.76 billion) and the majority of deal volume across all stages.
- Gaming-focused VC funds, including VENTURES, BEHOLD Venture, and Lightspeed Lvp., significantly increased their activity between 2020 and H1 2024, with capital deployed rising from $1.3 billion to over $2.4 billion.
- The number of VC-led funding rounds grew substantially from 67 in early 2020 to 289 by H1 2024, reflecting an overall increase in investment activity.
Europe’s Gaming Consolidators: The Magnificent Seven Post-M&A Rush
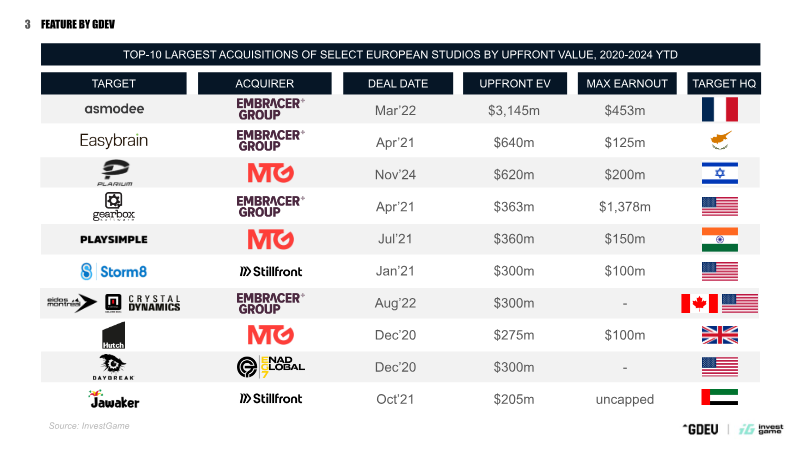
The analysis examines the surge of M&A activity among European gaming publishers between 2020 and 2024, highlighting a capital deployment of $19 billion across more than 140 deals.
- Between 2020 and 2024, seven major European gaming consolidators deployed $19 billion across over 140 deals, with mienn Easybrain Group accounting for 78 deals totaling $14.1 billion.
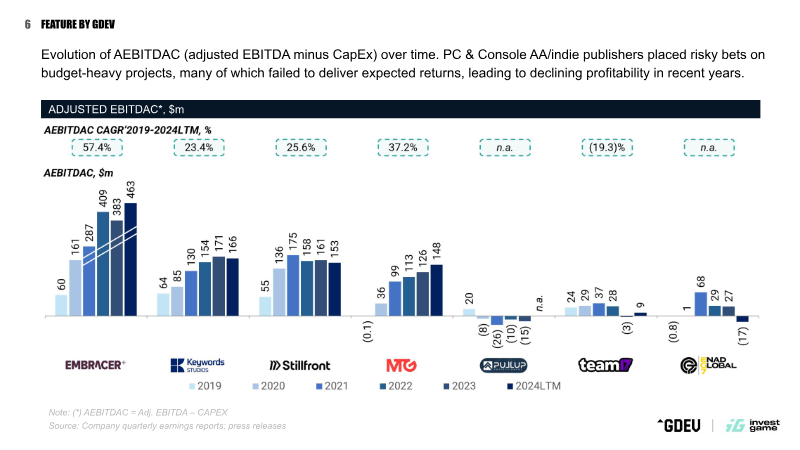
- Aggressive inorganic growth strategies failed to deliver sustainable shareholder value, as evidenced by a market cap collapse from a $25.5 billion peak in April 2021 to approximately $5.4 billion.
- Share prices for the primary acquirers corrected significantly, falling 30–70% from December 2019 levels as valuation multiples contracted from highs of 30× EV/NTM revenue.
The Rise of the Financial Kingmakers: Private Equity’s $21B+ Bet on Gaming
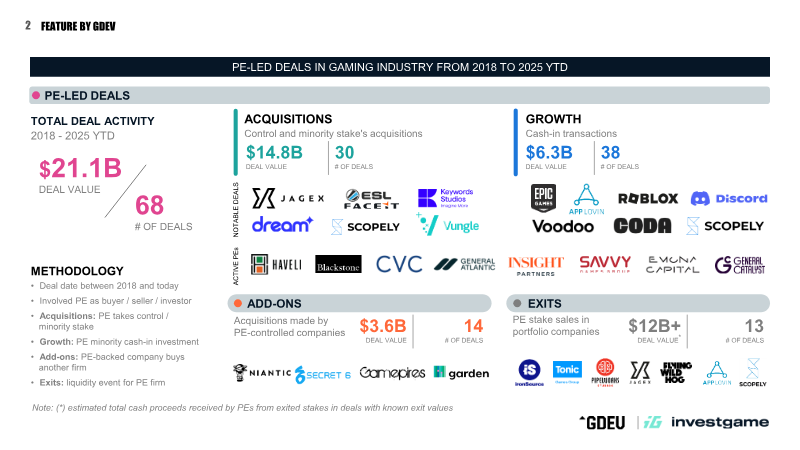
The analysis demonstrates that private equity (PE) has increasingly positioned itself as a decisive force in the gaming sector, channeling more than $21 billion into acquisitions and growth investments from 2018 through the first half of 2025.
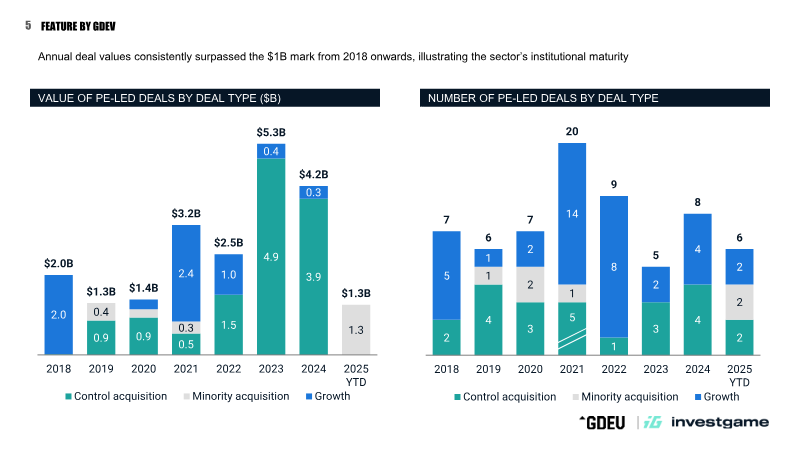
- Private equity firms deployed over $21 billion into the gaming sector between 2018 and mid-2025, with annual deal values consistently surpassing $1 billion.
- Control acquisitions represent the primary investment strategy, accounting for approximately 60% of total capital deployed in the sector.
- Content creation studios holding strong IP portfolios are the most targeted assets, securing 42 of the 68 total private equity-led deals identified.
The Take-Two Diaspora: Why Alumni Win Big in Mobile, Not AAA
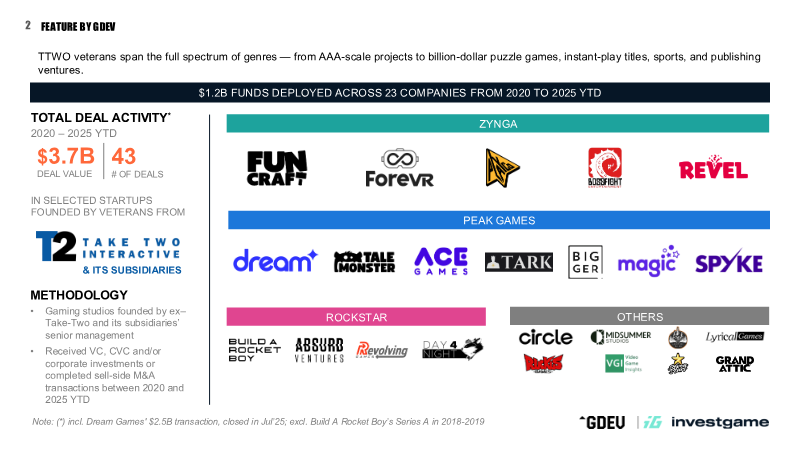
The analysis examines the investment trajectory of companies founded by former senior executives from Take-Two Interactive and its subsidiaries.
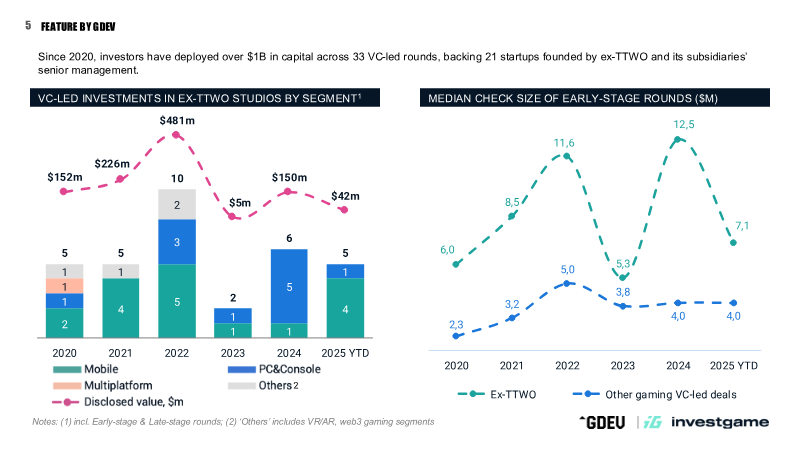
- Former Take-Two senior executives founded 23 startups between 2020 and 2025, securing $1.2 billion in capital across 43 deals.
- Dream Games, a prominent alumni-led studio, achieved a $2.5 billion exit in July 2025, highlighting the high valuation potential of these ventures.
- Alumni-led firms significantly outperform industry benchmarks, with a 60% rate of raising a second funding round within one year compared to the 20% industry average.
Beyond the Game: How Gamification is Becoming Mainstream
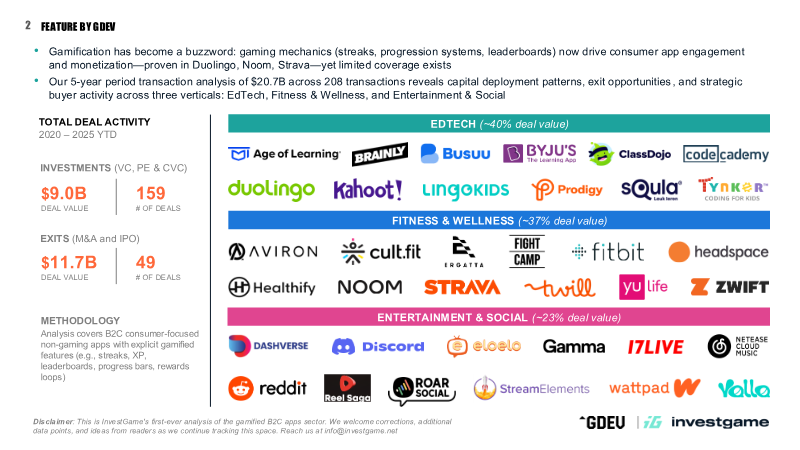
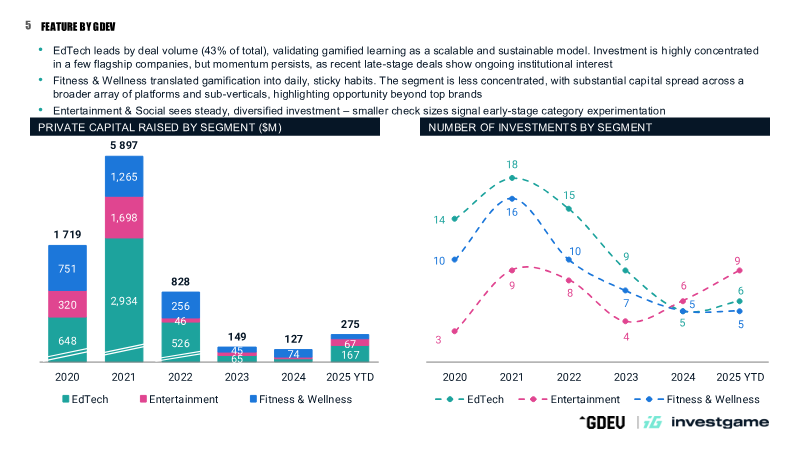
The analysis examines how gamification—applying game-like mechanics such as streaks, leaderboards, and reward loops—to non-gaming consumer apps has shifted the mobile app economy over a five-year period (2020-2025).
- Gamified non-gaming apps have surpassed mobile games in net revenue, generating $21.2 billion in Q2 2025 compared to $19.8 billion for games.
- Gamified apps are driving a 24% year-over-year growth in mobile consumer spending, while traditional mobile gaming revenue has stagnated.
- EdTech, Fitness & Wellness, and Entertainment & Social account for $20.7 billion in transaction value, with EdTech dominating deal volume (43%) and exit activity (45%).
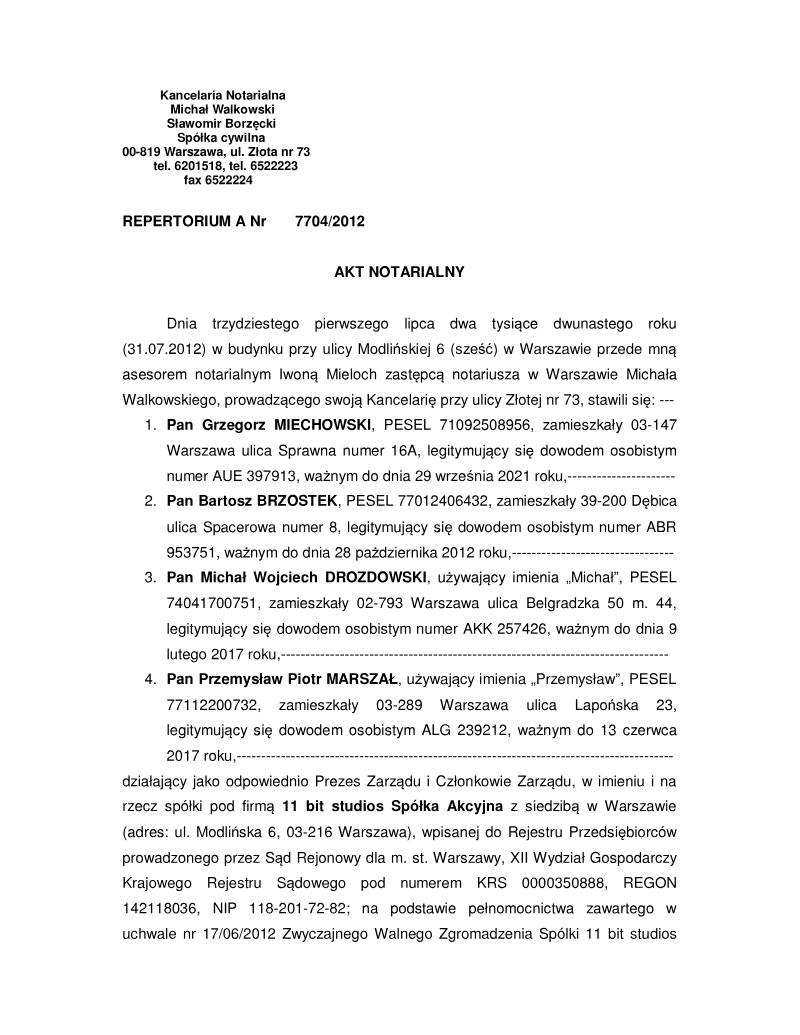
Dookreślenie kapitału — seria E
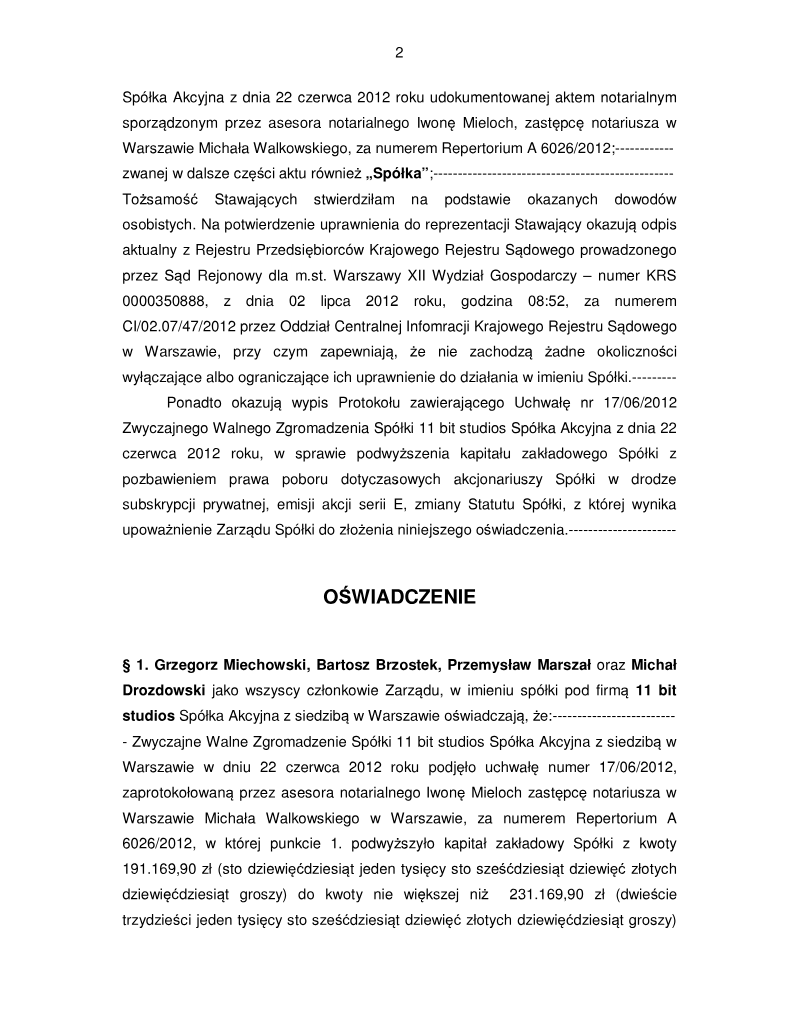
The document records a notarial act concerning the capital increase of 11 bit studios Spółka Akcyjna, a Warsaw-based video game developer.
- 11 bit studios S.A. increased its share capital in 2012 from PLN 191,169.90 to PLN 221,719.90.
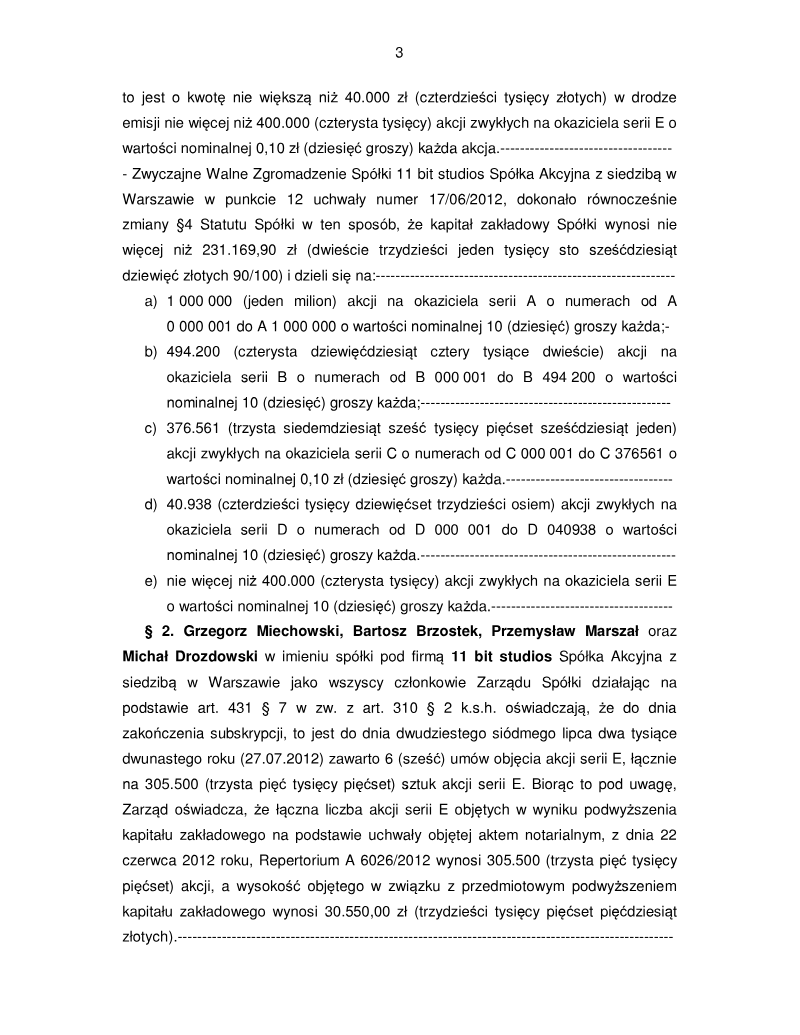
- The capital increase was achieved through the issuance of 305,500 new Series E ordinary shares with a nominal value of PLN 0.10 each.
- Subscription agreements for the 305,500 Series E shares were finalized by 27 July 2012, resulting in a total subscription value of PLN 30,550.00.
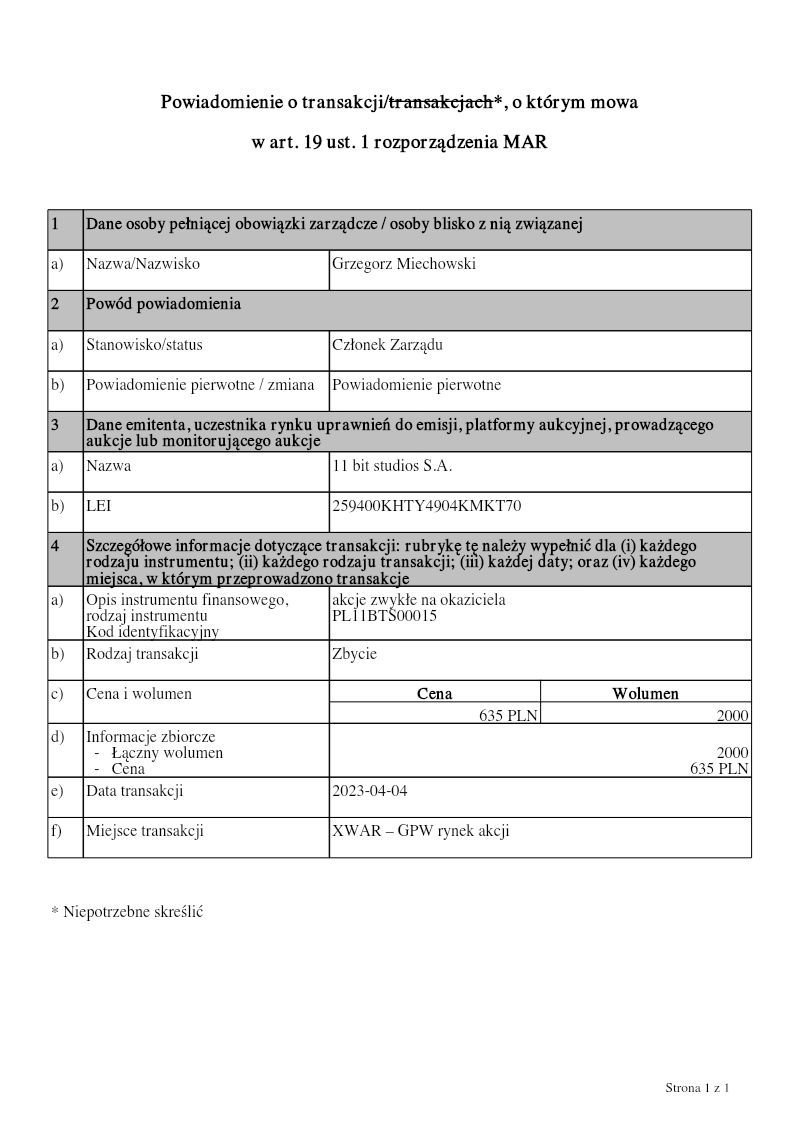
Powiadomienie o transakcji: Grzegorz Miechowski (04.04.2023)
The notification reports a transaction involving Grzegorz Miechowski, who holds the position of board member at 11 bit studios S.A.
- Grzegorz Miechowski, a board member at 11 bit studios S.A., sold 2,000 ordinary bearer shares on April 4, 2023.
- The shares were sold at a price of 635 PLN per share on the Warsaw Stock Exchange.
- The total gross value of the transaction amounted to 1,270,000 PLN.