Mergers & Acquisitions reports and market data
Documents
Video Games Market Update: Spring 2024
The global video game industry demonstrated significant resilience in 2023, returning to a growth trajectory fueled by improved hardware availability, a robust slate of high-profile releases, and the continued maturation of subscription and live service business models.
- The global video game market is projected to exceed $200 billion in total value by 2026, supported by a player base expected to reach nearly four billion individuals.
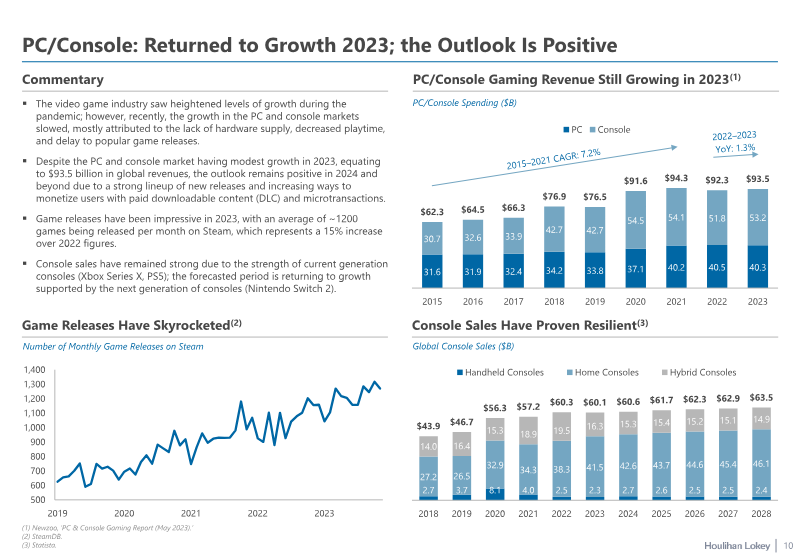
- PC and console segments generated $93.5 billion in 2023, outperforming traditional entertainment sectors like theatrical box office and video streaming.
- Market conditions are primed for a rebound in mergers, acquisitions, and investment throughout 2024 as industry valuations stabilize.
From Volatility to Stability: Q3 2024 Gaming Deals Report
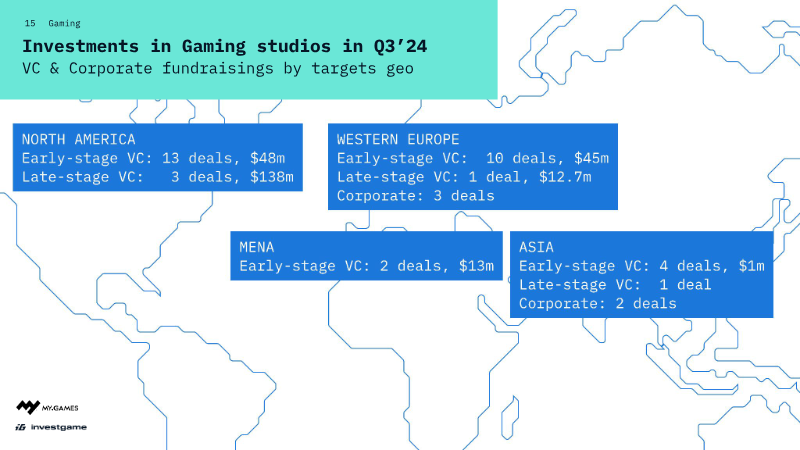
The third quarter of 2024 marks a period of stabilization for the global gaming industry, signaling a transition from post-pandemic volatility toward a new, normalized market environment.
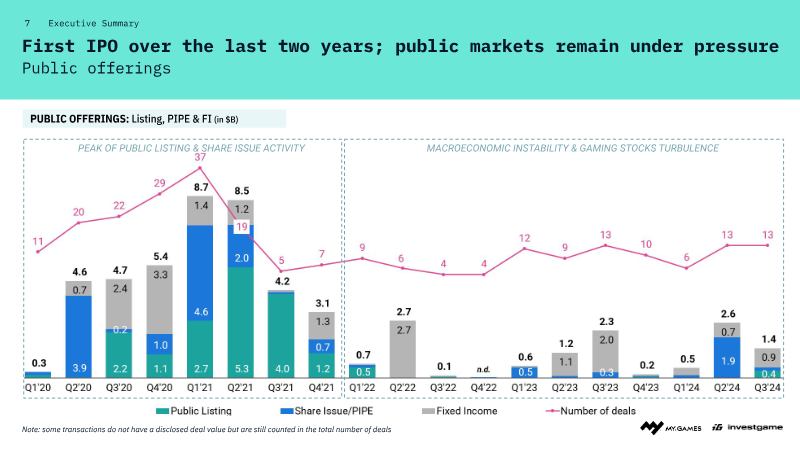
- The gaming industry has transitioned to a normalized market environment, with Q3 2024 private investment totaling approximately $1 billion across 120 rounds.
- AA and indie publishers are outperforming the broader market, driving a 35% year-over-year growth in gross revenue while AAA titles remain stagnant.
- Investor capital is shifting away from traditional content toward infrastructure, payment systems, and development tools.
Global MSP Report
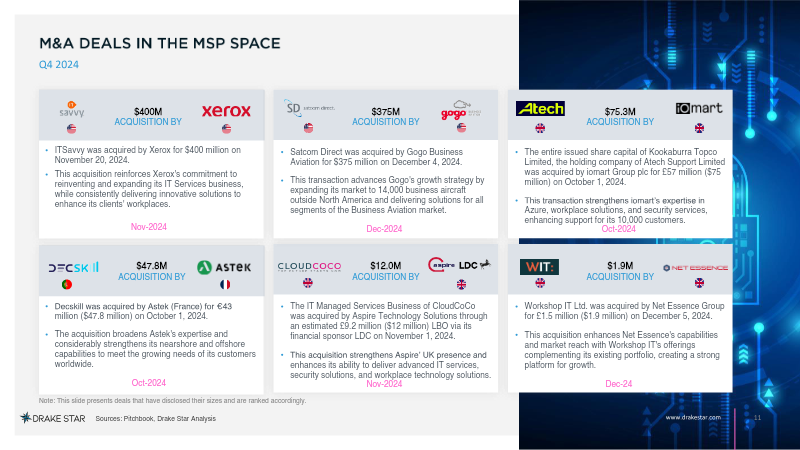
The Global MSP Report presents a comprehensive analysis of the managed services provider (MSP) market, focusing on transaction activity, valuation trends, and strategic consolidation across the United States and Europe.
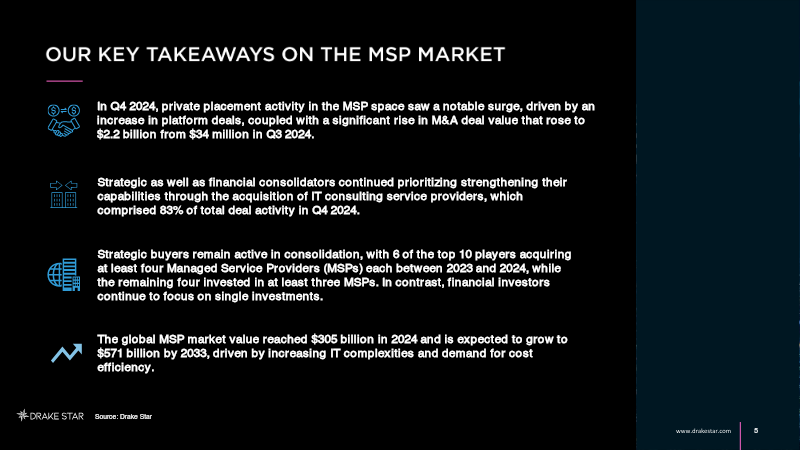
- The global MSP market reached a valuation of $305 billion in 2024 and is projected to grow at a 7.2% CAGR to $571 billion by 2033.
- Private-placement deal value surged from $34 million in Q3 2024 to $2.2 billion in Q4 2024, driven by a high volume of platform deals.
- Strategic buyers dominated Q4 2024 activity, accounting for 83% of total transactions as they aggressively acquired multiple MSPs.
Digital Services Report
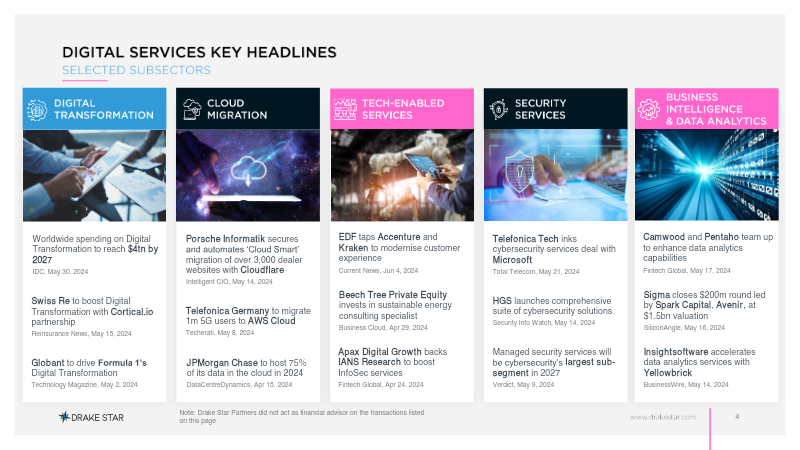
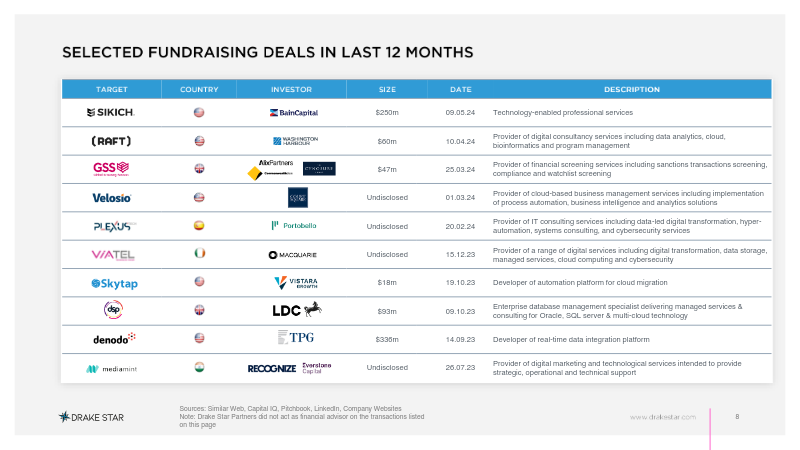
The quarterly Digital Services Report presents a comprehensive snapshot of the global digital services landscape for Q2 2024, focusing on mergers and acquisitions, fundraising activity, market trends, and key performance indicators across technology-enabled services.
- Q2 2024 saw robust activity in the digital services sector with over 350 M&A transactions totaling $7.4 billion and 880 fundraising deals raising $8.1 billion.
- Major M&A activity was headlined by EQT’s $3.0 billion acquisition of Perficient and Cognizant’s $1.3 billion purchase of Belcan, signaling a strategic focus on digital transformation capabilities.
- Generative AI and AI-powered technologies are identified as the primary catalysts for deal momentum, with expectations for increased M&A activity in Q3 2024.
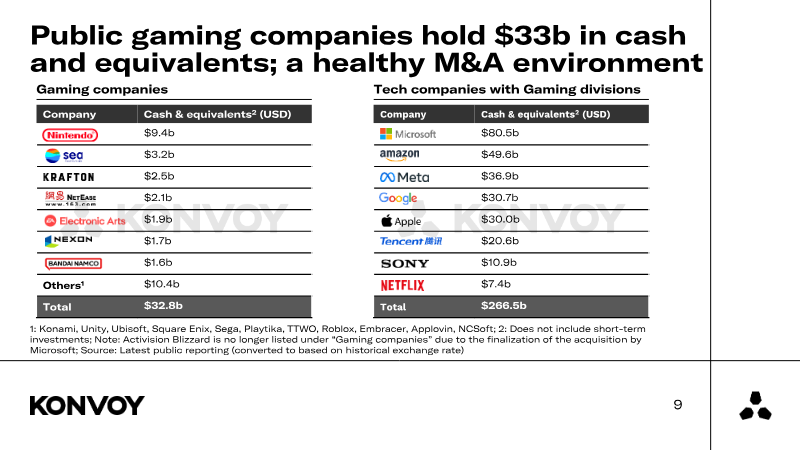
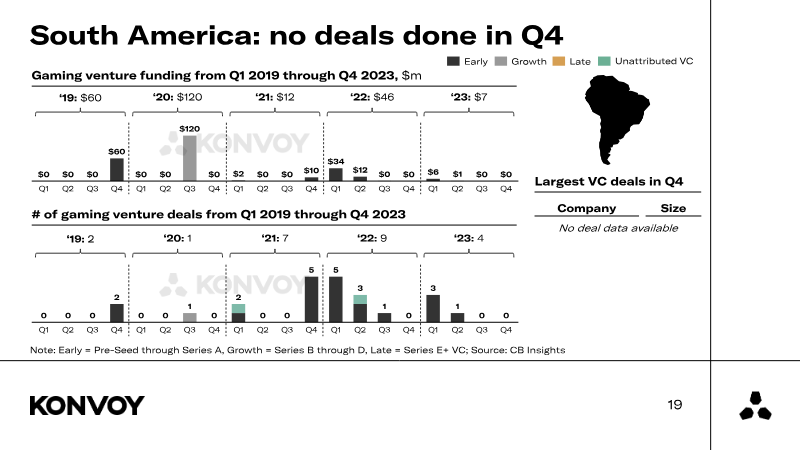
Gaming Industry Report: Q4 2023
The global gaming industry reached a market valuation of $184 billion in 2023, representing a modest year-over-year growth of 0.6%.
- The global gaming industry reached a $184 billion valuation in 2023, reflecting a modest year-over-year growth of 0.6%.
- Venture funding for the gaming sector dropped 33% quarter-over-quarter in Q4 2023 to $308 million, signaling a return to pre-pandemic capital levels.
- Approximately 10,500 industry layoffs occurred in 2023 as companies prioritized operational efficiency, asset consolidation, and high-retention projects.
Global Sports Tech Report 2024
I’m ready to craft a comprehensive synthesis, but I’ll need the remaining section summaries to capture the full scope, findings, and conclusions of the Global Sports Tech Report 2024.
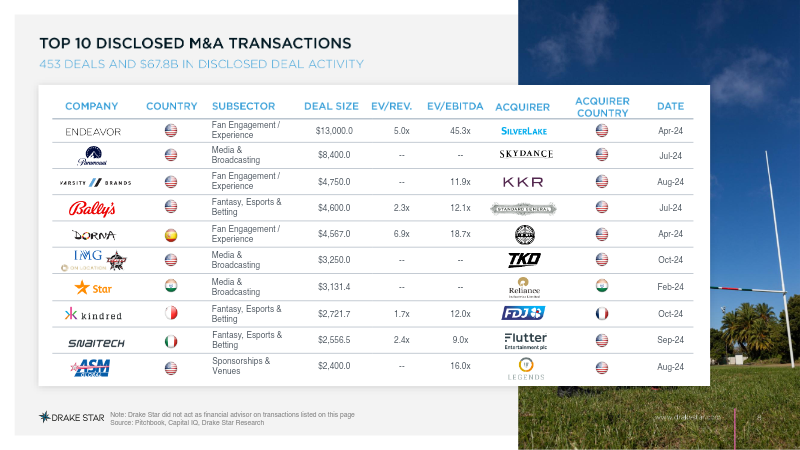
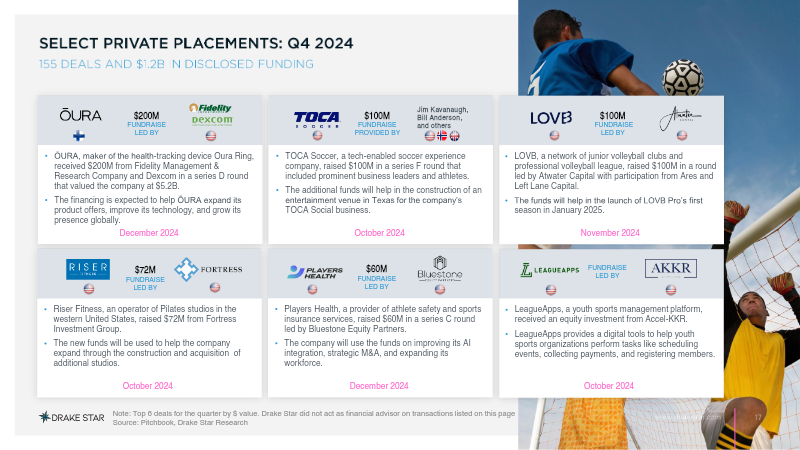
- The sports tech sector saw record deal-making in 2024, with $86 billion in total deal value across 1,152 deals, including 18 M&A deals over $1 billion and 17 financings over $50 million, and over $6 billion raised by new funds.
- Public markets experienced a rebound in investor confidence, evidenced by a wave of debt refinancings (e.g., Liberty Media, Peloton, Flutter) and follow-on equity rounds (e.g., Liberty Media, Amer Sports), with Canal+ spinning off from Vivendi to list on the LSE.
- Major acquisitions in 2024 included Silverlake's $13 billion acquisition of Endeavor, KKR's $4.75 billion acquisition of Varsity Brands, and Standard General's $4.6 billion acquisition of Bally's Fantasy, Esports & Betting.
State of the Game Industry 2024
The global game industry entered 2024 in a state of profound volatility, defined by a painful market correction following post-pandemic overexpansion.
- The industry is undergoing a severe market correction characterized by widespread layoffs affecting one-third of the global workforce and a surge in studio closures.
- Support for unionization has reached 57%, driven largely by younger professionals (ages 18–24) facing economic instability and dissatisfaction with corporate management.
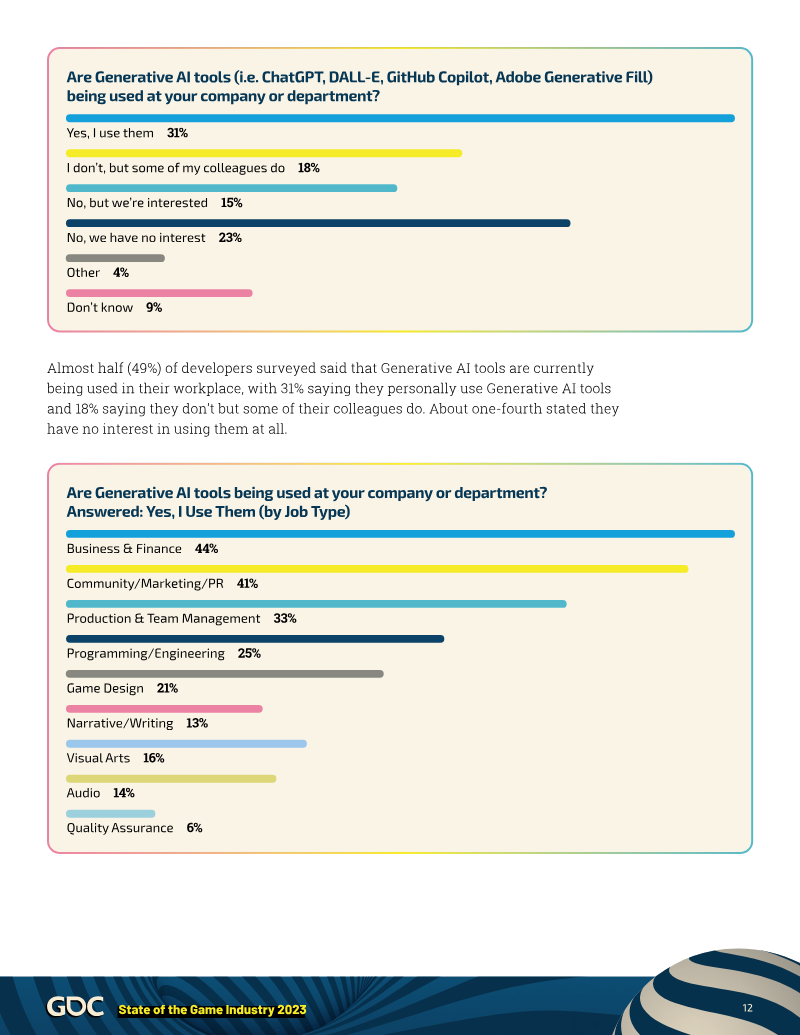
- While 49% of developers have adopted generative AI, 84% of the workforce reports significant concerns regarding copyright infringement and potential job displacement.
Nuverse Winds Down / Shrapnel Lawsuit / Business Of Gaming Awards
The global gaming industry underwent a profound structural reset in 2023, characterized by a transition from the unsustainable growth of the post-pandemic era toward a focus on operational efficiency and fiscal discipline.
- The gaming industry underwent a structural reset in 2023, shifting from post-pandemic growth to a focus on fiscal discipline and operational efficiency due to high interest rates and increased capital costs.
- ByteDance’s decision to wind down its Nuverse gaming subsidiary demonstrates that massive capital backing is insufficient to guarantee scale in a hit-driven market.
- High-quality, single-player AAA titles like Baldur’s Gate 3 and The Legend of Zelda successfully challenged the industry's long-standing reliance on live-service models.
Savvy Games Group’s Ambition, Strategy, and Future
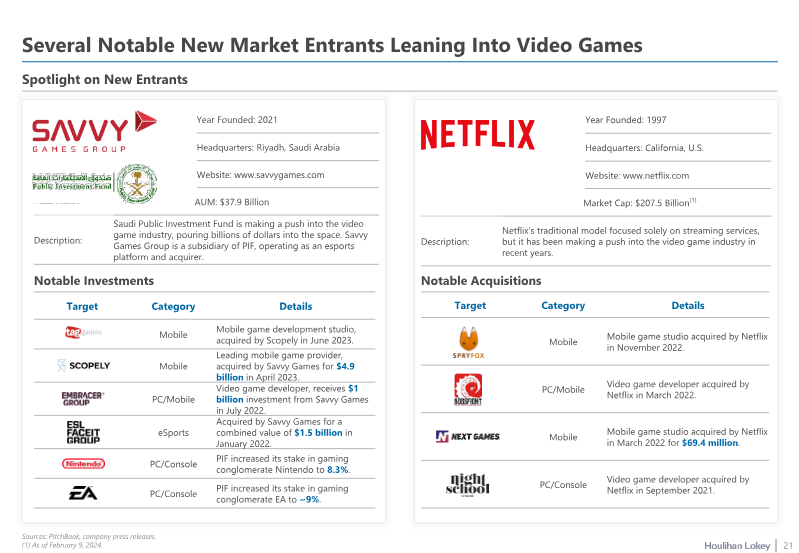
Savvy Games Group functions as a central pillar of Saudi Arabia’s Vision 2030, aiming to establish the Kingdom as a premier global hub for gaming and esports by 2033.
- Savvy Games Group aims to establish Saudi Arabia as a global gaming and esports hub by 2033 as a core component of the Vision 2030 initiative.
- The organization is executing a strategy to create 39,000 domestic jobs and develop a self-sustaining gaming infrastructure through internal studios like Steer Studios and the 966 entity.
- The group utilizes a decentralized management model that grants acquired studios, such as Scopely, creative autonomy while providing the capital necessary for long-term growth.
Bungie Layoffs / Live-Action Zelda / Epic v Google / FC 24 Sales
The gaming industry is currently navigating a period of significant structural adjustment, characterized by a shift away from hyper-casual mobile models toward sustainable, long-term engagement strategies.
- Bungie implemented layoffs following a 45% revenue shortfall in Destiny 2, highlighting the financial instability of relying on a single aging live-service title.
- EA successfully transitioned its football franchise away from the FIFA brand, retaining 14.5 million active accounts by prioritizing gameplay quality and existing licensing agreements.
- Epic Games achieved record-breaking engagement by leveraging nostalgia through Fortnite’s 'OG' season, signaling a shift toward using the Unreal Editor for user-generated content to reduce internal development overhead.
M&A Master Class: Chris Petrovic Teaches Acquiring Great Gaming Companies
Mergers and acquisitions in the gaming industry serve as critical mechanisms for scaling operations, acquiring specialized talent, and integrating innovative research and development.
- Successful M&A in gaming requires a clear strategy focused on long-term value creation through 'forever franchises' rather than short-term financial engineering.
- The industry is trending toward a conglomerate model similar to major entertainment studios, where large entities manage diverse portfolios of specialized developers to maximize cross-platform IP.
- To preserve the creative momentum that makes a studio valuable, acquirers should utilize an 'opt-in' integration strategy that maintains operational autonomy while providing access to centralized resources.
Why Is Gaming Spend Not Up More? / M&A and Funding Trends / Earnings Season Begins
The gaming industry is currently navigating a period of stagnation characterized by a complex interplay of macroeconomic pressures and structural shifts.
- Gaming content spending in the U.S. is down 6% to 7% from 2021 levels when adjusted for inflation, despite a nominal year-to-date increase of 2%.
- M&A deal volume has plummeted by 60% year-over-year, reflecting a broader retreat of investment activity to pre-pandemic levels.
- Funding is heavily skewed toward early-stage ventures, with 85% of current deals concentrated in pre-seed and seed rounds, leaving late-stage studios facing down-rounds or closure.