Market Forecast reports and market data
Documents
Web3 Gaming: What Will 2025 Bring?
The web3 gaming industry enters 2025 transitioning from a period of speculative volatility toward a focus on sustainable development and product quality.
- The web3 gaming funding landscape remains cautious, with 2024 seeing a 17% increase in investment rounds compared to 2023, though total capital remains significantly lower than the 2021-2022 peaks and is characterized by smaller, more conservative bets.
- AAA studios are currently prioritizing risk mitigation by focusing on established IP and smaller, internal studio experiments rather than large-scale web3 integration, waiting for a proven, scalable business model to emerge from smaller developers.
- Off the Grid has emerged as a critical industry benchmark for quality in web3 gaming, though its long-term success remains tied to whether its optional, tokenized economy features actually improve the core gameplay experience.
The Game Development Renaissance
The global game development industry is undergoing a fundamental transition toward a more sustainable and efficient operational model, moving away from volatile hiring cycles in favor of long-term stability.
- The global game development market is projected to reach $190 billion by 2025, with 77% of developers anticipating continued industry growth and reduced workforce instability.
- Studios are shifting toward leaner production models by outsourcing non-core technical infrastructure, with only 6% of developers planning to rely on internal builds by 2025.
- Nearly 50% of developers plan to integrate specialized third-party tools to manage complex requirements like cross-platform synchronization and unified player inventories.
TWIG #314 Market Predictions, Nintendo Leaks and an Award Ceremony
The gaming industry is currently navigating a period of significant volatility, characterized by a stark contrast between high-stakes venture capital activity and widespread operational instability.
- The gaming industry is experiencing a bifurcated market where speculative capital continues to flow into Web3 and metaverse projects, exemplified by Infinite Reality’s $12.3 billion valuation, despite widespread operational instability and layoffs throughout 2024.
- Success in the hero shooter genre is increasingly dependent on high-frequency content cadences, as demonstrated by Marvel Rivals successfully challenging established titles like Overwatch and Apex Legends.
- Major industry players such as Ubisoft and Embracer Group are undergoing significant reputational and operational damage, signaling a broader market rejection of unsustainable growth models and massive corporate restructuring.
Week in Mobile Games E41 - How Scopely made $10bn, and 2025's big stories to watch
The mobile gaming industry is currently defined by a tension between established giants achieving record-breaking scale and a volatile market environment that demands constant innovation.
- Scopely reached $10 billion in lifetime revenue, a milestone driven by the seven-year development cycle and strategic refinement of Monopoly Go.
- Established intellectual property remains a primary monetization driver, evidenced by Pokémon Trading Card Game Pocket generating $400 million in its first ten weeks.
- Major gameplay overhauls can drive significant revenue spikes, as seen with Zenless Zone Zero reaching $8.6 million in daily revenue following content updates.
The Truth About Gaming's Crisis: 2024 Recap & 2025 Predictions
The global gaming industry is currently navigating a profound transition from an era of unchecked expansion to a period defined by operational efficiency and fiscal discipline.
- The gaming industry is shifting from an era of unchecked expansion to fiscal discipline, evidenced by the fact that only 15 percent of Steam playtime in 2024 was dedicated to new releases.
- Chinese developers are successfully capturing Western market share by leveraging sophisticated, quasi-social gaming platforms and high-end production capabilities, putting pressure on established giants like Microsoft, Ubisoft, and Unity.
- Generative AI is transitioning from a simple production assistant to a foundational element of game design and live-ops, which is expected to significantly lower development costs by 2025.
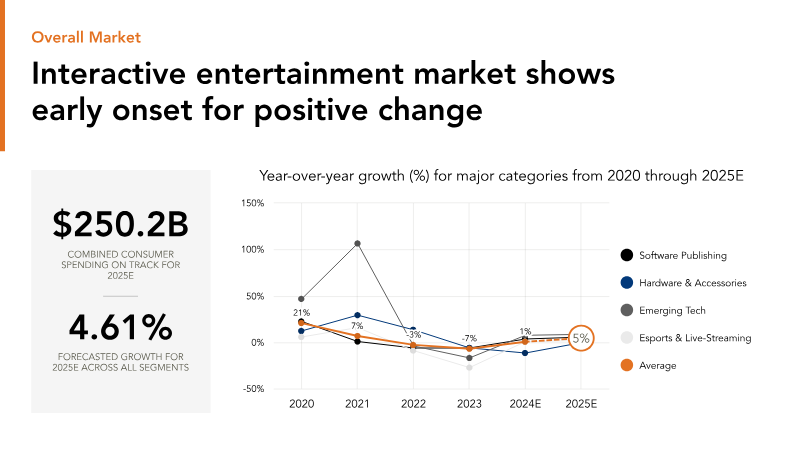
Interactive Entertainment: Global Market Sizing & Forecast 2025
The global interactive entertainment market is poised for a recovery in 2025, with total consumer spending projected to reach $250.2 billion, representing a 4.6% year-over-year growth.
- The global interactive entertainment market is projected to reach $250.2 billion in 2025, marking a 4.6% year-over-year recovery.
- Software publishing remains the dominant revenue driver at $196 billion, with mobile gaming leading the sector at $115.7 billion despite rising user acquisition costs.
- The console hardware sector is in a significant downturn, evidenced by a 31% decline in revenue during 2024 as the current cycle concludes.
The State of Video Gaming: 2025
The global video game industry is currently undergoing a structural correction following a decade of rapid expansion that concluded in 2021.
- The video game industry is undergoing a structural correction characterized by a 12% decline in real-term content spending following the post-2021 plateau of previous growth engines.
- Market polarization has intensified as AAA production budgets reach $500 million, causing revenue and engagement to concentrate within established franchises while crowding out new releases.
- Chinese developers have significantly expanded their global footprint, increasing their share of non-domestic content spending from 0.5% to 12.5% over the last 13 years.


China Game Industry Report 2025
The China Game Industry Report for 2025 presents a comprehensive assessment of the domestic and overseas gaming markets, highlighting sustained growth driven by youth protection initiatives, technological innovation, and cross-sector integration.
- Chinese self-developed mobile games generated US$20.455 billion in overseas revenue in 2025, marking a 10.23% year-on-year increase and the sixth consecutive year exceeding RMB 100 billion.
- The United States remains the primary overseas market for Chinese games, accounting for 32.31% of total export revenue, followed by Japan at 16.35% and South Korea at 9.15%.
- Strategy games (SLG) dominate the overseas market, capturing 49.97% of earnings, significantly outpacing shooters at 9.69% and RPGs at 9.39%.
Games 2025: The Industry Quest for Growth
The global games market reached a record $199.4 billion in 2024, cementing its status as the preeminent force in the entertainment sector.
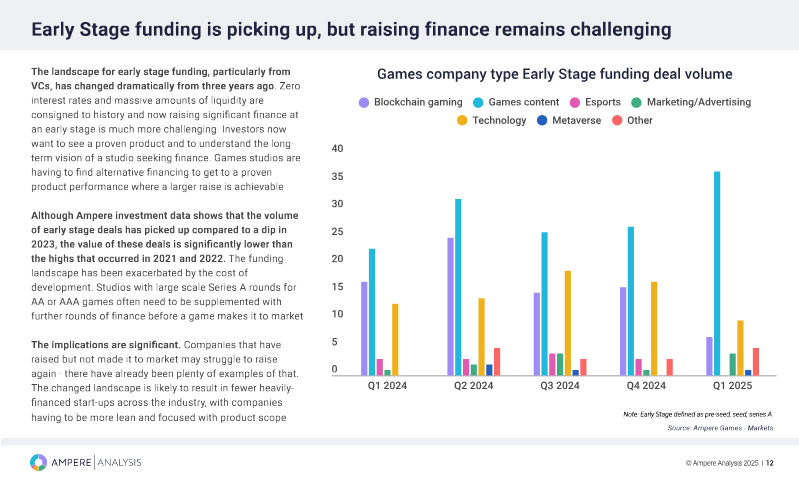
- The global games market reached $199.4 billion in 2024, but growth is projected to decelerate to approximately 1% in 2025 due to release delays and reduced early-stage funding.
- Publishers are prioritizing operational efficiency and asset optimization, focusing on remakes, remasters, and multi-platform porting to mitigate the rising costs of AAA development.
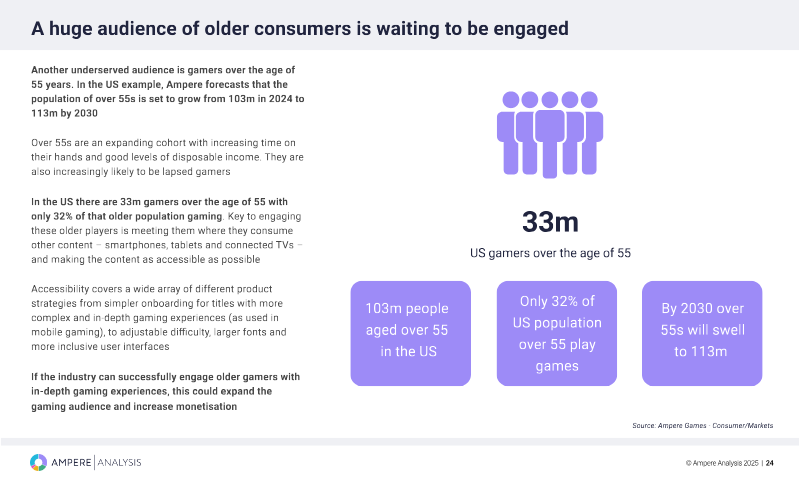
- Strategic growth is shifting toward geographic expansion in the Middle East and Southeast Asia, alongside targeting underserved demographics like older gamers and young adult females.
Africa Games Industry Report 2025
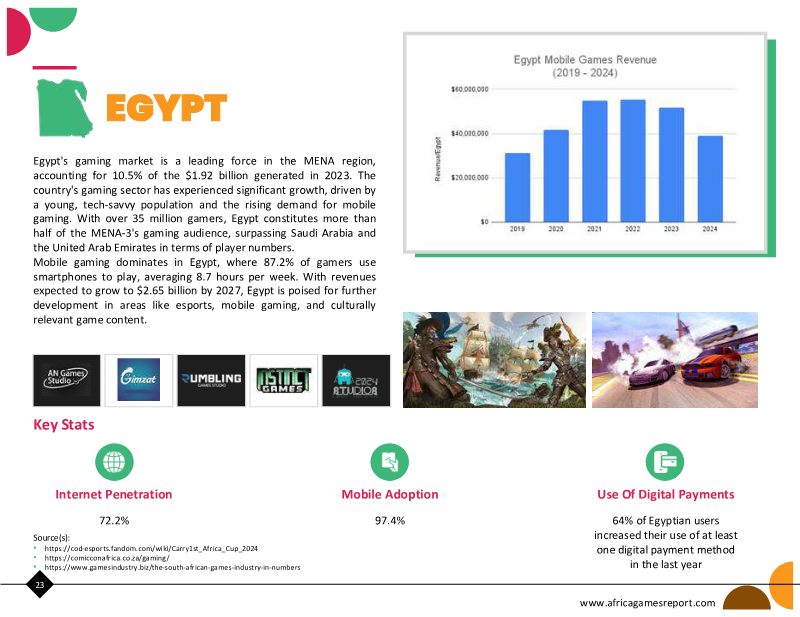
The African games industry is undergoing a period of rapid expansion, with total revenues projected to surpass $1 billion in 2024.
- The African games industry is projected to exceed $1 billion in revenue in 2024, driven by a mobile-first market that generates nearly 90% of total sector earnings.
- Nigeria has shown the most significant momentum in the region, with mobile revenues increasing fivefold since 2019, while South Africa remains the most lucrative individual market.
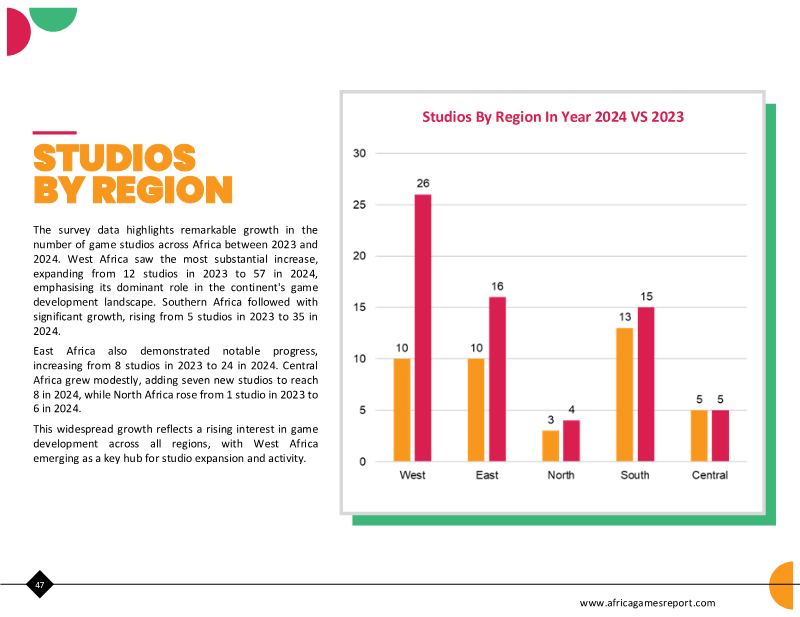
- The developer ecosystem has grown to approximately 250 studios by 2024, with West Africa emerging as the primary hub after a fivefold increase in active studios over the past year.
Gaming 2025 (Epyllion)
The global gaming industry has entered a period of structural stagnation following a decade of rapid expansion that concluded in 2021.
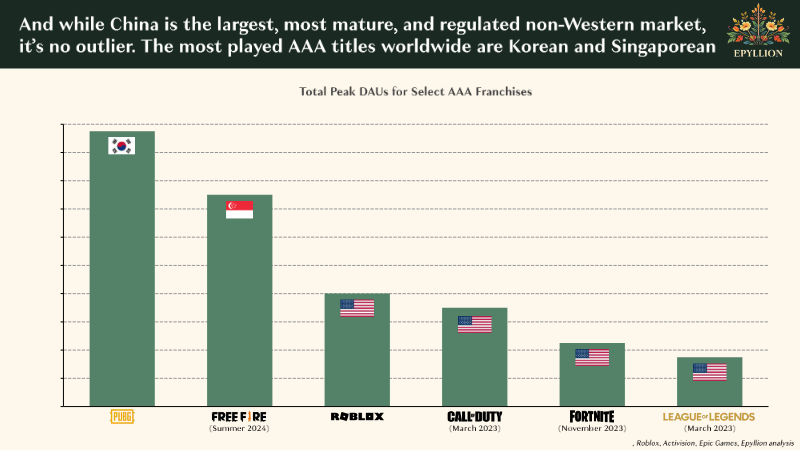
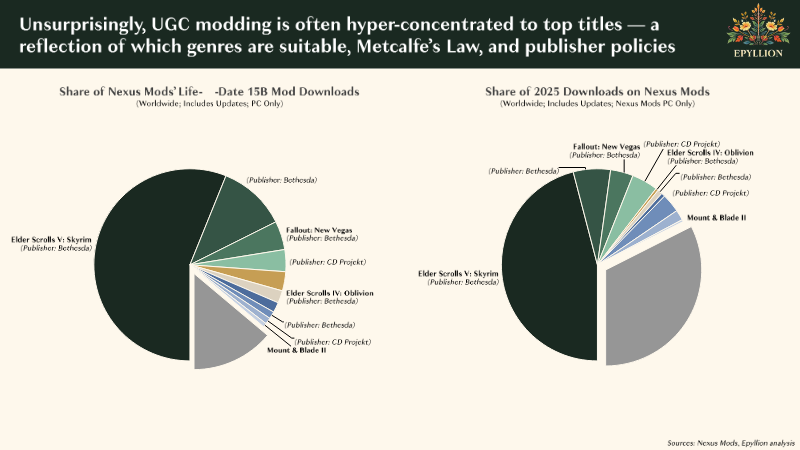
- The industry has shifted to a zero-sum environment where the top ten titles now capture 60% of all sales, forcing publishers to prioritize established franchises over new, risky ventures.
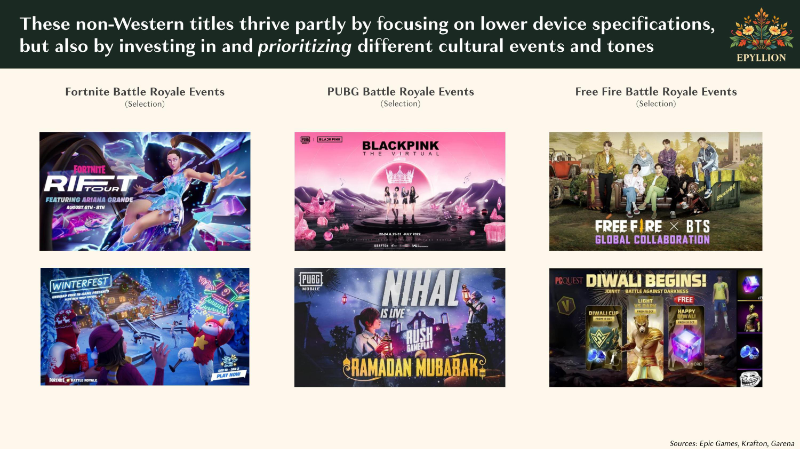
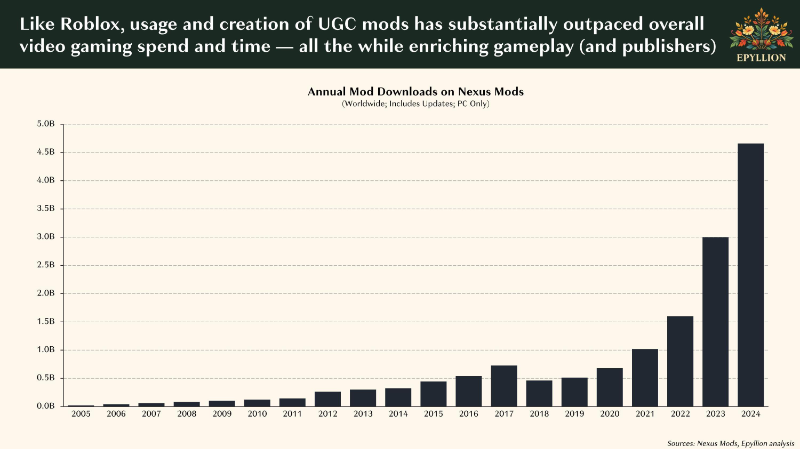
- Market dominance is increasingly concentrated in 'Black Hole' titles and UGC platforms like Roblox and Fortnite, which utilize deep social integration to create high consumer lock-in.
- Future revenue growth is shifting toward programmatic in-game advertising and the deregulation of mobile app stores, which is projected to improve developer margins by 10–20%.
MiDiA Research Global Games Forecasts 2025–2031
The global games market has transitioned into a phase of structural maturity, with 2025 revenues projected at $236.9 billion.
- The global games market is entering a phase of structural maturity with 2025 revenues projected at $236.9 billion, representing a 4.6% year-on-year increase that is effectively flat when adjusted for inflation.
- In-game spending remains the dominant revenue driver at 69% of the market, though the industry is shifting toward premium full-game purchases and the expansion of intellectual property into film and television.
- The global player base is forecast to reach 4.02 billion by 2031, with long-term growth increasingly reliant on strategic price adjustments and regional expansion rather than rapid user acquisition.