Report55 pages
Xsolla Report: State of Play – Winter 2024 Edition
The global gaming industry is currently navigating a period of stabilization following a massive 26% growth surge between 2019 and 2021. While the rapid pandemic-era expansion has moderated, the sector reached $106.8 billion in 2023 and is on a trajectory to hit $205.7 billion by 2026. This growth is underpinned by a global player base expanding to 3.79 billion people, with mobile gaming remaining the dominant force, accounting for nearly half of all consumer spending. Despite a downward revision in year-over-year growth forecasts to 0.6%, mobile spending is expected to reach $111.4 billion in 2024, led by strong performance in the United States and Japan.
The industry is undergoing a significant structural transformation driven by technological shifts and regulatory changes. The transition toward digital-only monetization, cloud-based services, and the metaverse—projected to reach $996 billion by 2030—reflects a broader convergence with the entertainment landscape. Furthermore, the implementation of the Digital Markets Act is opening doors for alternative billing systems and direct-to-consumer web stores. These shifts occur alongside a demographic evolution where women now represent nearly 50% of the player base, though they remain underrepresented in executive and professional roles.
Financial dynamics within the sector show a complex landscape of consolidation and rising costs. While AAA development budgets have tripled over the last five years, the investment market has faced volatility, characterized by a cooling M&A environment and significant layoffs. Despite a drop in deal volume, strategic investment value surged by 577% in mid-2023, reaching $7 billion in a single quarter. To counter high user acquisition costs and stricter privacy regulations, developers are increasingly adopting generative AI for efficiency and pivoting toward community-focused organic reach, early access models, and influencer partnerships to ensure long-term sustainability.
- The global gaming industry is projected to grow from $106.8 billion in 2023 to $205.7 billion by 2026, supported by a total player base of 3.79 billion people.
- Mobile gaming remains the industry's primary revenue driver, accounting for nearly 50% of total consumer spending and reaching a projected $111.4 billion in 2024.
- Strategic investment value saw a massive 577% surge in mid-2023 to reach $7 billion in a single quarter, despite an overall cooling in M&A activity and a volatile investment climate.
- The metaverse is projected to reach a valuation of $996 billion by 2030 as the industry shifts toward digital-only monetization and cloud-based services.
- Regulatory changes like the Digital Markets Act are forcing a structural shift toward alternative billing systems and direct-to-consumer web stores to bypass traditional platform constraints.
+1
XsollaJan 2024
Report6 pages
The Alumni Effect: A Deep Dive into Studios Founded by Ex-Rioters
The emergence of startups founded by former Riot Games employees represents a significant sub-sector of the venture capital landscape in gaming. Since 2020, investors have funneled nearly $500 million into 27 startups led by these alumni across 38 funding rounds. These founders command a substantial premium in the market, with an average round size of $11 million, which is 53% higher than the $7 million average seen across the broader gaming startup ecosystem.
The investment data reveals a high level of confidence from specialized venture capital firms, with Andreessen Horowitz (a16z Games) and Bitkraft Ventures leading the activity. These firms have participated in deals valued at $339.3 million and $236.3 million respectively. Furthermore, ex-Riot teams demonstrate superior fundraising momentum compared to the general market. A significantly higher percentage of these studios successfully secure follow-on financing within two to three years of their initial rounds, whereas the broader gaming market sees a much sharper decline in subsequent funding success over the same period.
While capital infusion is high, the majority of these ventures are currently in the pre-release phase. Out of 27 identified startups, only six have released products to date. The most well-funded projects include Theorycraft’s Supervoke, Believer’s unannounced AAA title, and Singularity 6’s Palia. The scope of these projects primarily focuses on high-ambition genres such as multiplayer RPGs, extraction MOBAs, and backend infrastructure. This trend underscores a strategic focus on complex, scalable platforms that mirror the live-service expertise associated with the founders' professional origins.
- Startups founded by former Riot Games employees have raised nearly $500 million across 27 companies since 2020.
- Ex-Riot founders command a 53% premium in average round size, securing $11 million per round compared to the $7 million industry average.
- Venture capital firms Andreessen Horowitz and Bitkraft Ventures are the primary backers, participating in deals worth $339.3 million and $236.3 million respectively.
- Alumni-led studios demonstrate superior fundraising momentum, with a higher rate of success in securing follow-on financing within two to three years compared to the broader gaming market.
- Despite significant capital infusion, only six of the 27 identified startups have released products to date.
+1
InvestGameJan 2024
Report76 pages
Game Developer Index: Sweden 2024
The analysis evaluates the health and trajectory of Sweden’s video‑game sector during 2023‑24, mapping its economic performance, creative output, ecosystem structure and emerging challenges. By quantifying sales, employment, investment and cultural impact, it argues that the industry remains a growth engine for the Swedish economy while confronting structural constraints that could limit future expansion.
Domestic net sales rose 6 % to SEK 34.6 billion (≈ EUR 3 billion, USD 3.2 billion) and total global revenue reached SEK 90.4 billion, a 4.5 % increase. The number of registered firms grew by 108 to 1,010, and Swedish‑owned companies expanded overseas to 218 subsidiaries in 54 countries, employing 15,792 staff abroad, of whom 29.5 % are women. Major titles such as Helldivers 2 (12 million copies in three months) and Satisfactory (6 million copies and a console launch) reinforced Sweden’s market presence, while Steam and Twitch data showed Swedish games accounting for over 700 million streamed hours in 2023 and nearly 500 million from January‑October 2024.
The ecosystem is heavily concentrated in Stockholm, home to 439 studios and 5,816 employees, with secondary hubs in Skåne‑Blekinge, Västra Götaland, Västerbotten‑Norrbotten and Östergötland. Educational provision spans bachelor, master and vocational programmes, serving roughly 700 students across multiple institutions. Inclusion initiatives have broadened participation, exemplified by a game‑developer camp for about 100 gender‑diverse teens and a network of scholarships and mentorships. Nevertheless, early‑stage capital has weakened, talent pipelines remain thin—with only 644 new hires in 2023 and rising work‑permit refusals—and public‑health screen‑time guidance remains ambiguous.
Capital flows revived in 2023‑24, highlighted by Embracer’s SEK 4.9 billion sale of Gearbox to Take‑Two and EQT’s SEK 28.7 billion acquisition of
- Sweden’s video-game sector grew to SEK 90.4 billion in total global revenue in 2023-24, a 4.5% increase, while domestic net sales rose 6% to SEK 34.6 billion.
- The industry’s footprint expanded to 1,010 registered firms, with Swedish-owned companies now operating 218 subsidiaries across 54 countries and employing 15,792 staff abroad.
- Major commercial successes like 'Helldivers 2', which sold 12 million copies in three months, and 'Satisfactory', which reached 6 million copies, drove significant market presence and over 700 million streamed hours in 2023.
- Capital activity remains robust, evidenced by major transactions including EQT’s SEK 28.7 billion acquisition and Embracer’s SEK 4.9 billion sale of Gearbox to Take-Two.
- Stockholm remains the primary industry hub with 439 studios and 5,816 employees, though the ecosystem faces structural challenges including a thin talent pipeline, with only 644 new hires in 2023, and rising work-permit refusals.
Swedish Games IndustryJan 2024
Report15 pages
Interactive Entertainment 2025: Global Market Sizing & Forecast
The interactive entertainment market is projected to reach $250.2 billion in consumer spending by 2025, representing a 4.6% year-over-year growth. This recovery follows a period of transition characterized by a significant cyclical downturn in console hardware, which is expected to decline by 31% in 2024 as the industry prepares for next-generation devices. The analysis covers global consumer spending across software publishing, hardware, emerging technology, and live-streaming segments for the period spanning 2023 through 2025.
Software publishing remains the primary market driver, with mobile gaming leading as the largest category, forecasted to reach $115.7 billion in 2025. While PC gaming shows the strongest growth rate at 8.1% for 2025, console software spending is also expected to rise in anticipation of new hardware cycles. In contrast, the esports and live-streaming sectors face ongoing profitability challenges; esports revenue is projected to decline by 8.3% in 2025, while streaming platforms struggle with high operational costs despite modest growth in user engagement.
Emerging technologies, including virtual reality and blockchain gaming, are identified as latent disruptors fueled by venture capital and platform investments. Virtual reality is expected to grow by 11% in 2025, supported by new hardware like the Apple Vision Pro. Additionally, the market is seeing a strategic shift as major entertainment firms like Sony and Disney evolve into all-round media conglomerates, leveraging established intellectual property across games, film, and virtual storefronts in platforms like Roblox to reach new audiences. Data for these findings is derived from company financials and a proprietary partner network tracking over 200 consumer brands.
- The global interactive entertainment market is projected to reach $250.2 billion in consumer spending by 2025, marking a 4.6% year-over-year growth.
- Mobile gaming remains the industry's largest segment, with forecasted consumer spending of $115.7 billion in 2025.
- Console hardware is experiencing a significant cyclical downturn, with spending expected to decline by 31% in 2024 ahead of next-generation device launches.
- PC gaming is the fastest-growing software segment, projected to achieve an 8.1% growth rate in 2025.
- Esports revenue is facing a downturn, with a projected decline of 8.3% in 2025 due to ongoing profitability challenges.
+3
AldoraJan 2024
Report111 pages
Annual Universe of Positive Gaming Experiences 2024
Stillfront Group’s 2024 fiscal year marks a pivotal transition into a synergy-driven operational phase, characterized by a major geographic reorganization into Europe, North America, and MENA & APAC business areas. This strategic shift aims to drive efficiency and mitigate a 2% organic revenue decline, which resulted in total net revenues of 6,737 MSEK. The financial year was defined by a significant net loss of 7,378 MSEK, primarily driven by a 6.9 billion SEK goodwill impairment in the North American segment due to lower-than-expected growth. Despite these non-cash charges, the group maintained a resilient financial foundation, generating over 1 billion SEK in free cash flow and improving gross margins to 80% through successful direct-to-consumer initiatives.
The group’s portfolio remains focused on free-to-play franchises, with North America and Europe accounting for 71% of player bookings. To reduce dependency on third-party platforms, which still facilitate 54% of revenue, management is prioritizing its internal payment systems and the "Stillops" platform for cost optimization. A comprehensive cost-savings program is underway, targeting up to 250 MSEK in annual savings by late 2025. Leadership has also stabilized under a new CEO and a board that remains fully compliant with the Swedish Code of Corporate Governance, focusing on organic growth and franchise scaling over dividend distributions.
Sustainability and governance have been deeply integrated into the corporate strategy in preparation for the EU’s Corporate Sustainability Reporting Directive. The group achieved Science Based Targets initiative validation, reducing market-based greenhouse gas emissions by 7% and more than doubling its renewable energy share to 37%. While social metrics show a stable workforce with improved turnover rates and high data security standards, challenges remain in gender diversity at the executive level. Executive remuneration is now tied to long-term sustainability targets, including employee satisfaction and data privacy, ensuring that environmental and social governance remains central to the group’s long-term value creation.
- Stillfront Group reported a net loss of 7,378 MSEK for fiscal year 2024, largely driven by a 6.9 billion SEK goodwill impairment in its North American segment.
- Total net revenues reached 6,737 MSEK, reflecting a 2% organic revenue decline that prompted a major geographic reorganization into Europe, North America, and MENA & APAC.
- Despite the net loss, the company generated over 1 billion SEK in free cash flow and improved gross margins to 80% through direct-to-consumer initiatives.
- Management is executing a cost-savings program targeting 250 MSEK in annual savings by late 2025 while prioritizing internal payment systems to reduce reliance on third-party platforms, which currently account for 54% of revenue.
- The company is shifting focus toward organic growth and franchise scaling, with 71% of player bookings currently concentrated in North America and Europe.
+1
StillfrontJan 2024
Report11 pages
Supercharged: Powering the Future of the UK Video Game and Interactive Entertainment Industry
The new five‑year strategy and action plan sets out a comprehensive roadmap for the UK video‑games and interactive‑entertainment sector, positioning it as the world’s leading hub for new intellectual property and innovation by 2030. Its core thesis is that sustained growth, enhanced global perception, and a resilient, diverse talent pipeline will secure the industry’s long‑term economic and cultural impact. The plan outlines four strategic priorities—transforming public and media perceptions, building a pro‑games policy agenda, cultivating a highly skilled and inclusive workforce, and strengthening businesses through targeted support.
Key initiatives include three flagship campaigns: energising industry to turn innovative stories into globally successful IPs, empowering talent by nurturing creators and entrepreneurs, and elevating games to showcase British‑made titles as forces for good. The 2024‑25 action schedule launches a coordinated PR strategy, high‑impact partnerships with cultural and digital brands, and an evidence‑led lobbying effort aimed at more competitive tax reliefs, increased investment, and the introduction of a Digital Creativity GCSE. A new research and evidence base will underpin policy advocacy, while a sector‑wide skills network and the refreshed #RaiseTheGame programme will drive diversity, equity, and inclusion across the talent pipeline.
The plan also commits to environmental responsibility through participation in the Playing for the Planet Alliance and internal sustainability measures. Supporting stronger businesses will involve a refreshed membership strategy, expansion of the Ukie Worldwide platform for trade and investment, and the continuation of the Video Games Growth Programme. By inviting industry stakeholders to engage through surveys, working groups, mentorship, and board participation, the strategy seeks broad collaboration to deliver its ambitious objectives across the UK’s mobile, console, core and casual game segments throughout the 2024‑2030 horizon.
- The UK video game industry has launched a five-year strategy aiming to establish the nation as the global leader in intellectual property and innovation by 2030.
- The 2024-25 action plan prioritizes lobbying for more competitive tax reliefs, increased investment, and the introduction of a Digital Creativity GCSE.
- Strategic efforts to strengthen the workforce include the expansion of the #RaiseTheGame diversity, equity, and inclusion programme and the creation of a sector-wide skills network.
- Business growth initiatives include the expansion of the Ukie Worldwide trade platform and the continuation of the Video Games Growth Programme.
- The industry is formalizing its commitment to environmental sustainability through participation in the Playing for the Planet Alliance.
+1
UkieJan 2024
Report72 pages
Serbian Gaming Industry Report 2023
The 2023 Serbian gaming industry assessment quantifies the sector’s rapid expansion, maps its ecosystem, and evaluates the conditions shaping future growth. Drawing on a 97‑question survey that reached 80 % of the domestic ecosystem and validated financial data for the 21 leading firms, the analysis establishes a clear upward trajectory for Serbia’s game development landscape.
Total industry revenue reached €175 million, a 17 % year‑on‑year increase, while the workforce nearly doubled to roughly 4,300 professionals. The market now hosts 38 active studios producing 81 titles, with mobile‑first games still dominant but ceding share to core and original‑IP projects. Talent inflows from Russia, Ukraine and Belarus, together with 70 % of respondents expressing optimism, underpin this momentum, and a quarter of companies are planning foreign offices despite lingering concerns over tax incentives and regulatory red tape.
The ecosystem comprises more than 140 companies and over 500 regional stakeholders, featuring high‑profile successes such as Foxy Voxel’s “Going Medieval” (850 k+ copies), GameBiz Consulting’s $250 million revenue from 80+ global studios, Onyx Studio’s 57 million monthly players, and Sozap’s NASDAQ listing with 30 million downloads. Collaborative ties with DICE/EA, Microsoft, Google and Epic Games, alongside mentoring programmes, Gamescom exposure, and the Shift2Games and Playing Narratives initiatives, reinforce Serbia’s emergence as a European development hub. At the same time, the rollout of generative‑AI tools raises IP, privacy and deep‑fake risks, prompting EU‑wide regulatory scrutiny.
Overall, the sector is maturing into a diversified, internationally connected hub with strong growth prospects. Realising its potential will require addressing regulatory and fiscal barriers, leveraging AI responsibly, and sustaining education and mentorship programmes that nurture talent and support SMEs in scaling their operations.
- The Serbian gaming industry generated €175 million in revenue in 2023, marking a 17% year-on-year increase.
- The sector's workforce nearly doubled to approximately 4,300 professionals, supported by talent inflows from Russia, Ukraine, and Belarus.
- The ecosystem now includes 38 active studios producing 81 titles, with a strategic shift occurring from mobile-first games toward core and original-IP projects.
- High-profile industry successes include Foxy Voxel’s 'Going Medieval' (850k+ copies), Onyx Studio’s 57 million monthly players, and Sozap’s NASDAQ listing.
- Serbia has established strong collaborative ties with major global players including DICE/EA, Microsoft, Google, and Epic Games.
+1
SGAJan 2024
Report2 pages
Comportamientos e Intereses de los Videojugadores: Spain
The study investigates how Spanish video‑game players experience play, what motivates them, and which social and cognitive benefits they perceive. It situates Spain within a broader cross‑national analysis that also includes Poland, South Korea and Australia, focusing on active gamers who play at least once a week.
Data were collected through an online questionnaire administered to 12,847 weekly players across the four markets, of which 1,139 respondents were from Spain. The sample spans ages 16 to 65 plus and includes both genders, allowing comparison of habits and attitudes between men and women and across age brackets.
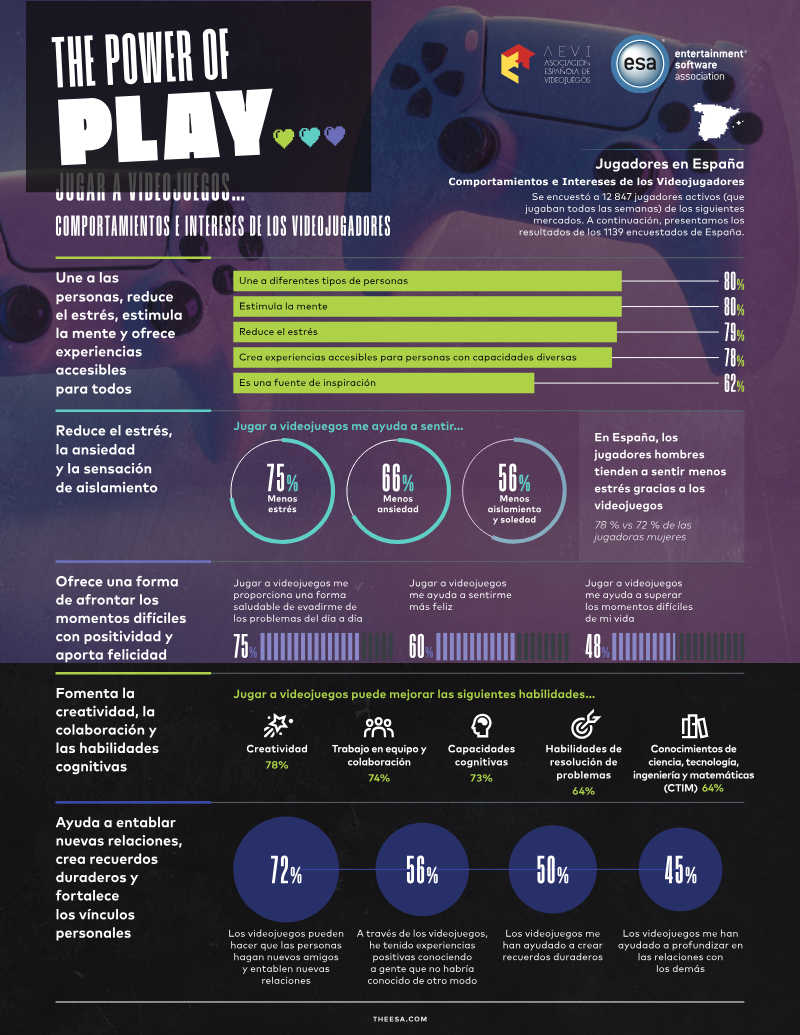
Among Spanish gamers, 80 % cite “meeting different people” and “stimulating the mind” as primary reasons for playing, while 78 % report that games help reduce stress and anxiety. Men are slightly more likely than women to feel less isolated (78 % vs 72 %) and to use gaming as a healthy outlet for daily pressures (75 % of men versus 60 % of women). Solo play remains the most common mode, yet eight out of ten men regularly play with others online, and roughly half of all respondents combine solo and online sessions.
Social interaction is linked to perceived skill gains: 78 % associate multiplayer play with enhanced creativity, 74 % with teamwork, and 64 % with improved cognitive and STEM‑related abilities. Integrated communication tools are used frequently by 29 % of younger male players, while 55 % of all participants view playing with others—whether online or in person—as a positive experience that fosters lasting friendships and shared memories.
Overall, Spanish gamers view video games as a versatile medium that delivers entertainment, mental‑health relief, social connection and transferable competencies, underscoring the sector’s relevance for both consumer satisfaction and broader wellbeing initiatives.
- 80% of Spanish gamers play primarily to meet new people and stimulate their minds, while 78% use gaming as a tool to reduce stress and anxiety.
- Multiplayer gaming is perceived as a driver for skill development, with 78% of players associating it with creativity, 74% with teamwork, and 64% with improved cognitive and STEM-related abilities.
- Social gaming is a core habit, as 55% of all participants view playing with others as a positive experience that fosters lasting friendships and shared memories.
- While solo play remains the most common mode, 80% of male gamers play online with others regularly, and roughly 50% of all respondents combine solo and online sessions.
- Gender differences exist in perceived benefits, with men more likely than women to report feeling less isolated (78% vs 72%) and using gaming as a healthy outlet for daily pressure (75% vs 60%).
+1
AEVIJan 2024
Report26 pages
Manifiesto de Video Games Europe 2024-2029
The European video‑game sector seeks recognition as a distinct blend of technology and creative culture and urges policymakers to embed this identity in the EU’s 2024‑2029 strategic framework. By positioning games as a driver of digital innovation, cultural expression, and economic growth, the manifesto argues that tailored legislation, financing, and data‑collection mechanisms are essential to sustain the industry’s momentum and competitiveness.
Between 2019 and 2024 the sector expanded by 16 %, reaching €24 billion in revenue and employing roughly 110 000 highly‑skilled workers across the Union. More than half of Europeans (53 %) now play games, with women accounting for 46.7 % of the audience and the average gamer aged 32. Research indicates that girls who game are three times more likely to pursue STEM studies, underscoring the medium’s educational impact. The self‑regulatory PEGI system, which has labelled over 40 000 titles in 40 countries, has cut non‑compliant sales by up to 50 %, demonstrating effective consumer protection without heavy legislative burden.
Current EU financing tools—tax credits and grants—are deemed insufficient to match the incentives offered by hubs such as Canada, the United Kingdom and France. The manifesto calls for a dedicated funding framework that channels public resources toward innovative, creative projects, alongside flexible talent‑attraction visas and Horizon‑funded labour‑market mapping to close digital‑skills gaps. It also highlights the strain of 850 new obligations introduced between 2017 and 2022, amounting to more than 5 000 pages of regulation, which increase compliance costs for developers and publishers.
To solidify the sector’s contribution, a unified intellectual‑property regime and a revision of NACE classification codes are proposed, enabling accurate economic measurement. Mandatory PEGI‑based age controls, parental‑lock tools and proactive chat moderation address the 53 % of Europeans prioritising child‑friendly environments. Finally, the industry’s low‑carbon digital products and initiatives such as “Playing for the Planet” and “Green Game Jam” are presented as foundations for a climate‑responsible future, aligning gaming with
- The European video game sector generated €24 billion in revenue between 2019 and 2024, representing a 16% growth rate and supporting 110,000 highly-skilled jobs.
- The industry faces a significant regulatory burden, having been subjected to 850 new obligations and over 5,000 pages of legislation between 2017 and 2022.
- Current EU financing tools are insufficient to compete with global hubs like Canada and the UK, prompting calls for a dedicated funding framework and improved tax incentives.
- The PEGI self-regulatory system has successfully labeled over 40,000 titles across 40 countries, reducing non-compliant sales by up to 50%.
- Video games have reached 53% of the European population, with a demographic split of 46.7% women and an average player age of 32.
+1
AEVIJan 2024
Report13 pages
Video Games Europe Manifesto 2024-2029
Europe’s video‑game sector has expanded by 16 % between 2019 and 2024, now delivering €24 billion in revenue and employing roughly 110 000 highly‑skilled workers. More than half of the continent’s gamers are under 20 years old, and nearly half of parents rely on the PEGI age‑rating system to ensure safe play. The industry’s dual nature—combining advanced technology with creative content—underpins a call for EU‑level measures that preserve an open, tax‑free single market, extend the Creative Europe programme, apply the General Exemption Regulation to games, and reinforce intellectual‑property protection while investing in digital‑skill education, particularly STEM pathways for girls.
The PEGI framework, supported by co‑regulation, has already classified around 40 000 titles across 40 European countries, halving non‑compliance penalties and cutting energy‑consumption violations by roughly 20 %. Nevertheless, the sector faces a regulatory load of 850 new EU obligations (over 5 000 pages of rules) introduced between 2017 and 2022. A shift toward transparent self‑regulation is advocated, emphasizing clearer in‑game purchase disclosures, stronger parental‑control tools, and EU‑wide educational programmes to close digital‑skills gaps and attract diverse talent.
Safety‑by‑design requirements now obligate all publishers to integrate PEGI‑based age classification, parental‑control portals, chat moderation, purchase limits and time‑spending caps, reflecting the predominance of minors among players. The climate‑and‑inclusion agenda shows progress: women represent 23.7 % of the video‑game workforce, surpassing the 17 % share in the broader ICT sector, and industry members are adopting gender‑equality guidelines and green initiatives such as the Green Game Jam. Coordinated self‑regulation, targeted public funding, and unified online‑safety strategies are presented as essential to sustain economic contribution, foster innovation, and position Europe as the leading hub for socially responsible game development.
- The European video game sector grew by 16% between 2019 and 2024, reaching €24 billion in annual revenue and employing approximately 110,000 highly-skilled workers.
- Between 2017 and 2022, the industry faced a significant regulatory burden consisting of 850 new EU obligations spanning over 5,000 pages of rules.
- The PEGI age-rating system has successfully classified 40,000 titles across 40 countries, contributing to a 50% reduction in non-compliance penalties and a 20% decrease in energy-consumption violations.
- Women currently account for 23.7% of the European video game workforce, outperforming the 17% representation found in the broader ICT sector.
- Industry stakeholders are advocating for EU-level policies that include the application of the General Exemption Regulation to games, the preservation of a tax-free single market, and the expansion of the Creative Europe programme.
+1
Video Games EuropeJan 2024
Report6 pages
2024 Professional Gamer Workforce and Career Structure in Korea
The analysis aims to map the composition, demographics, career trajectories, and income streams of South Korea’s professional e‑sports workforce, drawing on Statista surveys conducted between June and November 2024. It covers domestic players across major titles, Korean competitors active in overseas leagues, and the age, tenure, and earnings profiles of a sample of 138 active professionals, providing a snapshot of the industry’s structure during the current competitive season.
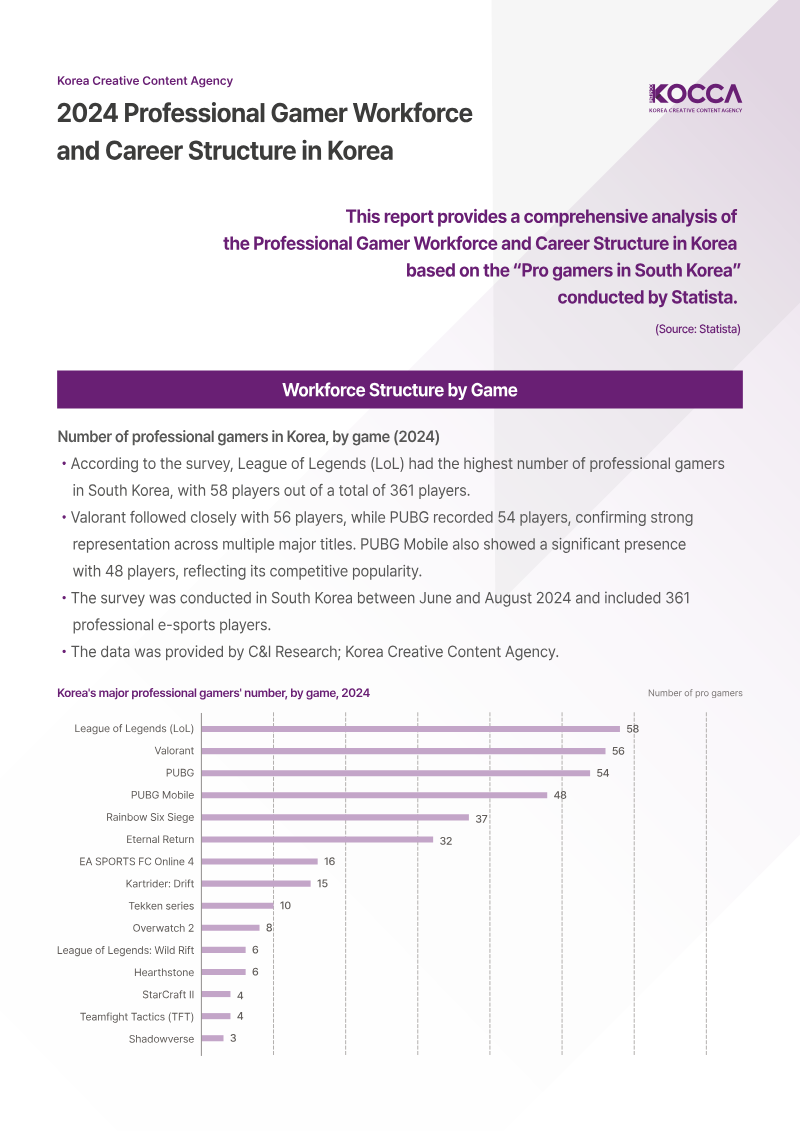
Domestic data identify 361 professional gamers, heavily clustered around four titles: League of Legends (58 players), Valorant (56), PUBG (54) and PUBG Mobile (48). Smaller but notable presences include Rainbow Six Siege (37) and Eternal Return (32). Internationally, 372 Korean e‑sports athletes were reported competing abroad, with League of Legends accounting for 169 participants and Overwatch 2 for 108, while StarCraft II, Valorant and other games each contributed fewer than 30 players.
Age distribution reveals a predominance of young adults, as 37.7 % fall within the 22‑24 year bracket, followed by 29.7 % aged 25 and older, 23.9 % aged 20‑21, and 8.7 % under 19. Career length shows a polarized pattern: 29.7 % have six or more years of experience, while the
- South Korea’s professional e-sports workforce consists of 361 domestic players and 372 athletes competing in overseas leagues.
- League of Legends is the dominant title for Korean professionals, accounting for 58 domestic players and 169 athletes competing internationally.
- The professional player base is heavily concentrated in four domestic titles: League of Legends (58), Valorant (56), PUBG (54), and PUBG Mobile (48).
- Overwatch 2 serves as the second-largest destination for Korean talent abroad, with 108 players currently competing in international leagues.
- The workforce is primarily composed of young adults, with 61.6% of professionals aged 20 to 24 and only 8.7% under the age of 19.
+2
KOCCA – Korea Creative Content AgencyJan 2024
Report5 pages
2024 Financial and Fan Support Structures in Korean eSports
The analysis examines the financial scale of Korean e‑sports organizations and the patterns of fan support, drawing on a longitudinal budget survey (2015‑2023) and two 2024 public opinion polls conducted across South Korea. It targets professional teams, the broader e‑sports audience aged ten and older, and the period from the mid‑2010s through mid‑2024, providing a comprehensive view of market growth and consumer behavior.
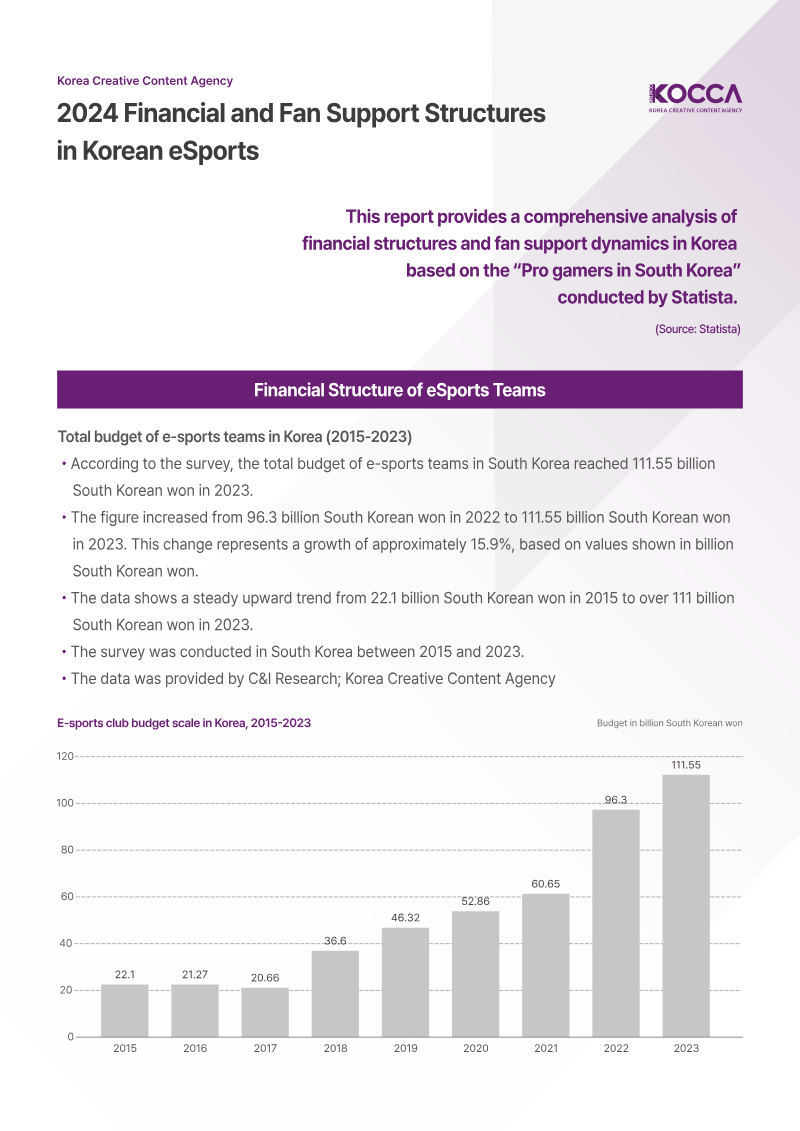
Budget data reveal a steady expansion, with total team expenditures rising from roughly 22.1 billion won in 2015 to 111.6 billion won in 2023—a near five‑fold increase over eight years. The most recent year alone saw a 15.9 % jump from 96.3 billion won in 2022, underscoring accelerating investment in the sector. These figures originate from C&I Research and are based on the Statista “Pro gamers in South Korea” survey.
Fan engagement remains modest: among 2,000 respondents surveyed between June and August 2024, only 35.3 % reported supporting a specific professional team, while 64.7 % did not align with any team. Of the 706 supporters who identified a favorite, T1 commanded an overwhelming 78.2 % share, with the runner‑up Gen.G attracting just 5.4 % and all other teams each receiving under 2 % of votes, indicating a highly concentrated fan base.
Motivational analysis shows that personal affinity for players drives support (48.6 %), followed by a positive perception of the team’s image (41.4 %). Interest in tactical or skill‑based aspects accounts for only 9.2 % of the rationale, highlighting the primacy of player appeal in shaping loyalty.
Overall, the sector demonstrates robust fiscal growth, yet the majority of the audience remains unaffiliated with specific teams, and fan allegiance is heavily skewed toward a single dominant organization. Player popularity emerges as the key lever for deepening fan commitment and expanding market participation.
- Korean e-sports team expenditures grew nearly five-fold between 2015 and 2023, rising from 22.1 billion won to 111.6 billion won.
- Market investment is accelerating, with total team spending increasing by 15.9% between 2022 and 2023 alone.
- Fan loyalty is highly concentrated, as T1 commands 78.2% of identified team supporters, while the runner-up Gen.G holds only 5.4%.
- The majority of the Korean e-sports audience remains unaligned, with 64.7% of 2024 survey respondents reporting no specific team affiliation.
- Player affinity is the primary driver of fan loyalty, accounting for 48.6% of support motivations, compared to just 9.2% for tactical or skill-based interest.
+1
KOCCA – Korea Creative Content AgencyJan 2024
Report7 pages
2024 E‑Sports Viewership and Engagement Trends in Korea
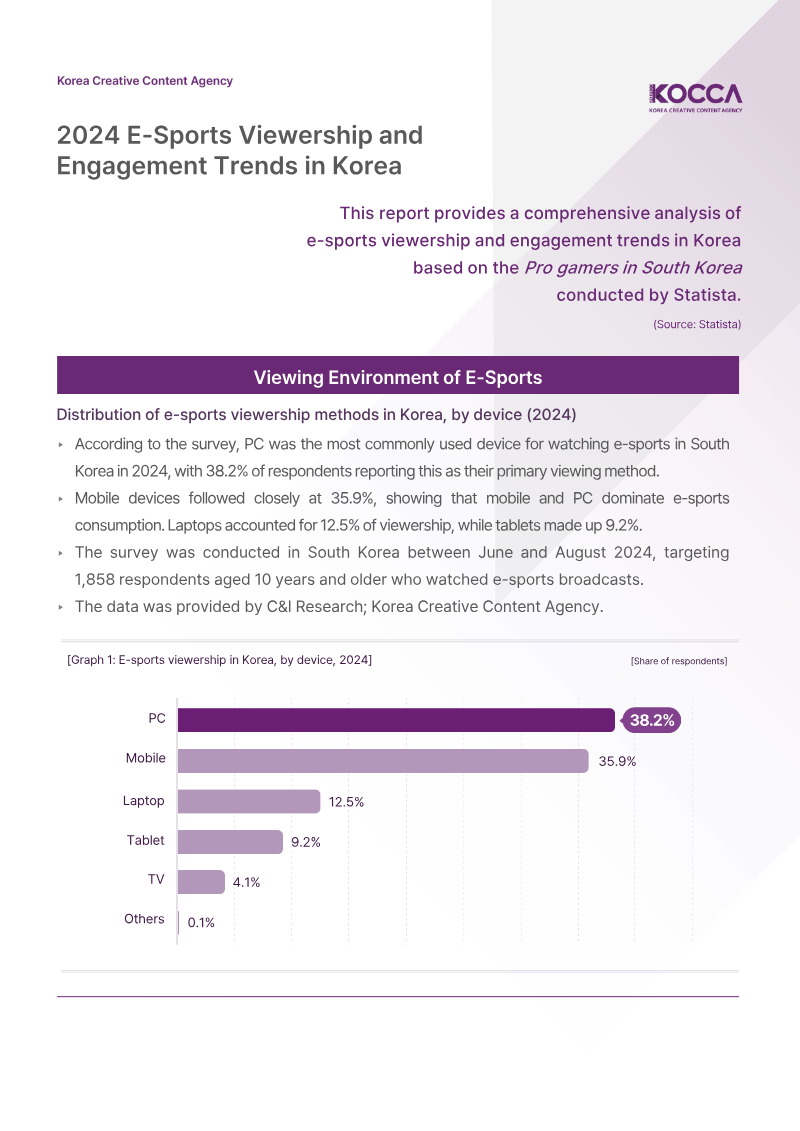
The analysis aims to map current e‑sports viewership and engagement patterns among South Korean audiences, highlighting how consumption devices, platforms, and motivations shape the market and indicating the potential for offline event conversion. Findings reveal a sharply concentrated viewing environment: personal computers account for 38.2 % of primary devices and mobile phones 35.9 %, together representing 74.1 % of usage, while laptops, tablets and televisions capture smaller shares. Platform preference is even more centralized, with YouTube commanding 78.5 % of respondents, far ahead of SOOP (14.1 %) and CHZZK (7.2 %).
Regularity of consumption is high; 38.5 % of participants watch e‑sports 1–2 times per week and 20.4 % watch 3–4 times weekly, meaning at least 58.9 % engage at least once a week. Weekday sessions cluster around one hour for the majority, whereas weekend viewing extends, with 22 % spending two hours on weekdays and 28.6 % doing so on weekends; longer sessions of five hours or more occur for 4.7 % of weekday viewers and 8.1 % of weekend viewers.
Motivational drivers are dominated by entertainment and self‑improvement: 62.1 % watch because the game is fun, 41.9 % seek to enhance their own gameplay, and 37.5 % cite stress relief. Additional reasons include boredom or free access (27.3 %), support for specific players (22.1 %), and social bonding with friends or coworkers (8.6 %).
The survey, conducted between June and August 2024, sampled 1,858 South Korean e‑sports viewers aged ten and older, with data supplied by C&I Research and the Korea Creative Content Agency. A clear majority—62.7 %—expressed willingness to attend live e‑sports events, while 26.9 % remain undecided and 10.4 %
- YouTube dominates the South Korean e-sports market with a 78.5% platform share, significantly outpacing competitors SOOP (14.1%) and CHZZK (7.2%).
- E-sports consumption is primarily mobile and desktop-driven, with PCs (38.2%) and mobile phones (35.9%) accounting for 74.1% of all viewing devices.
- Engagement is frequent and consistent, as 58.9% of viewers watch e-sports content at least once a week, with 20.4% watching 3–4 times weekly.
- Viewer motivation is driven primarily by entertainment (62.1%), gameplay improvement (41.9%), and stress relief (37.5%).
- There is strong potential for offline market growth, as 62.7% of the 1,858 surveyed viewers expressed a willingness to attend live e-sports events.
+1
KOCCA – Korea Creative Content AgencyJan 2024
Report68 pages
Spelbranschens roll i den gröna omställningen
Sweden’s gaming sector is positioned as a low‑impact yet high‑potential catalyst for the nation’s green transition. Compared with other Swedish industries and the global gaming market, the sector’s carbon emissions are modest, with the majority of resource use occurring during gameplay—a phase that remains difficult to quantify. By leveraging built‑in eco‑modes, energy consumption can fall by 20‑50 % per player, yet adoption is currently around two percent; making such modes the default could raise the estimated global saving to three percent.
The report highlights how core gaming technologies—game engines, GPUs, extended reality and artificial intelligence—are already being transferred to sectors such as infrastructure, mining and climate modelling, delivering measurable efficiency gains and emission reductions. Immersive tools like AR/VR, digital twins and AI are deployed in public‑sector pilots, including Sweco’s metaverse dialogue platform, Nacka’s “Greenovation Twin” and Vasakronan’s Twinfinity, to visualise climate impacts, streamline urban planning and cut travel‑related emissions. Hackathons and serious‑game prototypes further accelerate climate‑focused solutions, while gamified training and board‑game initiatives foster behavioural change and generate transport‑usage data.
Design guidance stresses that games must promote collective action and embed climate objectives into social norms, rather than focusing solely on individual behaviour. Educational programmes and events such as the 2023 Green Game Jam, which linked gameplay to snow‑leopard conservation and generated donation‑linked purchases, demonstrate the sector’s capacity to mobilise large audiences—evidenced by the UN‑backed “Peoples’ Climate Vote” reaching thirty million mobile users.
Collaboration across more than fifty studios
- Gaming eco-modes can reduce energy consumption by 20–50% per player, yet current adoption remains at approximately two percent.
- Making eco-modes the default setting across the global gaming industry could potentially reduce total energy consumption by three percent.
- Core gaming technologies—including game engines, GPUs, AI, and extended reality—are being applied to infrastructure, mining, and climate modeling to drive measurable efficiency gains.
- Public-sector projects like Sweco’s metaverse platform, Nacka’s “Greenovation Twin,” and Vasakronan’s Twinfinity utilize digital twins and AR/VR to streamline urban planning and reduce travel-related emissions.
- The UN-backed “Peoples’ Climate Vote” demonstrated the sector's mobilization potential by reaching thirty million mobile users.
DataspelsbranschenJan 2024
Report64 pages
The Game Industry of Finland Report 2024
The 2024 overview of Finland’s game sector presents a comprehensive assessment of an industry that remains a global technology leader while confronting a tightening financing environment. Employment reached roughly 4,300 individuals, equivalent to about 3,800 full‑time positions, underscoring the sector’s significance within the national economy. However, a pronounced drop in private risk capital and publisher backing has pushed many studios toward B2B subcontracting, co‑development agreements, and an expanding reliance on European Union and national public R&D programmes, especially after recent reductions in regional funding streams.
Talent depth continues to drive innovation, with Finnish teams at the forefront of AI‑assisted development, proprietary engines, and cloud‑gaming solutions. Persistent shortages of senior developers and specialists in Unreal Engine, together with increasing regulatory complexity and geopolitical uncertainty, pose constraints on future growth. New public R&D instruments and targeted regional SME support aim to mitigate these pressures and sustain the ecosystem’s dynamism.
Geographically, the industry is anchored by a network of regional hubs, notably Jyväskylä’s EXPA, which serves as a northern innovation cluster. The ecosystem is highly diversified, ranging from global powerhouses such as Supercell—employing over 800 staff and delivering seven worldwide hit titles—to agile indie studios like Snowhound, which hosts more than 120 employees from over twenty nationalities, and niche ventures such as Soihtu DTx, which secured a $4.2 million seed round for a clinically validated mental‑health game. Across the board, firms are expanding into cross‑platform and co‑development projects, exemplified by collaborations between Ubisoft RedLynx and Zaibatsu Interactive, reflecting a broader trend toward collaborative, multi‑disciplinary production.
- Finland’s game industry currently employs approximately 4,300 individuals, representing about 3,800 full-time positions.
- A significant decline in private risk capital and publisher funding has forced studios to pivot toward B2B subcontracting, co-development agreements, and increased reliance on EU and national public R&D programs.
- The ecosystem remains anchored by major players like Supercell, which employs over 800 staff and has produced seven global hit titles, alongside diverse ventures like the mental-health game developer Soihtu DTx, which recently secured a $4.2 million seed round.
- Finnish studios are increasingly adopting collaborative production models, evidenced by cross-platform partnerships such as the collaboration between Ubisoft RedLynx and Zaibatsu Interactive.
- Despite innovation in AI-assisted development and cloud gaming, the industry faces growth constraints due to a persistent shortage of senior developers and specialists proficient in Unreal Engine.
+1
Neogames FinlandJan 2024
Report54 pages
Live Streaming Trends Annual Report 2024
The live streaming landscape in 2024 reflects a maturing industry characterized by the stabilization of viewership hours and a strategic shift toward platform diversification. Following the volatile growth cycles of previous years, the current market demonstrates a consolidated ecosystem where Twitch, YouTube Gaming, and Kick represent the primary pillars of audience engagement. While Twitch maintains its dominance in the non-gaming and community-driven sectors, YouTube Gaming has leveraged its integrated VOD ecosystem to capture a larger share of the competitive esports market. Emerging platforms like Kick have successfully disrupted traditional market shares by offering aggressive revenue splits, leading to a more fragmented but competitive talent landscape.
Technological integration serves as a primary driver for growth, with mobile streaming accounting for nearly half of all global viewership. This trend is particularly pronounced in Southeast Asia and Latin America, where mobile-first infrastructure has allowed platforms like TikTok Live to challenge established desktop-centric services. Data indicates that short-form video integration acts as a critical discovery funnel, with creators who utilize cross-platform promotional strategies seeing a twenty percent higher retention rate compared to those relying solely on live broadcasts. Furthermore, the rise of "VTubing" and AI-enhanced avatars has expanded the creator economy, allowing for new forms of interactive entertainment that bypass traditional physical production constraints.
Monetization strategies have evolved beyond simple ad-revenue models to prioritize direct fan support and brand integrations. Virtual gifting and subscription tiers remain the most reliable revenue streams, though sponsored content and affiliate commerce are becoming increasingly sophisticated. The industry is also witnessing a significant push toward "shoppable" live streams, mirroring successful e-commerce trends in Asian markets. As the industry moves forward, the focus remains on enhancing low-latency infrastructure and developing more robust moderation tools to ensure brand safety and community longevity in an increasingly crowded digital marketplace.
- Mobile streaming now accounts for nearly 50% of global viewership, driven by mobile-first infrastructure in Southeast Asia and Latin America.
- Creators using cross-platform promotional strategies that integrate short-form video content achieve a 20% higher audience retention rate than those relying exclusively on live broadcasts.
- Twitch remains the leader in community-driven content, while YouTube Gaming is capturing significant market share in competitive esports through its integrated VOD ecosystem.
- The platform landscape is becoming increasingly fragmented as Kick disrupts traditional market shares by offering aggressive revenue splits to attract talent.
- Monetization is shifting away from simple ad-revenue toward direct fan support, subscription tiers, and the adoption of 'shoppable' live streams for e-commerce.
Stream HatchetJan 2024
Report27 pages
Global Sports Tech Report 2024
I’m ready to craft a comprehensive synthesis, but I’ll need the remaining section summaries to capture the full scope, findings, and conclusions of the Global Sports Tech Report 2024. Could you please provide the rest of the section-by-section summaries?
- The sports tech sector saw record deal-making in 2024, with $86 billion in total deal value across 1,152 deals, including 18 M&A deals over $1 billion and 17 financings over $50 million, and over $6 billion raised by new funds.
- Public markets experienced a rebound in investor confidence, evidenced by a wave of debt refinancings (e.g., Liberty Media, Peloton, Flutter) and follow-on equity rounds (e.g., Liberty Media, Amer Sports), with Canal+ spinning off from Vivendi to list on the LSE.
- Major acquisitions in 2024 included Silverlake's $13 billion acquisition of Endeavor, KKR's $4.75 billion acquisition of Varsity Brands, and Standard General's $4.6 billion acquisition of Bally's Fantasy, Esports & Betting.
- Significant fundraising rounds included ŌURA's $200 million Series D, TOCA Soccer's $100 million Series F, and LOVB's $100 million round, indicating strong investment in health-tracking devices, tech-enabled sports experiences, and new sports leagues.
- Athlete Performance was the top-performing sub-sector with a 52.03% cumulative stock price return, significantly outperforming the S&P 500 (23.31%) and other sports tech categories like Fantasy/Esports/Betting (10.36%) and Digital Media/OTT/Content (5.36%).
+1
Drake Star PartnersJan 2024
Report42 pages
ゲーム開発者の就業とキャリア形成 2024
The 2024 Game Developer Survey for Japan provides a comprehensive snapshot of compensation trends among the nation’s game development workforce, focusing on individuals with formal vocational‑school or university education. By capturing responses from a broad cross‑section of developers, the study aims to assess whether recent industry growth translates into tangible financial benefits for skilled professionals.
Findings reveal that more than 80 % of educated respondents reported a salary increase over the preceding year, a pattern that holds consistently for full‑time employees, with roughly the same proportion experiencing any rise in earnings. This upward trajectory suggests that Japanese studios are increasingly rewarding qualified talent, reflecting both heightened competition for skilled labor and the sector’s expanding revenue streams. The data also underscore the importance of formal education as a predictor of wage growth, indicating that employers value academic credentials when allocating compensation adjustments.
Overall, the survey indicates a robust and positive compensation environment for Japan’s game development sector in 2024, highlighting sustained investment in human capital. The prevalence of salary gains among highly educated, full‑time developers points to a healthy labor market that may enhance talent retention and support continued industry innovation.
- Over 80% of game developers with formal vocational or university education in Japan received a salary increase in 2024.
- The trend of rising earnings is consistent among full-time employees, with approximately 80% reporting wage growth over the past year.
- Formal academic credentials serve as a significant predictor of wage growth, as employers prioritize these qualifications when determining compensation adjustments.
- The widespread salary growth reflects heightened competition for skilled labor and the overall expansion of revenue streams within the Japanese gaming sector.
- The 2024 data indicates a robust labor market characterized by sustained investment in human capital and improved talent retention strategies.
+1
CESA – Computer Entertainment Supplier's AssociationJan 2024
Report20 pages
The Austrian Game Industry 2024
The Austrian game sector is portrayed as a youthful, fast‑growing cluster of predominantly small and micro enterprises whose economic relevance has expanded dramatically over the past six years. A 2023‑2024 survey commissioned by the Austrian Professional Association of Management Consultancy, Accounting and IT and executed by the Institute of Industrial Research gathered responses from roughly 150 active developers, with detailed data supplied by 78 firms on production output and by 23 firms on serious‑game activities. The study combines firm‑level questionnaires with macro‑economic modelling to assess direct, indirect and induced effects on the national economy.
Revenue generated by domestic developers reached €92.8 million in 2023, a nominal increase of more than 285 % compared with 2017, and still represents a 180 % rise after price‑level adjustment. Employment rose from 474 jobs in 2017 to 1 080 in 2024, a 128 % increase, and the sector’s multiplier effect creates roughly 2 260 jobs across Austria. Projections that assume a slowdown to one‑third of recent growth still forecast revenues of €149 million and a workforce of over 1 500 by 2029. In the preceding three years, the surveyed firms produced 405 games, while serious‑game developers now number 20‑30 companies employing 130‑150 staff, chiefly to raise awareness of social issues such as climate change.
The workforce is highly qualified: almost 80 % hold tertiary degrees, with the 25‑34 age group dominating. Educational provision is concentrated in three regional hubs—Salzburg, Upper Austria and Carinthia—where 25 university programmes supply the bulk of IT talent. Financing remains largely internal, with self‑funding cited by 92 % of firms; public subsidies rank second but are considered insufficient, reflected in the finding that 77 % of developers rate Austria’s location policy as poor or very poor. Nonetheless, only 5 % contemplate relocation, and the majority anticipate continued employment growth over the next three years.
- The Austrian game industry generated €92.8 million in revenue in 2023, marking a 285% nominal increase since 2017.
- Direct employment in the sector grew 128% over seven years, rising from 474 jobs in 2017 to 1,080 in 2024, with a total economic multiplier effect supporting 2,260 jobs.
- Projections for 2029 estimate industry revenue will reach €149 million and the workforce will exceed 1,500 employees, even assuming a significant slowdown in growth.
- The industry is characterized by small and micro enterprises that rely heavily on internal financing, with 92% of firms self-funding their operations.
- Despite 77% of developers rating Austria’s location policy as poor or very poor, only 5% of firms are considering relocation.
+1
Austrian Professional Association of Management ConsultancyJan 2024
Report4 pages
Czech Gaming Industry Report 2024
The Czech Gaming Developers Association compiled an annual industry overview to map the sector’s economic performance, workforce composition and structural trends for 2023 and early 2024. By aggregating self‑reported financial and employment data from member studios, the analysis aims to illustrate growth trajectories, geographic concentration and the evolving profile of talent within the Czech game development ecosystem.
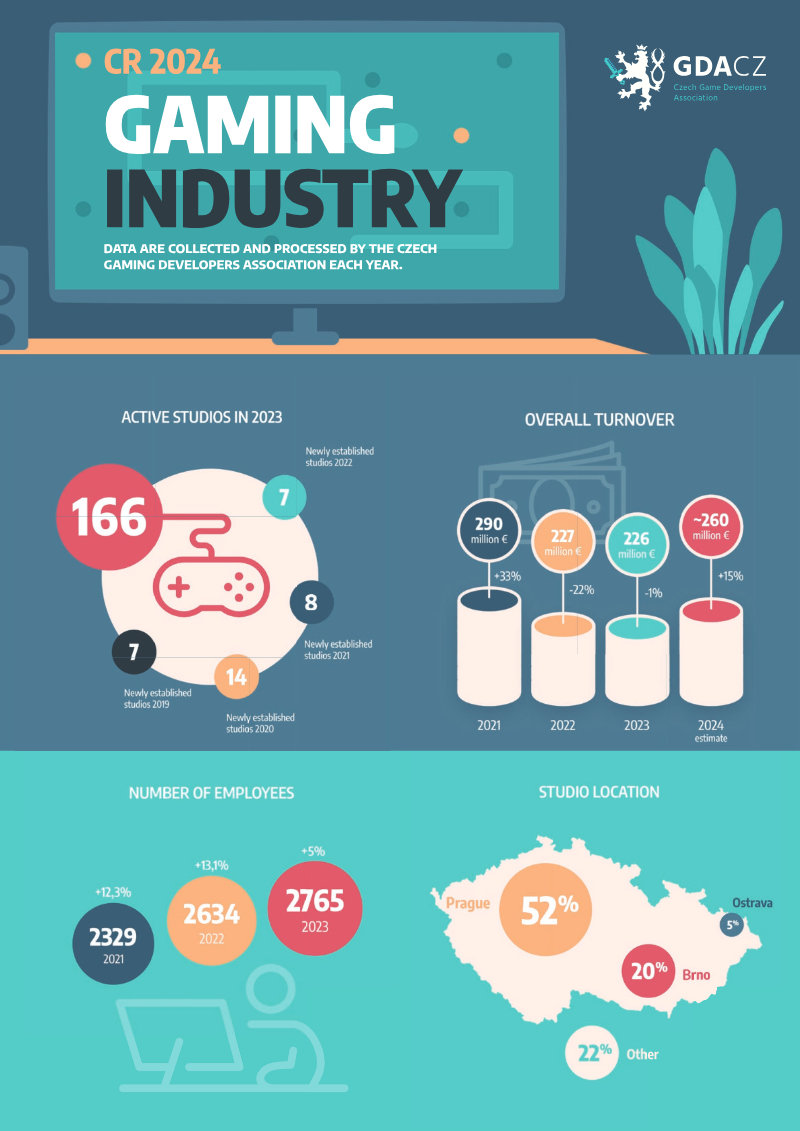
Overall turnover reached €226 million in 2023, marking a 33 % increase over the previous year, while the number of active studios rose modestly, with newly established entities numbering 166 in 2023 compared with 260 in 2022. Employment expanded to roughly 4,165 staff, a 12.3 % rise, with the majority concentrated in Prague (52 %), followed by Ostrava (13 %) and Brno (20 %). The sector released 29 new titles in 2023, supplemented by 10 early‑access projects and 10 DLCs, for a total of 39 releases.
Ownership structures remain dominated by private limited companies, accounting for the bulk of legal entities, while joint‑stock and foreign‑branch configurations each represent about 5 % of the market. Job creation accelerated, with over 430 new positions announced across the year, a 20‑23 % increase relative to prior periods. The workforce is increasingly international: 34 % of employees are foreign nationals, predominantly from EU member states, while 66 % are Czech. Educational backgrounds are diverse, with roughly half holding higher‑education degrees and a similar share possessing vocational or technical qualifications. The report’s methodology relies on annual surveys administered by the association, covering all registered Czech game development firms and providing a comprehensive snapshot of the industry’s health and direction.
- The Czech gaming industry reached a total turnover of €226 million in 2023, representing a 33% year-over-year growth.
- Total employment in the sector grew by 12.3% to 4,165 staff, with over 430 new positions created throughout 2023.
- The industry released 39 total projects in 2023, consisting of 29 new titles, 10 early-access projects, and 10 DLCs.
- The workforce is increasingly international, with foreign nationals—primarily from EU member states—comprising 34% of all employees.
- Geographic concentration remains high, with 52% of the workforce based in Prague, followed by 20% in Brno and 13% in Ostrava.
GDACZ – Czech Game Developers AssociationJan 2024