Key insights
9 slides
The year in numbers
Global mobile advertising spend reached $362 billion in 2023.
The mobile app industry demonstrated significant resilience throughout 2023. A late-year surge in installations characterized the period.
Privacy pressure
Evolving privacy regulations shaped the 2023 mobile landscape.
The industry faced challenges from rising acquisition costs and evolving privacy regulations.
Fintech momentum
Fintech saw a 42% increase in installs and 118% revenue surge.
Fintech emerged as a primary growth engine in 2023. The sector successfully optimized its acquisition strategies.
Revenue surge. Fintech experienced a 118% surge in in-app revenue.
Page 20 of the reportJAN 222.5
FEB 222.6
MAR 223
APR 223.2
MAY 223.4
JUN 223.2
JUL 223.2
AUG 223.3
E-commerce strength
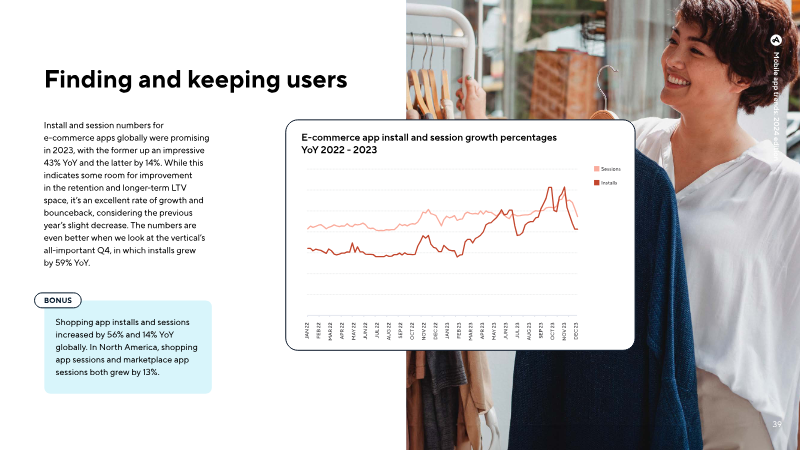
E-commerce installs rose 43% year-over-year with a 34% revenue increase.
E-commerce performance remained strong in 2023. The sector saw a 43% year-over-year rise in installs alongside a 34% increase in revenue.
Efficiency gains
Banking eCPIs fell from $2.33 to $1.37, enabling faster returns.
Banking sector efficiency improved significantly in 2023. Marketers achieved rapid returns on investment within the first week of user acquisition.
Page 17 of the reportAll2.6
Bank2.3
Payment1.4
Annual decline
Gaming ended 2023 with a 2% annual decline in installs.
The gaming sector navigated a more complex trajectory in 2023. It ended the year with a 2% annual decline in total installs.
Page 24 of the reportGlobal-2
APAC-3
EMEA-3
LATAM7
North America-6
Genre spikes
Racing and simulation genres recorded 61% and 53% install spikes.
Specific gaming subverticals outperformed the broader market in 2023. Racing and simulation genres recorded dramatic install spikes.
Page 28 of the reportAction20
Adventure9
Arcade38
Board30
Puzzle15
Racing61
Simulation53
Trivia12
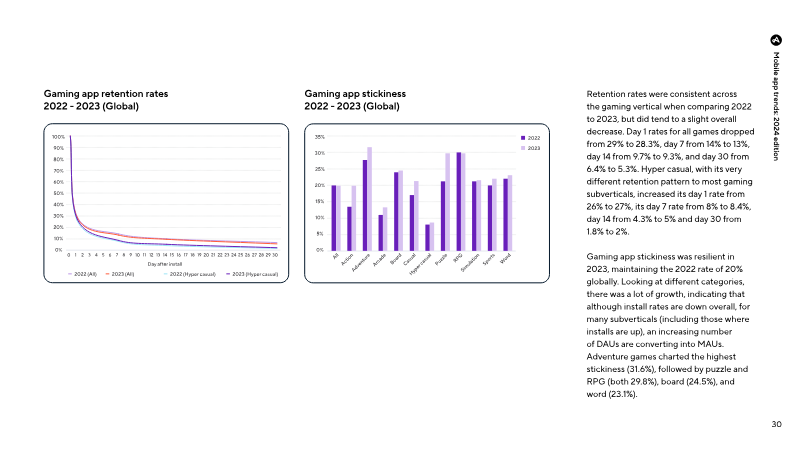
Stable engagement
Global gaming stickiness remained stable at 20% in 2023.
Global gaming stickiness remained stable at 20% despite broader retention pressures. High-engagement genres like RPG and adventure continued to command strong lifetime value.
Strategic integration
Future growth requires AI integration and media diversification.
Future industry success depends on the strategic integration of artificial intelligence and predictive analytics. Developers must diversify media mixes by expanding into emerging channels like Connected TV.
1 / 9
Ask AI about this report
Comments