FY2024 Report: Australian Game Development Survey
202413 pages~9 min full read
Key insights
4 slides
The headline number
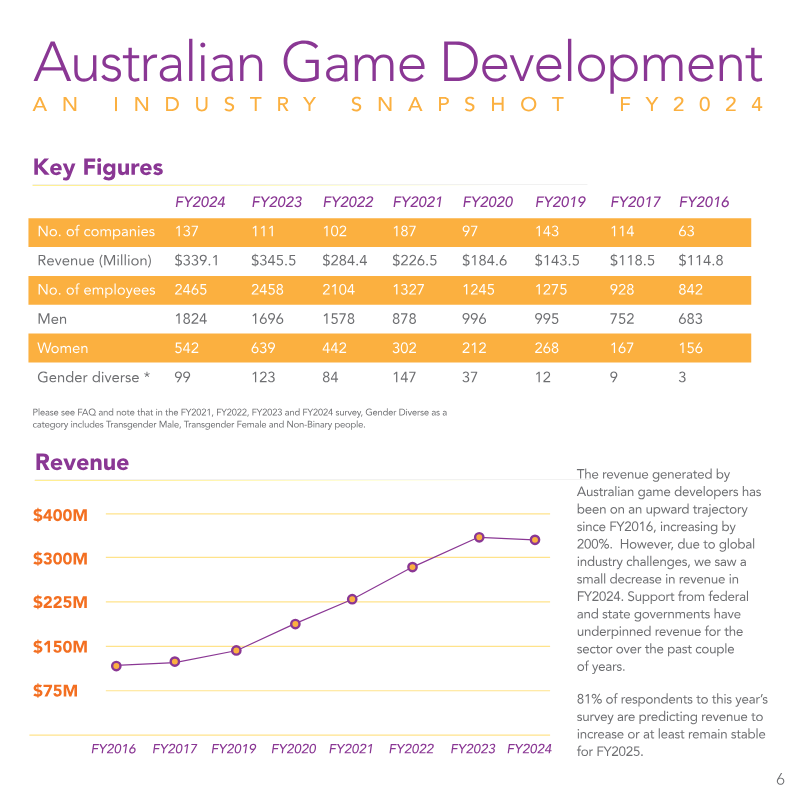
Australian game development revenue reached $339.1 million in FY2024.
Total income generated by local studios fell 1.9% from the previous year. Employment remained steady at 2,465 full-time equivalent workers.
Where revenue comes from
Ninety-three percent of revenue was generated from outside Australia.
The sector is heavily export-oriented. Eighty-five percent of studios focus on developing their own original intellectual property rather than work-for-hire projects.
Export-driven model. The sector is highly export-focused, with 93% of total revenue derived from international markets.
Page 2 of the report93%
Share of total revenue derived from international markets
- studios prioritizing original IP
- 85%
Where studios are based
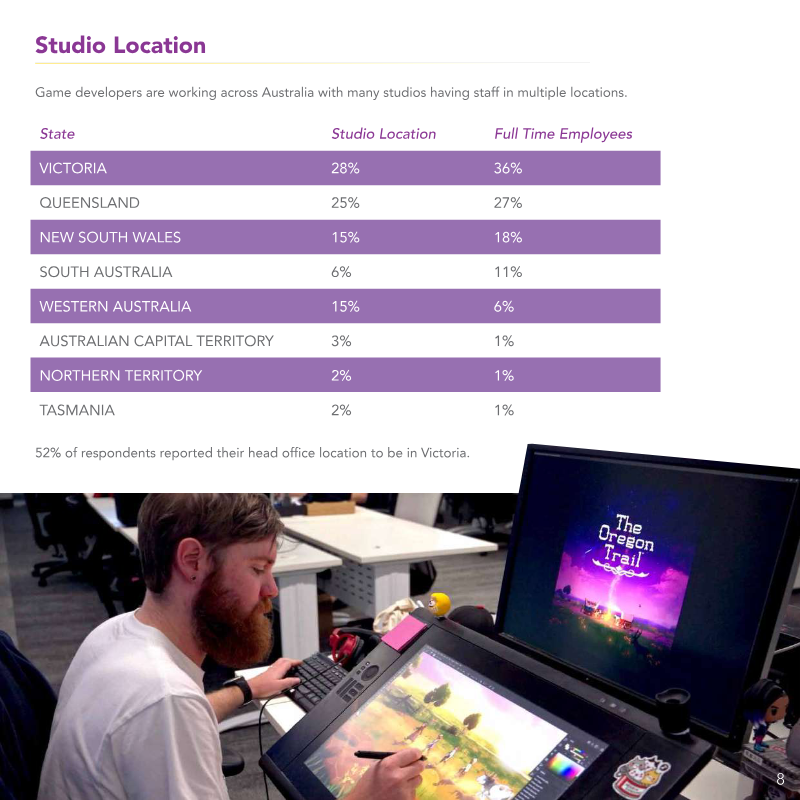
Victoria hosts 52% of studio head offices and 36% of the workforce.
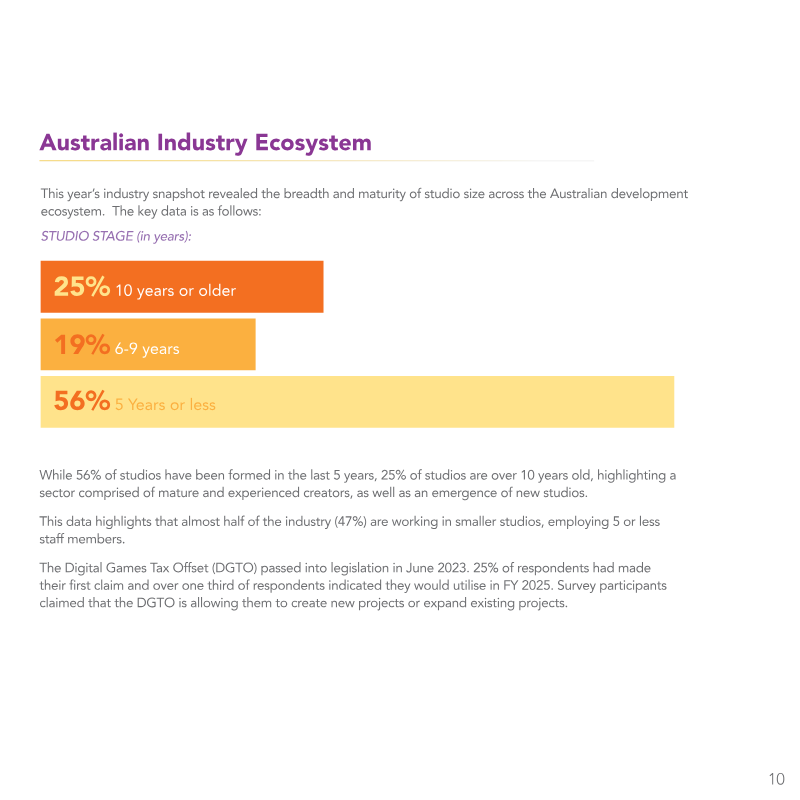
Victoria serves as the industry's primary hub, followed by Queensland and New South Wales. Small businesses dominate the ecosystem, with 47% of studios employing five or fewer staff members.
Government support
Twenty-five percent of studios use the Digital Games Tax Offset.
The offset, passed in mid-2023, is already being utilized by 25% of respondents to fund new projects or expand existing ones. Developers still cite securing publishing deals and early-stage funding as primary challenges.
1 / 4
Ask AI about this report