Mergers & Acquisitions reports and market data
Documents
Game Biz #3 | Game Company Growth Strategies ft Chris Petrovic and Eric Kress
The gaming industry is currently undergoing a structural transition as major players shift from a reliance on aggressive mergers and acquisitions toward the more complex challenge of organic growth.
- The gaming industry is shifting from an M&A-heavy growth model to a focus on organic growth, as high-quality independent acquisition targets become scarce and integration challenges persist.
- Investors are increasingly pressuring major firms like EA, Take-Two, and Zynga to demonstrate internal innovation and the ability to launch new franchises rather than relying on capital-intensive consolidation.
- Companies are pursuing vertical integration by acquiring ad-tech capabilities to optimize profitability and mirror the valuation models of firms like AppLovin.
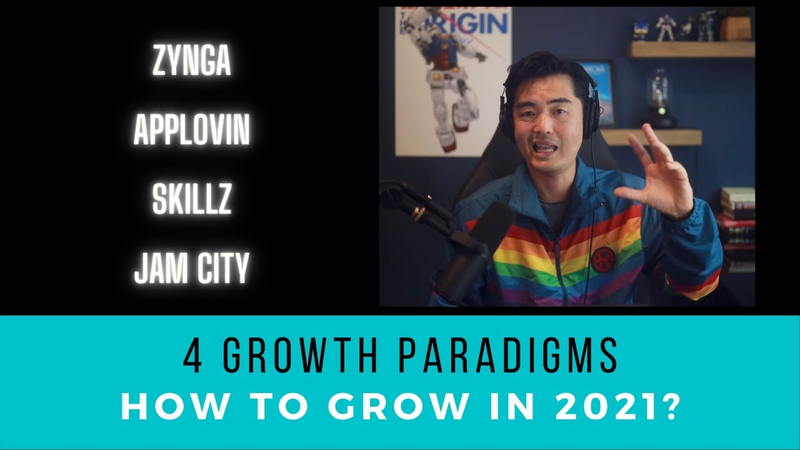
Game Company Growth Strategies in 2021 | Zynga, Applovin, Skillz, and Jam City
The mobile gaming industry is undergoing a fundamental transformation as traditional content-based mergers and acquisitions yield diminishing returns.
- The mobile gaming industry is shifting away from traditional content-based M&A toward vertical integration and cross-platform models to counter the impact of IDFA deprecation on user acquisition.
- AppLovin is attempting to transition from an ad-tech provider to a content-focused powerhouse, risking the alienation of its external client base by creating a potential walled garden.
- Zynga is pursuing ad-tech integration and cross-platform expansion, though its strategy faces significant industry skepticism regarding data privacy and trust.
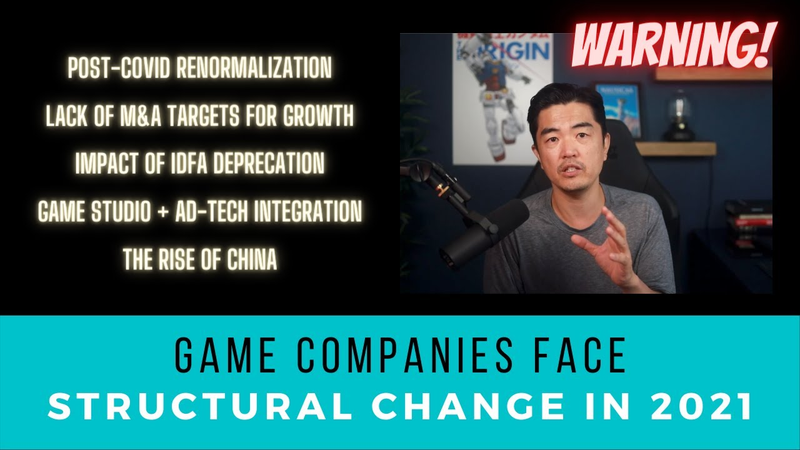
Game Companies Face Structural Change in 2021 | The Warning!
The gaming industry faces a period of significant structural transformation in 2021, driven by five converging factors that threaten to disrupt established business models.
- The gaming industry is transitioning from the 2020 pandemic-driven hyper-growth phase to a more complex, data-constrained environment characterized by normalized user behavior.
- The deprecation of Apple’s Identifier for Advertisers (IDFA) is eroding the efficacy of user acquisition, specifically threatening the monetization models of hyper-casual game developers.
- A scarcity of viable mid-tier M&A targets is forcing major firms to pivot toward riskier, larger public transactions or smaller, pre-revenue acquisitions to maintain growth.
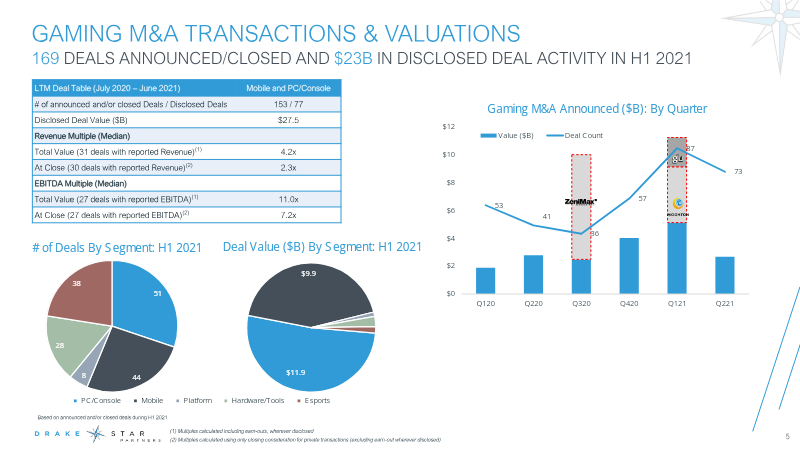
Global Gaming Industry Update: June 2021
The global gaming industry experienced unprecedented deal activity during the first half of 2021, characterized by rapid consolidation and record-breaking investment levels.
- In the first half of 2021, the gaming industry saw $23 billion in M&A activity across 169 deals, nearly doubling the total dollar value recorded for the entire year of 2020.
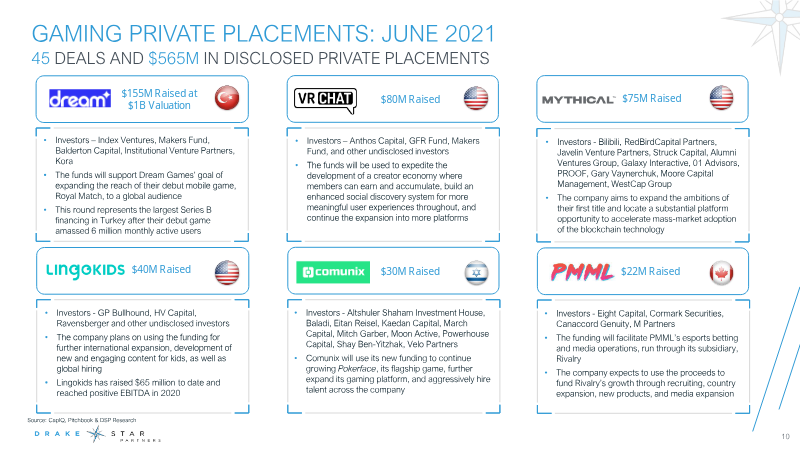
- Private placement transactions reached $4.8 billion across 364 deals during the first six months of 2021.
- Major strategic consolidators included Tencent, Electronic Arts, Take-Two, and Embracer Group, while private equity firms like The Carlyle Group and Bain Capital significantly increased their market participation.
Panel: Are M&As the New Markers of Success?
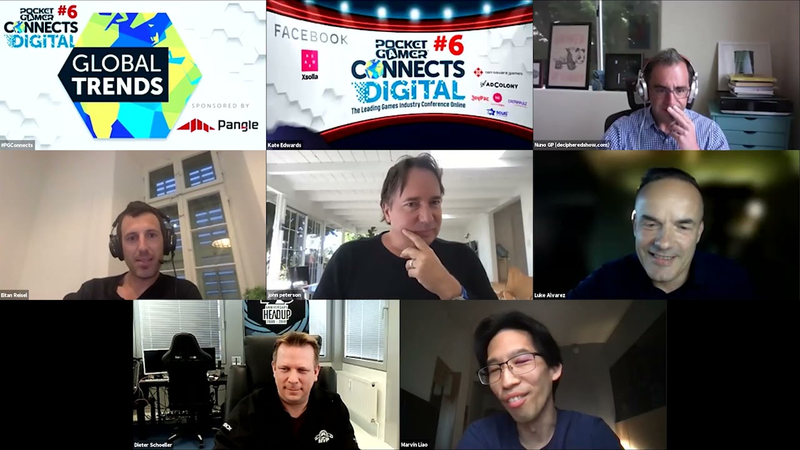
The global gaming industry is currently undergoing a period of intense consolidation, fueled by a sector valuation reaching $200 billion and consistent annual growth.
- The global gaming industry has reached a $200 billion valuation, driving intense consolidation as a primary mechanism for scaling.
- Early-stage studios are increasingly seeking acquisition to overcome the high barriers of global distribution, marketing, and live-operations infrastructure.
- Investment strategies have shifted toward rigorous, data-driven evaluations that prioritize team experience, player retention metrics, and long-term market viability.
Global Gaming Industry Update: May 2021
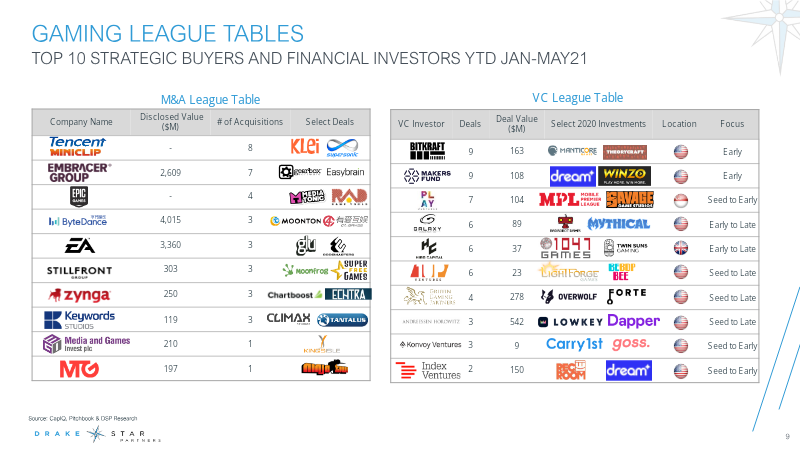
The global gaming industry experienced unprecedented financial activity during the first five months of 2021, with total deal value surpassing that of any previous full year.
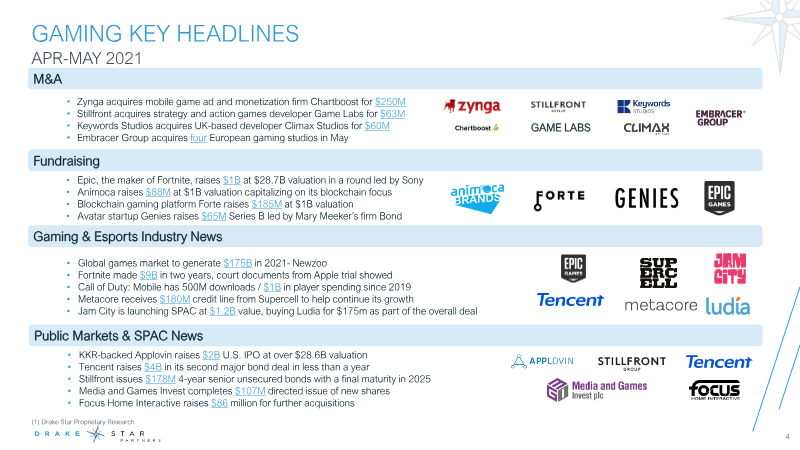
- The global gaming industry reached a record-breaking $49 billion in disclosed deal value during the first five months of 2021, surpassing the total deal value of any previous full year.
- Major industry players including Tencent, Embracer Group, Epic Games, and ByteDance drove aggressive market consolidation through high-volume M&A activity.
- Public markets experienced significant capital inflows, highlighted by the $2 billion IPO of AppLovin and a high volume of SPAC launches.
Ad Strategy in the Age of Consolidation #ELEVATEYOURGAME - PG.Biz Fireside Chat
Modern mobile gaming success relies on a sophisticated, data-driven approach to ad monetization that treats internal studios as collaborative partners rather than mere subordinates.
- Maximize ARPDAU by aligning ad supply and demand through a structured funnel focusing on eligibility, surfacing, and engagement.
- Utilize a diversified portfolio of titles to leverage cross-promotion and first-party data, treating internal studios as collaborative partners rather than subordinates.
- Implement a phased ad integration strategy starting with low-friction rewarded video before introducing interstitial formats to non-converting users.
Game Biz #2: Talking Strategy and Synergy with Stillfront Group!
Stillfront Group operates under a distributed operator model that prioritizes studio autonomy while leveraging the collective scale of a 19-studio network.
- Stillfront Group operates a decentralized network of 19 studios that prioritizes local autonomy and founder-led decision-making over top-down corporate mandates.
- The company utilizes a voluntary collaboration model where studios share specialized infrastructure, payment solutions, and expertise in ad monetization and IP licensing.
- Operational strategy focuses on pooling data and collective experimentation to mitigate industry-wide disruptions, such as the deprecation of IDFA.
TWIG 125: Mr. Beast Night Media VC Fund, Ironsource SPAC, NY Times Gaming, Discord for $10B?
The gaming industry is currently defined by a rapid acceleration of consolidation, strategic shifts toward the creator economy, and a complex interplay between privacy regulations and valuation models.
- Tech giants are aggressively pursuing platform and IP consolidation, exemplified by ByteDance’s acquisition of Moonton and Microsoft’s potential $10 billion purchase of Discord.
- Discord faces significant investor skepticism regarding its long-term viability due to high burn rates and the absence of a clear, sustainable monetization strategy.
- Ad-tech firms like ironSource and AppLovin are rebranding as high-margin software platforms to maintain aggressive valuation multiples following the deprecation of IDFA and the implementation of App Tracking Transparency.
TWIG 123 | Fortnite Maker Epic Buys Mediatonic, Ubisoft with Ethereum NFT Game, Dream Games $50M
The gaming industry is currently undergoing a period of rapid consolidation and strategic investment, characterized by high-profile acquisitions and significant venture capital inflows.
- Epic Games acquired Mediatonic to integrate the popular Fall Guys title into its broader metaverse development strategy.
- Dream Games raised $50 million in Series A funding to compete in the $3.7 billion mobile puzzle game market.
- Blockchain and NFT integration requires game design to be built around the technology from inception rather than retrofitting existing titles to achieve mass adoption.
Game Biz #1: Game Industry M&A [EA, Zynga, Glu, and More]
The gaming industry is currently undergoing a period of aggressive consolidation, characterized by a strategic shift toward vertical integration and the pursuit of mobile market dominance.
- Major publishers like Electronic Arts are acquiring mobile-focused entities such as Glu Mobile to address dormant mobile portfolios and satisfy investor growth demands.
- The deprecation of IDFA (Identifier for Advertisers) is forcing companies to internalize ad tech and user acquisition data to maintain control in a constrained privacy landscape.
- Industry M&A strategy is split between Zynga’s centralized, synergistic model and Embracer Group’s decentralized approach, with analysts questioning the long-term viability of the latter without centralized support.
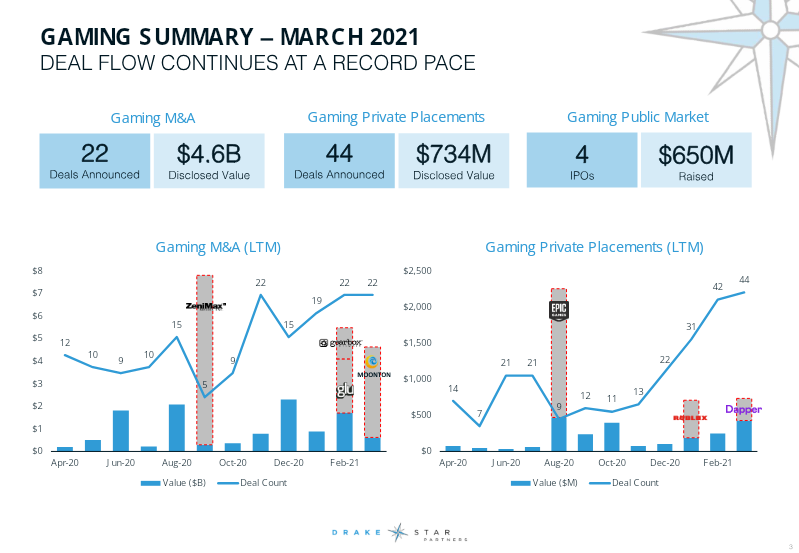
Global Gaming Industry Update: March 2021
The global gaming industry experienced significant financial activity throughout March 2021, characterized by robust deal flow across mergers and acquisitions, private placements, and public market entries.
- The gaming industry saw 22 M&A deals in March 2021 totaling $4.6 billion, anchored by ByteDance’s $4 billion acquisition of Moonton Technology.
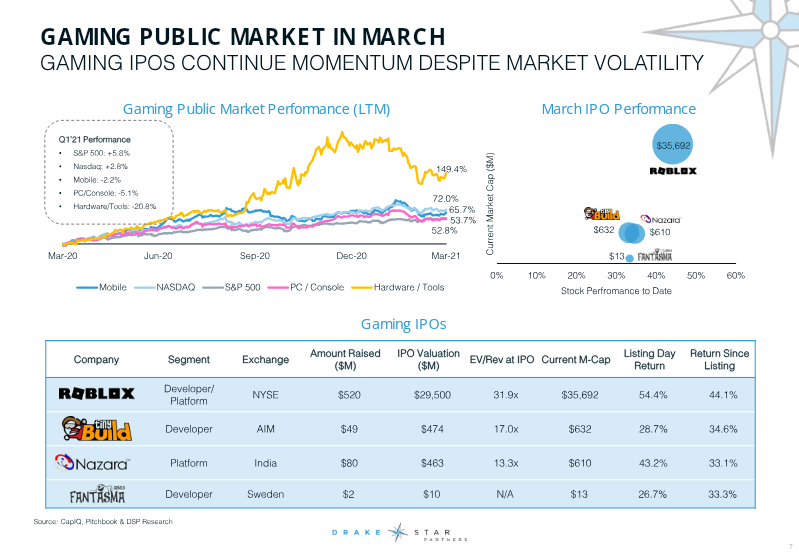
- Roblox entered the public market via direct listing at a $29.5 billion valuation, while companies like tinyBuild and Nazara completed successful IPOs.
- Private placement activity remained robust with 44 deals raising $734 million, highlighted by Dapper Labs securing $305 million at a $2.6 billion valuation.