Mergers & Acquisitions reports and market data
Documents
TWIG #302 Epic Legal Showdowns, Ubisoft Woes, and MMO Thrills
The global video game industry is currently navigating a period of significant structural volatility, characterized by shifting consumer ownership rights, evolving hardware paradigms, and the struggle to balance profitability with creative output.
- Western AAA publishers are struggling to replicate the dual-skew mobile and PC development models mastered by Eastern firms like HoYoverse, whose title Genshin Impact has generated over $4 billion in mobile revenue.
- The industry is shifting from aggressive expansion to cautious portfolio management as developers face audience cannibalization and the rising costs of maintaining high-fidelity gaming experiences.
- Major publishers are increasingly leveraging artificial intelligence to reduce headcounts and bolster profit margins, contributing to a period of structural volatility and internal instability at firms like Ubisoft.
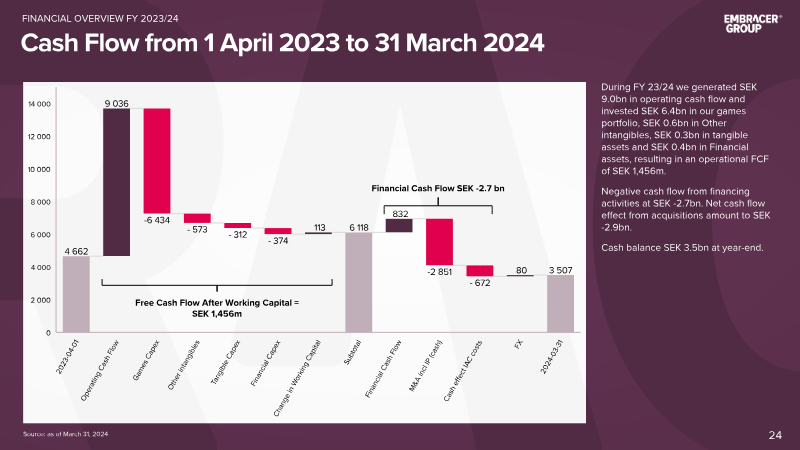
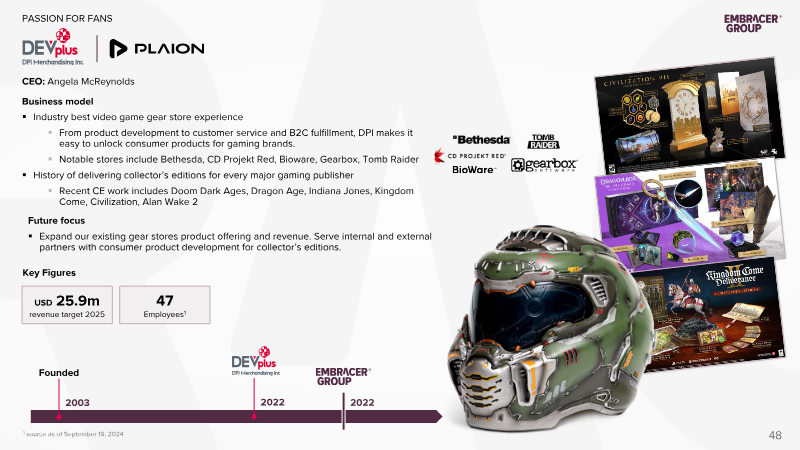
Embracer Group Annual General Meeting 2024: Presentation
Embracer Group concluded the 2023/24 fiscal year with a stable financial performance, reporting net sales of SEK 42.2 billion, representing a 12 percent year-over-year increase, alongside an adjusted EBIT of SEK 7.06 billion.
- Embracer Group is splitting into three independent, publicly listed entities: Asmodee, Coffee Stain & Friends, and Middle-Earth & Friends.
- The company reported fiscal year 2023/24 net sales of SEK 42.2 billion, a 12 percent year-over-year increase, with an adjusted EBIT of SEK 7.06 billion.
- The corporate restructuring follows a rigorous program initiated in 2023 that included the divestment of non-core assets and 54 Board of Directors meetings.
Console/PC Games Investment Report September 2024
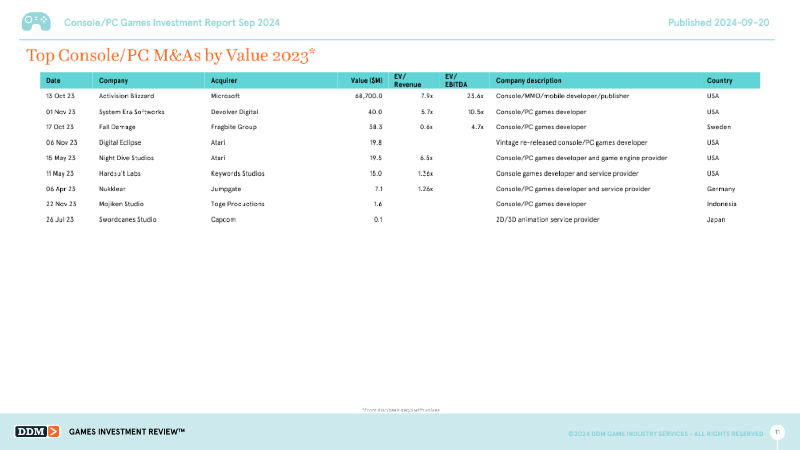
The analysis presents a comprehensive review of investment and merger-and-acquisition activity within the console and PC video-game sector for the 2023 fiscal year, positioning 2023 as an outlier driven primarily by Microsoft’s $68.7 billion acquisition of Activision Blizzard.
- The 2023 fiscal year saw total deal value reach $69.5 billion, a 612% increase driven almost entirely by Microsoft’s $68.7 billion acquisition of Activision Blizzard.
- While total deal value surged, the actual number of transactions fell by 25% compared to 2022, and investment volume dropped to $627.8 million across 161 deals.
- M&A activity dominated the market with $68.8 billion across 39 deals, accounting for more than 99% of North American M&A value.
Chinese Gaming Giants: Tencent vs. Netease | Pixels & Profits
Tencent and NetEase represent the dual pillars of the Chinese gaming industry, yet both face a precarious future defined by domestic saturation, regulatory volatility, and escalating geopolitical friction.
- Tencent achieved significant financial efficiency in 2023, increasing its operating margin to 31.5% from 25.8% in 2022 while generating $23 billion in free cash flow, an 89% year-over-year increase.
- Tencent maintains a dominant global gaming position through full ownership of major studios like Riot Games and Supercell, alongside significant minority stakes in companies including Epic Games, Ubisoft, and Krafton.
- Tencent faces substantial headwinds in the domestic Chinese market, which accounts for approximately 70% of its revenue, due to strict government regulations on gameplay and increasing competition from emerging rivals like miHoYo and Game Science.
TWIG #294 Bungie Fires, Supercell Hires and Roblox Grows
The global gaming industry is currently undergoing a period of intense structural correction, characterized by widespread workforce reductions and a shift in consumer spending habits.
- Roblox continues to demonstrate strong growth with a 22% year-over-year increase in bookings and a user base exceeding 380 million monthly active users.
- Major studios including Bungie and Jam City are implementing significant layoffs to combat unsustainable burn rates and high development costs in the current economic climate.
- The mobile gaming sector is increasingly adopting hybrid-casual strategies, exemplified by White Out Survival, which uses hyper-casual advertising to funnel users into complex 4X strategy games.
TWIG #289 King's AI, Amazon's games strategy, Netflix's problems solved
The gaming industry currently faces a period of intense strategic recalibration, characterized by a shift away from speculative venture-backed models toward sustainable, high-quality production.
- The gaming industry is shifting from speculative venture-backed models toward sustainable production, leading to consolidation and acquisition as startups struggle to justify high burn rates.
- Major studios, including Ubisoft and Perfect World, are undergoing significant layoffs as they struggle to balance the high costs of live-service content pipelines with long-term monetization.
- While King is successfully using AI as a co-pilot for level design and bot training, the broader industry remains skeptical of 'AI-first' narratives due to a lack of evidence that these tools actually increase production output.
Queen’s Gambit: The Big Business of Chess.com
Chess.com has transformed from a modest 2005 domain acquisition into a dominant global digital ecosystem, currently serving 175 million registered users and 50 million monthly active participants.
- Chess.com has scaled to 175 million registered users and 50 million monthly active participants by building a value-added ecosystem around a public-domain game.
- The company maintains operational independence and avoids venture capital by utilizing a self-funded, profitable growth model that reinvests cash flow into the business.
- Strategic consolidation of the professional chess market was achieved through key acquisitions, most notably the purchase of the Play Magnus Group.
Mobile Games Annual Investment Report: June 2024
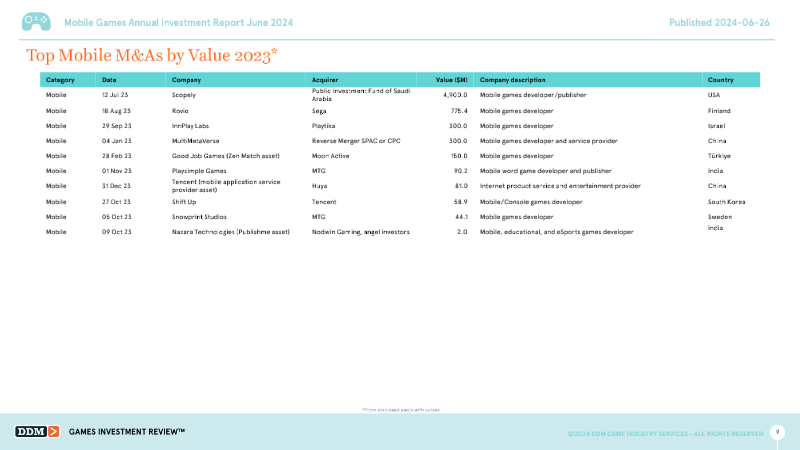
The mobile games sector experienced a significant contraction in 2023, with total investment and merger and acquisition (M&A) activity falling to a four-year low.
- Mobile gaming investment and M&A activity hit a four-year low in 2023, totaling $7.8 billion across 211 transactions, a 63% decline in value and 33% decrease in volume from 2022.
- M&A activity dominated the market with $6.7 billion across 32 deals, heavily bolstered by the Public Investment Fund of Saudi Arabia’s $4.9 billion acquisition of Scopely.
- Private investment in mobile gaming totaled $1.1 billion across 179 deals in 2023, reflecting a cooling market compared to the 2021 peak.
Toys x Games (with Spin Master)
Spin Master maintains a diversified business model centered on the cross-pollination of intellectual property across toys, entertainment, and digital games.
- Spin Master aims to derive 20 percent of its total revenue from digital gaming by integrating its toy, entertainment, and digital businesses into a cohesive ecosystem.
- The company utilizes a bifurcated digital strategy where mobile platforms focus on monetization, while Roblox serves as a high-engagement marketing engine to build brand awareness for new properties like Unicorn Academy.
- Toca Boca World functions as a core growth anchor, maintaining status as a top-20 global mobile title through a games-as-a-service model and rapid content iteration.
TWIG Clips: Voodoo's $500M BeReal acquisition
Voodoo’s acquisition of the photo-sharing app BeReal for a reported $500 million valuation represents a strategic expansion of the former’s mobile product portfolio.
- Voodoo has acquired the photo-sharing app BeReal for a reported valuation of $500 million, marking a strategic shift from a pure-play gaming company to a broader technology and product-focused entity.
- BeReal’s user engagement has declined significantly since its peak, with monthly downloads dropping from 14 million in September 2022 to approximately 1.4 million.
- Despite the decline in new downloads, BeReal retains a substantial user base of roughly 50 million monthly active users, primarily located in the United States and Europe.
Q2’24 Gaming Deals Report
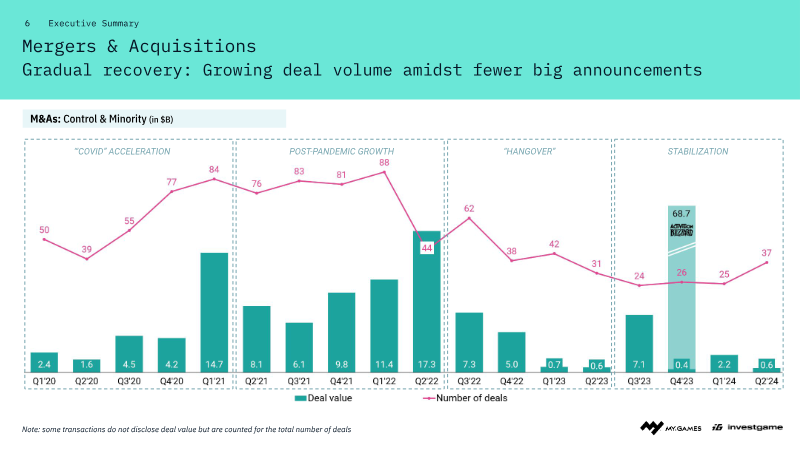
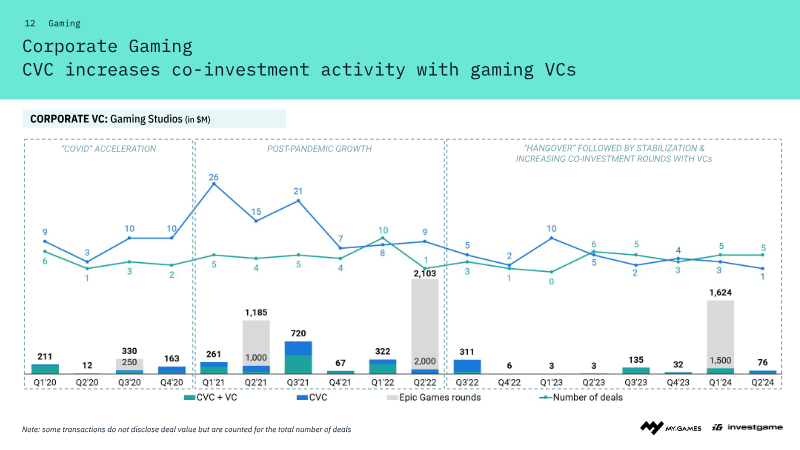
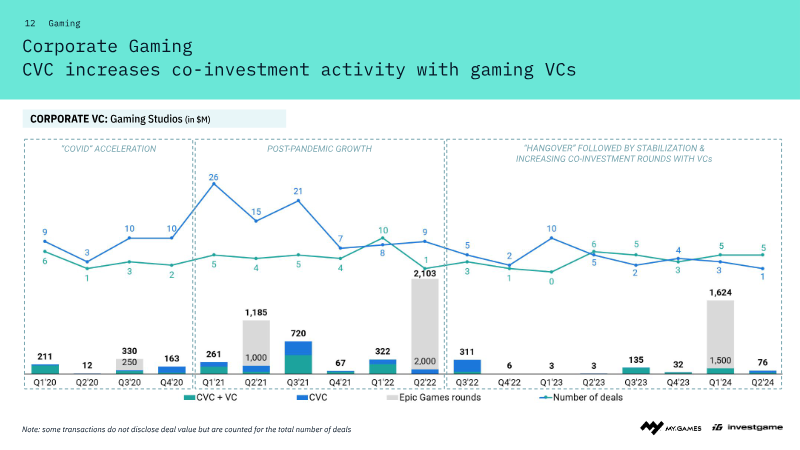
The second quarter of 2024 marks a period of stabilization for the global gaming industry, signaling an end to the post-pandemic "hangover" phase.
- Private investment in the gaming industry reached a new quarterly benchmark of $1 billion across 116 rounds in Q2 2024, signaling a stabilization of the market.
- Steam full-game sales grew by 27% year-over-year, driven primarily by a strong performance from indie and AA titles.
- Early-stage venture capital is fueling current market activity, while late-stage deal-making remains sluggish due to persistent economic headwinds.
Q2'24 Gaming Deals Report: Gradual Recovery
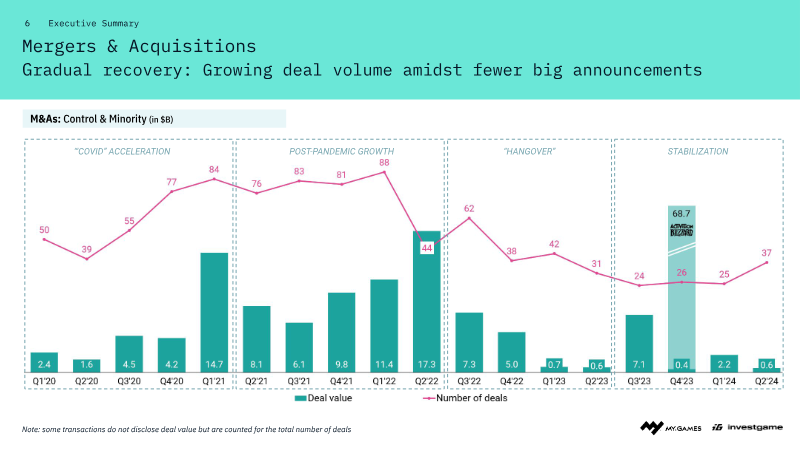
The second quarter of 2024 gaming industry analysis highlights a period of sustained activity in early-stage venture capital and a growing market for independent and mid-sized titles.
- Steam full-game sales grew 27% year-over-year in Q2 2024, driven primarily by strong performance from independent and mid-sized titles.
- Asia led global early-stage investment with $320 million across 28 deals, while North America dominated late-stage venture capital with $239 million across seven deals.
- BITKRAFT was the most active early-stage investor by volume with 18 rounds, while a16z Games led in total deal value with $124 million invested.