Market Analysis
Documents
The State of Mobile Gaming 2022: Market Trends and Top Titles in the U.S., Europe, and Asia
Global mobile gaming revenue experienced its first historical year-over-year decline in the first quarter of 2022, falling 6% to $21.2 billion. This contraction follows a period of unprecedented pandemic-driven growth and is largely attributed to market stabilization and rising inflation, which contributed to a 22% spending drop on Google Play. While established markets such as the United States and Japan saw double-digit revenue decreases, global game adoption remained resilient at approximately 14 billion quarterly downloads, a figure significantly higher than pre-pandemic benchmarks.
Geographic performance diverged sharply between mature and emerging regions. The U.S. market saw consumer spending fall 10% to $5.8 billion, and the broader Asian market declined 7% to $11.2 billion. Conversely, emerging markets in Southeast Asia and the APAC region showed significant growth. India solidified its position as the global leader in volume, accounting for 15% of worldwide installs and a 73% increase in consumer spending. In Europe, Turkey emerged as a primary growth hub, recording a 36% revenue increase and becoming the region's fastest-growing market for both downloads and development.
Genre and monetization trends indicate a shift toward sophisticated engagement mechanics. While RPG and Shooter revenues fell by 13% and 14% respectively, RPG remains the highest-grossing genre globally, and Hypercasual titles continue to dominate downloads with a 32.5% market share. Real-Time Strategy emerged as the fastest-growing sub-genre by revenue. To combat declining spending, developers are increasingly adopting Season Passes, now utilized by half of the world’s top-grossing titles to revitalize legacy games. Furthermore, strong correlations have emerged between specific aesthetics and monetization strategies, particularly the synergy between Anime art styles and Gacha mechanics, as well as the integration of ad-removal subscriptions within casual titles.
- Global mobile gaming revenue declined 6% year-over-year in Q1 2022 to $21.2 billion, ending a period of pandemic-driven growth due to market stabilization and inflation.
- Consumer spending dropped 10% in the U.S. and 7% in Asia, while Google Play saw a 22% decrease in spending despite global downloads remaining resilient at 14 billion.
- Emerging markets are driving growth, led by India’s 73% increase in consumer spending and Turkey’s 36% revenue surge, which established it as Europe’s fastest-growing market.
- While RPG and Shooter genres saw revenue declines of 13% and 14% respectively, Real-Time Strategy emerged as the fastest-growing sub-genre by revenue.
- Hypercasual titles continue to dominate the market with a 32.5% share of total downloads.
IP-Based Mobile Games: 2022
The mobile gaming landscape has shifted toward intellectual property (IP) as a primary strategy for navigating user-tracking challenges like Apple’s App Tracking Transparency. By 2021, nearly all top-downloaded new iOS titles were based on existing IPs, demonstrating that established brands are essential for driving organic acquisition and attracting high-spending players. While Western franchises like Disney and Marvel lead in global download volume, Eastern IPs—particularly those rooted in Japanese manga and Chinese literature—command superior revenue through specialized monetization models like gacha. This geographic divide highlights a fundamental difference in market behavior, where Western audiences prioritize battle mechanics while Asian markets focus on deep character development and simulation.
Success in this sector requires a rigorous alignment between an IP’s core values and the chosen game genre. Titles such as Marvel Strike Force and Umamusume: Pretty Derby illustrate how faithful adherence to lore and character-driven mechanics fosters emotional attachment and long-term retention. However, leveraging a known brand introduces operational complexities, including intensive stakeholder management, extended development timelines for licensor approvals, and the necessity of localized adaptations to meet regional preferences. The primary objective for developers is to deliver a unique IP experience rather than prioritizing original game design, as any perceived misalignment with the source material can lead to immediate user churn.
The industry is currently evolving toward a transmedia model where mobile games are no longer secondary products but integral components of a franchise’s universe. This strategy involves integrating game-original content back into the broader IP narrative to sustain community engagement across multiple platforms. Ultimately, the effectiveness of an IP-based title hinges on its ability to lower user acquisition costs while maintaining a "perfect fit" between the theme and gameplay. As the market matures, the integration of cross-platform strategies will be vital for publishers seeking to maximize the lifecycle and monetization potential of global entertainment brands.
- By 2021, nearly all top-downloaded new iOS titles were based on existing intellectual property, confirming IP as the primary strategy for organic user acquisition following privacy shifts like Apple’s App Tracking Transparency.
- Western IPs (e.g., Disney, Marvel) drive higher global download volumes, while Eastern IPs (e.g., Japanese manga, Chinese literature) generate superior revenue through specialized monetization models like gacha.
- Successful IP-based games require a 'perfect fit' between core gameplay mechanics and source material lore, as seen in titles like Marvel Strike Force and Umamusume: Pretty Derby.
- Developers must prioritize faithful adherence to IP values over original game design to prevent user churn, accepting the trade-off of increased operational complexity and longer development timelines due to licensor approvals.
- The industry is shifting toward a transmedia model where mobile games serve as integral narrative components of a broader franchise rather than secondary products.
State of Mobile: Germany 2022
The German mobile market experienced a period of rapid acceleration in 2021, characterized by a 72% increase in consumer spending over two years to reach $4.0 billion. Daily engagement rose to 3.4 hours per user, with social and video applications capturing 60% of that time. While gaming remains the primary economic driver, accounting for over 70% of total app spend and $2.8 billion in revenue, the broader ecosystem saw significant diversification into finance, retail, and health sectors. High-performance titles like Genshin Impact and Coin Master led the gaming sector, while neobanks and cryptocurrency platforms gained substantial traction among younger demographics.
The retail and service sectors underwent a digital transformation, evidenced by record-breaking engagement in shopping apps and a 37% surge in food and drink sessions. This growth was fueled by the rise of rapid delivery services and international publishers capturing larger shares of the German market. Simultaneously, the health sector remained robust, with local utility apps like CovPass and Corona-Warn-App dominating download charts due to pandemic-related requirements. This period also marked a significant rebound for travel and sports engagement, which grew by 25% and 45% respectively as restrictions eased and major international events returned.
Social and entertainment categories continue to anchor the mobile experience in Germany. WhatsApp maintains its position as the leading app by time spent, while TikTok saw a 75% year-over-year increase in engagement. Consumer spending in non-gaming categories is increasingly driven by dating and streaming services, with dating app revenue surging 115% since 2018. Overall, the German mobile landscape is defined by a sophisticated mix of high-spending gaming audiences, a rapidly maturing mobile commerce sector, and a strong reliance on mobile utilities for daily life and public health.
- The German mobile market reached $4.0 billion in consumer spending in 2021, marking a 72% increase over two years.
- Gaming remains the primary economic driver, generating $2.8 billion in revenue and accounting for over 70% of total app spending, led by titles like Genshin Impact and Coin Master.
- Daily mobile engagement reached 3.4 hours per user, with social and video applications capturing 60% of that time.
- Dating app revenue has surged 115% since 2018, while TikTok engagement grew by 75% year-over-year.
- The retail and service sectors saw significant digital transformation, highlighted by a 37% surge in food and drink app sessions.
Games India Plays!: A Look into the Gaming Habits of Indian Mobile Gamers and How to Reach Them
The Indian mobile gaming industry is undergoing a significant transformation, driven by affordable data, increased smartphone penetration, and a shift toward digital entertainment. This analysis, covering the 2022-2027 period, segments the market into Real Money Gaming (RMG)—including card-based and fantasy sports—and non-RMG categories like adventure, battle royale, and puzzles. Utilizing data from Newzoo and Affle MAAS, the findings highlight a market of 373 million online gamers as of 2022, with 91% playing on mobile devices. Revenue for 2022 reached $2.2 billion, with RMG contributing over 50% of the total industry revenue in the preceding year.
Demographic data reveals a young, male-skewing audience, particularly in the adventure and battle royale genres, where 55% of players are aged 13-27. While non-RMG players are motivated by stress relief and time-filling, RMG players are driven by seasonal events and the opportunity to earn rewards. Fantasy sports see massive spikes during major cricket tournaments, while card-based RMG peaks during festive seasons. Engagement is exceptionally high, with over 80% of mobile gamers consuming gaming video content and 44% engaging with esports.
For advertisers, the report establishes critical benchmarks and growth strategies. Successful user acquisition relies on navigating a complex funnel where install-to-registration rates hover around 25-50% depending on the sub-genre. Experts suggest that growth is increasingly driven by Tier 2 and Tier 3 cities, facilitated by UPI-based micro-payments. To maximize return on ad spend, marketers are encouraged to use vernacular creatives, programmatic targeting to reduce audience overlap, and a mix of ad formats like playable and short-video ads. The industry is poised for further disruption through the integration of Web3 technologies, blockchain-based play-to-earn models, and the rise of "gaming malls" or super-apps.
- The Indian mobile gaming market reached $2.2 billion in 2022, driven by a base of 373 million online gamers where 91% play exclusively on mobile devices.
- Real Money Gaming (RMG), including fantasy sports and card games, accounts for over 50% of total industry revenue.
- The core demographic for adventure and battle royale genres is young and male-skewing, with 55% of players falling within the 13-27 age bracket.
- User acquisition in the mobile gaming sector faces a 25-50% install-to-registration rate, with future growth increasingly concentrated in Tier 2 and Tier 3 cities.
- High engagement levels are evidenced by 80% of mobile gamers consuming gaming video content and 44% participating in esports.
Global Esports & Live Streaming Market Report
The global esports market is projected to reach $1.38 billion in revenue and an audience of 532 million by the end of 2022, signaling a period of robust expansion and structural evolution. China remains the dominant regional player, contributing nearly one-third of total global revenue. While sponsorships continue to serve as the industry’s financial backbone, accounting for approximately 60% of income, organizations are increasingly diversifying into direct-to-fan models. These new revenue streams include lifestyle apparel, blockchain-integrated loyalty programs, and educational platforms, reflecting a strategic shift toward positioning esports as a broader lifestyle brand.
The live-streaming ecosystem is experiencing even more rapid growth, with the audience expected to reach 1.41 billion by 2025 at a compound annual growth rate of 16.3%. This surge is fueled by the rise of non-gaming content and the explosive popularity of mobile esports in emerging markets such as Southeast Asia, Latin America, and the Middle East. Demographically, the esports audience represents a high-value target for advertisers, as nearly three-quarters of enthusiasts are employed full-time and 44% belong to high-income brackets.
Platform dynamics reveal a clear geographic and technological divide. Twitch maintains its dominance in Western markets for PC and console gaming, while YouTube Gaming and Facebook Gaming have successfully captured the mobile-centric audiences of emerging regions. To challenge established leaders, platforms are leveraging massive video-on-demand audiences and exclusivity deals to convert passive viewers into live participants. Despite this growth, the industry faces potential volatility from the fluctuating cryptocurrency sector and the possible migration of audiences toward emerging metaverse events.
- The global esports market is projected to reach $1.38 billion in revenue with 532 million viewers by the end of 2022, with China accounting for nearly one-third of total global revenue.
- The live-streaming audience is forecast to grow at a 16.3% compound annual growth rate, reaching 1.41 billion users by 2025.
- Sponsorships remain the primary financial driver at 60% of total income, though organizations are diversifying into lifestyle apparel, blockchain loyalty programs, and educational platforms.
- The esports demographic is highly attractive to advertisers, with 75% of enthusiasts employed full-time and 44% falling into high-income brackets.
- Platform dominance is split geographically, with Twitch leading Western PC and console markets while YouTube Gaming and Facebook Gaming capture mobile-centric audiences in Southeast Asia, Latin America, and the Middle East.
VR Games Market Report 2022
The virtual reality market is entering a period of significant expansion, with the global active hardware install base projected to reach 46 million units by 2024. This growth, characterized by a 42% compound annual growth rate, is primarily fueled by the rise of standalone headsets like the Meta Quest 2 and the release of high-quality software titles. While high-fidelity experiences still rely on PC-based hardware, the shift toward accessible, standalone devices has broadened the consumer base. Gaming remains the central pillar of the ecosystem, as 72% of headset owners identify it as their primary use case, and nearly 60% of users engage with their devices weekly.
Demographically, the VR audience consists largely of high-earning, tech-savvy males who prioritize immersion and social interaction. Popular genres such as adventure, shooters, and simulation dominate the landscape, mirroring traditional gaming trends, while survival horror and high fantasy themes capitalize on the unique immersive capabilities of the medium. The market is also seeing a diversification of content, with a balance between VR-exclusive titles and integrated experiences that offer VR support alongside traditional play modes.
The industry is maturing into a financially sustainable ecosystem through the adoption of hybridized monetization models, including downloadable content, subscriptions, and in-game transactions. Major investments from industry leaders like Meta, Sony, and Pico are driving the development of high-profile intellectual properties. Furthermore, the utility of VR is expanding beyond entertainment into social metaverse platforms and enterprise applications in healthcare, education, and manufacturing. This cross-sector growth is supported by the increasing versatility of 3D game engines, positioning VR as a critical technology for both consumer escapism and industrial innovation.
- The global active VR hardware install base is projected to reach 46 million units by 2024, driven by a 42% compound annual growth rate.
- Gaming is the primary driver of the VR ecosystem, with 72% of headset owners using devices for gaming and nearly 60% engaging with them on a weekly basis.
- Standalone headsets, such as the Meta Quest 2, are the primary catalysts for market expansion by increasing accessibility compared to traditional PC-based hardware.
- The VR market is achieving financial sustainability through hybridized monetization models that incorporate subscriptions, downloadable content, and in-game transactions.
- Industry leaders including Meta, Sony, and Pico are fueling growth by investing in high-profile intellectual properties and cross-sector applications in healthcare, education, and manufacturing.
Unity Gaming Report 2022
The global gaming industry experienced a massive production surge throughout 2021, characterized by a 93% increase in game creation and a 31% rise in the number of active creators. While the easing of pandemic-related restrictions led to a stabilization of engagement levels, the market established a "new normal" where total revenue grew by 30%. This growth was particularly pronounced in the Americas and EMEA regions, driven by a combination of in-app purchases and robust advertising revenue. Hypercasual and casual genres emerged as the primary catalysts for this expansion, with hypercasual titles seeing a 137% increase in production and a 162% surge in in-app purchase revenue.
Strategic shifts toward multiplatform development and multiplayer experiences are now essential for maximizing player retention and market reach. Although mobile remains the dominant platform, especially in markets like China and Japan, developers are increasingly prioritizing cross-platform compatibility to extend the lifespan of their titles. Industry consolidation reached record levels with $85 billion in acquisitions, yet small indie studios remain vital drivers of innovation. These smaller entities are leveraging accessible development tools and specialized analytics to compete with larger enterprises, focusing on "live game" models where consistent content updates can boost revenue by over 85% for top-performing games.
Portfolio diversification has proven to be a critical factor for financial success, as publishers operating across three or more genres generate up to 197% more daily revenue than those specializing in a single category. Despite this clear advantage, 76% of developers continue to focus on a single genre, representing a significant area for potential growth. Moving forward, the industry is trending toward the standardization of cross-platform play and the adoption of sophisticated third-party engagement tools. These advancements allow developers of all sizes to manage post-launch content more effectively, ensuring long-term sustainability in an increasingly competitive global market.
- Publishers operating across three or more genres generate up to 197% more daily revenue than those specializing in a single category, yet 76% of developers remain focused on a single genre.
- The gaming industry saw a 93% increase in game creation and a 30% rise in total revenue in 2021, with hypercasual titles experiencing a 137% production surge and a 162% increase in in-app purchase revenue.
- Industry consolidation reached record levels with $85 billion in acquisitions, while small indie studios continue to drive innovation by utilizing accessible tools and analytics.
- Top-performing 'live game' models that prioritize consistent content updates can boost revenue by over 85%.
- Multiplatform development and cross-platform compatibility have become essential strategies for maximizing player retention and extending the lifespan of titles.
Newzoo Gen Z & Gen Alpha Report 2022
This analysis examines the gaming behaviors and preferences of Gen Alpha (ages 10-12) and Gen Z (ages 13-27), positioning these cohorts as the primary drivers of the industry's future. The central thesis asserts that for these younger generations, gaming has evolved beyond a mere pastime into a ubiquitous "lifestyle" platform that fulfills fundamental needs for socialization, self-expression, and immersion. This shift is characterized by high engagement across multiple dimensions, including playing, viewing content, and participating in virtual social communities.
Key findings indicate that 90% of Gen Alpha and Gen Z are "game enthusiasts," significantly higher than the 79% found in the total online population. These groups invest a substantial portion of their leisure time in gaming; it is the top entertainment source for Gen Alpha and a top-three source for Gen Z, rivaling social networks and streaming. Socialization is a critical driver, with 70% of Gen Z expressing interest in using game worlds for social gatherings beyond active gameplay, such as attending virtual parties or watching movies. This behavior suggests these generations will be the primary catalysts for metaverse adoption.
Economic engagement is also high, with 52% of Gen Alpha and Gen Z spending money on games, compared to 42% of the general population. Mobile is the leading platform for both play and spend, though Gen Alpha shows a unique affinity for consoles driven by franchises like Fortnite and Mario. The primary motivators for spending include unlocking exclusive playable content and personalizing the in-game experience through virtual goods like currencies and gear.
The data is derived from Newzoo’s 2022 Global Gamer Research, utilizing Computer Assisted Web Interviewing (CAWI) conducted between February and April 2022. The study features a representative sample of 75,930 respondents across 36 global markets, covering North America, Europe, MEA, Latin America, and Asia-Pacific.
- 90% of Gen Alpha and Gen Z are game enthusiasts, significantly outpacing the 79% engagement rate found in the total online population.
- Gaming is the primary entertainment source for Gen Alpha and a top-three source for Gen Z, competing directly with social networks and streaming services.
- 70% of Gen Z are interested in using virtual game worlds for social activities beyond gameplay, such as attending parties or watching movies, positioning them as the primary drivers of metaverse adoption.
- Economic engagement is higher among younger cohorts, with 52% of Gen Alpha and Gen Z spending money on games compared to 42% of the general population.
- Mobile is the dominant platform for both play and spending, though Gen Alpha demonstrates a notable preference for consoles, specifically citing franchises like Fortnite and Mario.
Shooter Games
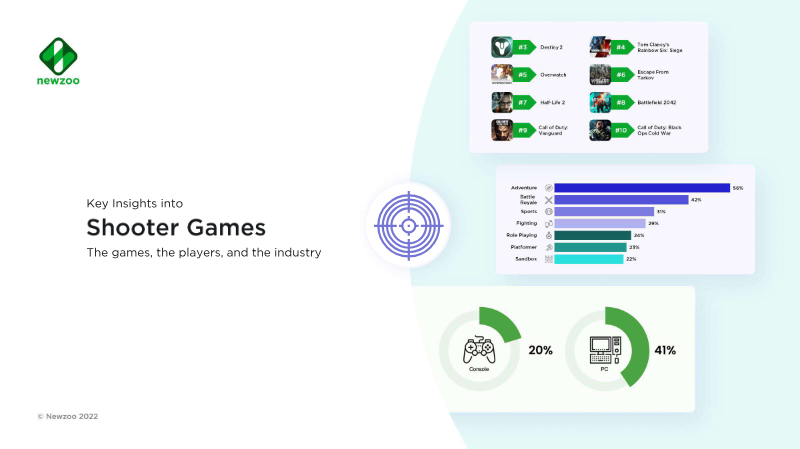
Shooter games represent the fifth highest-revenue generating genre globally as of 2022. This genre, defined by the primary mechanic of defeating enemies via firearms or projectiles, maintains a massive footprint across PC, console, and mobile platforms. While historical titles like Doom and Halo established the genre's foundation, modern success is driven by online competitive play and live streaming engagement. Notably, this analysis excludes Battle Royale and Vehicular Combat titles, which are classified as independent genres.
Data from August 2022 indicates that shooters command high engagement, ranking as a top genre for monthly active users on both Steam and consoles. The player base is predominantly male (63%) and young, with 38% of players falling between the ages of 10 and 20. High-intensity "Ultimate Gamers" and "All-Round Enthusiasts" show the strongest affinity for the genre, with 82% of the former group having played a shooter in the six months prior to the study. Beyond the core genre, shooter fans show significant cross-genre overlap with adventure and battle royale titles, while showing the least interest in simulation and strategy games.
The genre's ecosystem is heavily influenced by specific themes and monetization strategies. Contemporary war is the most popular theme, utilized by 68% of the player base, while levels and maps remain the dominant gameplay mechanic. In terms of monetization, the market is characterized by a high prevalence of both pay-to-play models and in-app purchases, with 97% of players engaging with titles that feature microtransactions. Geographically, the research covers 37 markets, excluding China and India, and utilizes a sample of over 19,000 active gamers to identify these behavioral and demographic trends.
- Shooter games are the fifth highest-revenue generating genre globally, maintaining a massive footprint across PC, console, and mobile platforms as of 2022.
- Monetization is heavily driven by microtransactions, with 97% of players engaging in titles that feature in-app purchases.
- The player base is predominantly male (63%) and young, with 38% of players falling within the 10 to 20 age demographic.
- Contemporary war is the most popular thematic element, preferred by 68% of the shooter player base.
- Engagement is highest among 'Ultimate Gamers,' 82% of whom have played a shooter in the six months prior to the August 2022 study.
Key Insights into Brazilian Gamers
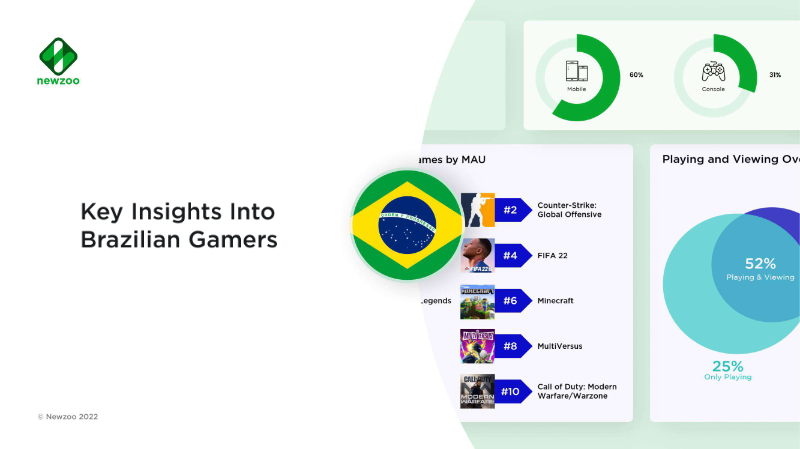
Brazil represents a significant force in the global gaming industry, ranking as the 10th largest market worldwide by revenue and 5th by total player count as of 2022. The region is characterized by high levels of engagement, with 80% of the online population identified as game enthusiasts. This engagement extends beyond play, as 60% of the audience both plays and watches gaming video content, while only 25% play without viewing.
The demographic profile of Brazilian gamers is diverse, though it skews toward younger males. Approximately 51% of players are male and 48% are female, with the 21–35 age bracket forming the largest segment at 43%. Mobile gaming is the dominant platform, utilized by 60% of the gaming population, followed by console and PC at 31% and 30% respectively. Despite the prevalence of mobile, average weekly play times are consistent across platforms, ranging from roughly four and a half to five hours.
Monetization trends indicate a healthy spending culture, with 43% of players classified as payers. The primary drivers for spending include unlocking exclusive playable content and personalizing in-game characters. Popular titles in the region include competitive and social games such as League of Legends, Fortnite, and Roblox.
The findings are based on a survey of 2,063 active internet users aged 10–65 in residential developed areas of Brazil. The methodology utilizes a "Residential Developed Approach," ensuring the data is representative of the connected population within these specific geographic zones. The research was conducted by Newzoo as part of their 2022 Global Games Market Report and Consumer Insights series.
- Brazil is the 10th largest gaming market globally by revenue and 5th by total player count as of 2022.
- Engagement is high, with 80% of the online population identified as game enthusiasts and 60% of players also consuming gaming video content.
- Mobile is the dominant platform, used by 60% of the gaming population, followed by consoles at 31% and PC at 30%.
- The player base is nearly evenly split by gender, with 51% male and 48% female, and the 21–35 age bracket representing the largest segment at 43%.
- 43% of Brazilian gamers are payers, with spending primarily driven by the desire to unlock exclusive content and personalize in-game characters.
Multiplayer Report 2022
The 2022 Multiplayer Report examines the evolving preferences, behaviors, and technical expectations of online gamers across major global markets. The primary thesis suggests that while traditional genres like Battle Royale and First-Person Shooters remain dominant, the success of multiplayer titles increasingly depends on social connectivity and technical reliability. The findings indicate that 77% of the global gaming population engages in multiplayer play, with overall engagement across all genres increasing by an average of 3.3% compared to the previous year.
Key data points highlight that genre is the primary factor for game selection (49%), followed closely by social drivers such as the ability to chat in-game (31%) and having friends already active in the title (34%). Technical performance is equally critical, with 35% of players prioritizing quick matchmaking and 33% requiring skill-based pairing. Regarding monetization, the data shows a 5% year-over-year increase in players purchasing downloadable content. While core gamers are 58% more likely to spend over $20 on additional content, casual audiences remain active spenders in lower price brackets.
The scope of the research covers four major gaming markets—the United States, United Kingdom, Japan, and South Korea—representing a significant portion of global gaming revenue. The analysis segments the industry into various categories, including mobile, PC, and console platforms, while distinguishing between casual and core gamer demographics. Internal data from Unity reveals a 150% growth in PC multiplayer development and a 40% increase in mobile multiplayer projects since early 2021.
Methodology for these insights involved a survey of approximately 1,500 multiplayer gamers conducted in Q3 2021 and Q3 2022. The sample was split evenly between casual players, defined by a minimum of 30 minutes of weekly multiplayer play, and core players, who engage for at least four hours weekly in competitive genres. This survey data was supplemented by anonymized, aggregated internal metrics from Unity’s live gaming solutions.
- Multiplayer gaming engagement grew by 3.3% year-over-year, with 77% of the global gaming population now participating in online play.
- Unity internal data shows a 150% surge in PC multiplayer development and a 40% increase in mobile multiplayer projects since early 2021.
- Genre remains the primary driver for game selection at 49%, followed by social connectivity factors including existing friend groups (34%) and in-game chat capabilities (31%).
- Technical performance is a critical retention factor, with 35% of players prioritizing quick matchmaking and 33% requiring skill-based pairing.
- Players purchasing downloadable content increased by 5% year-over-year, with core gamers being 58% more likely to spend over $20 on additional content than casual audiences.
Key Insights Into American Gamers
The United States represents the second-largest gaming market globally, generating $47.3 billion in revenue from a population of 191 million gamers. Research conducted in 2022 indicates that 72% of the American online population are game enthusiasts, a broad category encompassing those who play, watch, or socially engage with video games. While 71% of the population plays games, there is a significant overlap with viewership, as 44% of the population watches gaming video content and 18% engages with esports.
The demographic profile of American gamers is nearly evenly split by gender, with 52% identifying as male and 47% as female. Engagement spans all age groups, though the 21-35 bracket is the most active at 35%. Player motivations are diverse, led by social interaction (37%), action (37%), and achievement (36%). While mobile is the most popular platform by reach, capturing 48% of players, console gaming commands the highest engagement time, averaging six hours per week.
Economic engagement is high, with 49% of the online population spending money on games. The primary drivers for spending include the desire to play with friends or family, taking advantage of sales, and unlocking exclusive content. Popular titles like Fortnite, Grand Theft Auto V, and Call of Duty dominate the market, with shooters and adventure games ranking as the top genres by monthly active users. This data is derived from a 2022 consumer insights survey of 3,054 online respondents in the U.S., part of a broader global study covering 36 markets.
- The U.S. gaming market generated $47.3 billion in revenue from 191 million gamers, representing 72% of the online population.
- Engagement is driven by a mix of play and viewership, with 71% of the population playing games, 44% watching gaming content, and 18% engaging with esports.
- Mobile is the most popular platform by reach at 48%, while console gaming commands the highest engagement at an average of six hours per week.
- The demographic profile is nearly evenly split, with 52% male and 47% female, and the 21-35 age bracket serving as the most active segment at 35%.
- Nearly half of the online population (49%) spends money on games, primarily motivated by social interaction, sales, and exclusive content.