Market Analysis
Documents
The True Cost of Building a Mobile Game Backend
This analysis examines the financial and operational costs associated with developing in-house backend technology for mobile games. The primary thesis suggests that while third-party game engines have become industry standards, backend infrastructure is currently undergoing a similar shift as the technical demands of live-service games outpace the practicality of internal development.
The findings are based on a survey of 125 C-level executives and tech leads at US-based mobile game studios with at least 50 employees, conducted in April 2024. Data indicates that the average leading US studio employs 52 developers for 36 months to build and maintain an internal backend. With an average annual salary of $138,864 per developer, the direct financial investment for a custom backend is estimated at approximately $21.6 million. The research notes that strategy and shooter genres are most likely to require these complex systems, while hypercasual games are increasingly adopting them to support "hybridcasual" live-ops models.
Beyond direct costs, the analysis identifies significant "hidden" human and operational tolls. Approximately 50% of surveyed studios reported that diverting gameplay programmers to backend tasks slowed overall game development. Furthermore, one-third of respondents experienced higher employee turnover and increased "crunch" periods, while 20% reported direct revenue loss. The study concludes that the decision to build internal tech often results in negative knock-on effects across departments, suggesting that third-party solutions offer a more sustainable path for scaling live-service titles without sacrificing personnel well-being or development velocity.
- Building an in-house mobile game backend costs an average of $21.6 million, requiring 52 developers working over a 36-month period.
- Diverting gameplay programmers to backend infrastructure tasks slows overall development velocity for 50% of surveyed studios.
- Internal backend development contributes to negative organizational outcomes, including increased employee turnover, higher rates of crunch, and direct revenue loss for 20% of studios.
- The technical demands of live-service games are driving a shift toward third-party backend solutions, mirroring the industry-wide adoption of third-party game engines.
- While strategy and shooter genres have the highest requirement for complex backend systems, the rise of 'hybridcasual' models is expanding this need to the hypercasual sector.
The Golden Age of Video Game Remakes and Remasters
The video game industry has entered a definitive era of remakes and remasters, fueled by a risk-averse development climate and the significant purchasing power of nostalgic Millennial consumers. These projects serve as a strategic hedge against the rising costs of original intellectual property, allowing developers to re-engage dormant fanbases while attracting new audiences through modernized graphics and gameplay. Success in this sector depends heavily on timing and the specific nature of the renewal. Remasters perform most effectively when released within five years of an original title to capitalize on hardware transitions. Conversely, full remakes require a longer gestation period, typically between nine and twenty-five years, to ensure that technological advancements are substantial enough to justify a full-price purchase.
Effective remakes must strike a delicate balance between preservation and modernization. Developers are encouraged to maintain the core essence and iconic moments of a title—such as specific art styles or dialogue—while aggressively updating outdated mechanics like quick-time events. Leveraging contemporary hardware capabilities, such as 3D audio and advanced rendering, is essential for meeting modern player expectations. By aligning these updates with a clear vision for modernization, studios can successfully bridge the gap between historical authenticity and current industry standards.
This 2024 analysis provides a comprehensive overview of the global gaming landscape, focusing on the strategic advantages of revitalizing established franchises. While the findings highlight clear pathways to commercial success through market-tested IPs, the data is intended for informational purposes and reflects the broader trends shaping the current development cycle. Ultimately, the strategic deployment of remakes and remasters reduces financial volatility for studios while ensuring that classic gaming experiences remain accessible and relevant in a rapidly evolving technological environment.
- Remakes and remasters serve as a strategic financial hedge against the rising costs of developing original intellectual property in a risk-averse industry.
- Full remakes require a gestation period of nine to twenty-five years to ensure technological advancements are significant enough to justify a full-price purchase.
- Remasters are most commercially effective when released within five years of the original title to capitalize on hardware transitions.
- Successful revitalization requires balancing the preservation of iconic elements, such as art style and dialogue, with the aggressive modernization of outdated mechanics like quick-time events.
- Studios must leverage contemporary hardware capabilities, including 3D audio and advanced rendering, to meet modern player expectations for updated titles.
The Games We Watched: Lurkit’s Top 500 Streaming Report Q1 2024
The global game streaming market experienced a 10% year-over-year growth in the first quarter of 2024, with the top 500 titles on Twitch generating 3.8 billion hours of watch time. While industry mainstays like Grand Theft Auto V and League of Legends continue to lead the market with 479 million and 379 million hours watched respectively, the landscape is showing signs of gradual diversification. The market share held by the top ten developers decreased from 63% to 59% compared to the previous year, driven in part by breakout successes like Palworld, which secured the eleventh position with 76 million hours watched shortly after its release.
The streaming ecosystem maintains a robust long tail of engagement that spans various genres and eras. Beyond the top-tier competitive titles, significant viewership is distributed across a mix of recent AAA releases, such as Rise of the Ronin and The Legend of Zelda: Tears of the Kingdom, and enduring legacy games like Skyrim and Pokémon Red. Even titles at the lower end of the top 500 rankings, including older entries like L.A. Noire and Morrowind, consistently command over 328,000 hours watched per quarter. This indicates that community interest remains high for both modern indie simulations and classic console franchises long after their initial launch windows.
Methodologically, this analysis focuses strictly on video game content by excluding non-gaming categories such as Just Chatting and filtering out inactive streams to ensure data integrity. The findings highlight a healthy balance between the dominance of established live-service giants and the sustained relevance of a diverse catalog of titles. This trend underscores a maturing market where niche audiences and retro communities contribute significantly to the overall growth and stability of the global streaming audience throughout the early months of 2024.
- The global game streaming market grew 10% year-over-year in Q1 2024, with the top 500 titles on Twitch generating 3.8 billion hours of watch time.
- Market dominance by the top ten developers is softening, with their collective market share dropping from 63% to 59% compared to the previous year.
- Grand Theft Auto V and League of Legends remain the market leaders, recording 479 million and 379 million hours watched respectively.
- New releases are successfully disrupting the rankings, evidenced by Palworld securing the eleventh position with 76 million hours watched shortly after its launch.
- The streaming ecosystem shows high long-tail engagement, with even the lower-ranked titles in the top 500 consistently generating over 328,000 hours of watch time per quarter.
Live-Streaming Trends Report: Q1 2024
The live-streaming industry experienced a significant resurgence in the first quarter of 2024, with global viewership reaching 8.2 billion hours watched. This represents a 10% year-over-year increase and marks the first Q1 growth since 2021, signaling a recovery from the post-pandemic decline. While Twitch remains the dominant platform with a 69% market share, its lead narrowed as competitors like YouTube Gaming and Kick gained ground. Notably, Steam emerged as a breakout platform by doubling its hours watched, largely driven by developers using the service to market new releases.
Geographic shifts were prominent in South Korea following Twitch’s exit from the market. Local platforms AfreecaTV and the Naver-backed newcomer Chzzk successfully absorbed the displaced audience, with Chzzk showing rapid growth and high creator retention. In terms of content, Palworld dominated as the top game launch of the quarter, generating 95 million hours watched in its first 30 days and outperforming 2023’s major hits. Grand Theft Auto V reclaimed the overall top spot among games, while the First-Person Shooter (FPS) genre led all categories due to high-profile esports tournaments for Counter-Strike and VALORANT.
The analysis highlights a diversifying creator landscape where co-streaming major events remains a primary driver for top talent like Gaules and Jynxzi. In the female and VTuber segments, established names like Amouranth and Pekora Ch. reclaimed top rankings, while new entrants leveraged trending titles like Palworld and GTA V to achieve triple-digit growth. This data, compiled by Stream Hatchet, utilizes metrics such as hours watched and average concurrent viewers across all major global streaming platforms to provide a comprehensive overview of the current state of digital broadcast media.
- Global live-streaming viewership reached 8.2 billion hours in Q1 2024, marking a 10% year-over-year increase and the first Q1 growth since 2021.
- Twitch maintains a 69% market share, though its dominance is being challenged by YouTube Gaming, Kick, and Steam, the latter of which doubled its hours watched this quarter.
- Twitch’s exit from South Korea triggered a successful migration of viewers to local platforms, specifically AfreecaTV and the rapidly growing Chzzk.
- Palworld became the quarter's top game launch with 95 million hours watched in its first 30 days, while Grand Theft Auto V reclaimed the top spot for overall viewership.
- The First-Person Shooter (FPS) genre led all content categories in Q1 2024, bolstered by major esports tournaments for Counter-Strike and VALORANT.
State of Play: Spring Edition
Mobile gaming has solidified its position as the industry’s primary driver, currently engaging 1.9 billion players and tracking toward $118 billion in annual revenue by 2027. This growth is occurring alongside a fundamental restructuring of digital commerce. Regulatory shifts, such as the European Union’s Digital Markets Act and recent judicial rulings, are dismantling the traditional walled gardens of major app stores. By forcing the adoption of alternative billing systems and out-of-app commerce, these changes allow developers to bypass standard commission fees and engage in direct-to-consumer marketing, fundamentally altering the economics of mobile distribution.
The industry is simultaneously transitioning toward a cross-platform ecosystem where seamless play and unified payment systems across mobile, PC, and console are becoming standard. Consumer behavior supports this shift, as 87% of multiplayer gamers now engage in cross-platform play. Younger demographics, specifically Gen Alpha and Gen Z, exhibit a 52% payer conversion rate, significantly outperforming older cohorts. To capture this value, developers are increasingly forming strategic alliances with telecommunications providers to integrate 5G infrastructure and mobile wallets, ensuring frictionless transactions in a "cross-pay" environment.
Despite a significant cooling in investment during 2023—characterized by a 75% drop in Web3 funding and a 43% decline in merger and acquisition activity—the sector is recalibrating toward a sustainable "new normal." The workforce is becoming more formalized, with nearly three-quarters of designers holding university degrees. Market analysts anticipate a recovery throughout 2024, marked by a 20% increase in deal flow and the entry of major media entities like Netflix and Disney. This stabilization is supported by a shift in venture capital toward alternative models that prioritize marketing and operational support over traditional equity-only investments.
- Mobile gaming is the industry's primary growth engine, with 1.9 billion players and projected annual revenue of $118 billion by 2027.
- Regulatory changes like the EU's Digital Markets Act are dismantling app store walled gardens, enabling developers to bypass standard commission fees through alternative billing and direct-to-consumer commerce.
- Cross-platform play is now a standard expectation, with 87% of multiplayer gamers participating and developers increasingly integrating 5G and mobile wallets to facilitate unified 'cross-pay' ecosystems.
- Younger demographics (Gen Alpha and Gen Z) are driving monetization, exhibiting a 52% payer conversion rate that significantly outperforms older player cohorts.
- After a 2023 downturn featuring a 75% drop in Web3 funding and a 43% decline in M&A activity, the market is projected to recover in 2024 with a 20% increase in deal flow.
European Key Facts 2023: Video Games Industry
The European video games industry is a significant cultural and economic driver, characterized by steady growth and a commitment to responsible gameplay. In 2023, the European market reached €25.7 billion in revenue, a 5% year-on-year increase. The sector employs approximately 115,000 people across Europe, with 90,000 based in the EU. This growth is supported by a diverse player base; 53% of the European population aged 6-64 plays video games, with an average player age of 31.4 years. Notably, 75% of players are adults, and women make up 43.5% of the total gaming population.
The industry emphasizes a robust framework for minor protection and consumer transparency through the Pan European Game Information (PEGI) system. Celebrating its 20th anniversary, PEGI has issued nearly 40,000 age rating licenses across 40 countries. Awareness of these labels is high, with 79% of parents whose children play games recognizing the system. Furthermore, the industry actively promotes diversity and inclusion through various regional initiatives and addresses environmental sustainability via the Games Consoles Voluntary Agreement and the Playing for the Planet Alliance.
To maintain global competitiveness, the industry advocates for a strategic EU policy framework. Key priorities include recognizing video games as unique creative works distinct from the audiovisual sector, addressing the digital skills gap through education and STEAM programs, and maintaining a fair regulatory environment that supports small and medium-sized enterprises. The data for these findings is derived from GameTrack and Games Sales Data (GSD) surveys conducted by Ipsos, involving a sample of 60,000 individuals across major European markets to ensure national representation.
- The European video games industry generated €25.7 billion in revenue in 2023, representing a 5% year-on-year growth.
- The sector employs 115,000 people across Europe, with 90,000 of those roles based within the EU.
- Video games reach 53% of the European population aged 6–64, with an average player age of 31.4 years, 75% adult representation, and 43.5% female participation.
- The PEGI age-rating system has issued nearly 40,000 licenses over 20 years, with 79% of parents recognizing the labels.
- Industry advocacy focuses on securing a policy framework that classifies video games as unique creative works distinct from the audiovisual sector.
Brazilian Gaming Industry Report 2023
The Brazilian gaming industry represents a rapidly maturing ecosystem that defied global trends in 2022, growing by 3% to reach 103 million players while the international market experienced its first contraction. With 1,042 active studios as of 2023—a 177% increase over five years—the sector is primarily composed of micro and small enterprises concentrated in the Southeast and South regions. Despite this expansion, local studio revenue accounts for only 10% of domestic consumption, highlighting a significant gap between local production and the country’s status as the world’s fifth-largest online gaming population.
Development trends show a shift toward multi-platform strategies, with computers and mobile devices serving as the primary targets for the 1,009 games produced in 2022. While 93% of studios develop proprietary intellectual property, there is a burgeoning reliance on international markets; 65% of studios active abroad derive more than half of their revenue from exports. Furthermore, the industry has seen a 62% surge in outsourcing services, particularly in 3D art and animation, signaling a transition toward high-value service provision for the global entertainment sector.
The workforce expanded to over 13,000 professionals in 2022, characterized by a 70% remote work rate and an increasing focus on administrative roles that suggest greater corporate maturity. However, the industry faces persistent structural and social challenges. The lack of a specific national economic classification complicates data collection, while diversity remains a critical area for improvement. Women represent only 24.3% of the workforce, and minority groups remain underrepresented. While external initiatives and diversity councils aim to foster inclusivity, 82% of companies still lack formal internal inclusion policies, indicating that the sector’s social evolution has yet to match its rapid economic and technical acceleration.
- Brazil’s gaming market grew 3% in 2022 to 103 million players, even as the global market contracted, yet local studios capture only 10% of domestic consumption.
- The number of active gaming studios in Brazil reached 1,042 in 2023, representing a 177% increase over the previous five years.
- The industry is increasingly export-oriented, with 65% of studios operating abroad generating more than half of their revenue from international markets.
- Outsourcing services, particularly in 3D art and animation, surged by 62% in 2022, marking a shift toward providing high-value services to the global entertainment sector.
- The workforce grew to over 13,000 professionals in 2022, with a 70% remote work rate and a growing emphasis on administrative roles indicating increased corporate maturity.
Turkey Game Market 2023 Report
The Turkish gaming market demonstrated significant resilience and maturation throughout 2023, maintaining its status as a premier hub within the Europe and MENA regions despite economic volatility and regional challenges. Generating $580 million in revenue from a robust base of 47 million gamers, the industry is characterized by a dominant mobile sector that mirrors global trends. While total revenue in USD saw a slight decline due to currency fluctuations and platform policy changes, the market grew in local currency terms, fueled by high internet penetration and a population that views gaming as a primary social ritual.
Mobile gaming remains the cornerstone of the ecosystem, with Turkish developers achieving international acclaim. Notably, Dream Games’ Royal Match became the world’s highest-grossing mobile title in late 2023, underscoring the global competitiveness of domestic studios. Beyond entertainment, the industry is expanding into "serious games" and gamification, with major brands in finance, aviation, and retail integrating game mechanics to drive customer loyalty. This diversification extends to the defense and health sectors, where simulation technologies are increasingly utilized.
The investment landscape transitioned into a maturation phase in 2023, with $33.27 million across 35 deals. While this represents a decrease from pandemic-era peaks, the infrastructure continues to strengthen through the rise of digital entrepreneurship centers and structured esports regulations. The esports sector is professionalizing rapidly, supported by 188 licensed teams and significant international victories in titles like Valorant. However, a critical talent gap remains; while academic programs in game design are proliferating, there is an urgent need for better synchronization between university curricula and practical industry requirements to sustain long-term growth.
Looking toward 2024, the market is poised for further expansion driven by AI-driven content, AR/VR advancements, and a shift toward direct-to-consumer business models. Success for international and local players alike depends on deep localization and cultural sensitivity, ensuring engagement with a diverse demographic that increasingly prioritizes price-performance ratios and local payment solutions.
- The Turkish gaming market generated $580 million in 2023 from a base of 47 million gamers, maintaining its status as a key regional hub despite currency-related revenue fluctuations.
- Mobile gaming remains the industry cornerstone, highlighted by the domestic studio Dream Games, whose title 'Royal Match' became the highest-grossing mobile game globally in late 2023.
- The investment landscape matured in 2023 with $33.27 million deployed across 35 deals, reflecting a shift toward sustainable growth following pandemic-era peaks.
- Turkish industries are increasingly adopting gamification and simulation technologies, integrating game mechanics into sectors such as finance, aviation, retail, defense, and health.
- The esports ecosystem is professionalizing rapidly, currently supported by 188 licensed teams and bolstered by international competitive success in titles like 'Valorant'.
State of the Market 2023: An Annual Analysis of App Market and Advertising Activities
The 2023 market analysis evaluates global mobile advertising performance, concentrating on the two dominant operating systems, iOS and Android, and the leading social platforms that drive ad spend. Facebook and Instagram continue to command the largest share of the social advertising ecosystem, reinforcing their status as primary channels for marketers seeking broad reach and engagement across diverse audiences.
Video advertising emerged as the pre‑eminent format throughout the year, registering a 16 % increase on iOS and a markedly higher 37 % rise on Android. This divergence underscores Android’s accelerating momentum in video consumption and ad adoption, while iOS maintains steady growth. Interactive ad formats also showed modest gains, with a 2.7 % uplift on iOS, indicating a gradual shift toward more engaging user experiences, though the expansion remains limited compared with video.
Overall, the findings suggest that mobile video continues to dominate revenue generation, with Android delivering the strongest growth trajectory. The incremental rise in interactive formats points to emerging opportunities for richer creative solutions, yet video’s dominance will likely shape strategic allocations for the coming year. These trends highlight the importance of platform‑specific optimization and the need for advertisers to balance high‑impact video placements with exploratory interactive formats to maximize reach and performance across the mobile landscape.
- Video advertising is the primary revenue driver, experiencing a 37% growth on Android and a 16% increase on iOS during 2023.
- Facebook and Instagram remain the dominant platforms for social advertising, serving as the primary channels for broad audience reach and engagement.
- Android is outpacing iOS in video ad adoption, demonstrating a significantly stronger growth trajectory for video-based marketing strategies.
- Interactive ad formats saw a modest 2.7% growth on iOS, signaling a slow but emerging shift toward more engaging, non-video user experiences.
- Advertisers should prioritize platform-specific optimization by balancing high-impact video placements with exploratory interactive formats to maximize performance.
US Gaming Audience in 2023
The gaming landscape in 2024 has solidified as a mainstream entertainment pillar, with 62% of U.S. adults aged 18 to 65 identifying as active gamers. This audience is characterized by high engagement across multiple devices, as 77% of players utilize more than one platform and 40% play across PC, console, and mobile combined. While mobile-only gamers typically prefer free-to-play titles, console and PC players demonstrate a high willingness to invest in premium content, with 45% of all gamers spending over $40 on their most recent purchase.
The demographic profile of the U.S. gaming audience skews toward Millennials and spans a wide range of household income levels. Genre preferences vary by platform; PC gamers favor first-person shooters, action, and role-playing games, while console players show a strong preference for action-adventure, sports, and racing titles. This broad reach is further amplified by the success of video game intellectual property in other media, evidenced by significant box office performance for game-inspired films.
Advertising within the gaming ecosystem presents significant opportunities for brand growth through formats such as intrinsic in-game ads, rewarded video, and sponsorships. Approximately two-thirds of gamers view advertisements as having a positive or neutral impact on their experience, with 34% noting that product placements can enhance realism. Case studies, such as campaigns by Tommy Hilfiger, demonstrate that non-intrusive in-game ads can drive substantial lifts in brand favorability, recommendation, and purchase intent. Through partnerships between measurement firms like Comscore and ad-tech providers like Anzu, advertisers can now better quantify the incremental reach provided by these specialized digital environments.
- 62% of U.S. adults aged 18 to 65 are active gamers, with 77% of players utilizing multiple platforms and 40% playing across PC, console, and mobile combined.
- 45% of all gamers spent over $40 on their most recent purchase, indicating a strong willingness to invest in premium content among PC and console users.
- Approximately two-thirds of gamers view advertisements as having a positive or neutral impact on their gaming experience, with 34% stating that product placements can enhance realism.
- Non-intrusive in-game advertising, such as campaigns by Tommy Hilfiger, has been shown to drive measurable lifts in brand favorability, recommendation, and purchase intent.
- Genre preferences are platform-specific, with PC gamers favoring first-person shooters, action, and RPGs, while console players prefer action-adventure, sports, and racing titles.
The Ultimate Game Hype Tracking Guide
This guide provides a framework for tracking game performance through the purchase funnel, emphasizing the importance of monitoring consumer sentiment from the pre-launch phase through the post-release lifecycle. The primary thesis is that success in the competitive PC and console gaming market requires a data-driven understanding of player awareness, purchase intent, and demographic behavior. By benchmarking these metrics against competitors, developers can optimize marketing spend, identify target audiences, and sustain long-term engagement.
The analysis relies on data from the Game Health Tracker, which surveys over 3,000 PC and console players in the United States monthly. Key metrics include unaided awareness, which measures spontaneous brand recall, and aided awareness, which gauges maximum reach through prompted recognition. The findings demonstrate that awareness often fluctuates based on major industry events, such as trailer releases or gameplay reveals. Furthermore, the conversion rate—defined as the percentage of aided-aware players who express purchase intent—serves as a critical indicator of marketing effectiveness.
The research highlights that demographic profiling and channel analysis are essential for resource allocation. For example, data shows that younger players may be more effectively reached through specific social media platforms like TikTok and Snapchat, whereas older or different segments might prioritize online stores or gaming subscriptions. Post-release, the guide notes that awareness naturally plateaus, necessitating tactical interventions such as price drops, DLC releases, or content updates to re-engage potential buyers. Ultimately, the document concludes that while initial hype is valuable, sustained success depends on continuously monitoring the purchase funnel and adapting strategies to meet the evolving motivations of both primary and secondary player audiences.
- Success in the PC and console market requires tracking the purchase funnel through three core metrics: unaided awareness, aided awareness, and purchase intent conversion rates.
- The Game Health Tracker methodology relies on monthly surveys of over 3,000 PC and console players in the United States to benchmark performance against competitors.
- Conversion rate, defined as the percentage of aided-aware players who express purchase intent, serves as the primary indicator for measuring marketing effectiveness.
- Awareness levels are highly volatile and correlate directly with major industry milestones, such as trailer releases and gameplay reveals.
- Marketing resource allocation must be demographic-specific, as younger players are more effectively reached via TikTok and Snapchat, while older segments prioritize online stores and subscriptions.
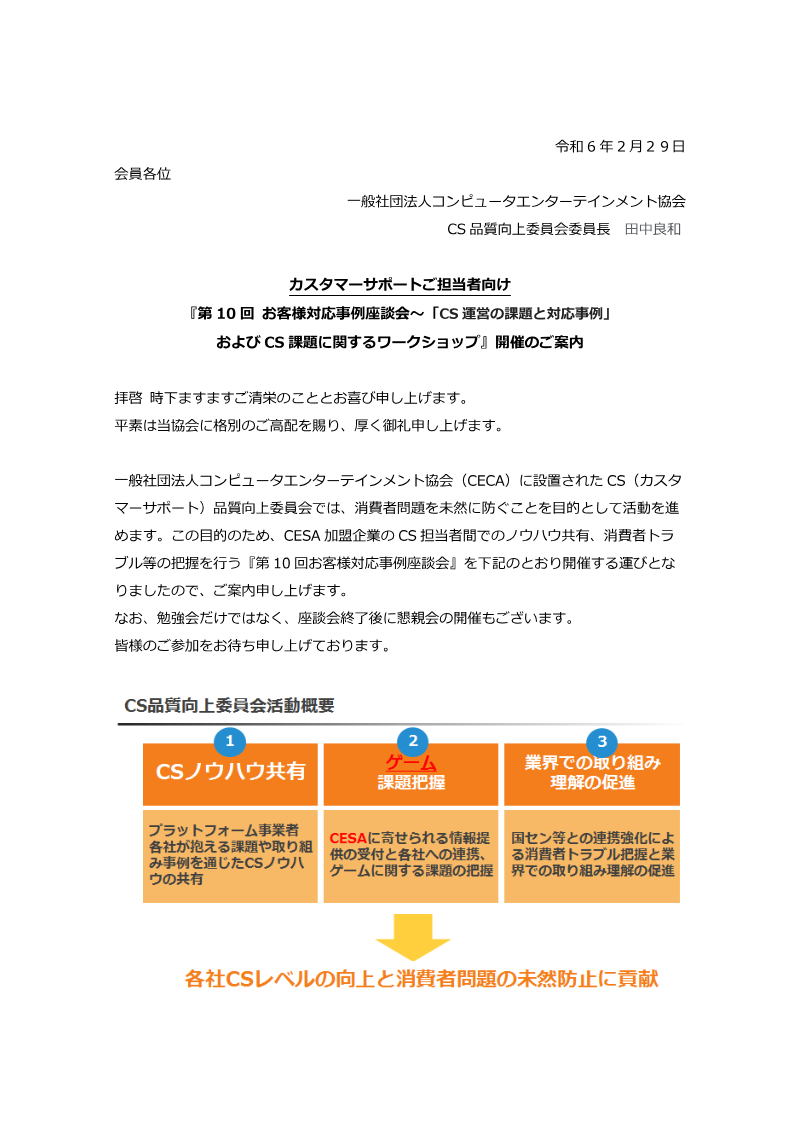
第10回 お客様対応事例座談会〜「CS運営の課題と対応事例」および CS課題に関するワークショップ
The announcement seeks to convene customer‑support managers from member firms of the Computer Entertainment Association (CECA) to exchange practical solutions for ongoing CS operational challenges. Its central aim is to foster preventive measures against consumer‑related issues by facilitating knowledge sharing on two focal topics: the integration of AI tools into support workflows and the management of customer harassment incidents.
The event is scheduled for March 19, 2024, running from 16:00 to 18:00, with a reception beginning at 15:30. It will be held simultaneously at the Shinjuku Sumitomo Sky Room in Tokyo and via Zoom, allowing both in‑person and online participation. Attendance is limited to CECA members, with pre‑registration required by March 8; excess demand may be redirected to the virtual format. The agenda includes opening remarks, case‑study presentations on AI adoption and harassment handling, and a workshop where groups of six to seven participants will discuss these issues in breakout rooms, followed by a plenary debrief. A networking reception follows, with an estimated fee of ¥5,000 per participant.
The scope is confined to the Japanese computer‑entertainment sector, targeting CS professionals active in 2024. While no empirical data are presented, the format emphasizes interactive discussion and peer‑learning rather than formal survey analysis, positioning the gathering as a practical forum for collective problem‑solving and the dissemination of best practices within the industry.
- The Computer Entertainment Association (CECA) is hosting a customer support forum on March 19, 2024, focused on AI integration and managing customer harassment.
- The event is restricted to CECA member firms, with a pre-registration deadline of March 8, 2024.
- The program features case-study presentations and small-group workshops of six to seven participants to facilitate peer-to-peer knowledge sharing.
- The session will be held in a hybrid format at the Shinjuku Sumitomo Sky Room in Tokyo and via Zoom, with a ¥5,000 fee for the networking reception.
- The forum aims to establish industry-wide preventive measures and best practices for CS operational challenges in the Japanese computer-entertainment sector.