Market Analysis reports and market data
Documents
GI Podcast | Call of Duty, Game Pass, and the Mario movie
Microsoft is fundamentally restructuring its Xbox Game Pass strategy, pivoting away from the aggressive "Netflix for games" model toward a more sustainable financial framework.
- Microsoft is restructuring Xbox Game Pass to move away from a 'Netflix for games' model toward a tiered, segmented strategy that restricts day-one access to protect revenue for high-budget titles.
- The release of Call of Duty: Black Ops 6 caused a 71 percent surge in monthly active users, but engagement levels quickly reverted to historical baselines, indicating that the franchise's core audience does not drive long-term subscription growth.
- Gaming studios are increasingly pivoting toward Hollywood adaptations, driven by the box office success of franchises like Super Mario and Sonic the Hedgehog, and are now scouting platforms like Roblox for future cinematic IP.
🚨📢 BREAKING NEWS: Microsoft changes Game Pass, Roblox goes over 3K headcount, Ubisoft as usual :/
This analysis covers significant industry shifts and corporate developments occurring in the gaming sector during the second quarter of 2026.
- Microsoft has adjusted its Game Pass strategy by lowering subscription prices and delaying the release of Call of Duty titles until one year after their initial launch.
- Roblox reported a 36% year-over-year revenue increase to nearly $5 billion and expanded its full-time workforce by 24% to over 3,000 employees.
- Ubisoft continues to implement cost-cutting measures, most recently resulting in the cancellation of its life-simulation project, Altera.
The story of Samson: The buggy GTA-style game that just had to launch this month
The global gaming industry is currently navigating a period of significant structural recalibration, characterized by shifting subscription models and volatile market performance.
- The gaming industry is undergoing structural recalibration, evidenced by a 5% increase in U.S. consumer spending and a 69% surge in U.K. hardware sales driven by anticipation for the Nintendo Switch 2.
- Major industry players are adjusting strategies, such as Xbox reducing Game Pass pricing by 23% and delaying the inclusion of flagship titles like Call of Duty.
- The open-world title Samson highlights the risks of independent production, as Liquid Swords was forced to pivot to a self-publishing model in 2025 due to a lack of publisher funding.
TWIG #380: Game Pass Gets Cheaper, China's Mobile Dominance & Division Resurgence Reviewed
The gaming industry is currently undergoing a structural realignment as the subscription-based model, often likened to a Netflix for games, fails to achieve long-term viability in Western markets.
- Xbox has reduced the price of Game Pass Ultimate by 23% and removed day-one access for major titles like Call of Duty, signaling a shift away from the unsustainable Netflix-style subscription model in Western markets.
- Publishers from China, Hong Kong, and Singapore now command 30% of Western mobile gaming revenue, highlighting the inability of Western developers to compete with Eastern production scale and rapid replication.
- Western firms are pivoting away from content-heavy subscription services to focus on high-margin infrastructure, including AI development, engine technology, and marketplace management.
🎲Dicero: Habby’s biggest bet (And biggest risk?)
Habby is undergoing a fundamental strategic transition, moving away from the hypercasual-adjacent success of titles like Survivor.io toward a more complex, midcore model exemplified by its latest release, Dicero.
- Habby is pivoting from hypercasual-adjacent titles like Survivor.io to a midcore model with Dicero, characterized by complex gacha mechanics, tiered evolution, and a slower-paced merging economy.
- The studio has abandoned rewarded advertisements in favor of a direct-to-consumer web store and high-intent monetization, marking a fundamental shift in its revenue strategy.
- Habby is currently facing its lowest revenue and download figures in recent history, casting doubt on whether its new, more complex gameplay can achieve the same market penetration as previous hits.
Apple's undercooked games efforts, Google's big AI claims, Ilkka's BAFTA speech, data, jobs, more
The mobile games industry is currently navigating a period of significant transition, marked by shifting leadership at major platform holders, the pervasive yet often clandestine integration of artificial intelligence, and the ongoing evolution of indie development.
- Google Cloud's games division reports that approximately 90% of game studios are currently using AI tools in development, though many studios underreport this usage to avoid public backlash.
- Apple's leadership under Tim Cook has historically shown disinterest in the gaming sector, exemplified by the perfunctory nature of the Apple Games app and Cook's own admission of not being a gamer during the Epic trial.
- Leadership changes at Apple, including the promotion of John Ternus and new App Store management under Carson Oliver and Anne Thai, may signal a shift toward better developer relations and increased focus on gaming hardware.
UA Monthly #3: Freecash Ban, Unity Kills ironSource & Vector’s Rise
The recent deplatforming of the rewarded ad network Freecash underscores a critical shift in the mobile user acquisition landscape, signaling that app stores are increasingly intolerant of aggressive, non-native incentive models.
- The deplatforming of Freecash signals that app stores are increasingly penalizing aggressive, non-native incentive models and deceptive affiliate marketing practices.
- Advertisers should treat rewarded traffic as a transient resource and diversify spending away from high-risk, single-network dependencies to mitigate performance decay.
- Unity is pivoting its advertising strategy toward the Vector AI solution following the integration of ironSource, though current performance metrics remain inconsistent.
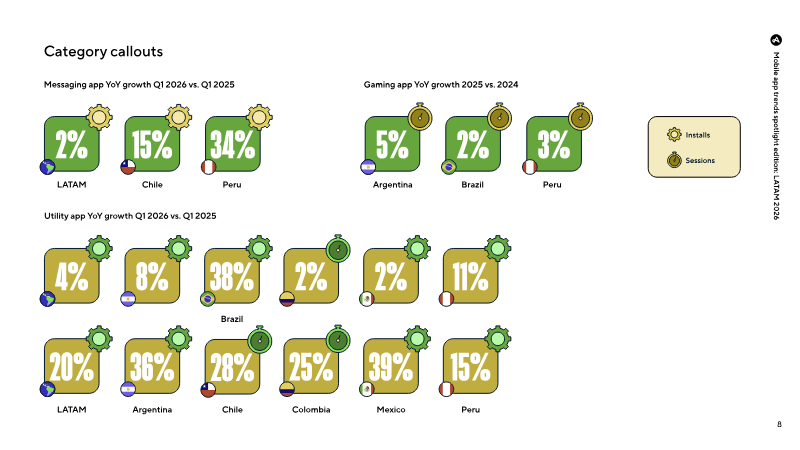
Mobile App Trends: LATAM
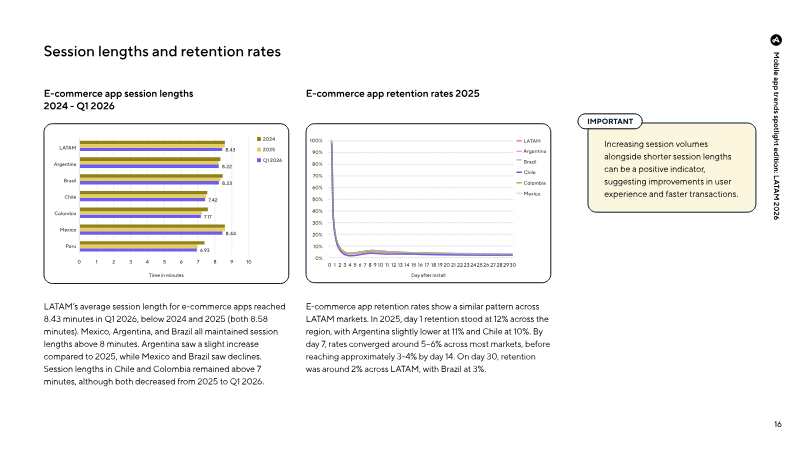
The "Mobile App Trends: LATAM 2026" report analyzes app performance benchmarks and insights across Latin America, focusing on installs, sessions, session lengths, and retention rates.
- The Latin American mobile app market is projected to reach a valuation of $56.1 billion by 2034, supported by a smartphone penetration rate expected to hit 93% by 2030.
- User privacy opt-in rates in the region reached 49% in Q1 2026, significantly outperforming the 38% global average, with Brazil leading at 54%.
- Finance apps experienced a 34% year-over-year increase in session activity during Q1 2026, driven by the adoption of super apps and real-time payment systems like Brazil’s Pix.
The Prosperous Society, Part 3: The Collapse of the Pareto Principle
The traditional dominance of the Pareto Principle in commerce is undergoing a fundamental collapse as artificial intelligence dismantles the industrial constraints that once necessitated mass-market homogeneity.
- AI-driven personalization is dismantling the Pareto Principle by removing the industrial constraints that previously forced firms to prioritize mass-market homogeneity over niche preferences.
- The shift from standardized production to precision demand routing allows firms to profitably serve idiosyncratic consumer segments that were previously commercially unviable.
- Economic value is being unlocked through improved matching efficiency between specialized supply and individual demand, moving the market away from synthetic demand creation.
The state of the UK games industry with UKIE CEO Nick Poole
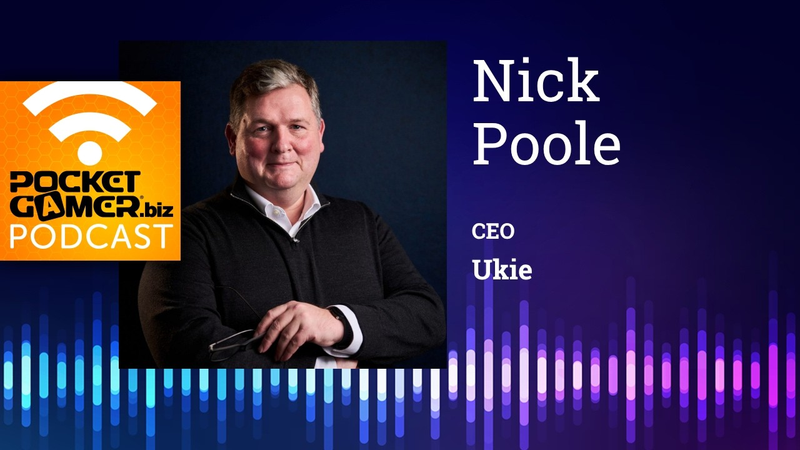
The United Kingdom games industry stands as a global creative powerhouse, yet its long-term stability is currently hindered by a lack of coordinated political advocacy and structural support comparable to the film and television sectors.
- The UK games industry contributes approximately £6 billion in Gross Value Added (GVA) to the economy and generates an additional £1.3 billion for other sectors through game technology.
- UK tax relief for games is currently 5 percentage points lower than the rates provided to the film and TV industries, creating a competitive disadvantage for domestic studios.
- The UK risks becoming an 'incubator economy' where talent and innovation are developed but not retained, necessitating a shift toward building sustainable, long-term companies rather than just individual games.
Left VC to Become a Founder Again. Here's What They Don't Tell You About Running a Fund
The venture capital landscape has undergone a significant shift, rendering the fundraising environment for micro-funds increasingly difficult in a post-pandemic economy.
- The current fundraising environment for micro-funds is increasingly difficult, forcing managers to spend over 50% of their time on capital acquisition rather than portfolio support.
- Industry clout and operational experience are insufficient substitutes for direct, high-level institutional relationships when attempting to secure fund backing.
- The micro-VC model is currently a low-margin, grueling endeavor that often requires independent wealth or a long-term bootstrapping mindset to remain sustainable.
How's it going, Outfit7? Learnings from 2025 to New Projects in 2026
Outfit7, the developer behind the Talking Tom franchise, navigated a challenging 2025 by shifting from a KPI-driven, siloed organizational structure back to its core creative roots.
- Outfit7’s Talking Tom IP remains the global leader in mobile game downloads, surpassing 27 billion lifetime downloads as of 2025.
- To combat declining organic reach and rising user acquisition costs, Outfit7 shifted its strategy back to its core roots by focusing on clear project goals, remastering original titles, and expanding into the kids' segment with new products like Talking Tom and Friends World.
- The company successfully launched the survival roguelike game 'Vampirio' by empowering a small, autonomous team with full trust and resources, demonstrating that focused, silo-free teams outperform larger, distracted groups.