Market Analysis
Documents
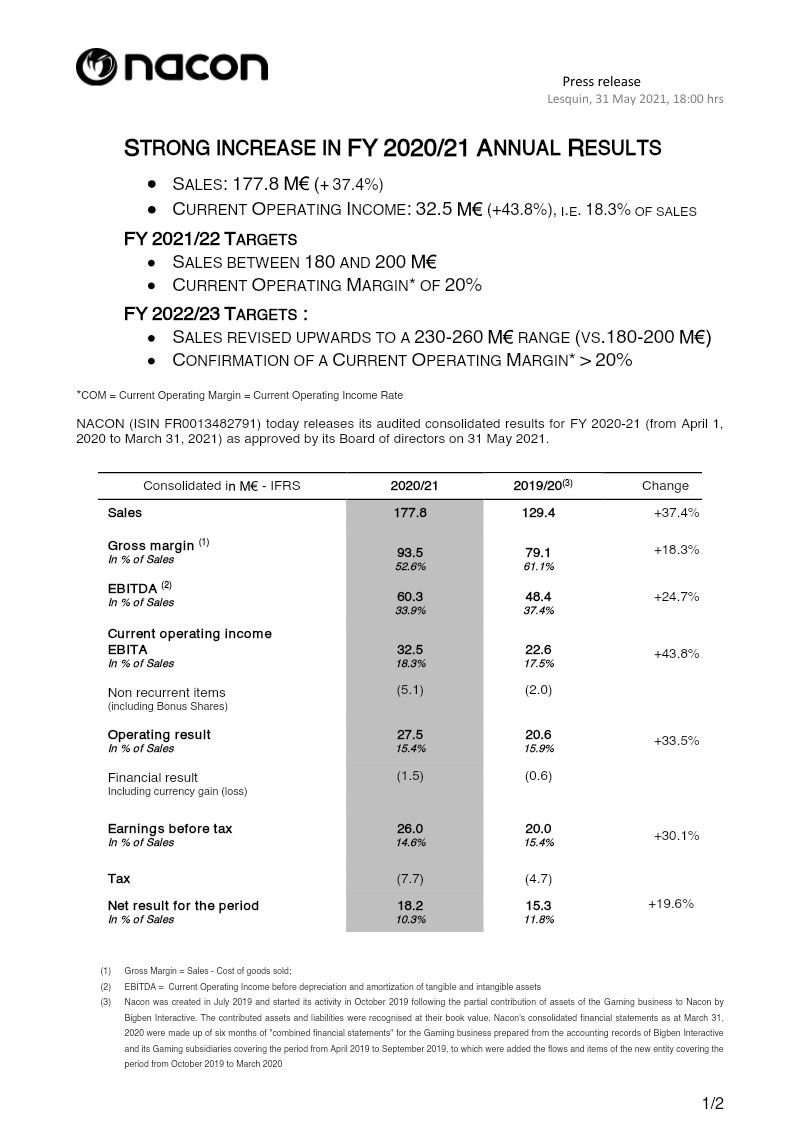
FY 2020/21 Annual Results: Nacon
Nacon reported a robust FY 2020/21 performance, with sales rising 37.4 % to €177.8 million and current operating income increasing 43.8 % to €32.5 million, representing 18.3 % of sales. Gross margin improved to 52.6 % from 61.1 %, while EBITDA grew 24.7 % to €60.3 million (33.9 % of sales). Net profit reached €18.2 million, up 19.6 %, after accounting for a €5.1 million bonus‑share expense, a €1.5 million financial charge and €7.7 million in tax. Operating cash flow surged 146 % to €55.7 million, sufficient to cover CAPEX of €56.4 million and bank repayments, leaving cash and equivalents at €96.7 million.
The company attributes growth to premium accessories, successful U.S. expansion, and a tripling of back‑catalogue sales. Forecasts for FY 2021/22 have been raised to €180–200 million in sales with a 20 % operating margin, driven by digital catalogues and new titles such as RIMS Racing and Blood Bowl 3. For FY 2022/23, sales targets are further increased to €230–260 million, maintaining a margin above 20 %, supported by studio acquisitions and high‑profile releases like The Lord of the Rings.
Nacon, listed on Euronext Paris (ISIN FR0013482791), operates through 18 subsidiaries and a distribution network covering 100 countries, employing over 600 staff. The board has opted to retain earnings for reinvestment rather than distribute a dividend in FY 2020/21.
- Nacon achieved strong FY 2020/21 growth with sales rising 37.4% to €177.8 million and current operating income increasing 43.8% to €32.5 million.
- Operating cash flow surged 146% to €55.7 million, supporting a year-end cash position of €96.7 million despite €56.4 million in capital expenditures.
- The company raised its FY 2021/22 sales guidance to €180–200 million with a 20% operating margin, followed by an increased FY 2022/23 target of €230–260 million.
- Growth drivers for the fiscal year included strong performance in premium accessories, successful U.S. market expansion, and a tripling of back-catalogue sales.
- Future revenue growth is anchored by upcoming titles including 'RIMS Racing', 'Blood Bowl 3', and 'The Lord of the Rings', alongside ongoing studio acquisitions.
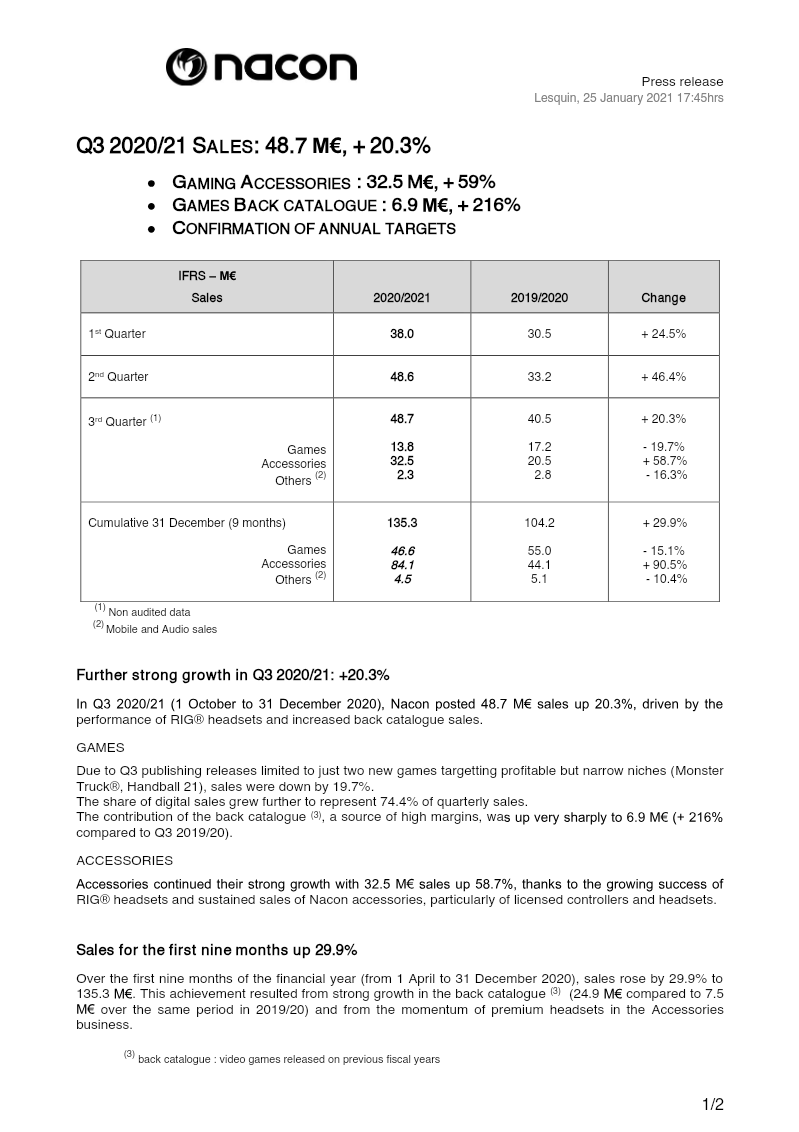
Q3 2020/21 Sales: 48.7 M€, + 20.3%
Nacon reported Q3 2020/21 sales of €48.7 million, a 20.3 % increase over the same period in 2019/20, driven primarily by a surge in gaming accessories and back‑catalogue sales. Accessories grew 58.7 % to €32.5 million, largely due to the RIG® headset line and licensed controller sales, while back‑catalogue revenue jumped 216 % to €6.9 million, reflecting high‑margin older titles. Game sales fell 19.7 % to €13.8 million, with only two new releases (Monster Truck® and Handball 21) and a digital sales share of 74.4 %. Other revenue, mainly mobile and audio, declined 16.3 % to €2.3 million.
Cumulative sales for the first nine months rose 29.9 % to €135.3 million, with accessories contributing a 90.5 % increase and back‑catalogue sales up 24.9 million versus €7.5 million in the prior year. The company projects Q4 growth, citing upcoming releases such as Werewolf® : The Apocalypse – Earthblood and new console versions of Monster Truck®, Tennis World Tour 2, and Hunting Simulator 2. Digital sales, back‑catalogue momentum, and a robust order book for RIG® headphones are expected to sustain the upward trajectory.
Nacon confirms its annual target of €160–170 million in sales with an 18 % operating margin, and it has announced the acquisition of Australian studio Big Ant to strengthen its sports‑game portfolio. No dividend will be paid in 2020/21, as funds are earmarked for studio acquisitions and development. The company maintains a 2023 plan targeting €180–200 million in sales with an operating margin above 20 % for 2022/23.
- Nacon reported Q3 2020/21 sales of €48.7 million, a 20.3% year-over-year increase, bringing cumulative nine-month sales to €135.3 million.
- Growth was driven by a 58.7% surge in accessories revenue to €32.5 million and a 216% increase in back-catalogue sales to €6.9 million.
- New game sales declined 19.7% to €13.8 million during the quarter, reflecting a light release schedule of only two titles.
- The company confirmed its annual fiscal target of €160–170 million in sales with an 18% operating margin, while maintaining a long-term 2022/23 goal of €180–200 million in sales.
- Nacon acquired Australian studio Big Ant to bolster its sports-game portfolio and will forgo a dividend payment to prioritize capital for acquisitions and development.
Universal Registration Document 2020/2021
Société anonyme governed by a Board of Directors with share capital of €84,908,919 Registered office: 396/466, Rue de la Voyette, CRT 2, 59273 Fretin, France Registration number: 852 538 461 RCS Lille Métropole UNIVERSAL REGISTRATION DOCUMENT This universal registration document was approved on 6 July 2021 by the Autorité des Marchés Financiers (“AMF”) as the competent authority in respect of regulation (EU) 2017/1129.
- Nacon, a gaming company, had its Universal Registration Document approved by the AMF on July 6, 2021, valid until July 5, 2022.
- Nacon amortizes game development costs for new games released from April 1, 2020, over a four-year period using the diminishing balance method, reflecting market digitalization and extended game lifespans.
- Nacon's strategy involves a balanced game lineup across four genres (racing, sports, action/adventure, simulations), including high-budget and lower-cost games, and both existing and new IPs, to mitigate risk and ensure long-term profitability.
- Nacon has nearly 30 years of experience in the third-party accessories market, with a strong European presence for 20 years, supported by subsidiaries across major European countries and exclusive global distributors.
- Nacon's staff turnover increased slightly from 12.9% at March 31, 2020, to 13.3% at March 31, 2021, despite an active HR policy focused on recruitment, training, retention, and an attractive workplace culture.
Interim Financial Report: First Half 2020/21
INTERIM FINANCIAL REPORT FOR THE SIX MONTHS ENDED 30 SEPTEMBER 2020 – NACON SIX MONTHS ENDED 30 SEPTEMBER 2020 SIX MONTHS ENDED 30 SEPTEMBER 2020 TABLE OF CONTENTS 2 1. STATEMENT BY THE PERSON RESPONSIBLE 3 2.
- NACON's net income significantly increased by 46.7% to €9.6 million in the first half of 2020/21, up from €6.5 million in the first half of 2019/20.
- Recurring operating income for NACON rose by 47.4% to €15.7 million in the first half of 2020/21, compared to €10.7 million in the prior year, driven by increased revenue, reduced external expenses, and controlled personnel costs.
- Consolidated revenue for NACON grew by 35.9% to €86.6 million in the first half of 2020/21, with gaming accessories revenue more than doubling from €23.6 million to €51.6 million, now representing 60% of total revenue.
- NACON acquired 100% of Belgian development studio Neopica Srl on October 19, 2020, a studio known for developing around 60 games including Hunting Simulator 1 & 2 and FIA European Truck Racing Championship.
- NACON's EBITDA reached €30.4 million in the first half of 2020/21, representing 35.1% of revenue, up from €23.5 million (37.0% of revenue) in the first half of 2019/20.
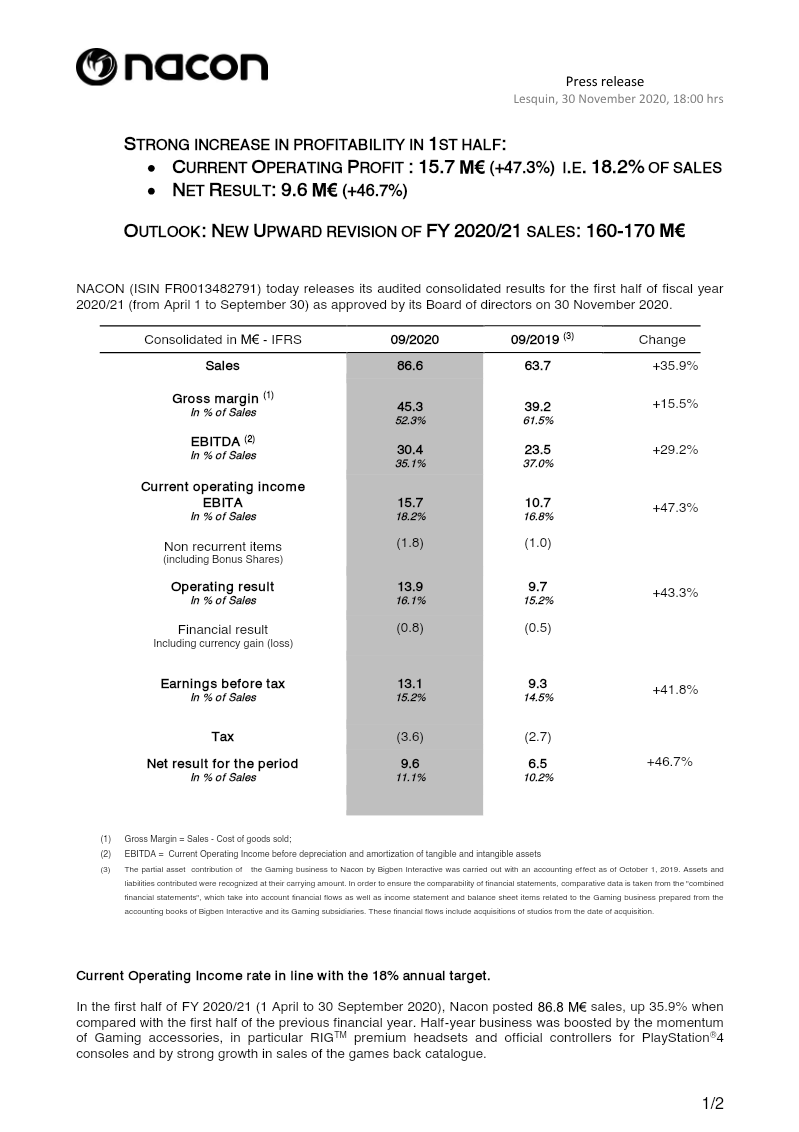
Strong Increase in Profitability in 1st Half: Fiscal Year 2020/21
Nacon reports a strong first‑half performance for fiscal year 2020/21, with sales rising 35.9 % to €86.6 million and gross margin improving from 39.2 % to 45.3 %. Current operating income (COI) increased by 47.3 % to €15.7 million, representing 18.2 % of sales and meeting the company’s annual COI target of 18 %. Net profit for the period reached €9.6 million, up 46.7 % from €6.5 million in the prior year’s first half, after accounting for €1.8 million in bonus‑share expenses and €0.8 million in net financial costs.
Operating cash flow surged to €34.1 million, enabling the group to self‑finance €25.9 million of capital expenditure and generate an €8.2 million free cash flow. Net cash at 30 September stood at €50.7 million, up from €42.8 million in March 2020, despite a €5 million increase in CAPEX and loan repayments.
The growth is attributed to momentum in gaming accessories—particularly premium headsets and official PlayStation 4 controllers—and a robust back‑catalogue of games. Nacon projects continued sales acceleration in the second half, driven by dual‑generation console support (PS 4/5, Xbox One/Xbox Series), digital sales expansion, and releases of next‑gen titles such as WRC 9 and Tennis World Tour 2. Consequently, the company has revised its FY 2020/21 sales target upward to €160–170 million and maintains an 18 % COI goal. For FY 2022/23, Nacon targets sales of €180–200 million with a COI exceeding 20 %. The data derive from audited consolidated IFRS statements covering April–September 2020, with comparative figures adjusted for the 2019 acquisition of Bigben Interactive’s gaming assets.
- Nacon reported a 35.9% increase in H1 2020/21 sales to €86.6 million, with net profit rising 46.7% to €9.6 million.
- Current operating income (COI) grew 47.3% to €15.7 million, hitting the company's 18% annual margin target ahead of schedule.
- The company raised its FY 2020/21 sales guidance to €160–170 million, while setting a long-term FY 2022/23 target of €180–200 million with a COI exceeding 20%.
- Operating cash flow reached €34.1 million, resulting in a net cash position of €50.7 million as of September 30, 2020.
- Growth was driven by strong performance in gaming accessories, specifically premium headsets and PlayStation 4 controllers, alongside a robust back-catalogue of games.
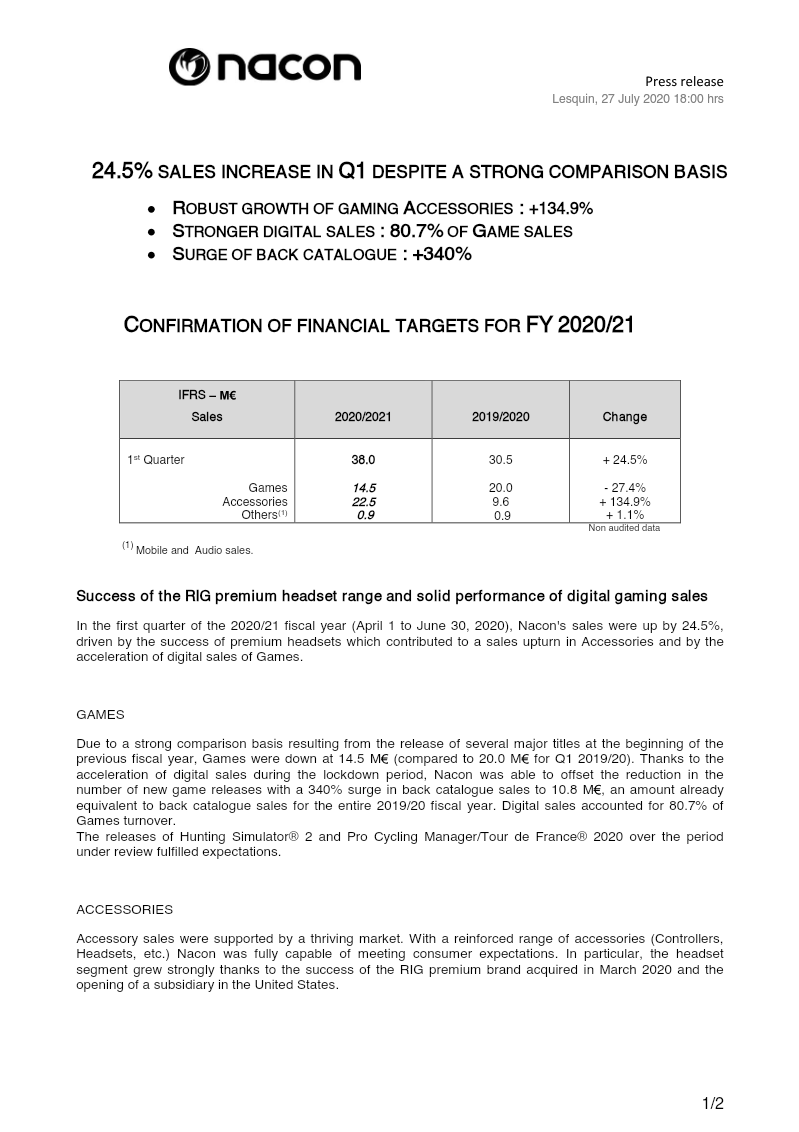
Q1 2020/21 Sales Results: 24.5% Sales Increase Despite a Strong Comparison Basis
Nacon reported a 24.5 % rise in first‑quarter sales for FY 2020/21, reaching €38.0 million against €30.5 million in the same period a year earlier, confirming its annual financial targets. The growth was driven primarily by accessories and digital game sales. Accessories surged 134.9 % to €22.5 million, propelled by the launch of the RIG premium headset line and a new U.S. subsidiary. Digital game sales, which accounted for 80.7 % of total game revenue, offset a decline in new releases; back‑catalogue sales jumped 340 % to €10.8 million, matching the entire previous year’s back‑catalogue volume.
Game sales fell to €14.5 million from €20.0 million due to a strong comparison base of major titles released in the prior fiscal year, but the accelerated digital channel and successful releases such as Hunting Simulator 2 and Pro Cycling Manager/Tour de France 2020 mitigated the impact. Other revenue categories remained flat.
Geographically, Nacon operates through 16 subsidiaries and a distribution network spanning 100 countries, with recent expansion into the United States. The company’s outlook for Q2 and the remainder of FY 2020/21 remains positive, citing upcoming releases (WRC 9, Tennis World Tour 2, Monster Truck Championship), continued digital momentum, and a new partnership with Microsoft for console‑compatible controllers. Nacon projects FY 2020/21 sales between €140–€150 million and a 18 % operating margin, while maintaining its 2023 plan targets of €180–€200 million sales and over 20 % margin for FY 2022/23.
- Nacon achieved a 24.5% year-over-year sales increase in Q1 2020/21, reaching €38.0 million and confirming its annual revenue target of €140–€150 million.
- Accessory sales surged 134.9% to €22.5 million, driven by the launch of the RIG premium headset line and the establishment of a new U.S. subsidiary.
- Back-catalogue digital game sales grew 340% to €10.8 million, matching the total volume of the previous fiscal year and offsetting a decline in new game releases.
- Total game revenue fell to €14.5 million from €20.0 million due to a strong comparison base from the prior year, though digital channels accounted for 80.7% of this segment.
- The company maintains its 2023 strategic targets of €180–€200 million in sales and an operating margin exceeding 20%.
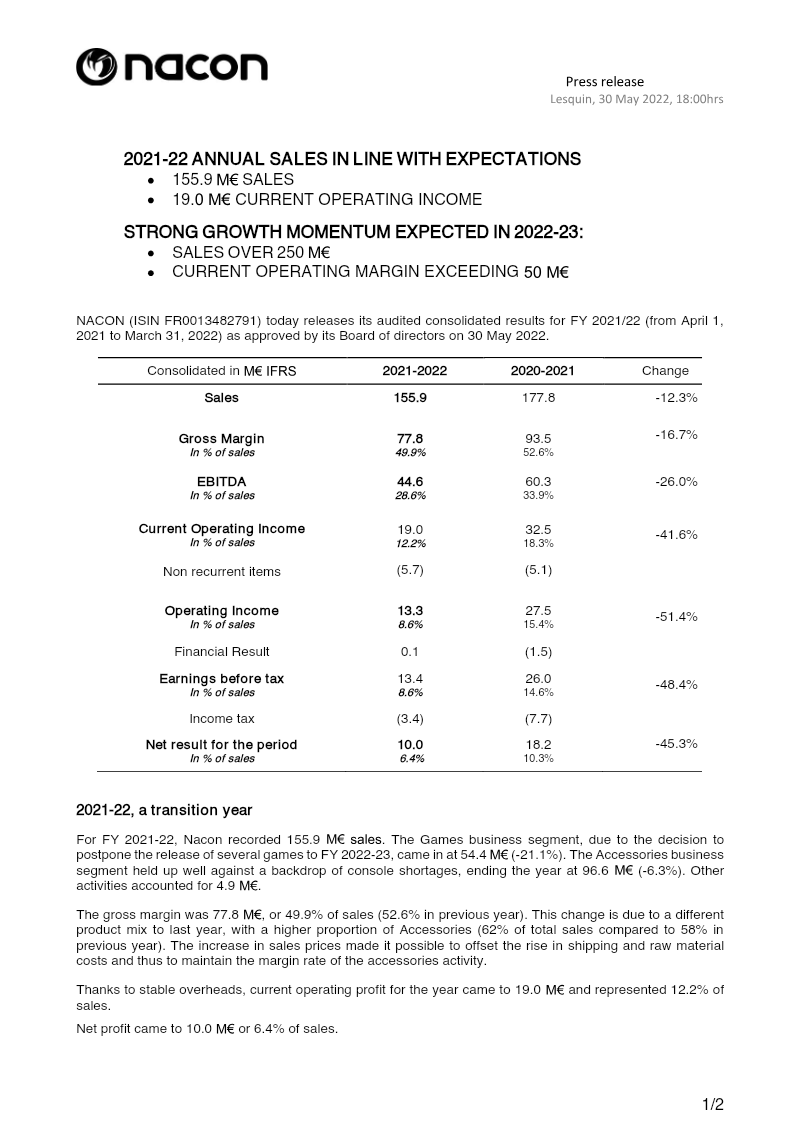
2021-22 Annual Sales: Audited Consolidated Results
Nacon’s audited consolidated results for the fiscal year ending 31 March 2022 show sales of €155.9 million, a decline of 12.3 % from the previous year’s €177.8 million, driven largely by a 21.1 % drop in the Games segment after postponing several releases to FY 2022‑23. The Accessories segment, however, remained resilient amid global console shortages, recording €96.6 million in sales (down 6.3 %) and contributing a higher proportion of revenue (62 % versus 58 % previously). Gross margin fell to €77.8 million (49.9 % of sales) from €93.5 million (52.6 %) due to the altered product mix, though price increases offset rising shipping and raw‑material costs. EBITDA contracted 26 % to €44.6 million (28.6 % of sales), and current operating income dropped 41.6 % to €19.0 million (12.2 % of sales). Net profit fell 45.3 % to €10.0 million (6.4 % of sales).
The balance sheet reflects significant investment activity: shareholders’ equity rose to €228.4 million, new bank debt of €52.5 million was issued at sub‑1 % interest, and net debt remained low at €10.4 million. Working capital increased by €8.7 million due to higher inventories, while operating cash flow reached €32.4 million and intangible CAPEX totaled €57.4 million. Over the past two years, Nacon has invested over €100 million in game development and acquired nine studios, expanding its pipeline to 46 titles from 33.
Management projects a sharp rebound in FY 2022‑23, targeting sales above €250 million and a current operating margin exceeding €50 million, supported by new releases such as Vampire: The Masquerade®‑Swansong and The Lord of the Rings Gollum. The company will continue external growth through studio acquisitions, notably Midgar Studio and Daedalic Entertainment.
- Nacon reported FY 2021-22 sales of €155.9 million, a 12.3% decline from the previous year, primarily due to a 21.1% drop in the Games segment following the postponement of several titles.
- Management projects a significant rebound for FY 2022-23 with a sales target exceeding €250 million and an operating margin above €50 million, driven by releases like 'Vampire: The Masquerade – Swansong' and 'The Lord of the Rings: Gollum'.
- Net profit fell 45.3% to €10.0 million, while current operating income dropped 41.6% to €19.0 million, reflecting the impact of the altered product mix and increased operational costs.
- The Accessories segment proved resilient despite global console shortages, generating €96.6 million in sales and increasing its share of total revenue to 62%.
- Nacon has aggressively expanded its development pipeline to 46 titles, supported by over €100 million in development investment and the acquisition of nine studios, including Midgar Studio and Daedalic Entertainment, over the past two years.
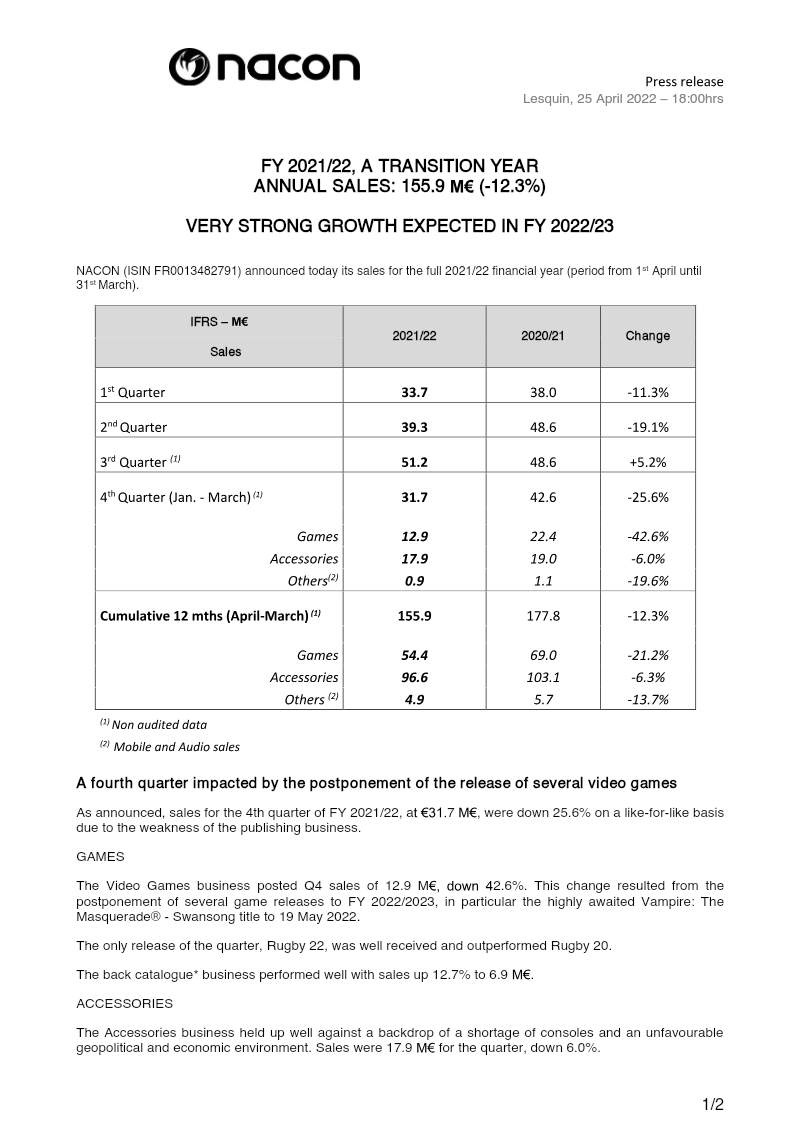
FY 2021/22 Annual Sales: A Transition Year
Nacon reported FY 2021/22 sales of €155.9 million, a 12.3 % decline from the previous year’s €177.8 million. The drop was driven mainly by a 25.6 % fall in fourth‑quarter sales to €31.7 million, largely due to postponed game releases such as Vampire: The Masquerade® – Swansong. Game sales for the year fell 21.2 % to €54.4 million, while accessories declined 6.3 % to €96.6 million; mobile and audio sales also contracted by 13.7 %. The back‑catalogue segment performed modestly better, up 12.7 % to €6.9 million.
Quarterly performance showed a sharp decline in Q1 (€33.7 M) and Q2 (€39.3 M), a modest rebound in Q3 (€51.2 M, +5.2 %), and a significant drop in Q4 (€31.7 M). The company’s operating income for the year is projected between €17 million and €19 million, reflecting the weaker Q4 results.
Looking ahead to FY 2022/23, Nacon anticipates a strong rebound driven by a robust game pipeline—including titles such as Vampire: The Masquerade® – Swansong, Zorro The Chronicles, and Tour de France 2022—and expects sales between €250 million and €300 million with an operating margin above 20 %. The strategy includes further external growth through acquisitions of Midgar Studio and Daedalic Entertainment to enhance internal development capabilities.
The figures cover global operations across 20 subsidiaries, with a workforce of over 700 employees and distribution in more than 100 countries. The data are presented under IFRS, with non‑audited figures for the fourth quarter and a note that mobile and audio sales are included in the “Others” category.
- Nacon reported FY 2021/22 sales of €155.9 million, representing a 12.3% year-over-year decline from €177.8 million.
- The company projects a significant recovery for FY 2022/23, targeting sales between €250 million and €300 million with an operating margin exceeding 20%.
- Annual game sales fell 21.2% to €54.4 million, while accessories declined 6.3% to €96.6 million.
- The sharp 25.6% drop in Q4 sales to €31.7 million was primarily attributed to the postponement of key titles like Vampire: The Masquerade – Swansong.
- Nacon is pursuing external growth through the acquisitions of Midgar Studio and Daedalic Entertainment to bolster internal development capabilities.
Results Briefing Materials: Third Quarter Fiscal Year Ending March 31, 2026
The briefing outlines Daemon Machina’s third‑quarter performance for the fiscal year ending March 2026, highlighting a 140.5 % jump in net sales to ¥29,121 million driven by the launch of three core titles—Rune Factory: Guardians of Azuma, Story of Seasons: Grand Bazaar, and Browser Sangokushi Ten—and robust amusement‑machine sales. Operating profit rose modestly to ¥1,776 million (6.1 % YoY) as high development costs offset gains; ordinary profit and owners’ attributable profit grew faster, largely due to foreign‑exchange gains. Segment analysis shows Digital Contents Business sales at ¥9,985 million (169.2 % YoY) and Amusement Business at ¥7,435 million (125.1 % YoY), while Audio & Visual Business declined by 88.7 %. The company’s balance sheet strengthened, with total assets increasing to ¥35,669 million and net assets rising by ¥1,104 million.
Strategic initiatives include scheduled releases of Rune Factory on PlayStation 5 and Xbox Series X|S in February 2026, a postponed launch of The Thousand Musketeers: Rhodoknight to June 2026, and ongoing promotion of new online titles. The amusement segment continues to expand overseas, with Pokémon‑branded machines generating significant revenue growth.
Full‑year forecasts remain unchanged: net sales projected at ¥35,000 million (125.2 % YoY), operating profit at ¥2,000 million (110 % YoY), and owners’ attributable profit at ¥1,400 million (171 % YoY). Dividend guidance is raised to ¥12 per share. The company acknowledges potential uncertainties that could affect future performance.
- Daemon Machina reported a 140.5% surge in net sales to ¥29,121 million for Q3 FY2026, driven by the release of three core titles and strong amusement-machine performance.
- Operating profit grew by 6.1% to ¥1,776 million, as significant development costs partially offset the substantial revenue gains.
- The Digital Contents segment saw a 169.2% increase in sales to ¥9,985 million, while the Amusement segment grew 125.1% to ¥7,435 million, bolstered by overseas Pokémon-branded machine sales.
- Full-year forecasts remain unchanged with projected net sales of ¥35,000 million and operating profit of ¥2,000 million, while dividend guidance was increased to ¥12 per share.
- The Audio & Visual Business experienced a sharp decline of 88.7% during the quarter.
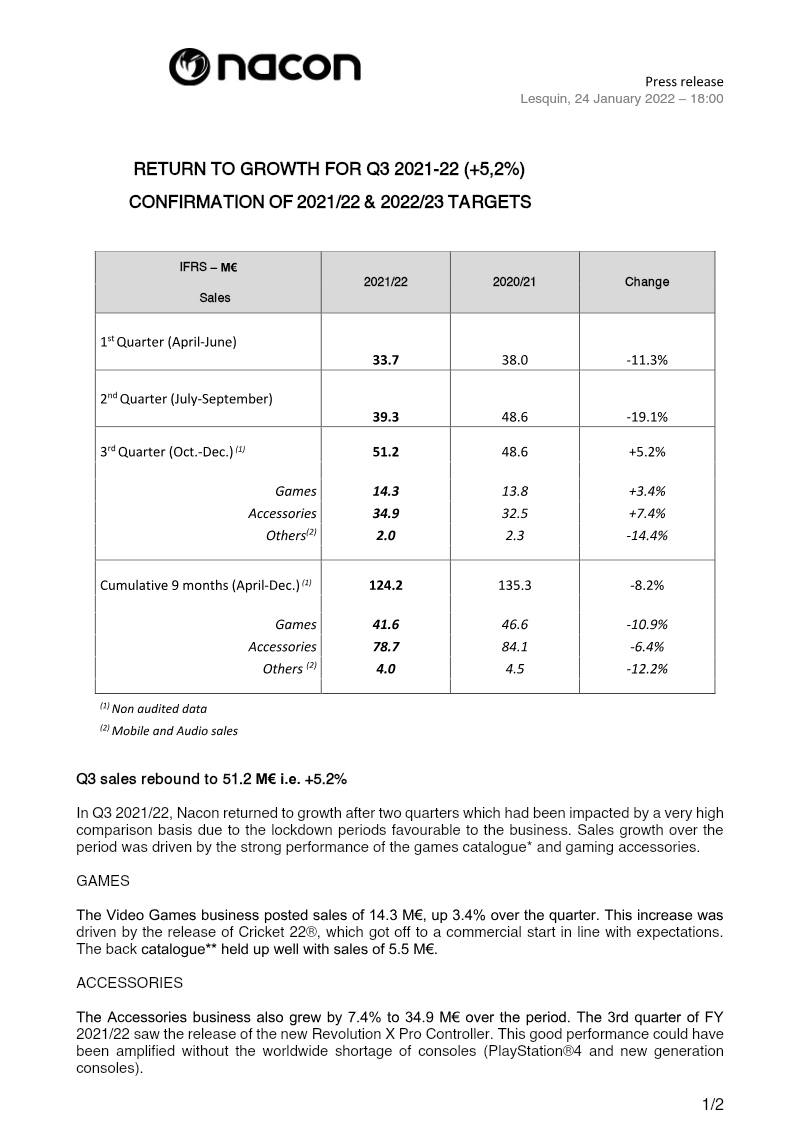
Return to Growth for Q3 2021-22: Confirmation of 2021/22 & 2022/23 Targets
Nacon reported a rebound in Q3 2021/22, with sales rising 5.2 % to €51.2 million after two quarters of decline driven by a high comparison base from lockdown‑related demand spikes. The growth was led by the games catalogue, which generated €14.3 million (+3.4 %) and a strong back‑catalogue contribution of €5.5 million, while accessories grew 7.4 % to €34.9 million thanks to the launch of the Revolution X Pro Controller, though global console shortages limited further upside. Other segments, including mobile and audio sales, contracted by 14.4 % to €2.0 million.
Cumulative sales for the first nine months fell 8.2 % to €124.2 million, with games down 10.9 % and accessories down 6.4 %. Nacon confirmed its FY 2021/22 targets of €150–180 million in sales and an operating income near €20 million. For FY 2022/23, the company projects a robust publishing pipeline of over 15 titles—including high‑profile releases such as Vampire: The Masquerade® – Swansong—and anticipates sales of €250–300 million with an operating margin above 20 %. The strategy includes selective acquisitions to strengthen the catalogue and position Nacon as a leading player in the global video‑game market. The outlook is based on continued demand for both new releases and established titles, with accessories sales expected to benefit from ongoing headset and controller launches across major console platforms.
- Nacon projects significant growth for FY 2022/23, targeting sales of €250–300 million and an operating margin exceeding 20%.
- Q3 2021/22 sales rebounded by 5.2% to €51.2 million, ending two consecutive quarters of decline.
- The company confirmed its FY 2021/22 targets of €150–180 million in sales and an operating income near €20 million, despite a 8.2% decline in cumulative nine-month sales to €124.2 million.
- Accessories growth of 7.4% to €34.9 million was driven by the Revolution X Pro Controller launch, though performance was constrained by global console shortages.
- The games catalogue contributed €14.3 million in Q3, supported by a strong back-catalogue performance of €5.5 million.
Interim Financial Report: First Half 2021/22
INTERIM FINANCIAL REPORT FOR THE SIX MONTHS ENDED 30 SEPTEMBER 2020 – NACON SIX MONTHS ENDED 30 SEPTEMBER 2021 SIX MONTHS ENDED 30 SEPTEMBER 2021 TABLE OF CONTENTS 2 1> STATEMENT BY THE PERSON RESPONSIBLE .3 2> BUSINESS REPORT 4 2.1 Key events in the first half of 2021/22 ...
- NACON's revenue for the first half of 2021/22 decreased by 15.7% to €73.0 million, down from €86.6 million in the same period last year, primarily due to a decline in accessories sales and fewer new video game releases.
- Net income for the first half of 2021/22 significantly dropped by 60.4% to €3.8 million, compared to €9.6 million in the prior year, while recurring operating income fell by 46.3% to €8.4 million.
- The company acquired two development studios in the first half of 2021/22: Big Ant Holding Pty Ltd (known for sports franchises) in May 2021 for €18 million plus potential earn-outs, and Crea-ture Studios Inc (skateboarding games) in July 2021.
- NACON has adjusted its 2021/22 guidance, reducing expected revenue to €150-180 million and recurring operating income to around €20 million, citing delayed game releases.
- Conversely, guidance for 2022/23 has been increased, with expected revenue of €250-300 million and a recurring operating margin of over 20%.
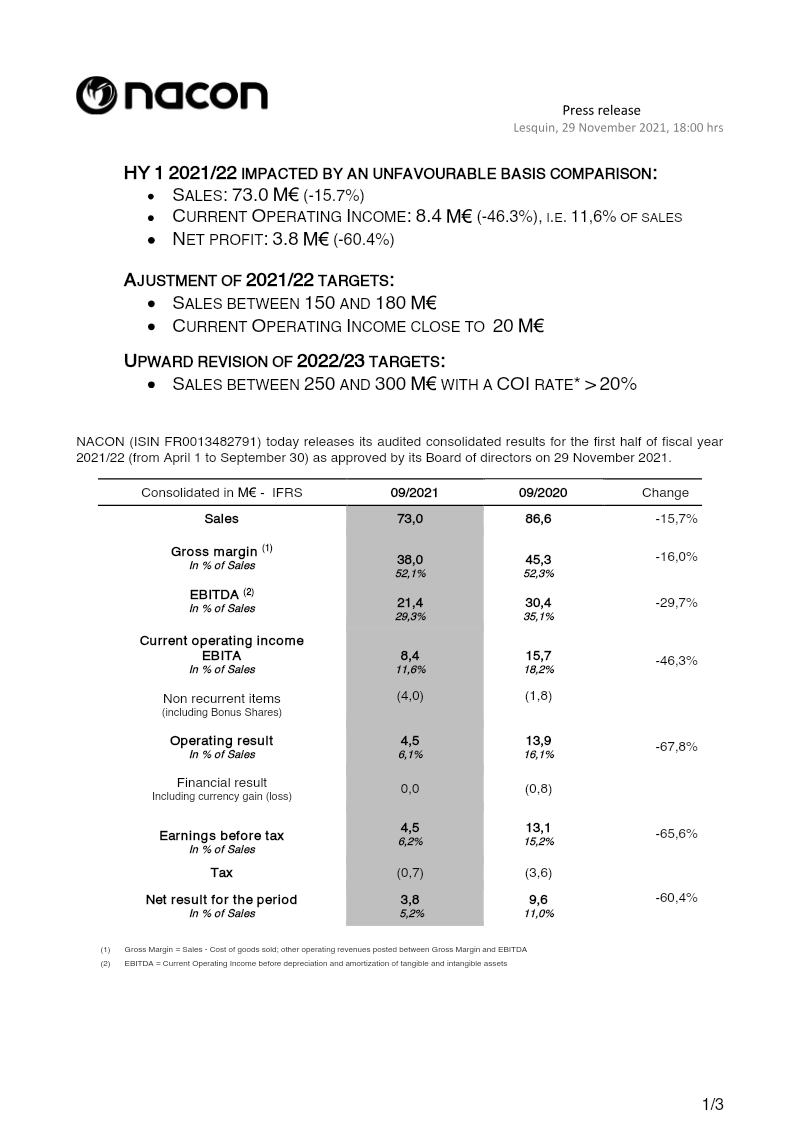
HY 1 2021/22 Consolidated Results: Impacted by an Unfavourable Basis Comparison
Nacon released audited consolidated results for the first half of fiscal year 2021/22, reporting sales of €73.0 million, a 15.7 % decline from the comparable period in 2020/21. Gross margin fell to €38.0 million (52.1 % of sales) and EBITDA dropped 29.7 % to €21.4 million (29.3 % of sales). Current operating income fell 46.3 % to €8.4 million, representing 11.6 % of sales, while net profit contracted 60.4 % to €3.8 million (5.2 % of sales). The decline is attributed mainly to a weaker editorial portfolio—video‑game sales fell 16.9 % to €27.3 million—and a high comparison basis for accessory sales, which decreased 15.1 % to €43.7 million.
The balance sheet remained solid, with shareholders’ equity at €219.0 million and cash reserves of €62.6 million, reflecting recent studio acquisitions and catalogue development. Working‑capital requirements increased by €2.5 million due to inventory build‑up, while operating cash flow reached €17.7 million and investment outflows rose to €45.6 million.
In response, Nacon revised its 2021/22 targets downward (sales €150–180 million; current operating income near €20 million) and lifted 2022/23 expectations (sales €250–300 million; operating‑income rate >20 %). The company postponed several high‑profile releases to 2022/23, citing a need for additional development time to enhance quality. The acquisition of Ishtar Games was completed on 25 November 2021, expanding Nacon’s studio portfolio. The outlook highlights a strong editorial pipeline for 2022/23, with over fifteen new titles and continued growth of the back‑catalogue.
- Nacon reported a 15.7% decline in HY 2021/22 sales to €73.0 million, with net profit contracting 60.4% to €3.8 million compared to the previous year.
- The company lowered its 2021/22 financial targets, now projecting sales of €150–180 million and current operating income near €20 million.
- Performance was impacted by a 16.9% drop in video-game sales to €27.3 million and a 15.1% decline in accessory sales to €43.7 million.
- Nacon postponed several high-profile titles to fiscal year 2022/23 to prioritize development quality, while simultaneously raising its 2022/23 sales guidance to €250–300 million.
- The balance sheet remains stable with €219.0 million in shareholders’ equity and €62.6 million in cash reserves, despite investment outflows rising to €45.6 million.