Market Analysis
Documents
Quarterly Report: 11 bit studios Q1-Q3 2024
QUARTERLY REPORT OF 11 BIT STUDIOS FOR NINE MONTHS ENDED 30 SEPTEMBER 2024 DEAR SHAREHOLDERS AND INVESTORS, It is with great pleasure that we present the quarterly report of 11 bit studios S.A. for the nine months ended 30 September 2024.
- 11 bit studios' net profit for the nine months ended September 30, 2024, was PLN 47,547,111, a significant increase from PLN 1,350,738 in the same period of 2023.
- Total comprehensive income for the nine months ended September 30, 2024, reached PLN 274,612,144, up from PLN 231,721,429 in the prior year.
- The company's cost of services increased to PLN 28,565,995 in Q1-Q3 2024, from PLN 20,038,142 in Q1-Q3 2023, driven by higher royalties (PLN 11,766,222) and marketing expenses (PLN 5,194,744).
- Salaries and wages rose to PLN 15,451,599 in Q1-Q3 2024 (from PLN 9,588,136 in 2023), including a non-cash provision of PLN 2,882,089 for the 2021–2025 Incentive Scheme.
- Finance costs significantly increased to PLN 2,781,184 in Q1-Q3 2024 from PLN 932,271 in Q1-Q3 2023, largely due to exchange differences (PLN 1,889,374) and measurement of financial instruments (Starward Industries S.A.) (PLN 440,287).
Quarterly Report: 11 bit studios Q1 2025
QUARTERLY REPORT OF 11 BIT STUDIOS FOR THE THREE MONTHS ENDED 31 MARCH DEAR SHAREHOLDERS AND INVESTORS, It is our pleasure to present to you the quarterly technical quality, balanced gameplay, and, of report of 11 bit studios S.A. for the three months course, a lot of excitement and entertainment. In ended 31 March 2025.
- 11 bit studios reported a profit loss of PLN 6,373,618 for Q1 2025, a significant increase from the PLN 1,605,666 loss in Q1 2024.
- Operating expenses increased to PLN 20,638,820 in Q1 2025 from PLN 15,614,303 in Q1 2024, primarily due to a more than fivefold increase in depreciation and amortization expense.
- The substantial rise in depreciation and amortization (from PLN 912,412 in Q1 2024 to PLN 4,581,735 in Q1 2025) is attributed to the amortization of recently released games like Frostpunk 2, The Thaumaturge, INDIKA, and Creatures of Ava.
- Net cash from operating activities decreased slightly to PLN 5,256,567 in Q1 2025 from PLN 5,438,889 in Q1 2024.
- The company's future performance will be largely influenced by upcoming releases of both proprietary and third-party titles, including Frostpunk 2 and The Alters.
Half-Year Report of 11 bit studios S.A.: H1 2025
HALF-YEAR REPORT OF 11 BIT STUDIOS S.A. FOR THE SIX MONTHS ENDED 30 JUNE DEAR SHAREHOLDERS AND INVESTORS, It is our pleasure to present to you the half-year report of 11 bit studios S.A. for the six months ended 30 June 2025. During the period, we earned PLN 57.24 million in revenue, a year-on-year increase of 86.09%.
- 11 bit studios S.A. reported a net profit of PLN 8,482,905 for H1 2025, a significant turnaround from a net loss of PLN 477,805 in H1 2024.
- Revenue for H1 2025 increased by 86.09% year-over-year to PLN 57,241,575, driven primarily by new titles 'The Alters' (PLN 20,415,393) and 'Frostpunk 2' (PLN 13,173,906).
- Operating profit saw a substantial improvement, reaching PLN 18,068,721 in H1 2025 compared to an operating loss of PLN 5,352,141 in H1 2024.
- Salaries, wages, and employee benefits decreased by 42.09% to PLN 7,711,456 in H1 2025, while depreciation and amortization increased by 275.18% to PLN 10,946,880.
- The company's liabilities decreased by 14.64% to PLN 27,644,524 as of June 30, 2025, mainly due to lower royalties payable to third-party developers.

Transaction Notification under Article 19(1) MAR
The notification reports a series of share purchases by Marcin Kuciapski, who holds the position of supervisory board member at 11 BIT Studios Spółka Akcyjna. The filing, required under Article 19(1) of the MAR regulation, details transactions executed on the Warsaw Stock Exchange (GPW) market for the company’s shares identified by ISIN PL11BTS00015. Two separate transaction dates are covered: 11 July 2024 and 12 July 2024. On the first date, a total of 80 shares were acquired at a uniform price of 632 PLN each, with individual trade volumes ranging from 5 to 10 shares. The second date involved the purchase of 40 shares at a price of 640 PLN each, with trade sizes between 1 and 23 shares. The aggregated volume for the two days totals 120 shares, all bought at a single price point per day. The notification specifies the transaction type as “Nabycie” (purchase) and lists the exchange venue as XWAR – GPW. No additional data on market impact, settlement terms or related parties beyond the supervisory board role is provided. The scope of the disclosure is limited to a single Polish listed company, covering only two days in mid‑July 2024, and focuses exclusively on the quantity and price of shares acquired by a key corporate officer.
- Marcin Kuciapski, a supervisory board member at 11 BIT Studios S.A., acquired a total of 120 company shares across two days in July 2024.
- On 11 July 2024, Kuciapski purchased 80 shares at a price of 632 PLN per share on the Warsaw Stock Exchange (GPW).
- On 12 July 2024, an additional 40 shares were acquired at a price of 640 PLN per share.
- All transactions were executed on the XWAR – GPW exchange venue and disclosed in compliance with Article 19(1) of the MAR regulation.
- The acquisitions were conducted in small trade volumes, ranging from 1 to 23 shares per individual transaction.
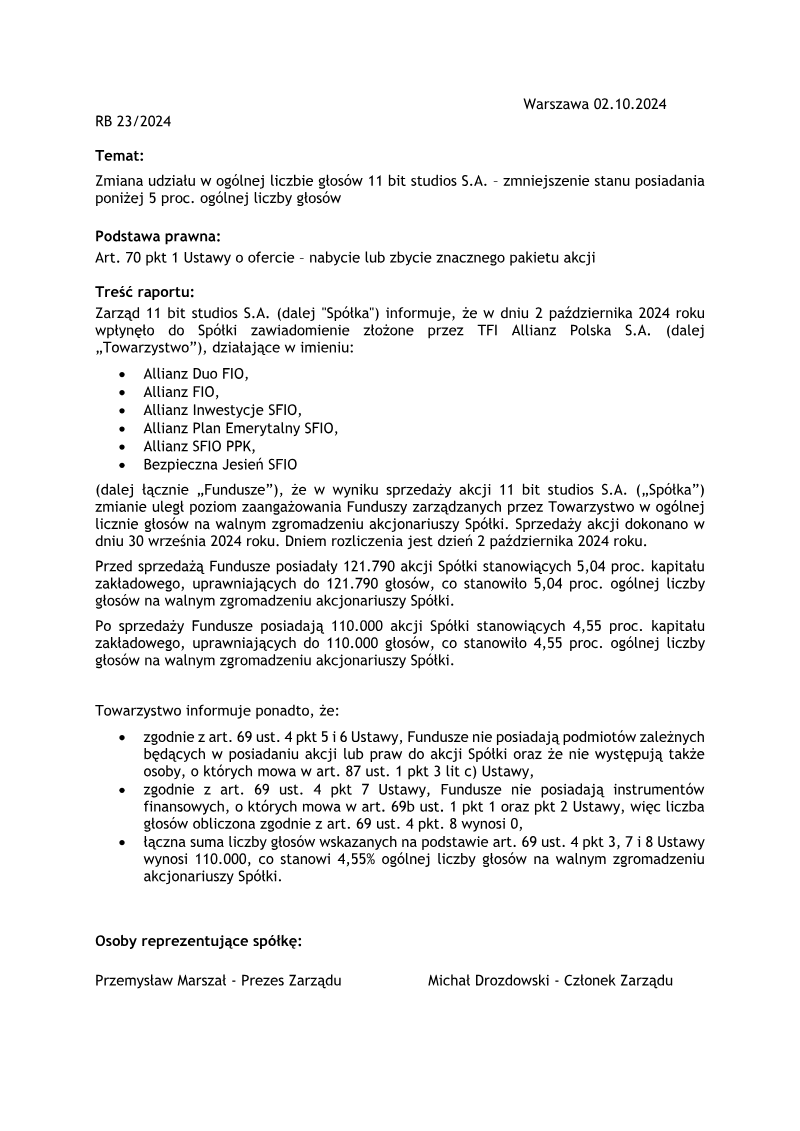
Zmiana udziału w ogólnej liczbie głosów 11 bit studios S.A.: Zmniejszenie stanu posiadania
The notice, dated 2 October 2024, informs shareholders that TFI Allianz Polska S.A., acting on behalf of several Allianz‑managed funds, has reduced its stake in 11 bit studios S.A. through a sale of shares executed on 30 September 2024. Prior to the transaction, the funds held 121 790 shares, representing 5.04 % of the company’s share capital and an equal proportion of voting rights at the shareholders’ meeting. After the sale, their holding decreased to 110 000 shares, amounting to 4.55 % of the share capital and voting power.
The filing confirms compliance with Polish securities law, noting that the funds possess no affiliated entities holding shares in 11 bit studios and hold no restricted financial instruments that would affect voting calculations. Consequently, the total number of votes attributable to the funds is 110 000, corresponding precisely to 4.55 % of all votes at the meeting.
The announcement is issued by the board of 11 bit studios, with Przemysław Marszał as Chairman and Michał Drozdowski as board member. The communication serves to satisfy regulatory disclosure requirements under Article 70(1) of the Polish Offer Act, ensuring transparency regarding significant shareholdings that fall below the 5 % threshold following the sale.
- TFI Allianz Polska S.A. reduced its stake in 11 bit studios S.A. to 4.55% following a share sale executed on 30 September 2024.
- The transaction involved the sale of 11,790 shares, decreasing the funds' total holding from 121,790 to 110,000 shares.
- The reduction in shareholding caused the funds' voting power in 11 bit studios S.A. to drop from 5.04% to 4.55%.
- The funds currently hold no affiliated entities with shares in the company and possess no restricted financial instruments that would impact voting rights.
- The disclosure was issued to comply with Article 70(1) of the Polish Offer Act, as the stake fell below the 5% reporting threshold.
Sales Report: The Alters
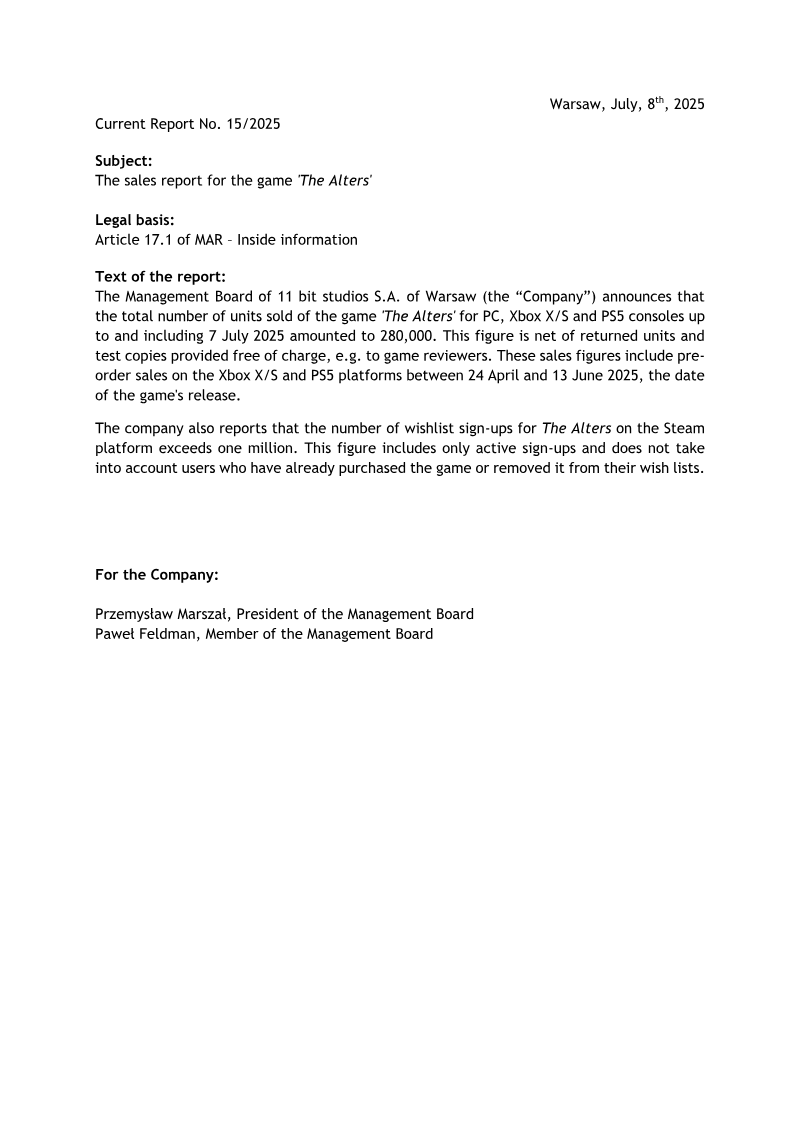
The report announces that the title “The Alters” has sold 280,000 units across PC, Xbox X/S and PS5 platforms through 7 July 2025, after deducting returns and complimentary copies. Pre‑order sales on Xbox X/S and PS5, recorded between 24 April and 13 June 2025, are included in this total. The company also highlights that more than one million users have added the game to their wish lists on Steam, a metric that excludes prior purchasers or those who later removed the title. The data covers sales up to mid‑July 2025 and focuses on three major platforms: PC, Xbox X/S, and PS5. No additional market segments or geographic breakdowns are provided beyond the platform‑level aggregation. The methodology is implicit: sales figures are reported by the company’s Management Board, presumably sourced from internal distribution and retail tracking systems. The report serves to inform stakeholders of the game’s commercial performance, emphasizing both actual sales and pre‑launch interest as measured by wish list activity. The information is presented under Article 17.1 of MAR, indicating it constitutes inside information for regulatory purposes.
- The Alters achieved 280,000 net unit sales across PC, Xbox Series X/S, and PS5 platforms as of 7 July 2025.
- Steam wish list activity for the title has surpassed one million users, excluding those who have already purchased or removed the game.
- The reported sales figures include pre-order data collected for Xbox Series X/S and PS5 between 24 April and 13 June 2025.
- The sales data reflects net performance after accounting for all returns and complimentary copies.
- This commercial performance data is classified as inside information under Article 17.1 of the Market Abuse Regulation (MAR).
Results Briefing Materials: Fiscal Year Ending March 2026, First Half
The briefing presents the first‑half financial performance of Marvelous Inc. for the fiscal year ending March 2026, covering April–September 2025. Net sales surged 157.5 % to ¥20,281 million, driven by the launch of three core video‑game titles—“Rune Factory: Guardians of Azuma,” “STORY OF SEASONS: Grand Bazaar,” and “DAEMON X MACHINA TITANIC SCION”—and robust sales of Pokémon‑branded amusement machines. Segment analysis shows Digital Contents Business revenue rising 198.7 % to ¥12,414 million, while Amusement Business increased 136.3 % to ¥5,982 million; Audio & Visual Business declined 84.0 %. Operating profit fell 38.2 % to ¥226 million due to elevated development costs, yet ordinary and net income rose 102.0 % and 234.7 %, respectively, largely from a shift to foreign‑exchange gains.
The company forecasts full‑year net sales of ¥35,000 million (125.2 % of FY2025), operating profit of ¥2,000 million (110.0 % increase), and a dividend uplift to ¥12 million per share, maintaining the initial earnings outlook. Cash flow improved markedly: operating cash inflows rose from a negative ¥786 million to ¥5,822 million, and net cash increased by ¥5,274 million to ¥12,386 million. Asset growth was modest, with total assets rising by ¥1,424 million and net assets slightly declining due to higher liabilities.
Methodologically, figures derive from consolidated financial statements for the semi‑annual period; no survey data are cited. The report covers Japan, North America, Europe, and Asia for game sales, and includes detailed segment‑level performance. The outlook remains unchanged, with emphasis on sustaining momentum from the newly released titles and existing online properties.
- Marvelous Inc. reported a 157.5% surge in net sales to ¥20,281 million for the first half of fiscal year 2026, driven by the release of three major titles and strong Pokémon-branded amusement machine sales.
- Operating profit declined 38.2% to ¥226 million due to increased development costs, though net income rose 234.7% primarily due to foreign-exchange gains.
- The Digital Contents Business segment saw revenue grow 198.7% to ¥12,414 million, while the Amusement Business grew 136.3% to ¥5,982 million, offsetting an 84.0% decline in the Audio & Visual Business.
- Cash flow improved significantly, with operating cash flow shifting from a negative ¥786 million in the prior period to a positive ¥5,822 million.
- The company maintained its full-year forecast of ¥35,000 million in net sales and a 110% increase in operating profit to ¥2,000 million.
Monthly Declaration Report: Nacon March 2023
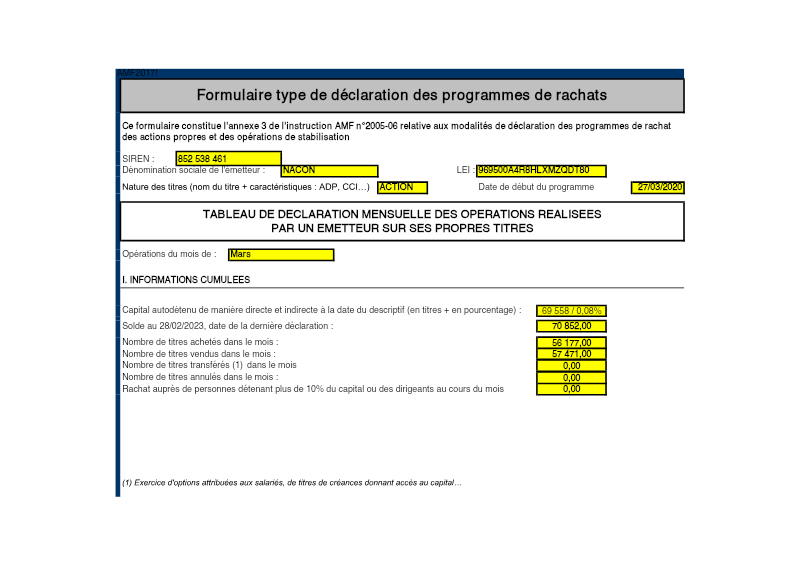
The monthly declaration for Nacon, filed with the AMF on March 2023, documents the company’s share‑buyback activity for the month of March. The report confirms that Nacon’s self‑held equity, both direct and indirect, stood at 69 558 shares (0.08 % of issued capital) as of the declaration date, slightly below the 70 852 shares reported at the end of February. During March, the issuer purchased 56 177 shares and sold 57 471 shares, resulting in a net sale of 1 294 shares. No transfers or cancellations occurred during the month, and no buybacks were executed from shareholders holding more than 10 % of capital or from directors.
The declaration follows the AMF instruction 2005‑06 and is filed under form type 2017, which requires monthly reporting of all transactions involving the issuer’s own shares. The data are presented in a table that lists cumulative information, including the number of shares bought and sold within the month, as well as any transfers or cancellations. The report covers only the period of March 2023 and pertains exclusively to Nacon’s equity securities. No additional methodology or external data sources are disclosed, as the declaration relies on internal transaction records maintained by the issuer.
- As of March 31, 2023, Nacon held 69,558 shares in treasury, representing 0.08% of its total issued capital.
- Nacon executed a net reduction of 1,294 shares in its treasury holdings during March 2023.
- Total market activity for the month consisted of 56,177 shares purchased and 57,471 shares sold.
- Treasury share holdings decreased slightly from the 70,852 shares reported at the end of February 2023.
- There were no share cancellations or transfers recorded during the month of March.
Strong Growth of Profitability: 2019/20 Full Year Results
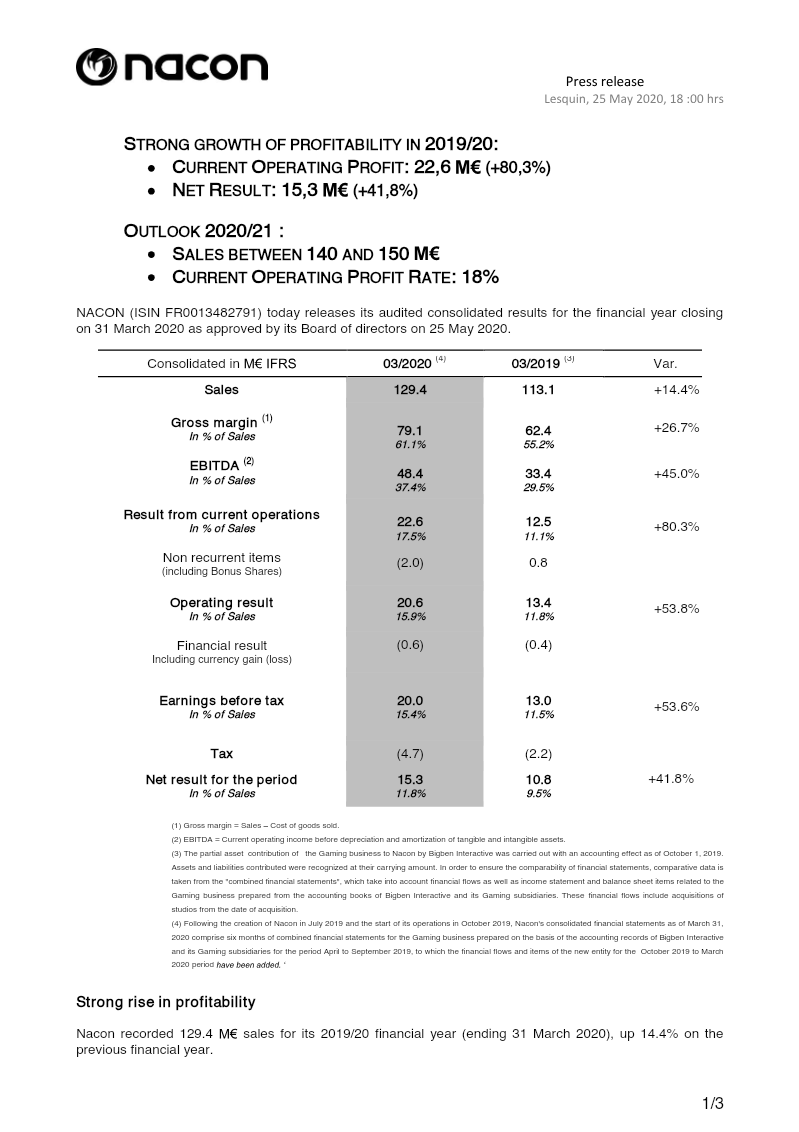
Nacon reported a robust 2019/20 fiscal year, with sales rising to €129.4 million—an increase of 14.4% from the prior year—and a gross margin expanding to 61.1 % of sales, up 26.7 percentage points largely due to a surge in digital game revenue (48.9 million €). EBITDA climbed 45.0% to €48.4 million, representing 37.4 % of sales, while current operating income surged 80.3% to €22.6 million (17.5 % of sales). After accounting for non‑recurring bonus share expenses and a modest financial loss, net profit reached €15.3 million, up 41.8% and translating to €0.18 per share.
The balance sheet strengthened markedly: shareholders’ equity rose from €67.5 million to €187.6 million, driven by a €103 million capital increase following the March 2020 IPO. Cash stood at €110.9 million, and net debt turned negative at €42.8 million after excluding IFRS‑16 lease liabilities.
Geographically, Nacon operates in 100 countries with a workforce of over 510 employees across eight studios. The company’s outlook for FY 2020/21 projects sales between €140–150 million and a current operating margin near 18%, building on its “NACON 2023” strategy to accelerate growth in both games and accessories. Planned investments target AA‑grade titles, studio acquisitions, 5G cloud gaming, and Game‑as‑a‑Service models, while premium accessory development—highlighted by the RIG™ headset acquisition—aims to broaden market reach. The board reaffirmed financial targets for FY 2022/23, anticipating sales of €180–200 million and a current operating margin above 20%.
- Nacon achieved a 14.4% increase in annual sales to €129.4 million, with net profit rising 41.8% to €15.3 million.
- Profitability metrics improved significantly, as EBITDA climbed 45.0% to €48.4 million and current operating income surged 80.3% to €22.6 million.
- The company’s balance sheet was strengthened by a March 2020 IPO that raised €103 million, resulting in a net cash position of €42.8 million.
- Gross margin expanded by 26.7 percentage points to 61.1% of sales, driven primarily by a surge in digital game revenue to €48.9 million.
- Management projects FY 2020/21 sales between €140–150 million with an operating margin near 18%.
Universal Registration Document: 2019/2020
Société anonyme governed by a Board of Directors with share capital of €84,908,919 Registered office: 396/466, Rue de la Voyette, CRT 2, 59273 Fretin, France Registration number: 852 538 461 RCS Lille Métropole UNIVERSAL REGISTRATION DOCUMENT This universal registration document was approved on 7 July by the Autorité des Marchés Financiers (“AMF”) as the competent authority in respect of regulation (EU) 2017/1129.
- NACON, a video game company, reported significant financial growth, with revenue increasing from €95.568 million in 2017/18 to €129.427 million in 2019/20, and recurring operating income rising from €3.728 million to €22.620 million over the same period.
- NACON's gross margin improved substantially, from 41.7% in 2017/18 to 61.1% in 2019/20, indicating increased profitability per sale.
- The company capitalised R&D costs for games, amounting to €30.1 million in 2018/19 and €32.8 million in 2019/20, and benefited from a French video game tax credit (CIJV) of €3.0 million in 2019/20 due to an increase from 20% to 30% of development expenditure.
- NACON has a broad editorial positioning through recent studio acquisitions, including Cyanide (cycling simulations, RPGs), Kylotonn Racing and RaceWard (racing games), Eko Software (Action/RPG, Hack’n Slash, team sports), and Spiders (RPG and action games).
- NACON focuses on digital sales due to their elimination of manufacturing and inventory costs, improved publisher margins, and increased visibility through commercial campaigns with platforms like Steam, Epic Store, PlayStation Store, Xbox Live, and Nintendo eShop.
2019/20 Annual Sales Report
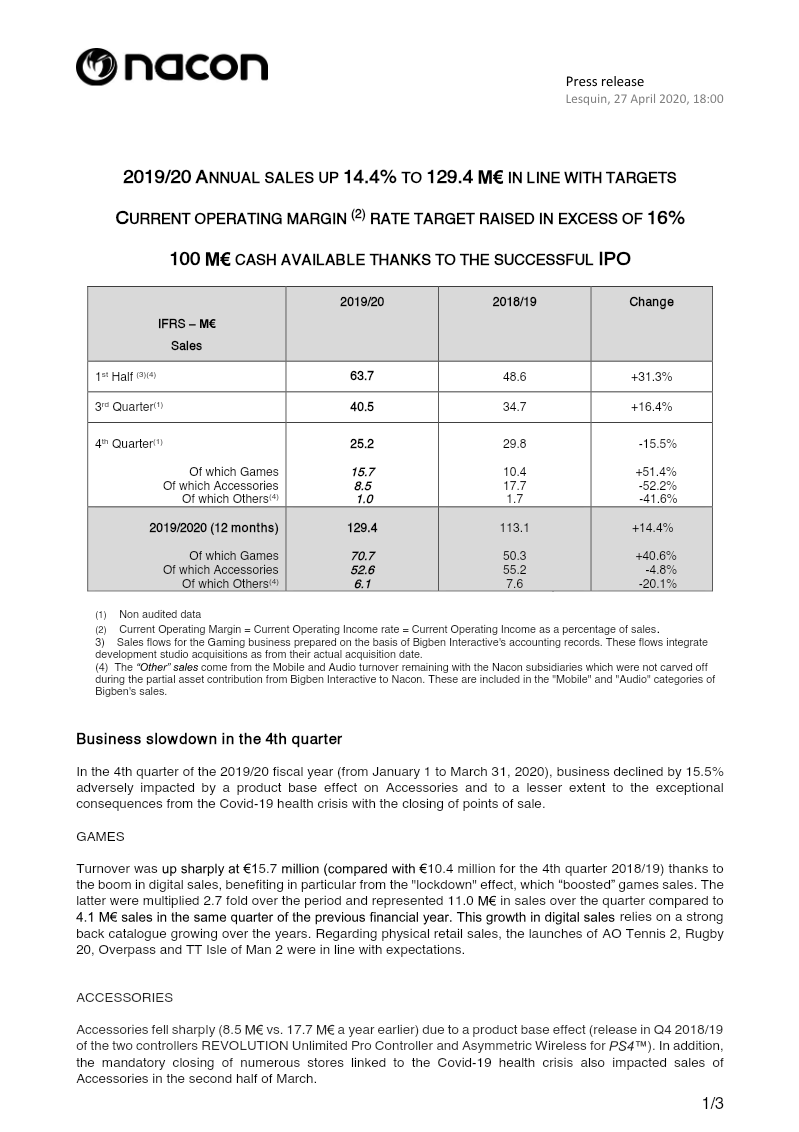
Nacon reported a 14.4 % increase in annual sales, reaching €129.4 million for the 2019/20 fiscal year, in line with its IPO guidance of €127–133 million. Total revenue rose from €113.1 million in 2018/19, driven largely by a 40.6 % jump in game sales to €70.7 million, while accessory revenue fell 4.8 % to €52.6 million and other categories declined 20.1 %. Digital game sales surged, accounting for 69 % of game revenue versus 41 % the previous year, a trend amplified by lockdown‑induced consumer behaviour. The fourth quarter saw a 15.5 % drop in overall sales, largely due to a product‑base effect on accessories and temporary store closures from the COVID‑19 crisis, though game sales remained robust.
Operating performance improved, with a current operating margin target of 16 % raised above expectations thanks to higher digital margins. Cash reserves stood at €100 million following a successful IPO that raised €109 million in March 2020, ensuring liquidity for the upcoming fiscal year. Nacon maintains its “NACON 2023” plan, targeting €180–200 million in sales and a margin above 20 % for FY 2022/23. The company projects continued momentum in Q1 2020/21, with new game releases and expanded headset distribution through a partnership with Poly (Plantronics Inc.). Operations have largely shifted to telework, and procurement has returned to normal levels. The company’s 16 subsidiaries operate across 100 countries, supporting a workforce of nearly 450 employees.
- Nacon reported a 14.4% increase in annual sales to €129.4 million for the 2019/20 fiscal year, meeting its IPO guidance range of €127–133 million.
- Game sales grew by 40.6% to €70.7 million, with digital channels accounting for 69% of that revenue compared to 41% in the previous year.
- Accessory revenue declined by 4.8% to €52.6 million, contributing to a 15.5% drop in overall Q4 sales due to store closures and product-base effects.
- The company raised its current operating margin target to 16% due to higher margins from digital game sales.
- Following a March 2020 IPO that raised €109 million, Nacon holds €100 million in cash reserves to ensure liquidity.
FY 2020/21 Sales Results: Nacon
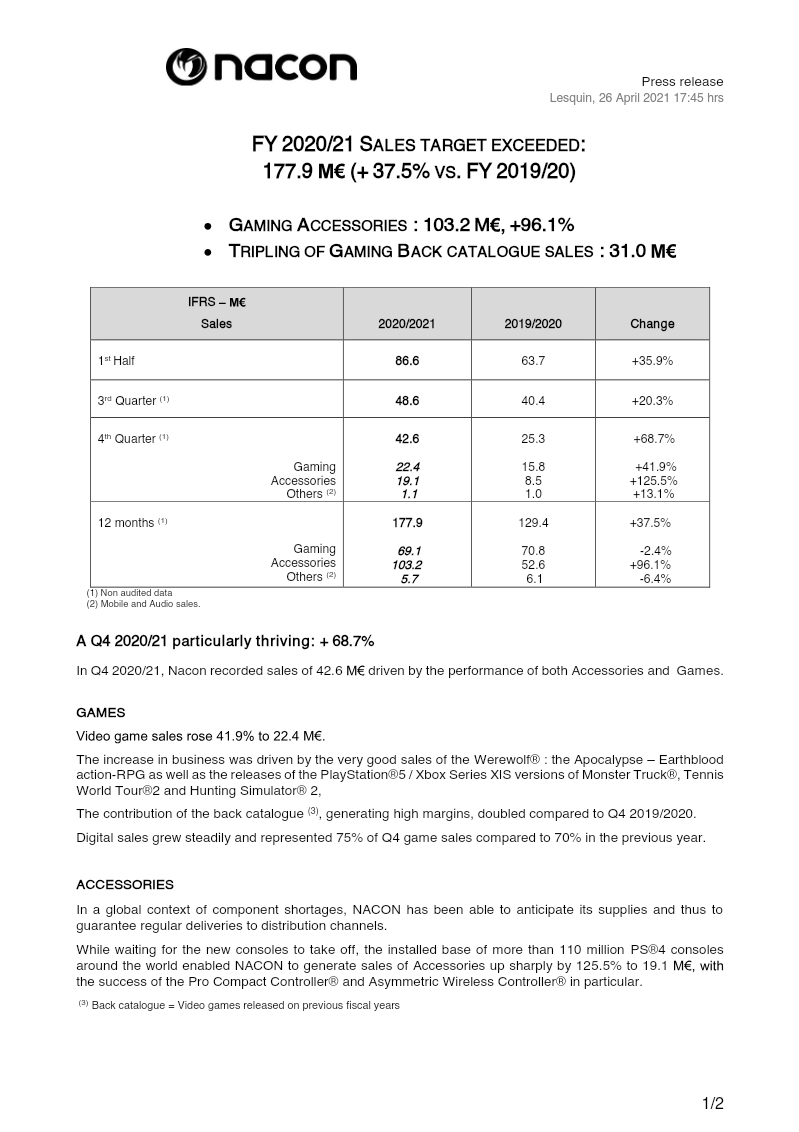
Nacon reported FY 2020/21 sales of €177.9 million, a 37.5 % increase over the previous fiscal year and surpassing the revised target of €160–170 million. Gaming revenue remained flat at €69.1 million, while accessories sales surged to €103.2 million, up 96.1 %. The accessories boom was driven by premium RIG® headsets, licensed controllers, and new Xbox Series X|S accessories launched late in the year. Back‑catalogue game sales tripled to €31 million, contributing high margins and offsetting a slight decline in overall game sales. Digital game sales rose to 75 % of Q4 revenue, up from 70 % the prior year.
Quarterly performance highlighted a strong fourth quarter: €42.6 million in sales, a 68.7 % increase over Q4 2019/20, with gaming and accessories both outperforming. The company’s strategy, outlined during its March 2020 IPO, included acquisitions of Neopica, Passtech Games, and BigAnt Studios, expansion into the U.S. market with RIG® accessories, and a licensing agreement with Microsoft for Xbox Series X|S. These moves are expected to lift sales and operating margins in FY 2022/23 and 2023/24.
Nacon confirmed a 18 % operating income rate for FY 2020/21 and plans to revise its 2023 guidance upward. The company operates globally, with a distribution network in 100 countries and over 510 employees across 17 subsidiaries.
- Nacon achieved FY 2020/21 sales of €177.9 million, representing a 37.5% year-over-year increase that exceeded the company's revised target of €160–170 million.
- Accessories sales were the primary growth driver, surging 96.1% to €103.2 million due to the success of RIG® headsets, licensed controllers, and new Xbox Series X|S hardware.
- Back-catalogue game sales tripled to €31 million, providing high-margin revenue that offset a slight decline in overall gaming segment sales, which remained flat at €69.1 million.
- Digital distribution continues to grow, accounting for 75% of Q4 revenue compared to 70% in the prior year.
- The company reported an 18% operating income rate for the fiscal year and plans to revise its 2023 guidance upward based on recent performance.